
 Borescope Market | 2026-2036
Borescope Market Size, Share, and Industry Trends Forecast 2026-2036
Borescope Market Analysis
Remote diagnostic software subscriptions is restructuring how borescope vendors capture lifetime value from hardware placements. Olympus Corporation leverages its cloud-enabled image management platform to lock in recurring revenue from airline maintenance contracts. Baker Hughes Company anchors its energy-sector position through integrated inspection-as-a-service bundles that bundle hardware, analytics, and field technician deployment. SKF competes by extending its rotating equipment expertise into borescope-based condition monitoring for wind turbine gearboxes.
A borescope is a slender optical or digital instrument inserted into confined spaces to transmit visual data from inaccessible interiors, typically featuring diameters from 2.8 mm to 8 mm and articulating tip angles up to 360 degrees for steering around obstructions. Its core purpose is non-destructive evaluation of turbine blades, heat exchanger tubes, and engine combustion chambers without disassembly. Videoscopes with digital imaging technology command the highest margin pools due to CMOS sensor resolution advances and onboard storage capacity. Flexible borescopes retain structural importance in pipeline inspection where complex bend geometries defeat rigid instruments. Aerospace inspection applications generate the most intensive utilization rates, with fleet operators mandating borescope checks at prescribed flight-cycle intervals.
The FAA mandates borescope documentation standards under Part 43 maintenance rules, while the EPA enforces leak detection protocols that drive optical inspection of refinery flare stacks and storage tank internals. The EU AI Act and MDR framework increasingly shape how automated defect-recognition algorithms in videoscopes gain regulatory acceptance for safety-critical assessments. Stakeholders must weigh certification requirements against the pace of machine-learning feature deployment in next-generation inspection platforms.
Market Dynamics
The FAA's tightened airworthiness directive windows are compressing inspection cycles and forcing MRO facilities to upgrade from analog fiberscopes to digital videoscopes with automated defect recognition.
Growth Catalysts
- Engine hot-section mandates:The FAA's updated Part 43 maintenance rules now prescribe borescope documentation at reduced flight-cycle thresholds, accelerating hardware refresh cycles across US carrier fleets.
- Wind turbine gearbox monitoring:European offshore wind operators are deploying articulating videoscopes for in-situ drivetrain inspection, eliminating costly crane disassembly.
- CMOS sensor resolution advances:4K imaging modules now enable crack detection below 50 microns, expanding borescope applicability to precision casting and additive manufacturing quality control.
Market Restraints
- Specialized optical fiber supply:German and Japanese suppliers dominate high-purity glass fiber production for flexible borescopes, creating input cost volatility during energy price spikes.
- Calibration infrastructure gaps:Certified metrology labs capable of validating 360-degree articulation accuracy remain concentrated in the United States and Germany, extending lead times for Asian operators.
- Handheld thermal imagers:Lower-cost infrared screening tools are substituting for borescope inspection in certain predictive maintenance workflows where surface temperature anomalies suffice.
Strategic Opportunities
- India defense modernization:The country's PLI scheme for aerospace components is funding indigenous MRO capacity, creating first-mover advantage for inspection equipment vendors establishing local calibration partnerships.
- EU AI Act compliance:Automated defect-recognition algorithms in videoscopes can secure CE marking under the MDR framework for safety-critical assessments, locking out non-compliant imports.
- Drone-borescope convergence:UAV-mounted insertion systems are enabling flare stack and chimney inspection without scaffolding, opening refinery and chemical plant applications previously inaccessible to manual deployment.
Industry Challenges
- Level 3 NDT certification scarcity:Interpreting borescope imagery for turbine blade creep damage requires specialized training pipelines that lag equipment deployment rates.
- Legacy system integration:Airlines with decades-old maintenance management software face data format incompatibilities when connecting cloud-enabled videoscope platforms to existing record-keeping architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Borescope Market |
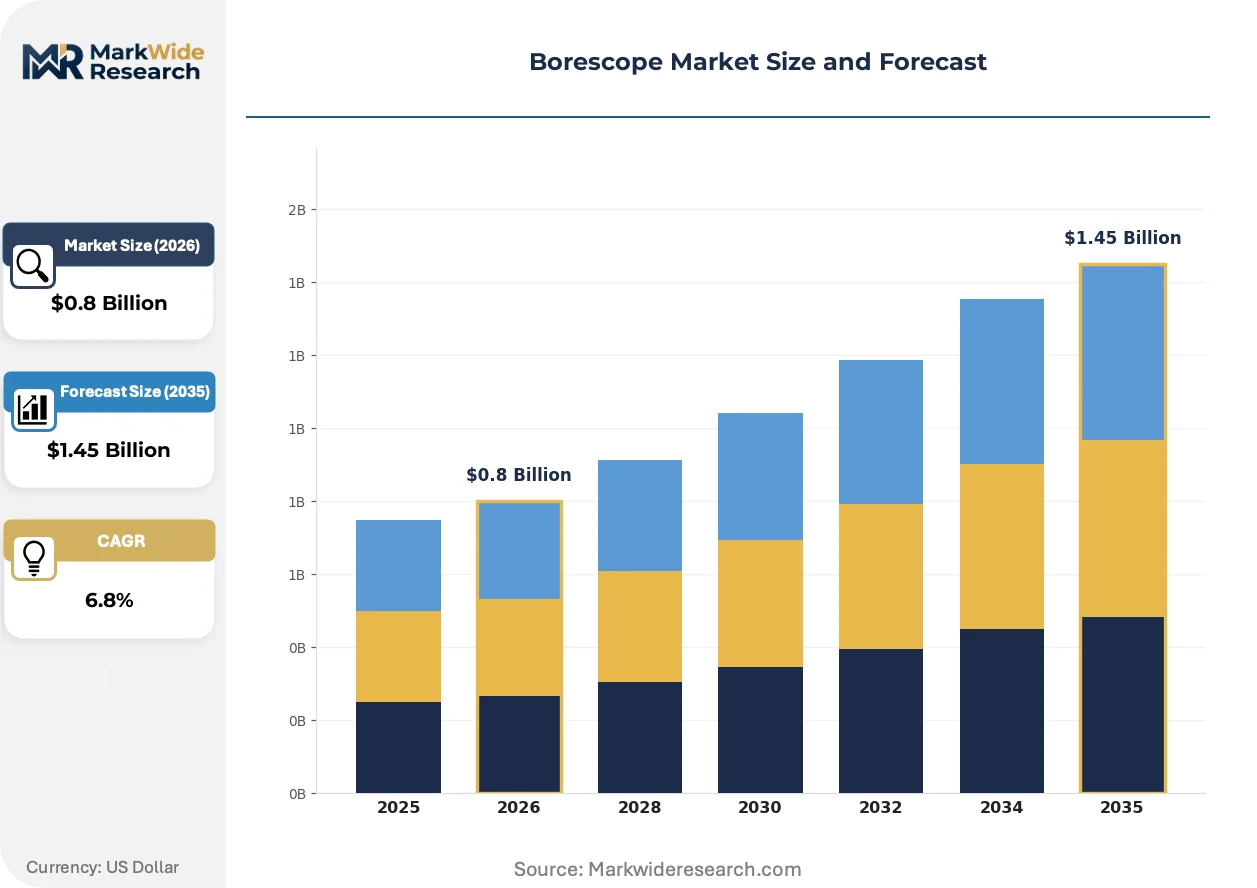
| Market Size in 2026 | $0.8 Billion |
| Market Size in 2035 | $1.45 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Borescopes, Flexible Borescopes, Videoscopes, Fiberscopes Application: Aerospace Inspection, Manufacturing Quality Control, Automotive Diagnostics, Pipeline Inspection Technology: Digital Imaging, Optical Technology, Video Technology, Miniaturized Sensors End User: Aerospace Companies, Automotive Service Centers, Oil & Gas Industries, Manufacturing Plants |
| Companies Covered | Olympus Corporation, Fluke Corporation, GE Inspection Technologies, Baker Hughes Company, SKF, Karl Storz, Teledyne FLIR, MORITEX Corporation, Ametek, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Borescope Market Emerging Trajectories
Digital imaging pipelines and machine-learning defect classification are compressing inspection timelines while raising the technical bar for equipment differentiation. Vendors now compete on software-enabled workflow integration rather than optical specifications alone.
Artificial intelligence inference engines are integrating directly into videoscope handset firmware, enabling real-time crack propagation scoring without external processing latency. MRO facilities in the United States are piloting these systems for engine hot-section checks. The technology is integrating inspection and documentation into a single operator workflow, collapsing the traditional two-step image capture and desktop analysis sequence.
The EU AI Act's risk-classification framework is mandating validation documentation for automated defect-detection algorithms used in safety-critical assessments. Manufacturers must now submit conformity evidence to notified bodies before CE marking. Videoscope vendors with established quality management systems under ISO 13485 are adapting fastest, while smaller players face certification timeline compression.
Maintenance organizations are consolidating inspection equipment procurement through integrated service contracts that bundle hardware, software subscriptions, and technician training. Airlines with large narrow-body fleets are favoring vendors offering guaranteed uptime commitments over capital purchase models. This shift is most visible in North America and Western Europe, where labor arbitrage for specialized NDT personnel has eroded the economic case for in-house equipment ownership.
Borescope Market Segmentation
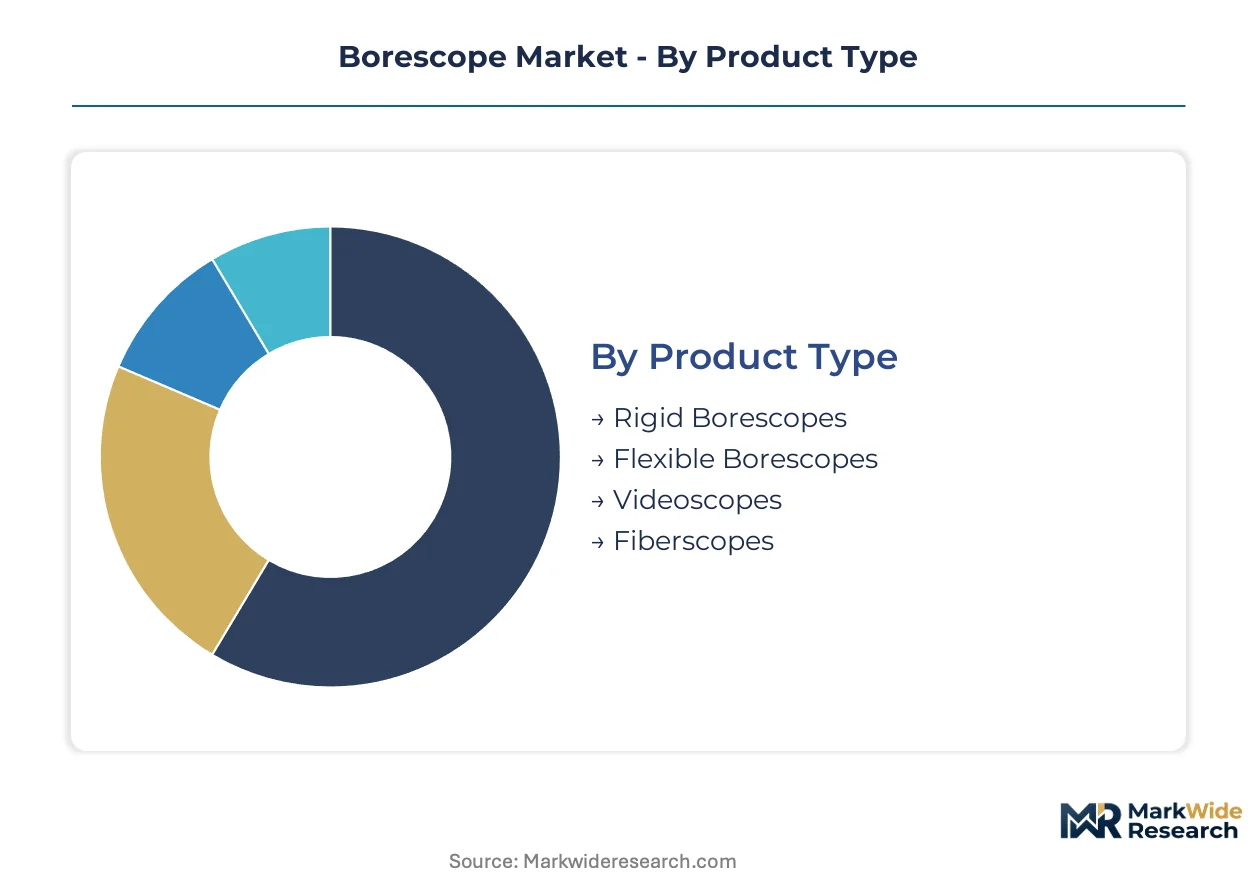
Borescope procurement patterns diverge sharply across inspection environments. Product specifications, deployment frequency, and regulatory documentation requirements create distinct demand profiles that vendors must address through specialized feature sets and service bundles.
Product Type:
Buyers differentiate primarily by access geometry and image fidelity requirements, trading off articulation range against optical resolution.
- Videoscopes:CMOS sensor arrays deliver 4K resolution with onboard storage and wireless image transmission. US airline MRO facilities are standardizing on these systems to meet FAA Part 43 documentation mandates for engine hot-section inspections.
- Flexible Borescopes:Fiber-optic bundles navigate complex bend geometries in pipeline networks and heat exchanger tube arrays. Demand concentrates in Gulf Coast refinery maintenance operations where 360-degree steering around obstructions eliminates vessel disassembly.
- Rigid Borescopes:Straight-line optical paths serve manufacturing quality control stations with fixed inspection fixtures.
- Fiberscopes:Legacy analog systems persist in budget-constrained automotive service centers performing basic cylinder bore examination.
Videoscopes lead volumes today; flexible borescopes are gaining share fastest in energy-sector deployments.
Application:
Inspection cycle frequency and asset criticality determine equipment specification tiers across end-use environments.
- Aerospace Inspection:Fleet operators mandate borescope checks at prescribed flight-cycle intervals for turbine blade creep and combustion chamber distress. The FAA's tightened airworthiness directive windows are compressing turnaround times and forcing hardware upgrades.
- Pipeline Inspection:Long-haul transmission operators deploy kilometer-length push-cable systems with self-leveling camera heads. North American midstream companies are replacing manual crawler inspections with continuous monitoring arrays.
- Manufacturing Quality Control:Precision casting and additive production lines integrate bench-mounted systems for micron-level defect detection.
- Automotive Diagnostics:Service centers perform intermittent cylinder head and catalytic converter examinations with handheld entry-level units.
Aerospace inspection commands the steepest expansion trajectory; pipeline applications show the strongest replacement cycle acceleration.
Technology:
Image processing architecture separates premium systems from commodity hardware, with software-enabled features now driving purchase decisions.
- Digital Imaging:Raw sensor data streams enable AI-powered defect classification directly on the handset. MRO facilities in the United States are piloting real-time crack propagation scoring that collapses traditional two-step capture and analysis workflows.
- Miniaturized Sensors:Sub-3mm probe diameters access turbine blade cooling passages and medical device lumens previously unreachable. European precision engineering clusters are adopting these for additive manufacturing in-process monitoring.
- Video Technology:Compressed digital transmission supports remote expert consultation during live inspection sequences.
- Optical Technology:Pure fiber systems retain niche positions in hazardous environments where electronic ignition risks prohibit powered components.
Digital imaging dominates current procurement; miniaturized sensors are climbing the fastest as access constraints tighten across industries.
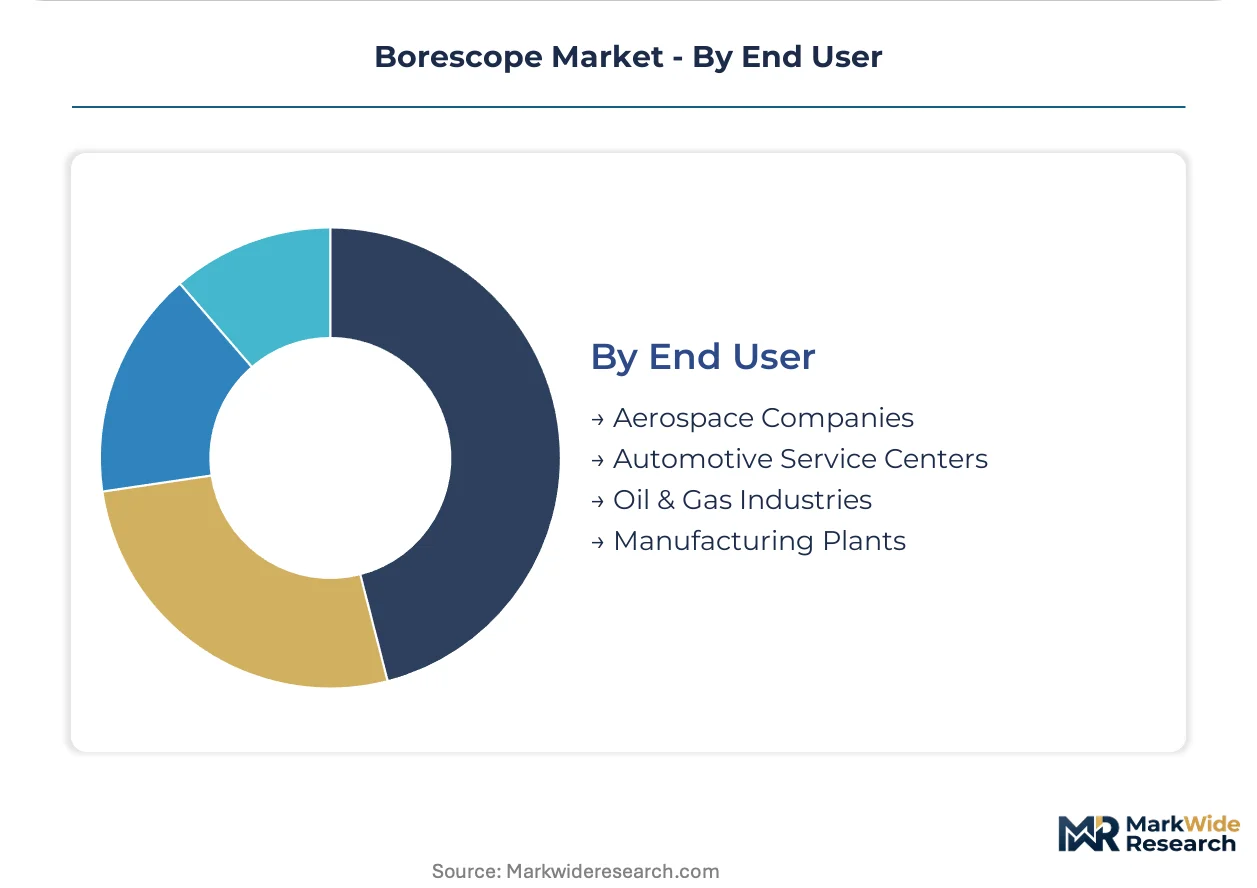
End User:
Capital availability and technical staffing depth create distinct purchasing patterns between in-house operations and outsourced service providers.
- Aerospace Companies:Major carriers and independent MRO facilities maintain extensive videoscope inventories with dedicated Level 3 NDT-certified interpreters. The scarcity of qualified personnel is forcing consolidation toward vendors offering bundled training and certification programs.
- Oil & Gas Industries:Integrated majors and pipeline operators specify explosion-proof housings and extended cable reach for storage tank and flare stack deployment. Drone-borescope convergence is eliminating scaffolding costs in refinery turnaround planning.
- Manufacturing Plants:Automotive and precision component producers integrate inspection stations directly into production lines for statistical process control.
- Automotive Service Centers:Independent repair chains and dealership service departments operate with single-handset configurations and limited diagnostic depth.
Aerospace companies anchor equipment volumes; oil and gas industries are expanding procurement most aggressively through inspection-as-a-service contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany maintains tighter calibration standards than Japan, yet both markets drive premium equipment procurement through distinct regulatory pathways. The United States concentrates the largest installed base of advanced videoscope systems, while emerging demand in India and the UAE reshapes vendor geographic priorities.
United States
FAA Part 43 maintenance rules mandate borescope documentation at reduced flight-cycle thresholds, forcing MRO facilities to upgrade from analog fiberscopes to digital systems. The EPA enforces leak detection protocols that drive optical inspection of refinery flare stacks. Dallas-Fort Worth and Atlanta host the densest clusters of airline maintenance operations, where Level 3 NDT-certified interpreters command premium wages.
Germany
Certified metrology labs validating 360-degree articulation accuracy concentrate in Stuttgart and Munich, extending lead times for Asian operators seeking calibration services. The EU AI Act's risk-classification framework mandates validation documentation for automated defect-detection algorithms. Baden-Württemberg's precision engineering clusters adopt sub-3mm probe systems for additive manufacturing in-process monitoring.
China
MIIT standards for industrial inspection equipment accelerate domestic videoscope production, though high-purity glass fiber inputs remain import-dependent from Japanese suppliers. The country's dual carbon goals drive wind turbine gearbox inspection demand across coastal provinces. Yangtze River Delta manufacturing hubs integrate bench-mounted rigid borescopes for automotive quality control stations.
India
The PLI scheme for aerospace components funds indigenous MRO capacity, creating first-mover advantage for inspection equipment vendors establishing local calibration partnerships. BIS certification requirements for imported optical instruments create compliance barriers for non-resident suppliers. Bangalore and Hyderabad defense contractors expand remote visual inspection programs to reduce aircraft downtime.
Japan
METI industrial technology roadmaps prioritize CMOS sensor resolution advances for precision casting applications. JIS standards for non-destructive testing equipment shape procurement specifications across automotive and energy sectors. Nagoya's aerospace supply chain maintains intensive utilization rates for turbine blade creep damage assessment.
Borescope Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium videoscope vendors capturing recurring software revenue while commodity producers compete on probe diameter specifications. The vendor base concentrates among diversified industrial conglomerates with existing NDT portfolios and specialized optical equipment houses with deep articulation mechanics expertise. Three archetypes dominate: cloud-enabled platform providers bundling hardware and analytics, rotating equipment specialists extending into condition monitoring, and pure-play inspection technology firms defending optical resolution leadership. Consolidation proceeds through strategic partnerships linking drone operators with insertion system designers, alongside vertical integration into CMOS sensor module production.
Among diversified industrial technology groups, Olympus Corporation and Baker Hughes Company exemplify contrasting platform strategies, while SKF occupies a position bridging rotating equipment expertise with borescope-based monitoring. Karl Storz represents the specialized medical-industrial optical heritage segment, and Teledyne FLIR anchors thermal-imaging convergence plays. These five entities collectively illustrate how software-enabled workflow integration now supersedes pure optical specifications as the primary competitive vector.
| Leading Market Players |
|---|
| Olympus Corporation |
| Fluke Corporation |
| GE Inspection Technologies |
| Baker Hughes Company |
| SKF |
| Karl Storz |
| Teledyne FLIR |
| MORITEX Corporation |
| Ametek |
| Others |
Supply Flow & Price Mechanics
The EPA's leak detection protocols for refinery flare stack inspection gate qualified supply access and premium-tier pricing power, as only vendors with explosion-proof housings and extended cable reach meet procurement specifications for integrated majors. This environmental mandate concentrates buyer leverage among oil and gas operators while elevating entry costs for equipment providers lacking hazardous-location certifications.
Pricing Analysis
Capacity additions in China's Yangtze River Delta manufacturing hubs are reshaping price floors for entry-level rigid borescopes used in automotive quality control stations. Three-tier pricing structure across premium, standard, and economy levels separates FAA Part 43-compliant videoscopes with automated defect recognition from legacy fiberscopes and handheld thermal imagers. Cost compression in the economy tier is intensifying because lower-cost infrared screening tools substitute for borescope inspection in certain predictive maintenance workflows. Automotive service centers exhibit the highest price sensitivity, while US airline MRO facilities prioritize guaranteed uptime commitments over capital purchase models.
Supply Chain Analysis
High-purity glass fiber production for flexible borescopes rests on German and Japanese specialty suppliers, creating input dependency for articulating probe manufacturers serving Gulf Coast refinery maintenance operations. CMOS sensor modules draw from South Korean and Taiwanese semiconductor fabrication, while explosion-proof housings source from certified foundries in Germany and the United States. Single-source vulnerability in specialized optical fiber supply generates cost volatility during energy price spikes. Distribution runs through authorized service partners providing calibration, technician training, and software subscription management.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with FAA-mandated documentation standards and EU AI Act compliance requirements shifting procurement toward premium videoscope systems with validated automated defect-recognition algorithms.
For Market Incumbents: Hedge against handheld thermal imager substitution by embedding AI inference engines directly into handset firmware, collapsing traditional two-step capture and analysis workflows for engine hot-section checks. Secure backward integration into CMOS sensor module production to defend margin position against South Korean and Taiwanese component suppliers. Prioritize ISO 13485 quality management system adaptation for fastest CE marking under the EU AI Act's risk-classification framework. For New Entrants and Emerging Players: Independent wind turbine service providers in European offshore markets represent an underserved buyer archetype lacking in-house Level 3 NDT-certified interpreters for drivetrain inspection. Establish local calibration partnerships in India under the PLI scheme for aerospace components, where BIS certification requirements create compliance barriers for non-resident suppliers. Lead with inspection-as-a-service contracts bundling hardware, analytics, and field technician deployment rather than capital sale positioning. For Investors and Strategic Acquirers: Roll-up economics work for specialized optical equipment houses with deep articulation mechanics expertise because cloud-enabled platform providers require proven insertion system technology to complete integrated inspection bundles. Target mid-cap vendors with established FAA Part 43 compliance documentation and existing airline maintenance contracts. Watch drone-borescope convergence adoption rates in refinery turnaround planning as the inflection signal for inspection-as-a-service contract expansion.| Strategic Initiative | Industry Significance |
|---|---|
| AI Firmware Integration | Onboard defect classification collapses traditional two-step workflows for US airline MRO facilities. |
| Calibration Partnership Expansion | Local metrology validation accelerates market access under India's BIS certification requirements. |
| Drone-Borescope Convergence | UAV-mounted insertion eliminates scaffolding costs for EPA-mandated flare stack inspection. |
| Backward Integration into Sensors | In-house CMOS production reduces dependency on South Korean and Taiwanese semiconductor suppliers. |
| Inspection-as-a-Service Bundling | Guaranteed uptime commitments displace capital purchase models among North American fleet operators. |
Methodological Framework
Multiple input streams — primary interviews with maintenance directors at airline MRO facilities, plant engineers at Gulf Coast refineries, and aftermarket service heads at wind turbine operators; secondary validation through FAA airworthiness directive filings, EPA enforcement data, and SEC 10-K disclosures from diversified industrial technology groups; plus customs records for high-purity glass fiber trade flows — were reconciled through bottom-up equipment shipment analysis and top-down end-use demand estimation.
Historical installation base data was cross-referenced against expert panel input from Level 3 NDT-certified interpreters and calibration lab operators across the analysis window. Segmentation dimensions modeled include product type (videoscope, flexible borescope, rigid borescope), application (aerospace inspection, pipeline inspection, manufacturing quality control), technology tier (digital imaging, miniaturized sensors), and end-user capital availability. CAGRs were derived from equipment refresh cycle compression rates and regulatory mandate timing, with wind turbine gearbox inspection demand and CMOS sensor resolution advances serving as key forecast inputs.
Underlying measurement precision varies by segment; aerospace inspection applications carry tighter precision than automotive diagnostics due to mandatory flight-cycle documentation requirements. Forecasts reflect assumptions about FAA enforcement consistency, EU AI Act implementation timelines, and offshore wind capacity expansion rates. A small set of triggers — handheld thermal imager substitution acceleration, single-source optical fiber supply disruption, and Level 3 NDT certification pipeline constraints — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Fiducial Markers Market
Imaging
Global 4K Camera Market
Imaging
360-Degree Camera Market
Imaging
Handheld Fluorescence Imaging Devices Market
Imaging
Microscopic Camera Market
Imaging
Europe IP Camera Market
Imaging
Global Cell Imagers Market
Imaging
Global Ingaas Camera Market
Imaging
Smart Camera Market
Imaging
Micro-Magnetic Resonance Imaging Market
Imaging
Gige Camera Market
Imaging
Photoconductor Drums Market
Imaging
Webcam Market
Imaging
Holotomographic Imaging Market
Imaging
Global Computed Radiography Market
Imaging
Global Phosphor Plate Scanners Market