
 Middle East and Africa Thermal Imaging Systems Market | 2026-2036
Middle East and Africa Thermal Imaging Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Thermal Imaging Systems Market Foresight
The EU Green Deal's extraterritorial reach into supplier compliance is broadening sustainability scrutiny across defense electronics supply chains serving Middle East and Africa buyers. FLIR Systems Inc. leverages its vertically integrated sensor fabrication to maintain cost discipline on uncooled camera modules for regional industrial clients. L3Harris Technologies Inc. anchors its position through long-term service contracts with national security agencies in the Gulf. Leonardo S.p.A. competes on cooled infrared technology leadership for high-resolution military applications.
Thermal imaging systems detect infrared radiation emitted by objects and convert it into visible images using focal plane arrays operating across wavelengths from 3 to 14 micrometers, enabling temperature measurement and heat signature visualization in complete darkness or obscured atmospheric conditions. The uncooled segment dominates unit shipments due to lower power requirements and elimination of cryogenic cooling mechanisms suited for prolonged desert deployment. Cooled technology captures premium value in military surveillance where detector sensitivity below 20 millikelvin noise-equivalent temperature difference enables long-range target identification. Software analytics represent the fastest-expanding margin pool as AI-enabled threat detection and predictive maintenance algorithms migrate from hardware to recurring license revenue.
Saudi Arabia's Communications and Information Technology Commission imposes cybersecurity certification on imported surveillance equipment, while South Africa's National Regulator for Compulsory Specifications enforces electromagnetic compatibility standards for industrial thermal devices. The UAE's mandatory Emirates Conformity Assessment Scheme for critical infrastructure equipment creates compliance barriers for uncertified suppliers. Buyers must evaluate dual-use export control classifications under US International Traffic in Arms Regulations and European Union dual-use regulations before finalizing procurement timelines.
Market Dynamics
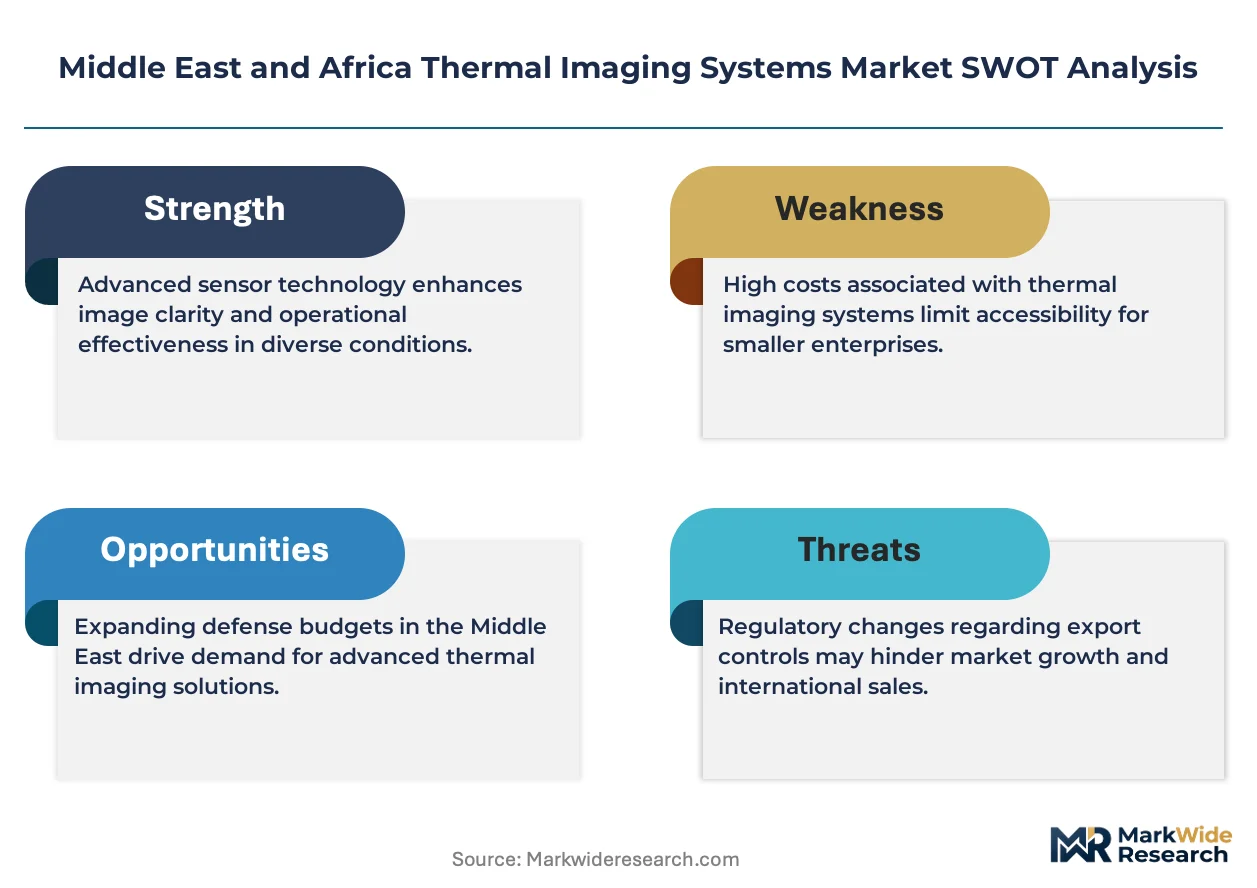
Uncooled focal plane array maturation is compressing unit economics and extending desert deployment lifespans, while Gulf Cooperation Council defense procurement centralization concentrates demand among national security agencies.
Growth Catalysts
- EU Green Deal supply chain scrutiny:Extraterritorial sustainability mandates are forcing component suppliers to certify carbon footprints, accelerating compliant vendor qualification among European defense electronics exporters serving Middle East buyers.
- Border security infrastructure:Saudi Arabia and UAE defense ministries are expanding thermal surveillance networks for perimeter monitoring, creating sustained replacement demand for cooled detector arrays in harsh climate conditions.
- AI-enabled analytics migration:Software-based threat detection algorithms are shifting revenue from hardware sales to recurring license models, expanding margin pools for predictive maintenance applications in oilfield safety.
Market Restraints
- Cryogenic cooler supply concentration:Stirling cycle cooler manufacturing concentrates among German and Japanese precision engineering specialists, creating single-source vulnerability for high-resolution military detector modules.
- Dual-use export control friction:US International Traffic in Arms Regulations and EU dual-use regulations impose multi-month licensing timelines on cooled infrared systems, delaying procurement cycles for national security buyers.
- Silicon wafer input volatility:Microbolometer fabrication depends on 8-inch silicon wafer supply chains subject to foundry capacity constraints, transmitting semiconductor cycle volatility into uncooled camera module pricing.
Strategic Opportunities
- Underpenetrated African mining corridors:Copper and cobalt extraction operations across Zambia and Democratic Republic of Congo lack thermal monitoring infrastructure, creating first-mover advantage for equipment vendors establishing local service presence.
- Emirates Conformity Assessment Scheme:UAE mandatory certification for critical infrastructure equipment creates compliance barrier that pre-qualified suppliers can leverage to lock out uncertified competitors in airport and port security segments.
- Edge-AI convergence:On-device neural network inference is enabling real-time anomaly detection without cloud connectivity, opening deployment in remote pipeline monitoring where bandwidth constraints previously excluded automated analytics.
Industry Challenges
- Multispectral sensor integration complexity:Defense buyers demand fused thermal-visible-swir outputs, requiring optical engineers capable of aligning disparate detector technologies within unified mechanical packages.
- Saudi CITC cybersecurity certification timelines:Communications and Information Technology Commission evaluation periods for imported surveillance equipment extend procurement cycles by six to twelve months, compressing vendor cash conversion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Thermal Imaging Systems Market |
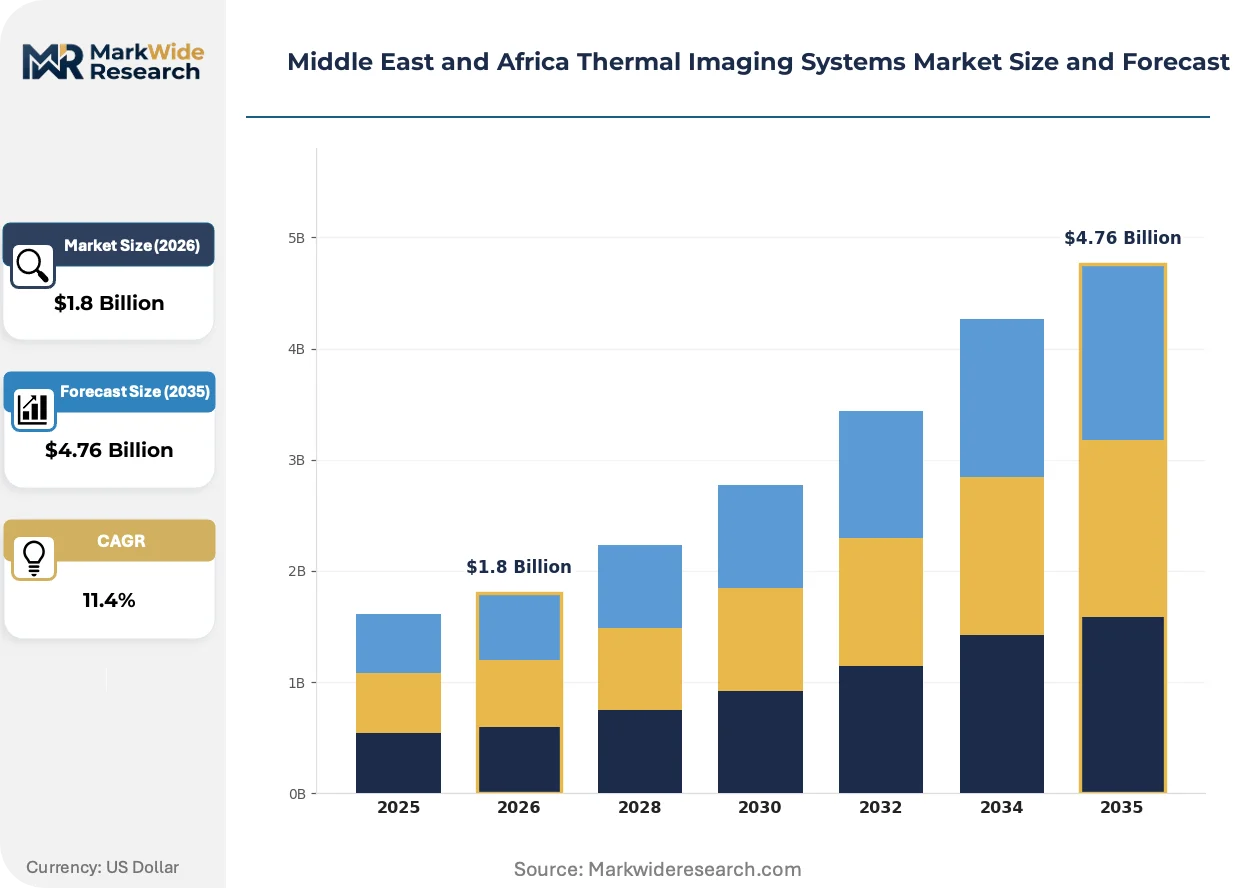
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cameras, Scanners, Software, Accessories End User: Military, Healthcare, Industrial, Environmental Technology: Uncooled, Cooled, Hybrid, Advanced Application: Surveillance, Maintenance, Research, Safety |
| Companies Covered | FLIR Systems Inc., Axis Communications AB, L3Harris Technologies Inc., Leonardo S.p.A., BAE Systems, Opgal Optronic Industries Ltd., Thermoteknix Systems Ltd., Infratec GmbH, Teledyne Technologies Incorporated, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Thermal Imaging Systems Market Shifts & Advancements
Software-defined functionality is migrating threat detection intelligence from hardware to algorithm layers, compressing equipment replacement cycles while expanding recurring revenue attachment rates.
Vanadium oxide microbolometer technology is absorbing increasing share of industrial monitoring applications as fabrication yields improve and pixel pitch shrinks below 12 micrometers. Oilfield operators across Kuwait and Qatar are adopting uncooled modules for flare stack monitoring, displacing legacy thermocouple networks. The cost compression this enables is absorbing price pressure from commoditized hardware segments into software analytics bundles.
South Africa's National Regulator for Compulsory Specifications is enforcing electromagnetic compatibility standards for industrial thermal devices, requiring shielding redesigns that add material cost but create compliance moats against uncertified imports. Mining equipment suppliers are responding by pre-integrating certified modules into original manufacturing rather than retrofitting post-installation.
Service contract unbundling is separating hardware ownership from predictive maintenance obligations among Gulf national security agencies. System integrators are capturing multi-year technical support mandates that previously bundled with initial procurement, shifting buyer preference toward vendors with regional depot maintenance infrastructure. This pattern concentrates most visibly in UAE border security programs where uptime guarantees dominate source selection criteria.
Middle East and Africa Thermal Imaging Systems Market Segmentation
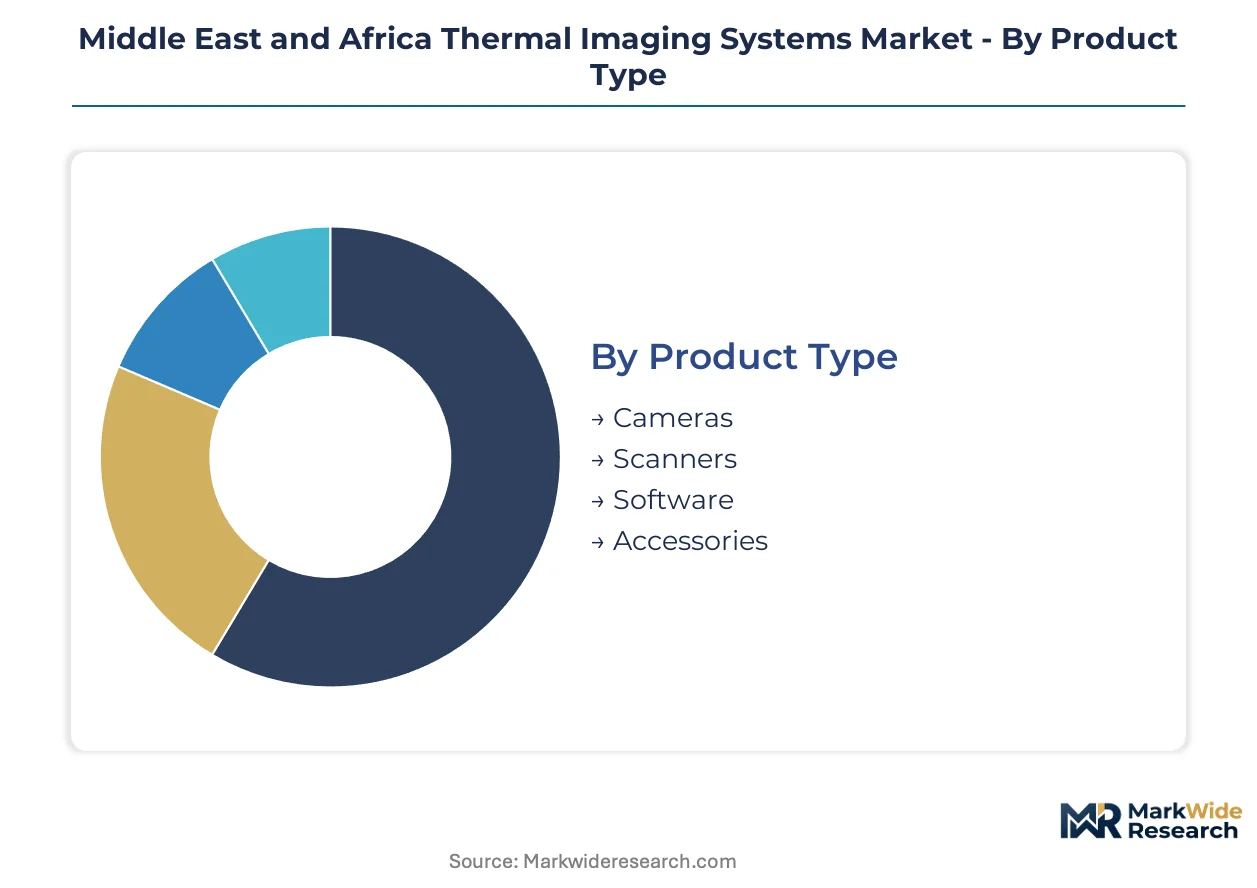
Thermal imaging procurement across the Middle East and Africa fragments sharply between volume-driven industrial monitoring and premium defense surveillance. Technology choices, end-use requirements, and application environments create distinct margin profiles that vendors must navigate through differentiated product architectures.
Product Type:
Cameras dominate unit shipments while software captures expanding recurring revenue attachment.
- Cameras:Uncooled focal plane array modules constitute the hardware backbone for border security and oilfield monitoring across Saudi Arabia and the UAE. Demand concentrates in fixed-mount perimeter installations where desert thermal cycling drives replacement cycles.
- Software:AI-enabled threat detection algorithms and predictive maintenance platforms are migrating revenue from one-time equipment sales to multi-year license agreements. Analytics bundles now attach to hardware procurement in Gulf Cooperation Council defense contracts.
- Scanners:Handheld thermal scanners serve industrial inspection and fever screening applications in South African mining and healthcare facilities.
- Accessories:Lens assemblies, protective housings, and calibration equipment support extended deployment lifespans in harsh climate conditions.
Mature deployment sits with cameras. Newer deployment is concentrated in software.
End User:
Military procurement anchors premium pricing while industrial adoption drives volume scaling.
- Military:National security agencies in Saudi Arabia and the UAE procure cooled detector arrays for long-range target identification. CITC cybersecurity certification requirements extend procurement timelines but lock in qualified vendors.
- Industrial:Oilfield operators across Kuwait and Qatar deploy uncooled modules for flare stack monitoring and pipeline inspection. Emirates Conformity Assessment Scheme compliance creates vendor selection barriers in critical infrastructure.
- Healthcare:Fever screening installations in South African hospitals and clinics utilize handheld thermal devices for infectious disease containment protocols.
- Environmental:Conservation authorities deploy thermal systems for wildlife monitoring and anti-poaching operations in East African reserves.
Volume concentration rests with industrial buyers. Premium margins concentrate with military procurement.
Technology:
Cost tier separation between uncooled volume production and cooled precision engineering defines competitive positioning.
- Uncooled:Vanadium oxide microbolometers eliminate cryogenic cooling mechanisms, reducing power consumption and maintenance requirements. Pixel pitch compression below 12 micrometers is absorbing industrial monitoring applications from legacy thermocouple networks.
- Cooled:Stirling cycle cooled detectors achieve noise-equivalent temperature difference below 20 millikelvin, enabling military-grade long-range surveillance. German and Japanese precision engineering specialists control cooler manufacturing, creating supply vulnerability.
- Hybrid:Dual-mode systems switch between cooled and uncooled operation based on mission requirements, serving border security agencies with variable-range detection needs.
- Advanced:Emerging technologies including quantum dot infrared photodetectors and type-II superlattice structures target next-generation sensitivity benchmarks.
Cost-sensitive deployment clusters around uncooled technology. Performance-critical applications concentrate in cooled systems.
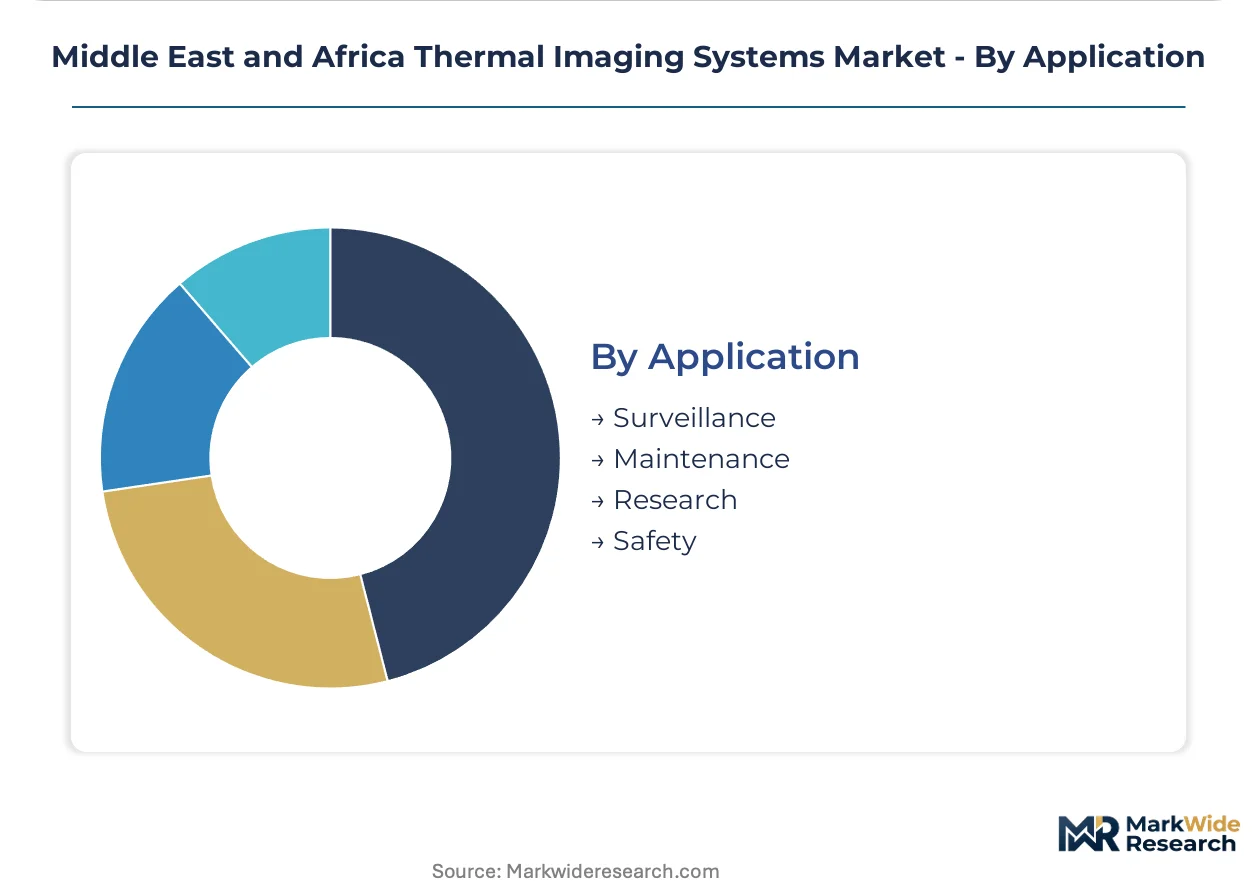
Application:
Surveillance infrastructure absorbs capital expenditure while maintenance applications generate recurring service revenue.
- Surveillance:Perimeter monitoring for airports, ports, and border crossings across the GCC states drives cooled infrared procurement. UAE mandatory certification schemes pre-qualify vendors for critical infrastructure contracts.
- Maintenance:Predictive thermal inspection of electrical substations and rotating machinery creates service contract opportunities for regional integrators with depot maintenance infrastructure.
- Research:Academic and meteorological institutions utilize calibrated thermal systems for climate monitoring and atmospheric studies.
- Safety:Fire detection and emergency response thermal imaging serves industrial facilities and urban emergency services.
Installed base maturity concentrates in surveillance. Service revenue expansion is concentrated in maintenance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Abu Dhabi's Khalifa Industrial Zone anchors thermal imaging manufacturing and integration activity for Gulf defense and oilfield clients, with Riyadh and Dubai forming secondary demand clusters for border security procurement.
Saudi Arabia
Defense procurement from the Ministry of Interior and Saudi Aramco drives cooled detector demand for perimeter surveillance and flare stack monitoring. The Communications and Information Technology Commission enforces cybersecurity certification on imported surveillance equipment, extending vendor qualification timelines. Riyadh's King Abdullah Financial District concentrates system integrators serving national security agencies.
United Arab Emirates
Airport and port security modernization across Dubai and Abu Dhabi sustains premium thermal camera procurement for critical infrastructure protection. The Emirates Conformity Assessment Scheme mandates certification for surveillance equipment, creating compliance barriers for uncertified suppliers. Dubai South's logistics corridor hosts regional depot maintenance facilities for Gulf Cooperation Council clients.
South Africa
Platinum and gold mining operations in the Bushveld Igneous Complex deploy thermal monitoring for conveyor belt inspection and predictive maintenance. The National Regulator for Compulsory Specifications enforces electromagnetic compatibility standards for industrial thermal devices. Johannesburg's industrial suburbs concentrate mining equipment suppliers pre-integrating certified modules.
Israel
Defense electronics exports and domestic border surveillance programs sustain demand for cooled infrared systems with sub-20 millikelvin sensitivity. The country's national security regulator imposes end-user verification protocols on dual-use thermal exports. Haifa's technology corridor hosts precision optics specialists serving military detector integration.
Kuwait
Oilfield operators across the Burgan Field deploy uncooled modules for pipeline leak detection and flare monitoring, displacing legacy thermocouple networks. The country's national oil company mandates equipment certification aligned with Gulf Cooperation Council technical standards. Ahmadi's industrial zone concentrates service providers for petrochemical thermal inspection contracts.
Middle East and Africa Thermal Imaging Systems Market Competitive Landscape
The competitive structure tilts toward vertically integrated sensor fabricators with captive microbolometer production and regional service infrastructure. European and North American defense electronics groups anchor premium-tier positioning through long-term technical support contracts with Gulf national security agencies. Three archetypes dominate: vertically integrated sensor manufacturers with in-house focal plane array fabrication; system integrators bundling hardware procurement with multi-year maintenance mandates; and specialized cooler engineering houses controlling Stirling cycle supply. Consolidation pressure concentrates around regional depot maintenance capabilities and Emirates Conformity Assessment Scheme pre-qualification status.
Among North American defense electronics groups, FLIR Systems Inc. and L3Harris Technologies Inc. occupy positions anchored by vertically integrated sensor production and Gulf service infrastructure. Leonardo S.p.A. represents European precision engineering specialization in cooled infrared technology. These three exemplify the premium-tier competitive vector where long-term technical support contracts and national security agency relationships determine vendor selection outcomes.
| Leading Market Players |
|---|
| FLIR Systems Inc. |
| Axis Communications AB |
| L3Harris Technologies Inc. |
| Leonardo S.p.A. |
| BAE Systems |
| Opgal Optronic Industries Ltd. |
| Thermoteknix Systems Ltd. |
| Infratec GmbH |
| Teledyne Technologies Incorporated |
| Others |
Supply & Pricing Matrix
Captive microbolometer fabrication within vertically integrated sensor houses anchors both supply security and premium pricing power for cooled infrared arrays serving Gulf defense ministries. This backward integration into focal plane array production insulates qualified vendors from silicon wafer foundry volatility while supporting value-based contracting for long-range surveillance deployments.
Pricing Analysis
Uptime-guarantee contracts anchor value-based pricing for military-grade cooled detector systems, with Saudi and UAE national security agencies paying premium rates for operational availability commitments. Price differentiation separates Emirates Conformity Assessment Scheme-certified suppliers from uncertified competitors, while software analytics bundles absorb hardware commoditization pressure in industrial segments. Cost compression in uncooled vanadium oxide modules intensifies as pixel pitch shrinks below 12 micrometers, making industrial buyers the most price-sensitive segment and defense agencies the least.
Supply Chain Analysis
Direct-to-agency channels handle hyperscale defense procurement across Riyadh and Abu Dhabi, bypassing distributor markups for national security contracts. German and Japanese precision engineering specialists concentrate Stirling cycle cooler manufacturing, creating single-source vulnerability for high-resolution military detector modules. Microbolometer fabrication draws from 8-inch silicon wafer supply chains centered in Taiwan, South Korea, and China, transmitting semiconductor cycle volatility into component pricing. Tariff exposure runs through dual-use export control classifications under US International Traffic in Arms Regulations and EU dual-use regulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cryogenic cooler manufacturing concentration among German and Japanese specialists props pricing for cooled infrared systems, constraining supply elasticity for defense procurement timelines. This bottleneck sustains premium margins for qualified vendors while extending qualification barriers for new entrants.
For Market Incumbents: Extend regional depot maintenance infrastructure across Dubai South and Riyadh to capture unbundled service contracts separating hardware ownership from predictive maintenance obligations. Deepen captive microbolometer fabrication to defend against silicon wafer foundry capacity constraints. Lock in Emirates Conformity Assessment Scheme pre-qualification status to exclude uncertified competitors from UAE critical infrastructure segments.
For New Entrants and Emerging Players: Cloud-based thermal analytics platforms offer low-capital entry into software-defined functionality migration, bypassing hardware fabrication barriers. Target Zambian and Democratic Republic of Congo mining corridors where thermal monitoring infrastructure remains underpenetrated. Establish local service presence in African extraction zones before incumbents consolidate maintenance relationships.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by North American and European defense electronics groups seeking regional service infrastructure. Long-term viability hinges on software recurring revenue attachment rates outpacing hardware commoditization. Watch for AI-enabled threat detection algorithm licensing deals as inflection indicators of margin pool migration from equipment to analytics.
| Strategic Initiative | Industry Significance |
|---|---|
| Regional Depot Maintenance Expansion | Captures unbundled service contracts from UAE border security programs requiring uptime guarantees. |
| Emirates Conformity Assessment Scheme Certification | Creates compliance moats against uncertified competitors in airport and port security segments. |
| AI-Enabled Analytics Platform Development | Shifts revenue from hardware sales to recurring license models for predictive maintenance applications. |
| African Mining Corridor Market Entry | Secures first-mover advantage in Zambia and DRC copper and cobalt extraction operations lacking thermal infrastructure. |
| Backward Integration into Microbolometer Fabrication | Insulates against 8-inch silicon wafer foundry capacity constraints affecting uncooled camera module supply. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with defense procurement officers at Saudi and UAE national security agencies, thermal systems integration engineers, and oilfield safety managers at Kuwait Petroleum Corporation. Defense ministry budget disclosures, CITC certification databases, and Emirates Authority for Standardization and Metrology compliance registries provided demand-side validation. Bottom-up equipment shipment tracking and top-down defense expenditure analysis were triangulated against industrial procurement patterns.
Data-stream reconciliation across technology tiers, end-user segments, and application environments shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include product architecture, cooling mechanism, detector sensitivity tier, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles and new procurement pipeline analysis. Forecast inputs incorporated desert climate degradation curves for focal plane arrays and AI analytics attachment rate trajectories.
The model holds under stable dual-use export licensing timelines; deviation in US ITAR or EU dual-use regulation enforcement would shift procurement cycle assumptions. Forecasts reflect documented base conditions around silicon wafer foundry capacity and cryogenic cooler supply availability. Periodic stress-testing of base assumptions is recommended given semiconductor cycle volatility and geopolitical friction in defense electronics trade.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Whole Slide Imaging Systems Market
Imaging
Acoustic Microscopy Market
Imaging
Facial Recognition Machine Market
Imaging
Digital X-Ray Technology Market
Imaging
Uncooled Infrared Imaging Market
Imaging
Multimodal Imaging Market
Imaging
Global Microscopy Market
Imaging
Global Thermal Imager Market
Imaging
Pico Projector Market
Imaging
Low-Light Imaging Market
Imaging
Printed Image Sensors Market
Imaging
Global Waterproof Camera Market
Imaging
Global Pathology Imaging Systems Market
Imaging
In Vivo Imaging Systems Market
Imaging
Thermal Imaging Camera Market
Imaging
Photoacoustic Tomography Market