
 Industrial IoT Market | 2026-2036
Industrial IoT Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial IoT Market Intelligence
A shift in purchasing power from IT departments to Operational Technology (OT) teams is redrawing the competitive landscape. This places a premium on solutions that integrate seamlessly with existing factory floor equipment. Siemens AG leverages its deep domain expertise in industrial automation to embed connectivity directly into its hardware. In contrast, Cisco Systems Inc. provides the foundational network infrastructure and security protocols required for reliable data transmission from the edge to the cloud.
Industrial Internet of Things (IIoT) refers to the network of interconnected sensors, instruments, and other devices integrated with industrial applications. These systems use protocols like MQTT or OPC-UA to gather real-time data for process optimization and automation. Within solution types, predictive maintenance is displacing traditional asset management due to its direct impact on uptime and operational costs. Cloud-based deployments are becoming standard for new projects, though hybrid models persist in sectors with stringent data residency requirements.
Regulatory frameworks significantly influence IIoT architecture and data handling protocols. The EU's GDPR and the upcoming EU AI Act impose strict requirements on data processing and algorithmic transparency for European operations. Concurrently, standards like ISO/IEC 27001 and security guidelines from the US's NIST provide a baseline for cyber-resilience in critical infrastructure. Navigating this complex compliance environment is now a central part of any large-scale IIoT deployment strategy.
Market Dynamics
The central force shaping the market is the transfer of purchasing authority from IT departments to Operational Technology (OT) teams. This shift prioritizes IIoT solutions that offer seamless integration with legacy factory machinery and demonstrate clear, immediate impact on production metrics like uptime and yield.
Growth Catalysts
- Predictive Maintenance Demand:Adoption within manufacturing, particularly in the automotive and heavy machinery sectors, is accelerating to reduce unplanned downtime and optimize maintenance schedules based on real-time asset health data.
- Regulatory Mandates:The European Union's Corporate Sustainability Reporting Directive (CSRD) compels large enterprises to deploy verifiable sensor networks for energy consumption and emissions tracking, directly driving investment in IIoT infrastructure.
- LPWAN Technology Maturation:The proliferation of Low-Power Wide-Area Networks enables cost-effective connectivity for massive sensor deployments across logistics, smart agriculture, and utility grids, expanding the addressable market beyond the factory floor.
Market Restraints
- Protocol Fragmentation:A lack of interoperability between proprietary communication protocols from different industrial automation vendors creates significant integration hurdles and increases the complexity and cost of deploying unified IIoT solutions.
- Data Governance Complexity:Strict regulations like the EU's GDPR and the upcoming AI Act impose rigorous requirements on data processing, residency, and algorithmic transparency, adding significant compliance overhead to multi-national deployments.
- High Retrofitting Costs:The substantial capital investment required to upgrade aging "brownfield" industrial sites with modern sensors, gateways, and network infrastructure acts as a significant barrier for many small and medium-sized enterprises.
Strategic Opportunities
- Digital Twin Expansion:Moving beyond single-asset monitoring, there is a significant opportunity in developing sophisticated digital twin models that simulate and optimize entire production lines or supply chains in real-time for enhanced operational intelligence.
- Edge-AI and 5G Convergence:The combination of private 5G networks and on-premise edge computing creates opportunities for ultra-low-latency applications, such as AI-powered machine vision for real-time quality control on high-speed manufacturing lines.
- Smart Manufacturing Initiatives:National programs like Germany's Industrie 4.0 and China's Made in 2025 provide direct government incentives, subsidies, and supportive frameworks that de-risk and encourage large-scale IIoT adoption in strategic industries.
Industry Challenges
- Hybrid Skills Scarcity:The industry faces a critical shortage of professionals who possess the integrated expertise spanning operational technology (OT) engineering, data science, and cybersecurity needed to design, deploy, and manage complex IIoT systems.
- Legacy System Integration:Integrating modern IIoT platforms with decades-old, isolated industrial control systems like SCADA and MES without causing production disruptions remains a primary operational challenge, particularly in established industrial plants.
- Expanding Cybersecurity Surface:Connecting previously air-gapped OT networks to corporate IT networks and the cloud dramatically increases vulnerability to cyberattacks, demanding robust security architectures compliant with standards like IEC 62443.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial IoT Market |
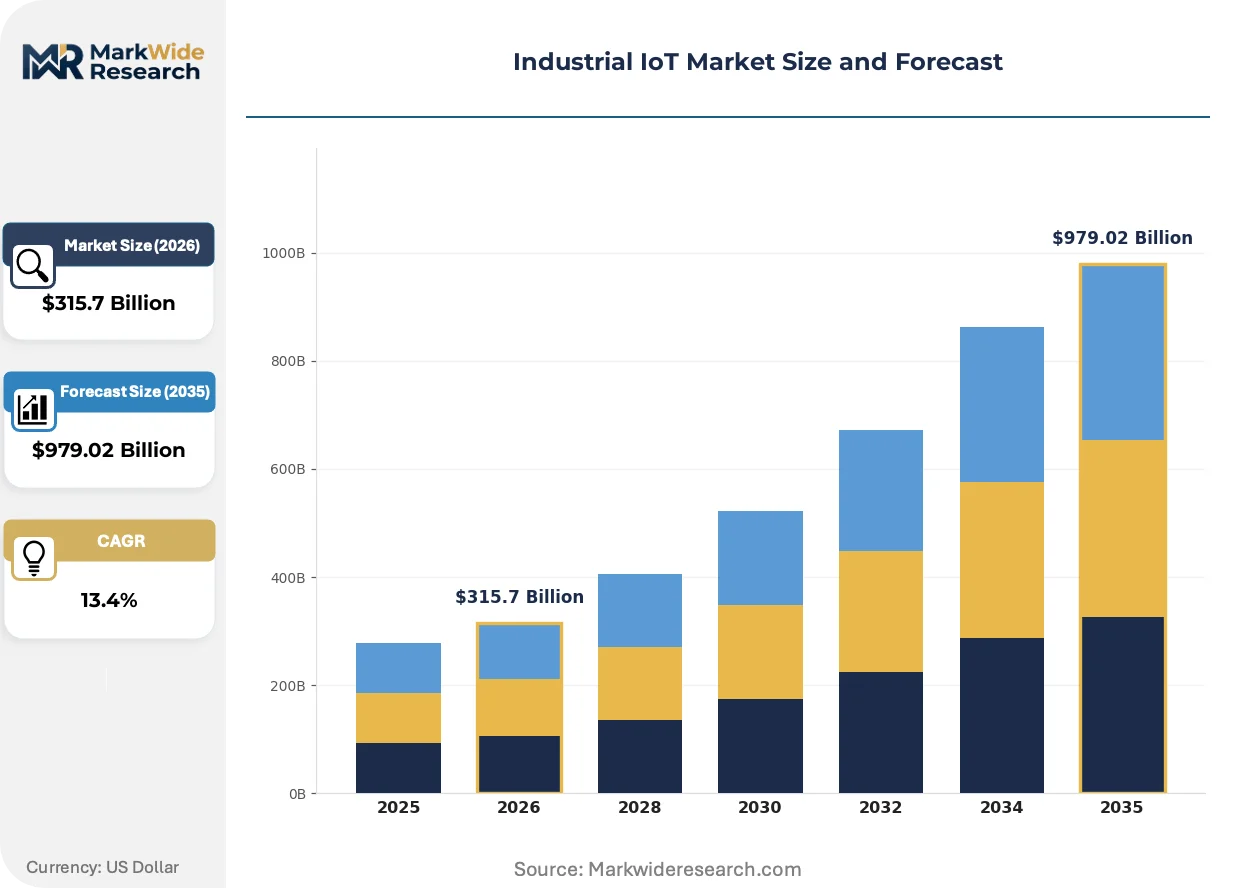
| Market Size in 2026 | $315.7 Billion |
| Market Size in 2035 | $979.02 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing, Fog Computing Solution Type: Asset Management, Predictive Maintenance, Inventory Tracking, Quality Control, Safety Management Application: Smart Manufacturing, Energy Management, Supply Chain Monitoring, Equipment Monitoring, Environmental Monitoring End User Industry Vertical: Manufacturing Plants, Utilities, Transportation Facilities, Oil & Gas Operators, Mining Companies |
| Companies Covered | Siemens AG, Cisco Systems Inc., ABB Ltd., Rockwell Automation Inc., Honeywell International Inc., General Electric, Intel Corporation, Microsoft, SAP SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial IoT Market Strategic Shifts & Innovations
The market's evolution is defined by the fusion of physical industrial assets with data-driven intelligence. This transformation turns immense volumes of raw sensor data into the predictive and prescriptive insights necessary for creating more autonomous, efficient, and resilient industrial operations across sectors.
Micro-Electro-Mechanical Systems (MEMS) sensors combine processing and sensing elements on a single silicon substrate to measure physical parameters like vibration and pressure. The aerospace and automotive industries are rapidly adopting these sensors for granular component-level health monitoring. The core technology is miniaturizing, enabling direct embedding into smaller machine parts like bearings or motor windings, which facilitates a level of asset intelligence previously unattainable.
In the United States, guidelines from the Cybersecurity and Infrastructure Security Agency (CISA) are establishing new performance goals for critical infrastructure sectors. These frameworks compel operators in energy, water, and transportation to implement stronger network segmentation and continuous threat monitoring within their OT environments. Consequently, the utilities sector is now prioritizing IIoT platforms that feature built-in compliance with security standards from bodies like NIST.
A definitive shift from one-time capital equipment sales toward subscription-based models for industrial machinery is underway. This change disrupts traditional OEM sales channels, as vendors increasingly offer "Equipment-as-a-Service" (EaaS) packages that bundle hardware, software, and ongoing maintenance. This trend is most prominent in heavy equipment and robotics, where customers pay for guaranteed uptime or production output rather than owning the physical asset outright.
Industrial IoT Market Segmentation
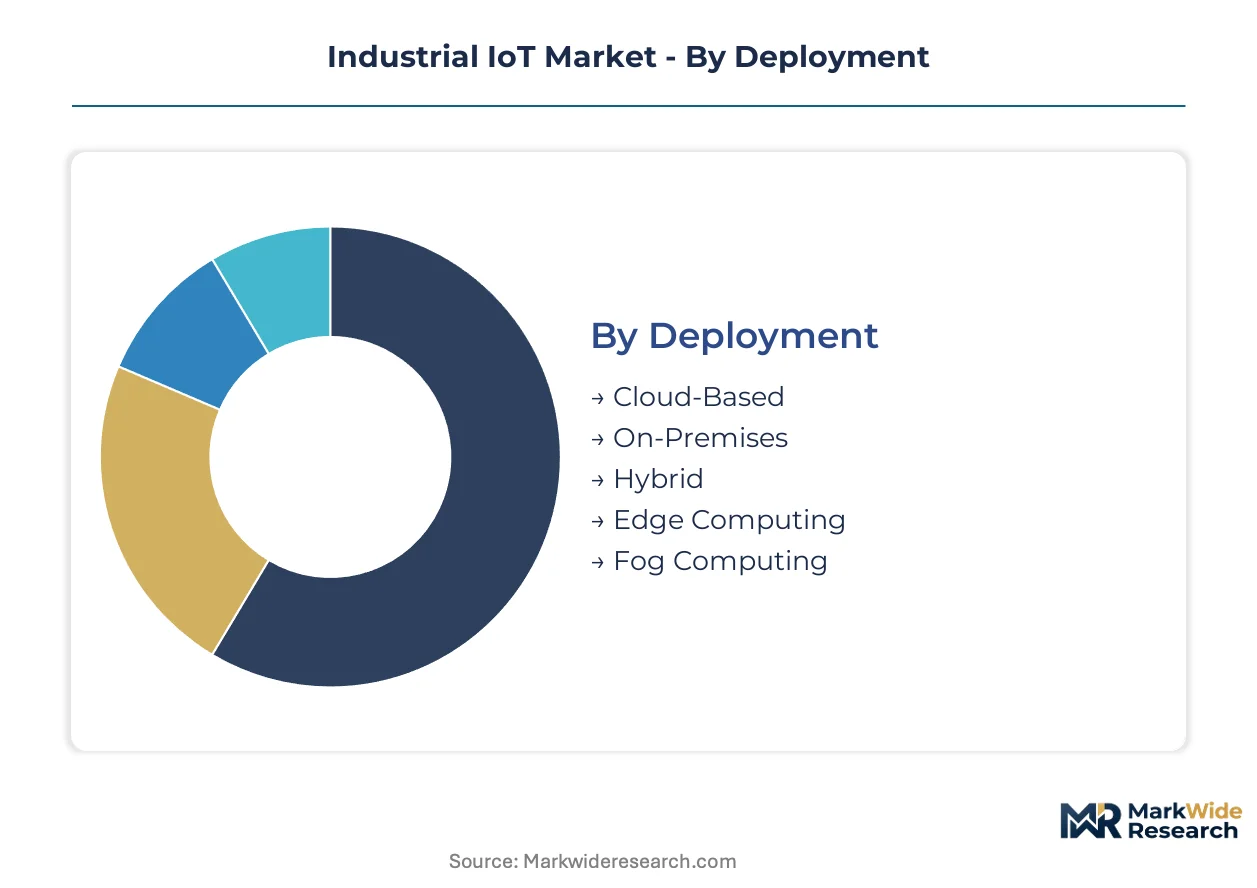
The Industrial IoT market structure reflects diverse technological approaches and operational priorities across industries. Understanding these distinct segments reveals how enterprises deploy IIoT solutions to enhance efficiency, drive automation, and meet evolving regulatory mandates. This granular view highlights concentrated investment and emerging technological shifts.
Deployment:
The deployment landscape faces significant substitution pressure, with distributed architectures challenging traditional centralized models. Enterprises evaluate options based on latency, data volume, and security posture.
- Cloud-Based:These deployments leverage remote servers for IIoT data storage and processing, offering scalability and reduced infrastructure costs. Demand concentrates in smart manufacturing for data analytics, driven by flexible, on-demand compute resources.
- Edge Computing:Data processing occurs closer to the source, reducing latency and bandwidth for real-time applications. This is critical in automotive manufacturing and robotics for instantaneous decision-making and AI-powered quality control.
- On-Premises:Solutions hosted within enterprise data centers ensure maximum control over data security.
- Hybrid:This model combines cloud and on-premises elements, balancing scalability with data residency.
- Fog Computing:Fog devices extend edge computing, acting as intermediaries to distribute processing power.
On-Premises deployments anchor the volume base while Edge Computing gains share at the steepest rate.
Solution Type:
Volume in IIoT solution types is heavily influenced by immediate operational pain points and regulatory compliance. Organizations prioritize solutions offering tangible returns through efficiency gains or risk mitigation.
- Predictive Maintenance:This solution uses sensor data and analytics to forecast equipment failures, enabling proactive maintenance and minimizing unplanned downtime. Manufacturing plants adopt this for optimizing asset lifespan.
- Asset Management:These solutions track location, status, and performance of physical assets, improving utilization and accountability. Utilities leverage this for extensive infrastructure monitoring.
- Inventory Tracking:Real-time monitoring of goods and materials enhances logistics efficiency and reduces stockouts.
- Quality Control:IIoT sensors and machine vision systems monitor production to detect defects and ensure product quality standards.
- Safety Management:These systems use connected devices to monitor environmental conditions and worker safety in hazardous industrial environments.
Predictive Maintenance and Asset Management drive the largest market value, with Inventory Tracking solutions expanding most quickly.
Application:
The maturity of IIoT applications varies, with smart manufacturing having established frameworks while others like environmental monitoring are developing. Adoption rates reflect this readiness.
- Smart Manufacturing:This application integrates IIoT devices, data analytics, and automation for efficient, flexible, and responsive production systems. Automotive manufacturers invest heavily to optimize lines and enhance product quality.
- Equipment Monitoring:Real-time data from industrial machinery is collected to assess performance, detect anomalies, and schedule maintenance. This is crucial for heavy machinery and oil & gas operations.
- Energy Management:IIoT sensors monitor energy consumption, enabling optimization and compliance with sustainability mandates like the EU's CSRD.
- Supply Chain Monitoring:Tracking goods in transit and storage provides visibility, optimizing logistics and improving inventory accuracy.
- Environmental Monitoring:Sensors measure air quality, water levels, and other parameters, supporting regulatory compliance and sustainable operations.
Smart Manufacturing maintains its lead in adoption, while Environmental Monitoring applications are experiencing the fastest expansion.
End User Industry Vertical:
The cost tier for IIoT deployments varies across industries, influenced by existing infrastructure, regulatory burden, and potential ROI. High capital intensity often justifies larger IIoT investments.
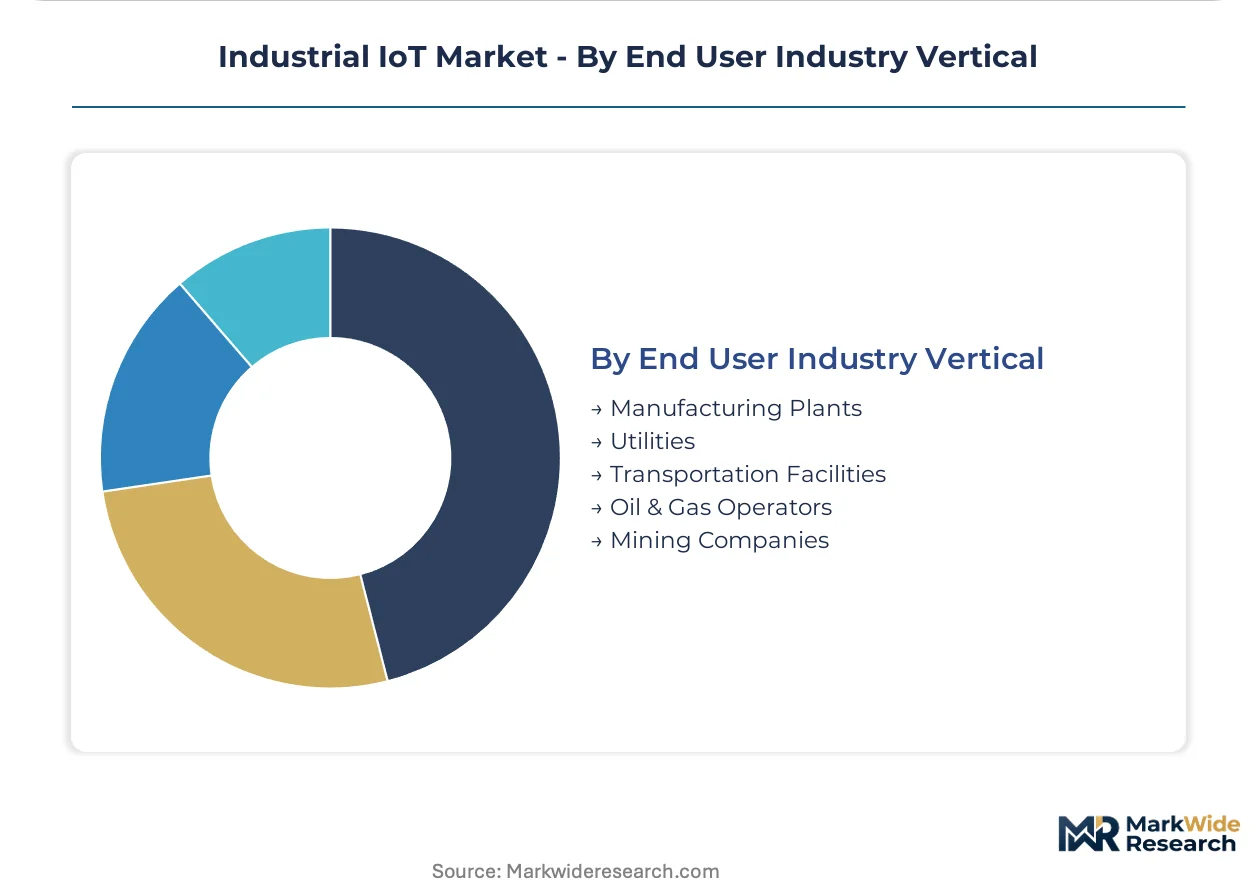
- Manufacturing Plants:This sector integrates IIoT for process automation, quality control, and predictive maintenance. German automotive sectors are prominent adopters for operational excellence and competitive advantage.
- Utilities:IIoT solutions enhance grid reliability, optimize energy distribution, and monitor critical infrastructure. US utilities prioritize IIoT for compliance with CISA guidelines and enhanced cyber-resilience.
- Transportation Facilities:IIoT improves logistics, fleet management, and asset tracking for ports, airports, and railway systems.
- Oil & Gas Operators:Remote monitoring of pipelines, drilling equipment, and refineries improves safety, reduces risks, and optimizes extraction.
- Mining Companies:IIoT sensors monitor equipment health, track personnel, and optimize resource extraction in challenging, remote environments.
Manufacturing Plants represent the largest segment by installed base, with Utilities showing significant momentum in IIoT adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The transfer of purchasing authority to Operational Technology (OT) teams concentrates IIoT investment in countries with mature industrial bases. These buyer archetypes prioritize solutions integrating seamlessly with existing factory floor equipment. This focus drives adoption in manufacturing-heavy nations across the globe.
Germany
Germany's advanced manufacturing sectors drive significant demand for predictive maintenance and smart factory solutions. The EU's Corporate Sustainability Reporting Directive (CSRD) compels German firms to deploy verifiable sensor networks for emissions tracking. Automotive and machinery sectors in Bavaria and Baden-Württemberg actively adopt IIoT for operational excellence and competitive advantage.
United States
Utilities in the United States prioritize IIoT for enhancing grid reliability and monitoring critical infrastructure. Guidelines from the Cybersecurity and Infrastructure Security Agency (CISA) establish performance goals for critical infrastructure sectors. The US manufacturing belt and Texas oil & gas operations integrate IIoT for enhanced safety, efficiency, and compliance with security standards.
China
Industrial hubs in China exhibit strong demand for smart manufacturing and supply chain monitoring applications. The national Made in 2025 initiative provides direct government incentives, encouraging large-scale IIoT adoption. Manufacturing clusters in the Yangtze River Delta and Pearl River Delta drive IIoT deployment for process automation and quality control.
Japan
Japanese industries demonstrate substantial demand for equipment monitoring and robotics integration within their sophisticated production lines. The Ministry of Economy, Trade and Industry (METI) actively promotes advanced manufacturing technologies through various supportive programs. Automotive and electronics manufacturers in the Kanto region and Aichi Prefecture deploy IIoT for precision production and anomaly detection.
India
Expanding manufacturing capabilities in India fuel demand for asset management and energy optimization solutions. The Production Linked Incentive (PLI) scheme supports domestic manufacturing, thereby encouraging IIoT adoption across various industries. Industrial corridors in Maharashtra and Gujarat utilize IIoT for process optimization, resource tracking, and improving overall operational efficiency.
Industrial IoT Market Key Industry Players
Player mix skews toward established industrial automation vendors and IT infrastructure providers, reflecting the hybrid nature of IIoT deployment. The market exhibits a tiered structure, with large conglomerates alongside specialized software developers and hardware manufacturers. Strategic archetypes include integrated solution providers, network infrastructure specialists, and niche analytics platforms. Dominant competitive moves involve strategic partnerships to bridge OT-IT gaps and portfolio diversification into edge AI capabilities.
Within the integrated solution providers archetype, Germany-based Siemens AG exemplifies deep domain expertise in industrial automation, offering embedded connectivity directly within its hardware. US-based Cisco Systems Inc. anchors the foundational network infrastructure segment, providing essential security protocols and reliable data transmission from edge to cloud. Switzerland-based ABB Ltd. also occupies a position among the established industrial technology providers, representing comprehensive offerings for process optimization and asset management across diverse sectors. These entities underscore the market's reliance on vendors capable of delivering robust, secure, and scalable IIoT ecosystems.
| Leading Market Players |
|---|
| Siemens AG |
| Cisco Systems Inc. |
| ABB Ltd. |
| Rockwell Automation Inc. |
| Honeywell International Inc. |
| General Electric |
| Intel Corporation |
| Microsoft |
| SAP SE |
Cost & Logistics Intelligence
The EU AI Act, with its strict requirements for algorithmic transparency and data processing, gates supply qualification and price differentiation for IIoT solutions within European operations. This regulatory framework influences how vendors develop and price their AI-powered edge computing offerings.
Pricing Analysis
Cost-plus contract patterns, often indexed to component costs like MEMS sensors and microcontrollers, frequently govern large-scale IIoT infrastructure deployments. Project-based pricing dominates for complex system integrations, reflecting the high customization and engineering effort involved. Price differentiation stems from the level of integration with legacy OT systems and the depth of cybersecurity compliance, such as adherence to IEC 62443 standards. Pricing pressure stems from the increasing commoditization of basic sensor hardware, particularly for non-critical monitoring tasks. Small and medium-sized enterprises (SMEs) exhibit the highest price sensitivity, whereas critical infrastructure operators prioritize reliability and compliance over cost.
Supply Chain Analysis
Port congestion in major Asian logistics hubs and fluctuating container availability drive inbound logistics costs for IIoT hardware components. Geographic supply concentration for critical components centers on East Asia, particularly China for microcontrollers and passive components, and Germany for specialized industrial automation hardware. The IIoT market depends on a steady supply of MEMS sensors, industrial-grade microprocessors, and specialized communication modules. A structural risk exists in geopolitical tensions affecting semiconductor supply, creating single-source vulnerabilities for advanced processing units. Downstream distribution runs through a network of system integrators and value-added resellers, particularly for complex, customized deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
A critical shortage of integrated expertise spanning operational technology, data science, and cybersecurity creates capability gaps across the Industrial IoT market. This scarcity necessitates strategic interventions to build and retain specialized talent for complex deployments.
For Market Incumbents:
Secure advanced software development capabilities through targeted acquisitions of niche AI/ML analytics firms. Deepen platform integration with existing industrial control systems to counter emerging specialized software entrants. Invest significantly in cybersecurity R&D to maintain compliance with evolving standards like NIST and CISA guidelines, mitigating threats from increasingly sophisticated cyberattacks. Prioritize talent development programs that blend OT engineering with data science skills, addressing the hybrid skills scarcity.
For New Entrants and Emerging Players:
Differentiate on specialized application expertise, targeting underserved verticals like smart agriculture or environmental monitoring. Focus on providing solutions that address specific regulatory compliance needs, for instance, verifiable emissions tracking for CSRD mandates. The brownfield retrofitting segment, particularly for small and medium-sized enterprises, represents a penetrable white space. Adopt a "solution-as-a-service" go-to-market angle, bundling hardware, software, and ongoing maintenance to lower upfront capital expenditure for customers.
For Investors and Strategic Acquirers:
Capital-intensity ratios are inflecting upward across the edge computing and private 5G infrastructure segment, indicating significant long-term growth potential. The market exhibits sustained viability over the next decade, driven by ongoing digital transformation and regulatory mandates for efficiency and sustainability. Acquisition targets should focus on firms specializing in secure data orchestration, AI-powered predictive analytics, or those with deep expertise in specific industrial communication protocols like OPC-UA. A key signal to watch is the increasing standardization of IIoT protocols, which will streamline integration and accelerate adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration with Legacy Systems | Ensures seamless operation within existing factory environments, reducing disruption for manufacturers. |
| Acquisition of Edge AI Specialists | Enhances real-time data processing capabilities at the source, critical for autonomous operations. |
| Development of Cybersecurity-as-a-Service | Addresses expanding vulnerability surfaces by offering continuous threat monitoring for OT networks. |
| Strategic Partnerships for 5G Connectivity | Leverages private 5G networks for ultra-low-latency applications in advanced manufacturing. |
| Talent Development in Hybrid OT/IT Skills | Mitigates the critical shortage of professionals capable of managing complex IIoT ecosystems. |
Research Approach
A standing panel of OT engineers, IT security architects, plant managers, and data scientists provided ongoing calibration for market sizing and trend validation. This involved combining primary interviews with these industry stakeholders and rigorous secondary validation against public data. Secondary sources included industrial association reports, government industrial policy documents, and technology vendor whitepapers, ensuring robust data triangulation.
Market volume and value outputs underwent consistency checks against external benchmarks across the analysis window. The analytical framework modeled segmentation dimensions including deployment model, solution type, application, end-user industry vertical, and regional market maturity. Compound annual growth rates were derived from historical data extrapolation and forward-looking projections based on key industry-specific forecast inputs, such as capital expenditure in manufacturing and regulatory compliance deadlines.
Material uncertainties — geopolitical instability affecting supply chains and faster-than-expected technological disruption — sit outside the modeled envelope of this study. Forecasts reflect assumptions documented through extensive primary and secondary research. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Smart Connected Device Market
Internet of Things (IoT)
Global Internet of Things (IoT) Software Market
Internet of Things (IoT)
IoT Gateway Devices Market
Internet of Things (IoT)
Global Residential Smart Thermostats Market
Internet of Things (IoT)
UK IoT Software Market
Internet of Things (IoT)
Wifi IoT Market
Internet of Things (IoT)
IoT at Workplace Market
Internet of Things (IoT)
IoT Connected Machines Market
Internet of Things (IoT)
Healthcare M2M Market
Internet of Things (IoT)
Narrowband-Internet of Things (NB-IoT) Market
Internet of Things (IoT)
Connected IoT Devices Market
Internet of Things (IoT)
North America and Europe IoT Gateway Market
Internet of Things (IoT)
Satellite IoT Communication Market
Internet of Things (IoT)
IoT for Cold Chain Monitoring Market
Internet of Things (IoT)
GCC Indoor LBS Market
Internet of Things (IoT)
Airline IoT Market