
 UK IoT Software Market | 2026-2036
UK IoT Software Market Size, Share, and Industry Trends Forecast 2026-2036
UK IoT Software Market Intelligence
A divergence in capital allocation for platform development versus specialized connectivity services is rotating the competitive landscape in the UK. Global hyperscalers like Microsoft Corp. leverage vast cloud infrastructure to offer integrated analytics and device management suites. In contrast, UK-based specialists such as Eseye Ltd. focus on global cellular connectivity management for specific IoT deployments. Arm Ltd. anchors its position through its pervasive processor architecture and associated software development ecosystems.
IoT software comprises platforms and applications that manage, process, and analyze data from connected physical objects, often using lightweight protocols like MQTT for efficient transmission. Its primary purpose is to translate raw sensor data into actionable intelligence for automation and business decision-making. Within solution offerings, data analytics and security software command premium value due to their complexity and impact on operational outcomes. The manufacturing vertical shows high adoption, driven by use cases in predictive maintenance and supply chain visibility.
The regulatory environment in the UK is shaped by the Product Security and Telecommunications Infrastructure (PSTI) Act, which mandates baseline security standards for consumer IoT devices. Concurrently, compliance with data protection principles enforced by the Information Commissioner's Office (ICO) governs how personal data from connected systems is handled. Vendor selection will increasingly hinge on a provider's ability to demonstrate robust security compliance and deliver scalable, industry-specific analytics capabilities.
Market Dynamics
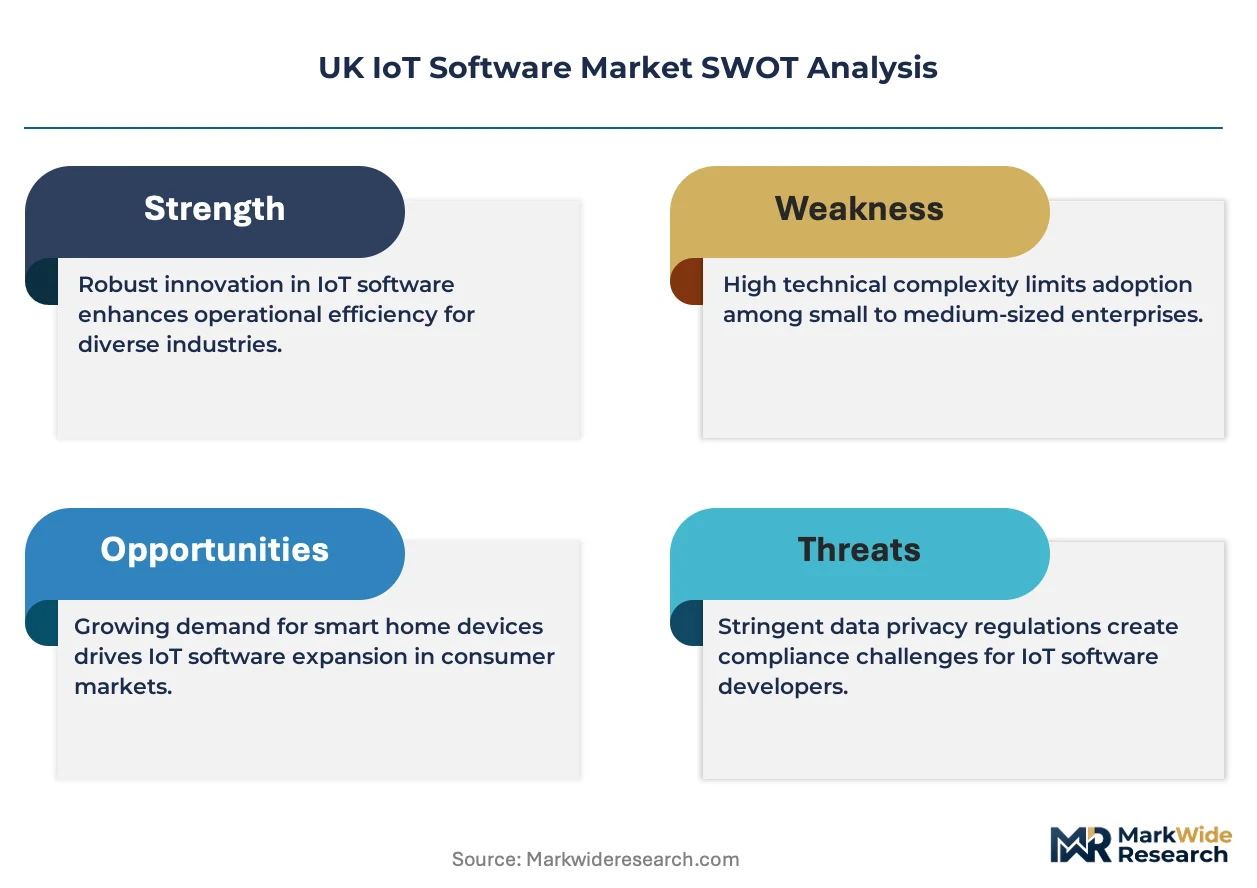
The primary structural force shaping the UK market is the bifurcation between security compliance and advanced analytics. The PSTI Act mandates a baseline for security, while competitive advantage increasingly comes from sophisticated, industry-specific data processing capabilities, creating a two-tiered value structure.
Growth Catalysts
- Industrial Digitalisation Policies:UK government initiatives promoting Industry 4.0 and the Made Smarter programme encourage manufacturers in regions like the North West to invest in IoT software for predictive maintenance and operational efficiency.
- Smart Infrastructure Investment:Public and private investment in smart cities and national 5G network deployment creates foundational infrastructure that supports large-scale IoT software applications in transport, utilities, and public services.
- Digital Twin Technology:Adoption of digital twin software in the UK's aerospace, automotive, and construction sectors allows for complex simulation and asset performance management, driving demand for high-fidelity IoT data integration platforms.
Market Restraints
- Legacy System Interoperability:Many UK industrial sites operate on aged operational technology (OT) systems, and the cost and complexity of integrating them with modern IoT software platforms presents a significant barrier.
- Data Governance Ambiguity:Post-Brexit uncertainty regarding cross-border data transfer regulations and alignment with EU data adequacy rules creates compliance risks for companies using cloud-based IoT platforms hosted outside the UK.
- High Implementation Costs:The total cost of ownership for enterprise-grade IoT solutions, including software, hardware, integration services, and specialized data science talent, remains a considerable restraint for many small and medium-sized enterprises.
Strategic Opportunities
- ESG and Sustainability Reporting:IoT software offers a clear opportunity to automate the collection and analysis of data for environmental, social, and governance (ESG) reporting, helping UK firms meet regulatory and investor demands for carbon accounting.
- Agri-Tech Sector Penetration:The UK's agriculture sector remains comparatively underpenetrated by IoT solutions, presenting a significant white space for software focused on precision farming, livestock monitoring, and supply chain traceability.
- Edge AI Integration:The convergence of IoT platforms with edge artificial intelligence allows for real-time data processing on-device, creating opportunities for applications in autonomous systems and remote asset monitoring where low latency is critical.
Industry Challenges
- Cybersecurity Skills Gap:A persistent shortage of cybersecurity professionals with expertise in securing connected operational technology and IoT ecosystems challenges vendors and end-users in implementing secure-by-design principles.
- Platform Fragmentation:The high number of disparate IoT platforms and communication protocols complicates the development of a unified data strategy, leading to data silos and increased integration costs for end-users.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK IoT Software Market |
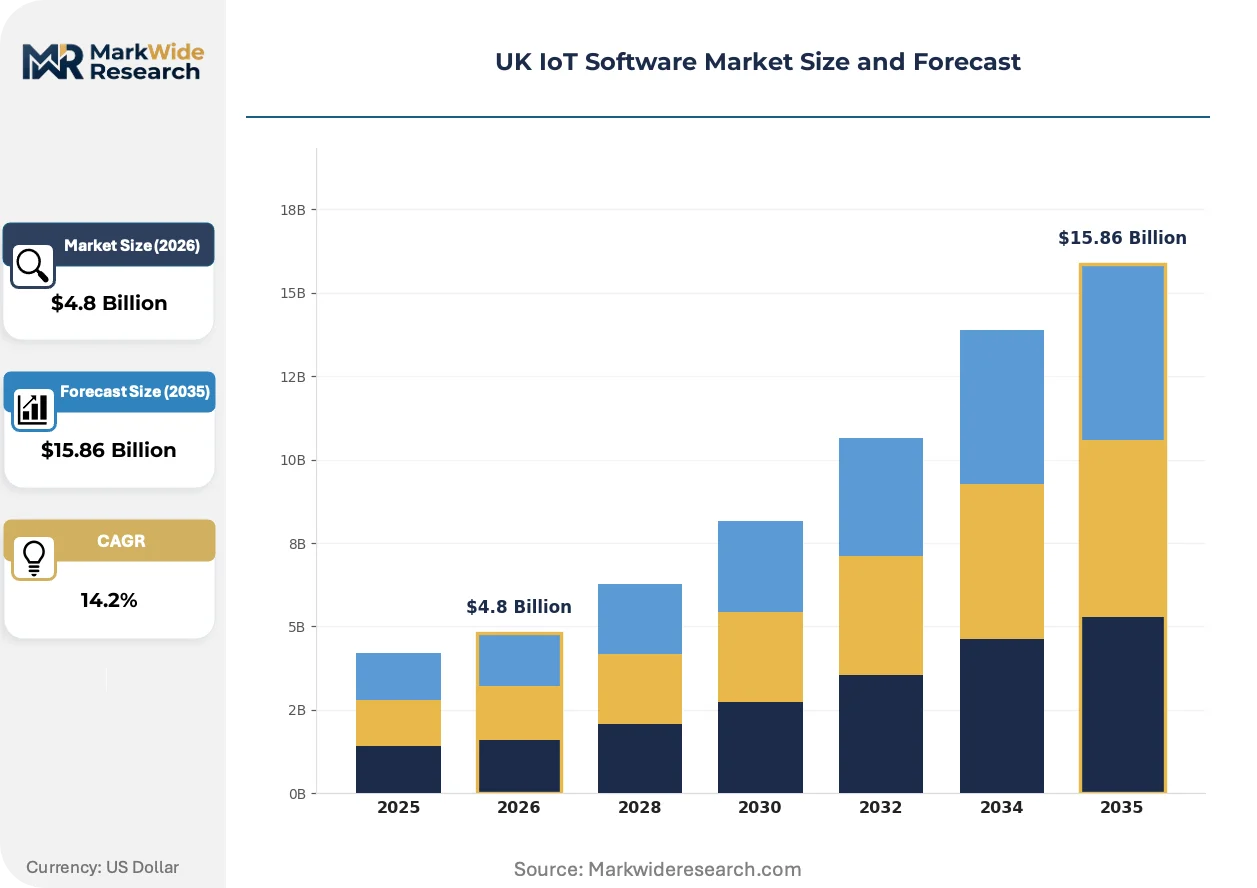
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Edge Computing Solution Offering: Device Management, Data Analytics, Security, Connectivity Management, Application Enablement Use Case: Smart Buildings, Asset Tracking, Predictive Maintenance, Supply Chain Visibility, Environmental Monitoring End User Industry Vertical: Manufacturing, Transportation, Agriculture, Utilities, Energy Production |
| Companies Covered | Arm Ltd., Eseye Ltd., EVRYTHNG Ltd., Microsoft Corp., Amazon.com Inc., Oracle Corp., Intel Corp., Cisco, IBM, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK IoT Software Market Strategic Shifts & Innovations
Innovation is shifting from horizontal platform capabilities to vertically-specialized solutions that address specific industrial outcomes. This move is driven by enterprise demand for demonstrable return on investment and regulatory pressures that elevate the importance of security and data provenance within IoT software stacks.
Tiny Machine Learning (TinyML) enables sophisticated data processing and pattern recognition to run directly on low-power microcontrollers embedded within IoT devices. Electronics designers and industrial sensor manufacturers in the UK are adopting this technology to improve response times and enhance data privacy by minimizing raw data transmission. This development is decomposing the monolithic, cloud-dependent architecture of early IoT systems, distributing intelligence to the network edge.
The Product Security and Telecommunications Infrastructure (PSTI) Act creates a new regulatory floor for cybersecurity in the UK. This legislation mandates that manufacturers of consumer-facing connectable devices, from smart speakers to home security cameras, adhere to baseline security standards like banning universal default passwords. The consumer electronics software segment is most affected, now required to embed security features and transparent vulnerability disclosure processes directly into product development cycles.
A notable demand-side evolution is the move from perpetual software licensing to consumption-based pricing models. This trend disrupts the traditional enterprise sales cycle, favoring platform providers that can offer flexible, pay-as-you-go terms tied to metrics like device count or data volume. This procurement model is particularly visible within the UK's logistics and smart building management sectors, where project scopes often require scalable and predictable operational expenditures.
UK IoT Software Market Segmentation
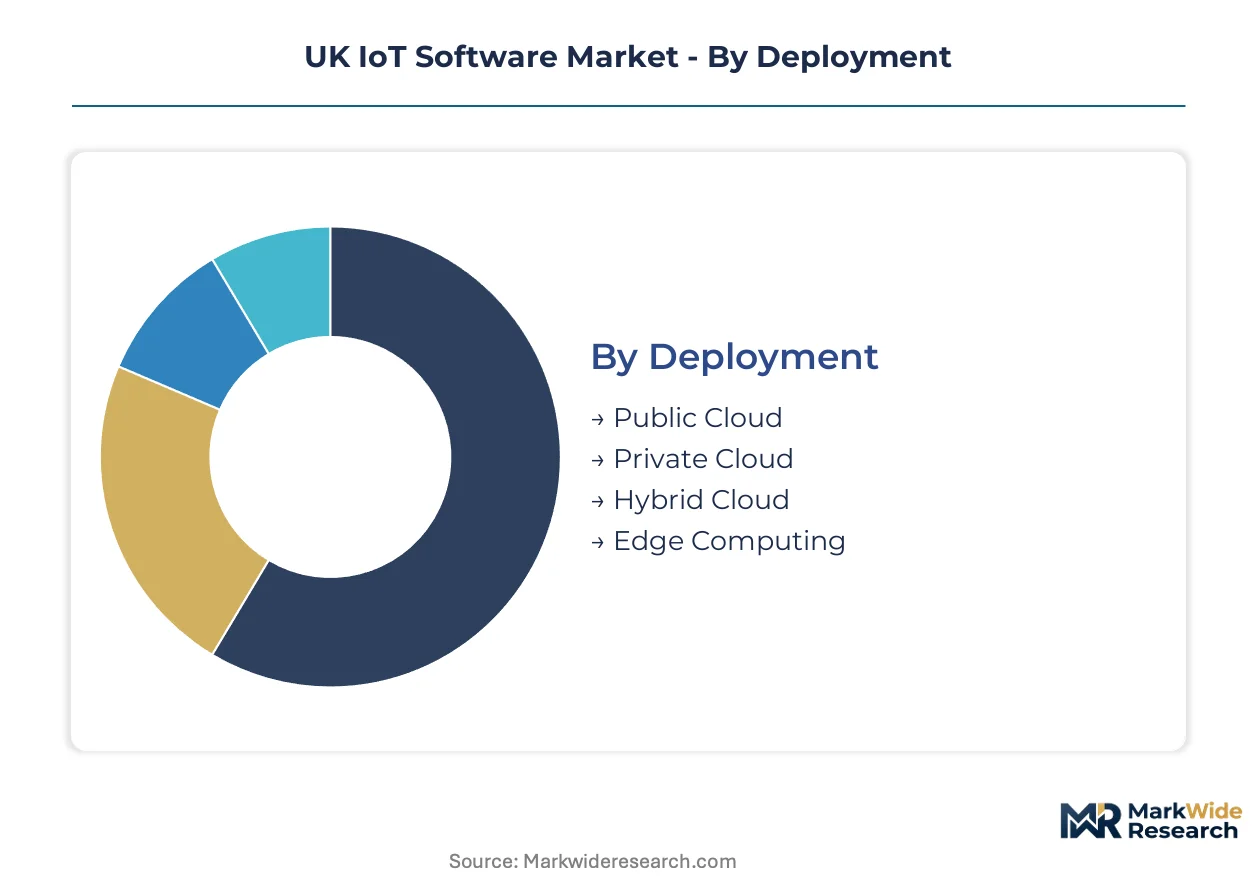
The UK IoT software market exhibits diverse requirements and adoption patterns across its various segments, reflecting specific operational needs and technological maturity levels. Understanding these segment dynamics is crucial for providers aiming to align their offerings with the distinct demands of UK industries.
Deployment:
The channel-mix for IoT software deployment in the UK varies based on data sensitivity, processing needs, and infrastructure preferences of end-user organizations.
- Public Cloud:This deployment model leverages shared, scalable infrastructure provided by global hyperscalers, offering flexibility and reduced capital expenditure for UK businesses. Demand concentrates within London's technology ecosystem and general enterprise adoption for integrated analytics and device management.
- Edge Computing:Processing data closer to the source, edge computing minimizes latency and bandwidth usage, enabling real-time decision-making for connected devices. Demand for this model is significant in UK critical national infrastructure and autonomous systems requiring immediate data processing.
- Private Cloud:Dedicated infrastructure hosts IoT software for enhanced security and control, often preferred by UK organizations handling highly sensitive data or requiring stringent compliance.
- Hybrid Cloud:This model combines the benefits of both public and private cloud environments, offering a flexible approach for UK enterprises managing diverse IoT workloads and data types.
Public Cloud platforms dominate the installed base across UK enterprises. Edge Computing is where expansion concentrates, driven by demand for real-time processing.
Solution Offering:
The value proposition across solution offerings varies significantly, influencing procurement decisions for UK enterprises.
- Data Analytics:These solutions extract actionable insights from raw IoT sensor data, employing advanced algorithms for pattern recognition and predictive modeling. This offering commands premium value due to its impact on operational outcomes, particularly in UK manufacturing for predictive maintenance.
- Security:Security software protects connected devices, networks, and data from cyber threats, ensuring compliance with regulations like the UK's PSTI Act and data protection principles. This segment is critical for consumer electronics and critical national infrastructure within the UK.
- Device Management:This category encompasses software for monitoring, configuring, and maintaining the lifecycle of IoT devices, from provisioning to firmware updates for UK IoT deployments.
- Connectivity Management:Specialists like Eseye Ltd. provide global cellular connectivity management, enabling seamless communication for specific IoT deployments across the UK and internationally.
- Application Enablement:These platforms provide tools and frameworks that accelerate the development and deployment of customized IoT applications for various UK industry verticals.
Data Analytics solutions drive significant operational improvements, while Security software mitigates increasing regulatory and cyber risks for UK firms.
Use Case:
Specific application areas define the immediate operational benefits and adoption patterns within the UK IoT software market.
- Predictive Maintenance:Utilizing AI and machine learning algorithms, this use case analyzes sensor data from industrial assets to forecast potential equipment failures, minimizing downtime. UK manufacturing facilities widely adopt predictive maintenance to optimize operational efficiency and extend asset lifespans.
- Supply Chain Visibility:This application tracks goods and assets in real-time across the entire logistics chain, providing transparency and improving inventory management. UK logistics and retail sectors leverage this for enhanced traceability and operational optimization.
- Smart Buildings:IoT software integrates various building systems to optimize energy consumption, enhance occupant comfort, and improve facility management in UK commercial and public infrastructure.
- Asset Tracking:Solutions in this segment monitor the location and status of valuable physical assets, which is crucial for UK transport, construction, and field service industries.
- Environmental Monitoring:This use case involves deploying IoT sensors to collect data on air quality, water levels, and pollution, supporting sustainability initiatives in UK urban and agricultural settings.
Predictive Maintenance solutions are widely implemented in industrial settings, with Supply Chain Visibility gaining traction across UK logistics.
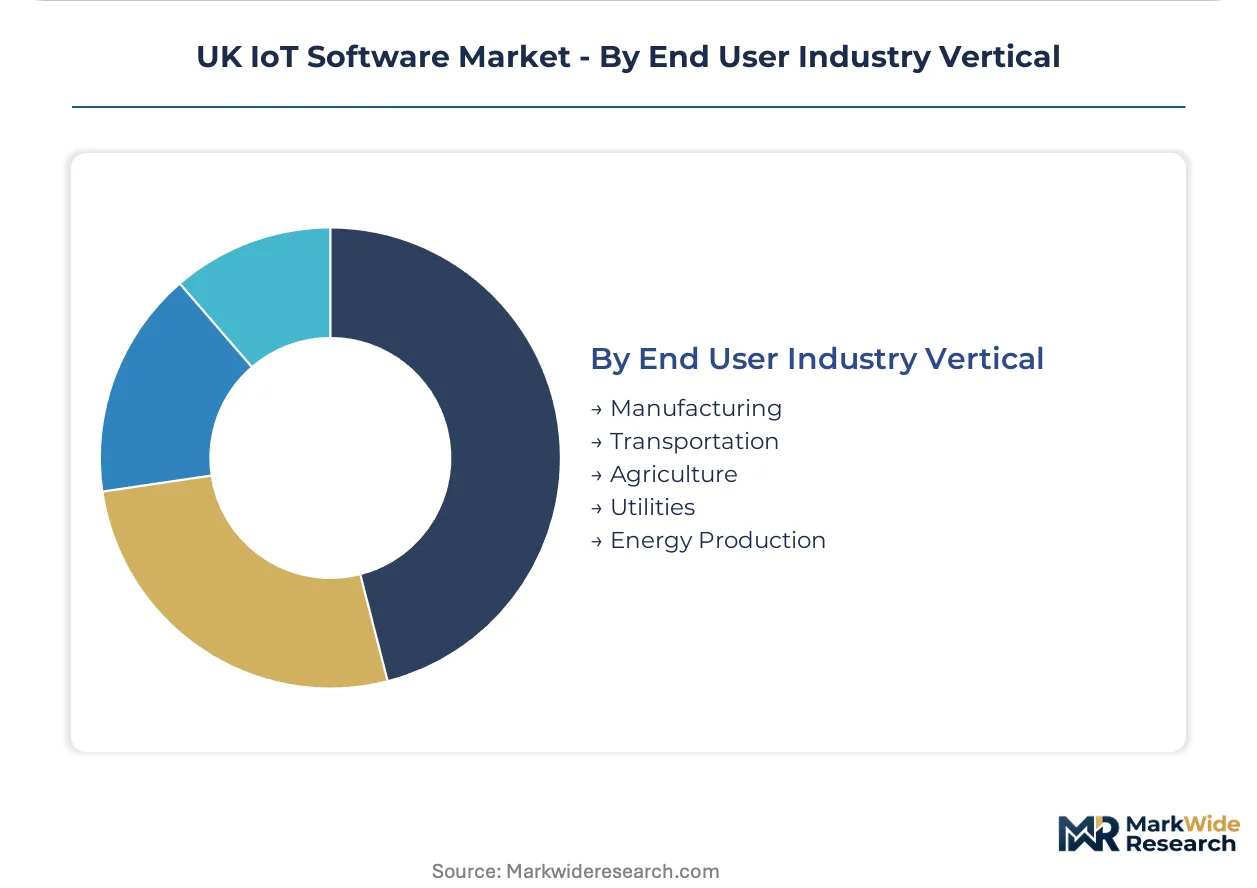
End User Industry Vertical:
Different customer types across industry verticals exhibit distinct requirements for UK IoT software solutions.
- Manufacturing:This vertical shows high adoption of IoT software for applications such as predictive maintenance, quality control, and process automation, aligning with UK Industry 4.0 initiatives. The Made Smarter programme in regions like the North West specifically encourages this investment.
- Agriculture:The UK's agriculture sector remains comparatively underpenetrated, presenting a significant opportunity for IoT software focused on precision farming, livestock monitoring, and supply chain traceability. This supports efficiency and sustainability reporting.
- Transportation:IoT software supports fleet management, smart traffic systems, and logistics optimization, enhancing efficiency and safety across UK road, rail, and maritime networks.
- Utilities:This sector utilizes IoT for smart metering, grid management, and infrastructure monitoring, improving service delivery and operational resilience for UK power, gas, and water providers.
- Energy Production:IoT solutions are deployed for monitoring renewable energy assets, optimizing performance, and managing traditional power generation facilities throughout the UK.
Manufacturing represents a mature vertical for IoT software deployment, while Agriculture offers substantial growth potential for UK providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
A notable pricing-power asymmetry characterizes the UK IoT software market, with premium value concentrated in London's advanced technology ecosystem. In contrast, the industrial corridors of the Midlands prioritize cost-effective solutions for operational efficiency. This divergence reflects distinct demands for specialized analytics versus scalable, integration-focused platforms across UK regions.
London/Southeast
Demand for advanced analytics and security software is high within London's financial and technology sectors. The PSTI Act mandates robust security standards, influencing procurement decisions for connected devices. London's vibrant technology ecosystem drives innovation in integrated analytics and device management suites.
Midlands
Industrial digitalization initiatives drive significant demand for predictive maintenance solutions across the Midlands' manufacturing base. The Made Smarter programme encourages investment in IoT software for process optimization. Major industrial clusters in Birmingham and Coventry are adopting digital twin technologies to enhance asset performance management.
North West
Government programs like Made Smarter directly stimulate IoT software adoption among manufacturers in the North West. Compliance with data protection principles enforced by the ICO is a critical factor for regional enterprises. Cities such as Manchester and Liverpool are becoming hubs for smart infrastructure investment, supporting large-scale IoT applications.
Scotland
Investment in smart cities and renewable energy projects fuels demand for IoT software in Scotland. The UK's commitment to ESG reporting creates opportunities for environmental monitoring solutions. Glasgow and Edinburgh are developing integrated platforms for utilities and public services, leveraging foundational 5G network deployments.
UK IoT Software Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the UK IoT software market. The competitive landscape is tiered, with global hyperscalers offering broad, integrated platforms alongside specialized providers focusing on niche connectivity or industry-specific analytics. Strategic partnerships and targeted portfolio diversification are common competitive moves as firms seek to expand their market reach and solution breadth.
Global technology providers and specialized connectivity firms define the competitive dynamics, with Microsoft Corp. exemplifying the hyperscaler model offering vast cloud infrastructure and integrated analytics platforms. UK-based Eseye Ltd. occupies a position as a specialist in global cellular connectivity management, catering to specific IoT deployments. Arm Ltd. anchors its market presence through its pervasive processor architecture and associated software development ecosystems, influencing device-level software innovation across the ecosystem.
| Leading Market Players |
|---|
| Arm Ltd. |
| Eseye Ltd. |
| EVRYTHNG Ltd. |
| Microsoft Corp. |
| Amazon.com Inc. |
| Oracle Corp. |
| Intel Corp. |
| Cisco |
| IBM |
| Others |
Cost & Logistics Intelligence
The Product Security and Telecommunications Infrastructure (PSTI) Act gates both supply qualification and price differentiation simultaneously, particularly for consumer-facing IoT devices. This regulatory framework necessitates higher security standards from suppliers, influencing the cost structure across the UK market.
Pricing Analysis
Configured-to-order solutions command a premium over standard offerings, reflecting the customization level required for specific industrial outcomes. Consumption-based pricing models, tied to device count or data volume, are gaining traction within UK logistics and smart building management sectors. Price differentiation stems from the complexity of data analytics capabilities and the level of security compliance embedded in the software. Pricing softness impacts commoditized device management tools, while advanced analytics for predictive maintenance maintain premium value. Small and medium-sized enterprises (SMEs) exhibit higher price sensitivity compared to large enterprises in critical national infrastructure.
Supply Chain Analysis
The UK IoT software supply chain draws from global hyperscalers like Microsoft Corp. for cloud infrastructure, while UK-based specialists such as Eseye Ltd. anchor global cellular connectivity management. Arm Ltd. provides pervasive processor architecture, influencing device-level software innovation. Key dependencies include semiconductor components for devices and specialized software talent. A structural supply chain risk is the cybersecurity skills gap, challenging secure-by-design principles across the ecosystem. Distribution runs through direct enterprise sales for complex solutions and cloud marketplaces for more standardized offerings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK IoT software market represents a defensive-moat story, primarily due to the regulatory entrenchment created by the PSTI Act. This legislation establishes a baseline for security, increasing switching costs for compliant solutions.
For Market Incumbents: Fortify core platform capabilities by investing in advanced, industry-specific analytics and robust security features. This helps counter the threat of platform fragmentation and the rise of specialized edge AI solutions. Deepen vertical specialization within high-value sectors like manufacturing and critical national infrastructure. Strategic partnerships can extend connectivity reach and bolster compliance offerings, reducing overall operational risk.
For New Entrants and Emerging Players: Differentiate on niche vertical expertise and outcome-based pricing models. Target the underpenetrated Agri-Tech sector with precision farming and supply chain traceability solutions, offering clear return on investment. Focus on developing edge AI integrations that provide real-time processing benefits for specific industrial problems, addressing low-latency requirements in autonomous systems. A go-to-market angle could involve offering flexible, pay-as-you-go terms tailored for regional SMEs.
For Investors and Strategic Acquirers: The PSTI Act reshapes the acquisition landscape, favoring firms with proven security compliance and deep industry-specific analytics. Long-term viability is strong, driven by sustained industrial digitalization and regulatory mandates for security and sustainability. Seek out specialized analytics providers, cybersecurity solution firms focused on operational technology, and edge AI startups with demonstrable intellectual property. The signal to watch is the evolution of data governance rules post-Brexit, which could further define data residency and transfer requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Firm | Expands vertical expertise and accelerates market penetration in niche segments like Agri-Tech. |
| Platform Integration | Enhances interoperability and offers comprehensive solutions across diverse IoT ecosystems. |
| Product Launch | Introduces new solutions addressing emerging needs such as ESG reporting and TinyML applications. |
| Strategic Partnership | Leverages complementary strengths to broaden market reach and improve solution breadth. |
| Geographic Expansion | Extends presence into underserved UK regions or international markets with similar regulatory needs. |
Research Approach
Operator-level perspectives from CTOs, IT procurement officers, platform engineers, and manufacturing plant managers anchored the qualitative base for this analysis. Primary interviews were triangulated with secondary validation from UK government reports, company financial filings, and technology market analyses. This dual approach ensured a robust understanding of market dynamics through both bottom-up and top-down data collection.
Sensitivity analysis framed the forecast framework, modeling the UK IoT software market across the analysis window. Segmentation dimensions included deployment model, solution offering, use case, end-user industry vertical, and regional adoption patterns. Compound annual growth rates were derived from historical trends and projected growth drivers, incorporating industry-specific inputs like IoT device shipment growth and regulatory compliance costs.
Material uncertainties — including shifts in UK data transfer regulations or the evolution of cybersecurity threats — sit outside the modeled envelope. Forecasts reflect assumptions based on current market conditions and anticipated technological trajectories. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
IoT Gateway Hardware and Software Market
Internet of Things (IoT)
AI in IoT Market
Internet of Things (IoT)
Connected IoT Devices Market
Internet of Things (IoT)
IoT Device Management Market
Internet of Things (IoT)
IoT Application Development Services Market
Internet of Things (IoT)
Narrow Band IoT Tracker Market
Internet of Things (IoT)
IoT Network Management Market
Internet of Things (IoT)
Smart Home M2M Market
Internet of Things (IoT)
Marine Internet of Things Market
Internet of Things (IoT)
5G IIOT Market
Internet of Things (IoT)
North America Narrowband-Internet of Things (NB-IoT) Market
Internet of Things (IoT)
Aviation IoT Solutions Market
Internet of Things (IoT)
IoT for Cold Chain Monitoring Market
Internet of Things (IoT)
IoT at Workplace Market
Internet of Things (IoT)
IoT Technology Market
Internet of Things (IoT)
Massive IoT Market