
 Airline IoT Market | 2026-2036
Airline IoT Market Size, Share, and Industry Trends Forecast 2026-2036
Airline IoT Market Analysis
Aerospace manufacturing in Toulouse and Seattle is recalibrating production lines to embed native IoT architectures into next-generation airframes before delivery. Honeywell International Inc. leverages its auxiliary power unit installed base to push predictive maintenance subscriptions into airline operations centers. Collins Aerospace sustains channel control through exclusive supplier relationships with Boeing and Airbus connectivity programs. Thales Group competes on cybersecurity-certified avionics gateways that meet European and North American airworthiness mandates.
Airline IoT encompasses networked sensors, edge processors, and cloud analytics platforms that monitor airframe health, passenger environments, and ground operations in real time, typically transmitting via satellite or cellular links at latency thresholds below 100 milliseconds for critical alerts. The primary commercial purpose is to reduce unscheduled maintenance events and optimize fuel burn through continuous performance telemetry. Predictive maintenance tools command the deepest margin pools because airlines pay subscription fees tied to avoided downtime costs. Edge computing is displacing pure cloud architectures as carriers demand real-time anomaly detection without satellite link dependency. Fleet management applications anchor volume demand since every connected aircraft requires baseline telemetry infrastructure regardless of cabin service sophistication.
The FAA mandates cybersecurity management systems under evolving airworthiness criteria, while EASA enforces its own connected aircraft certification pathways that vendors must duplicate for European operators. GDPR and emerging aviation-specific data governance frameworks restrict how passenger biometric and behavior data flows across jurisdictions, forcing dual infrastructure deployments. Stakeholders must monitor whether regulators harmonize cross-border data standards or perpetuate the compliance fragmentation that currently doubles deployment costs for international carriers.
Market Dynamics
Fleet management departments at full-service carriers are expanding sensor deployments across connected aircraft platforms. The FAA's Part 25 airworthiness standards for connected avionics systems are accelerating certification requirements for IoT-enabled equipment.
Growth Catalysts
- Regulatory Push:The FAA's evolving cybersecurity management systems mandate under Part 25 airworthiness criteria compel airlines to upgrade legacy telemetry infrastructure.
- Edge Computing:Real-time anomaly detection without satellite link dependency is displacing pure cloud architectures as carriers demand sub-100 millisecond latency for critical alerts.
- Narrow-Body Retrofits:United States-based carriers are retrofitting fleets with predictive maintenance infrastructure, concentrating demand in North American maintenance hubs.
Market Restraints
- Certification Duplication:EASA's connected aircraft certification pathways force vendors to duplicate compliance efforts for European operators, doubling deployment costs.
- Data Governance Fragmentation:GDPR and emerging aviation-specific frameworks restrict passenger biometric data flows across jurisdictions, requiring dual infrastructure.
- Latency Thresholds:Satellite transmission limitations create technical barriers for real-time critical alerts in oceanic routes beyond cellular coverage.
Strategic Opportunities
- Cybersecurity Gateways:European and North American airworthiness mandates create demand for certified avionics gateways that meet dual-jurisdiction standards.
- Biometric Data Services:Cabin environment monitoring applications remain underpenetrated compared to airframe health telemetry, offering white space for passenger experience optimization.
- Predictive Subscriptions:Airlines pay fees tied to avoided downtime costs, creating recurring revenue pools deeper than hardware sales margins.
Industry Challenges
- Cross-Border Harmonization:Regulators have not aligned data standards, perpetuating compliance fragmentation that inflates operational complexity for international carriers.
- Legacy System Integration:Retrofitting narrow-body fleets requires interfacing with decades-old avionics architectures, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airline IoT Market |
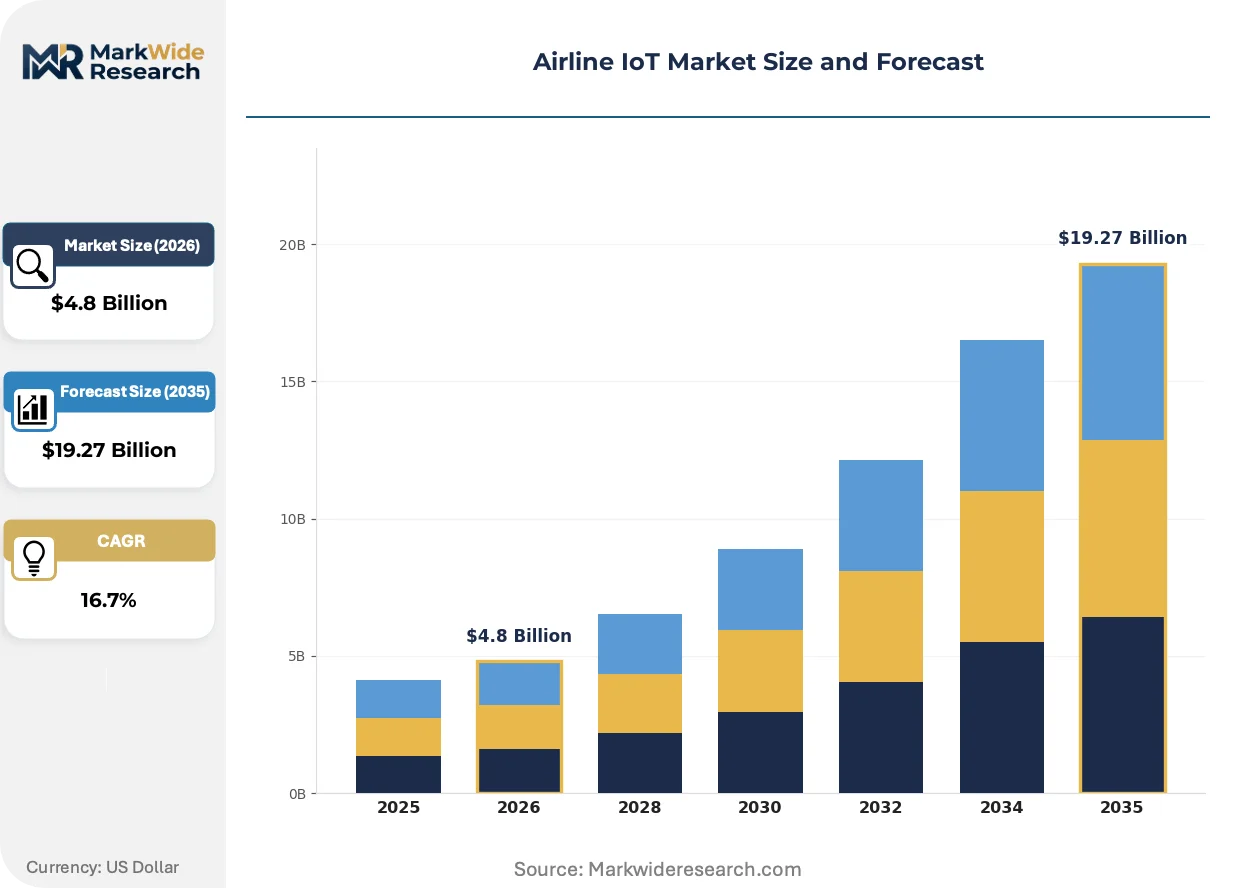
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $19.27 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monitoring Systems, Passenger Management Solutions, Predictive Maintenance Tools, IoT Gateways Technology: Machine Learning, RFID, Cloud Computing, Edge Computing End User: Airlines, Ground Handling Services, Airport Authorities, Aviation Consultants Application: Fleet Management, In-Flight Services, Customer Experience, Baggage Tracking |
| Companies Covered | Honeywell International Inc., Collins Aerospace, SITAONAIR, Cisco Systems, Inc., IBM Corporation, Thales Group, GE Aerospace, Panasonic Avionics Corporation, Huawei Technologies Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airline IoT Market Emerging Trajectories
Edge processors are actively reshaping how airlines handle telemetry, compressing decision cycles from minutes to milliseconds. This shift is redefining competitive positioning between satellite-dependent and autonomous onboard systems.
Onboard edge computing is overtaking pure cloud architectures for critical alert processing. Full-service carriers operating transoceanic routes are deploying edge processors in auxiliary power unit compartments to enable real-time anomaly detection without satellite link dependency. This compression of decision latency is eliminating the vulnerability windows that previously forced airlines to delay maintenance responses until ground connectivity restored.
EASA's connected aircraft certification pathways are tightening cybersecurity requirements for avionics gateways entering European airspace. Vendors must now demonstrate compliance with dual jurisdiction standards before equipment installation, extending pre-delivery validation cycles. Narrow-body retrofit programs in France and Germany are experiencing the most pronounced timeline impacts as suppliers recalibrate testing protocols.
Subscription pricing tied to avoided downtime costs is displacing capital expenditure models for predictive maintenance tools. Low-cost carriers operating high-utilization schedules are adopting performance-based contracts that align vendor payments with measurable operational improvements. This shift is most visible in United States-based fleet management departments, where procurement teams prioritize cash flow predictability over asset ownership.
Airline IoT Market Segmentation
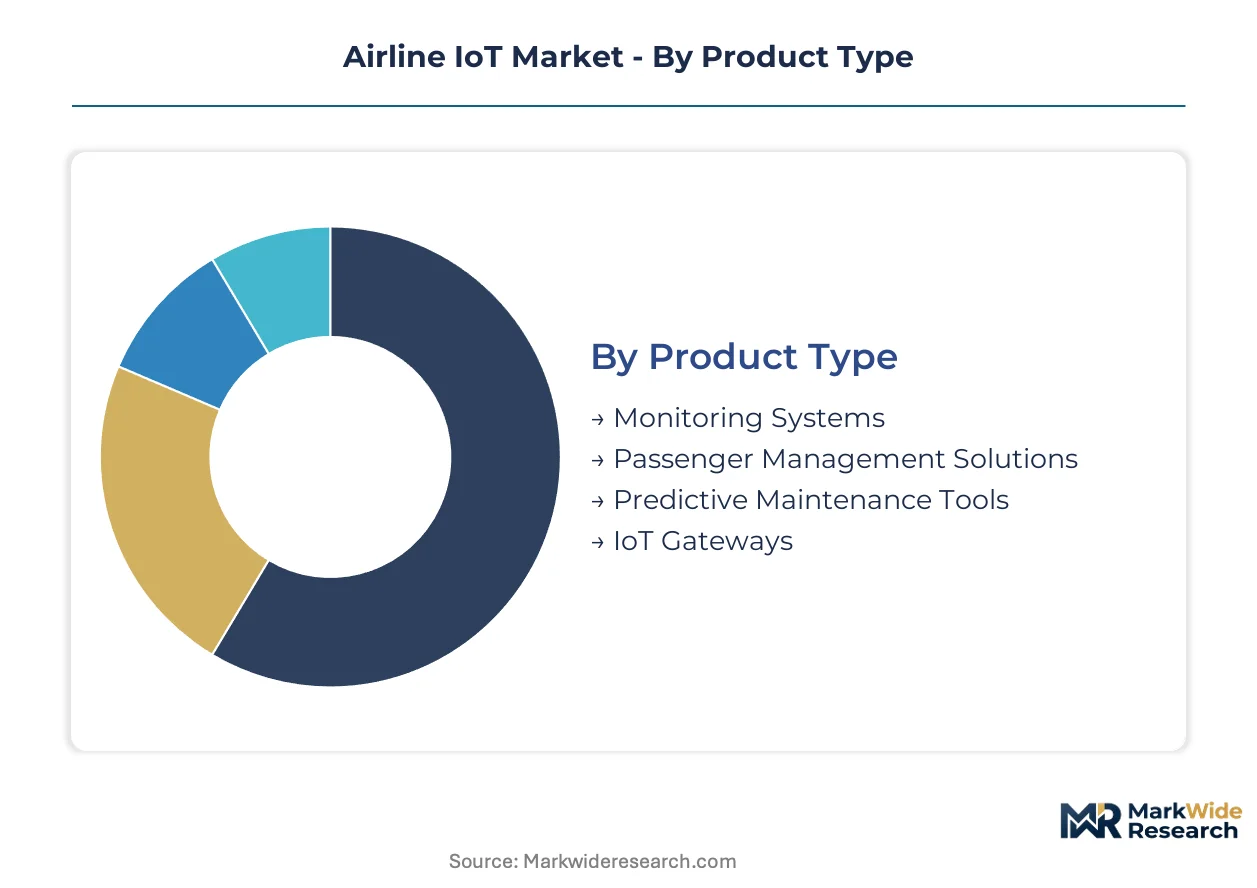
Airline IoT procurement decisions split sharply between operational imperatives and passenger-facing investments. Fleet managers prioritize airframe health telemetry with immediate ROI, while passenger experience applications compete for discretionary technology budgets.
Product Type:
Capital allocation intensity drives purchasing patterns, with maintenance-avoidance value commanding premium subscription pricing.
- Predictive Maintenance Tools:Continuous performance telemetry platforms monitor engine parameters, hydraulic systems, and structural integrity through embedded sensor networks. United States-based full-service carriers retrofit narrow-body fleets with these systems first, as unscheduled downtime costs exceed subscription fees by an order of magnitude.
- IoT Gateways:Cybersecurity-certified avionics interfaces aggregate sensor data streams and manage satellite or cellular transmission protocols. EASA and FAA dual-certification requirements extend validation cycles for equipment entering European and North American airspace simultaneously.
- Monitoring Systems:Real-time telemetry infrastructure for environmental controls, fuel systems, and landing gear status.
- Passenger Management Solutions:Cabin environment optimization including biometric boarding and personalized climate control.
Predictive Maintenance Tools leads on scale; IoT Gateways leads on momentum.
Technology:
Latency tolerance thresholds determine architectural selection between centralized and distributed processing models.
- Edge Computing:Autonomous onboard processors enable sub-100 millisecond anomaly detection without satellite link dependency. Full-service carriers operating transoceanic routes deploy these systems in auxiliary power unit compartments to eliminate vulnerability windows during oceanic segments beyond cellular coverage.
- Machine Learning:Pattern recognition algorithms trained on historical failure signatures predict component degradation trajectories. Airlines pay performance-based fees tied to measurable downtime avoidance, displacing capital expenditure models.
- Cloud Computing:Centralized analytics platforms for non-critical data aggregation and long-term trend analysis.
- RFID:Short-range identification systems for baggage tracking and ground equipment location services.
Edge Computing leads on scale; Machine Learning leads on momentum.
End User:
Operational control boundaries determine which stakeholder funds specific IoT deployments.
- Airlines:Fleet owners bear primary investment responsibility for airframe health and predictive maintenance infrastructure. Their procurement teams prioritize cash flow predictability through subscription contracts rather than asset ownership.
- Ground Handling Services:Third-party operators deploy equipment tracking and turnaround optimization systems. These vendors face compressed margins that limit technology investment to proven ROI applications.
- Airport Authorities:Infrastructure owners fund passenger flow monitoring and gate utilization analytics.
- Aviation Consultants:Advisory firms deploy diagnostic tools for fleet optimization studies and regulatory compliance assessments.
Airlines leads on scale; Ground Handling Services leads on momentum.
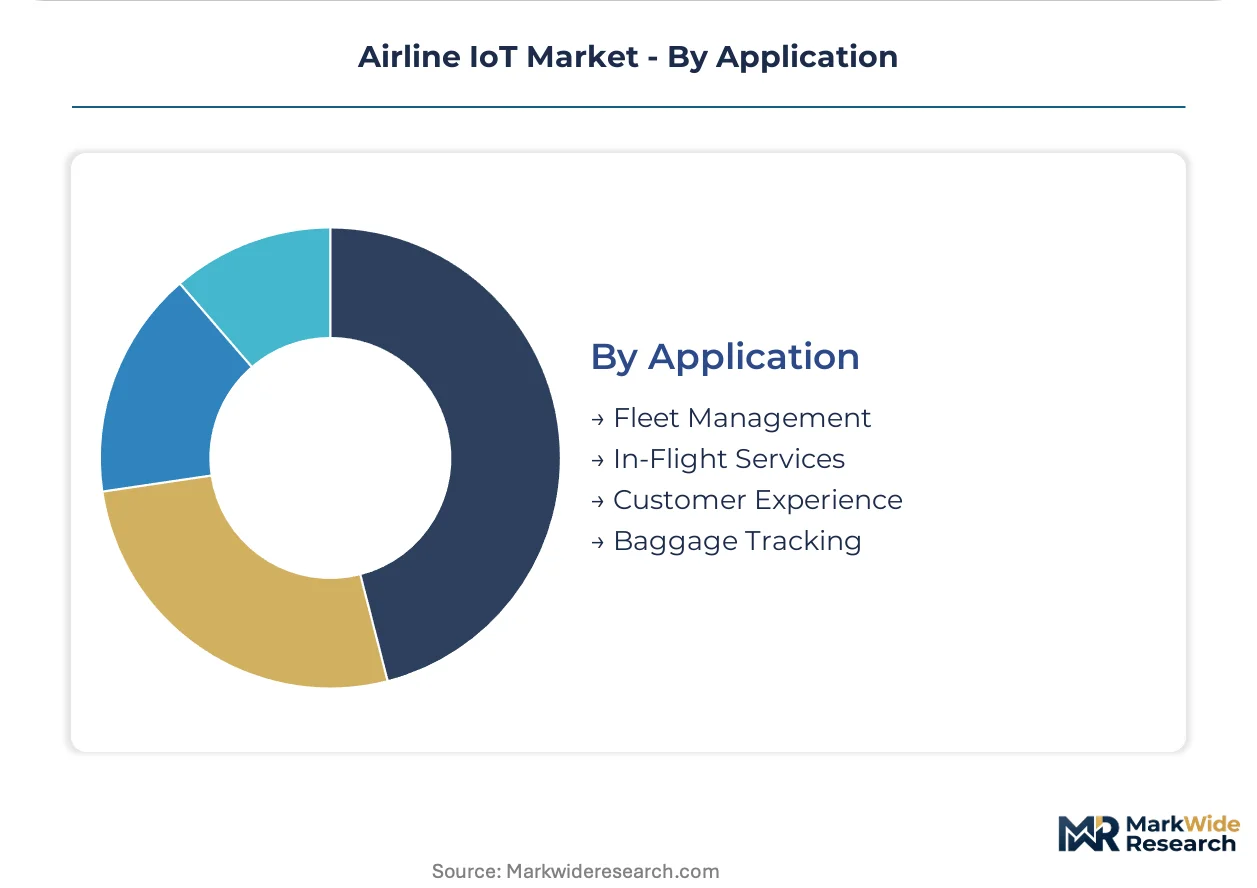
Application:
Revenue protection versus revenue generation frames internal budget competition between operational and commercial departments.
- Fleet Management:Baseline telemetry infrastructure required for every connected aircraft regardless of cabin service sophistication. This application anchors volume demand through mandatory sensor deployments across engine, airframe, and auxiliary systems.
- Baggage Tracking:RFID and cellular-enabled location services reduce mishandled luggage costs and passenger compensation exposure. International carriers face GDPR restrictions on passenger biometric data flows that complicate cross-border system architecture.
- In-Flight Services:Connected cabin systems for crew coordination and passenger request management.
- Customer Experience:Personalized entertainment, connectivity, and environmental control applications.
Fleet Management leads on scale; Baggage Tracking leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States carriers outpace European counterparts in narrow-body retrofit intensity, while Chinese airlines accelerate greenfield IoT deployments on domestically manufactured airframes.
United States
Full-service carriers retrofit aging narrow-body fleets with predictive maintenance infrastructure to avoid unscheduled downtime costs. FAA Part 25 airworthiness standards for connected avionics systems accelerate certification timelines for IoT-enabled equipment entering domestic airspace. Seattle aerospace manufacturing clusters embed native IoT architectures into next-generation airframes before delivery to major airline customers.
France
Airbus supply chain partners in Toulouse recalibrate production lines for cybersecurity-certified avionics gateways meeting EASA mandates. EASA connected aircraft certification pathways tighten requirements for equipment entering European airspace, extending validation cycles. Aerospace clusters in Occitanie experience pronounced timeline impacts as suppliers recalibrate testing protocols for dual-jurisdiction compliance.
Germany
Lufthansa Group fleet management departments expand sensor deployments across long-haul connected aircraft platforms serving transoceanic routes. EASA enforcement of cybersecurity management systems compels upgrades to legacy telemetry infrastructure for European operators. Industrial concentration in Bavaria supports edge processor manufacturing for auxiliary power unit compartment installations.
China
Domestic airlines deploy IoT infrastructure on COMAC C919 airframes to reduce dependency on foreign avionics suppliers. MIIT standards for connected aircraft equipment create parallel certification pathways distinct from FAA and EASA frameworks. Yangtze River Delta manufacturing hubs develop indigenous telemetry platforms for state-owned carrier fleets.
United Arab Emirates
Emirates and Etihad Airways invest in passenger-facing IoT applications including biometric boarding and personalized cabin environments. MOHAP data governance frameworks intersect with aviation-specific regulations on passenger biometric flows across jurisdictions. Dubai aviation clusters serve as testing grounds for biometric data services before wider Middle East deployment.
Airline IoT Market Vendor Landscape
United States producers anchor one tier; French specialists hold certification advantages in European markets. The vendor base splits between diversified conglomerates with installed base leverage and pure-play connectivity providers competing on latency performance. Three archetypes dominate: auxiliary power unit incumbents converting hardware relationships into predictive maintenance subscriptions, avionics gateway specialists capturing margin from dual-certification complexity, and satellite connectivity providers defending against edge computing displacement. Competitive moves concentrate on exclusive supplier relationships with airframe OEMs and performance-based contract structures that align vendor compensation with airline operational improvements.
Among diversified technology conglomerates, Honeywell International Inc. and Cisco Systems, Inc. exemplify archetypes built on installed base leverage and enterprise networking expertise respectively. Collins Aerospace occupies a position representing avionics integration specialists with exclusive Boeing and Airbus program relationships. Thales Group anchors the cybersecurity-certified gateway tier, competing through compliance with European and North American airworthiness mandates simultaneously.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Collins Aerospace |
| SITAONAIR |
| Cisco Systems, Inc. |
| IBM Corporation |
| Thales Group |
| GE Aerospace |
| Panasonic Avionics Corporation |
| Huawei Technologies Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between FAA-EASA dual-certified avionics gateways and single-jurisdiction alternatives manifests in both subscription pricing tiers and supplier geographic concentration. Airlines operating transoceanic routes pay premium subscription multiples for equipment meeting both regulatory frameworks, while vendors concentrate final assembly in Toulouse and Seattle aerospace clusters to minimize dual-validation logistics.
Pricing Analysis
Distributor margins on IoT gateway hardware compress as direct-to-airline subscription contracts displace capital expenditure models. Three-tier pricing structure across premium, standard, and economy levels reflects certification complexity, with dual-jurisdiction gateways commanding subscription fees tied to avoided downtime costs. Cost compression in standard-tier equipment is intensifying because Chinese avionics suppliers enter narrow-body retrofit markets with MIIT-certified alternatives. Low-cost carriers exhibit highest price sensitivity, prioritizing cash flow predictability over feature depth.
Supply Chain Analysis
MIIT domestic-content mandates for COMAC C919 programs are reshaping sourcing patterns toward Yangtze River Delta manufacturing hubs. Edge processor fabrication draws from Taiwan, South Korea, and Germany; satellite connectivity modules rest on US and French supplier networks. Single-source vulnerability concentrates in cybersecurity-certified gateway chipsets subject to export control restrictions. Distribution runs through exclusive supplier relationships with Boeing and Airbus connectivity programs rather than open channel networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Airline IoT procurement has shifted toward premium specifications as EASA and FAA cybersecurity mandates eliminate uncertified equipment from consideration. This quality migration favors vendors with pre-positioned dual-jurisdiction validation.
For Market Incumbents: Anticipate margin compression from Chinese avionics suppliers entering narrow-body retrofit markets with MIIT-certified alternatives at standard-tier pricing. Defend position by deepening backward integration into edge processor design and expanding exclusive supplier relationships with COMAC for C919 programs. Certification investment in emerging aviation-specific data governance frameworks represents the priority defensive lever.
For New Entrants and Emerging Players: Ground handling services operators present the most penetrable entry point, as compressed margins have delayed their technology investment relative to airline fleet management departments. Target biometric data services for cabin environment monitoring, a segment underpenetrated compared to airframe health telemetry. A channel partnership with established satellite connectivity providers offers the fastest route to airline procurement committees.
For Investors and Strategic Acquirers: Consolidation pressure builds where dual-certification complexity creates capability scarcity among mid-tier avionics gateway specialists. Long-term viability centers on vendors converting hardware relationships into predictive maintenance subscriptions with recurring revenue visibility. The signal to watch is EASA-FAA harmonization progress on cross-border data standards, which would eliminate the compliance fragmentation currently protecting incumbent positions.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Jurisdiction Certification Investment | EASA-FAA validation cycles extend competitive moats for gateway vendors serving transoceanic carriers. |
| Edge Processor Manufacturing Scale-Up | Bavaria-based production capacity supports auxiliary power unit compartment installations for real-time anomaly detection. |
| Predictive Maintenance Subscription Conversion | Performance-based contracts align vendor payments with measurable downtime avoidance for high-utilization fleets. |
| Biometric Data Service Platform Launch | Cabin environment optimization applications capture discretionary technology budgets from passenger experience departments. |
| COMAC Supply Chain Partnership | Indigenous telemetry platform integration on C919 airframes reduces foreign avionics dependency for Chinese state-owned carriers. |
Methodological Framework
Multiple input streams — fleet management executive interviews, avionics procurement officer surveys, and regulatory filing analysis — were reconciled to construct market estimates. Primary fieldwork engaged predictive maintenance platform directors, EASA certification specialists, airline operations center managers, and ground handling technology leads. Secondary validation drew from FAA Part 25 airworthiness documentation, EASA connected aircraft certification pathways, MIIT equipment standards, and customs records for avionics component trade flows. Bottom-up aircraft retrofit program counts were triangulated against top-down aerospace OEM delivery projections.
Historical certification timeline patterns were cross-referenced against expert panel assessments of regulatory harmonization probability across the analysis window. Segmentation modeling captured product type hierarchies, technology architecture choices, end-user control boundaries, and application priority rankings. CAGRs were derived from fitted growth curves calibrated to disclosed retrofit program schedules and OEM connectivity program commitments. Forecast inputs included satellite bandwidth pricing trajectories and edge processor cost decline curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EASA-FAA regulatory harmonization progress and Chinese domestic aviation market expansion rates. Forecasts reflect documented assumptions about certification timeline stability and airline capital allocation priorities. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Narrow Band IoT Tracker Market
Internet of Things (IoT)
Cellular Machine to Machine Market
Internet of Things (IoT)
IoT Device Management Market
Internet of Things (IoT)
IoT Integration Services Market
Internet of Things (IoT)
Location of Things Market
Internet of Things (IoT)
IoT in Manufacturing Market
Internet of Things (IoT)
Indonesia IoT Market
Internet of Things (IoT)
Global 5G Industrial IOT Market
Internet of Things (IoT)
Connected Bottles Market
Internet of Things (IoT)
Global IoT Engineering Services Market
Internet of Things (IoT)
IoT in Automotive Market
Internet of Things (IoT)
Industrial IoT Market
Internet of Things (IoT)
IoT Integration Market
Internet of Things (IoT)
IoT Services Market
Internet of Things (IoT)
IoT Gateway Hardware and Software Market
Internet of Things (IoT)
IoT Solutions Market