
 Healthcare M2M Market | 2026-2036
Healthcare M2M Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare M2M Market Outlook
Subscription-based leasing for connected medical devices is reshaping competitive dynamics in the Healthcare M2M space. GE Healthcare leverages its installed base of imaging equipment to extend monitoring services through embedded cellular modules. Medtronic anchors its position through in-house production of cardiac sensors with integrated telemetry. Cisco Systems controls network infrastructure layers that hospitals depend on for secure device connectivity.
Healthcare M2M encompasses machine-to-machine communication systems that transmit clinical data between medical devices, healthcare providers, and patient management platforms without human intervention. These systems typically operate over cellular networks with latency requirements under 250 milliseconds for emergency alerting applications. Remote Patient Monitoring commands the largest revenue pool as health systems seek to reduce readmission penalties through continuous outpatient tracking. Wearable Devices represent the fastest-expanding category, though margin compression from consumer-grade entrants limits profitability for pure-play vendors. Smart Sensors concentrate margin pools in specialized applications such as continuous glucose monitoring where calibration algorithms create switching costs.
FDA oversees wireless medical device cybersecurity through premarket guidance, while HIPAA mandates encryption standards for transmitted patient data, and FCC governs spectrum allocation for healthcare IoT transmissions. These frameworks elevate compliance costs for new entrants but protect incumbent positions for certified suppliers. Stakeholders must monitor evolving FDA guidance on artificial intelligence integration in autonomous diagnostic alerts.
Market Dynamics
Cellular module miniaturization and embedded SIM technology are compressing hardware costs for connected medical devices, enabling mass deployment of disposable sensors that previously required reusable capital equipment. This shift from fixed infrastructure to consumable connectivity is restructuring vendor economics and procurement patterns across hospital systems.
Growth Catalysts
- Hospital readmission penalty frameworks:Medicare reimbursement cuts for excessive 30-day readmissions push health systems toward continuous outpatient monitoring through cellular-enabled wearables.
- 5G network slicing capabilities:Ultra-reliable low-latency communication channels guarantee sub-100 millisecond transmission for emergency cardiac alerts, satisfying clinical-grade reliability requirements.
- FDA premarket cybersecurity guidance:Standardized 510(k) submission pathways for wireless devices accelerate regulatory clearance timelines for qualified manufacturers.
Market Restraints
- Semiconductor foundry concentration:Taiwan-based fabrication capacity constraints create 26-week lead times for cellular baseband chips, throttling device production schedules.
- Lithium-ion cell volatility:Cobalt supply instability from Democratic Republic of Congo mining operations injects cost uncertainty into wearable device battery procurement.
- Interoperability protocol fragmentation:Competing standards between HL7 FHIR, IEEE 11073, and proprietary platforms force redundant engineering investment.
Strategic Opportunities
- India's Ayushman Bharat digital health mission:Government-funded remote diagnostics infrastructure creates demand for low-cost cellular glucometers and blood pressure monitors in tier-2 and tier-3 cities.
- Artificial intelligence-edge convergence:On-device inference chips combined with cellular telemetry enable autonomous arrhythmia detection without cloud dependency.
- Direct-to-employer contracting channels:Self-insured corporations bypass traditional distribution to procure population health monitoring bundles for workforce risk reduction.
Industry Challenges
- Firmware security engineering talent scarcity:Healthcare device manufacturers compete with automotive and financial sectors for embedded systems specialists capable of implementing FDA-mandated secure boot architectures.
- Legacy hospital IT integration friction:Decades-old electronic health record systems lack native API connectivity, requiring expensive middleware development for M2M data ingestion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare M2M Market |
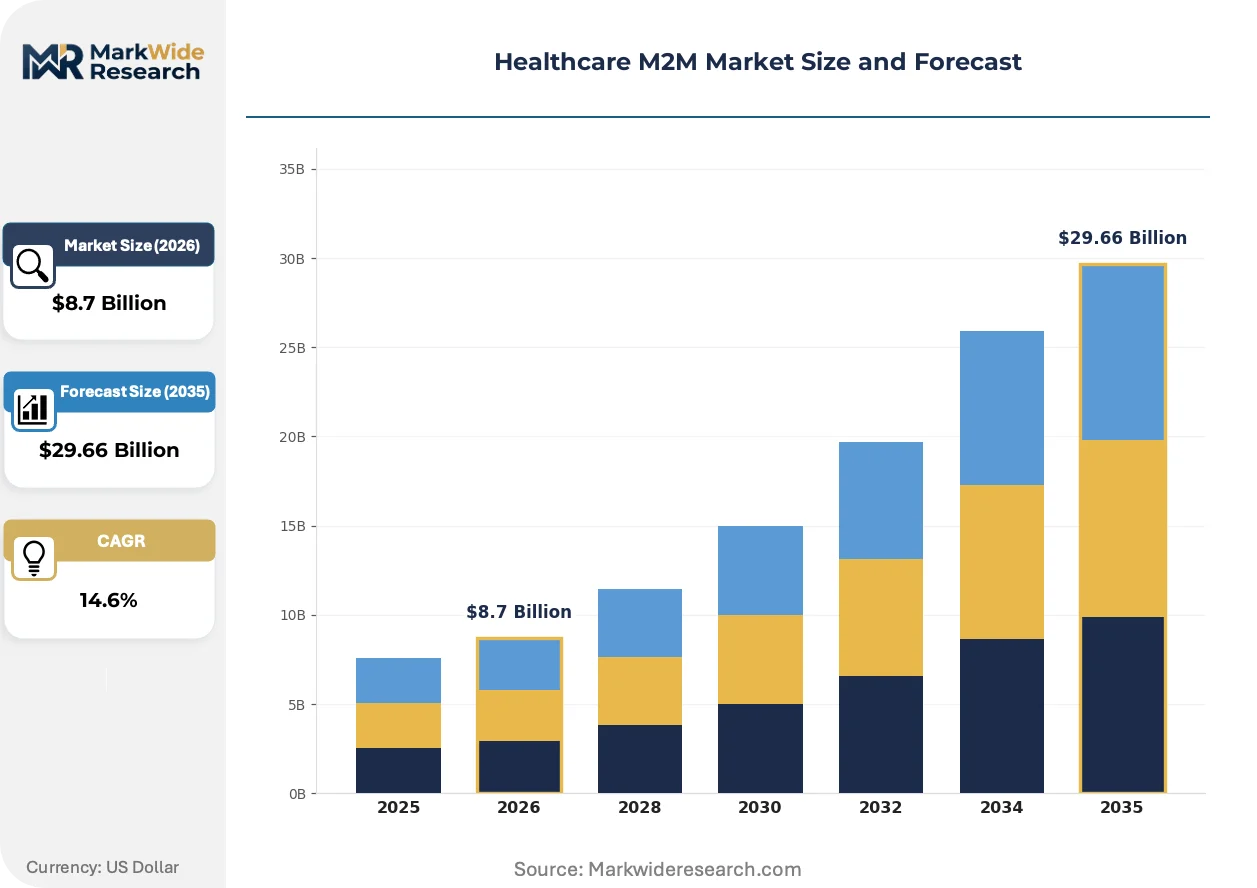
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $29.66 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Remote Patient Monitoring, Smart Sensors, Telehealth Solutions Technology: Wireless Communication, Bluetooth, Wi-Fi, Cellular Networks End User: Hospitals, Clinics, Homecare Providers, Healthcare Professionals Application: Chronic Disease Management, Emergency Response, Health Monitoring, Medication Adherence |
| Companies Covered | Epic Systems Corporation, GE Healthcare, IBM Corporation, Cisco Systems, Apple Inc., Allscripts Healthcare Solutions, Sierra Wireless, Deutsche Telekom, Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare M2M Market Strategic Shifts
Edge computing architectures are migrating clinical decision logic from centralized cloud servers to device-local processors, reducing latency and bandwidth consumption while complicating software update distribution. This decentralization is redrawing competitive boundaries between hardware manufacturers and platform vendors.
Bluetooth Low Energy 5.3 with coded PHY is rendering obsolete traditional Wi-Fi dependent patient monitoring systems that required expensive hospital infrastructure deployment. Ambulatory surgical centers and home health agencies are adopting these long-range, low-power protocols for post-operative vital sign tracking. The shift eliminates gateway hardware costs and extends battery life from days to months, compressing total cost of ownership by two-thirds for distributed care models.
The EU Medical Device Regulation's post-market surveillance requirements mandate systematic cybersecurity monitoring throughout device lifecycles. Manufacturers must establish coordinated vulnerability disclosure mechanisms and maintain software bills of materials. Cardiac implantable electronic device suppliers face the steepest compliance burden, with notified body audit intervals compressing from five years to annual reviews for Class III products.
Health system procurement committees now prioritize subscription-based service agreements over capital equipment purchases, unbundling hardware acquisition from data analytics and clinical decision support. Integrated delivery networks in Texas and Florida lead this transition, negotiating per-patient-per-month fees that align vendor incentives with outcome metrics. The model transfers obsolescence risk from hospital balance sheets to device manufacturers, accelerating refresh cycles for connected monitoring platforms.
Healthcare M2M Market Segmentation
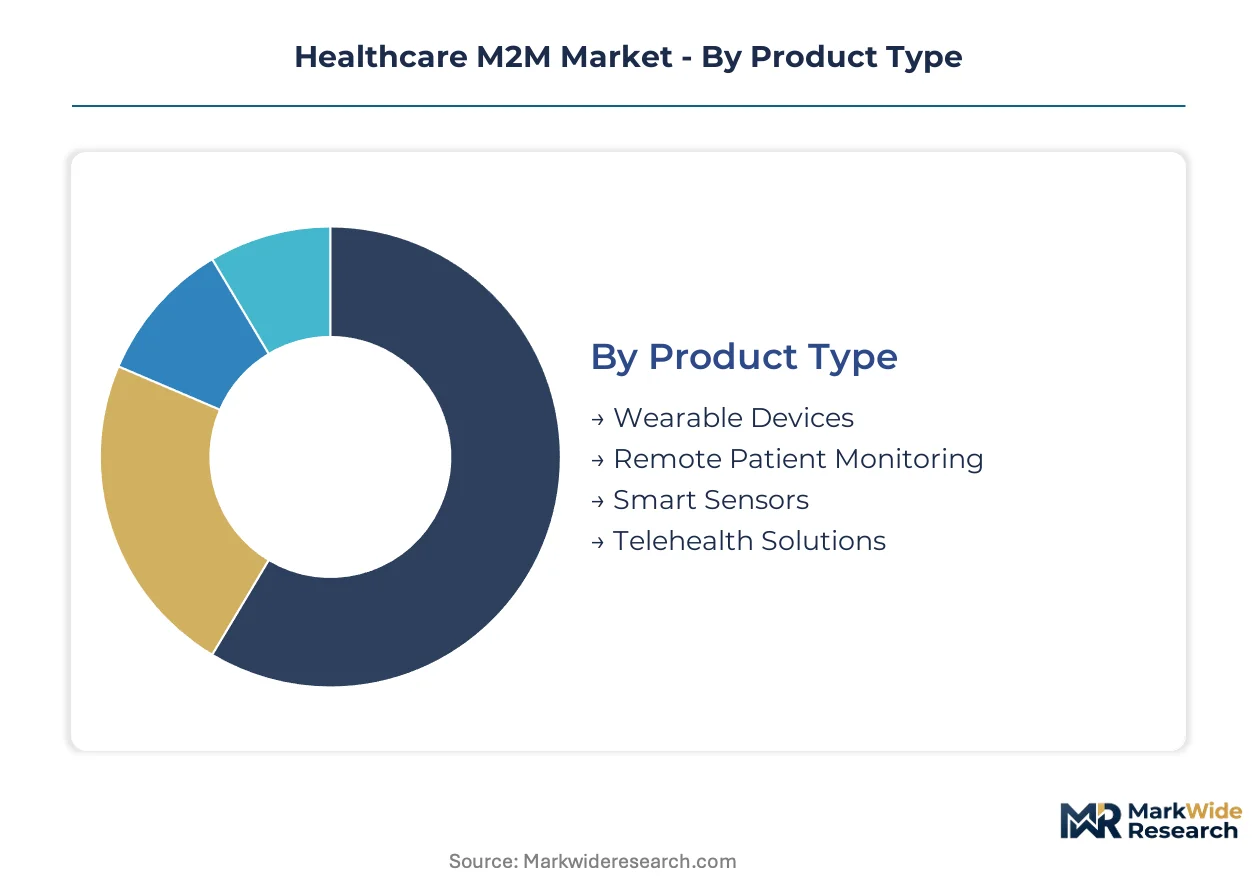
Segmentation in Healthcare M2M reveals divergent service intensity requirements across device categories. Wearable manufacturers face compressed margins from consumer-grade competition, while remote monitoring platforms command recurring revenue through clinical integration.
Product Type:
After-sales service intensity varies dramatically across product categories, with implantable sensors requiring decade-long cybersecurity maintenance versus disposable patches needing minimal technical support.
- Wearable Devices:Consumer-grade fitness bands and clinical-grade cardiac monitors operate on overlapping hardware but diverge sharply in FDA validation requirements. Demand concentrates in Medicare Advantage plans seeking HEDIS measure improvements through continuous glucose and blood pressure tracking.
- Remote Patient Monitoring:Cellular-enabled hub devices aggregate biometric data from multiple peripheral sensors for cloud transmission. Health systems in Texas and Florida deploy these platforms to reduce CMS readmission penalties through post-discharge surveillance.
- Smart Sensors:Miniaturized continuous monitoring implants with decade-long lifecycles.
- Telehealth Solutions:Integrated video and biometric platforms for synchronous virtual consultations.
Remote Patient Monitoring holds the largest share; momentum sits with Wearable Devices.
Technology:
Technology selection determines power budgets, latency floors, and regulatory complexity for device certification pathways.
- Wireless Communication:Proprietary sub-GHz protocols serve implantable cardiac devices where cellular penetration fails. Manufacturers targeting rural home health agencies prioritize these frequencies for reliable transmission through building materials.
- Bluetooth:Low Energy 5.3 with coded PHY extends range to 300 meters while slashing power draw versus legacy standards. Ambulatory surgical centers adopt these long-range variants for post-operative monitoring without gateway infrastructure.
- Wi-Fi:Hospital-grade 6E implementations for high-bandwidth imaging transmission.
- Cellular Networks:LTE-M and NB-IoT modules enabling nationwide coverage for mobile patients.
Cellular Networks anchor revenue concentration; Bluetooth is climbing the fastest.
End User:
Procurement authority fragmentation shapes sales cycle complexity across institutional buyers.
- Hospitals:Integrated delivery networks negotiate enterprise-wide device standardization to reduce interoperability engineering costs. IDNs in the United States increasingly demand subscription pricing that transfers obsolescence risk to vendors.
- Clinics:Federally qualified health centers seek low-cost cellular glucometers for underserved populations. India's Ayushman Bharat mission funds procurement for tier-2 and tier-3 city deployments.
- Homecare Providers:Franchise networks requiring fleet management platforms for distributed device logistics.
- Healthcare Professionals:Individual practitioners purchasing direct-to-consumer monitoring tools.
Hospitals dominate procurement volume; Homecare Providers show steepest expansion trajectory.
Application:
Clinical use case determines reimbursement eligibility and thus device economics.
- Chronic Disease Management:Continuous outpatient tracking for diabetes, heart failure, and COPD patients. Medicare's remote patient monitoring billing codes created sustainable revenue streams for cellular-enabled device deployments.
- Emergency Response:Fall detection and automated cardiac alert systems with sub-100 millisecond latency requirements. 5G network slicing guarantees clinical-grade reliability for these time-critical transmissions.
- Health Monitoring:Preventive wellness tracking for employer population health programs.
- Medication Adherence:Connected pill dispensers with cellular confirmation of dose consumption.
Chronic Disease Management captures the largest share; Emergency Response is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medicare reimbursement penalties for excessive hospital readmissions are accelerating cellular-enabled remote patient monitoring deployments across health systems. Government-funded digital health missions in emerging economies are creating procurement channels for low-cost connected diagnostic devices. Regulatory frameworks governing wireless medical device cybersecurity are shaping certification pathways and market access conditions.
United States
Integrated delivery networks in Texas and Florida negotiate enterprise-wide device standardization to reduce interoperability engineering costs. FDA premarket cybersecurity guidance accelerates 510(k) clearance timelines for qualified wireless device manufacturers. The Medicare remote patient monitoring billing codes have created sustainable revenue streams for cellular-enabled deployments in post-acute care settings.
Germany
The EU Medical Device Regulation mandates systematic cybersecurity monitoring throughout device lifecycles for cardiac implantable electronic devices. Notified body audit intervals compress from five years to annual reviews for Class III products under MDR requirements. Industrial clusters in Baden-Württemberg concentrate precision sensor manufacturing for continuous glucose monitoring systems.
China
NMPA regulations on wireless medical device security shape product certification pathways for domestic and imported connected diagnostics. The country's dual carbon goals are accelerating battery technology transitions in wearable device supply chains. Manufacturing concentration in the Yangtze River Delta supports mass production of cellular modules for disposable medical sensors.
India
The Ayushman Bharat digital health mission funds procurement of low-cost cellular glucometers and blood pressure monitors in tier-2 and tier-3 cities. CDSCO guidelines on wireless medical devices establish certification requirements for connected diagnostic equipment. Industrial corridors in Gujarat and Karnataka are attracting contract manufacturers for export-oriented wearable device assembly.
Japan
PMDA regulatory frameworks govern cybersecurity requirements for wireless cardiac monitoring and implantable telemetry systems. METI initiatives on healthcare IoT spectrum allocation support reliable transmission for emergency alerting applications. Medical device clusters in the Kansai region specialize in miniaturized sensor production for decade-lifecycle implantable applications.
Healthcare M2M Market Competitive Environment
On the supply side, the industry is structured around three distinct capability tiers. Established medical technology conglomerates leverage installed bases of imaging and therapeutic equipment to extend into monitoring services. Specialized connectivity vendors control cellular module and network infrastructure layers that enable device communication. Consumer technology entrants are compressing margins in wearable categories through fitness-tracker economics. Dominant competitive moves include strategic partnerships between device manufacturers and network operators, plus backward integration into sensor fabrication to secure supply chains.
Within the medical technology conglomerate tier, GE Healthcare and Medtronic exemplify divergent strategic positions. GE Healthcare leverages its installed base of imaging equipment to extend monitoring services through embedded cellular modules. Medtronic anchors its position through in-house production of cardiac sensors with integrated telemetry. Among network infrastructure specialists, Cisco Systems occupies a position controlling the secure connectivity layers that hospital systems depend upon for device communication.
| Leading Market Players |
|---|
| Epic Systems Corporation |
| GE Healthcare |
| IBM Corporation |
| Cisco Systems |
| Apple Inc. |
| Allscripts Healthcare Solutions |
| Sierra Wireless |
| Deutsche Telekom |
| Medtronic |
| Others |
Value Chain & Pricing Dynamics
The Yangtze River Delta freight corridor carries cellular module assemblies from Shanghai to Shenzhen assembly plants, with container cost volatility feeding directly into wearable device margins and forcing three-tier pricing stratification across FDA-grade, CE-marked, and unbranded sensor tiers.
Pricing Analysis
Certification level creates the primary spread between premium and economy tiers in Healthcare M2M. Subscription-based SaaS pricing dominates hospital procurement, with per-patient-per-month models transferring obsolescence risk to vendors. Price differentiation hinges on FDA 510(k) validation status and embedded cybersecurity architecture. Pricing pressure stems from consumer-grade fitness tracker entrants compressing margins in the wearable segment. Federally qualified health centers exhibit highest price sensitivity, while integrated delivery networks prioritize total cost of ownership over unit economics.
Supply Chain Analysis
Semiconductor foundry capacity in Taiwan, South Korea, and the United States anchors cellular baseband chip supply for connected medical devices. Raw material dependencies center on cobalt-bearing lithium-ion cells, ceramic substrate packaging, and precision MEMS wafers. Single-source vulnerability concentrates in Taiwan-based fabrication for sub-6GHz cellular modems. Distribution runs through medical device GPOs and direct-to-hospital contracting channels, with subscription logistics managed via third-party fleet operators for wearable device refresh cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Healthcare M2M sits in a cyclical recovery phase as hospital capital expenditure budgets normalize post-pandemic and Medicare reimbursement codes stabilize remote patient monitoring revenue streams.
For Market Incumbents: Entrench position through backward integration into sensor fabrication and captive supply of cellular modules. Lock in hospital system partnerships via outcome-based subscription contracts that align vendor incentives with readmission reduction metrics. Defend against consumer-grade entrants by accelerating FDA cybersecurity validation for embedded AI diagnostic chips.
For New Entrants and Emerging Players: Establish a beachhead in India's Ayushman Bharat-funded tier-2 city deployments where procurement specifications favor low-cost cellular glucometers over premium-tier alternatives. Target direct-to-employer contracting channels for workforce population health monitoring, bypassing entrenched hospital GPO relationships. Lead with Bluetooth Low Energy 5.3-enabled disposable patches that eliminate gateway infrastructure costs for ambulatory surgical centers.
For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates divesting non-core medical connectivity divisions amid portfolio rationalization. Long-term viability favors platforms with integrated reimbursement strategy capabilities and hospital EHR integration middleware. Watch FDA guidance evolution on autonomous diagnostic alerts as the inflection signal for AI-edge convergence valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Cybersecurity Submission | Accelerates 510(k) clearance for wireless cardiac monitors under premarket guidance pathways. |
| Hospital System Partnership | Locks in subscription revenue through Texas and Florida integrated delivery network standardization. |
| Backward Integration into Sensors | Secures supply of MEMS fabrication for continuous glucose monitoring calibration algorithms. |
| Software Companion Development | Enables autonomous arrhythmia detection via on-device inference without cloud dependency. |
| Reimbursement Strategy | Aligns cellular-enabled RPM deployments with Medicare billing codes for sustainable revenue. |
Study Parameters
A spread of perspectives from hospital purchasing committees, biomedical engineers, GPO contracts managers, and cellular module procurement leads converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) databases, CMS Medicare reimbursement filings, and hospital procurement contract repositories. Bottom-up device shipment modeling triangulated against top-down health system IT expenditure forecasts.
Demand-supply balance dynamics shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, communication technology, end-user institution scale, and clinical application intensity. CAGRs derived from regression analysis of historical cellular module adoption curves and Medicare claims data for remote patient monitoring utilization. Key inputs incorporated 5G network slicing deployment timelines and FDA cybersecurity guidance evolution.
Stress conditions across semiconductor foundry capacity constraints, cobalt supply disruption, and hospital IT integration friction were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about reimbursement code stability and regulatory clearance timelines. Cross-checking against CMS Medicare claims benchmarks and hospital capital expenditure surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Solar Based Internet of Things (IoT) Market
Internet of Things (IoT)
IoT Lpwans Market
Internet of Things (IoT)
Maritime Internet of Things Market
Internet of Things (IoT)
IoT at Workplace Market
Internet of Things (IoT)
Europe Massive IoT Market
Internet of Things (IoT)
Europe IoT in Smart Cities Market
Internet of Things (IoT)
Global IoT in Aerospace and Defense Market
Internet of Things (IoT)
North America Internet of Things Devices Market
Internet of Things (IoT)
IoT Gateway Hardware and Software Market
Internet of Things (IoT)
Global Narrowband IoT Market
Internet of Things (IoT)
IoT Network Management Market
Internet of Things (IoT)
Internet of Things (IoT) Platform Market
Internet of Things (IoT)
Global IOT Gateway Market
Internet of Things (IoT)
Smart Sound and Gateway Market
Internet of Things (IoT)
Global Internet of Things Technology Market
Internet of Things (IoT)
Global IOT Connectivity Management Platform (CMP) Market