
 GCC Indoor LBS Market | 2026-2036
GCC Indoor LBS Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Indoor LBS Market Intelligence
Platform licensing revenue is tilting away from perpetual hardware sales toward recurring cloud-based subscription models. Cisco Systems Inc. leverages its enterprise networking installed base to bundle indoor positioning with WLAN infrastructure refreshes. Google Inc. anchors consumer-grade location intelligence through Android ecosystem penetration and mapping data layers. Qualcomm Technologies Inc. specializes in chipset-level Bluetooth and ultra-wideband integration for original equipment manufacturers across the Gulf.
Indoor location-based services encompass real-time positioning, navigation, and contextual analytics delivered through radio-frequency signal triangulation, sensor fusion, and beacon networks operating within enclosed environments. These systems achieve spatial accuracy between one and three meters using Bluetooth Low Energy, Wi-Fi fingerprinting, or ultrasound time-of-flight measurements to support commercial wayfinding, asset visibility, and occupancy intelligence. Wi-Fi and Bluetooth technologies dominate current deployments due to existing infrastructure reuse, while RFID-based asset tracking commands premium pricing in warehouse and logistics environments. Cloud services and integrated systems capture expanding margin pools as end users in hospitality and airports shift from on-premises servers to managed subscription architectures.
Saudi Communications and Information Technology Commission spectrum allocations and UAE Telecommunications and Digital Government Regulatory Authority device certification requirements shape permissible signal power levels and interoperability standards for indoor positioning hardware. GDPR-equivalent data protection frameworks emerging in Bahrain and Qatar impose consent and retention obligations on location data collection in retail and hospitality settings. Stakeholders must monitor evolving national data sovereignty mandates and spectrum harmonization timelines to align deployment roadmaps with compliance windows.
Market Dynamics
Cloud-native positioning architectures are compressing deployment timelines from twelve months to under six weeks across Gulf retail and aviation verticals. This infrastructure shift is redistributing margin pools from hardware vendors toward software platforms and managed service providers.
Growth Catalysts
- Smart mall mandates:Dubai and Riyadh development authorities are embedding indoor positioning infrastructure into new retail construction codes, creating captive demand for wayfinding and footfall analytics systems.
- Bluetooth spectrum harmonization:UAE Telecommunications and Digital Government Regulatory Authority and Saudi Communications and Information Technology Commission have aligned 2.4 GHz power thresholds, enabling cross-border equipment certification and vendor scale economies.
- Airport modernization programs:Abu Dhabi International and King Abdulaziz International are deploying passenger flow optimization systems, establishing reference architectures for secondary airports across Oman and Bahrain.
Market Restraints
- Silicon supply concentration:Bluetooth and ultra-wideband chip fabrication concentrates in Taiwan and South Korea foundries, exposing Gulf integrators to lead time volatility and currency hedging costs.
- GDPR-equivalent compliance friction:Bahrain and Qatar data protection frameworks impose explicit consent requirements for location data collection, complicating passive analytics deployments in hospitality settings.
- Wi-Fi fingerprinting saturation:Dense 5 GHz spectrum in Dubai and Riyadh commercial districts degrades signal stability, limiting accuracy in high-rise retail environments without supplemental beacon infrastructure.
Strategic Opportunities
- Underpenetrated logistics vertical:Saudi Arabia's warehouse automation initiatives remain underserved by RFID-integrated indoor positioning, presenting first-mover margins for asset visibility providers.
- Ultra-wideband convergence:Integration with smartphone OEM chipsets is enabling centimeter-accuracy use cases in museum and exhibition spaces previously uneconomical with Bluetooth alone.
- Subscription model migration:Hospitality groups in Qatar are piloting usage-based positioning analytics, shifting capital expenditure to operational expenditure and expanding addressable market to mid-tier hotel chains.
Industry Challenges
- RF engineering talent scarcity:Gulf universities produce limited graduates with expertise in time-of-flight calibration and multipath mitigation, forcing vendors to import specialized deployment teams from Europe and Asia-Pacific.
- Legacy building management system integration:Pre-2015 HVAC and lighting controllers in established Dubai malls lack API compatibility, requiring costly middleware development for unified occupancy intelligence.
- Certification timeline compression:MOHAP device approval pathways for healthcare-grade indoor positioning in UAE hospitals extend deployment cycles by four to six months versus commercial retail applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Indoor LBS Market |
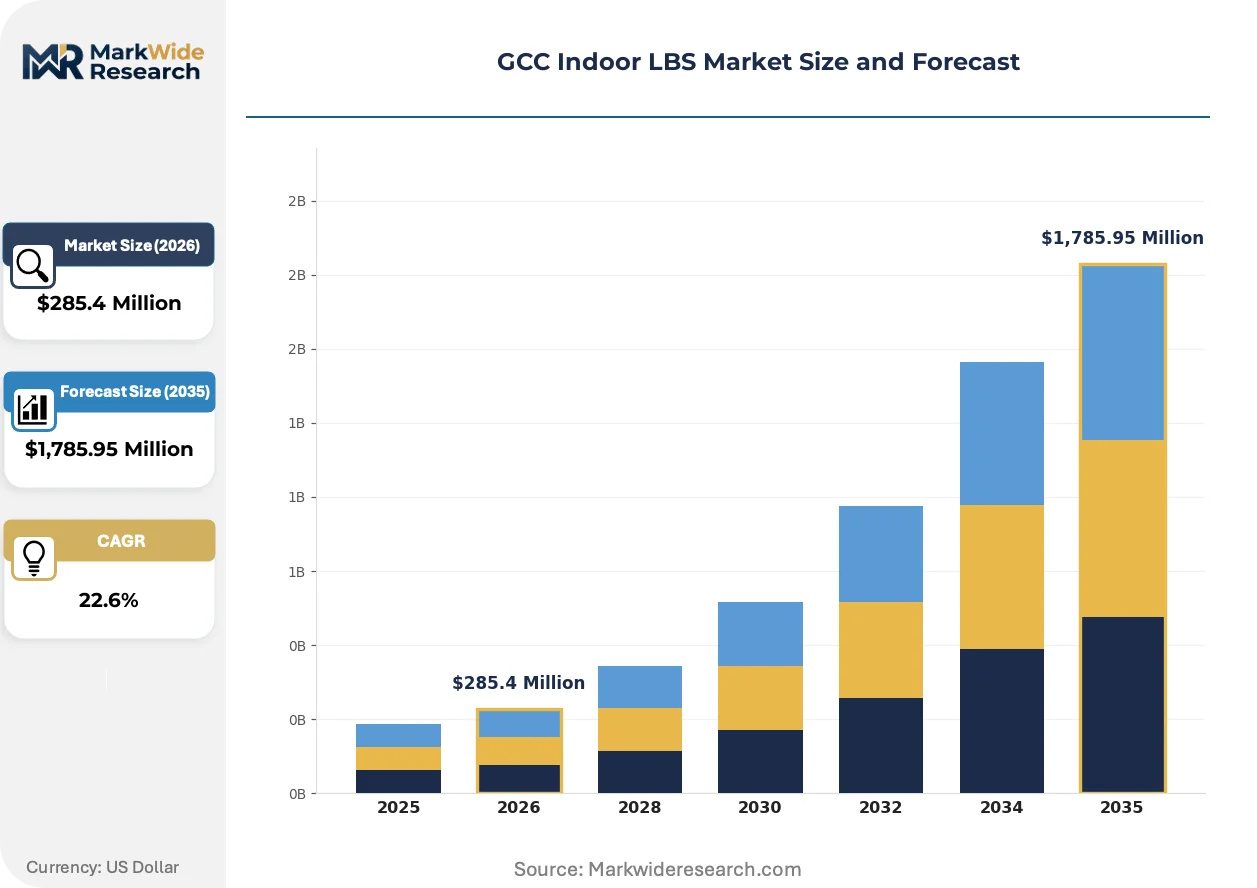
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $1,785.95 Million |
| CAGR (2026 – 2036) | 22.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Wi-Fi, Bluetooth, RFID, Ultrasound Application: Retail Analytics, Asset Tracking, Navigation, Emergency Management End User: Hospitality, Retail Chains, Educational Institutions, Airports Solution: Hardware, Software, Cloud Services, Integrated Systems |
| Companies Covered | Apple Inc., Cisco Systems Inc., Google Inc., HERE, IndoorAtlas Ltd., Micello, Inc., Qualcomm Technologies Inc., Microsoft Corp., GloPos, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Indoor LBS Market Strategic Shifts & Innovations
Artificial intelligence inference at the edge is redefining latency benchmarks and data sovereignty compliance for indoor positioning networks. This computational shift is unlocking real-time occupancy prediction and automated space reconfiguration previously constrained by cloud round-trip delays.
Ultra-wideband time-of-flight chips with integrated angle-of-arrival calculation are rendering obsolete Wi-Fi fingerprinting systems that require extensive site surveys and periodic recalibration. King Abdulaziz International Airport's Terminal 1 retrofit has adopted this architecture for passenger tracking, compressing deployment from eight months to ten weeks. The technology is enabling sub-meter accuracy without beacon density penalties, collapsing total cost of ownership for large-footprint venues.
UAE Telecommunications and Digital Government Regulatory Authority's 2024 device certification framework for short-range devices has harmonized testing protocols with Saudi Communications and Information Technology Commission standards, eliminating duplicate compliance costs for multi-country deployments. This regulatory convergence is accelerating vendor market entry timelines and reducing certification expenditure by approximately thirty percent for regional system integrators. Bahrain and Qatar are expected to adopt equivalent frameworks by 2026, completing Gulf Cooperation Council alignment.
Buyer procurement patterns are pivoting from capital purchase toward multi-year service agreements bundling hardware, software, and maintenance. Saudi hospitality groups now favor subscription contracts with uptime guarantees and accuracy service-level agreements over traditional equipment ownership. This shift is compressing vendor cash conversion cycles and favoring balance-sheet-strong platforms capable of financing customer deployments internally. The model is most advanced in Dubai's premium hotel segment, where operators prioritize operational flexibility over asset control.
GCC Indoor LBS Market Segmentation
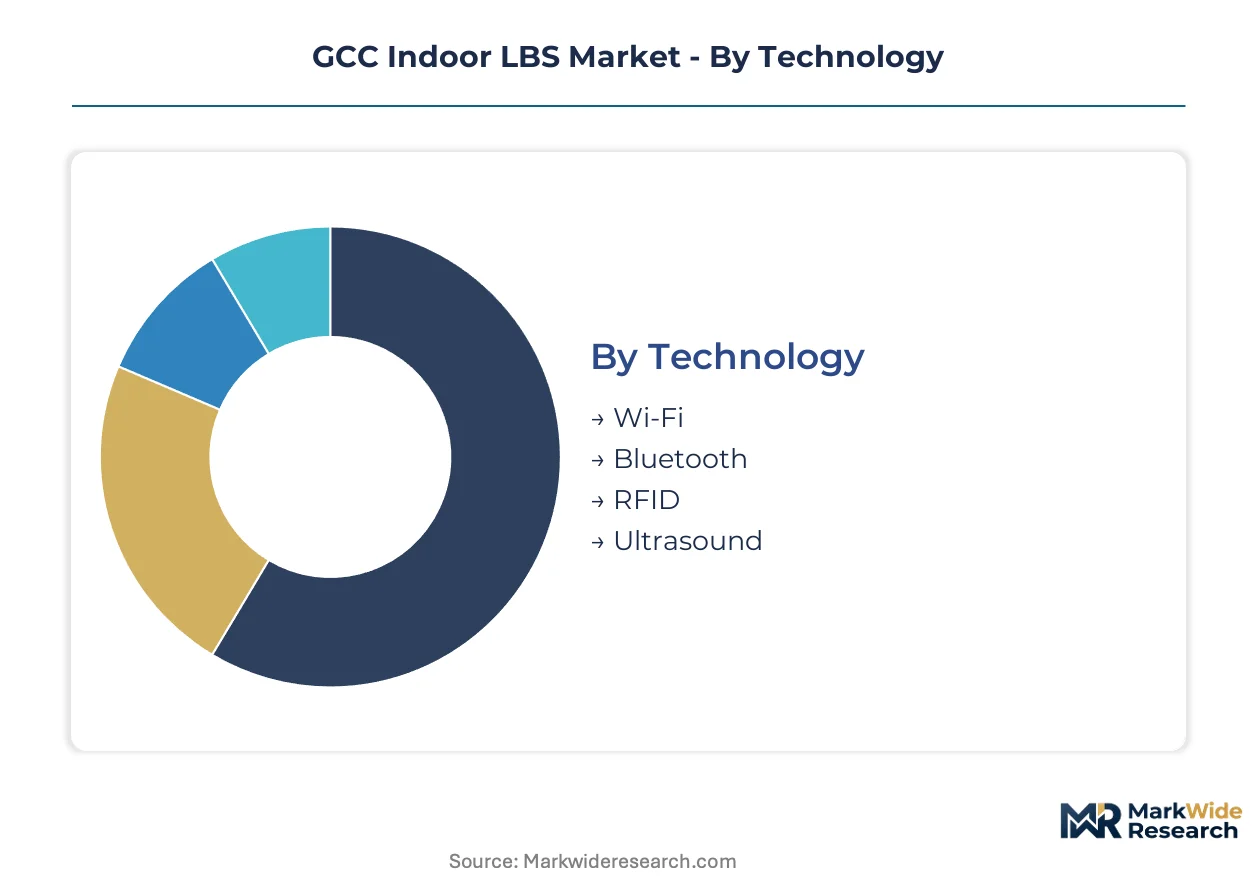
Technology heterogeneity across the GCC Indoor LBS Market creates divergent deployment economics and refresh cycles. Vendors must align solution architectures with venue-specific accuracy requirements and existing infrastructure reuse potential.
Technology:
Wi-Fi fingerprinting cycles every 3-4 years due to access point obsolescence, while Bluetooth beacon networks refresh every 18-24 months as battery-dependent nodes require replacement. RFID installations in logistics facilities operate on 7-10 year replacement horizons given passive tag durability.
- Wi-Fi:Signal triangulation leverages existing enterprise WLAN infrastructure to achieve 3-5 meter positioning accuracy without dedicated hardware overlays. Dubai Mall and Riyadh Park deployments concentrate demand here, though 5 GHz spectrum saturation in high-rise retail degrades stability during peak hours.
- Bluetooth:Low-energy beacon networks deliver 1-3 meter accuracy through received signal strength fingerprinting, with mesh topologies enabling battery-free operation via energy harvesting. Saudi smart mall mandates and UAE airport modernization programs are driving dense deployments across 2.4 GHz harmonized spectrum.
- RFID:Passive ultra-high-frequency tags support sub-meter asset visibility in warehouse and logistics environments where line-of-sight interrogation is feasible. Saudi Arabia's warehouse automation initiatives remain underserved, creating first-mover margins for integrated positioning providers.
- Ultrasound:Time-of-flight measurements using inaudible acoustic signals achieve centimeter-grade accuracy immune to radio-frequency interference. Museum and exhibition spaces in Doha and Manama pilot this technology where Bluetooth density proves uneconomical.
Wi-Fi anchors the volume base while Bluetooth gains share at the steepest rate.
Application:
Navigation deployments command premium pricing per square meter given real-time path calculation requirements, whereas retail analytics solutions scale through sensor density economies. Asset tracking applications exhibit the longest sales cycles due to enterprise resource planning integration complexity.
- Retail Analytics:Footfall pattern recognition, dwell time measurement, and conversion funnel analysis support merchandising decisions and lease rate negotiations. Dubai and Riyadh development authorities embed this capability into new construction codes, creating captive demand for wayfinding-integrated deployments.
- Asset Tracking:Real-time location systems monitor high-value equipment, inventory, and personnel across warehouse, healthcare, and industrial environments. King Abdulaziz International Airport's baggage handling optimization establishes reference architectures for secondary Gulf airports.
- Navigation:Turn-by-turn wayfinding guides visitors through complex indoor environments including multi-level retail, healthcare campuses, and transit hubs. Qatar's hospitality digitization initiatives prioritize this use case for guest experience differentiation.
- Emergency Management:Occupant location tracking and egress route optimization support first responder coordination during facility evacuations. UAE hospital MOHAP certification requirements extend deployment timelines for healthcare-grade implementations.
Retail Analytics generates the highest revenue concentration while Emergency Management expands most quickly as regulatory mandates harden.
End User:
Airport procurement operates on 5-7 year master plan cycles with bundled long-term service agreements, while retail chain deployments compress to 12-18 month rollout schedules across multiple properties. Hospitality buyers increasingly favor operational expenditure models over capital ownership.
- Hospitality:Guest wayfinding, staff coordination, and space utilization analytics enhance operational efficiency across hotel portfolios. Dubai's premium hotel segment leads subscription model adoption with uptime-guaranteed service-level agreements replacing equipment purchase.
- Retail Chains:Multi-site footfall standardization and loyalty program integration drive demand for cloud-native positioning architectures. Smart mall mandates in Dubai and Riyadh accelerate vendor consolidation as developers pre-qualify approved technology stacks.
- Educational Institutions:Campus safety applications and classroom occupancy optimization support hybrid learning space management. Bahrain and Qatar universities pilot these deployments as student experience investments.
- Airports:Passenger flow optimization, gate proximity marketing, and ground crew coordination demand sub-meter accuracy across expansive terminal footprints. Abu Dhabi International and King Abdulaziz International establish reference architectures for Oman and Bahrain secondary airports.
Airports dominate capital deployment value while Hospitality climbs the fastest on subscription model conversion.
Solution:
Hardware margins compress as beacon commoditization accelerates, whereas cloud services capture expanding margin pools through recurring revenue annuities. Integrated systems command price premiums for unified occupancy intelligence combining positioning with building management data.
- Hardware:Beacon nodes, access points, and gateway infrastructure form the physical sensing layer requiring periodic refresh. Taiwan and South Korea foundry concentration exposes Gulf integrators to lead time volatility and currency hedging costs.
- Software:Positioning engines, analytics dashboards, and application programming interfaces transform raw signal data into actionable intelligence. Cisco Systems bundles these capabilities with WLAN infrastructure refreshes leveraging enterprise networking installed base.
- Cloud Services:Managed subscription architectures eliminate on-premises server requirements while enabling multi-site data aggregation. Saudi hospitality groups and Qatar mid-tier hotel chains favor this operational expenditure shift.
- Integrated Systems:Unified hardware-software-service bundles with accuracy guarantees and uptime commitments reduce buyer procurement complexity. Pre-2015 HVAC and lighting controllers in established Dubai malls force costly middleware development for full integration.
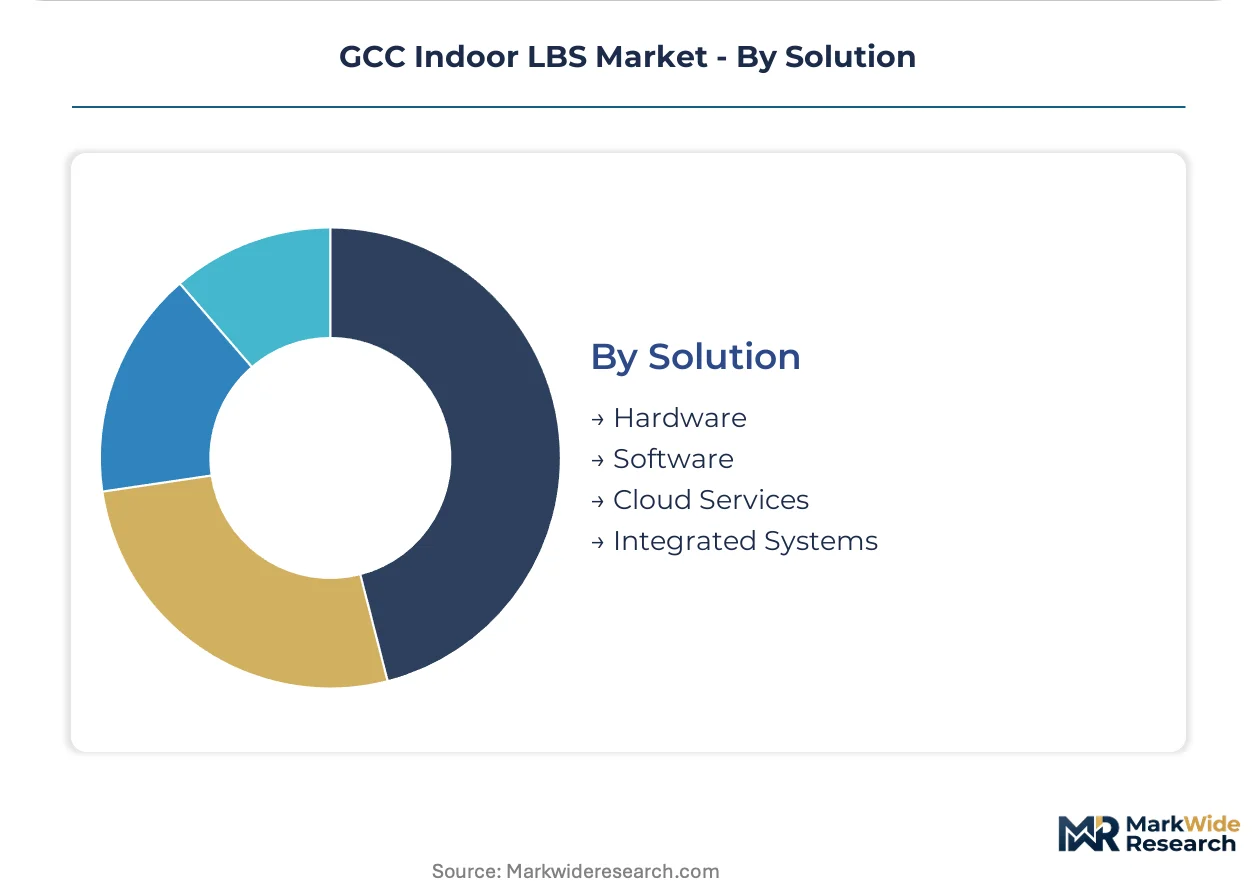
Hardware anchors the volume base while Cloud Services gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Subscription elasticity varies sharply across Gulf Cooperation Council states. UAE hospitality buyers absorb premium pricing for uptime-guaranteed service-level agreements, while Saudi retail chains negotiate aggressively on hardware refresh cycles. Bahrain and Qatar mid-tier operators delay deployments pending clearer data protection enforcement timelines.
United Arab Emirates
Dubai Mall and Abu Dhabi International Airport anchor regional deployment volumes for wayfinding and passenger flow optimization. UAE Telecommunications and Digital Government Regulatory Authority's 2024 short-range device certification framework harmonized testing protocols with Saudi standards, eliminating duplicate compliance costs. Dubai's premium hotel segment leads subscription model conversion across the Gulf.
Saudi Arabia
King Abdulaziz International Airport Terminal 1 retrofit established ultra-wideband reference architecture for secondary airports across Oman and Bahrain. Saudi Communications and Information Technology Commission aligned 2.4 GHz power thresholds with UAE regulators, enabling cross-border equipment certification. Riyadh Park and smart mall mandates in the capital create captive demand for footfall analytics systems.
Qatar
Museum and exhibition spaces in Doha pilot ultrasound time-of-flight technology where Bluetooth beacon density proves uneconomical. GDPR-equivalent data protection frameworks impose explicit consent requirements for location data collection, complicating passive analytics in hospitality settings. Qatar's hospitality digitization initiatives prioritize navigation use cases for guest experience differentiation.
Bahrain
Universities in Manama pilot campus safety applications and classroom occupancy optimization as student experience investments. Bahrain's emerging data protection framework mirrors Qatar's consent and retention obligations for retail and hospitality location data collection. Regulatory alignment with UAE and Saudi standards is expected by 2026.
Oman
Secondary airports defer passenger flow optimization deployments pending reference architecture validation from Abu Dhabi and Jeddah implementations. Spectrum allocation frameworks remain under development, creating uncertainty for cross-border equipment procurement. Logistics automation initiatives in Muscat remain underserved by RFID-integrated indoor positioning.
GCC Indoor LBS Market Key Industry Players
Capability concentration sits with specialized positioning engine developers; scale advantage sits with enterprise networking incumbents with installed base leverage. The market structures around three tiers: chipset-level hardware suppliers, cloud-native software platforms, and integrated infrastructure vendors bundling WLAN refreshes with positioning services. Dominant competitive moves include strategic partnerships between beacon manufacturers and system integrators, plus portfolio diversification into subscription-based managed services.
Within the integrated infrastructure tier, Cisco Systems Inc. and Qualcomm Technologies Inc. exemplify divergent scale strategies. Cisco leverages enterprise networking installed base across Gulf commercial real estate for bundled positioning deployments. Qualcomm anchors chipset-level Bluetooth and ultra-wideband integration for original equipment manufacturers. Google Inc. occupies a consumer-grade intelligence position through Android ecosystem penetration and mapping data layers.
| Leading Market Players |
|---|
| Apple Inc. |
| Cisco Systems Inc. |
| Google Inc. |
| HERE |
| IndoorAtlas Ltd. |
| Micello, Inc. |
| Qualcomm Technologies Inc. |
| Microsoft Corp. |
| GloPos |
| Others |
Cost & Logistics Intelligence
Single-source dependency on Taiwan and South Korea foundries for Bluetooth and ultra-wideband chip fabrication compresses pricing tier spreads while forcing Gulf integrators into currency-hedged procurement structures. This concentration simultaneously elevates premium pricing for guaranteed supply allocations and erodes margins on standard-tier deployments exposed to spot-market volatility.
Pricing Analysis
Subscription service tiers and multi-year managed service agreements now drive lifetime value capture, displacing perpetual hardware licensing. Three-tier pricing structure across premium accuracy-guaranteed, standard cloud-native, and economy self-managed levels differentiates by SLA uptime commitments and calibration support depth. Pricing pressure stems from beacon commoditization as Shenzhen-based manufacturers flood the 2.4 GHz module market. Saudi retail chains exhibit acute price sensitivity on hardware refresh cycles, while UAE hospitality buyers absorb premiums for operational expenditure flexibility.
Supply Chain Analysis
Upstream feedstock of semiconductor wafers and rare-earth magnet materials for beacon assembly draws from Taiwan, South Korea, and Chinese packaging facilities. Bluetooth Low Energy chipsets, ultra-wideband transceivers, and passive UHF RFID inlays constitute critical component dependencies. Single-source vulnerability concentrates in TSMC advanced node allocation for angle-of-arrival calculation silicon. Distribution runs through Dubai-based system integrators serving Saudi and UAE deployment clusters, with secondary routing via Doha for Qatar and Bahrain projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GCC Indoor LBS sits at high-growth disruption driven by UAE-Saudi regulatory harmonization eliminating cross-border certification friction. This inflection compresses vendor entry timelines and redistributes margin pools toward software platforms.
For Market Incumbents: Pre-empt cloud-native platform consolidation by acquiring specialized positioning engine developers before subscription economics lock in customer switching costs. Defend against Qualcomm chipset bundling by embedding proprietary calibration IP in managed service layers. Prioritize UAE Telecommunications and Digital Government Regulatory Authority pre-certification to accelerate Saudi Communications and Information Technology Commission reciprocal approval.
For New Entrants and Emerging Players: Pursue Saudi warehouse automation verticals where RFID-integrated asset tracking remains structurally underserved. Target Bahrain and Oman secondary airports pending reference architecture validation from Abu Dhabi and Jeddah implementations. Lead with usage-based analytics pilots converting capital expenditure to operational expenditure for Qatar mid-tier hospitality chains.
For Investors and Strategic Acquirers: The market sits at a platform consolidation phase that favors balance-sheet-strong vendors capable of financing customer deployments internally. Long-term viability over the coming decade hinges on recurring revenue annuity capture rather than hardware shipment volume. Signal to watch: Saudi smart mall mandate expansion beyond Riyadh into secondary cities as inflection indicator for addressable market scaling.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Cisco bundles positioning engines with WLAN refreshes leveraging enterprise installed base. |
| Strategic Partnership | Beacon manufacturers align with Dubai system integrators for smart mall mandate compliance. |
| Acquisition of Specialist Firm | Cloud-native positioning engine developers command premium multiples for AI inference capabilities. |
| Geographic Expansion | UAE-Saudi regulatory harmonization enables cross-border equipment certification at reduced cost. |
| Product Launch | Ultra-wideband time-of-flight chips with integrated angle-of-arrival displace Wi-Fi fingerprinting. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with airport IT directors, hospitality technology officers, retail chain operations executives, and system integration project managers; and secondary validation through UAE Telecommunications and Digital Government Regulatory Authority certification filings, Saudi Communications and Information Technology Commission spectrum allocation notices, Dubai Mall and Riyadh Park procurement documentation, and Gulf Cooperation Council trade flow records. Bottom-up deployment volume estimates triangulated against top-down infrastructure investment disclosures.
Forecast inputs span technology refresh cycles, regulatory harmonization timelines, and vertical adoption curves across the projection horizon. Segmentation dimensions modeled include positioning technology, application use case, end-user vertical, and solution architecture. CAGRs derive from deployment run-rate analysis and infrastructure investment pipeline tracking. Industry-specific inputs incorporate smart mall construction permit data and airport master plan disclosure patterns.
Sensitivities concentrate around Taiwan foundry allocation disruptions, Bahrain and Qatar data protection enforcement timing, and 5 GHz spectrum saturation thresholds in high-rise retail environments. Cross-checking against Dubai Department of Economy and Tourism hospitality investment disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Smart Sprinkler Controller Market
Internet of Things (IoT)
Smart Connected Device Market
Internet of Things (IoT)
Airline IoT Market
Internet of Things (IoT)
Mobile-Connecting Smart Objects Market
Internet of Things (IoT)
Global Narrowband IoT Market
Internet of Things (IoT)
US Smart Thermostat Market
Internet of Things (IoT)
Global IoT in Warehouse Market
Internet of Things (IoT)
Global IoT Engineering Services Market
Internet of Things (IoT)
LAMEA Bluetooth 5.0 Market
Internet of Things (IoT)
Cellular IoT Module Market
Internet of Things (IoT)
IoT Device Management Market
Internet of Things (IoT)
IoT IAM Market
Internet of Things (IoT)
UK IoT Software Market
Internet of Things (IoT)
Global IoT Connectivity Market
Internet of Things (IoT)
Consumer Internet of Things (IoT) Market
Internet of Things (IoT)
IoT Cloud Platform Market