
 Global Internet of Things (IoT) Software Market | 2026-2036
Global Internet of Things (IoT) Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Internet of Things (IoT) Software Market Foresight
Platform bundling is repositioning buyer procurement patterns across the IoT software stack. Microsoft leverages its Azure IoT suite to anchor enterprise contracts through integrated cloud and edge modules. Amazon Web Services competes with specialized device management and analytics layers that extend its infrastructure footprint. Siemens dominates industrial IoT through its MindSphere platform, which sustains deep manufacturing vertical integration.
Internet of Things (IoT) Software encompasses embedded middleware, device management protocols, data analytics engines, and security frameworks that enable connected hardware to transmit, process, and act upon operational data in real time. The technology serves commercial and industrial purposes by converting sensor streams into actionable intelligence for automated control and predictive decision-making. Cloud-based deployment leads in revenue contribution due to scalability requirements across distributed device fleets, while edge computing represents the fastest-expanding configuration as latency-sensitive applications proliferate in smart grids and precision agriculture. Security solutions command premium margins because regulatory mandates and ransomware exposure have elevated encryption and access management to board-level procurement criteria.
The U.S. Food and Drug Administration, the European Union's GDPR and AI Act frameworks, and China's Ministry of Industry and Information Technology standards collectively shape product certification pathways and cross-border data governance obligations for IoT software vendors. FDA cybersecurity guidance for connected medical devices directly elevates security module spending, while MIIT's GB standards for industrial internet platforms mandate domestic encryption protocols that influence market access conditions in China. Stakeholders must monitor divergence between regional compliance architectures when architecting product roadmaps and partnership strategies.
Market Dynamics
Platform consolidation is compressing vendor margins as hyperscalers bundle device management, analytics, and security into unified subscriptions that displace point solutions.
Growth Catalysts
- EU AI Act compliance mandates:European manufacturers must embed explainable AI modules in predictive maintenance systems, accelerating procurement of certified edge analytics stacks.
- Precision agriculture sensor networks:Variable-rate irrigation controllers in water-stressed regions demand low-latency edge processing for real-time soil moisture response.
- Industrial digitalization programs:Germany's Industrie 4.0 initiatives and China's MIIT industrial internet standards drive platform standardization across automotive and heavy machinery supply chains.
Market Restraints
- Semiconductor supply concentration:Advanced microcontroller and FPGA fabrication concentrates in Taiwan and South Korea, exposing IoT gateway manufacturers to geopolitical disruption risk.
- GDPR cross-border data friction:EU data localization requirements complicate cloud-to-edge synchronization architectures for multinational fleet operators.
- Legacy OT protocol incompatibility:Proprietary Modbus and PROFIBUS implementations in brownfield manufacturing plants resist seamless IP-based integration without costly middleware layers.
Strategic Opportunities
- India smart city infrastructure:Municipal IoT deployments for traffic management and waste collection remain underpenetrated relative to urban population growth trajectories.
- Digital twin convergence with AI:Physics-based simulation merged with machine learning enables closed-loop optimization in process industries previously limited to static modeling.
- Outcome-based service contracting:Equipment manufacturers monetize uptime guarantees rather than software licenses, capturing lifetime value through performance-linked pricing.
Industry Challenges
- Embedded cybersecurity expertise scarcity:Firmware hardening, secure boot implementation, and side-channel attack mitigation require specialized skill sets in short supply across vendor engineering teams.
- Multi-certification timeline compression:FDA cybersecurity guidance for connected medical devices, EU MDR conformity assessment, and IEC 62443 industrial security standards impose overlapping validation cycles that extend product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Internet of Things (IoT) Software Market |
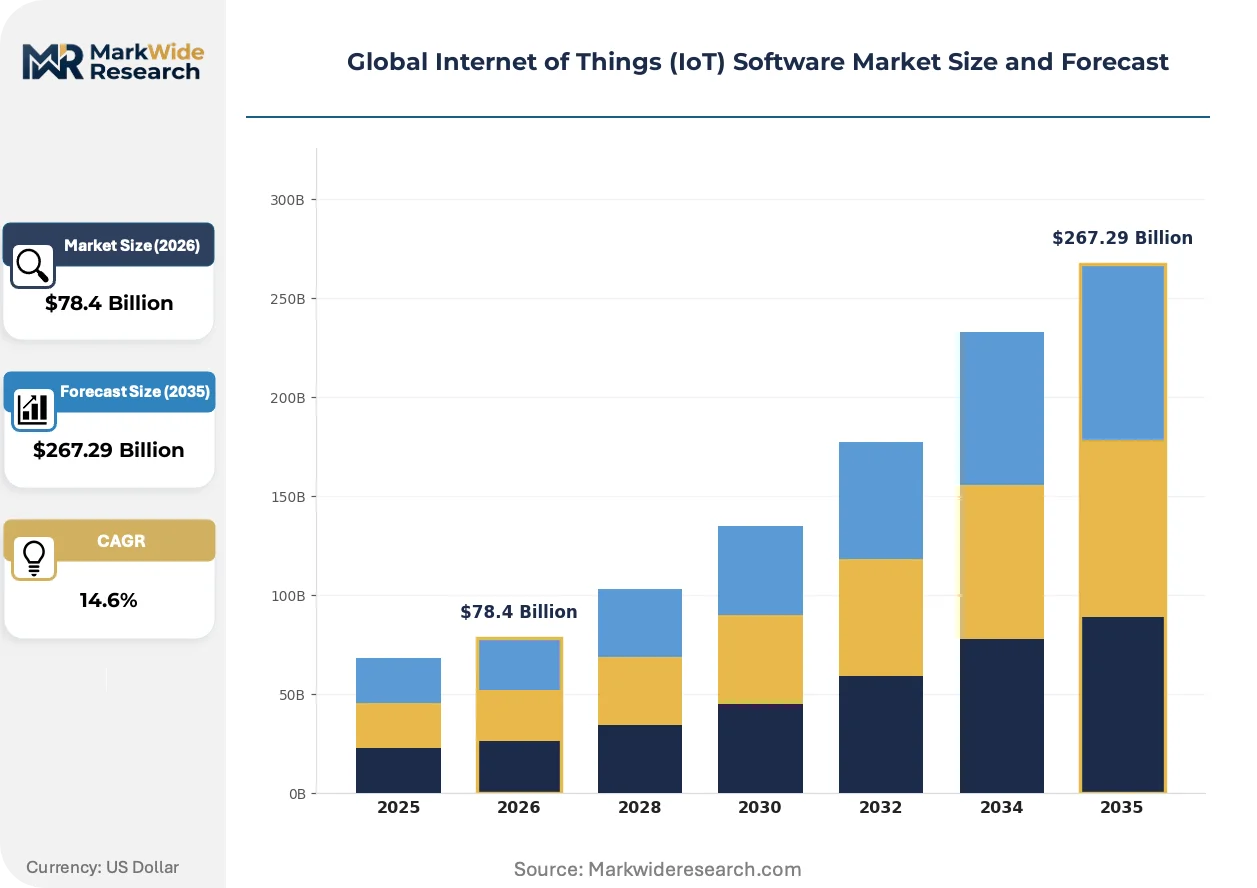
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $267.29 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing Solution Type: Device Management, Data Analytics, Security, Connectivity Management, Application Enablement Use Case: Smart Cities, Precision Agriculture, Fleet Management, Environmental Monitoring, Smart Grids End User Industry: Manufacturing, Energy & Utilities, Transportation, Agriculture, Consumer Electronics |
| Companies Covered | Microsoft, Amazon Web Services, IBM, Cisco Systems, Siemens, Oracle, PTC, SAP, Google, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Internet of Things (IoT) Software Market Shifts & Advancements
Software-defined architectures are dissolving hardware-software boundaries as virtualized network functions and containerized workloads migrate to resource-constrained edge devices.
Federated learning architectures are absorbing training workloads that previously required centralized cloud aggregation. Agricultural cooperatives and distributed manufacturing sites now refine machine learning models locally using aggregated telemetry without transmitting raw sensor data. This compression of data gravity is reshaping cloud provider edge service roadmaps and data residency compliance strategies.
China's MIIT GB standards for industrial internet platforms mandate domestic encryption protocols and data governance frameworks that diverge from ISO/IEC 27001 baselines. Equipment vendors serving multinational manufacturers must maintain parallel certification tracks, elevating compliance engineering headcount and extending product qualification timelines for the Chinese market specifically.
Subscription bundling is displacing perpetual licensing across enterprise procurement functions. Industrial buyers now expect predictive analytics, security patches, and API access as standard inclusions rather than separately negotiated modules. German automotive suppliers and US pharmaceutical manufacturers have been fastest to consolidate vendor relationships around platform ecosystems that reduce integration overhead.
Global Internet of Things (IoT) Software Market Segmentation
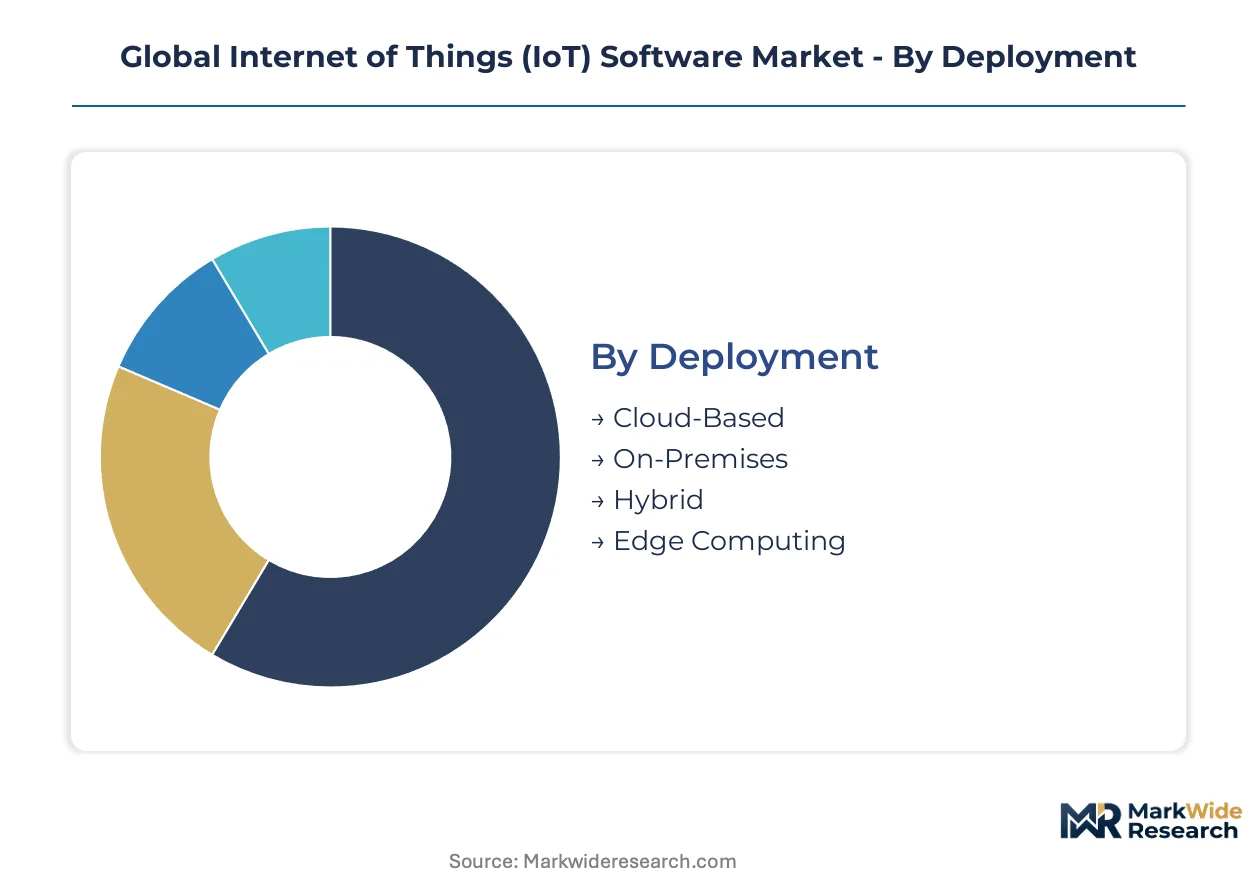
IoT software segmentation reveals divergent procurement patterns across deployment architectures, solution stacks, and vertical applications. Buyers prioritize different capability bundles based on latency tolerance, regulatory exposure, and legacy infrastructure constraints.
Deployment:
Standardization dominates at the infrastructure layer, yet customization intensity varies sharply by latency requirements and data sovereignty obligations.
- Cloud-Based:Centralized orchestration platforms handle device provisioning, over-the-air updates, and telemetry aggregation across distributed fleets. German automotive suppliers and US pharmaceutical manufacturers consolidate procurement around hyperscaler ecosystems to reduce integration overhead.
- Edge Computing:Containerized workloads execute inference and control loops on resource-constrained gateways. Water-stressed agricultural regions in Spain and Australia deploy variable-rate irrigation controllers requiring sub-100ms response times for soil moisture adjustments.
- On-Premises:Air-gapped installations serve defense contractors and critical infrastructure operators with zero-trust network architectures.
- Hybrid:Policy-driven workload placement splits processing between local nodes and remote data centers based on data classification tiers.
Most installed capacity flows through Cloud-Based deployments. Expansion is steepest in Edge Computing.
Solution Type:
Margin concentration tracks regulatory complexity rather than functional sophistication, with security modules commanding premium pricing due to compliance mandates.
- Security:Embedded encryption, secure boot chains, and access management frameworks harden firmware against side-channel attacks. FDA cybersecurity guidance for connected medical devices and EU AI Act conformity requirements elevate procurement to board-level decisions in US and European healthcare systems.
- Data Analytics:Stream processing engines convert sensor telemetry into operational intelligence through time-series databases and machine learning pipelines. Chinese industrial internet platforms under MIIT GB standards mandate domestic analytics stacks for state-owned manufacturing enterprises.
- Device Management:Lifecycle orchestration covers provisioning, configuration, and retirement of heterogeneous hardware fleets.
- Connectivity Management:Protocol abstraction layers normalize communication across cellular, LPWAN, and satellite networks.
- Application Enablement:Low-code development environments accelerate vertical solution deployment without embedded engineering expertise.
Security solutions capture the highest margin per seat. Application Enablement is gaining share fastest among mid-market manufacturers lacking dedicated IoT engineering teams.
Use Case:
Volume scales with public infrastructure budgets, while private deployment velocity correlates with commodity price volatility and climate risk exposure.
- Smart Cities:Integrated traffic signal optimization, waste collection routing, and public safety sensor networks. Indian municipal corporations under the Smart Cities Mission drive procurement concentration despite implementation gaps relative to urban population growth trajectories.
- Precision Agriculture:Soil moisture, weather, and crop health sensors enable variable-input management. Australian Murray-Darling Basin water authorities mandate telemetry installation for irrigation license compliance amid chronic drought conditions.
- Fleet Management:Vehicle telematics optimize routing, fuel consumption, and predictive maintenance for logistics operators.
- Environmental Monitoring:Air quality, water quality, and emissions sensors support regulatory compliance and public health surveillance.
- Smart Grids:Distribution automation and demand response systems balance renewable intermittency across electrical networks.
Smart Cities account for the largest public-sector committed spend. Precision Agriculture shows the steepest expansion trajectory as water stress intensifies across major growing regions.
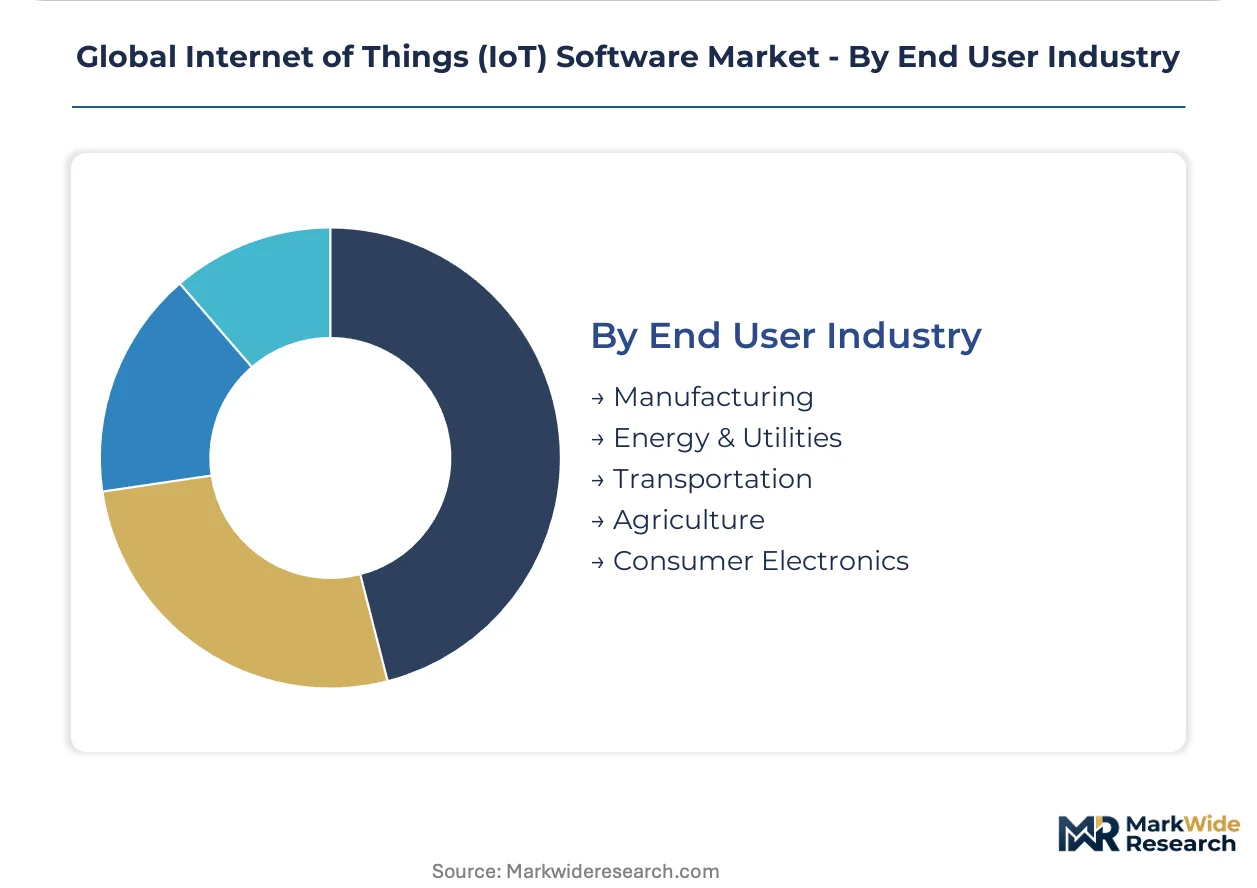
End User Industry:
Technology maturity separates industries with standardized reference architectures from those wrestling with brownfield protocol fragmentation.
- Manufacturing:Predictive maintenance, digital twin simulation, and quality control automation. Germany's Industrie 4.0 initiatives and China's MIIT industrial internet standards drive platform standardization across automotive and heavy machinery supply chains.
- Energy & Utilities:Grid modernization, distributed energy resource management, and pipeline integrity monitoring. US FERC Order 2222 accelerates aggregation platform deployment for behind-the-meter assets.
- Transportation:Connected vehicle platforms, autonomous navigation systems, and freight optimization engines.
- Agriculture:Mechanization telemetry and precision input management for large-scale farming operations.
- Consumer Electronics:Smart home ecosystems, wearable health monitors, and connected appliance firmware.
Manufacturing hosts the deepest installed base of industrial IoT platforms. Energy & Utilities is climbing the fastest as electrification mandates reshape grid investment cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Internet of Things software industry traces its commercial origins to Silicon Valley's sensor-network startups of the late 2000s, with industrial scale emerging from Germany's automotive automation clusters and China's state-directed manufacturing upgrades during the 2010s.
United States
FDA cybersecurity guidance for connected medical devices drives hospital procurement of hardened edge analytics stacks. FERC Order 2222 accelerates distributed energy resource aggregation platforms across Texas and California grid operators. Seattle and Boston harbor dense concentrations of cloud-native device management vendors serving pharmaceutical and defense verticals.
Germany
Industrie 4.0 reference architectures standardize predictive maintenance deployments across automotive supply chains. EU AI Act conformity requirements mandate explainable AI modules in manufacturing execution systems. Stuttgart and Munich industrial clusters anchor Siemens MindSphere ecosystem penetration among tier-one suppliers.
China
MIIT GB standards for industrial internet platforms mandate domestic encryption protocols for state-owned manufacturing enterprises. Dual carbon goals accelerate smart grid software procurement across provincial power utilities. Yangtze River Delta manufacturing hubs concentrate indigenous IoT platform development for textile and electronics exporters.
India
Smart Cities Mission allocations fund municipal IoT deployments for traffic signal optimization and waste collection routing. Bureau of Indian Standards certification requirements shape gateway procurement specifications for utilities. Bangalore and Hyderabad technology corridors incubate edge analytics startups serving agricultural cooperatives in Karnataka and Maharashtra.
Japan
METI digital transformation subsidies support precision agriculture sensor networks in Hokkaido grain belts. JIS standards for industrial communication protocols influence domestic platform interoperability requirements. Nagoya automotive manufacturing clusters deploy digital twin software for production line optimization and quality control automation.
Global Internet of Things (IoT) Software Market Competitive Landscape
Premium-margin players sit above commodity-margin players across security certification depth and vertical integration intensity. Hyperscalers bundle device management, analytics, and cloud infrastructure into unified subscriptions that compress point-solution vendor pricing power. Three archetypes dominate: cloud-native platform providers, industrial automation incumbents with captive hardware ecosystems, and specialized cybersecurity vendors. Consolidation proceeds through strategic partnerships between semiconductor fabricators and software stack vendors, plus geographic expansion via localized data residency compliance.
Among hyperscaler-platform providers, Microsoft and Amazon Web Services anchor enterprise procurement consolidation through integrated cloud-edge modules. Siemens occupies a distinct position within industrial automation archetypes, leveraging manufacturing vertical integration to sustain platform ecosystem lock-in. These three exemplify divergent competitive vectors: horizontal infrastructure scale versus vertical industry depth versus hybrid bundling strategies.
| Leading Market Players |
|---|
| Microsoft |
| Amazon Web Services |
| IBM |
| Cisco Systems |
| Siemens |
| Oracle |
| PTC |
| SAP |
| Others |
Supply & Pricing Matrix
China's dual carbon goals and EU Green Deal compliance mandates gate qualified supply and premium-tier pricing access for IoT software vendors serving energy-intensive manufacturing verticals. Vendors lacking certified green software modules face exclusion from state-owned enterprise procurement in China and carbon-adjusted contract terms in Europe, compressing margins for uncertified competitors while rewarding sustainability-integrated platforms with pricing power.
Pricing Analysis
Subscription bundling across cloud-edge-security modules stratifies procurement into premium, standard, and economy tiers based on certification depth and vertical integration intensity. Price differentiation hinges on FDA cybersecurity validation for medical device stacks and MIIT GB compliance for Chinese industrial platforms. Pricing pressure stems from hyperscaler bundling that compresses point-solution vendor margins. Mid-market manufacturers lacking dedicated IoT engineering teams exhibit highest price sensitivity, while defense contractors and pharmaceutical manufacturers accept premium tiers for air-gapped deployments and regulatory assurance.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and Singapore anchor hub-and-spoke fulfillment patterns for edge gateway hardware and embedded security modules. Semiconductor fabrication concentrates in Taiwan and South Korea, exposing IoT gateway manufacturers to single-source vulnerability for advanced microcontrollers and FPGAs. Raw material dependencies span silicon wafers, rare earth elements for sensor components, and lithium-ion cells for field-deployed power systems. Distribution runs through authorized channel partners serving discrete manufacturing verticals, with direct fulfillment growing among hyperscaler-platform providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities separate vendors with EU AI Act compliance infrastructure from competitors lacking European certification capabilities, creating margin capture potential for cross-regional platform standardization. Cost differentials between German Industrie 4.0 reference architecture investments and India's emerging smart city deployments favor modular software architectures adaptable to both premium and price-sensitive procurement contexts.
For Market Incumbents: Deepen vertical integration into semiconductor supply partnerships to secure microcontroller allocation priority during fabrication constraints. Fortify certification moats by accelerating FDA cybersecurity validation and EU MDR conformity assessment timelines ahead of competitor product launches. Hyperscaler bundling threats demand ecosystem lock-in through predictive maintenance outcome guarantees that displace point-solution alternatives. For New Entrants and Emerging Players: Launch via agricultural cooperative channels in water-stressed regions of Spain and Australia where variable-rate irrigation controllers face low incumbent saturation. Target municipal IoT deployments in Indian smart cities where implementation gaps exceed urban population growth trajectories. Federated learning architectures for soil moisture analytics offer differentiated entry without centralized cloud infrastructure investment. For Investors and Strategic Acquirers: Roll-up economics work for cybersecurity specialists because regulatory fragmentation across FDA, EU AI Act, and MIIT GB standards prevents single-vendor compliance scale, creating acquisition value in certified niche players. Five-to-ten-year viability hinges on embedded firmware hardening capabilities scarce across vendor engineering teams. Watch FDA enforcement actions against connected medical device vulnerabilities as inflection indicator for security module valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Microsoft Azure IoT suite anchors enterprise contracts through unified cloud-edge modules. |
| Regulatory Certification Investment | FDA cybersecurity guidance elevates procurement of hardened medical device stacks to board-level decisions. |
| Strategic Partnership | Siemens MindSphere ecosystem sustains manufacturing vertical integration among German automotive suppliers. |
| Geographic Expansion | MIIT GB standards compliance enables market access for industrial platforms serving Chinese state-owned enterprises. |
| Acquisition of Specialist Firm | Embedded security vendors capture premium margins as ransomware exposure elevates encryption to procurement priority. |
Research Methodology
Multiple input streams — primary interviews with platform engineers and IT procurement officers, hyperscaler capex disclosures, and regulatory filing analysis — were reconciled through bottom-up and top-down triangulation. Conversations with CTOs at German automotive suppliers, integration specialists serving pharmaceutical manufacturers, and channel partners in Indian smart city deployments informed demand-side validation. Secondary sources encompassed SEC filings from publicly traded vendors, FDA cybersecurity guidance documents, EU AI Act implementation texts, and MIIT GB standard specifications.
Data-stream reconciliation across deployment models, organization size tiers, vertical applications, and regional adoption patterns structured the analytical framework. CAGRs were derived from installed base expansion rates and average revenue per account trajectories across cloud-based, edge computing, on-premises, and hybrid configurations. Forecast inputs incorporated semiconductor supply constraints, regulatory timeline compression effects, and federated learning adoption curves in precision agriculture.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained Taiwan Strait geopolitical disruption or accelerated EU AI Act enforcement timelines. Outputs reflect documented assumptions regarding hyperscaler bundling velocity and legacy OT protocol substitution rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
IoT Application Development Services Market
Internet of Things (IoT)
Edge Computing in IoT Market
Internet of Things (IoT)
Global IoT Engineering Services Market
Internet of Things (IoT)
IoT in Warehouse Management Market
Internet of Things (IoT)
Internet of Things (IoT) Platform Market
Internet of Things (IoT)
IoT Software Market
Internet of Things (IoT)
Qatar Internet of Things (IoT) Market
Internet of Things (IoT)
IoT Utilities Market
Internet of Things (IoT)
IoT Development Kit Market
Internet of Things (IoT)
South Africa IoT Market
Internet of Things (IoT)
Connected Bottles Market
Internet of Things (IoT)
IoT Device Management Market
Internet of Things (IoT)
IOT in Aviation Market
Internet of Things (IoT)
Global Pervasive Computing Technology Market
Internet of Things (IoT)
Europe IoT Services Market
Internet of Things (IoT)
Private Narrowband IoT Market