
 IoT at Workplace Market | 2026-2036
IoT at Workplace Market Size, Share, and Industry Trends Forecast 2026-2036
IoT at Workplace Market Foresight
Market Context
The capability gap between cloud-native platform builders and legacy automation suppliers is unwinding as capital requirements for edge-to-cloud infrastructure diverge. Microsoft leverages its Azure IoT stack to anchor enterprise workplace deployments across hybrid work environments. Cisco competes through specialized networking hardware that dominates building-scale connectivity installations. Siemens sustains its position via deep vertical expertise in smart HVAC and building management systems.
Technical Definition and Segment Structure
IoT at Workplace encompasses sensor networks, edge gateways, and cloud analytics platforms that monitor environmental conditions, asset locations, and occupant behavior within commercial facilities, typically operating on sub-gigahertz wireless protocols with latency thresholds under 100 milliseconds for real-time climate and security adjustments. Smart HVAC systems command the largest installed base among product types due to energy cost pressures, while wearables represent the fastest-expanding category as biometric safety monitoring spreads through manufacturing and logistics sites. Facility management applications capture the deepest margin pools by integrating multiple building systems into unified command platforms.
Regulatory Framework and Outlook
The EU AI Act and GDPR impose strict algorithmic transparency and data residency requirements on workplace biometric and behavioral analytics systems, compelling vendors to rearchitect cloud processing pipelines. The FCC in the United States governs spectrum allocation for Zigbee and Wi-Fi deployments in commercial buildings, directly shaping device certification timelines and market access conditions. NIST cybersecurity frameworks further constrain how sensor data traverses corporate networks. Stakeholders must monitor evolving interoperability mandates between these regulatory regimes to anticipate compliance-driven procurement shifts.
Market Dynamics
EU AI Act enforcement timelines and GDPR data residency mandates are compressing vendor cloud architectures and redistributing competitive advantage toward edge-native platform providers.
Growth Catalysts
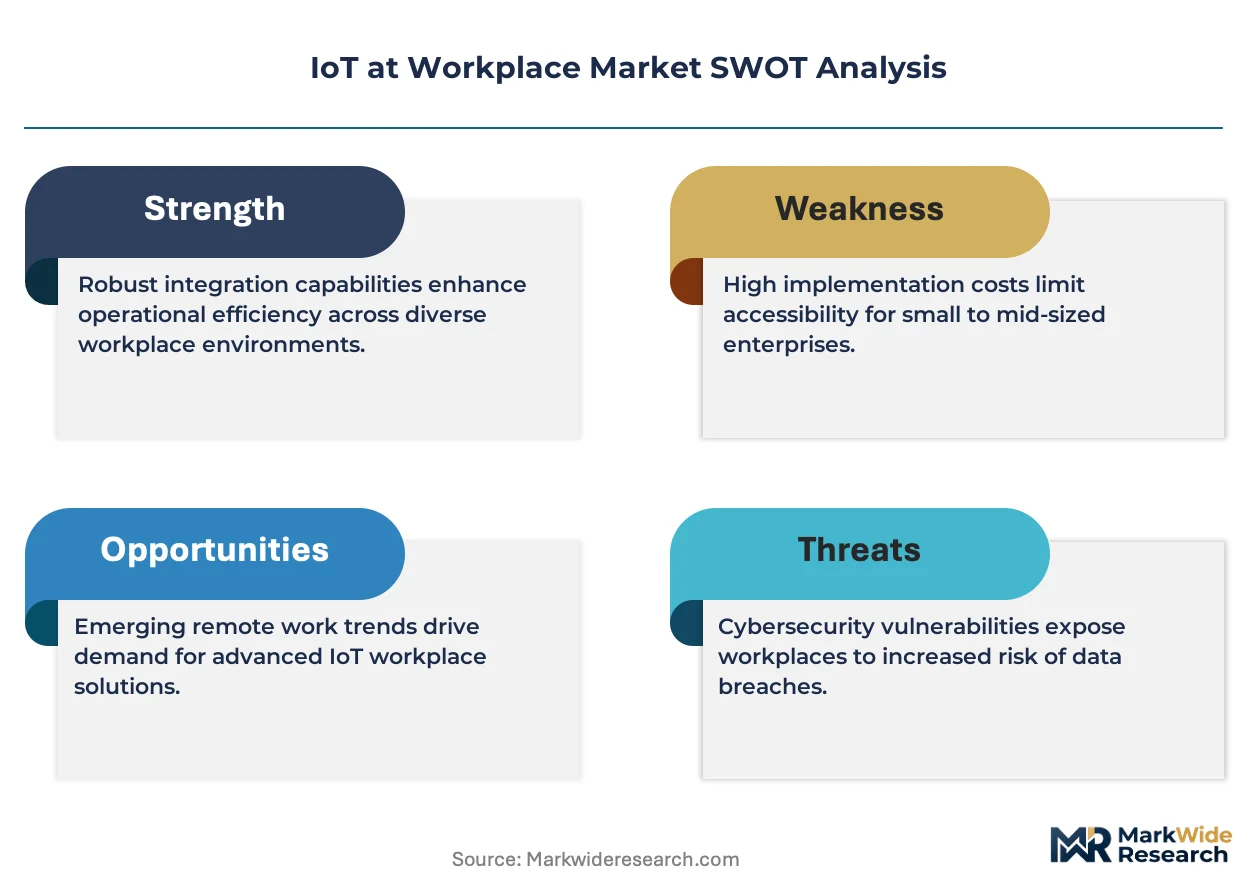
- Smart HVAC Retrofit Mandates:Corporate net-zero commitments in Germany and France are accelerating sensor deployment in existing building stock. Energy cost pressures drive replacement cycles.
- EU AI Act Compliance:Algorithmic transparency requirements for workplace biometric systems are creating procurement preference for certified edge-analytics platforms over unvalidated cloud alternatives.
- Sub-Gigahertz Protocol Maturation:LoRaWAN and Zigbee certification programs are reducing interoperability friction in multi-vendor building deployments across industrial campuses.
Market Restraints
- Silicon Supply Concentration:Edge gateway semiconductor fabrication concentrates in Taiwan, exposing deployment timelines to geopolitical supply disruptions.
- GDPR Cross-Border Friction:Data residency requirements block centralized cloud processing for multinational headquarters, fragmenting platform economics.
- Legacy Building Infrastructure:Pre-digital HVAC and access control systems in European commercial stock require costly middleware layers for sensor integration.
Strategic Opportunities
- Biometric Wearables in Logistics:Fatigue and heat-stress monitoring devices remain underdeployed in German and Dutch warehouse operations relative to manufacturing.
- F-Gas Regulation Tailwind:Refrigerant phase-down mandates under EU F-Gas Regulation are forcing HVAC replacement cycles that bundle IoT controls.
- Digital Twin Convergence:Integration between building information modeling and real-time sensor streams enables predictive maintenance contracts in facility management.
Industry Challenges
- Edge-AI Engineering Scarcity:Vendors compete for limited talent capable of optimizing neural networks for sub-watt gateway processors.
- Multi-Standard Certification Burden:CE marking, FCC Part 15, and NIST cybersecurity frameworks impose overlapping testing timelines that delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IoT at Workplace Market |
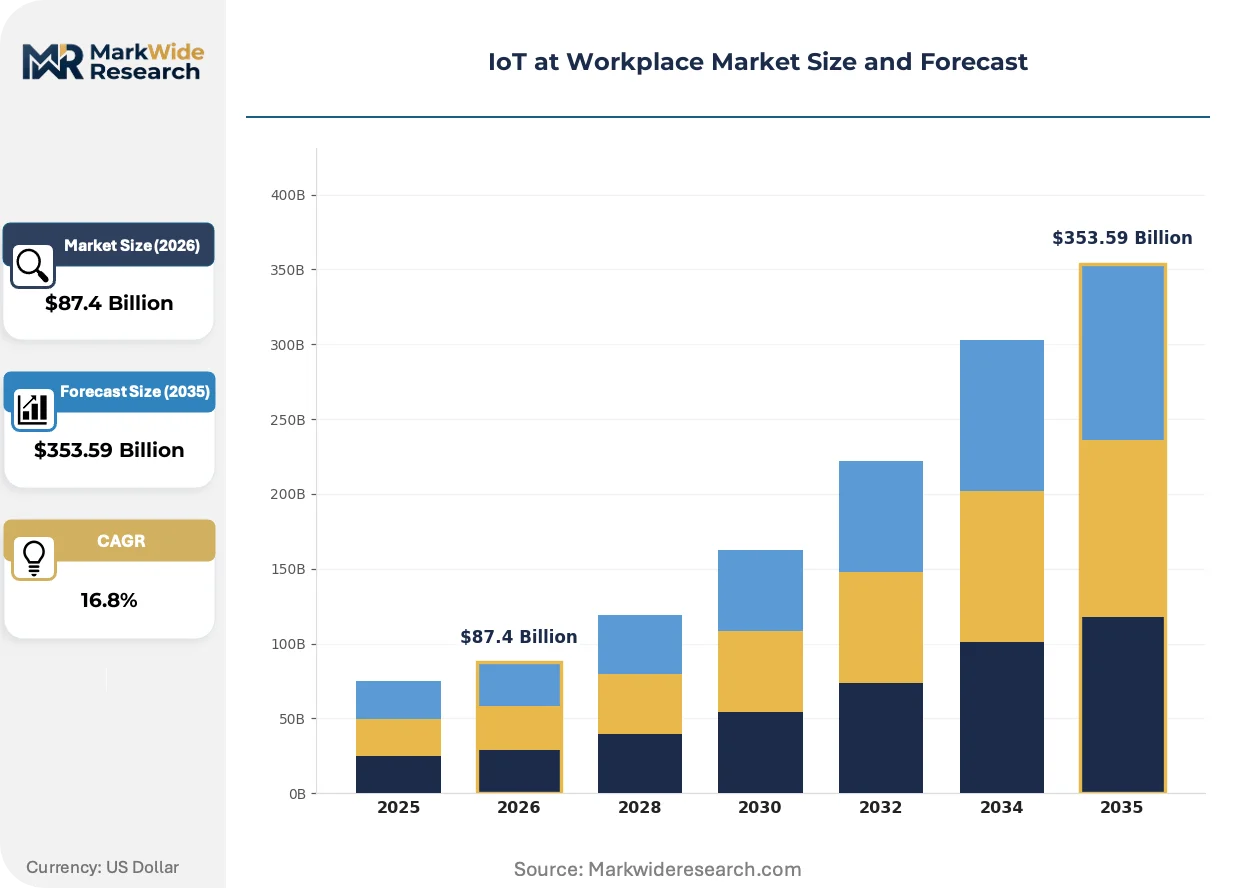
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $353.59 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearables, Smart Lighting, Smart HVAC, Security Systems Technology: Wi-Fi, Bluetooth, Zigbee, RFID Application: Facility Management, Employee Productivity, Energy Management, Security Monitoring End User: Corporates, SMEs, Educational Institutions, Healthcare Facilities |
| Companies Covered | Microsoft, Amazon, Cisco, Google, Siemens, Intel, Samsung, PTC, Huawei, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IoT at Workplace Market Shifts & Advancements
Workplace IoT architectures are pivoting from cloud-centric analytics toward distributed edge intelligence, driven by latency requirements and regulatory data constraints.
On-device machine learning inference is supplanting cloud-based pattern recognition for real-time occupancy and climate adjustments. Facility managers in German automotive headquarters are deploying tensor-optimized gateways to eliminate round-trip latency. This compression of decision loops is enabling sub-second HVAC response that cloud pipelines cannot match.
GDPR Article 44 transfer mechanism restrictions are forcing vendors to regionalize data processing within EU boundaries. Cloud providers are establishing sovereign cloud instances in Frankfurt and Amsterdam to host workplace behavioral analytics. Smart access control and space utilization platforms face the steepest rearchitecture costs.
Subscription-based platform licensing is displacing perpetual hardware sales in enterprise procurement. German industrial conglomerates now prioritize operational expenditure models that bundle sensors, connectivity, and analytics. This preference shift is most pronounced in headquarters and R&D campus deployments where capital allocation flexibility outweighs total cost considerations.
IoT at Workplace Market Segmentation
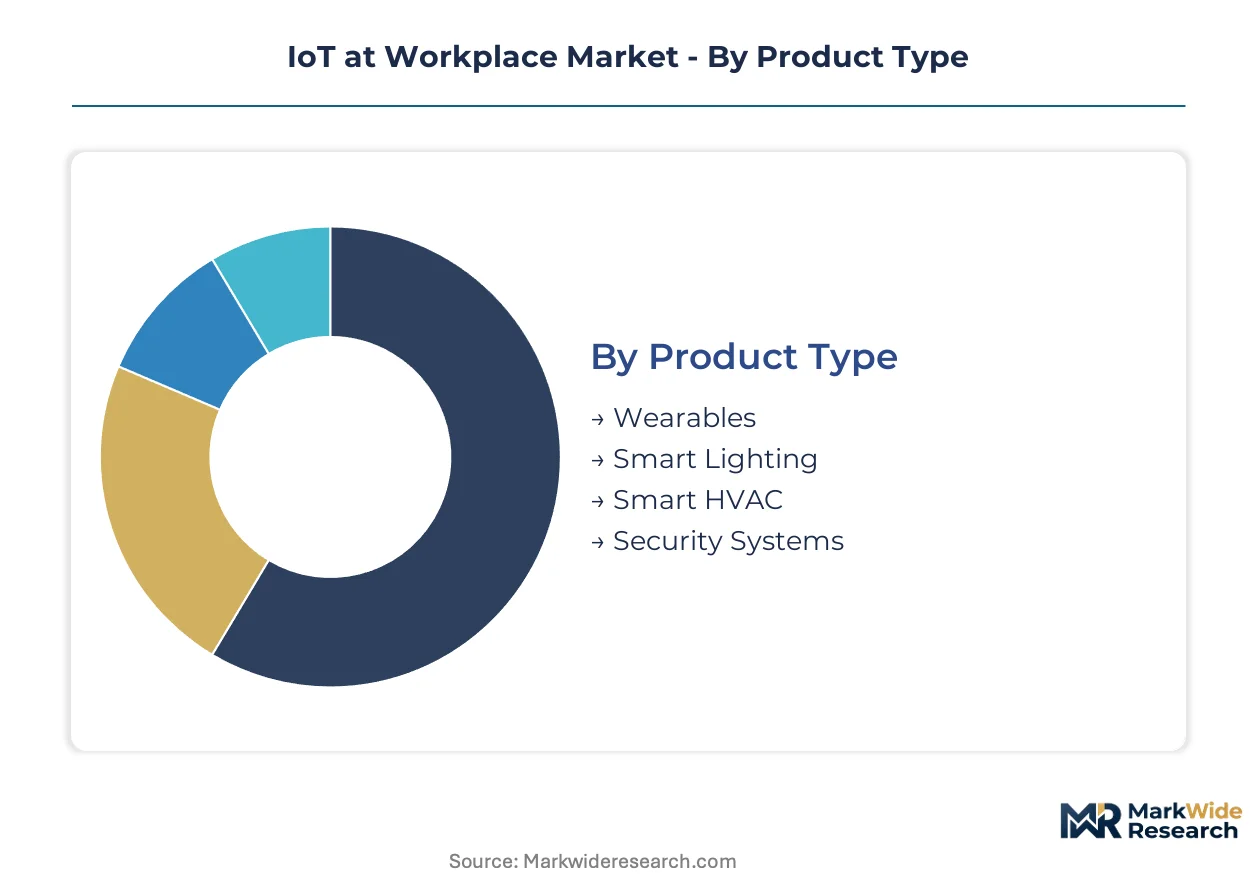
Segmentation in workplace IoT reveals distinct margin architectures across hardware, connectivity, and software layers. Product type and application dimensions show the sharpest divergence in vendor profitability, while technology and end-user splits expose procurement power dynamics that reshape pricing structures.
Product Type:
Margin pools concentrate in systems requiring deep building integration and ongoing service contracts rather than discrete hardware sales.
- Smart HVAC:Sensor-integrated climate control systems combine temperature, occupancy, and air quality monitoring with automated damper and vent adjustments. Demand clusters in German automotive headquarters and French corporate campuses where EU F-Gas Regulation mandates drive replacement cycles bundled with IoT controls.
- Wearables:Biometric monitoring devices track fatigue, heat stress, and location through wristbands, vests, and hardhat attachments. German and Dutch logistics warehouses show underpenetration relative to manufacturing, creating expansion headroom as safety regulations tighten.
- Smart Lighting:LED fixtures with embedded occupancy sensors and daylight harvesting algorithms reduce energy consumption through automated dimming.
- Security Systems:Integrated access control, video analytics, and intrusion detection platforms with edge-based facial recognition and behavioral pattern analysis.
The dominant share belongs to Smart HVAC, while Wearables is closing the gap fastest.
Technology:
Protocol selection directly determines installation cost, battery life, and interoperability friction in multi-vendor deployments.
- Zigbee:Mesh networking protocol operating at 2.4 GHz with self-healing topology and sub-100 millisecond latency for real-time climate adjustments. German industrial campuses favor Zigbee for its proven interoperability with legacy building management systems.
- Wi-Fi:High-bandwidth connectivity standard supporting video streaming and cloud backhaul in bandwidth-intensive security and analytics applications. Corporate headquarters in France and Germany deploy Wi-Fi for unified communications integration.
- Bluetooth:Low-energy beacon protocol enabling precise indoor positioning and proximity-based access control with minimal power draw.
- RFID:Passive and active tag systems for asset tracking and personnel location without requiring line-of-sight scanning.
Zigbee commands the deepest installed base, though Wi-Fi is gaining share fastest in new corporate headquarters builds.
Application:
Revenue per deployment varies by an order of magnitude between single-function monitoring and integrated command platforms.
- Facility Management:Unified building automation integrating HVAC, lighting, access, and energy systems through centralized dashboards and predictive maintenance algorithms. German automotive and industrial conglomerates drive demand for operational expenditure models bundling sensors, connectivity, and analytics.
- Energy Management:Granular consumption monitoring, demand response coordination, and carbon accounting tools supporting net-zero compliance reporting.
- Security Monitoring:Real-time threat detection, emergency response automation, and forensic investigation capabilities through edge-video analytics.
- Employee Productivity:Space utilization tracking, desk booking optimization, and collaboration environment tuning based on occupancy patterns.
Facility Management captures the highest revenue per deployment, while Energy Management is expanding most quickly under corporate sustainability mandates.
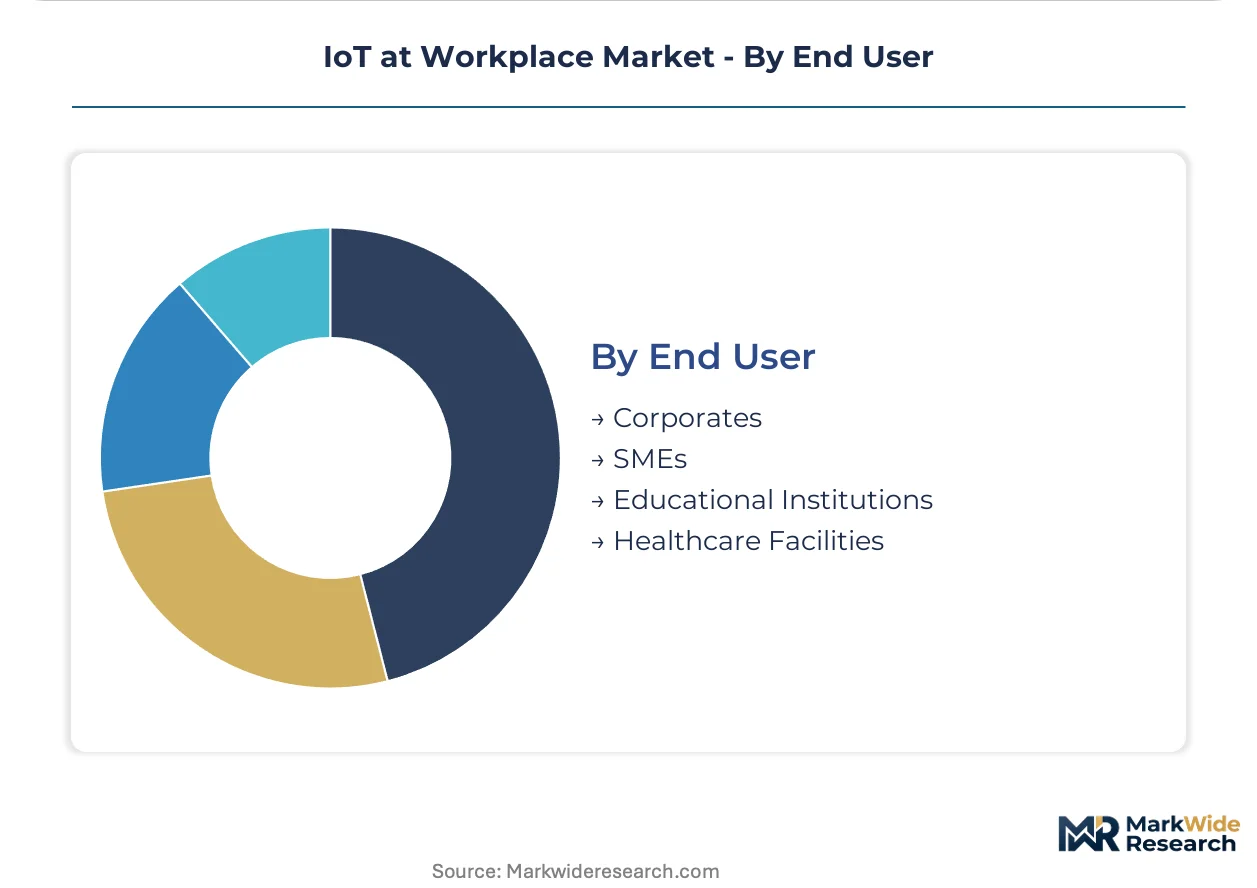
End User:
Procurement sophistication and contract scale fragment sharply across organizational size and sector.
- Corporates:Large enterprises with dedicated facilities teams, capital allocation flexibility, and multi-site standardization requirements. German headquarters and R&D campuses prioritize subscription-based platform licensing over perpetual hardware purchases.
- Healthcare Facilities:Hospitals and clinics with stringent infection control, patient tracking, and equipment location demands.
- Educational Institutions:Universities and research campuses with distributed building portfolios and deferred maintenance backlogs requiring phased sensor deployment.
- SMEs:Small and medium enterprises with limited IT infrastructure and preference for turnkey managed services over self-operated platforms.
Corporates dominate absolute spending, though Healthcare Facilities are climbing fastest as patient safety regulations mandate environmental monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate buyers in Germany show the lowest price elasticity, absorbing premium subscription models for integrated facility platforms, while SMEs in Southern Europe and emerging markets remain highly price-sensitive, delaying deployments until hardware costs compress further.
Germany
Industrial workplace digitization programs and automotive headquarters retrofits drive sensor deployment volumes. The EU AI Act and F-Gas Regulation compress vendor certification timelines while mandating algorithmic transparency for biometric systems. Bavarian automotive clusters and North Rhine-Westphalia industrial campuses anchor European demand for smart HVAC and predictive maintenance contracts.
United States
Corporate net-zero commitments and hybrid work infrastructure investments accelerate building automation procurement. FCC spectrum allocation for Zigbee and Wi-Fi governs device certification timelines, while NIST cybersecurity frameworks constrain sensor data network traversal. Seattle and San Francisco Bay Area tech headquarters prioritize edge-native platforms for sub-100 millisecond latency requirements.
France
Corporate campus sustainability mandates and energy cost pressures stimulate smart lighting and HVAC replacement cycles. GDPR data residency requirements and EU AI Act enforcement compel cloud providers to establish sovereign instances in Paris and Frankfurt. Île-de-France headquarters clusters lead adoption of subscription-based facility management platforms over perpetual hardware purchases.
China
Manufacturing facility automation and logistics warehouse safety monitoring expand biometric wearable deployments. MIIT governs sub-gigahertz spectrum allocation for industrial IoT protocols, while GB standards shape device interoperability requirements. Yangtze River Delta and Pearl River Delta industrial zones concentrate demand for edge gateway hardware serving real-time production line adjustments.
Netherlands
Logistics warehouse safety regulations and port facility automation drive occupant behavior monitoring demand. GDPR Article 44 transfer restrictions force behavioral analytics platforms to regionalize processing within Amsterdam data centers. Rotterdam port complexes and Eindhoven technology campuses underpenetrate relative to German manufacturing in fatigue-monitoring wearable deployment.
IoT at Workplace Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with cloud-native platform builders commanding premium pricing for analytics software while hardware specialists compete on gateway unit economics. The market structure tilts toward consolidated platform ecosystems anchored by hyperscale cloud providers, with specialized networking and building automation vendors occupying defended vertical niches. Three archetypes dominate: integrated cloud-to-edge platform providers, connectivity-focused infrastructure specialists, and vertical building systems incumbents. Competitive moves concentrate on strategic partnerships bundling sensors with analytics subscriptions, and geographic expansion through regional data sovereignty compliance.
Among hyperscale platform providers, Microsoft and Amazon exemplify the cloud-native archetype, anchoring enterprise workplace deployments through Azure and AWS IoT stacks. Cisco occupies a position within the connectivity-specialist tier, dominating building-scale networking hardware installations. Siemens represents the vertical incumbent archetype, leveraging deep expertise in smart HVAC and building management systems to sustain platform relationships with German industrial conglomerates.
| Leading Market Players |
|---|
| Microsoft |
| Amazon |
| Cisco |
| Siemens |
| Intel |
| Samsung |
| PTC |
| Huawei |
| Others |
Supply & Pricing Matrix
Edge-native processing substitution for cloud-centric architectures redraws vendor cost structures while compressing data sovereignty compliance spend. This shift concentrates gateway production in East Asian fabrication hubs and tilts pricing power toward semiconductor-integrated platform providers.
Pricing Analysis
Subscription-based service and predictive maintenance contracts drive lifetime value across workplace IoT deployments. Three-tier pricing structure across premium, standard, and economy levels separates certified EU AI Act-compliant platforms from uncertified alternatives and basic sensor hardware. Price differentiation rests on algorithmic transparency certification and edge-AI inference capability. Pricing pressure stems from subscription fatigue among German mid-market corporates. SMEs in Southern Europe show highest price sensitivity, while German automotive headquarters absorb premium platform licensing.
Supply Chain Analysis
Taiwan and South Korea anchor edge gateway semiconductor fabrication for sub-watt neural network processors. China supplies passive components and PCB assemblies. The supply chain draws from rare earth elements for sensor magnetics and lithium for battery-backed edge devices. Single-source vulnerability concentrates in advanced node chip fabrication. Distribution runs through systems integrators and building automation specialists rather than direct vendor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Workplace IoT sits in early-cycle expansion as EU F-Gas Regulation mandates force HVAC replacement cycles that bundle sensor deployment. Corporate net-zero commitments accelerate penetration beyond early-adopter headquarters into mid-market facilities.
For Market Incumbents: Consolidate platform relationships through predictive maintenance contract bundling and edge-AI certification investment. Defend against hyperscale cloud entrants by deepening Siemens-style vertical expertise in smart HVAC integration. Prioritize backward integration into sensor manufacturing to compress hardware cost structures. For New Entrants and Emerging Players: Lead with biometric wearables deployment in Dutch and German logistics warehouses, where safety regulation tightening meets current underpenetration. Target facility management platforms for mid-market corporates seeking operational expenditure flexibility. Pursue channel partnerships with building automation specialists rather than direct enterprise sales. For Investors and Strategic Acquirers: EU AI Act enforcement timelines reshape the acquisition landscape toward edge-native platform providers with sovereign cloud infrastructure. Position for five-to-ten year holding periods as regulatory compliance becomes a durable competitive moat. Target mid-cap specialists with Frankfurt or Amsterdam data center presence and CE marking depth. Watch F-Gas Regulation implementation velocity as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-AI Platform Certification | EU AI Act compliance creates procurement preference for validated inference engines. |
| Predictive Maintenance Contract Bundling | German automotive campuses prioritize operational expenditure models over hardware purchases. |
| Sovereign Cloud Infrastructure Deployment | GDPR Article 44 restrictions force data residency within Frankfurt and Amsterdam boundaries. |
| Biometric Wearables Channel Partnership | Dutch logistics safety regulations tighten ahead of warehouse deployment saturation. |
| Smart HVAC Retrofit Integration | F-Gas Regulation mandates accelerate replacement cycles bundling IoT controls. |
Research Methodology
A spread of perspectives from facilities directors, building automation engineers, IoT platform architects, and corporate sustainability officers converged on the working assumptions. Primary interviews combined with secondary validation against hyperscaler capex disclosures, FCC equipment authorization databases, and EU regulatory filings. Bottom-up sensor deployment estimates triangulated against top-down corporate facility spend analysis.
Segmentation dimensions modeled span product type, wireless protocol technology, application use case, and end-user organization size across the projection horizon. CAGRs derived from installed base growth curves and replacement cycle acceleration under regulatory mandate. Forecast inputs incorporated F-Gas Regulation implementation schedules and EU AI Act certification timeline assumptions.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement or supply chain stabilization would require recalibration. Forecasts reflect documented assumptions regarding corporate net-zero commitment durability and edge-AI engineering talent availability. Recalibration cycles align with material shifts in EU AI Act enforcement velocity or semiconductor fabrication capacity expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
North America IoT Software Market
Internet of Things (IoT)
Internet of Things (IoT) in Healthcare Market
Internet of Things (IoT)
IoT Integration Market
Internet of Things (IoT)
IoT in Chemical Industry Market
Internet of Things (IoT)
Global IOT Gateway Market
Internet of Things (IoT)
IoT Gateway Devices Market
Internet of Things (IoT)
Satellite IoT Market
Internet of Things (IoT)
GCC Indoor LBS Market
Internet of Things (IoT)
Bluetooth Smart Plugs Market
Internet of Things (IoT)
Internet of Things in BFSI Market
Internet of Things (IoT)
IoT Cellular Market
Internet of Things (IoT)
5G IIOT Market
Internet of Things (IoT)
IoT Application Development Services Market
Internet of Things (IoT)
Internet of Things (IoT) Platform Market
Internet of Things (IoT)
US Smart Thermostat Market
Internet of Things (IoT)
Global IoT Connectivity Market