
 IoT Connected Machines Market | 2026-2036
IoT Connected Machines Market Size, Share, and Industry Trends Forecast 2026-2036
IoT Connected Machines Market Intelligence
Industrial distribution networks are reshaping how OEMs deliver IoT-enabled machinery to end users. Siemens AG leverages its digital industries division to control software-hardware bundling across European manufacturing hubs. Honeywell International Inc. anchors its connected machine portfolio through building automation and aerospace channel partnerships. Rockwell Automation specializes in programmable logic controllers with embedded edge analytics, competing for factory-floor retrofit contracts.
IoT connected machines integrate sensors, actuators, and communication modules into industrial equipment to enable real-time data exchange and autonomous decision-making. These systems typically operate on IP-based protocols with latency thresholds under 50 milliseconds for time-critical control loops, serving to optimize throughput and reduce unplanned downtime in capital-intensive operations. Predictive maintenance applications command the largest current revenue pool due to measurable ROI from avoided failures, while 5G connectivity is expanding fastest as private network deployments at manufacturing plants enable deterministic wireless control. Automated guided vehicles represent a maturing segment where price competition intensifies, though margin pools persist in fleet management software layers.
The EU AI Act classifies certain autonomous industrial machines as high-risk systems, mandating conformity assessments before CE marking and market access. FDA cybersecurity guidance for connected medical devices is spilling into adjacent industrial equipment standards as manufacturers adopt unified risk management frameworks. ISO/IEC 27001 and IEC 62443 certifications are becoming baseline requirements for procurement by energy producers and logistics providers. Stakeholders must monitor evolving liability frameworks for machine-initiated decisions as regulators weigh product safety against innovation velocity.
Market Dynamics
Private 5G network deployments at manufacturing plants are compressing latency thresholds below 10 milliseconds, enabling deterministic wireless control loops that displace wired industrial ethernet architectures and reshape capital allocation across factory automation budgets.
Growth Catalysts
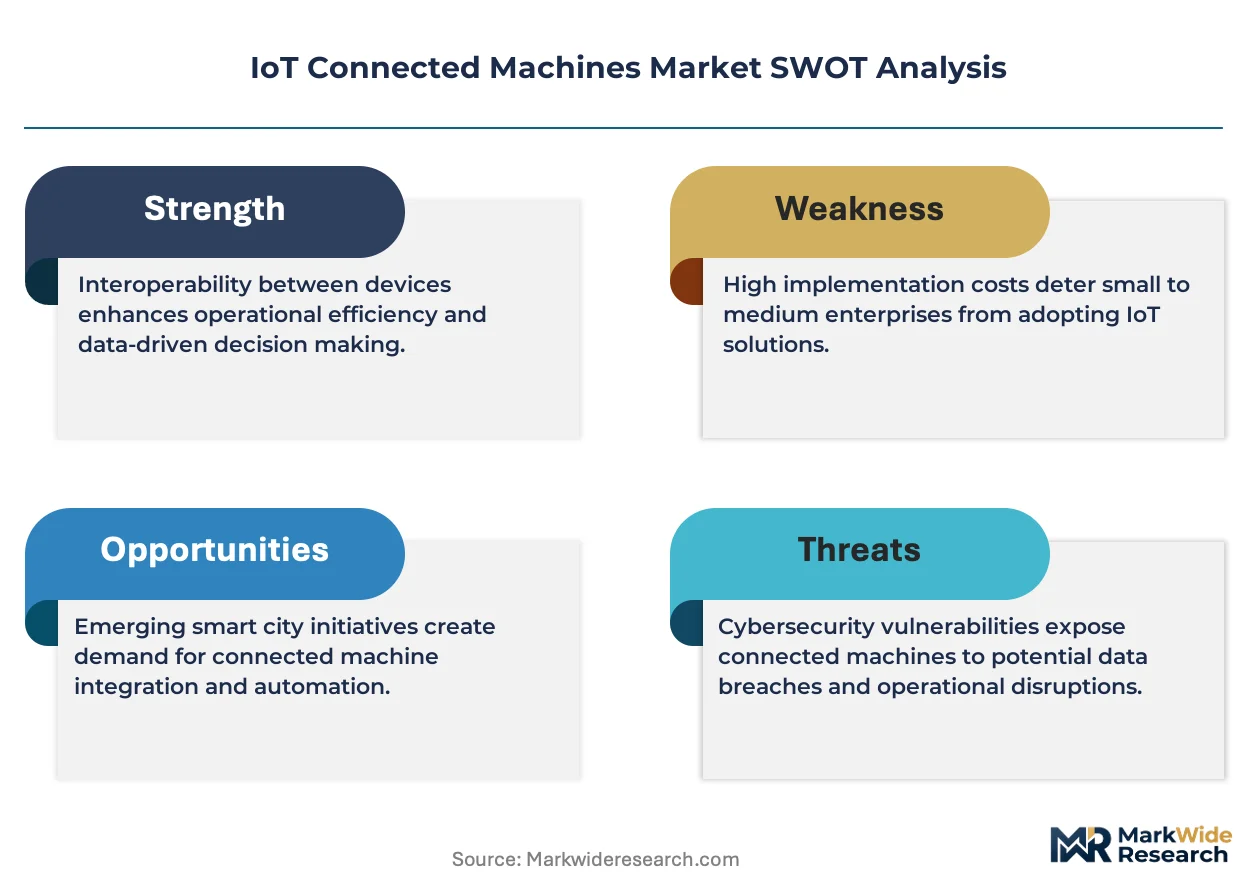
- Predictive maintenance ROI:Energy producers and automotive assembly plants quantify avoided downtime costs, accelerating sensor deployment on rotating equipment and thermal assets.
- EU AI Act compliance pathway:High-risk system classification for autonomous industrial machinery creates structured conformity assessment demand, pulling certification services and risk management software into procurement bundles.
- Edge analytics hardware:Programmable logic controllers with embedded inference engines reduce cloud dependency, appealing to semiconductor fabs and pharmaceutical batch processors with data sovereignty requirements.
Market Restraints
- Silicon supply concentration:Advanced sensor microcontrollers and 5G modem chipsets depend on Taiwan and South Korea foundry capacity, exposing lead time volatility to German and Japanese automation OEMs.
- Cyber insurance cost escalation:Underwriters apply IEC 62443 maturity scoring to premium calculations, elevating total cost of ownership for mid-tier logistics providers below critical scale thresholds.
- Legacy protocol fragmentation:Proprietary fieldbus installations at brownfield petrochemical and steel facilities resist IP-native retrofit, extending sales cycles and implementation risk.
Strategic Opportunities
- India manufacturing automation:PLI scheme incentives for electronics and automotive component production create first-mover advantage for connected machine vendors establishing local assembly and service infrastructure.
- Digital twin convergence:Integration of physics-based simulation with real-time operational data enables virtual commissioning, compressing facility startup timelines for battery gigafactories and green hydrogen electrolyzer plants.
- FDA cybersecurity spillover:Medical device guidance adoption by adjacent industrial equipment manufacturers opens unified risk management framework sales into food processing and pharmaceutical packaging verticals.
Industry Challenges
- OT-IT security skill scarcity:Industrial control system expertise rarely overlaps with enterprise cybersecurity certification, forcing manufacturers to compete for hybrid talent against financial services and defense contractors.
- Multi-standard certification stacking:Simultaneous ISO/IEC 27001, IEC 62443, and CE marking timelines extend product launch windows, consuming engineering resources without incremental revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IoT Connected Machines Market |
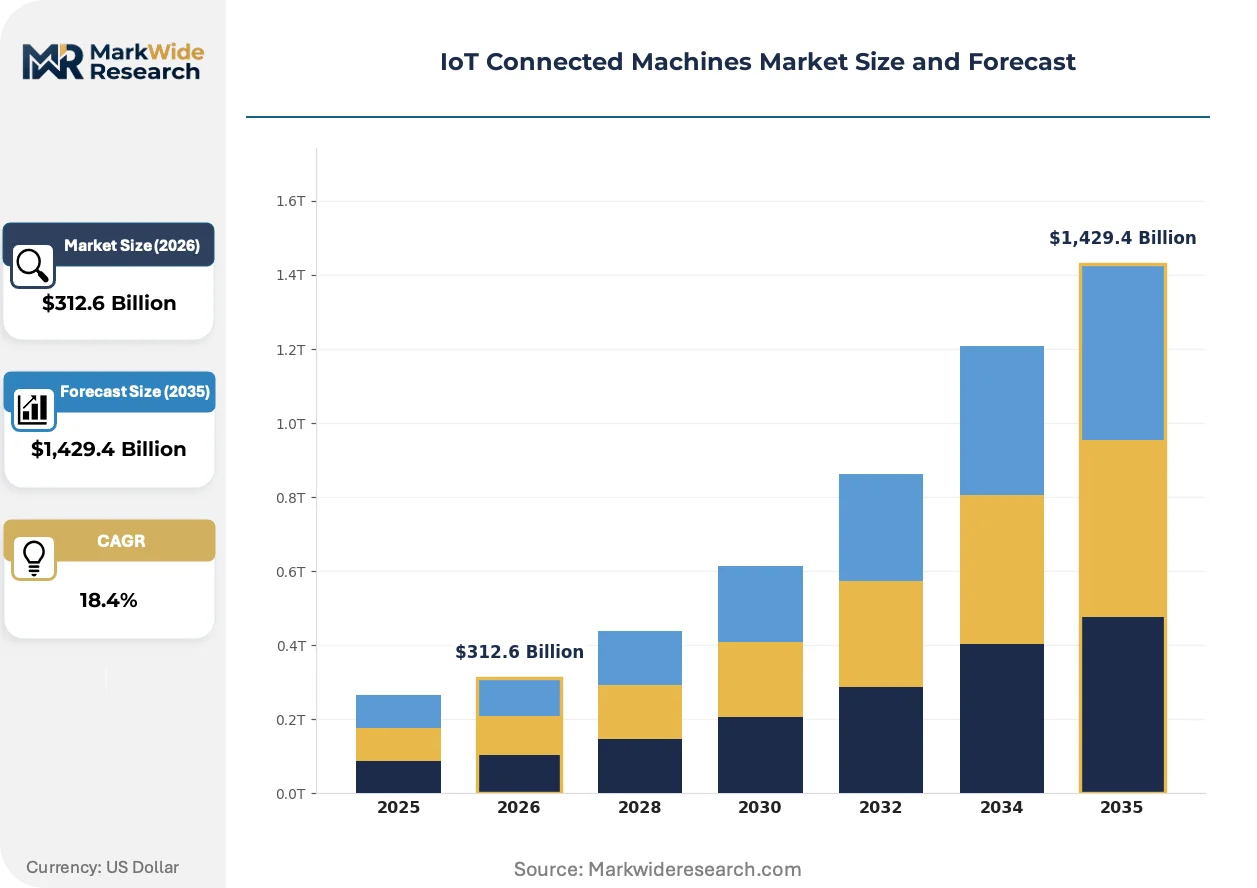
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $1,429.4 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Industrial Robots, Automated Guided Vehicles, CNC Machines, 3D Printers, Drones Connectivity Technology: Wi-Fi, LPWAN, 5G, Bluetooth, Zigbee Application: Predictive Maintenance, Asset Tracking, Quality Control, Remote Monitoring, Fleet Management End User Industry: Manufacturing Plants, Logistics Providers, Agriculture Operators, Construction Sites, Energy Producers |
| Companies Covered | Siemens AG, Honeywell International Inc., General Electric Company, IBM Corporation, Rockwell Automation, Schneider Electric, ABB Ltd., Intel Corporation, Cisco Systems, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IoT Connected Machines Market Strategic Shifts & Innovations
Software-defined automation architectures are dissolving traditional boundaries between operational technology and information technology layers, compressing vendor stack positions and enabling new subscription-based commercial models.
Digital twin technology is virtualizing physical asset behavior through real-time sensor fusion and physics-based simulation. Automotive OEMs and semiconductor fabricators deploy these systems for virtual commissioning and scenario testing. This capability is virtualizing traditional pilot plant requirements, reducing capital deployment risk and accelerating production ramp timelines.
The EU AI Act's high-risk system classification mandates conformity assessments before CE marking for autonomous industrial equipment. Machinery manufacturers must document risk management systems and human oversight protocols. German automotive suppliers and Italian packaging equipment producers are restructuring product development cycles to embed compliance documentation from initial design stages.
After-sales service unbundling is fragmenting traditional OEM maintenance contracts. End users in chemical processing and power generation now procure predictive analytics software separately from hardware, favoring independent software vendors with vertical-specific algorithm libraries. This pattern is most pronounced in the US Gulf Coast refining corridor and Rotterdam port logistics clusters.
IoT Connected Machines Market Segmentation
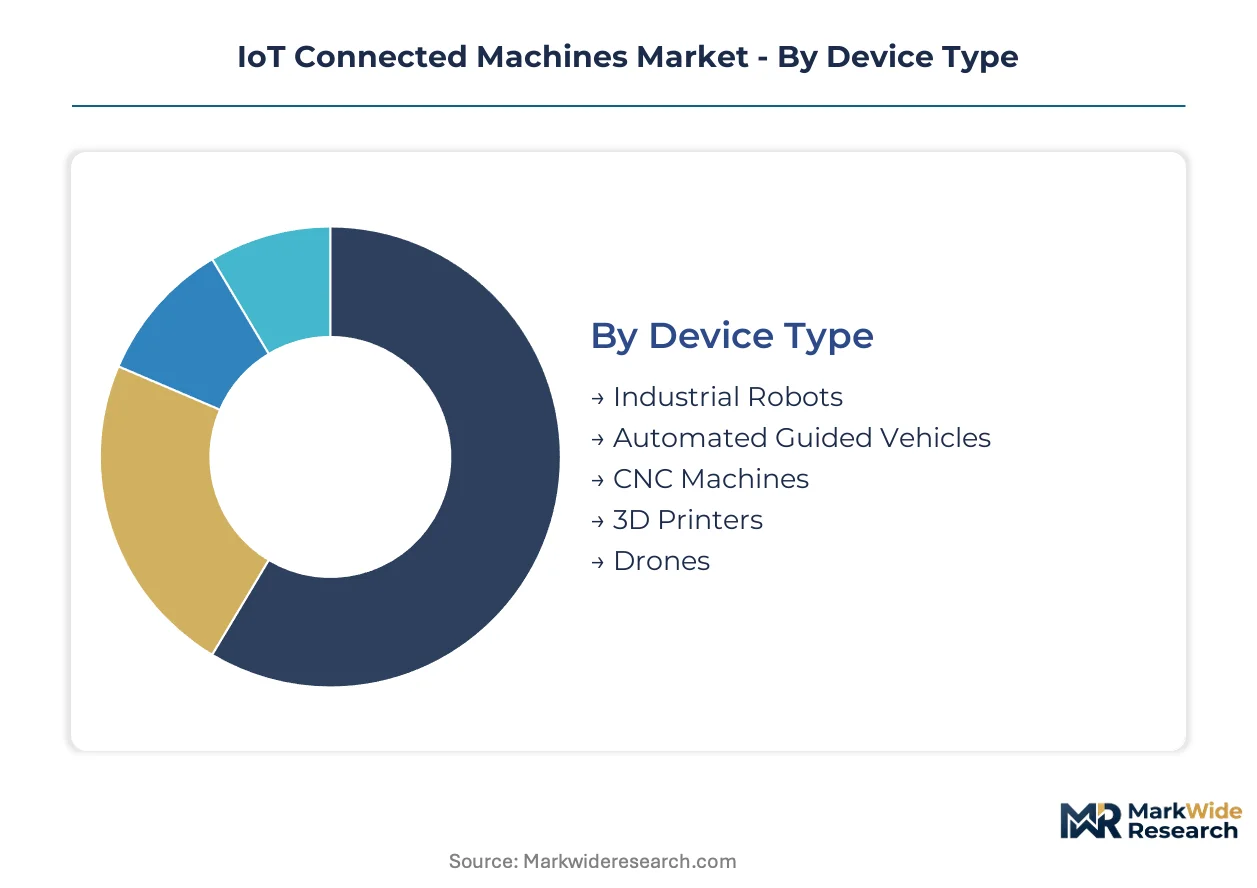
Segmentation in IoT connected machines reveals divergent capital cycles across device types, connectivity protocols, and end-use applications. Procurement patterns vary dramatically between heavy industrial assets with decade-long replacement horizons and lightweight sensors refreshing every 18-36 months.
Device Type:
Cycle times range from 7-10 years for capital-intensive industrial robots to 2-3 years for modular drone fleets, reshaping vendor cash flow profiles and service contract structures.
- Industrial Robots:Articulated and collaborative arm systems with embedded torque sensors and safety-rated control loops. Demand concentrates in German automotive assembly plants and Japanese electronics contract manufacturers, constrained by lengthy integration timelines and specialized technician shortages.
- Automated Guided Vehicles:Mobile platforms integrating LiDAR, magnetic tape, and vision-based navigation for material transport. Logistics providers in Rotterdam and Hamburg port clusters drive replacement demand as battery chemistry improvements enable 24-hour continuous operation cycles.
- CNC Machines:Computer-numerical control systems with spindle vibration monitoring and tool-wear prediction algorithms.
- 3D Printers:Additive manufacturing systems with thermal camera feedback and powder bed monitoring sensors.
- Drones:Aerial platforms with multispectral cameras and RTK-GPS positioning for inspection and surveying missions.
Industrial robots anchor the volume base while drones gain share at the steepest rate.
Connectivity Technology:
Cost tiers separate enterprise-grade private 5G deployments from low-power wide-area alternatives, with total cost of ownership spanning two orders of magnitude across protocol choices.
- 5G:Ultra-reliable low-latency communication enabling deterministic control with sub-10 millisecond response thresholds. Semiconductor fabs in Taiwan and South Korea deploy private network slices for equipment coordination, driven by electromagnetic interference immunity requirements in cleanroom environments.
- LPWAN:LoRa and NB-IoT protocols optimized for battery-constrained sensors transmitting infrequent telemetry bursts. Agriculture operators across Australia's wheat belt and Brazil's soybean regions favor these modules for soil moisture and livestock tracking applications.
- Wi-Fi:IEEE 802.11ax/ay standards for high-bandwidth video and vibration spectrum analysis in factory settings.
- Bluetooth:Short-range mesh networking for proximity-based asset location and condition monitoring.
- Zigbee:Low-power mesh topology for building automation and energy management integrations.
LPWAN dominates shipment volumes while 5G climbs the fastest in value terms.
Application:
Maturity curves separate established predictive maintenance deployments from emerging quality control automation, with implementation risk profiles determining vendor selection criteria.
- Predictive Maintenance:Vibration, thermal, and oil analysis algorithms forecasting bearing failures and motor degradation. Energy producers in Texas and Alberta oil sands operations quantify avoided downtime costs, accelerating sensor deployment on gas turbines and pumping stations.
- Quality Control:Machine vision and dimensional inspection systems with real-time defect classification. Automotive stamping plants in Stuttgart and Detroit integrate these modules for weld seam verification, pressured by zero-defect warranty commitments from electric vehicle OEMs.
- Asset Tracking:RFID and GPS-based location systems for inventory and equipment positioning.
- Remote Monitoring:Cloud-connected dashboards for distributed equipment fleets and environmental conditions.
- Fleet Management:Optimization algorithms for vehicle routing, maintenance scheduling, and fuel consumption.
Predictive maintenance commands the largest installed base while quality control expands most quickly.
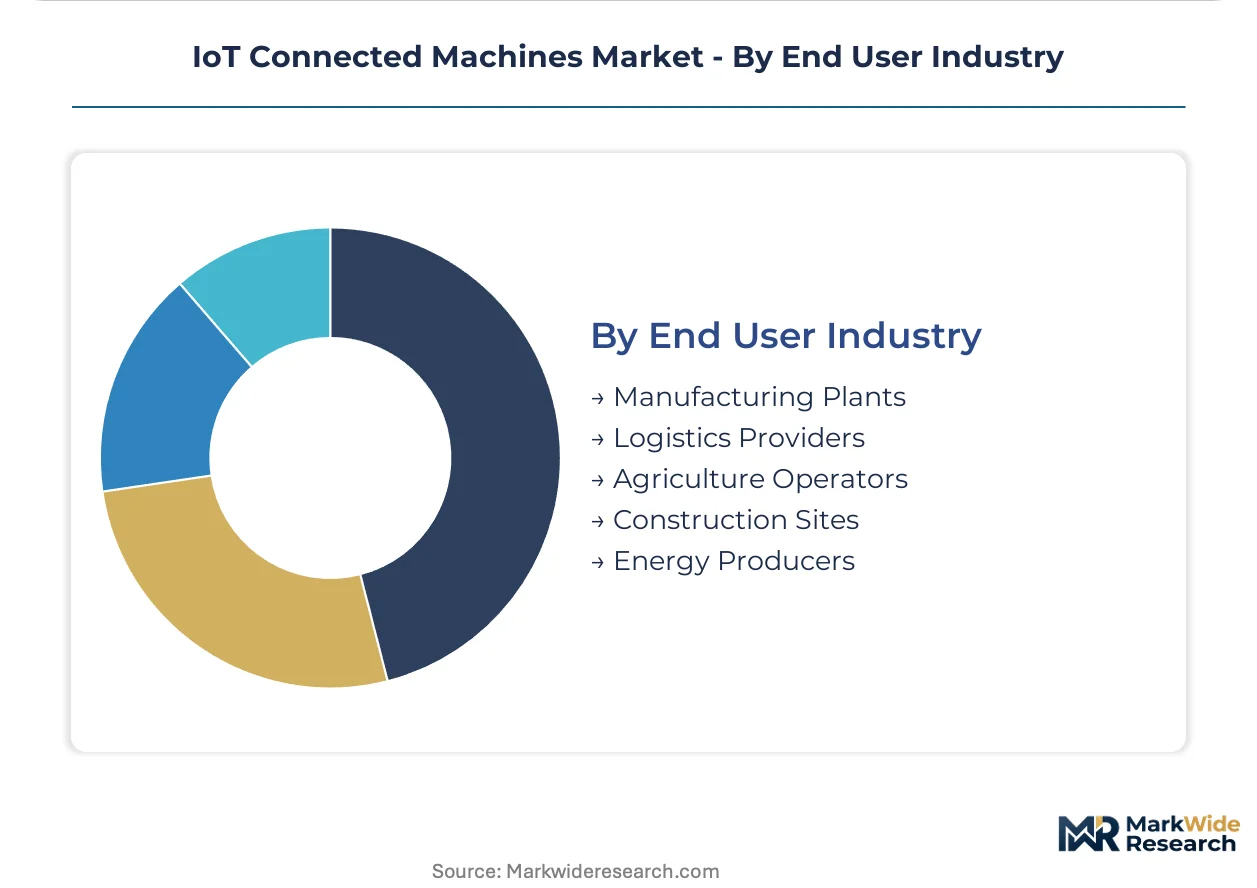
End User Industry:
Customer type differentiation separates capital-intensive process industries from asset-light service providers, with procurement authority residing in operations versus IT functions accordingly.
- Manufacturing Plants:Discrete and process production facilities deploying connected machines for throughput optimization and safety compliance. German chemical processors and Italian packaging equipment producers anchor demand, restructuring procurement around EU AI Act conformity assessment requirements.
- Energy Producers:Utilities and independent power generators monitoring generation and distribution assets. Wind farm operators in Denmark and offshore platforms in the North Sea drive ruggedized hardware specifications for salt spray and temperature extremes.
- Logistics Providers:Warehousing, port, and freight operators coordinating material flows.
- Agriculture Operators:Precision farming deployments for irrigation, fertilization, and harvest automation.
- Construction Sites:Equipment telematics and autonomous earthmoving for project efficiency and safety.
Manufacturing plants represent the deepest revenue pool while energy producers show the steepest adoption trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's automated container handling systems anchor Europe's demand for deterministic wireless control infrastructure. Germany's industrial heartland clusters around Munich and Stuttgart drive precision manufacturing requirements. India's PLI scheme incentives redirect electronics assembly capacity toward connected automation platforms.
United States
Texas oilfield operators deploy predictive maintenance sensors on gas turbines and pumping stations to quantify avoided downtime costs. The FDA cybersecurity guidance for connected medical devices spills into adjacent industrial equipment standards as manufacturers adopt unified risk management frameworks. Houston's refining corridor and Detroit's automotive stamping plants anchor demand concentration.
Germany
Automotive assembly plants in Stuttgart expand predictive maintenance deployment on rotating equipment to minimize unplanned downtime. The EU AI Act classifies autonomous industrial machinery as high-risk systems, mandating conformity assessments before CE marking. Munich and Stuttgart anchor industrial IoT clusters where Siemens AG and Bosch coordinate software-hardware bundling across European manufacturing hubs.
China
Semiconductor fabricators in Taiwan and South Korea deploy private 5G network slices for equipment coordination, driven by electromagnetic interference immunity requirements in cleanroom environments. MIIT standards and GB certification frameworks govern industrial equipment interoperability. The Yangtze River Delta concentration of battery gigafactories accelerates digital twin adoption for virtual commissioning.
India
Electronics and automotive component producers leverage PLI scheme incentives to establish local assembly and service infrastructure for connected machines. BIS certification requirements and CEA grid codes shape procurement specifications for industrial automation. Maharashtra and Gujarat manufacturing zones attract first-mover vendors building captive service networks.
Japan
Electronics contract manufacturers drive replacement demand for industrial robots with embedded torque sensors and safety-rated control loops. METI industrial standards and JIS certification frameworks govern machine-to-machine data integrity requirements. The Chubu/Nagoya automotive supplier belt restructures product development cycles to embed EU AI Act compliance documentation from initial design stages.
IoT Connected Machines Market Key Industry Players
On the supply side, the industry is consolidating around diversified industrial conglomerates with captive software capabilities. Tiered competitive positioning separates premium-tier vendors bundling predictive analytics with hardware from mid-market specialists competing on retrofit integration speed. Three archetypes dominate: automation incumbents with embedded edge analytics, IT infrastructure providers extending into operational technology, and vertical specialists with industry-specific algorithm libraries. Geographic expansion and strategic partnerships represent the dominant competitive moves as vendors establish local assembly footprints in India and Southeast Asia.
Among diversified industrial conglomerates, Siemens AG and Honeywell International Inc. exemplify the automation incumbent archetype with integrated digital industries portfolios. Rockwell Automation occupies a specialist position in programmable logic controllers with embedded inference engines, competing primarily for factory-floor retrofit contracts against broader-platform rivals. These three companies represent distinct strategic postures within a market where software-defined architectures compress traditional vendor stack positions.
| Leading Market Players |
|---|
| Siemens AG |
| Honeywell International Inc. |
| General Electric Company |
| IBM Corporation |
| Rockwell Automation |
| Schneider Electric |
| ABB Ltd. |
| Intel Corporation |
| Cisco Systems, Inc. |
| Others |
Cost & Logistics Intelligence
Taiwan and South Korea foundry concentration for advanced sensor microcontrollers and 5G modem chipsets anchors margin capture at the semiconductor tier, forcing automation OEMs in Germany and Japan to absorb lead-time volatility or pre-pay for capacity reservation.
Pricing Analysis
Volume-discount tiering separates enterprise-scale manufacturing plants procuring predictive maintenance bundles from mid-tier logistics providers purchasing standalone sensors. Three-tier pricing structure across premium, standard, and economy levels reflects IEC 62443 certification grade and after-sales analytics bundling. Pricing pressure stems from automated guided vehicle commoditization in port logistics clusters. Mid-tier logistics providers exhibit highest price sensitivity, while semiconductor fabs accept premium positioning for data sovereignty-compliant edge analytics hardware.
Supply Chain Analysis
Export-control restrictions on advanced lithography equipment and AI accelerator chips limit flows from Netherlands and US suppliers into Chinese semiconductor fabricators. Taiwan, South Korea, and Japan anchor wafer production for industrial sensor microcontrollers. German automation OEMs source rare-earth magnets from China and battery cells from South Korea. Single-source vulnerability concentrates in 5G baseband modem supply. Distribution runs through authorized system integrators with IEC 62443 certification credentials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial IoT incumbents face substitution pressure from cloud-native automation platforms unbundling hardware-software stacks, requiring defensive repositioning around captive data infrastructure and compliance certification assets.
For Market Incumbents: Build switching-cost moats through predictive analytics software layer embedding and IEC 62443 certification bundling. Siemens AG and Honeywell International Inc. anchor this approach through digital industries portfolio control. Defend against independent software vendors by tightening API access and virtual commissioning integration. Prioritize vertical integration into edge inference hardware to reduce cloud dependency exposure. For New Entrants and Emerging Players: Pursue white-space penetration in India's PLI scheme manufacturing zones where captive service infrastructure remains underdeveloped. Target battery gigafactory digital twin deployments for virtual commissioning acceleration. Food processing and pharmaceutical packaging verticals offer FDA cybersecurity spillover entry points with unified risk management framework positioning. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed industrial software specialists holding vertical-specific algorithm libraries but lacking hardware distribution scale. Five-to-ten year viability hinges on OT-IT convergence execution capability. Monitor private 5G network deployment velocity at semiconductor fabs as inflection signal for deterministic wireless control adoption curves.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Analytics Hardware Integration | Embedded inference engines in programmable logic controllers reduce cloud dependency for pharmaceutical batch processors. |
| Private 5G Network Deployment | Sub-10 millisecond latency enables deterministic wireless control loops displacing wired industrial ethernet architectures. |
| EU AI Act Compliance Bundling | Conformity assessment documentation embedded from design stages accelerates CE marking for German automotive suppliers. |
| Digital Twin Platform Convergence | Physics-based simulation with real-time data compresses facility startup timelines for green hydrogen electrolyzer plants. |
| India Manufacturing Footprint Establishment | PLI scheme incentives for electronics assembly create first-mover advantage in local service network construction. |
Research Approach
Operator-level perspectives from plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads anchored the qualitative base. Primary interviews combined with secondary validation from SEC filings, customs and trade data, IEC certification registries, and hyperscaler capex disclosures. Bottom-up sensor shipment aggregation and top-down industrial automation spend analysis provided triangulation discipline.
Scenario-bracketing around connectivity protocol adoption curves and regulatory implementation timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include device type, connectivity technology, application maturity, and end-user industry procurement authority. CAGRs derived from installed base expansion rates and replacement cycle compression. Private 5G deployment velocity at Taiwan semiconductor fabs and EU AI Act conformity assessment pipeline depth served as industry-specific forecast inputs.
Sensitivities concentrate around Taiwan semiconductor supply disruptions, EU AI Act enforcement intensity, and India PLI scheme incentive continuity. Forecasts reflect documented assumptions on sensor cost decline trajectories and OT-IT security skill scarcity persistence. Material shifts in export-control regime stringency or battery chemistry disruption would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
IoT Network Management Market
Internet of Things (IoT)
IoT Communication Protocol Market
Internet of Things (IoT)
IoT Data Governance Market
Internet of Things (IoT)
IoT Utilities Market
Internet of Things (IoT)
Global IoT in Smart Cities Market
Internet of Things (IoT)
IoT Monetization Market
Internet of Things (IoT)
North America Industrial IoT Market
Internet of Things (IoT)
Global IoT Elevators Market
Internet of Things (IoT)
LTE IoT Market
Internet of Things (IoT)
Internet of Things (IoT) Platform Market
Internet of Things (IoT)
Smart Sprinkler Controller Market
Internet of Things (IoT)
North America IoT Software Market
Internet of Things (IoT)
Europe IoT in Smart Cities Market
Internet of Things (IoT)
IoT Market
Internet of Things (IoT)
IoT Solutions Market
Internet of Things (IoT)
Wireless Smart Plug Market