
 Automotive Cloud Based System Market | 2026-2036
Automotive Cloud Based System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Cloud Based System Market Analysis
Edge computing silicon is hardening as the dominant processing substrate for in-vehicle latency-sensitive workloads, displacing pure centralized cloud architectures in safety-critical domains. Amazon Web Services Inc. leverages its Greengrass edge runtime to anchor hybrid deployments across Tier 1 supplier networks. Microsoft Corporation sustains regulatory-compliant sovereign cloud instances for European OEM data residency requirements. Google LLC specializes in mapping and perception AI layers that extend its consumer platform dominance into automotive subscription revenue streams.
An automotive cloud based system constitutes a distributed computing architecture that ingests telemetry from vehicle sensors, executes analytics workloads across edge and cloud nodes, and delivers over-the-air functional updates with sub-100-millisecond latency thresholds for autonomous emergency braking protocols. Its primary commercial purpose is to convert raw vehicle data into monetizable services spanning predictive maintenance, usage-based insurance, and fleet optimization. Public cloud deployments capture the majority of current workloads among OEMs seeking elastic compute scaling for infotainment and non-critical telematics, while hybrid cloud configurations are expanding fastest as cybersecurity frameworks mandate air-gapped environments for powertrain control modules. Fleet operators represent a concentrated margin pool within the end-user landscape due to multi-thousand-unit contract scales and long-term platform lock-in dynamics.
FDA guidance on software as a medical device intersects with NHTSA cybersecurity mandates to shape validation protocols for cloud-connected advanced driver assistance systems in the United States. EMA and EU AI Act conformity requirements impose algorithmic transparency standards on European deployments of machine-learning-based hazard prediction. The report indicates stakeholders must evaluate sovereign infrastructure requirements against latency specifications before committing to single-vendor cloud architectures.
Market Dynamics
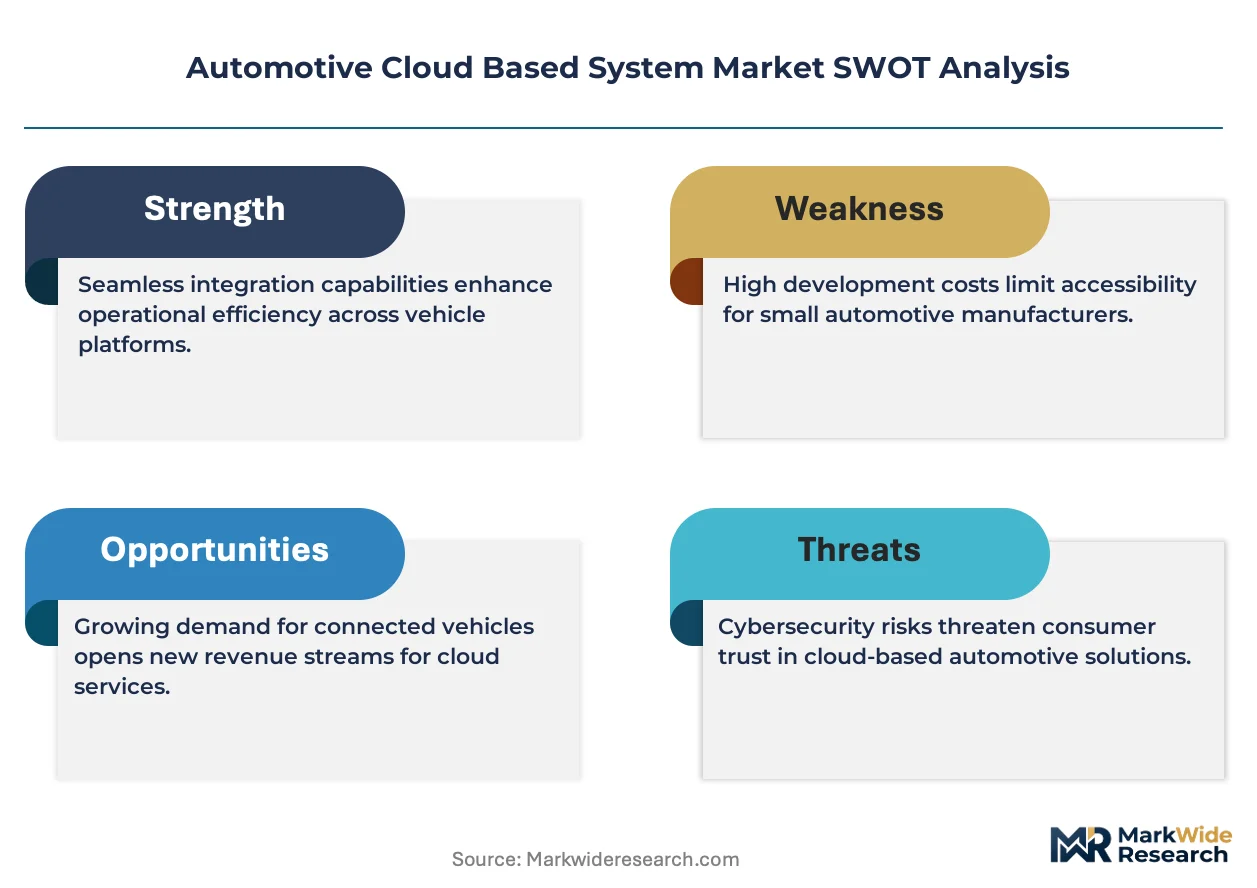
Edge-to-cloud workload orchestration is fragmenting legacy centralized architectures as automakers partition safety-critical functions from infotainment telemetry. The EU AI Act's algorithmic transparency mandates and NHTSA cybersecurity rules are forcing dual-infrastructure investments that favor hybrid deployments over pure public cloud commitments.
Growth Catalysts
- Fleet telematics mandates:Commercial vehicle operators in Germany face compulsory real-time emissions monitoring under KBA enforcement protocols, accelerating sovereign cloud procurement for data residency compliance.
- GDPR data-localization requirements:European OEMs must maintain EU-bound vehicle telemetry within regional boundaries, creating captive demand for region-locked cloud instances with automated failover architectures.
- Over-the-air update proliferation:Powertrain control modules now require sub-100-millisecond latency for autonomous emergency braking patches, pulling compute workloads toward hardened edge nodes.
Market Restraints
- Silicon supply concentration:Automotive-grade edge processors depend on TSMC's 7nm and 5nm fabrication capacity concentrated in Taiwan, exposing Tier 1 suppliers to geopolitical disruption risk.
- Certification timeline friction:ISO 26262 functional safety validation for cloud-connected control units extends development cycles 18-24 months beyond conventional embedded systems.
- Substitution threat from private 5G:Industrial campus networks are displacing cellular-V2X for captive fleet operations, compressing addressable cloud connectivity revenue per vehicle.
Strategic Opportunities
- India PLI scheme leverage:Component suppliers establishing local cloud-edge nodes for Tata Motors and Mahindra & Mahindra gain 4-6% cost advantage through production-linked incentive credits.
- Usage-based insurance convergence:Telematics data streams are enabling dynamic premium pricing partnerships between insurers and connected fleet operators in Japan's commercial vehicle segment.
- Software-defined vehicle architectures:Domain controller consolidation is creating unified data pipelines that merge powertrain, chassis, and cabin telemetry into single subscription monetization platforms.
Industry Challenges
- Embedded systems talent scarcity:Functional safety engineering expertise for ISO 26262-compliant cloud gateways commands 40-60% salary premiums, constraining Tier 1 scaling capacity.
- Legacy ECU integration complexity:1990s-era controller area network protocols require protocol translation layers that introduce latency and cybersecurity attack surfaces in hybrid architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Cloud Based System Market |
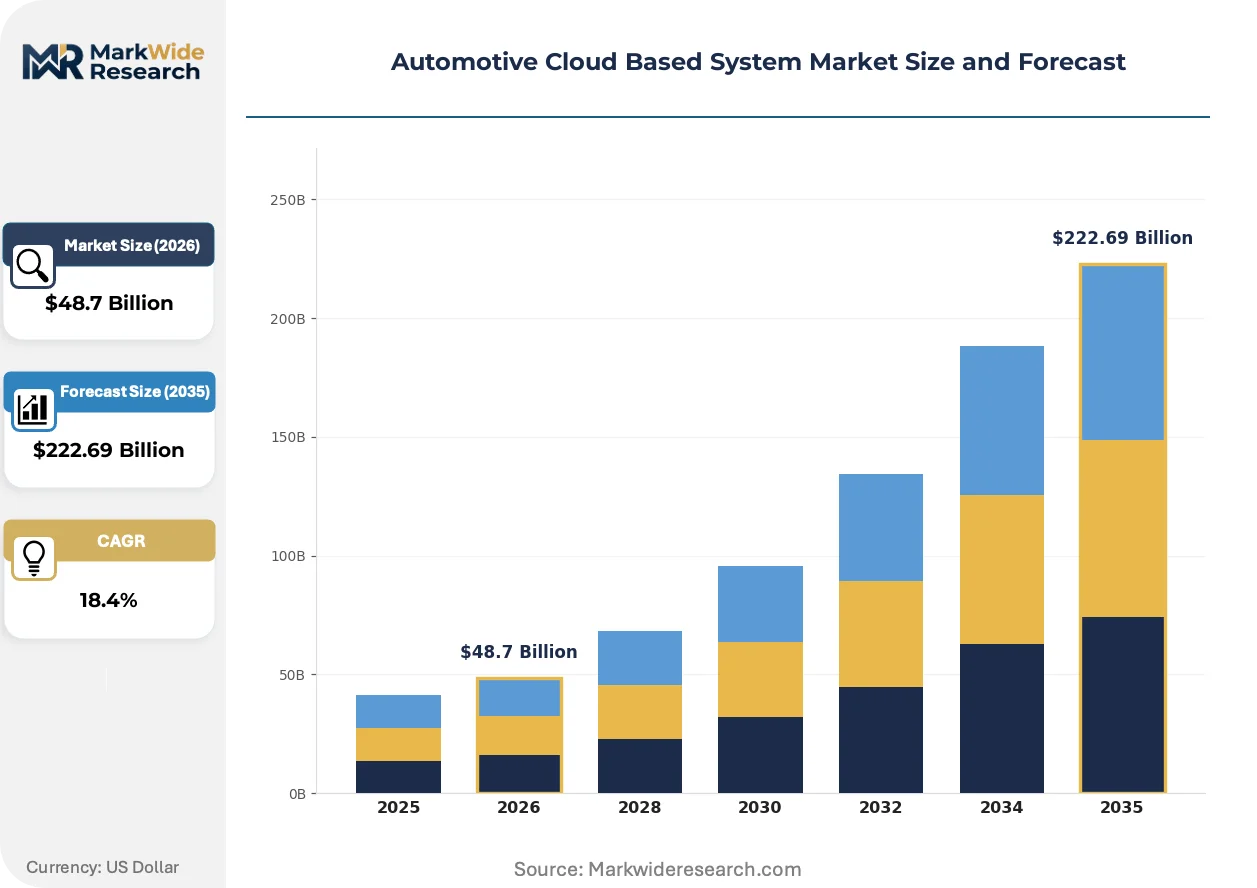
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $222.69 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Telematics, Vehicle Management, Fleet Tracking, Software Updates Deployment: Public Cloud, Hybrid Cloud, Private Cloud, Multi-Cloud End User: OEMs, Fleet Operators, Dealerships, Aftermarket Providers Technology: IOT, Machine Learning, Data Analytics, Connectivity Solutions |
| Companies Covered | Google LLC, Microsoft Corporation, Amazon Web Services Inc., Robert Bosch GmbH, IBM Corporation, Oracle Corporation, Continental AG, Denso Corporation, Verizon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Cloud Based System Market Emerging Trajectories
Containerized microservices architectures are dissolving monolithic automotive software stacks into modular, updateable components. This decomposition is enabling continuous integration pipelines that parallel consumer electronics release cadences while introducing new supply chain dependencies on orchestration platform vendors.
Function-as-a-service edge runtimes are rewriting how latency-critical workloads execute in vehicle gateways. Tier 1 suppliers are deploying these lightweight compute frameworks across braking and steering control modules to process sensor fusion locally before cloud telemetry transmission. The structural consequence is a compression in pure cloud processing revenue per vehicle as edge silicon captures safety-critical value pools.
The EU AI Act's conformity assessment procedures are mandating algorithmic audit trails for machine-learning-based hazard prediction systems deployed in European markets. Automotive OEMs must now maintain version-controlled model repositories with explainability documentation for EMA and national regulator inspection. This regulatory architecture is most acutely affecting German premium manufacturers whose Level 2+ assistance systems rely on neural network perception stacks.
Fleet procurement departments are consolidating vendor relationships around full-stack platform providers capable of delivering edge hardware, connectivity management, and cloud analytics through unified service agreements. This pattern is displacing point-solution procurement for telematics hardware and separate software licensing. The shift is most visible in United States commercial trucking, where large operators are negotiating enterprise-wide contracts spanning ten-thousand-plus vehicle deployments.
Automotive Cloud Based System Market Segmentation
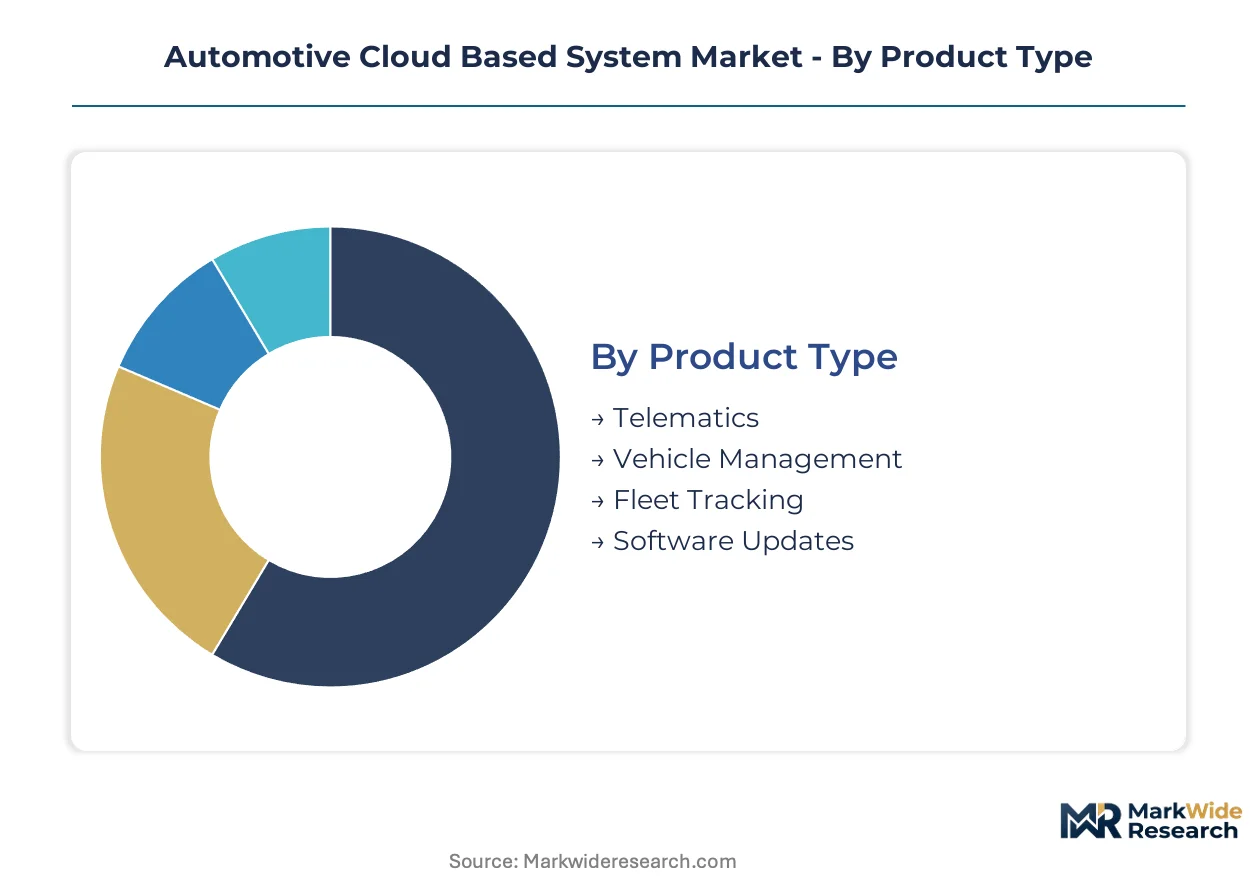
Cloud-based automotive systems fragment across four distinct taxonomies that shape procurement priorities and margin structures. Deployment architecture determines compliance exposure and latency performance, while end-user category dictates contract scale and platform stickiness.
Product Type:
Fleet operators prioritize predictive capabilities over basic connectivity, while OEMs monetize software layers through subscription tiers.
- Telematics:Real-time sensor ingestion platforms process location, diagnostics, and driver behavior telemetry through cellular or satellite uplinks. German commercial fleets under KBA emissions mandates anchor current procurement volumes for compliance-driven deployments.
- Software Updates:Over-the-air distribution systems deliver powertrain patches, infotainment releases, and security fixes with rollback safeguards. Sub-100-millisecond latency requirements for autonomous emergency braking protocols are pulling compute toward hardened edge nodes rather than pure cloud delivery.
- Vehicle Management:Unified dashboards consolidating maintenance scheduling, warranty tracking, and remote diagnostics.
- Fleet Tracking:GPS-based asset visibility systems with geofencing and route optimization for logistics operators.
Volume sits with Telematics; growth tilts toward Software Updates.
Deployment:
Regulatory geography dictates infrastructure choice more than cost optimization for European and Japanese operators.
- Hybrid Cloud:Partitioned architectures air-gap safety-critical control modules from infotainment workloads while maintaining elastic scaling for non-critical analytics. EU AI Act algorithmic transparency mandates and GDPR data residency requirements are accelerating sovereign cloud procurement that keeps telemetry within regional boundaries.
- Public Cloud:Elastic compute instances serving infotainment, navigation, and non-critical telematics with pay-per-use scaling. United States OEMs dominate current adoption due to less stringent data localization requirements compared to European counterparts.
- Private Cloud:Captive infrastructure for defense contractors and government fleet operators with classified mobility requirements.
- Multi-Cloud:Vendor-distributed workloads reducing single-provider dependency for Tier 1 suppliers managing multi-OEM contracts.
Public Cloud captures current volume; Hybrid Cloud is climbing the fastest as cybersecurity frameworks harden.
End User:
Contract scale and platform lock-in duration vary dramatically across buyer categories.
- Fleet Operators:Multi-thousand-unit commercial vehicle managers negotiating enterprise-wide platform agreements spanning ten-thousand-plus deployments. United States trucking consolidation and Japan's usage-based insurance partnerships are concentrating margin pools in this segment through long-term subscription lock-in.
- OEMs:Vehicle manufacturers integrating cloud-native architectures into software-defined vehicle platforms. Domain controller consolidation across powertrain, chassis, and cabin systems is creating unified data pipelines for subscription monetization.
- Dealerships:Service network operators leveraging remote diagnostics for predictive maintenance scheduling and parts inventory optimization.
- Aftermarket Providers:Third-party telematics installers serving owner-operated vehicles and small fleet segments with retrofit hardware.
Fleet Operators hold volume concentration; OEMs are gaining share fastest through software-defined vehicle transitions.
Technology:
Processing location and algorithmic transparency requirements differentiate competitive positioning.
- Machine Learning:Neural network perception stacks for hazard prediction and driver assistance with version-controlled model repositories. EU AI Act conformity assessment procedures mandate explainability documentation for EMA and national regulator inspection, most acutely affecting German premium manufacturers.
- IOT:Sensor-to-cloud telemetry pipelines ingesting CAN bus data, camera feeds, and LiDAR point clouds through vehicle gateways.
- Data Analytics:Batch and stream processing workloads converting raw telemetry into predictive maintenance alerts and usage-based insurance pricing.
- Connectivity Solutions:Cellular-V2X, 5G, and satellite uplink management with network failover orchestration.
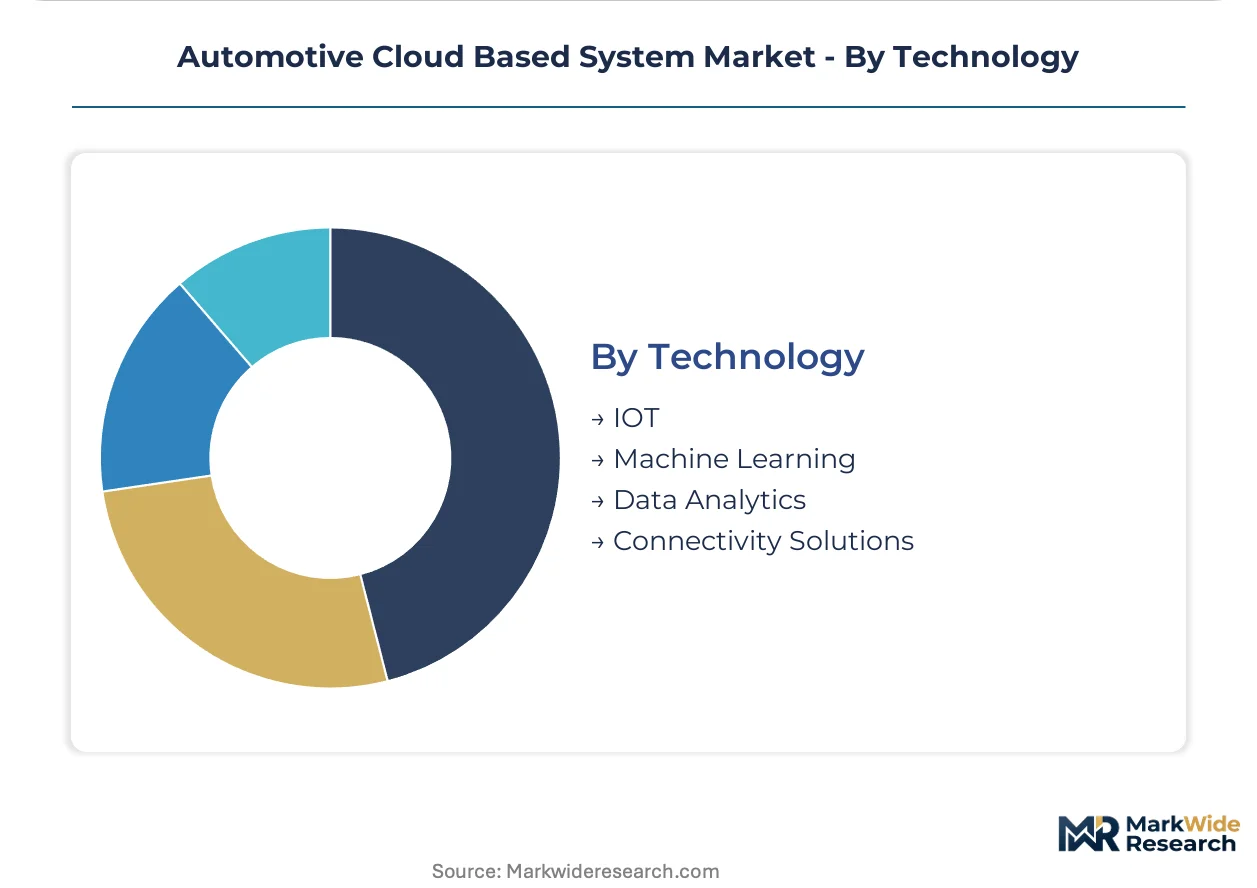
IOT anchors current volume; Machine Learning shows steepest expansion trajectory as Level 2+ assistance systems proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive cloud infrastructure concentrates in special economic zones offering tax incentives for data center construction and sovereign cloud certification. Germany's KBA enforcement zones and India's PLI corridors anchor current capacity expansion. Regional procurement patterns diverge sharply between GDPR-bound European operators and latency-optimized Asian deployments.
United States
NHTSA cybersecurity mandates and FDA software-as-medical-device guidance shape dual-validation protocols for connected vehicle platforms. Fleet operators in Michigan and California negotiate enterprise contracts spanning ten-thousand-plus vehicle deployments. Detroit's automotive corridor hosts concentrated edge computing R&D for autonomous emergency braking systems.
Germany
KBA emissions monitoring mandates drive sovereign cloud procurement for commercial vehicle fleets operating under real-time compliance requirements. EU AI Act algorithmic transparency rules impose version-controlled model repositories on Stuttgart and Munich-based premium manufacturers. Baden-Württemberg's Tier 1 supplier network anchors hybrid edge-cloud validation facilities.
Japan
Usage-based insurance partnerships between METI-regulated insurers and commercial fleet operators monetize telematics data streams. Toyota City and Nagoya's manufacturing clusters integrate cloud-native architectures into software-defined vehicle platforms. Domestic OEMs prioritize sub-100-millisecond latency specifications for autonomous emergency braking protocols.
India
PLI scheme incentives deliver 4-6% cost advantages for suppliers establishing cloud-edge nodes for Tata Motors and Mahindra & Mahindra. BIS certification requirements and TRAI data localization norms shape infrastructure procurement decisions. Pune and Chennai automotive corridors concentrate domestic cloud platform development for export-bound vehicle programs.
South Korea
Seoul Capital Area's connected vehicle testbeds validate 5G-V2X integration with cloud-based hazard prediction systems. MFDS-aligned software validation protocols intersect with automotive cybersecurity frameworks. Hyundai Motor Group's Ulsan complex deploys unified data pipelines merging powertrain and cabin telemetry into subscription monetization platforms.
Automotive Cloud Based System Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with hyperscale cloud providers capturing public workloads while Tier 1 suppliers anchor hybrid edge deployments. Market structure tilts toward consolidation among full-stack platform vendors capable of delivering edge hardware, connectivity management, and cloud analytics through unified service agreements. Three archetypes dominate: hyperscale cloud operators with automotive-specific edge runtimes, diversified technology conglomerates with sovereign cloud instances, and automotive-native suppliers with embedded systems integration expertise. Competitive moves center on strategic partnerships for domain controller consolidation and geographic expansion into PLI-incentivized manufacturing corridors.
Within the hyperscale tier, Amazon Web Services Inc. and Microsoft Corporation exemplify divergent regulatory positioning strategies, with the former anchoring hybrid deployments through edge runtime frameworks and the latter sustaining sovereign cloud instances for European data residency requirements. Google LLC occupies a position specializing in mapping and perception AI layers that extend consumer platform architectures into automotive subscription revenue streams. Among automotive-integrated technology providers, IBM Corporation and Oracle Corporation sit within the enterprise software archetype, representing legacy system migration pathways for OEMs consolidating legacy ECU architectures into cloud-native platforms.
| Leading Market Players |
|---|
| Google LLC |
| Microsoft Corporation |
| Amazon Web Services Inc. |
| Robert Bosch GmbH |
| IBM Corporation |
| Oracle Corporation |
| Continental AG |
| Denso Corporation |
| Verizon |
| Others |
Supply Flow & Price Mechanics
Automotive-grade edge processor silicon from TSMC's Taiwan fabrication facilities flows through Tier 1 supplier networks into three-tier pricing structures across premium, standard, and economy levels, with sovereign cloud certification tiers commanding substantial premiums in GDPR-bound European markets.
Pricing Analysis
Premium pricing for sub-12-week lead times on ISO 26262-certified edge gateways separates emergency procurement from contracted volume commitments. Subscription-based SaaS tiers dominate software layer monetization, with algorithmic transparency documentation under EU AI Act mandates differentiating premium compliance-grade offerings. Pricing pressure stems from TSMC capacity constraints tightening automotive silicon allocation, squeezing margins most acutely for small fleet operators lacking multi-year supply agreements.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for hybrid cloud deployments, while aftermarket distributors serve fragmented retrofit segments. Taiwan, South Korea, and Germany anchor semiconductor and Tier 1 component supply, with automotive-grade edge processors drawing from TSMC's 7nm and 5nm nodes. Single-source vulnerability in Taiwan Strait logistics exposes Tier 1 suppliers to geopolitical disruption, forcing inventory buffer strategies that inflate working capital requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive cloud infrastructure operates under acute silicon supply constraints, with TSMC's automotive-grade fabrication capacity serving as the binding bottleneck propping pricing power for incumbent Tier 1 suppliers.
For Market Incumbents: Acquire sovereign cloud certification capabilities to defend against hyperscaler encroachment into European data residency markets. Consolidate edge runtime software stacks through backward integration into containerized microservices orchestration, neutralizing substitution threats from function-as-a-service entrants. For New Entrants and Emerging Players: The mid-market pricing gap between premium German OEM-grade deployments and economy aftermarket retrofit solutions opens white-space in India PLI-corridor cloud-edge nodes. Target Tata Motors and Mahindra & Mahindra supplier qualification programs, leveraging production-linked incentive credits as a go-to-market wedge against established Tier 1 incumbents. For Investors and Strategic Acquirers: Distressed-cycle entries favor automotive-native software specialists with embedded systems integration expertise in South Korea and Japan. Long-term viability hinges on domain controller consolidation trajectories; monitor Hyundai Motor Group and Toyota Motor Corporation software-defined vehicle platform procurement announcements as inflection indicators for full-stack platform consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Runtime Acquisition | AWS Greengrass and Azure IoT Edge deployments anchor hybrid cloud architectures for Tier 1 supplier networks. |
| Sovereign Cloud Certification | GDPR-compliant instances from Microsoft sustain European OEM data residency requirements under EU AI Act mandates. |
| Domain Controller Consolidation | Unified data pipelines merging powertrain and cabin telemetry enable subscription monetization for software-defined vehicles. |
| PLI Scheme Manufacturing Footprint | India production-linked incentives deliver cost advantages for cloud-edge node suppliers to domestic OEM programs. |
| Algorithmic Transparency Investment | Version-controlled model repositories satisfy EMA inspection requirements for German premium manufacturer Level 2+ systems. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations managers. NHTSA cybersecurity guidance documents, EU AI Act conformity assessment procedures, KBA emissions enforcement protocols, and PLI scheme administrative records provided regulatory calibration. Bottom-up vehicle production database triangulation against top-down cloud infrastructure capex disclosures validated market sizing.
Data-stream reconciliation across deployment architecture segmentation, end-user contract scale tiers, and technology processing location dimensions shaped the analytical framework throughout the forecast period. CAGRs derived from elasticity-adjusted adoption curves incorporating fleet telematics mandate compliance timelines and software-defined vehicle platform transition rates. Vehicle class and propulsion architecture splits informed content-per-vehicle estimates for edge silicon and cloud connectivity modules.
Inputs from semiconductor foundry utilization reports and automotive OEM earnings disclosures were available through the study window; gaps in private fleet operator contract terms introduce uncertainty bands around subscription revenue projections. Forecasts reflect assumptions regarding TSMC capacity allocation continuity and regulatory enforcement consistency. Practitioners should monitor KBA emissions mandate expansion patterns and NHTSA cybersecurity rule finalization timelines for early signals of demand inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Private Cloud Market
Cloud Computing
Cloud Management Market
Cloud Computing
Multi-Cloud Networking Market
Cloud Computing
Cloud Orchestration Market
Cloud Computing
Cloud Enterprise Content Management Market
Cloud Computing
Cloud-Managed LAN Market
Cloud Computing
Global Personal Cloud Market
Cloud Computing
Cloud Identity Management Market
Cloud Computing
Israel Cloud Computing Market
Cloud Computing
Commercial Cloud Market
Cloud Computing
Global Multi Cloud Management Market
Cloud Computing
Saudi Arabia Cloud Computing Market
Cloud Computing
Cloud ECS Market
Cloud Computing
Global Cloud/Mobile Backend AS a Service (Baas) Market
Cloud Computing
Global Cloud Computing Iaas in Life Science Market
Cloud Computing
Application Hosting Market