
 Narrowband-Internet of Things (NB-IoT) Market | 2026-2036
Narrowband-Internet of Things (NB-IoT) Market Size, Share, and Industry Trends Forecast 2026-2036
Narrowband-Internet of Things (NB-IoT) Market Foresight
The EU Green Deal is rebalancing procurement criteria for cellular IoT modules across European utility tenders. Ericsson leverages its radio access network heritage to dominate infrastructure supply for Nordic operators. Nokia Corporation anchors its position through private wireless integration with existing LTE core assets. Qualcomm Technologies, Inc. differentiates via integrated baseband-modem silicon that reduces module bill-of-materials complexity.
Narrowband-Internet of Things (NB-IoT) denotes a low-power wide-area (LPWA) radio technology standardized by 3GPP, operating in licensed spectrum below 1 GHz with uplink bandwidth of 3.75 kHz or 15 kHz and peak data rates near 200 kbps, designed to enable decade-long battery life for sensor devices in deep indoor or underground environments. The technology serves industrial asset monitoring, utility meter reading, and agricultural soil sensing where intermittent small-payload transmission outweighs bandwidth requirements. Deployment mode selection shapes margin structures, with private network implementations commanding premium integration services while public operator subscriptions drive volume scale. End-user concentration in utilities and smart cities channels module demand toward certified ruggedized form factors with extended temperature tolerance.
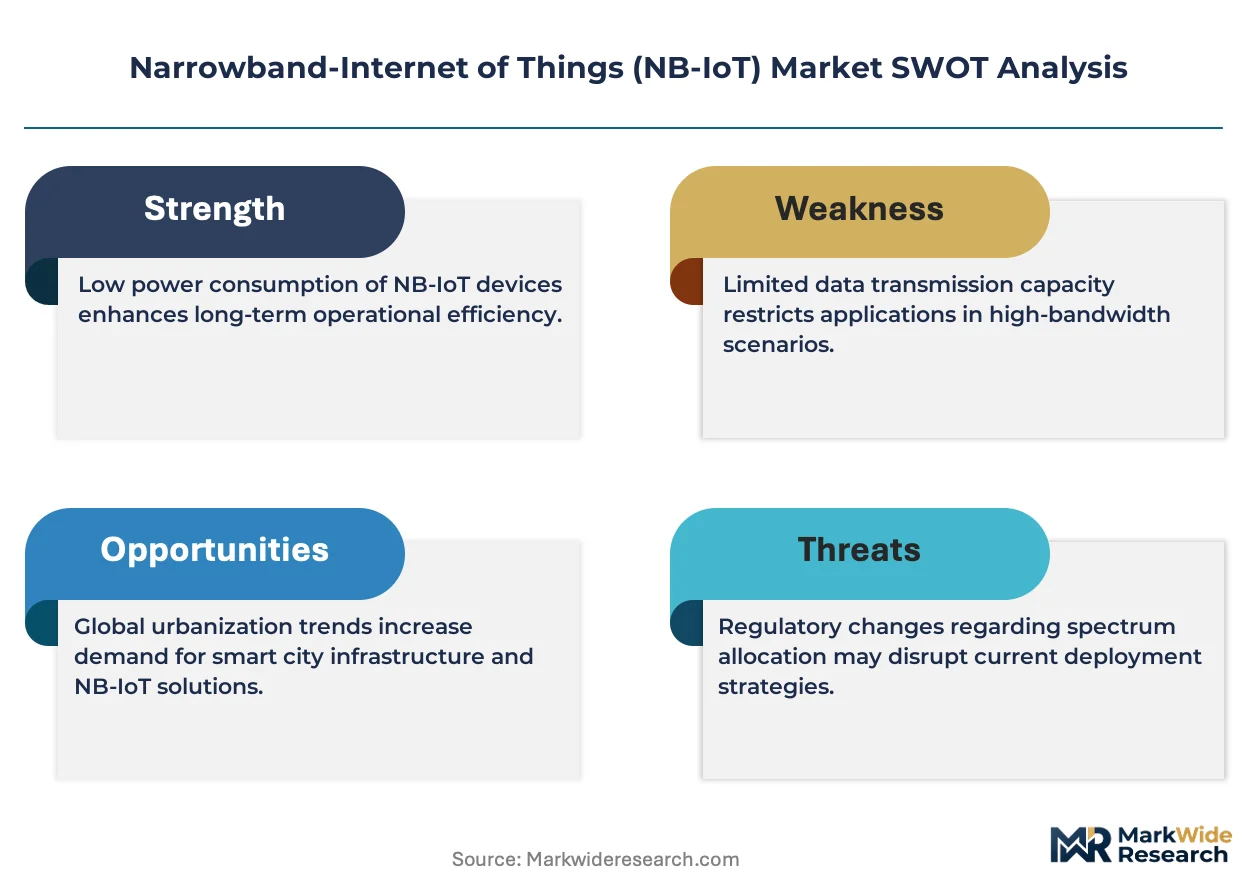
FCC spectrum allocation rules in the United States, CE marking requirements under the EU Radio Equipment Directive, and China's MIIT type-approval framework collectively determine module market access and interoperability testing burdens. ETSI harmonized standards for power spectral density and coexistence with legacy GSM bands constrain hardware design choices across European deployments. Stakeholders must monitor 3GPP Release 17 RedCap specifications and national spectrum reframing decisions to calibrate R&D roadmaps against evolving performance benchmarks and regulatory compliance thresholds.
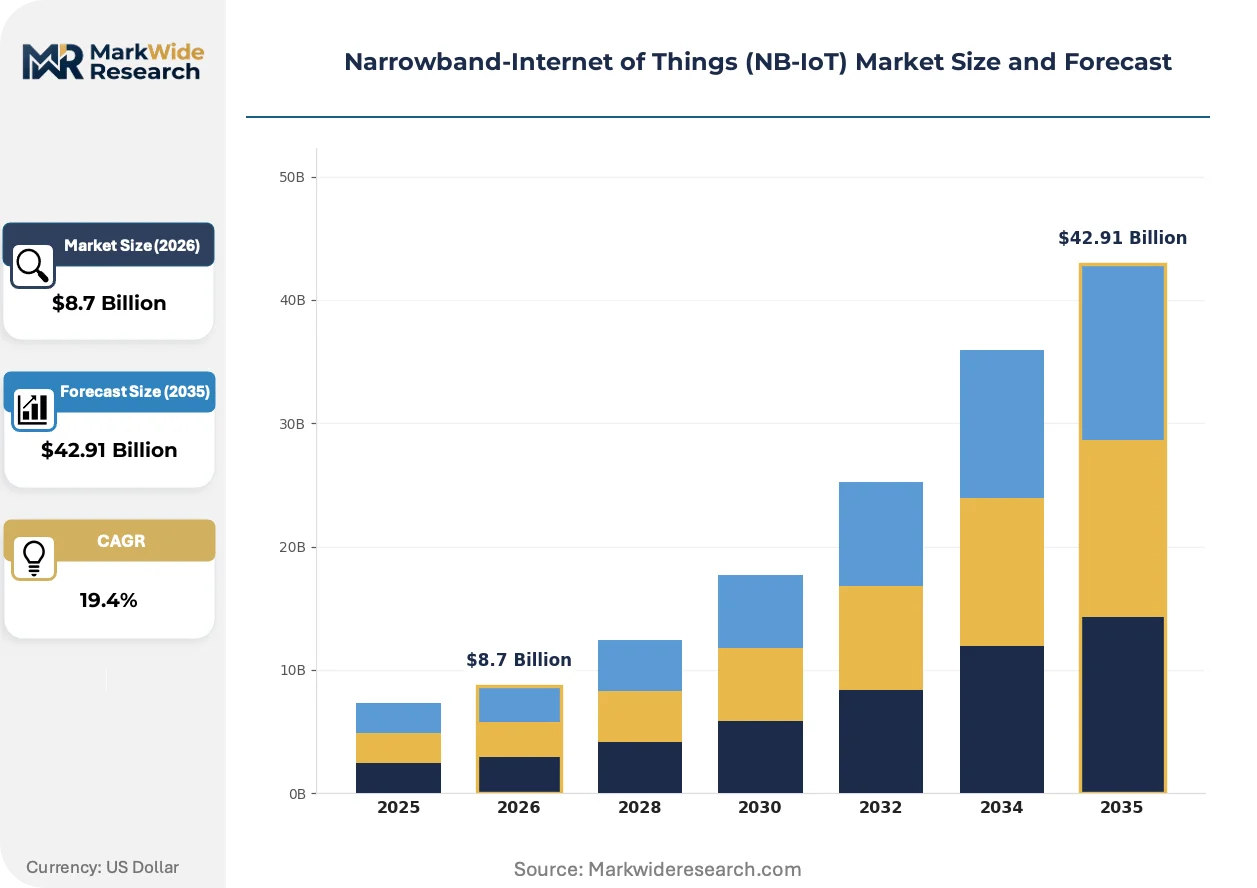
Market Dynamics
3GPP Release 13 harmonization is compressing module interoperability costs while China's manufacturing concentration and EU Green Deal procurement rules create divergent margin pressures across deployment modes.
Growth Catalysts
- Licensed spectrum allocation:FCC rules in the United States and MIIT type-approval in China reduce interference risk versus unlicensed alternatives, accelerating utility meter adoption.
- Smart city infrastructure:Municipal governments in Asia-Pacific deploy deep-indoor sensors for waste management and street lighting, channeling volume demand toward ruggedized modules.
- EU Green Deal procurement criteria:European utility tenders now prioritize energy-efficient cellular modules, rebalancing supplier selection toward low-power certified hardware.
Market Restraints
- Limited uplink bandwidth:The 3.75 kHz and 15 kHz channel options constrain firmware update payload sizes, forcing device makers to fragment software architectures.
- Module cost structure:Integrated baseband-modem silicon reduces bill-of-materials complexity but concentrates supply among semiconductor foundries in East Asia.
- Legacy network substitution:Existing 2G and LTE-M deployments in Latin America and Africa delay NB-IoT migration timelines for cost-sensitive meter reading projects.
Strategic Opportunities
- Agricultural soil sensing:Brazilian and Australian farming cooperatives pilot moisture monitoring networks where decade-long battery life outweighs bandwidth constraints.
- 3GPP Release 17 RedCap:Reduced capability specifications will bridge performance gaps between NB-IoT and full LTE, opening industrial asset monitoring to mid-tier sensor vendors.
- Private wireless integration:Manufacturing facilities in Germany and South Korea combine NB-IoT with existing LTE core assets to bypass public subscription models.
Industry Challenges
- Certification timeline compression:CE marking under the EU Radio Equipment Directive and FCC equipment authorization require parallel testing tracks, extending product launch schedules.
- RF engineering talent scarcity:Deep indoor propagation optimization and power spectral density tuning demand specialized expertise that module vendors struggle to source.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Narrowband-Internet of Things (NB-IoT) Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $42.91 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: NBIoT, LTE-M, Sigfox, LoRaWAN End User: Utilities, Automotive OEMs, Smart Cities, Agriculture Deployment: Public, Private, Hybrid, On-Premises Application: Smart Metering, Asset Tracking, Environmental Monitoring, Wearable Devices |
| Companies Covered | Ericsson, Nokia Corporation, Huawei Technologies Co. Ltd., Qualcomm Technologies, Inc., Sierra Wireless, Quectel Wireless Solutions Co., Ltd, u-blox Holding, Samsung Electronics Co., Ltd., Intel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Narrowband-Internet of Things (NB-IoT) Market Shifts & Advancements
Module architecture is converging around integrated silicon platforms while regulatory frameworks and procurement patterns force simultaneous adaptation across hardware design and go-to-market strategies.
Multi-protocol system-in-package designs are consolidating baseband, RF front-end, and power management functions into single-die solutions. Industrial sensor OEMs in Nordic countries and Japan are adopting these consolidated modules to reduce PCB footprint and thermal design overhead. The structural compression of discrete component sourcing is consolidating supplier tiers and squeezing mid-tier module assemblers.
ETSI harmonized standards for power spectral density and GSM coexistence are constraining transmit power profiles across European deployments. Hardware designers must recalibrate PA efficiency curves and filter banks to meet tighter emission masks. German and French utility operators are responding by pre-qualifying only modules certified to the latest EN 301 908-13 revisions, filtering vendor pools.
Subscription-based device management is displacing perpetual license models for public network deployments. Municipal smart city agencies in Spain and Italy now demand usage-based pricing with guaranteed SLA tiers, forcing module vendors to embed eSIM provisioning and remote monitoring capabilities. This shift is most visible in street lighting and environmental monitoring tenders where total cost of ownership calculations dominate award criteria.
Narrowband-Internet of Things (NB-IoT) Market Segmentation
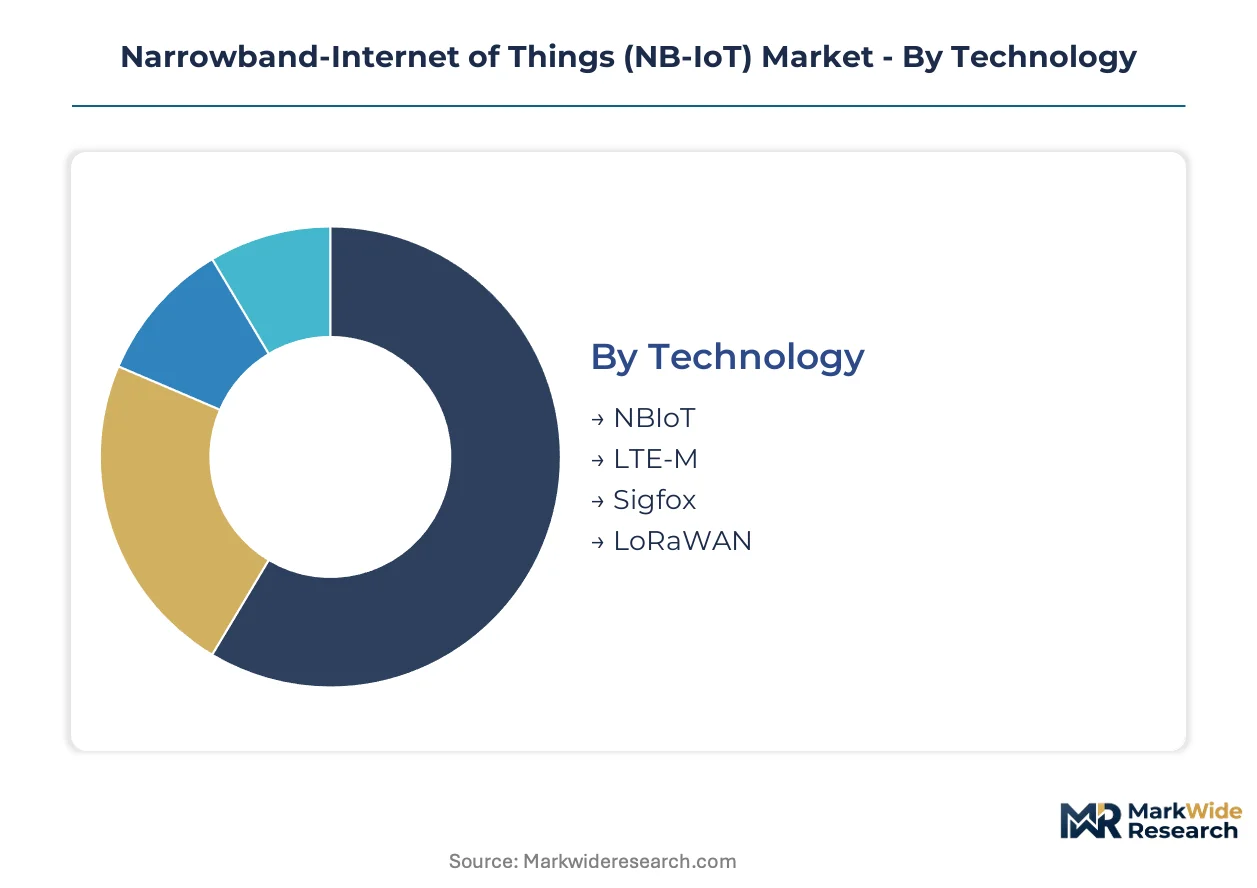
NB-IoT segmentation reveals how deployment economics and regulatory requirements fragment addressable markets. Technology choices determine spectrum licensing costs, while end-user concentration in utilities and smart cities shapes module certification priorities.
Technology:
Upgrade cycles from legacy 2G networks and coexistence requirements with existing cellular infrastructure drive technology selection.
- NBIoT:Operates in licensed spectrum below 1 GHz with 3.75 kHz or 15 kHz uplink bandwidth and decade-long battery life specifications. Chinese utility operators and German municipal water authorities dominate demand, prioritizing deep indoor penetration for basement-mounted meters.
- LTE-M:Supports higher mobility and voice transmission with peak rates near 1 Mbps, attracting Japanese automotive OEMs for connected vehicle telematics where firmware over-the-air updates require larger payload capacity.
- Sigfox:Unlicensed ultra-narrowband protocol with proprietary network infrastructure.
- LoRaWAN:Open-standard unlicensed technology with private gateway deployment flexibility.
NBIoT sits at the top of the volume ranking, with LTE-M climbing the fastest as automotive OEMs migrate from 2G telematics.
End User:
Procurement scale and certification requirements concentrate margin capture among vertically integrated module vendors serving high-volume accounts.
- Utilities:Electric, gas, and water meter operators in Spain, Italy, and China mandate ruggedized modules with extended temperature tolerance and decade-long service life. FCC equipment authorization and CE marking under the EU Radio Equipment Directive impose parallel testing burdens that filter supplier pools.
- Smart Cities:Municipal agencies deploy street lighting controllers and waste bin sensors where intermittent small-payload transmission outweighs bandwidth needs. Brazilian and Australian pilot programs for environmental monitoring are expanding addressable demand.
- Automotive OEMs:Connected vehicle and fleet management applications.
- Agriculture:Soil moisture and livestock tracking networks.
Utilities command the highest procurement volumes, while Smart Cities expand most quickly as Asia-Pacific infrastructure budgets accelerate.
Deployment:
Margin structures diverge sharply between subscription-based public models and premium integration services for private implementations.
- Public:Operator-managed subscriptions with guaranteed SLA tiers dominate Spanish and Italian street lighting tenders. Module vendors embed eSIM provisioning and remote monitoring capabilities to meet usage-based pricing demands from municipal agencies.
- Private:Manufacturing facilities in Germany and South Korea combine NB-IoT with existing LTE core assets to bypass public subscription models, commanding premium integration fees.
- Hybrid:Blended public-private architectures.
- On-Premises:Fully captive network infrastructure.
Public deployment leads volume rankings, with Private implementations gaining share fastest among industrial asset monitoring applications.
Application:
Payload size requirements and transmission frequency determine module specification tiers across use cases.
- Smart Metering:Dominates module consumption through electric, gas, and water utility rollouts. Deep indoor propagation optimization for basement and underground installations drives demand for certified ruggedized form factors with power spectral density tuning.
- Asset Tracking:Industrial equipment and container monitoring applications.
- Environmental Monitoring:Air quality and noise sensors in urban deployments.
- Wearable Devices:Personal health and safety monitors with strict power constraints.
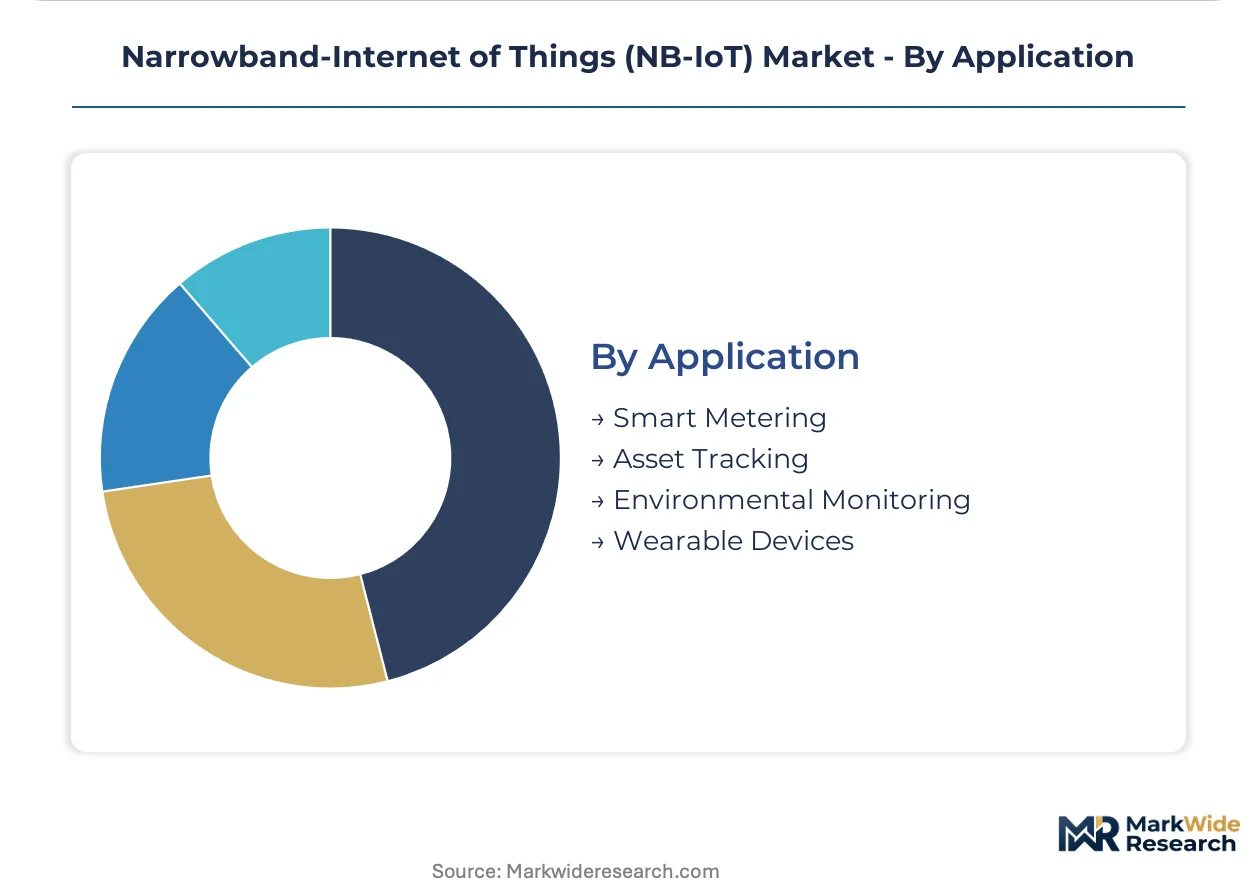
Smart Metering anchors volume demand, with Asset Tracking showing steepest expansion trajectory as 3GPP Release 17 RedCap specifications bridge performance gaps for mid-tier sensor vendors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
RF engineering talent clusters in Shenzhen, Espoo, and San Diego anchor NB-IoT module design. Manufacturing scale concentrates in East Asian foundry corridors. Regulatory divergence across FCC, CE marking, and MIIT frameworks fragments certification pathways.
China
Utility meter operators in Jiangsu and Zhejiang provinces drive module procurement volumes for basement-mounted water and gas sensors. MIIT type-approval frameworks mandate rigorous interoperability testing before network deployment authorization. Shenzhen's electronics manufacturing corridor hosts concentrated baseband-modem silicon packaging operations serving domestic operators and export markets.
Germany
Municipal water authorities in North Rhine-Westphalia and Bavaria prioritize deep indoor penetration for underground meter installations. ETSI harmonized standards under EN 301 908-13 constrain power spectral density profiles and emission masks. Industrial manufacturing clusters around Stuttgart and Munich integrate NB-IoT with existing LTE core assets for private wireless implementations.
United States
Electric utilities in California and Texas deploy licensed spectrum networks for grid monitoring and demand response systems. FCC equipment authorization rules require parallel testing tracks alongside international certification programs. San Diego's wireless engineering hub anchors integrated baseband design activities for module vendors targeting North American operator tenders.
Japan
Automotive OEMs in Aichi Prefecture evaluate NB-IoT for connected vehicle telematics alongside LTE-M alternatives. METI spectrum allocation policies favor licensed LPWA technologies for industrial applications. Yokohama's smart city pilot programs test environmental monitoring sensors where intermittent small-payload transmission meets decade-long battery specifications.
Brazil
Farming cooperatives in São Paulo and Mato Grosso pilot soil moisture monitoring networks where low bandwidth requirements align with extended field deployment cycles. ANVISA regulatory frameworks for connected health devices indirectly shape module certification expectations for agricultural sensor vendors. Campinas technology corridor hosts emerging integration services for Latin American utility migration projects.
Narrowband-Internet of Things (NB-IoT) Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the NB-IoT value chain. Foundry-dependent semiconductor vendors face margin pressure from integrated platform specialists. Three archetypes dominate: radio access network infrastructure suppliers, silicon-integrated module designers, and ruggedized hardware assemblers. Strategic moves concentrate on private wireless integration partnerships and multi-protocol system-in-package consolidation.
Within the infrastructure tier, Ericsson and Nokia Corporation represent contrasting Nordic approaches to operator supply. Qualcomm Technologies, Inc. exemplifies silicon-level integration that compresses bill-of-materials complexity for downstream module vendors. These three anchors illustrate how heritage in radio access networks, LTE core assets, or baseband-modem design shapes competitive positioning without guaranteeing segment dominance.
| Leading Market Players |
|---|
| Ericsson |
| Nokia Corporation |
| Huawei Technologies Co. Ltd. |
| Qualcomm Technologies, Inc. |
| Sierra Wireless |
| Quectel Wireless Solutions Co., Ltd |
| u-blox Holding |
| Samsung Electronics Co., Ltd. |
| Intel Corporation |
| Others |
Supply & Pricing Matrix
Silicon wafer spot indices from East Asian foundry corridors cascade through NB-IoT module bill-of-materials, compressing margin structures at the standard tier while premium certified variants retain pricing power through CE marking and FCC authorization bundling.
Pricing Analysis
Bundled certification-plus-connectivity service splits from pure hardware transactions separate procurement economics across European utility tenders. Three-tier pricing structure across premium ruggedized, standard commercial, and economy reference designs stratifies module offerings, with CE marking under EN 301 908-13 revisions and decade-long battery specifications driving tier separation. Cost compression in economy modules intensifies because Chinese foundry concentration feeds component oversupply, while German municipal water authorities show least price sensitivity due to total cost-of-ownership calculations dominating award criteria.
Supply Chain Analysis
Single-source vulnerability sits with baseband-modem silicon packaging operations concentrated in Shenzhen manufacturing corridors. Module assembly draws from Taiwanese foundry outputs for integrated system-in-package designs, South Korean memory components, and Chinese PCB substrate supply. Tariff exposure on semiconductor inputs threatens margin stability for vendors serving North American operator tenders. Distribution runs through direct OEM supply agreements for volume utility accounts alongside distributor channels serving mid-tier sensor vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The NB-IoT market reads as a late-cycle quality story where procurement criteria under the EU Green Deal shift demand toward energy-efficient certified modules with extended temperature tolerance specifications.
For Market Incumbents: Deepen private wireless integration capabilities to capture premium services revenue from German and South Korean manufacturing facilities combining NB-IoT with existing LTE core assets. Fortify certification investment pipelines against CE marking timeline compression under evolving ETSI harmonized standards. Anchor capacity allocation toward ruggedized form factors as Brazilian and Australian agricultural pilots expand addressable demand.
For New Entrants and Emerging Players: Industrial system integrators represent the most accessible channel partner type for bypassing entrenched operator supply relationships. Target agricultural soil sensing networks in São Paulo and Mato Grosso farming cooperatives where incumbent presence remains thin. Lead with usage-based device management platforms embedding eSIM provisioning to match Spanish and Italian municipal procurement patterns.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier module assemblers lose sourcing leverage against integrated silicon platform specialists. Long-term viability favors vendors with captive RF engineering talent clusters in San Diego or Espoo paired with MIIT type-approval track records for Chinese market access. Monitor 3GPP Release 17 RedCap specification adoption rates as inflection indicator for industrial asset monitoring segment expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Protocol System-in-Package Consolidation | Reduces PCB footprint for Nordic industrial sensor OEMs adopting consolidated baseband-RF-power management dies. |
| Private Wireless Integration Partnership | Captures premium integration fees from German automotive clusters bypassing public subscription models. |
| CE Marking Pre-Qualification Investment | Filters vendor pools as French and German utilities mandate EN 301 908-13 revision compliance. |
| eSIM Provisioning Capability Embedding | Matches usage-based pricing demands from Spanish and Italian smart city agencies. |
| Agricultural Pilot Program Expansion | Opens Brazilian and Australian moisture monitoring networks where battery life outweighs bandwidth constraints. |
Research Methodology
Coverage spans China, Germany, the United States, Japan, and Brazil, with primary inputs from each market informing demand calibration. The study combines structured interviews with RF engineering directors at module vendors, procurement leads at European utility operators, and smart city technology officers at Asia-Pacific municipal agencies with secondary validation from 3GPP specification documents, FCC equipment authorization databases, MIIT type-approval registries, and ETSI harmonized standard publications. Bottom-up module shipment estimates triangulate against top-down operator network deployment disclosures.
Granularity-level modeling captures technology splits across NBIoT, LTE-M, Sigfox, and LoRaWAN alongside deployment mode differentiation between public subscription and private wireless implementations. End-user segmentation tracks utilities, smart cities, automotive OEMs, and agricultural cooperatives across the analysis window. CAGRs derive from installed base growth curves adjusted for legacy 2G substitution timelines and spectrum reframing decisions. Forecast inputs incorporate 3GPP Release 17 RedCap specification timelines and national spectrum allocation rulings from FCC, MIIT, and METI regulators.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to semiconductor foundry capacity allocation shifts and regulatory reframing of licensed spectrum bands. Projections reflect documented assumptions regarding module cost curves, certification timeline standardization, and utility procurement cycle phasing. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
North America Narrowband-Internet of Things (NB-IoT) Market
Internet of Things (IoT)
Global Machine-To-Machine (M2M) Connections Market
Internet of Things (IoT)
Wifi IoT Market
Internet of Things (IoT)
UK IoT Software Market
Internet of Things (IoT)
IoT Gateway Hardware and Software Market
Internet of Things (IoT)
IoT Lpwans Market
Internet of Things (IoT)
Global IoT in Aerospace and Defense Market
Internet of Things (IoT)
Internet of Things (IoT) Market
Internet of Things (IoT)
Asia-Pacific Massive IoT Market
Internet of Things (IoT)
IoT Microcontroller Market
Internet of Things (IoT)
IIOT Gateway for Utility Market
Internet of Things (IoT)
Smart Tracker Market
Internet of Things (IoT)
Smart Sprinkler Controller Market
Internet of Things (IoT)
IoT Communication Technologies Market
Internet of Things (IoT)
Europe IoT Device Market
Internet of Things (IoT)
Massive IoT Market