
 IoT Gateway Devices Market | 2026-2036
IoT Gateway Devices Market Size, Share, and Industry Trends Forecast 2026-2036
IoT Gateway Devices Market Analysis
Industrial-grade gateway specifications with IEC 62443-4-2 security certification is collapsing the gap between legacy operational technology networks and modern IP-based infrastructure. Cisco Systems leverages its dominant position in enterprise routing to anchor high-availability gateway deployments across process manufacturing. Advantech Co., Ltd. specializes in ruggedized edge hardware for temperature-extreme environments, while Huawei Technologies Co., Ltd. competes aggressively on integrated 5G-and-Wi-Fi module designs for smart city backbones.
An IoT gateway device is a networked compute node that translates between heterogeneous device protocols, typically incorporating ARM or x86 processors with 512 MB to 4 GB RAM, and enforces local data filtering before cloud transmission. Its primary purpose is to bridge resource-constrained sensors and actuators to enterprise or hyperscaler platforms without exposing low-power endpoints to direct internet connectivity. Edge gateways now capture the dominant margin pool as latency-sensitive applications in industrial automation demand sub-10 millisecond local decisioning. Cellular connectivity technology is expanding fastest where wireline infrastructure remains uneconomical, particularly across agricultural telemetry and remote asset monitoring.
The US Federal Communications Commission governs radio frequency emissions for unlicensed gateway spectrum, while the European Union's Cybersecurity Act mandates baseline security certification for network equipment placed on the EU market. China's Ministry of Industry and Information Technology enforces GB/T standards for domestic IoT device interoperability, creating divergent compliance burdens for multinational suppliers. Stakeholders must decide whether to architect modular certification-ready platforms or region-locked product variants as regulatory fragmentation deepens.
Market Dynamics
Industrial automation's shift toward deterministic edge computing is compressing gateway procurement cycles as automotive and machinery OEMs mandate sub-10 millisecond protocol translation for legacy equipment retrofit programs.
Growth Catalysts
- EU Cybersecurity Act certification mandates:Network edge hardware placed on the European market must achieve baseline security certification, creating replacement demand for uncertified installed base across Germany's automotive corridor.
- 5G-integrated module adoption:Smart city infrastructure deployments in temperature-extreme environments require ruggedized gateways with cellular backhaul where wireline infrastructure remains uneconomical.
- Healthcare telemetry expansion:Connected patient monitoring infrastructure procurement is accelerating as hospital systems deploy bedside-to-cloud data pipelines without exposing low-power medical endpoints to direct internet connectivity.
Market Restraints
- Semiconductor supply concentration:ARM and x86 processor availability depends on concentrated foundry capacity in East Asia, exposing gateway manufacturers to input volatility for 512 MB to 4 GB RAM configurations.
- Regulatory fragmentation costs:China's MIIT enforces GB/T standards for domestic IoT interoperability while the EU mandates IEC 62443-4-2 certification, forcing suppliers to maintain region-locked product variants or absorb modular platform development costs.
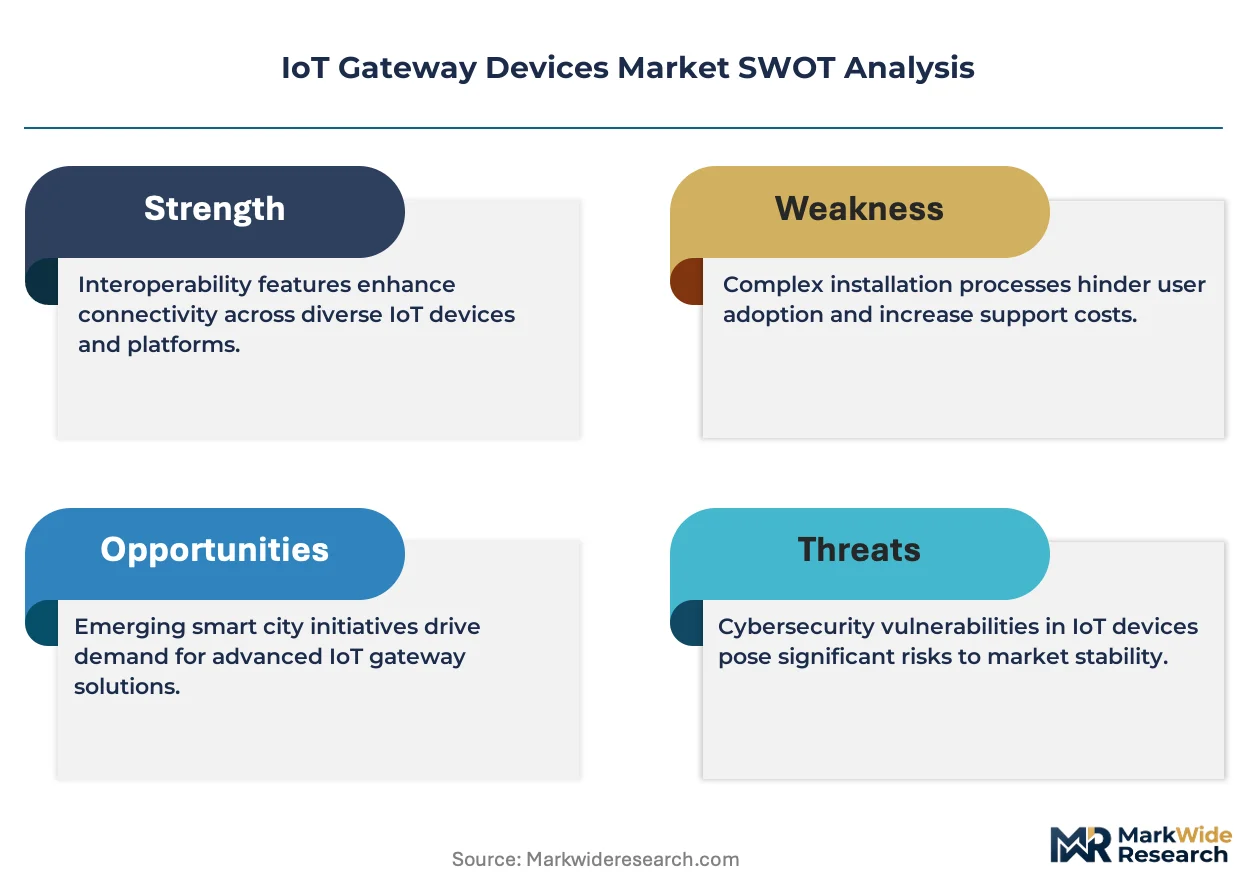
- Technical protocol legacy lock-in:Operational technology networks running proprietary fieldbus standards resist IP-based translation without extensive site-specific engineering, extending sales cycles for brownfield deployments.
Strategic Opportunities
- Agricultural telemetry penetration:Remote asset monitoring in Brazil and Australia's pastoral regions presents white space for solar-powered cellular gateways where grid connectivity is absent.
- AI Act compliance services:The European Union's AI Act creates adjacent revenue streams for gateway vendors offering embedded audit logging and local inference capabilities that satisfy high-risk system documentation requirements.
- Wi-Fi 6 and 5G convergence:Integrated radio modules enabling seamless handoff between private cellular and enterprise wireless are capturing specification wins in process manufacturing facilities requiring mobility support.
Industry Challenges
- IEC 62443-4-2 certification timeline:Security certification for industrial-grade gateways requires 12-18 month validation cycles that delay product launches and compress effective revenue windows before standards revision.
- Embedded systems talent scarcity:Firmware engineering for real-time protocol translation competes with consumer electronics and automotive sectors for constrained ARM architecture specialists.
- Multi-protocol integration complexity:Gateway deployments must simultaneously translate Modbus, Profinet, EtherCAT, and OPC-UA traffic while maintaining deterministic latency guarantees, expanding pre-sales engineering requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IoT Gateway Devices Market |
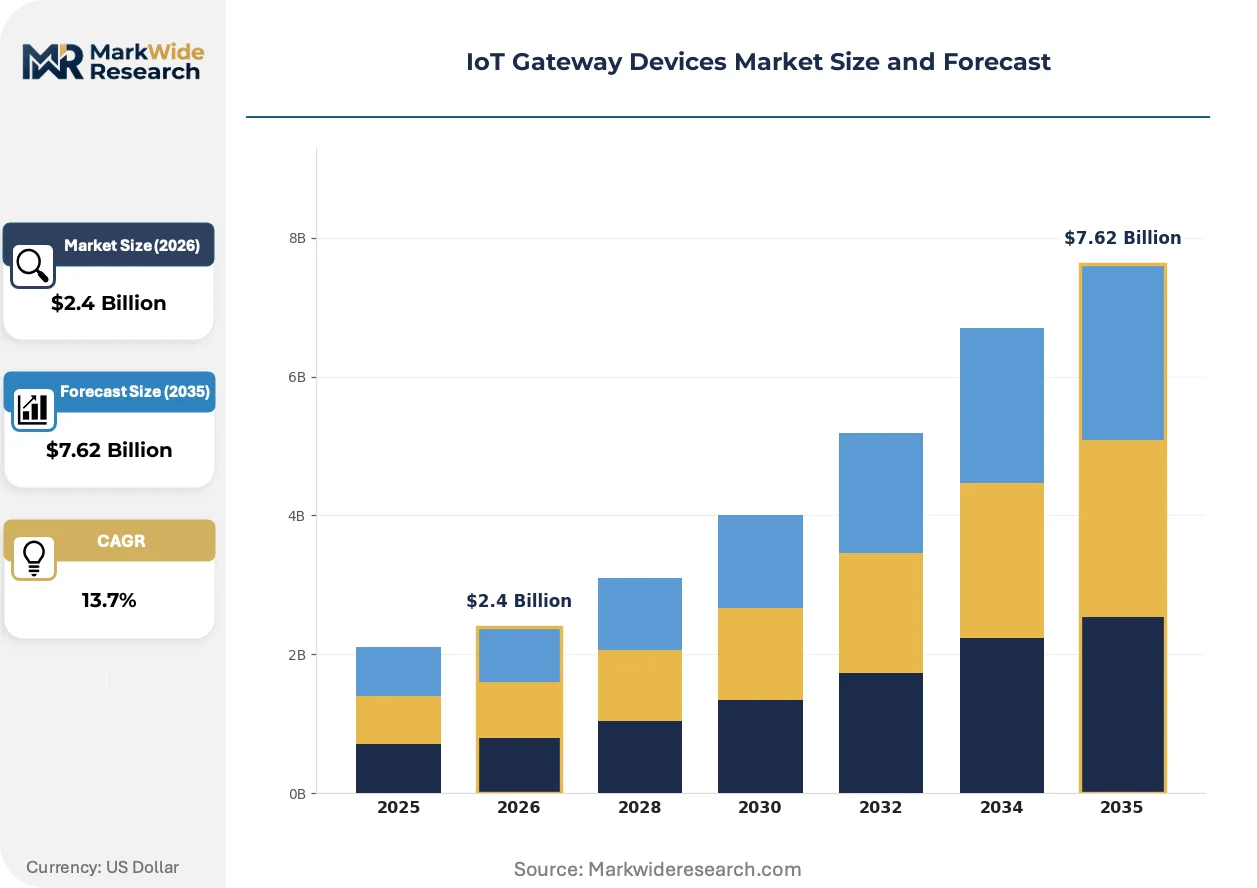
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $7.62 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Edge Gateways, Cloud Gateways, Device Gateways, Network Gateways Application: Smart Home, Industrial Automation, Smart Healthcare, Smart Transportation Connectivity Technology: Wi-Fi, Bluetooth, Zigbee, Cellular End User: Retail, Healthcare, Manufacturing, Agriculture |
| Companies Covered | Cisco Systems, Inc., Advantech Co., Ltd., Huawei Technologies Co., Ltd., Dell Technologies, Intel Corporation, Texas Instruments Incorporated, NXP Semiconductors N.V., Qualcomm Technologies, Inc., Microchip Technology Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IoT Gateway Devices Market Emerging Trajectories
Edge intelligence architectures are collapsing the boundary between data acquisition and local decisioning, forcing gateway vendors to embed inference capabilities that previously resided in cloud or SCADA layers.
Multi-core ARM Cortex-A53 system-on-modules with hardware-accelerated encryption engines are displacing single-purpose protocol translators in automotive production lines. Tier-1 suppliers specify these compact compute nodes for welding robot cells requiring deterministic cycle times. The form factor is miniaturizing from DIN-rail enclosures to PCB-mount modules that integrate directly into machine control cabinets, compressing bill-of-materials costs and installation labor.
The EU Cybersecurity Act's baseline certification requirements for network equipment are mandating secure boot chains and firmware signing across all gateway categories placed on the European market. Industrial OEMs in Germany's machinery sector now exclude uncertified vendors from approved supplier lists. Response patterns show accelerated R&D allocation toward hardware security module integration and automated vulnerability scanning pipelines.
Buyers in process manufacturing are unbundling gateway hardware from integration services, preferring direct procurement of certified edge devices followed by third-party systems integrator deployment. This pattern compresses vendor margins on professional services while expanding volume through distribution channel partners. The shift is most visible in North American chemical processing facilities where capital project procurement teams have restructured vendor qualification criteria.
IoT Gateway Devices Market Segmentation
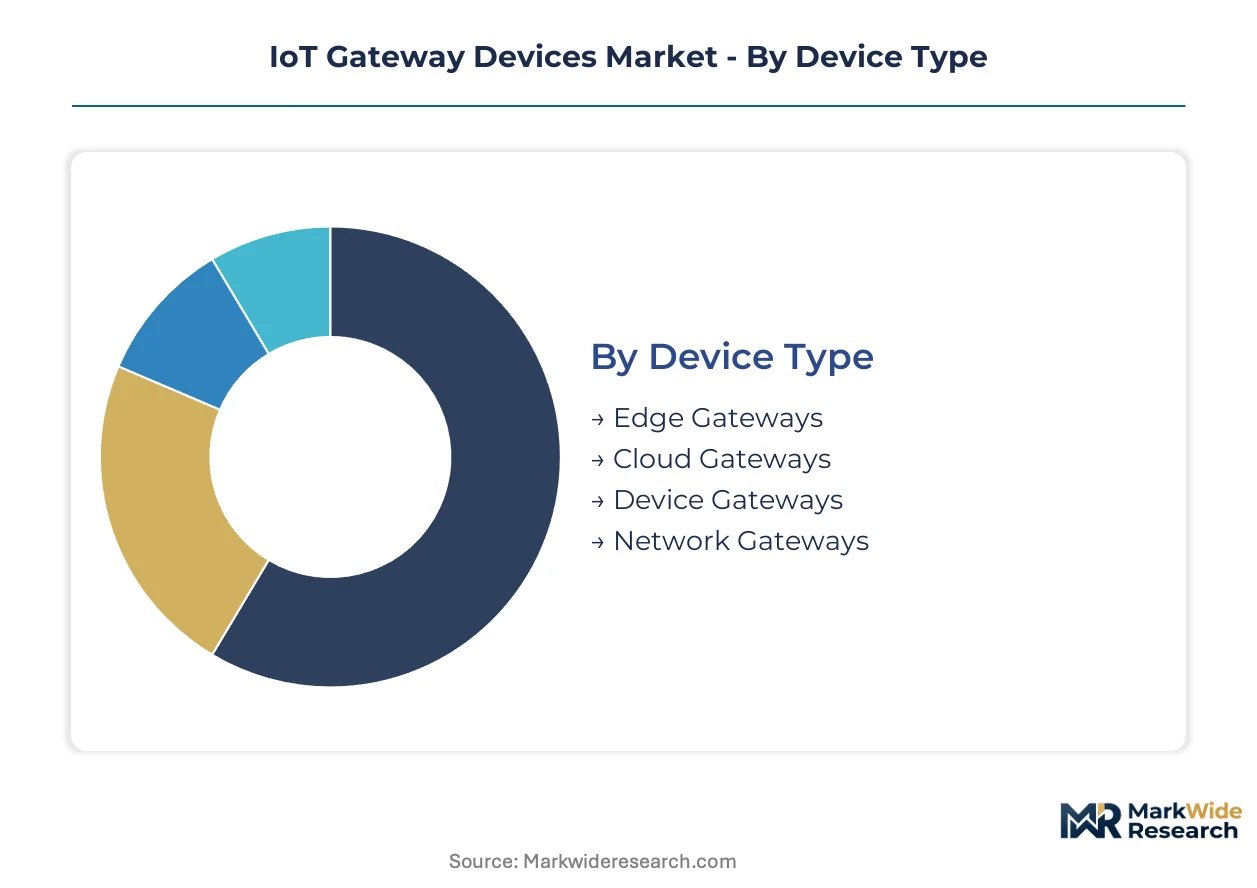
Gateway segmentation determines procurement channel strategy, as industrial buyers source through systems integrators while smart home deployments flow through retail distribution. The four-dimensional structure—device type, application, connectivity, and end user—creates distinct margin pools and certification requirements across each axis.
Device Type:
Edge gateways move through industrial distributors and direct OEM relationships, while cloud and device variants split between enterprise VARs and consumer electronics retail.
- Edge Gateways:ARM or x86 compute nodes with 512 MB to 4 GB RAM enforce local data filtering and protocol translation before cloud transmission. Germany's automotive corridor concentrates procurement for deterministic sub-10 millisecond retrofit applications on legacy production lines. IEC 62443-4-2 certification mandates from the EU Cybersecurity Act are collapsing the gap between operational technology and IP infrastructure.
- Cloud Gateways:Aggregation nodes managing bidirectional traffic between distributed edge clusters and hyperscaler platforms. Smart city infrastructure deployments in temperature-extreme environments require ruggedized hardware with automated vulnerability scanning pipelines.
- Device Gateways:Compact protocol translators for resource-constrained sensor networks.
- Network Gateways:Enterprise-grade routing hardware with integrated security policy enforcement.
Edge gateways dominate installed base. Cloud gateways are where expansion concentrates.
Application:
Cost tier stratification separates premium-certified industrial automation from standard-tier smart home deployments, with healthcare occupying a mid-tier compliance-heavy position.
- Industrial Automation:Deterministic edge computing for welding robot cells and process manufacturing requiring hardware-accelerated encryption engines. Multi-core ARM Cortex-A53 modules with secure boot chains capture specification wins as Tier-1 suppliers mandate firmware signing. Brownfield fieldbus translation extends sales cycles for Modbus and Profinet integration.
- Smart Healthcare:Bedside-to-cloud data pipelines protecting low-power medical endpoints from direct internet exposure. Hospital systems accelerate procurement of connected patient monitoring infrastructure without compromising HIPAA compliance for telemetry backhaul.
- Smart Home:Consumer-grade protocol bridging for residential sensor ecosystems.
- Smart Transportation:Mobile gateways enabling vehicle-to-infrastructure communication and fleet telemetry.
Industrial automation commands premium pricing. Smart healthcare is climbing the fastest as regulatory compliance creates vendor stickiness.
Connectivity Technology:
Volume concentration favors Wi-Fi for indoor deployments, while margin accrues to cellular where wireline infrastructure remains uneconomical.
- Cellular:Solar-powered modules with 5G-and-Wi-Fi convergence for remote asset monitoring in Brazil and Australia's pastoral regions. Agricultural telemetry penetration presents white space where grid connectivity is absent and private cellular handoff enables mobility support in process manufacturing.
- Wi-Fi:Enterprise wireless backbone for smart city infrastructure and indoor industrial environments. Wi-Fi 6 integrated radio modules capture specification wins in North American chemical processing facilities where capital project procurement teams restructured vendor qualification criteria.
- Bluetooth:Low-energy personal area networking for wearable medical devices and proximity sensing.
- Zigbee:Mesh topology for smart home lighting and climate control ecosystems.
Wi-Fi dominates unit shipments. Cellular is gaining share fastest where infrastructure economics favor wireless backhaul.
End User:
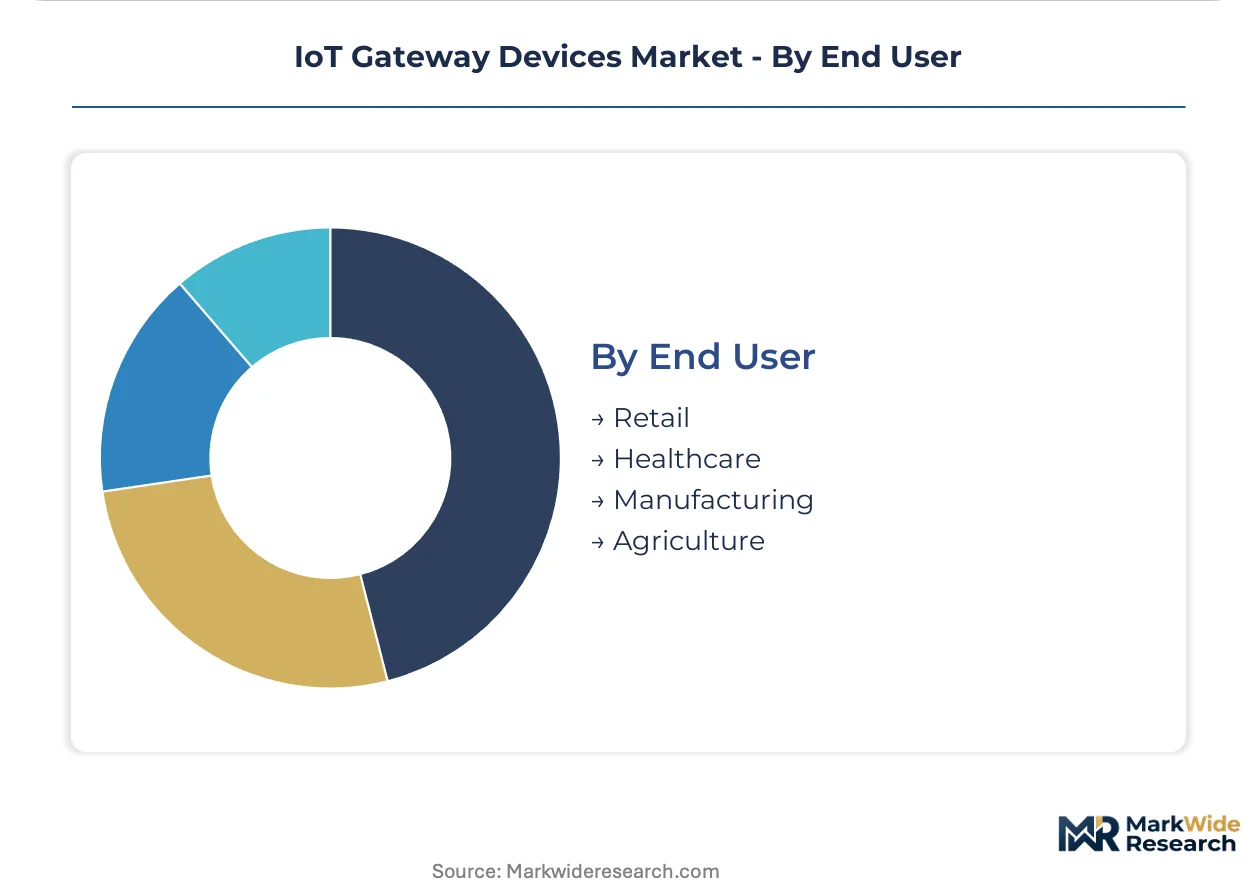
Customer type determines procurement modality: manufacturing buyers unbundle hardware from integration services, while healthcare and retail prefer bundled solutions.
- Manufacturing:Direct procurement of certified edge devices followed by third-party systems integrator deployment. Germany's machinery OEMs now exclude uncertified vendors from approved supplier lists, compressing vendor margins on professional services while expanding volume through distribution channel partners.
- Healthcare:Hospital systems and outpatient clinics requiring embedded audit logging for EU AI Act compliance. Adjacent revenue streams emerge for gateway vendors offering local inference capabilities that satisfy high-risk system documentation requirements.
- Retail:Point-of-sale and inventory tracking infrastructure with standardized deployment protocols.
- Agriculture:Pastoral telemetry for livestock monitoring and irrigation control in remote grid-absent regions.
Manufacturing dominates current revenue. Healthcare represents the steepest expansion trajectory as bedside monitoring infrastructure scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gateway device trade flows reflect divergent industrial digitization speeds, with Germany and the United States running structural deficits in certified edge hardware while China maintains surplus capacity in module assembly. Import dependence concentrates in markets with stringent IEC 62443-4-2 timelines, compressing procurement flexibility.
Germany
Automotive OEMs in Stuttgart and Munich mandate sub-10 millisecond protocol translation for welding robot retrofits, driving demand for ARM-based edge modules. The EU Cybersecurity Act excludes uncertified vendors from approved supplier lists, tightening procurement criteria. Baden-Württemberg's machinery corridor concentrates specification wins for hardware security module-integrated gateways.
United States
Process manufacturing facilities in Texas and Louisiana restructure capital project procurement to unbundle hardware from integration services. The FCC governs unlicensed spectrum emissions for industrial wireless backhaul. Houston's chemical processing cluster accelerates direct procurement of certified edge devices through distribution channel partners.
China
MIIT enforces GB/T standards for domestic IoT interoperability, creating compliance divergence with IEC certification requirements. The Yangtze River Delta anchors module assembly capacity for 5G-integrated gateway designs. Shenzhen's electronics ecosystem supplies hardware-accelerated encryption engines for temperature-extreme smart city deployments.
Japan
METI promotes edge computing adoption in precision manufacturing, aligning gateway procurement with Industry 4.0 roadmaps. The Kanto region around Tokyo concentrates demand for deterministic protocol translation in semiconductor fabrication facilities. Nagoya's automotive supply chain specifies miniaturized PCB-mount modules for machine control cabinet integration.
Brazil
Agricultural telemetry in Mato Grosso and Goiás presents white space for solar-powered cellular gateways where grid infrastructure remains absent. ANVISA regulates connected medical device data pipelines, creating adjacent compliance requirements for healthcare gateway deployments. São Paulo's industrial belt drives modest demand for brownfield fieldbus translation in food processing plants.
IoT Gateway Devices Market Vendor Landscape
Listed leaders compete with private specialists across certification depth and integration complexity, producing a tiered structure where scale advantages in enterprise routing clash with agility in ruggedized edge hardware. The vendor base spans three strategic archetypes: networking incumbents with dominant channel presence, industrial computing specialists with temperature-extreme credentials, and semiconductor vendors with captive module supply. Competitive moves concentrate on strategic partnerships for protocol stack licensing and geographic expansion through distribution channel capture.
Within the networking incumbent tier, Cisco Systems, Inc. anchors high-availability positioning through enterprise routing relationships. Among industrial computing specialists, Advantech Co., Ltd. exemplifies ruggedized edge hardware credentials for temperature-extreme environments. On the integrated telecommunications vector, Huawei Technologies Co., Ltd. occupies a position emphasizing converged 5G-and-Wi-Fi module designs. These three represent distinct strategic bets on where gateway value capture concentrates.
| Leading Market Players |
|---|
| Cisco Systems, Inc. |
| Advantech Co., Ltd. |
| Huawei Technologies Co., Ltd. |
| Dell Technologies |
| Intel Corporation |
| Texas Instruments Incorporated |
| NXP Semiconductors N.V. |
| Qualcomm Technologies, Inc. |
| Microchip Technology Inc. |
| Others |
Supply Flow & Price Mechanics
The EU Cybersecurity Act's IEC 62443-4-2 certification gates both supplier qualification and price stratification, forcing uncertified vendors into discount tiers while accredited OEMs capture premium positioning across Germany's automotive corridor.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with IEC 62443-4-2 certification and hardware security module integration driving price differentiation. Pricing pressure stems from procurement teams unbundling hardware from integration services, compressing vendor margins on professional services. Healthcare systems exhibit lowest price sensitivity due to HIPAA compliance requirements and patient safety liability exposure, while agricultural telemetry buyers in remote regions prioritize unit economics over feature depth.
Supply Chain Analysis
China and Taiwan anchor module assembly and ARM processor fabrication, while South Korea supplies advanced memory components for 512 MB to 4 GB RAM configurations. The gateway supply chain draws from concentrated foundry capacity for multi-core ARM Cortex-A53 system-on-modules and hardware-accelerated encryption engines. Single-source vulnerability in East Asian semiconductor fabrication creates exposure to input volatility. Distribution runs through industrial distributors for edge gateway variants and enterprise VARs for cloud aggregation nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory moat story where IEC 62443-4-2 certification creates switching costs that entrench incumbents and complicate new entrant access.
For Market Incumbents: Shield market position by deepening certification depth ahead of standards revision cycles and securing exclusive distribution partnerships with systems integrators in Germany's machinery corridor. The 12-18 month validation timeline for industrial-grade gateways creates a barrier against emerging players lacking R&D scale. Vertical integration into hardware security module sourcing reduces exposure to semiconductor supply concentration. For New Entrants and Emerging Players: Differentiate on solar-powered cellular gateway designs for agricultural telemetry in Brazil and Australia's pastoral regions where grid infrastructure remains absent. Target healthcare telemetry as the most penetrable segment given accelerating procurement of bedside-to-cloud infrastructure. Pursue direct relationships with hospital procurement committees rather than competing through industrial distribution channels. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed industrial computing specialists possessing temperature-extreme credentials and established IEC certification pipelines. Long-term viability hinges on regulatory entrenchment rather than technology differentiation, favoring targets with embedded audit logging capabilities for EU AI Act compliance. Watch certification backlog duration as the inflection signal for supply-constrained pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| IEC 62443-4-2 Certification Investment | Accreditation gates access to Germany's automotive OEM approved supplier lists and commands premium pricing tiers. |
| Hardware Security Module Integration | Embedded encryption engines satisfy EU Cybersecurity Act mandates while differentiating industrial-grade edge offerings. |
| Systems Integrator Partnership | Channel capture compensates for margin compression as manufacturing buyers unbundle hardware from deployment services. |
| Agricultural Telemetry Product Line | Solar-powered cellular gateways address white space in Brazil and Australia's grid-absent pastoral regions. |
| Healthcare Compliance Service Bundle | Adjacent revenue streams emerge from embedded audit logging and local inference for EU AI Act documentation requirements. |
Methodological Framework
Initial hypotheses were tested against primary input from plant engineers at automotive OEMs, procurement leads at machinery manufacturers, hospital biomedical engineering directors, and distribution channel partners, then refined through secondary validation across SEC filings of listed networking vendors, IEC certification registry databases, EU Cybersecurity Act implementation guidance, and customs trade data for gateway module flows. Bottom-up unit economics and top-down market sizing were triangulated to constrain variance.
Variance decomposition across the projection horizon isolates volume drivers by device type, application tier, connectivity technology, and end-user procurement modality, with CAGRs derived from segment-level growth rate reconciliation. Modeled inputs include industrial automation capital expenditure patterns, hospital infrastructure procurement cycles, and cellular module adoption curves in remote asset monitoring.
Material uncertainties — semiconductor supply disruptions, IEC standards revision timing, and regulatory fragmentation between EU Cybersecurity Act and China's GB/T regimes — sit outside the modeled envelope. Forecasts reflect assumptions about certification timeline stability and procurement pattern continuity. Recalibration cycles align with material shifts in industrial digitization spending and healthcare telemetry deployment velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
IoT in Automotive Market
Internet of Things (IoT)
AI in IoT Market
Internet of Things (IoT)
Asia-Pacific Massive IoT Market
Internet of Things (IoT)
Cellular Machine to Machine Market
Internet of Things (IoT)
IoT Connected Machines Market
Internet of Things (IoT)
Wifi IoT Market
Internet of Things (IoT)
Europe IoT in Smart Cities Market
Internet of Things (IoT)
IIOT Gateway for Utility Market
Internet of Things (IoT)
Telecom Internet of Things (IoT) Market
Internet of Things (IoT)
Marine Internet of Things Market
Internet of Things (IoT)
IoT Software Engineering Market
Internet of Things (IoT)
Internet of Things in BFSI Market
Internet of Things (IoT)
IoT in Chemical Industry Market
Internet of Things (IoT)
Aviation IoT Solutions Market
Internet of Things (IoT)
IoT in Energy Market
Internet of Things (IoT)
IoT in Warehouse Management Market