
 Global Residential Smart Thermostats Market | 2026-2036
Global Residential Smart Thermostats Market Size, Share, and Industry Trends Forecast 2026-2036
Global Residential Smart Thermostats Market Outlook
EU F-Gas Regulation is consolidating the cost-of-entry calculus for smart thermostat vendors selling into European residential markets. Honeywell International leverages its building automation heritage to sustain channel control across North American retail and contractor networks. Ecobee specializes in voice-integrated learning algorithms that differentiate its hardware from commodity programmable units. Schneider Electric anchors its position through backward integration into energy management software that locks in landlord and property manager segments.
Residential smart thermostats are digitally connected climate control devices that modulate HVAC equipment through sensor-driven temperature sensing, occupancy detection, and algorithmic scheduling with typical wireless connectivity via Wi-Fi or mesh protocols like Zigbee and Z-Wave. Their primary commercial purpose is to reduce residential energy consumption while enabling remote management through mobile applications. Wi-Fi-enabled units dominate volume because broadband penetration makes zero-hub deployment cost-effective for homeowners, while learning thermostats capture disproportionate margin pools through subscription-based energy analytics. Zigbee technology leads in multi-device smart home ecosystems where landlords and property managers standardize on protocol-unified hardware to simplify fleet maintenance across rental portfolios.
FCC certification governs radio-frequency emissions for devices sold in the United States, while REACH compliance shapes material composition rules for European market access, and Japan's METI enforces Top Runner energy-efficiency standards that effectively mandate smart controls in new residential construction. These frameworks collectively elevate product testing burdens for entrants while creating compliance moats for established vendors with dedicated regulatory affairs teams. Stakeholders must monitor how building electrification mandates in multiple jurisdictions will expand addressable markets while simultaneously tightening interoperability requirements that could strand proprietary communication protocols.
Market Dynamics
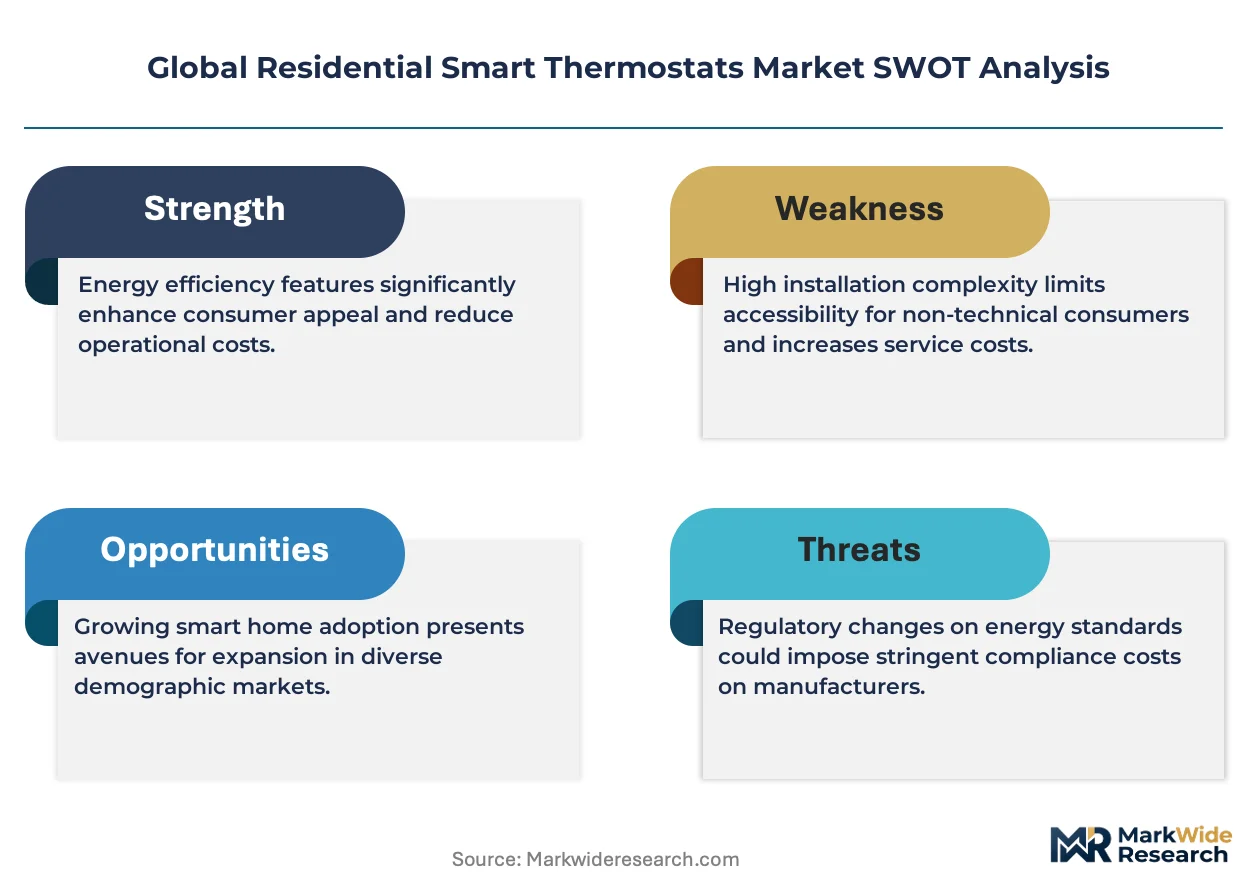
The EU F-Gas Regulation and parallel building electrification mandates across Germany, the United States, and Japan are compressing replacement cycles for legacy HVAC controls while elevating technical compliance burdens for market entrants.
Growth Catalysts
- Building decarbonization timelines:Germany's federal building energy law mandates smart heating controls in new residential construction and major renovations, creating hardware pull-through for connected thermostat vendors.
- Mesh protocol standardization:Zigbee and Z-Wave unification across multi-family property portfolios reduces landlord fleet maintenance costs and accelerates bulk procurement decisions.
- FCC Part 15 certification pathways:Streamlined radio-frequency equipment authorization for Wi-Fi-enabled devices lowers time-to-market for North American entrants relative to European REACH compliance cycles.
Market Restraints
- Semiconductor input volatility:Discrete sensor and RF module supply concentration in East Asian foundries exposes thermostat OEMs to allocation risk and component lead time extension.
- REACH substance restrictions:European material composition rules for heavy metals and flame retardants in electronics housings create formulation reformulation costs that disadvantage smaller hardware vendors.
- Hub-dependent ecosystem lock-in:Proprietary mesh protocol silos strand consumer hardware investments and suppress cross-platform switching, limiting addressable market expansion for independent thermostat brands.
Strategic Opportunities
- Japan METI Top Runner expansion:Energy-efficiency standard tightening for residential HVAC equipment creates regulatory pull-through for learning algorithm thermostats in new construction.
- Utility demand response integration:Convergence of thermostat APIs with grid-edge software platforms enables virtual power plant participation and recurring revenue streams for hardware-software bundles.
- Insurance channel embedding:Homeowner policy discounts for connected climate controls create alternative distribution paths outside traditional retail and contractor channels.
Industry Challenges
- Cybersecurity certification complexity:ETSI EN 303 645 and UL 2900 IoT security standards impose firmware audit burdens that extend product launch timelines by 6-12 months.
- Legacy HVAC interoperability:Proprietary furnace and heat pump communication protocols require thermostat vendors to maintain extensive equipment compatibility databases and field calibration support infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Residential Smart Thermostats Market |
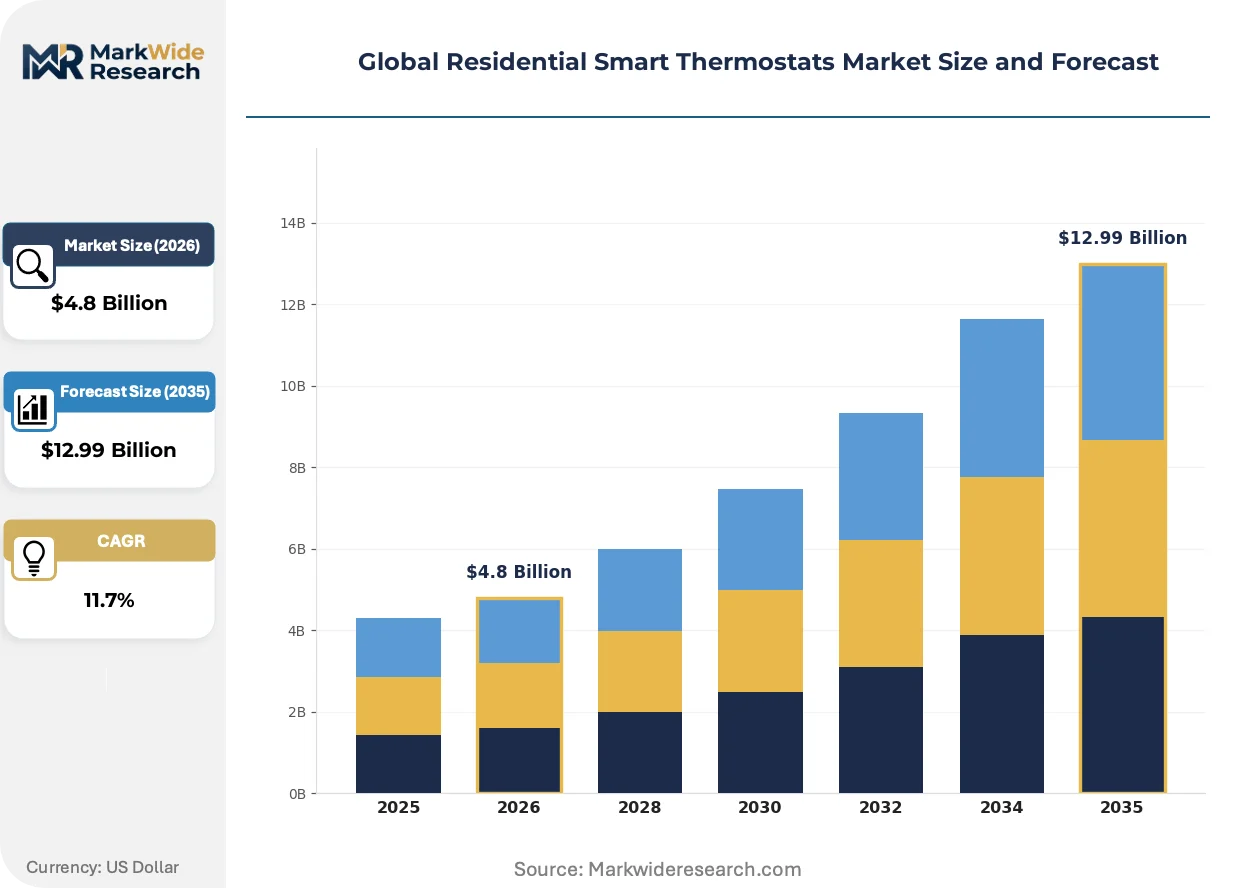
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wi-Fi, Programmable, Learning, Wired Technology: Zigbee, Z-Wave, Bluetooth, RF End User: Homeowners, Landlords, Property Managers, Tenants Distribution Channel: Online Retail, Wholesale, Direct Sales, Specialty Stores |
| Companies Covered | Alphabet (Google Nest), Honeywell International, ecobee, Emerson Electric, Johnson Controls, Resideo Technologies, Schneider Electric, Carrier Corporation, Netatmo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Residential Smart Thermostats Market Strategic Shifts
Machine learning inference at the edge is compressing cloud dependency for occupancy prediction while regulatory pressure on refrigerant and embodied carbon intensifies hardware material scrutiny.
Occupancy-sensing radar modules embedded in thermostat housings are rewriting how heating and cooling loads anticipate resident presence rather than react to schedule programming. Multi-family developers in Germany and the Netherlands specify these units for common area energy accountability. The technology is compressing payback calculations for landlord capital expenditure decisions by 30-40 percent relative to schedule-based alternatives.
REACH SVHC candidate list expansion to include additional plasticizers and flame retardants is forcing housing stock renovation projects toward thermostats with full material disclosure documentation. European property managers now require Environmental Product Declarations for fleet standardization decisions. Hardware vendors with pre-certified supply chains capture specification preference in public housing tenders.
Renter-facing mobile applications are displacing landlord-controlled building management systems as the primary interface for multi-family climate control. Property technology platforms in the United States unbundle thermostat hardware from legacy energy management software, enabling tenant direct enrollment in utility rebate programs. This channel shift concentrates procurement influence with regional utility administrators rather than traditional HVAC distributors.
Global Residential Smart Thermostats Market Segmentation
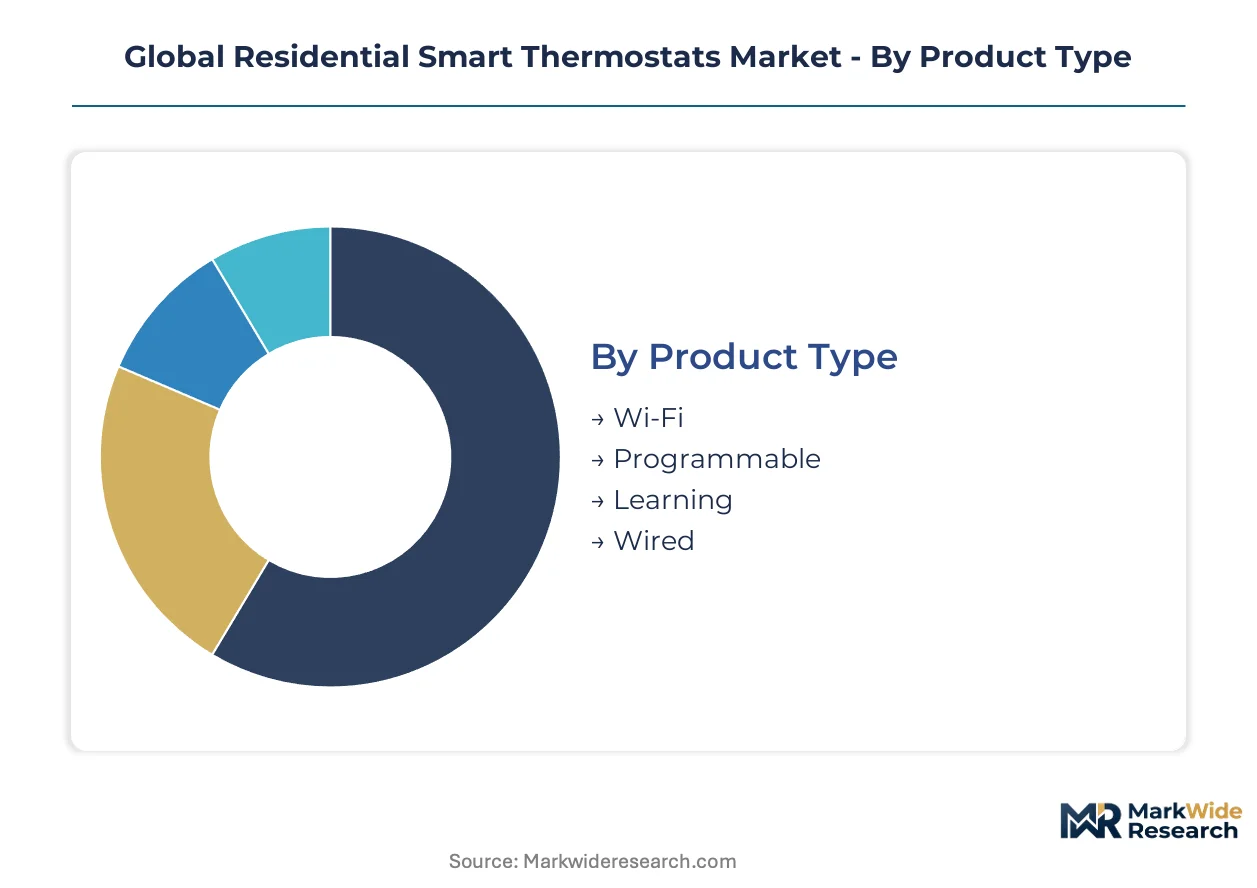
Smart thermostat segmentation reveals how hardware specifications, communication protocols, and procurement pathways fragment addressable revenue pools. Vendors must align product roadmaps with the divergent technical requirements and buying behaviors of residential end-users versus institutional property managers.
Product Type:
Supply concentration in semiconductor foundries favors manufacturers with volume scale to secure Wi-Fi and learning algorithm chip allocation.
- Wi-Fi:Broadband-enabled units connect directly to home networks without intermediary hubs, slashing deployment costs for single-family retrofits. Demand clusters in the United States where FCC Part 15 certification streamlines radio-frequency authorization for mass-market retail placement.
- Learning:Occupancy-predictive algorithms with embedded machine learning inference reduce cloud dependency while enabling subscription-based energy analytics revenue. Germany's federal building energy law mandates smart heating controls in new construction, pulling hardware with learning capabilities through regulatory compliance channels.
- Programmable:Schedule-based units with fixed temperature setbacks serve price-sensitive replacement markets and legacy HVAC system upgrades.
- Wired:Hardline power and data connections satisfy multi-family developers seeking elimination of battery maintenance across rental portfolios.
Today's leader: Wi-Fi. Tomorrow's challenger: Learning.
Technology:
Protocol selection determines ecosystem lock-in depth and fleet maintenance economics for institutional buyers managing distributed housing stock.
- Zigbee:Mesh networking with self-healing topology supports 65,000+ node deployments, enabling whole-building automation across multi-family properties. Landlords in the Netherlands standardize on Zigbee-unified hardware to simplify cross-portfolio maintenance and reduce technician dispatch frequency.
- Z-Wave:Sub-GHz spectrum penetration avoids Wi-Fi congestion in dense urban housing while delivering extended range for detached accessory dwellings. Japanese property technology platforms specify Z-Wave for METI Top Runner-compliant new construction where interference resilience matters.
- Bluetooth:Low-energy pairing enables smartphone-native configuration without dedicated hub hardware, appealing to DIY homeowner segments.
- RF:Proprietary radio-frequency implementations serve utility demand response programs requiring dedicated, non-IP communication paths for grid-edge control.
Zigbee holds institutional procurement preference. Z-Wave gains in interference-sensitive deployments.
End User:
Buying authority fragmentation between occupants and asset owners reshapes channel strategy and feature prioritization across vendor portfolios.
- Homeowners:Individual purchasers prioritize mobile application usability and voice assistant integration, driving retail placement decisions at big-box and online channels.
- Landlords:Portfolio owners demand remote diagnostics and tenant submetering compatibility to allocate heating costs and reduce capital expenditure payback periods.
- Property Managers:Third-party operators require fleet-wide firmware update capabilities and API access for integration with building management software platforms.
- Tenants:Renter-facing mobile interfaces displace landlord-controlled systems, concentrating influence with utility rebate program administrators rather than HVAC distributors.
Landlords control bulk procurement volume. Tenants are gaining specification influence through utility channel shifts.
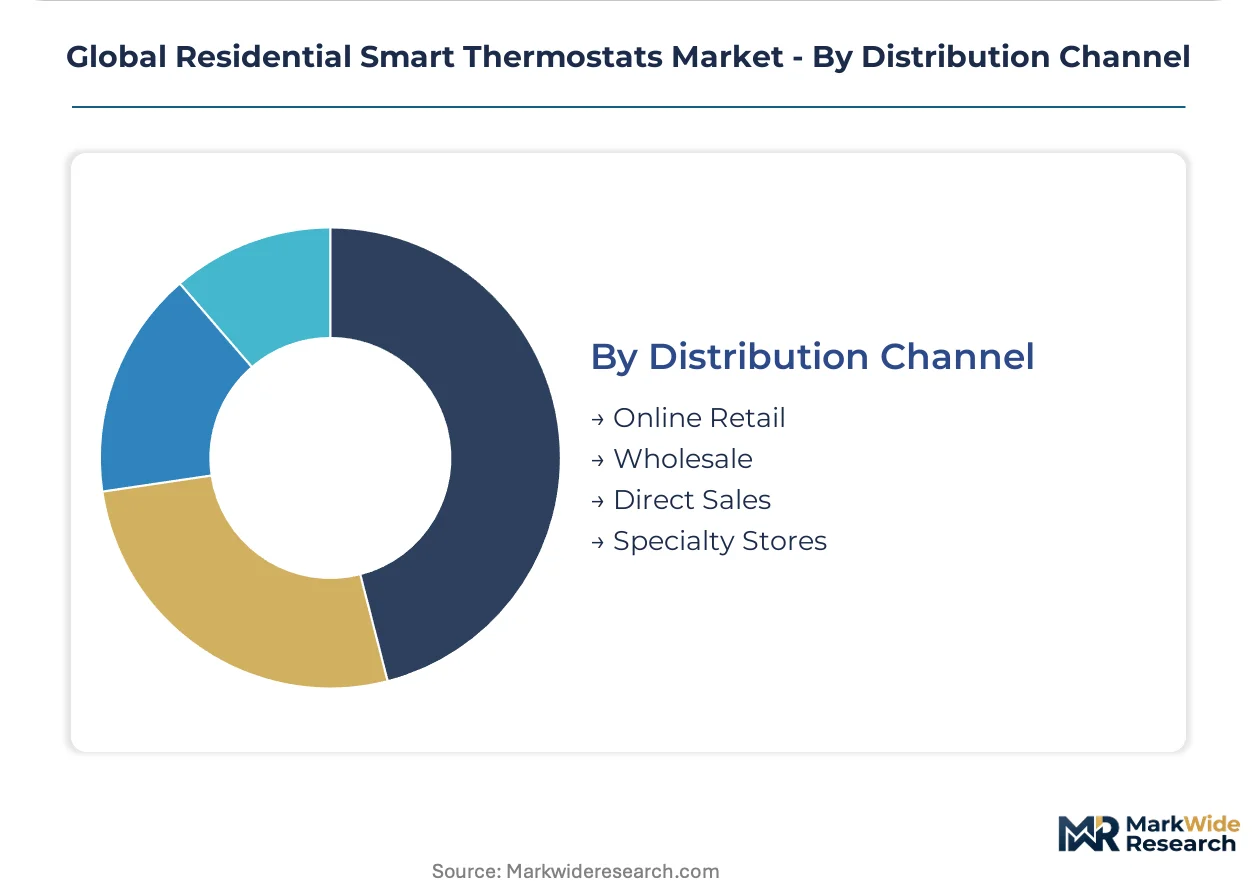
Distribution Channel:
Channel mix determines margin capture and customer acquisition cost structures for hardware-software bundle economics.
- Online Retail:E-commerce platforms enable direct-to-consumer learning thermostat sales with subscription attachment for energy analytics services.
- Wholesale:HVAC contractor networks dominate replacement cycle capture in North American residential markets where professional installation maintains warranty validity.
- Direct Sales:Utility and insurance channel embedding creates alternative paths outside traditional retail, leveraging policy discounts for connected climate controls.
- Specialty Stores:Smart home focused retailers serve early adopter segments seeking ecosystem compatibility verification before purchase commitment.
Wholesale retains installation-tied volume. Direct sales through utility channels represents the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The residential smart thermostat industry traces its commercial roots to North American energy efficiency programs of the early 2000s, where utility demand response pilots first validated connected HVAC controls at scale. From this foundation, hardware deployment patterns now diverge across regulatory jurisdictions with distinct building decarbonization enforcement timelines.
United States
FCC Part 15 certification streamlines radio-frequency authorization for Wi-Fi-enabled thermostats, accelerating retail placement cycles relative to European compliance pathways. The Inflation Reduction Act channels homeowner tax credits toward connected climate controls in retrofit applications. Texas and California utility territories concentrate bulk procurement decisions through virtual power plant enrollment programs.
Germany
The federal building energy law mandates smart heating controls in new residential construction and major renovations, creating hardware pull-through for connected thermostat vendors. The EU F-Gas Regulation tightens refrigerant phase-down schedules that indirectly elevate HVAC control sophistication requirements. The Rhine-Ruhr metropolitan corridor anchors multi-family developer standardization on Zigbee-unified hardware for portfolio-wide fleet maintenance.
Japan
METI Top Runner energy-efficiency standards for residential HVAC equipment mandate smart controls in new construction, compressing replacement cycles for legacy programmable units. The country's building energy conservation law tightens performance benchmarks for heating and cooling systems in commercial and residential applications. The Kanto region surrounding Tokyo concentrates property technology platform deployment of Z-Wave hardware for interference resilience in dense urban housing.
Netherlands
Multi-family landlords standardize on Zigbee mesh protocol hardware to simplify cross-portfolio maintenance and reduce technician dispatch frequency across rental portfolios. The EU Green Deal building renovation wave channels public housing capital expenditure toward thermostats with Environmental Product Declaration documentation. The Randstad conurbation drives specification preference for occupancy-sensing radar modules in common area energy accountability applications.
China
Dual carbon goals accelerate building electrification mandates in tier-one cities, expanding addressable markets for connected thermostat hardware. MIIT enforces cybersecurity certification for IoT devices that extends product launch timelines but creates compliance moats for established vendors. The Yangtze River Delta manufacturing cluster concentrates semiconductor foundry capacity for RF module and sensor component supply.
Global Residential Smart Thermostats Market Competitive Environment
The competitive structure tilts toward diversified industrial conglomerates with building automation heritage and specialized smart home pure-plays with voice integration capabilities. Market concentration remains moderate, with established HVAC controls vendors defending channel relationships against technology entrants from adjacent consumer electronics sectors. Two strategic archetypes dominate: legacy building automation suppliers leveraging contractor network lock-in, and algorithm-focused specialists capturing subscription-based energy analytics revenue. Competitive moves center on utility channel embedding for demand response program participation and insurance policy discount partnerships for alternative distribution paths.
Among North American technology platforms, Alphabet (Google Nest) and ecobee exemplify the voice-integrated learning algorithm archetype that differentiates hardware from commodity programmable alternatives. Honeywell International anchors the legacy building automation tier, representing diversified industrial conglomerates with sustained channel control across retail and contractor networks. These three companies occupy positions that illustrate the market's bifurcation between consumer-facing smart home ecosystems and professionally installed HVAC controls.
| Leading Market Players |
|---|
| Alphabet (Google Nest) |
| Honeywell International |
| ecobee |
| Emerson Electric |
| Johnson Controls |
| Resideo Technologies |
| Schneider Electric |
| Carrier Corporation |
| Netatmo |
| Others |
Value Chain & Pricing Dynamics
Silicon wafer spot indices and discrete sensor commodity benchmarks cascade through thermostat manufacturing tiers, compressing margins on Wi-Fi-enabled units while learning algorithm variants sustain subscription-anchored pricing power across German and Japanese regulatory compliance channels.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by certification grade and algorithm sophistication. Premium tiers attach energy analytics subscriptions and carry UL 2900 cybersecurity certification, while economy units compete on FCC Part 15 compliance alone. Cost compression in the standard tier intensifies as Zigbee chip allocation tightens, with landlords exhibiting lowest price sensitivity due to fleet-scale procurement and tenants showing highest sensitivity in retail replacement cycles.
Supply Chain Analysis
Dual-sourcing requirements for RF modules and occupancy sensors now dominate procurement qualification protocols across North American and European thermostat OEMs. Semiconductor fabrication concentrates in Taiwan, South Korea, and the Yangtze River Delta manufacturing cluster, with MEMS sensor supply drawing from Japanese and German specialty foundries. Single-source vulnerability in Zigbee system-on-chip supply creates allocation risk, while distribution runs through HVAC contractor networks in North America and direct utility channel embedding in German and Dutch markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The residential smart thermostat market functions as a stable compounder, with building electrification mandates across Germany, the United States, and Japan delivering regulatory-anchored replacement demand.
For Market Incumbents: To counter proprietary mesh protocol silos that strand consumer hardware investments, deepen backward integration into energy management software platforms and expand API interoperability certification. Channel control through contractor network lock-in remains essential, but utility direct enrollment portals threaten this position. For New Entrants and Emerging Players: Begin with insurance channel embedding for homeowner policy discount programs, the most penetrable white-space target outside traditional retail and contractor networks. Target Z-Wave hardware specifications for Japanese METI Top Runner-compliant new construction where interference resilience differentiates technical bids. For Investors and Strategic Acquirers: Asymmetric upside sits with algorithm-focused specialists capturing recurring energy analytics revenue rather than commodity hardware vendors. The five-to-ten-year viability window favors acquisition targets with pre-certified REACH supply chains and landlord-facing fleet management software. Watch for ETSI EN 303 645 cybersecurity certification completion rates as an inflection indicator for European market access velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Utility Demand Response Integration | Convergence with grid-edge software platforms enables virtual power plant participation in Texas and California territories. |
| REACH Supply Chain Certification | Pre-certified material disclosure documentation captures specification preference in EU Green Deal building renovation tenders. |
| Edge Machine Learning Deployment | On-device inference reduces cloud dependency while satisfying Japan METI energy-efficiency performance benchmarks. |
| Insurance Channel Partnership | Homeowner policy discounts for connected climate controls create alternative distribution paths outside retail and contractor networks. |
| Multi-Protocol Hardware Unification | Zigbee-Z-Wave dual-stack compatibility reduces landlord fleet maintenance costs across mixed-vintage property portfolios. |
Study Parameters
Bottom-up residential end-use modeling reconciled against top-down semiconductor supply-side tracking forms the analytical core of this study. Primary interviews with HVAC controls product managers, multi-family property technology directors, utility demand response program administrators, and regulatory affairs specialists at thermostat OEMs combined with secondary validation from FCC equipment authorization databases, ECHA REACH registration dossiers, METI Top Runner compliance filings, and utility rebate program enrollment records. Triangulation across these sources calibrated installation volume estimates against component shipment data.
Input-output matrices map Wi-Fi, Zigbee, Z-Wave, and learning algorithm unit volumes across homeowner, landlord, property manager, and tenant end-user segments throughout the projection horizon. Modeled dimensions include communication protocol, product type, procurement channel, and regional regulatory framework cluster. CAGRs derive from regression analysis of historical replacement cycle compression against building code adoption curves, with forecast sensitivity tested against semiconductor foundry capacity expansion announcements and EU F-Gas Regulation phase-down schedules.
Several conditions sit outside the modeled scope, including abrupt changes to Inflation Reduction Act tax credit eligibility, forced divestiture of smart home platform assets under antitrust action, and geopolitical disruption to Taiwan Strait semiconductor logistics. Deviation in Zigbee chip allocation priority or REACH SVHC list expansion timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Europe IoT Device Market
Internet of Things (IoT)
Global IoT Elevators Market
Internet of Things (IoT)
Iot-Enabled Devices Market
Internet of Things (IoT)
Wi-Fi Smart Scale Market
Internet of Things (IoT)
Smart Sprinkler Controller Market
Internet of Things (IoT)
South Africa IoT Market
Internet of Things (IoT)
Global Open IoT Platform Market
Internet of Things (IoT)
Mobile-Connecting Smart Objects Market
Internet of Things (IoT)
Europe IoT Services Market
Internet of Things (IoT)
Consumer Internet of Things (IoT) Market
Internet of Things (IoT)
Location of Things Market
Internet of Things (IoT)
Marine Internet of Things Market
Internet of Things (IoT)
North America Internet of Things Devices Market
Internet of Things (IoT)
IoT Infrastructure Market
Internet of Things (IoT)
Internet of Things (IoT) in Utilities Market
Internet of Things (IoT)
Connected IoT Devices Market