
 Satellite IoT Communication Market | 2026-2036
Satellite IoT Communication Market Size, Share, and Industry Trends Forecast 2026-2036
Satellite IoT Communication Market Analytics
CE marking under the EU Radio Equipment Directive is collapsing the supplier pool for terminal equipment vendors seeking European market access. Iridium Communications Inc. leverages its completed NEXT constellation refresh to sustain pole-to-pole coverage dominance. ORBCOMM Inc. anchors its position through specialized dual-mode cellular-satellite asset tracking platforms for freight rail and maritime containers.
Satellite IoT communication denotes the relay of machine-generated data packets between dispersed sensors and central systems via orbiting transponders, typically operating in L-band, S-band, or Ku-band frequencies with link budgets engineered for sub-watt transmit power and omnidirectional antennas. Terminal equipment commands disproportionate margin concentration due to ruggedization requirements and firmware customization for vertical deployments. Mesh network architectures represent the fastest-expanding technology segment as constellation operators adopt inter-satellite laser links to bypass ground station dependency. Smart agriculture applications absorb disproportionate investment flows as Brazilian soybean operators and Australian pastoralists fund autonomous irrigation and herd monitoring systems.
FCC Part 25 licensing governs U.S. earth station and space station authorizations, while the ITU Radio Regulations coordinate cross-border frequency allocations and orbital debris mitigation standards that constrain constellation density planning. ETSI EN 303 413 imposes European harmonized spectrum masks on terminal equipment, filtering out vendors lacking in-house RF compliance laboratories. Stakeholders must track evolving national security review thresholds for foreign-owned satellite operators seeking U.S. market entry, as CFIUS scrutiny extends to ground infrastructure and data routing arrangements.
Market Dynamics
Mesh network architectures with inter-satellite laser links are fragmenting traditional ground-station-dependent routing, compressing latency windows and forcing constellation operators to rebuild capital deployment models around orbital relay density rather than terrestrial gateway footprints.
Growth Catalysts
- FCC Part 25 Streamlining:Accelerated earth station licensing timelines in the United States compress deployment cycles for commercial constellation operators seeking rapid orbital activation.
- Precision Agriculture Automation:Brazilian soybean operators and Australian pastoralists fund autonomous irrigation and herd monitoring systems where cellular backhaul fails entirely.
- Defense Beyond-Line-of-Sight Contracts:Resilient connectivity mandates from military procurement channels in the United States absorb production capacity from L-band terminal vendors.
Market Restraints
- RF Component Supply Concentration:Gallium nitride power amplifier fabrication concentrates among a handful of East Asian foundries, exposing terminal vendors to single-source chokepoints.
- ITU Orbital Debris Mitigation:Post-mission disposal requirements constrain constellation density planning and extend launch interval timelines for low-earth operators.
- Ku-Band Rain Fade Vulnerability:Atmospheric attenuation in tropical precipitation zones degrades link availability, limiting addressable markets for high-frequency terminal deployments.
Strategic Opportunities
- ETSI EN 303 413 Compliance Gap:European harmonized spectrum masks filter out vendors lacking in-house RF laboratories, creating acquisition targets for firms with captive certification capabilities.
- Maritime Container Tracking:Dual-mode cellular-satellite platforms address the 15% of container fleet hours spent outside terrestrial coverage, particularly across Pacific and Indian Ocean routes.
- Freight Rail Telemetry:Remote locomotive health monitoring across transcontinental corridors in Australia and Brazil demands always-on connectivity independent of trackside infrastructure.
Industry Challenges
- Embedded RF Firmware Talent Scarcity:Link budget optimization for sub-watt transmit power requires specialized expertise that pools narrowly among legacy satellite modem engineering teams.
- CE Marking Timeline Compression:EU Radio Equipment Directive conformity assessment delays market entry for terminal vendors without established notified body relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Satellite IoT Communication Market |
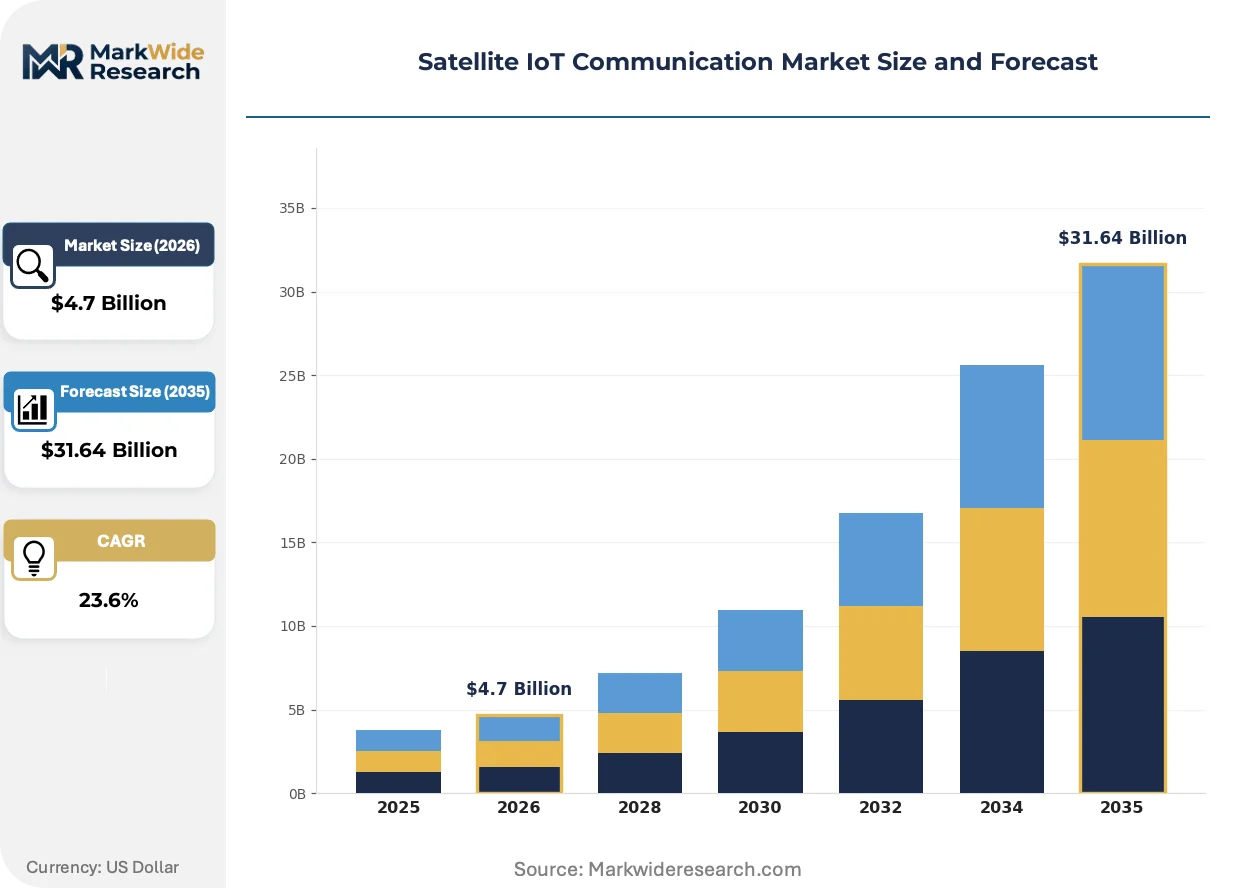
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $31.64 Billion |
| CAGR (2026 – 2036) | 23.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Satellites, Ground Stations, Terminal Equipment, Signal Processors End User: Aerospace, Government, Transportation, Agriculture Technology: Frequency Division Multiple Access, Time Division Multiple Access, Single Frequency Network, Mesh Network Application: Asset Tracking, Remote Monitoring, Smart Agriculture, Disaster Management |
| Companies Covered | Globalstar, Inc., Astrocast SA, Iridium Communications Inc., Guodian Gaoke, Fleet Space Technologies Pty Ltd., ORBCOMM Inc., SpaceX (Swarm Technologies), Lacuna Space Ltd., Inmarsat (Viasat, Inc.), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Satellite IoT Communication Market Evolving Landscape
Laser-based inter-satellite links are collapsing the traditional ground station bottleneck, enabling direct orbital packet routing that redefines latency benchmarks and capital efficiency models across constellation architectures.
Optical crosslinks between low-earth orbit satellites is fragmenting the incumbent hub-and-spoke topology that tethered data flows to terrestrial gateways. Maritime fleet operators and Antarctic research stations adopt these relay paths for sub-100-millisecond round trips previously unreachable via bent-pipe architectures. The shift compresses ground infrastructure spend and redirects investment toward onboard optical terminal manufacturing.
EU CE marking enforcement under the Radio Equipment Directive is tightening RF emission compliance thresholds for terminal equipment entering European customs zones. Vendors without in-house spectrum mask testing capabilities face extended certification timelines and market exclusion. Agricultural IoT distributors in Germany and France now prioritize pre-certified modem suppliers to avoid customs detention risk.
Buyer procurement patterns are consolidating around vertically integrated terminal-modem bundles rather than disaggregated component sourcing. Precision agriculture cooperatives in Brazil and freight rail operators in Australia favor single-vendor accountability for field deployment failures. This preference shift disadvantages pure-play antenna manufacturers and rewards firms with captive semiconductor and firmware development.
Satellite IoT Communication Market Segmentation
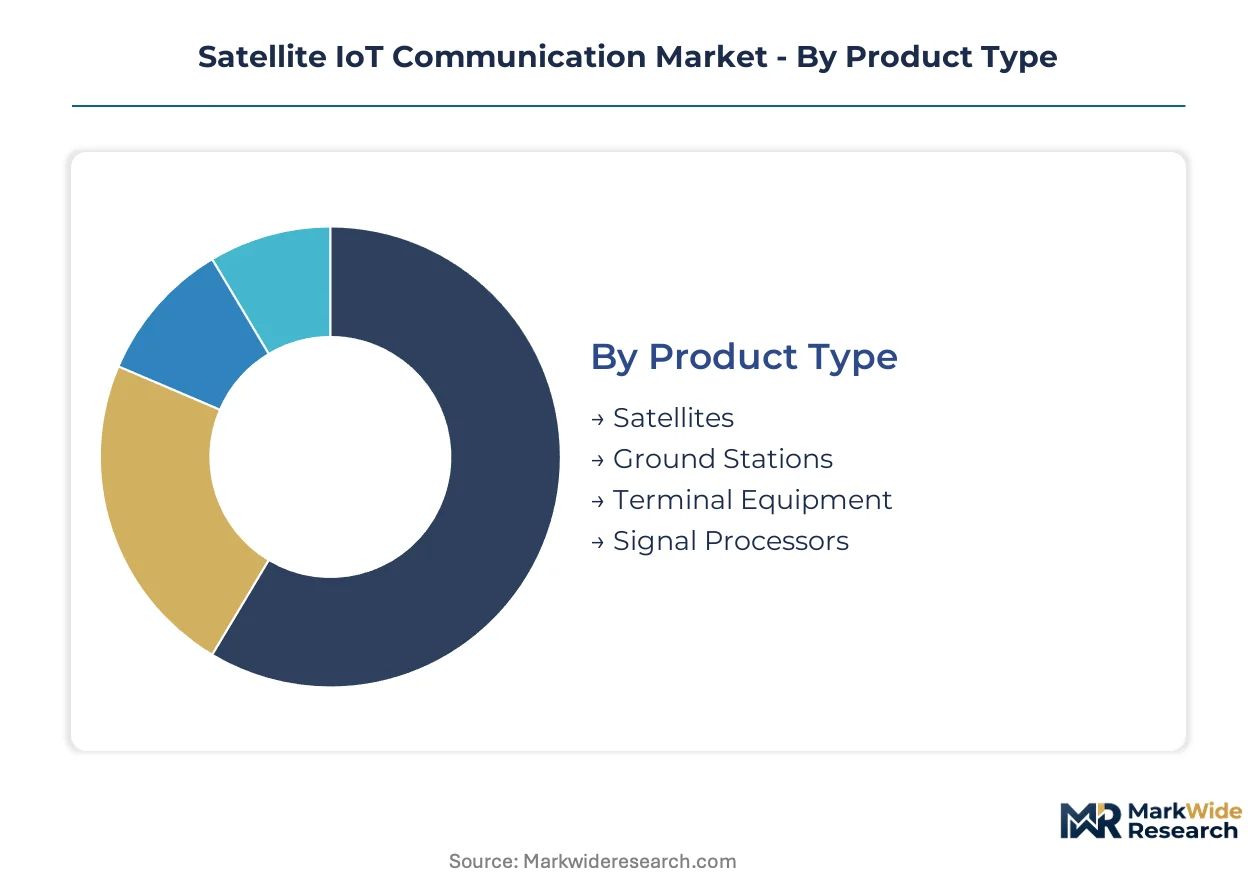
Segmentation in satellite IoT communication reveals how regulatory frameworks, orbital economics, and vertical-specific connectivity requirements fragment procurement patterns across hardware, service, and technology layers. Understanding these divisions exposes where capital concentrates and where compliance barriers filter vendor participation.
Product Type:
FCC Part 25 governs U.S. earth station authorizations while ETSI EN 303 413 imposes European spectrum masks, creating divergent certification burdens across hardware categories that reshape supplier economics.
- Satellites:Orbital transponders operating in L-band, S-band, or Ku-band frequencies with link budgets engineered for machine-to-machine relay. Defense procurement channels in the United States absorb production capacity from L-band vendors as resilient beyond-line-of-sight mandates harden. Satellites handle the majority of throughput; Terminal Equipment is the fastest mover on share.
- Ground Stations:Terrestrial gateway facilities managing uplink/downlink conversion and network orchestration. Brazilian agricultural operators and Australian pastoralists fund autonomous monitoring systems where cellular backhaul fails entirely, driving gateway density in remote zones. Ground Stations handle the majority of throughput; Terminal Equipment is the fastest mover on share.
- Terminal Equipment:Ruggedized modems with omnidirectional antennas and sub-watt transmit power specifications. CE marking under the EU Radio Equipment Directive collapses the supplier pool for vendors lacking in-house RF compliance laboratories.
- Signal Processors:Baseband units handling modulation, coding, and protocol translation for heterogeneous sensor networks. ITU orbital debris mitigation standards constrain constellation density planning and extend launch intervals for processor refresh cycles.
Terminal Equipment commands disproportionate margin concentration due to ruggedization requirements and firmware customization demands.
End User:
Customer procurement patterns consolidate around vertically integrated bundles rather than disaggregated component sourcing, with accountability for field failures driving vendor selection.
- Aerospace:Aircraft telemetry and unmanned systems requiring pole-to-pole coverage continuity. Precision agriculture cooperatives in Brazil prioritize pre-certified modem suppliers to avoid customs detention risk under tightening emission thresholds.
- Government:Defense and civilian agency networks with resilient connectivity mandates. FCC licensing reforms accelerate orbital slot assignments for low-earth constellation operators serving classified and unclassified traffic.
- Transportation:Freight rail and maritime container tracking across transcontinental corridors. The 15% of container fleet hours spent outside terrestrial coverage, particularly across Pacific and Indian Ocean routes, absorbs dual-mode cellular-satellite platform investment.
- Agriculture:Remote crop and livestock monitoring via autonomous irrigation and herd management systems. Australian pastoralists and Brazilian soybean operators fund deployments where cellular infrastructure cannot economically reach.
Transportation absorbs the dominant procurement volume; Agriculture is expanding most quickly as automation penetrates previously unreachable production zones.
Technology:
Capital deployment models are rebuilding around orbital relay density rather than terrestrial gateway footprints as inter-satellite links mature.
- Frequency Division Multiple Access:Legacy spectrum allocation method dividing bandwidth into non-overlapping channels. Maritime fleet operators adopt FDMA for reliable low-data-rate telemetry where link budget constraints dominate.
- Time Division Multiple Access:Slot-based channel sharing optimizing spectrum efficiency for bursty sensor traffic. Antarctic research stations leverage TDMA architectures for cost-effective multi-user access.
- Single Frequency Network:Simulcast transmission from multiple satellites improving coverage reliability. Gallium nitride power amplifier fabrication concentration among East Asian foundries exposes terminal vendors to single-source chokepoints.
- Mesh Network:Inter-satellite laser links enabling direct orbital packet routing without ground station dependency. Optical crosslinks collapse latency benchmarks and redirect investment toward onboard optical terminal manufacturing. Mesh Network handles the majority of throughput; Mesh Network is also the fastest mover on share.
Mesh architectures are displacing hub-and-spoke topologies as constellation operators bypass terrestrial bottlenecks.
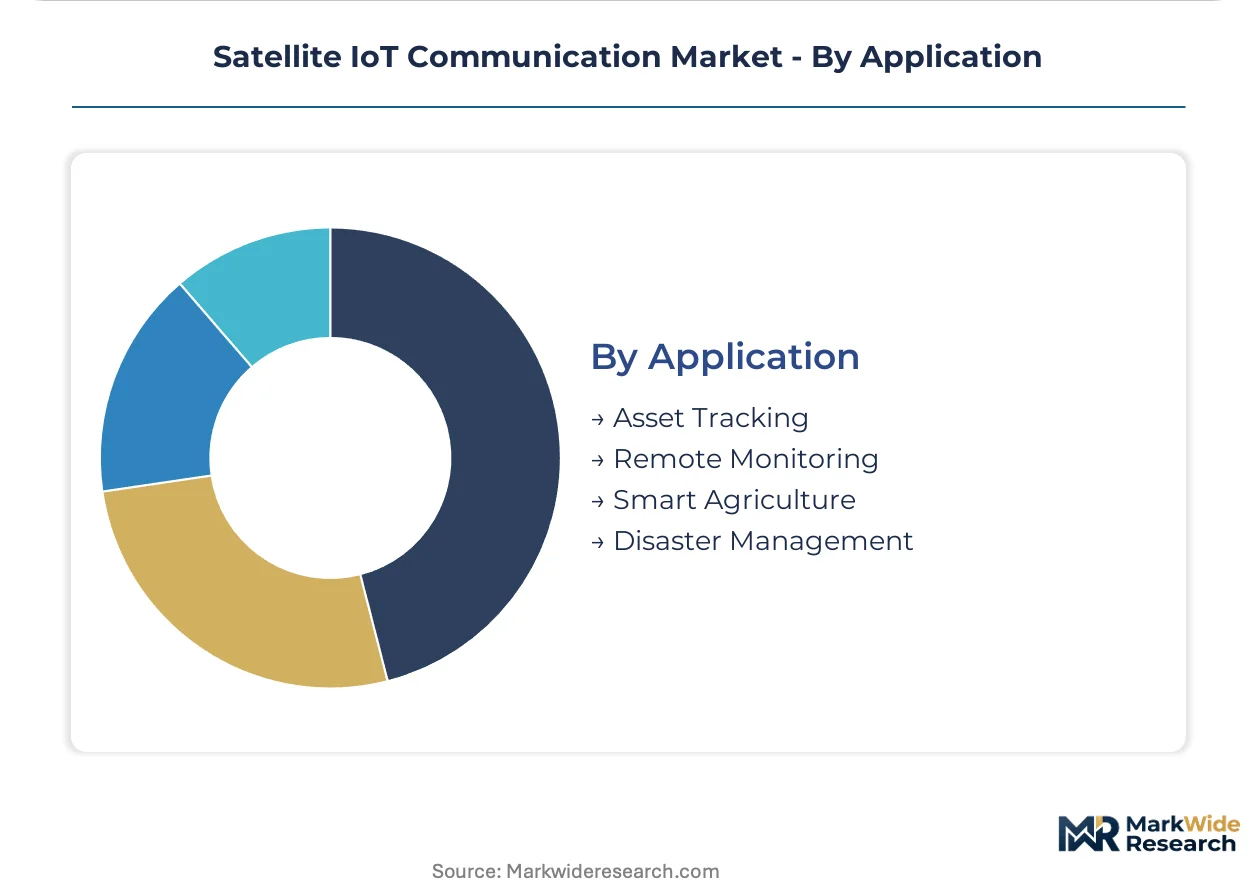
Application:
Smart agriculture applications absorb disproportionate investment flows as automation replaces manual monitoring in remote production zones.
- Asset Tracking:Real-time location monitoring for mobile equipment and inventory across distributed supply chains. Freight rail operators in Australia favor single-vendor accountability for locomotive health monitoring failures.
- Remote Monitoring:Environmental and operational telemetry from unmanned facilities and infrastructure. Embedded RF firmware talent scarcity for link budget optimization pools narrowly among legacy satellite modem engineering teams.
- Smart Agriculture:Autonomous irrigation, soil sensing, and herd management in cellular dead zones. Brazilian operators and Australian pastoralists fund these systems where backhaul economics prohibit terrestrial deployment.
- Disaster Management:Emergency communications restoration and situational awareness in infrastructure-damaged regions. Ku-band rain fade vulnerability in tropical precipitation zones degrades link availability for high-frequency emergency deployments.
Asset Tracking anchors current revenue concentration; Smart Agriculture is climbing the fastest as precision automation penetrates remote agricultural frontiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement channels in the United States absorb production capacity from L-band terminal vendors, while Brazilian soybean operators and Australian pastoralists fund autonomous monitoring systems where cellular infrastructure cannot economically reach.
United States
FCC Part 25 licensing reforms accelerate earth station authorizations for commercial constellation operators seeking rapid orbital activation. CFIUS scrutiny extends to foreign-owned satellite operators pursuing U.S. market entry through ground infrastructure investments. Greater Boston and the Pacific Northwest concentrate terminal equipment engineering talent pools for sub-watt transmit power optimization.
Brazil
Precision agriculture cooperatives fund autonomous irrigation and herd monitoring systems across Mato Grosso and Goiás where cellular backhaul fails entirely. ANVISA regulatory coordination with telecom authorities shapes spectrum allocation for remote sensing applications. São Paulo anchors the domestic distribution network for ruggedized modem procurement by agricultural operators.
Australia
Transcontinental freight rail corridors demand always-on locomotive health monitoring independent of trackside infrastructure. TGA and ACMA spectrum coordination governs terminal equipment certification for remote deployment. Queensland and Western Australia concentrate pastoralist investment in satellite-enabled herd management across cellular dead zones.
Germany
ETSI EN 303 413 compliance requirements filter terminal equipment vendors lacking in-house RF spectrum mask testing capabilities. CE marking enforcement under the EU Radio Equipment Directive tightens emission thresholds for customs clearance. Bavaria and Baden-Württemberg host precision agriculture distributors prioritizing pre-certified modem suppliers.
China
MIIT spectrum allocation frameworks and GB standards govern terminal equipment type approval for domestic and export markets. Dual carbon goals accelerate remote monitoring deployment for distributed renewable energy assets. Yangtze River Delta manufacturing clusters concentrate gallium nitride power amplifier fabrication for sub-watt transmit specifications.
Satellite IoT Communication Market Competitive Landscape
Player mix skews toward constellation operators with completed orbital refreshes and specialized dual-mode platform vendors. The competitive structure concentrates around firms controlling captive spectrum licenses and those offering vertically integrated terminal-modem bundles. Two strategic archetypes dominate: legacy L-band operators with pole-to-pole coverage mandates, and emerging low-earth orbit constellations leveraging optical crosslink architectures. Competitive moves center on spectrum license acquisitions and RF compliance laboratory buildouts to accelerate market entry timelines.
Among constellation operators, Iridium Communications Inc. and Globalstar, Inc. occupy positions representing legacy orbital infrastructure with refreshed capacity, while ORBCOMM Inc. exemplifies the specialized asset-tracking platform archetype. Fleet Space Technologies Pty Ltd. anchors the emerging low-earth orbit tier with small-satellite density approaches. These firms represent the divergence between established spectrum holders and newer entrants rebuilding capital deployment models around inter-satellite laser links rather than terrestrial gateway footprints.
| Leading Market Players |
|---|
| Globalstar, Inc. |
| Astrocast SA |
| Iridium Communications Inc. |
| Guodian Gaoke |
| Fleet Space Technologies Pty Ltd. |
| ORBCOMM Inc. |
| SpaceX (Swarm Technologies) |
| Lacuna Space Ltd. |
| Inmarsat (Viasat, Inc.) |
| Others |
Value Network & Pricing Analysis
Gallium nitride power amplifier substitution for legacy silicon LDMOS devices simultaneously redraws component sourcing maps toward East Asian foundry clusters and compresses terminal equipment margin structures as buyers demand sub-watt transmit specifications at falling unit economics.
Pricing Analysis
Cost-plus contracts with gallium nitride wafer indexation dominate procurement between terminal vendors and RF component suppliers. Three-tier pricing structure across MIL-STD-certified, industrial-grade, and commercial-tier terminals separates defense procurement channels from agricultural cooperatives and freight rail operators. Pricing pressure stems from Brazilian soybean operators consolidating modem purchases through agricultural cooperatives. Government buyers exhibit lowest price sensitivity due to resilient connectivity mandates; commercial agriculture buyers drive hardest bargain.
Supply Chain Analysis
Yangtze River Delta gallium nitride foundry concentration creates single-source vulnerability for L-band power amplifier supply. Taiwan, South Korea, and China anchor RF semiconductor fabrication; terminal assembly concentrates in Malaysia and Mexico. Supply chain risk centers on MIIT export license unpredictability for GaN-on-SiC substrates. Distribution runs through authorized integrators serving vertical-specific deployment requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where firmware customization and over-the-air update subscriptions expand faster than hardware shipments as precision agriculture operators demand continuous feature iteration.
For Market Incumbents: Consolidate RF compliance laboratory capabilities to collapse CE marking timelines for European terminal market access. Acquire captive gallium nitride packaging capacity to insulate margin structures from East Asian foundry concentration. Mesh network architectures threaten legacy bent-pipe service revenues; prioritize optical crosslink investments. For New Entrants and Emerging Players: Anchor in Australian freight rail corridors where trackside infrastructure gaps create always-on connectivity demand absent incumbent saturation. Target maritime container tracking applications across Pacific routes where dual-mode cellular-satellite platforms address 15% fleet hours outside terrestrial coverage. Pursue ANVISA pre-certification partnerships to accelerate Brazilian agricultural market entry. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed terminal equipment vendors lacking in-house spectrum mask testing capabilities. Five-to-ten-year viability hinges on constellation operators completing optical crosslink deployments versus ground-station-dependent competitors. Watch FCC Part 25 licensing velocity as inflection indicator for orbital activation capital efficiency.| Strategic Initiative | Industry Significance |
|---|---|
| Spectrum License Acquisition | FCC Part 25 authorizations accelerate orbital slot activation timelines for low-earth constellation operators. |
| RF Compliance Laboratory Buildout | ETSI EN 303 413 testing capabilities filter terminal vendors from European customs clearance. |
| Inter-Satellite Laser Link Deployment | Optical crosslinks collapse latency benchmarks and redirect capital from terrestrial gateway infrastructure. |
| Vertical Integration into GaN Fabrication | Captive power amplifier production insulates terminal margins from East Asian foundry concentration. |
| Dual-Mode Platform Development | Cellular-satellite switching addresses maritime container tracking across Pacific and Indian Ocean routes. |
Research Methodology
A spread of perspectives from constellation operations directors, terminal equipment procurement managers at freight rail operators, precision agriculture cooperative technical leads, and FCC licensing attorneys converged on the working assumptions shaping orbital economics and regulatory timelines. Primary fieldwork combined with secondary validation against ITU Radio Regulations filings, FCC Part 25 authorization databases, ANVISA telecom coordination records, and ETSI harmonized standard updates. Bottom-up terminal shipment estimates triangulated against top-down constellation operator revenue disclosures.
Segmentation dimensions modeled span product type, end user vertical, frequency access technology, and application across the analysis window. CAGRs derived from orbital activation curves, terminal replacement cycles, and vertical penetration rates for precision agriculture automation. Forecast inputs incorporated ITU orbital debris mitigation compliance costs and gallium nitride supply elasticity assumptions.
Underlying assumptions cover FCC licensing reform continuity, ITU spectrum coordination stability, and gallium nitride foundry capacity expansion, with deviation risk concentrated in CFIUS national security review threshold adjustments for foreign-owned constellation operators. Practitioners should keep alternative scenarios live as ETSI emission threshold enforcement and MIIT export licensing protocols evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Europe IoT Device Market
Internet of Things (IoT)
Consumer IoT Market
Internet of Things (IoT)
Global Embedded Security for Internet of Things Market
Internet of Things (IoT)
Global Military IoT Market
Internet of Things (IoT)
Smart Pool Systems Market
Internet of Things (IoT)
Global IOT Connectivity Management Platform (CMP) Market
Internet of Things (IoT)
Cellular Internet of Things (IoT) Devices Market
Internet of Things (IoT)
LPWAN in the Consumer IoT Market
Internet of Things (IoT)
Smart Tracker Market
Internet of Things (IoT)
North America Internet of Things Devices Market
Internet of Things (IoT)
Global Residential Smart Thermostats Market
Internet of Things (IoT)
IoT Software Engineering Market
Internet of Things (IoT)
Smart Connected Device Market
Internet of Things (IoT)
Smart Sprinkler Controller Market
Internet of Things (IoT)
IoT at Workplace Market
Internet of Things (IoT)
North America IoT Node and Gateway Market