
 Global Artificial Intelligence (AI) in Food and Beverages Market | 2026-2036
Global Artificial Intelligence (AI) in Food and Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Global Artificial Intelligence (AI) in Food and Beverages Market Intelligence
China's rapid expansion of smart food processing facilities is narrowing the technology gap with established markets in North America and Europe. Siemens AG leverages its extensive industrial automation portfolio to integrate AI across entire production lines, from processing to packaging. Concurrently, TOMRA Systems ASA specializes in advanced sensor-based sorting for granular quality control, while IBM Corporation provides the cloud-based machine learning platforms necessary for large-scale consumer analytics.
Artificial Intelligence in food and beverages applies computational models, such as machine learning, to data from production, processing, and distribution. These systems often utilize computer vision with deep learning algorithms for tasks like automated quality inspection, identifying defects smaller than a millimeter. Quality control and supply chain optimization represent the largest application segments by investment. While cloud-based deployments offer scalability for large-scale data analytics, edge computing is gaining traction for real-time processing on the factory floor.
Regulatory frameworks create significant incentives for AI adoption. The U.S. FDA's Food Safety Modernization Act (FSMA) drives demand for AI-powered traceability and compliance documentation. In parallel, Europe's GDPR places constraints on how consumer data is used for behavior analytics. The critical decision for operators involves balancing investments in predictive maintenance against the immediate returns from quality control systems.
Market Dynamics
The convergence of stringent food safety regulations, such as the U.S. FDA's Food Safety Modernization Act, and the proliferation of edge computing for real-time factory floor data processing represents the central force shaping AI adoption in the food and beverage industry.
Growth Catalysts
- Regulatory Mandates:The U.S. FDA's Food Safety Modernization Act (FSMA) directly incentivizes the adoption of AI-powered traceability systems to meet stringent documentation and compliance requirements.
- Computer Vision Maturation:Advances in deep learning allow computer vision to automate quality control, identifying microscopic defects on production lines and reducing food waste.
- Demand Concentration in China:National initiatives in China focused on food safety and manufacturing efficiency are creating significant, concentrated demand for AI systems in food processing facilities.
Market Restraints
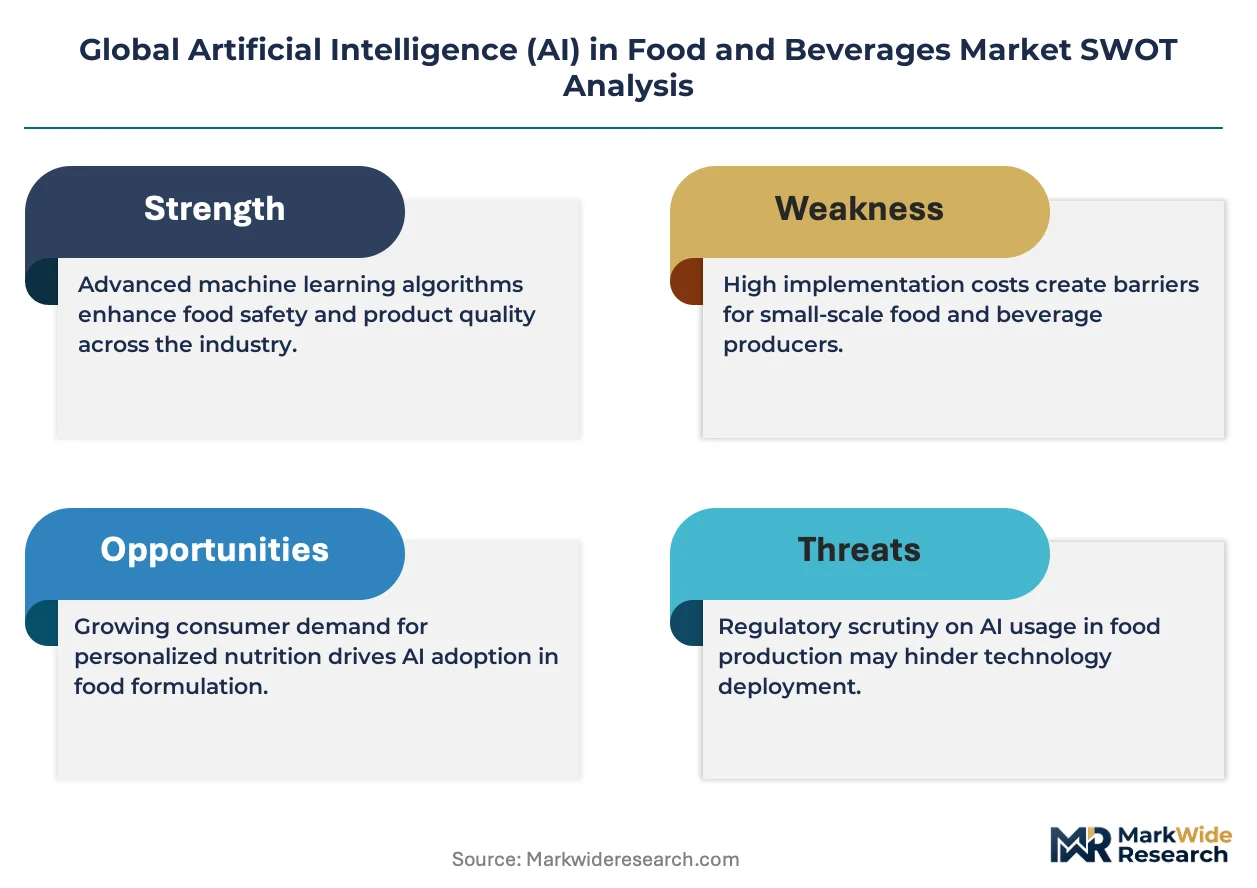
- High Implementation Costs:The capital expenditure for AI hardware, software, and integration with legacy equipment is a major adoption barrier for small and medium-sized food producers.
- Data Privacy Constraints:Europe's GDPR strictly limits using consumer data for behavior analytics, restricting AI applications in personalized marketing and large-scale demand forecasting.
- Specialized Talent Scarcity:A shortage of data scientists with domain expertise in food manufacturing creates a bottleneck for developing and deploying effective, customized AI models.
Strategic Opportunities
- Predictive Maintenance Services:Deploying AI models using sensor data from production equipment creates an opportunity to offer services that predict and prevent machinery failures, reducing downtime.
- AI and Blockchain Convergence:Integrating AI analytics with blockchain creates immutable supply chain records, offering verifiable proof of food origin and safety to consumers and regulators.
- Expansion in Southeast Asia:The industrializing food processing sectors in Vietnam and Indonesia represent a key growth market for foundational AI quality control and efficiency solutions.
Industry Challenges
- Legacy System Integration:Operators face significant complexity integrating modern AI platforms with existing, often proprietary, operational technology (OT) and enterprise resource planning (ERP) systems on the factory floor.
- Data Standardization Gaps:A lack of common data formats and communication protocols across equipment vendors and software providers complicates the creation of unified datasets needed for effective AI model training.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Artificial Intelligence (AI) in Food and Beverages Market |
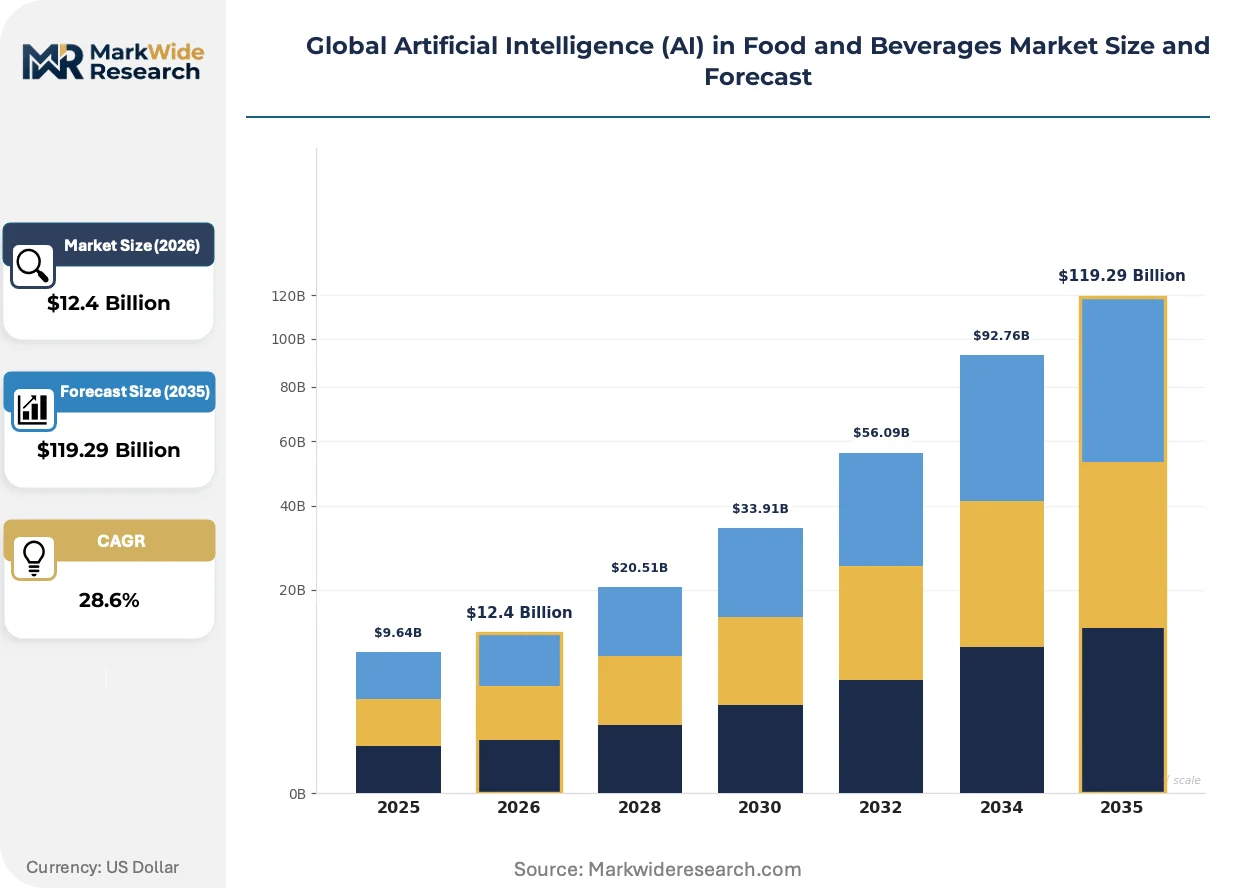
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $119.29 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Machine Learning Platforms, Natural Language Processing, Computer Vision, Robotics Process Automation, Expert Systems Application: Supply Chain Optimization, Quality Control, Consumer Behavior Analytics, Predictive Maintenance, Food Safety Compliance Deployment Mode: Cloud-Based, On-Premise, Hybrid, Edge Computing End User Industry: Food Processing, Beverage Manufacturing, Packaging Services, Ingredients Suppliers |
| Companies Covered | TOMRA Systems ASA, ABB Ltd., Rockwell Automation Inc., Sesotec GmbH, Honeywell International Inc., Siemens AG, Key Technology Inc., Raytec Vision SpA, IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Artificial Intelligence (AI) in Food and Beverages Market Strategic Shifts & Innovations
A fundamental shift toward decentralized intelligence is redefining the application of AI in the food and beverage sector. The focus is moving from large-scale, cloud-based analytics to real-time decision-making directly on the production line, driven by new computing architectures and regulatory demands.
Edge computing allows for the processing of data directly on or near its source, such as a sensor on a production line. Food and beverage manufacturers are adopting this technology for latency-sensitive applications like high-speed sorting and defect detection. Consequently, the core of AI processing is migrating from centralized cloud platforms, which handle large-scale analytics, to intelligent devices on the factory floor for immediate operational response.
The European Union's AI Act establishes a risk-based framework, creating new compliance obligations for artificial intelligence systems. This regulation mandates that high-risk AI, including systems for food safety, meet strict requirements for data quality, transparency, and human oversight. Consequently, AI vendors serving the European food market must now invest in extensive documentation and conformity assessments to demonstrate system reliability.
Consumer demand is shifting from brand promises to a requirement for verifiable data on product origin, ingredients, and ethical sourcing. This change disrupts traditional marketing, as trust is now built on transparent, data-driven traceability rather than brand reputation alone. This trend is most prominent in the organic and specialty food segments, where consumers actively seek products with accessible and detailed supply chain information.
Global Artificial Intelligence (AI) in Food and Beverages Market Segmentation
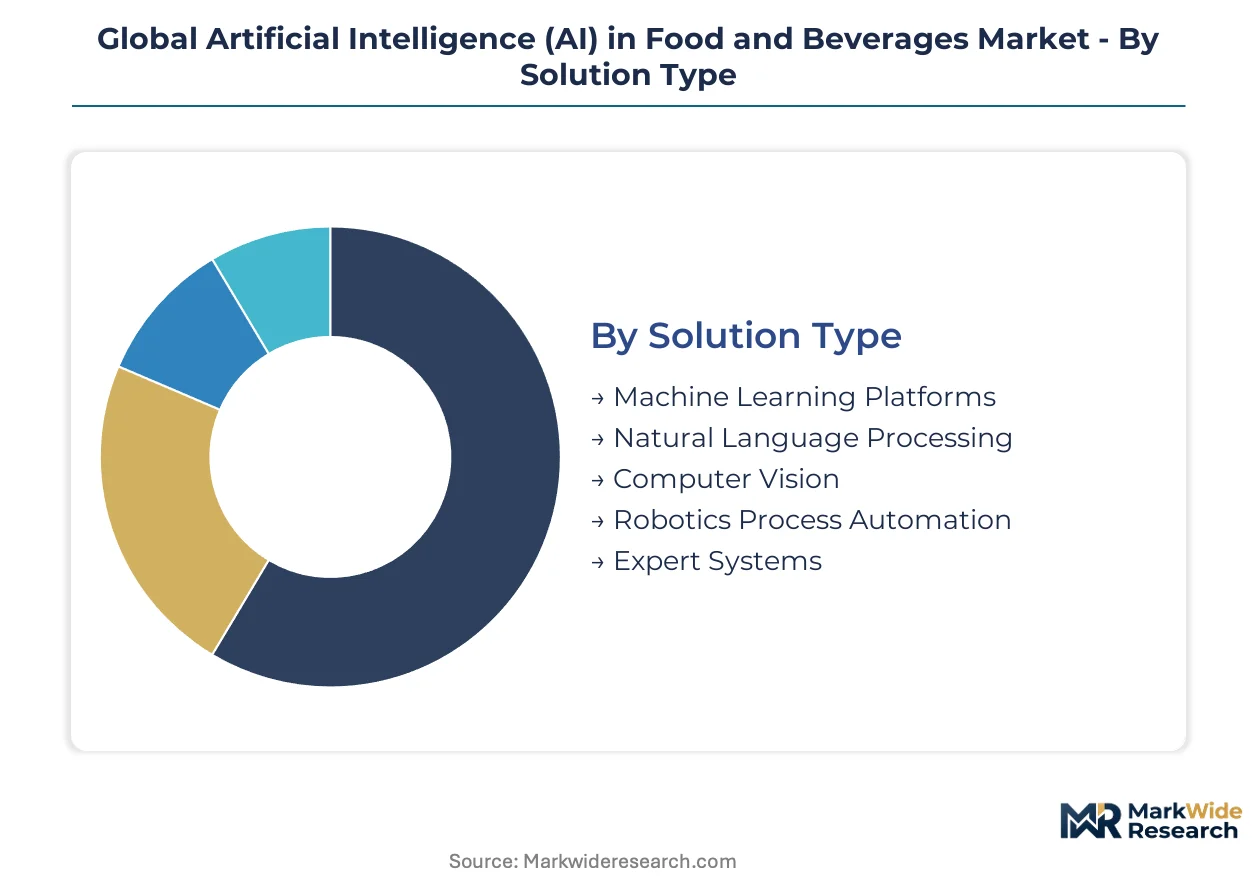
The artificial intelligence market in food and beverages segments across various dimensions, each reflecting distinct operational needs and technological maturities. Understanding these segments is critical for operators to prioritize investments and for technology providers to tailor their offerings effectively. This segmentation highlights where AI deployments are most impactful and where future growth concentrates.
Solution Type:
Different AI solution types offer varying deployment speeds and impact cycles within food and beverage operations. Some solutions provide immediate, tangible benefits on the production line, while others require longer integration periods for broader analytical outcomes.
- Computer Vision:These systems utilize deep learning algorithms to process visual data from cameras, enabling automated quality inspection and defect detection. Demand for computer vision solutions concentrates in food processing facilities, driven by the need to identify microscopic defects and reduce food waste on high-speed lines.
- Machine Learning Platforms:These platforms provide the underlying infrastructure and algorithms for data analysis, pattern recognition, and predictive modeling across diverse datasets. Their demand is concentrating in large-scale food manufacturers seeking to optimize complex processes and leverage consumer analytics for product development.
- Natural Language Processing:This technology processes and understands human language, facilitating applications in customer service automation and analysis of unstructured text data.
- Robotics Process Automation:RPA automates repetitive, rule-based tasks within business processes, improving efficiency in administrative and back-office functions.
- Expert Systems:These AI systems mimic human decision-making processes based on predefined rules and knowledge bases, offering guidance for complex operational challenges.
Computer Vision dominates the installed base for immediate operational impact. Machine Learning Platforms are where broader analytical expansion concentrates.
Application:
AI applications address specific operational pain points, ranging from enhancing product quality to optimizing logistical flows within the food and beverage industry.
- Quality Control:AI systems, particularly computer vision, automate the inspection of products for defects, foreign objects, and consistency, ensuring adherence to quality standards. This application commands significant investment across food processing, driven by stringent regulatory requirements and consumer expectations for product integrity.
- Supply Chain Optimization:AI models analyze vast datasets to predict demand, optimize inventory levels, and streamline logistics, improving efficiency and reducing waste across the entire supply chain. Demand for these solutions concentrates in large food and beverage corporations, aiming for greater visibility and resilience in their global operations.
- Consumer Behavior Analytics:AI analyzes purchasing patterns, preferences, and feedback to provide insights into consumer trends, informing product development and marketing strategies.
- Predictive Maintenance:AI uses sensor data from machinery to forecast equipment failures, enabling proactive maintenance and minimizing costly downtime on production lines.
- Food Safety Compliance:AI-powered systems assist in tracking, tracing, and documenting food products throughout the supply chain, ensuring adherence to regulatory mandates like the U.S. FDA's FSMA.
The market for Quality Control solutions commands significant investment. Supply Chain Optimization solutions demonstrate the steepest expansion trajectory.
Deployment Mode:
The choice of AI deployment mode reflects trade-offs between scalability, latency, and data security requirements for food and beverage operators.
- Edge Computing:This mode processes data directly on or near the data source, such as factory floor sensors, reducing latency for real-time decision-making. Edge computing is gaining traction for latency-sensitive applications like high-speed sorting and defect detection in manufacturing facilities.
- Cloud-Based:Cloud deployments offer scalability and flexibility for large-scale data storage and complex analytical workloads, accessible remotely. Cloud-based solutions are widely adopted by large enterprises for extensive data analytics and machine learning model training.
- On-Premise:On-premise deployments involve installing and running AI software on local servers within a company's own infrastructure, offering maximum control and security.
- Hybrid:Hybrid models combine elements of both cloud and on-premise deployments, allowing organizations to leverage the benefits of each for different workloads.
Cloud-Based deployments underpin foundational data processing. Edge Computing deployments are gaining share fastest for real-time operations.
End User Industry:
AI adoption varies across different segments of the food and beverage industry, driven by specific operational complexities and regulatory pressures.
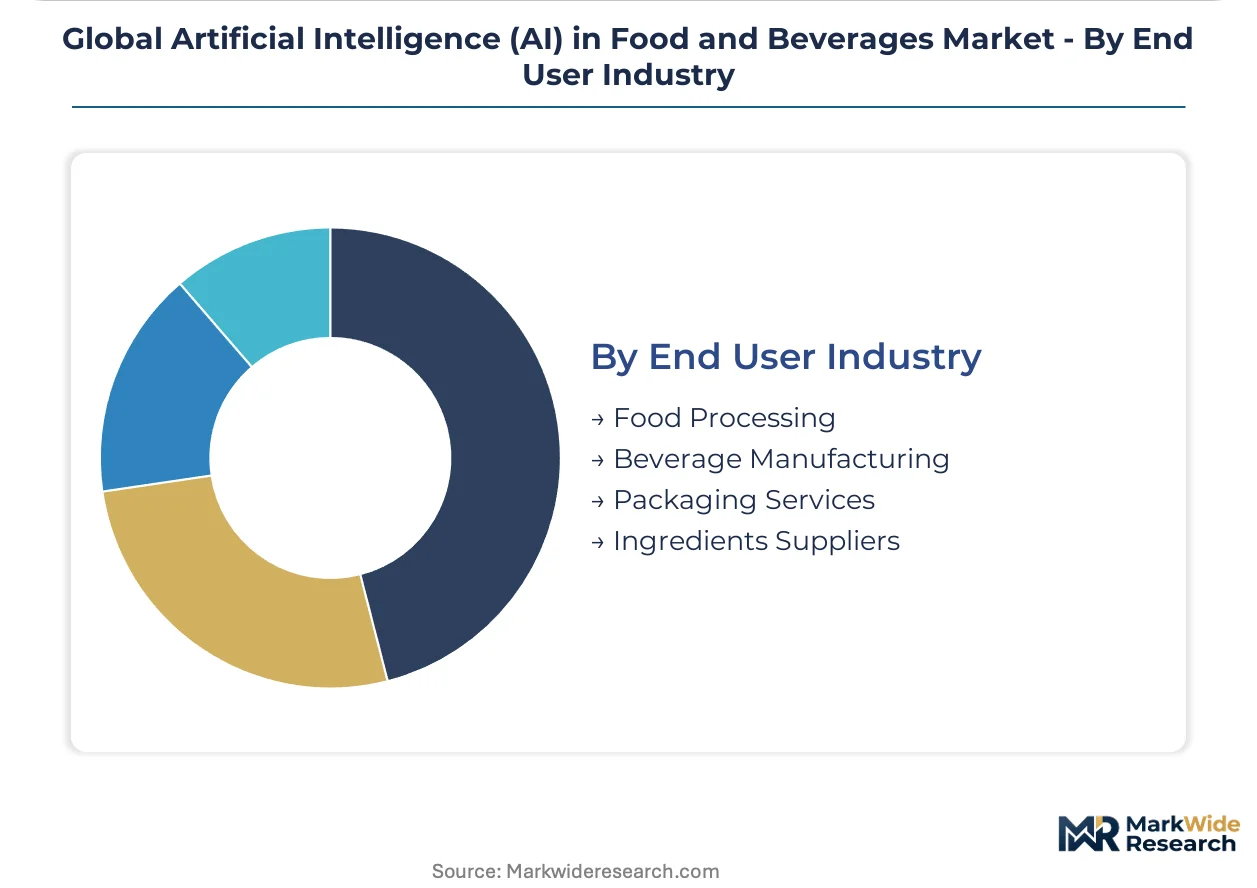
- Food Processing:This segment includes facilities that transform raw agricultural products into finished food items, involving various stages from cleaning to packaging. Food processing represents the largest demand pool for AI, particularly for quality control and efficiency improvements, with significant concentration in China.
- Beverage Manufacturing:This segment encompasses the production of alcoholic and non-alcoholic drinks, including brewing, bottling, and packaging operations. Beverage manufacturing is rapidly integrating AI for operational efficiencies, such as predictive maintenance and supply chain optimization.
- Packaging Services:These services involve the design, production, and assembly of packaging for food and beverage products, ensuring product integrity and shelf-life.
- Ingredients Suppliers:This segment provides raw materials and processed components to food and beverage manufacturers, often requiring quality assurance and traceability solutions.
Food Processing represents the largest demand pool for AI technologies. Beverage Manufacturing is rapidly integrating AI for operational efficiencies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global development of AI in food and beverages is increasingly concentrated in specific national markets. China's rapid expansion of smart food processing facilities exemplifies this trend. This concentration is driven by a blend of national initiatives, stringent regulatory frameworks, and technological advancements.
China
China's market for AI in food and beverages experiences concentrated demand, driven by national initiatives to enhance food safety and manufacturing efficiency. The country's GB standards enforce strict quality controls, incentivizing AI adoption for compliance. Smart food processing facilities in the Yangtze River Delta region are rapidly deploying AI solutions for automation and inspection.
United States
United States operators demand AI for traceability and compliance documentation, especially under the U.S. FDA's Food Safety Modernization Act. This regulatory push incentivizes AI-powered systems across the food supply chain. Food processing hubs in California are adopting computer vision and predictive maintenance for enhanced product integrity.
Germany
Germany exhibits strong demand for AI in food and beverages, particularly for industrial automation and precise quality control. The EU AI Act establishes a risk-based framework for high-risk AI, including food safety systems. Industrial automation clusters in Bavaria integrate AI across production lines, leveraging expertise from companies like Siemens AG.
Vietnam
Vietnam's industrializing food processing sector represents a growing market for foundational AI quality control and efficiency solutions. National food safety regulations, enforced by the Vietnam Food Administration, drive initial AI deployments. Food manufacturing facilities around Ho Chi Minh City are implementing basic AI for sorting and defect detection.
Global Artificial Intelligence (AI) in Food and Beverages Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, providing sensor technology and analytical tools. This market is characterized by a mix of large industrial automation conglomerates and specialized AI solution providers. Strategic archetypes include comprehensive solution providers, niche technology developers, and cloud-based analytics platforms. Competitive moves center on strategic partnerships to integrate diverse technologies and portfolio diversification into new application areas.
Specialists in advanced sorting and industrial integration exemplify the diverse vendor landscape. TOMRA Systems ASA, a Norwegian public limited company, occupies a position as a leading component specialist in sensor-based sorting for granular quality control. Germany-based Siemens AG represents a major industrial automation conglomerate, integrating AI across entire production lines. Meanwhile, the US-headquartered IBM Corporation anchors the cloud-based machine learning platforms segment, providing scalable infrastructure for large-scale consumer analytics. These entities demonstrate the market's segmentation by capability and deployment focus.
| Leading Market Players |
|---|
| TOMRA Systems ASA |
| ABB Ltd. |
| Rockwell Automation Inc. |
| Sesotec GmbH |
| Honeywell International Inc. |
| Siemens AG |
| Key Technology Inc. |
| Raytec Vision SpA |
| IBM Corporation |
| Others |
Cost & Logistics Intelligence
Global cold chain logistics corridors significantly influence the cost dynamics of AI-enabled food distribution, impacting both supply concentration and downstream price differentiation for perishable goods. The integration of AI solutions adds complexity, necessitating investment in real-time monitoring and predictive analytics across these critical pathways.
Pricing Analysis
U.S. FDA's Food Safety Modernization Act (FSMA) dictates the pricing tier structure for AI-powered traceability and compliance systems in the United States. Value-based pricing models dominate the market, reflecting the operational efficiencies and risk mitigation offered by AI solutions. Price differentiation stems from the certification level required for specific applications, such as EU AI Act compliance, and the degree of customization for unique production line integration. Pricing pressure stems from increased competition in foundational AI solutions, especially for basic quality control features. Small and medium-sized food producers are highly price-sensitive, while large multinational corporations prioritize advanced features and comprehensive service bundles.
Supply Chain Analysis
Component specialists providing advanced sensor technology for AI systems concentrate their manufacturing capacity in specific regions, notably Germany, the United States, and parts of Asia. The AI supply chain relies heavily on semiconductor chips, specialized optical sensors, and cloud infrastructure services as primary inputs. Geopolitical tensions impacting semiconductor chip supply represent a significant structural risk for the broader AI in food and beverages market. Distribution primarily occurs through direct sales to large enterprises and channel partnerships with industrial automation integrators, ensuring specialized deployment and ongoing technical support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Artificial Intelligence (AI) in Food and Beverages Market represents an early-cycle expansion story, primarily driven by the maturation of computer vision technology for real-time quality control.
For Market Incumbents: Pre-empt emerging AI-native startups by rapidly integrating AI capabilities across their existing industrial automation portfolios. Incumbents like Siemens AG should leverage their extensive client base to cross-sell advanced AI modules for predictive maintenance and supply chain optimization. Investing in vertical integration into AI software development strengthens proprietary offerings, mitigating threats from specialized point solution providers. Pursue strategic partnerships with niche AI specialists to accelerate innovation in areas like natural language processing for consumer analytics.
For New Entrants and Emerging Players: Establish a beachhead in underserved geographies, such as industrializing food processing facilities in Southeast Asia, where foundational AI quality control solutions are in high demand. Focus on offering AI-as-a-Service models with lower upfront capital expenditure, appealing to small and medium-sized producers. Target specialty food segments requiring hyper-traceability and verifiable origin data, leveraging consumer demand for transparency. Develop highly specialized computer vision algorithms for unique defect detection challenges, differentiating from broader platform offerings.
For Investors and Strategic Acquirers: Niche AI solution developers specializing in food safety compliance and supply chain traceability represent attractive acquisition targets. This market offers long-term viability driven by non-discretionary food safety and efficiency demands across the food and beverage industry. Investors should prioritize companies demonstrating strong intellectual property in deep learning algorithms for real-time edge computing applications. Escalating regulatory enforcement actions in major markets, such as the U.S. FDA's FSMA, serve as a critical signal to watch for accelerating adoption and market growth.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Integrates diverse AI functionalities into cohesive solutions, simplifying deployment for food manufacturers. |
| Acquisition of Specialist Firm | Secures proprietary AI algorithms and specialized domain expertise in food processing applications. |
| Geographic Expansion | Captures new demand in industrializing regions like Southeast Asia for foundational AI solutions. |
| Strategic Partnership | Leverages complementary technologies and market access from established industrial automation providers. |
| Product Launch (AI Module) | Introduces targeted AI capabilities for specific operational pain points, such as advanced defect detection. |
Research Approach
Desk research of academic journals, industry reports, company financial filings, and regulatory documents preceded structured interviews with food processing plant managers, AI solution architects, supply chain directors, and food safety compliance officers. This approach combined primary insights with secondary validation, ensuring a comprehensive understanding of market dynamics. Bottom-up data aggregation and top-down market sizing were triangulated to establish robust market estimates.
The forecast framework integrates a core set of assumptions regarding technological advancements and regulatory developments across the analysis window. Market segmentation dimensions modeled include solution type, application, deployment mode, end-user industry, and regional regulatory landscapes. Compound annual growth rates were derived from historical data, projected technology adoption curves, and expert consensus. Industry-specific forecast inputs included food safety regulatory changes and AI hardware cost trends.
Macroeconomic conditions sit as an overlay; deviation in global inflation or trade policies would shift the trajectory of capital expenditure in food processing. Forecasts reflect assumptions documented through extensive primary and secondary research. Quarterly review of AI adoption rates in food processing and new regulatory mandates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Artificial Intelligence in Logistics Market
Artificial Intelligence (AI)
Industrial Artificial Intelligence [AI] Market
Artificial Intelligence (AI)
Commercial Artificial Intelligence Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) Market
Artificial Intelligence (AI)
Artificial Intelligence Based Personalization Market
Artificial Intelligence (AI)
Automotive Gesture Recognition Market
Artificial Intelligence (AI)
Artificial Intelligence in Business Market
Artificial Intelligence (AI)
Consumer Facing AI Products Market
Artificial Intelligence (AI)
Europe AI Orchestration Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Pharmaceutical Market
Artificial Intelligence (AI)
Natural Language Processing in BFSI Market
Artificial Intelligence (AI)
Global Artificial Intelligence in Security Market
Artificial Intelligence (AI)
Reinforcement Learning Market
Artificial Intelligence (AI)
AI in Construction Market
Artificial Intelligence (AI)
Intelligent Virtual Assistant Market
Artificial Intelligence (AI)
Smart Virtual Personal Assistants Market