
 Smart Connected Device Market | 2026-2036
Smart Connected Device Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Connected Device Market Outlook
Silicon carbide power semiconductors is consolidating around premium smart home energy management systems, displacing traditional silicon-based inverters in connected appliances. Samsung Electronics leverages its captive semiconductor foundry to integrate custom SoCs across its smart home ecosystem. Amazon anchors consumer-facing connectivity through Alexa-enabled device partnerships and proprietary mesh networking protocols. Apple differentiates via its closed-loop architecture spanning wearables, home hubs, and health data encryption.
Smart connected devices are physical hardware systems embedding sensors, microprocessors, and wireless transceivers to collect, transmit, and act on data without continuous human intervention, typically operating on sub-6 GHz radio bands with power envelopes under 15W for residential units. Their primary purpose spans ambient intelligence in buildings, predictive maintenance in factories, and continuous physiological monitoring in clinical settings. Smart Home Devices capture the largest installed base among product types, though Industrial IoT Devices command the highest average selling prices and service attach rates. Edge Computing deployment architectures are expanding fastest as latency-sensitive applications in automotive and healthcare outpace cloud-reliant configurations.
The FCC governs spectrum allocation and device certification for radio-frequency emissions in the United States, directly constraining which connectivity modules manufacturers can deploy. The EU AI Act and GDPR impose algorithmic accountability and data localization mandates that reshape firmware development cycles for vendors serving European consumers. Stakeholders must monitor evolving cybersecurity labeling requirements from multiple regulators, as fragmented compliance obligations threaten to fragment supply chains and delay product launches across jurisdictions.
Market Dynamics
Silicon carbide power semiconductors are compressing energy losses in connected appliances, forcing manufacturers to redesign thermal architectures and procurement strategies around wide-bandgap materials.
Growth Catalysts
- Medicare reimbursement codes:Remote therapeutic monitoring codes in the United States accelerate hospital procurement of connected health devices for chronic disease management.
- EU AI Act compliance mandates:Algorithmic transparency requirements drive firmware upgrades across European device portfolios, creating replacement cycles for legacy installed base.
- Edge computing architectures:Latency-sensitive automotive and healthcare applications pull compute resources closer to sensors, expanding hardware attach rates for local inference chips.
Market Restraints
- Silicon carbide substrate shortages:Wolfspeed and Coherent control over 150mm SiC wafer supply creates allocation bottlenecks for power module manufacturers.
- GDPR data localization costs:European cloud infrastructure requirements raise operational expenditure for device fleets processing biometric data across borders.
- Sub-6 GHz spectrum congestion:FCC licensing constraints in dense urban deployments force expensive module redesigns for unlicensed band coexistence.
Strategic Opportunities
- India PLI scheme for electronics:Production-linked incentives for semiconductor assembly and testing attract device OEMs to establish local manufacturing footprints.
- Matter protocol convergence:Unified interoperability standard across Apple, Amazon, Google ecosystems reduces certification fragmentation for smart home accessory vendors.
- Continuous glucose monitoring expansion:Non-invasive optical sensing technologies open ambulatory monitoring applications beyond diabetic patient populations.
Industry Challenges
- Embedded systems security engineering:Shortage of firmware developers with hardware-level cryptography expertise delays secure boot implementations for resource-constrained sensors.
- Multi-jurisdiction certification timelines:Divergent cybersecurity labeling schemes from FCC, ETSI, and national bodies extend product launch windows by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Connected Device Market |
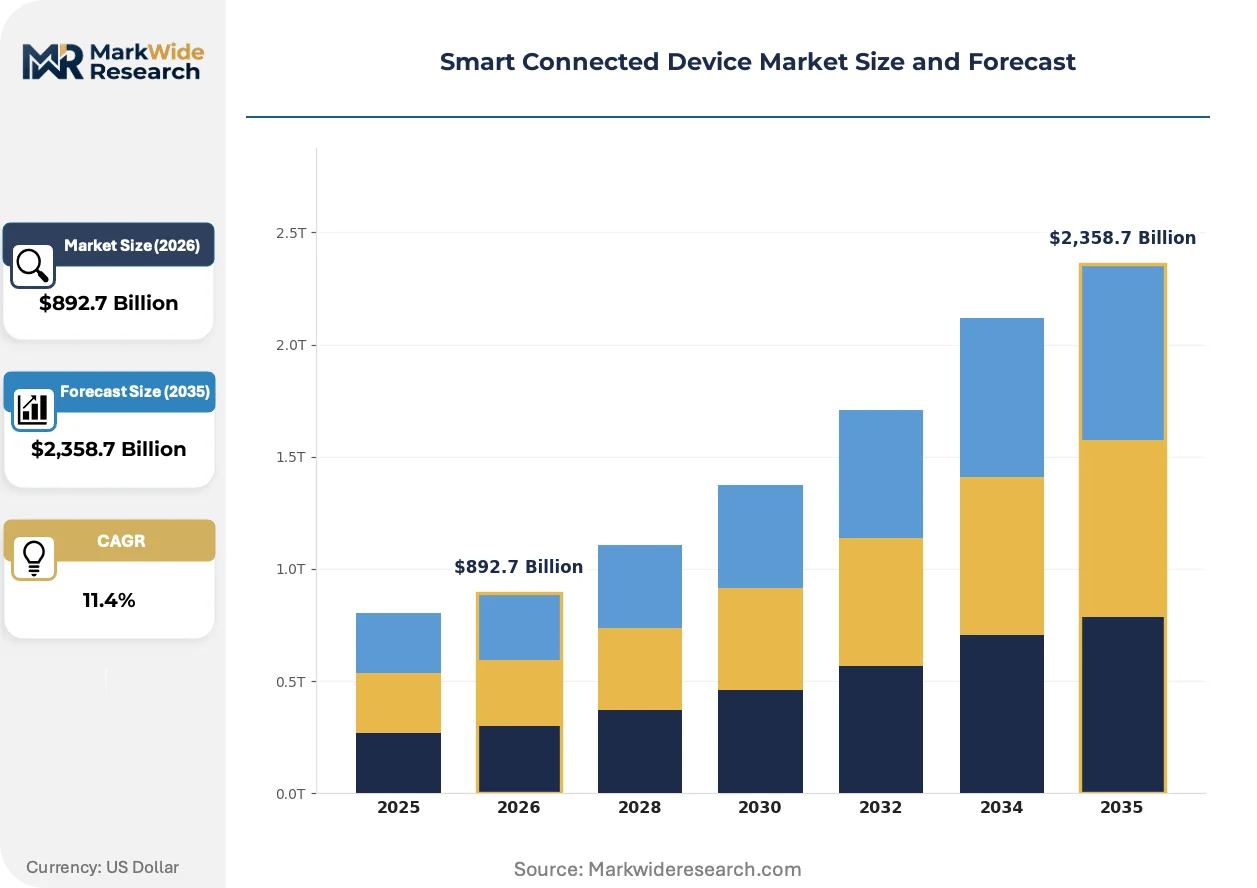
| Market Size in 2026 | $892.7 Billion |
| Market Size in 2035 | $2,358.7 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Wearables, Smart Home Devices, Connected Appliances, Industrial IoT Devices Connectivity: Wi-Fi, Bluetooth, Zigbee, Cellular End User: Commercial, Residential, Healthcare, Automotive Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | Samsung Electronics, SimpliSafe, Amazon, Ecovacs Robotics, Ring, Google, Wyze Labs, Centriq, Apple, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Connected Device Market Strategic Shifts
Device architectures are pivoting from cloud-dependent pipelines toward federated edge networks, compressing response latency while complicating software update orchestration across heterogeneous hardware generations.
Digital twin simulation is converging with physical sensor deployments, enabling predictive maintenance models that anticipate component degradation before failure thresholds. Industrial asset operators in Germany and Japan are deploying these paired systems for critical rotating equipment, reducing unplanned downtime through synthetic environment testing of failure modes.
The EU AI Act's risk classification framework restructures firmware development cycles for biometric-enabled devices, mandating conformity assessments before market placement. High-risk categories including remote patient monitoring systems face notified body scrutiny that extends validation timelines, compressing competitive windows for European launches versus other regions.
Hospital procurement committees are consolidating vendor relationships around integrated platform contracts, displacing point-solution purchasing for connected diagnostics. Health systems in the United States increasingly mandate API interoperability and centralized fleet management as table-stake requirements, favoring suppliers with end-to-end ecosystem control over specialized hardware vendors.
Smart Connected Device Market Segmentation
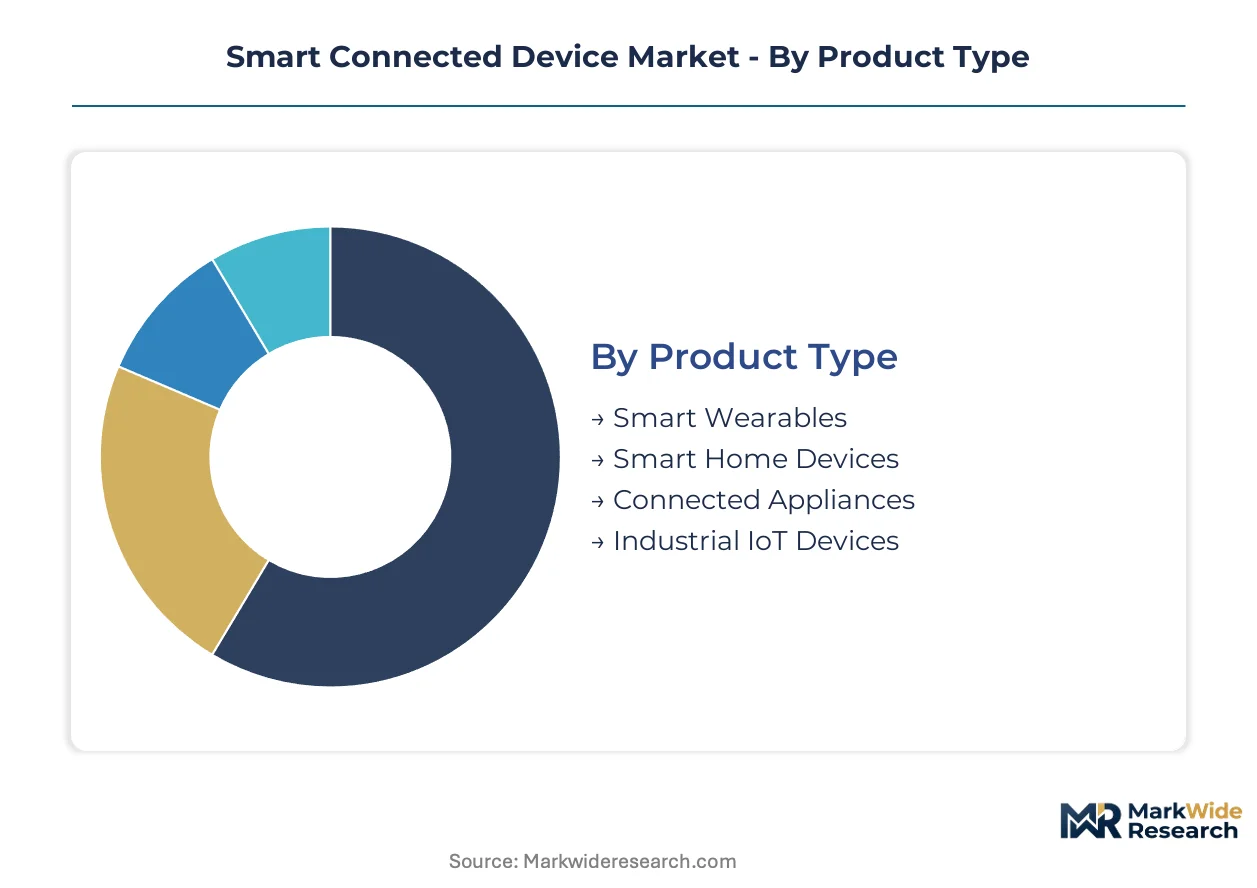
Smart connected device procurement hinges on matching connectivity protocols to environmental constraints, balancing latency requirements against power budgets, and navigating divergent regulatory regimes across deployment geographies. Segmentation reveals how vendor specialization clusters around distinct technical and commercial trade-offs.
Product Type:
Purchase volume concentrates in segments where ecosystem lock-in and service attach rates justify hardware margin compression.
- Smart Home Devices:Voice-controlled hubs, lighting controllers, and security systems integrate multiple radio protocols under unified management platforms. Residential retrofit demand in the United States and Germany drives volume, though Matter protocol standardization is eroding proprietary ecosystem advantages.
- Industrial IoT Devices:Ruggedized sensors and actuators withstand temperature extremes, vibration, and chemical exposure in manufacturing and energy infrastructure. Predictive maintenance contracts in Japanese automotive plants and German chemical facilities command premium pricing and multi-year service agreements.
- Smart Wearables:Wrist-worn and body-worn devices with biometric sensing capabilities. FDA and EU MDR clearance requirements for clinical-grade monitoring compress margins for non-specialist vendors.
- Connected Appliances:Refrigerators, washing machines, and HVAC units with embedded connectivity modules. Energy efficiency mandates from the EPA and EU Ecodesign Directive accelerate replacement cycles in North American and European households.
Smart Home Devices lead on scale; Industrial IoT Devices lead on momentum.
Connectivity:
Module selection determines regulatory certification burden, power consumption profile, and interoperability reach.
- Wi-Fi:High-throughput protocol dominating residential video streaming and cloud-backed analytics. FCC Part 15 unlicensed band congestion in dense US urban markets forces manufacturers toward Wi-Fi 6E and 6 GHz migration.
- Cellular:Licensed spectrum connectivity enabling wide-area mobility and guaranteed quality-of-service. Automotive telematics and remote patient monitoring in rural United States deploy LTE-M and NB-IoT modules to circumvent Wi-Fi infrastructure gaps.
- Bluetooth:Low-energy protocol for short-range personal area networks. Hearing aids, continuous glucose monitors, and fitness trackers leverage Bluetooth LE Audio and Auracast broadcast capabilities.
- Zigbee:Mesh networking standard for battery-operated sensor networks. Smart lighting and occupancy sensing in commercial buildings exploit self-healing topology to reduce wiring costs.
Wi-Fi dominates installed base; Cellular is climbing the fastest on automotive and healthcare deployment.
End User:
Vertical-specific compliance requirements and procurement authority structures reshape go-to-market economics.
- Healthcare:FDA-cleared remote therapeutic monitoring devices and in-hospital connected diagnostics. Medicare reimbursement codes in the United States accelerate hospital procurement for chronic disease management programs.
- Automotive:Connected infotainment, advanced driver assistance, and vehicle-to-everything communication systems. NHTSA cybersecurity guidelines and UNECE WP.29 regulations mandate over-the-air update capabilities and intrusion detection.
- Residential:Consumer-purchased smart home ecosystems with DIY installation. Amazon, Apple, and Google platform competition fragments accessory vendor strategies around voice assistant compatibility.
- Commercial:Building automation, asset tracking, and energy management for enterprise facilities. LEED certification requirements and ESG reporting obligations under EU CSRD drive connected sensor deployment in European office portfolios.
Healthcare leads on pricing power; Automotive is gaining share fastest on software-defined vehicle architectures.
Deployment:
Compute location selection trades latency sensitivity against operational complexity and capital intensity.
- Edge Computing:Local inference processing on device or gateway to minimize round-trip delay. Autonomous vehicle perception and surgical robotics in the United States and Germany demand sub-10 millisecond response times.
- Cloud-Based:Centralized data processing with elastic scaling and model training aggregation. Consumer smart home analytics and non-critical industrial monitoring exploit hyperscaler infrastructure in Virginia, Frankfurt, and Singapore regions.
- Hybrid:Tiered architecture with time-critical processing at edge and model refinement in cloud. Retail computer vision and predictive maintenance blend local inference with centralized fleet learning.
- On-Premises:Air-gapped or private data center deployment for classified or sovereignty-sensitive workloads. Defense and intelligence applications in the United States mandate disconnected operation under NSA supply chain guidelines.
Cloud-Based retains scale leadership; Edge Computing shows steepest expansion trajectory on latency-critical application proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors the dominant electronics manufacturing cluster for connected device assembly and component sourcing. The United States, Germany, China, India, and Japan concentrate distinct competitive advantages across hardware design, industrial application, and regulatory innovation.
United States
Medicare reimbursement codes for remote therapeutic monitoring accelerate hospital procurement of connected health devices. FDA cybersecurity guidelines for medical devices mandate pre-market submission of software bills of materials. The Boston-Cambridge corridor hosts FDA-cleared wearable startups developing continuous glucose monitoring platforms.
Germany
Industrial IoT deployment in automotive and chemical manufacturing drives demand for predictive maintenance sensors. EU AI Act conformity assessments extend validation timelines for biometric-enabled devices entering European markets. The Stuttgart region concentrates Industry 4.0 implementation with Siemens and Bosch anchoring smart factory sensor networks.
China
Domestic consumption of smart home ecosystems and EV telematics expands module demand for Wi-Fi and cellular connectivity. MIIT cybersecurity certification requirements for networked devices impose firmware documentation burdens on foreign vendors. The Yangtze River Delta manufacturing belt supplies 60% of global Bluetooth module assembly capacity.
India
Production-linked incentive schemes for electronics manufacturing attract device OEMs to establish local assembly operations. BIS certification mandates for wireless equipment delay import timelines for unlicensed band modules. Karnataka's Bengaluru-Tumkur corridor hosts R&D centers for Amazon and Google developing India-specific voice assistant hardware.
Japan
Aging demographics and labor shortages accelerate robotic automation and remote patient monitoring adoption. METI data governance guidelines for IoT platforms require explicit user consent mechanisms for biometric data processing. The Nagoya-Toyota industrial zone integrates connected sensors into just-in-time manufacturing lines for automotive suppliers.
Smart Connected Device Market Competitive Environment
Platform ecosystem expansion dominates the current landscape as vendors consolidate control over device interoperability and data pipelines. The market structures around three tiers: captive semiconductor foundries with vertical hardware-software integration, cloud hyperscalers leveraging voice assistant distribution, and specialized sensor manufacturers serving regulated healthcare verticals. Strategic archetypes include ecosystem orchestrators, component suppliers, and vertical application specialists. Capacity expansion in wide-bandgap semiconductor fabrication and strategic partnerships around Matter protocol certification represent the dominant competitive moves.
Within the ecosystem orchestrator tier, Samsung Electronics exemplifies captive foundry advantages through in-house SoC production for smart home portfolios. Amazon and Apple anchor contrasting architectural philosophies—Amazon through open Alexa-enabled partnerships spanning multiple hardware vendors, Apple via closed-loop encryption and wearable-home hub integration. These three entities represent the primary competitive anchors shaping procurement standards and developer platform economics.
| Leading Market Players |
|---|
| Samsung Electronics |
| SimpliSafe |
| Amazon |
| Ecovacs Robotics |
| Ring |
| Wyze Labs |
| Centriq |
| Apple |
| Others |
Value Chain & Pricing Dynamics
Silicon carbide wafer spot price indices cascade through power module procurement into tiered hardware pricing, compressing margins for appliance OEMs while concentrating margin capture among substrate suppliers Wolfspeed and Coherent. The pass-through elasticity varies by device category: industrial IoT sensors absorb cost spikes through long-term service contracts, whereas consumer smart home devices face immediate retail price pressure.
Pricing Analysis
Input-cost pass-through from SiC substrate shortages and cellular module tariffs is reshaping contract structures across device tiers. Pricing stratifies across FDA-cleared clinical devices, Matter-certified smart home hardware, and uncertified consumer accessories, with certification grade and volume scale as primary differentiation drivers. Cost compression in the consumer tier intensifies because of Amazon and Google ecosystem subsidy strategies. Hospital procurement committees show lowest price sensitivity due to Medicare reimbursement code coverage, while DIY residential buyers exhibit highest elasticity.
Supply Chain Analysis
Dual-sourcing requirements for 150mm SiC wafers and cellular baseband modules are forcing OEMs to qualify secondary suppliers in Japan and Germany alongside dominant Taiwan and China sources. The supply chain draws from concentrated semiconductor fabrication in Taiwan, sensor assembly in China, and specialty component production in Germany and Japan. Single-source vulnerability around Wolfspeed's substrate capacity creates allocation risk for power module manufacturers. Distribution runs through direct enterprise contracts for industrial and healthcare verticals, consumer electronics retail for residential devices, and GPO contracts for hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
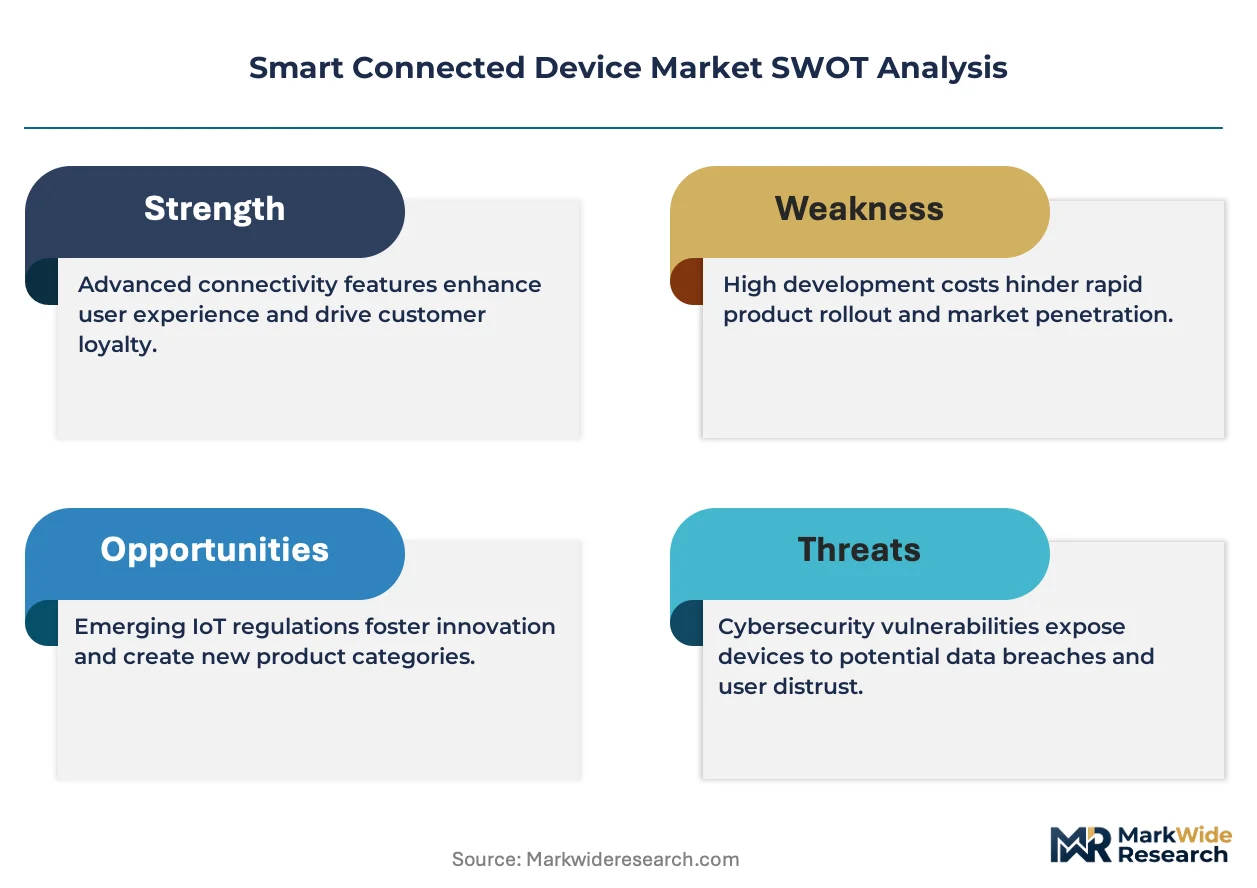
This market functions as a geographic-arbitrage play: EU AI Act compliance costs in Europe run 15-20% above US regulatory expenditure, creating margin expansion opportunity for vendors with US-first launch strategies and European market delay options.
For Market Incumbents: Cement ecosystem lock-in through captive silicon carbide foundry partnerships and Matter protocol certification acceleration, defending against modular sensor vendors eroding hardware margins. Priority levers include backward integration into wide-bandgap semiconductor supply and FDA pre-submission pathways for remote patient monitoring devices. For New Entrants and Emerging Players: Capture white-space in India-specific voice assistant hardware and non-invasive continuous glucose monitoring platforms, where regulatory pathways remain less congested than US and EU corridors. The most penetrable segment is BIS-certified wireless modules for price-sensitive Indian residential markets, accessed through PLI scheme manufacturing partnerships. For Investors and Strategic Acquirers: Asymmetric upside sits with verticalized healthcare sensor platforms possessing FDA-cleared algorithms and hospital GPO contract access. Long-term viability hinges on reimbursement strategy execution and cybersecurity labeling compliance across FCC, ETSI, and emerging national frameworks. The signal to watch is Medicare remote therapeutic monitoring code expansion or contraction as demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Matter Protocol Certification | Unified interoperability standard reduces Amazon, Apple, Google ecosystem fragmentation for accessory vendors. |
| Silicon Carbide Foundry Partnership | Wolfspeed and Coherent substrate allocation secures power module supply for premium appliance tiers. |
| FDA Pre-Submission Pathway | Remote therapeutic monitoring clearance unlocks Medicare reimbursement and hospital procurement acceleration. |
| India PLI Manufacturing Footprint | Production-linked incentives attract device assembly and testing operations for cost-competitive export positioning. |
| Edge Computing Chip Integration | Local inference hardware attachment expands margins in automotive ADAS and surgical robotics applications. |
Study Parameters
Bottom-up connected device shipment modeling reconciled against top-down semiconductor foundry capacity tracking forms the analytical core of this study. Primary interviews with connected health procurement managers, smart home platform engineers, industrial IoT maintenance directors, and cellular module sourcing leads combined with secondary validation from FCC equipment authorization databases, FDA 510(k) filings, EU MDR notified body registers, and hyperscaler IoT platform capex disclosures. Triangulation across these sources yields volume estimates segmented by connectivity protocol, deployment architecture, and regulatory jurisdiction.
Historical trendline analysis of installed base growth, replacement cycle compression, and service attach rate expansion informs the projection framework. Segmentation dimensions modeled include product type, connectivity technology, end-user vertical, and compute deployment location, with additional stratification by certification tier across FDA, CE marking, and MIIT cybersecurity frameworks. CAGRs derive from curve-fitting against technology adoption S-cycles and regulatory milestone timing, with specific inputs from Medicare reimbursement code expansion trajectories and EU AI Act implementation phase-ins.
Underlying measurement precision varies by segment; FDA-cleared medical devices and cellular-connected automotive systems carry tighter precision than uncertified consumer smart home accessories due to mandatory registration and production reporting requirements. Forecasts reflect assumptions around SiC substrate supply normalization, Matter protocol adoption velocity, and reimbursement code stability. Deviation in EU AI Act enforcement intensity or FCC spectrum reallocation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
IoT in Warehouse Management Market
Internet of Things (IoT)
Telecom Internet of Things (IoT) Market
Internet of Things (IoT)
IoT Software Engineering Market
Internet of Things (IoT)
IoT Infrastructure Market
Internet of Things (IoT)
Qatar Internet of Things (IoT) Market
Internet of Things (IoT)
Global Internet of Behaviors Market
Internet of Things (IoT)
Massive IoT Market
Internet of Things (IoT)
Edge Computing in IoT Market
Internet of Things (IoT)
US Smart Thermostat Market
Internet of Things (IoT)
Europe Industrial IoT Market
Internet of Things (IoT)
IoT Communication Protocol Market
Internet of Things (IoT)
IoT in Energy Market
Internet of Things (IoT)
Narrowband-Internet of Things (NB-IoT) Market
Internet of Things (IoT)
IoT Monetization Market
Internet of Things (IoT)
LTE IoT Market
Internet of Things (IoT)
Internet of Everything Market