
 IoT Network Management Market | 2026-2036
IoT Network Management Market Size, Share, and Industry Trends Forecast 2026-2036
IoT Network Management Market Foresight
The capital-intensity gap between cloud-native specialists and legacy hardware incumbents is collapsing as software-defined networking becomes table stakes. Cisco Systems leverages its installed base of routing infrastructure to extend management capabilities into edge environments. IBM Corporation anchors its competitive position through AI-driven predictive analytics layered over hybrid cloud deployments. Microsoft Corporation dominates the platform layer by integrating Azure IoT with enterprise identity and security stacks.
IoT network management encompasses the software platforms, protocols, and operational frameworks that provision, monitor, secure, and optimize connected device ecosystems across distributed infrastructures, typically handling latency thresholds below 50 milliseconds for time-critical industrial applications. Its primary purpose is ensuring reliable data flow from sensors and actuators to analytics engines while maintaining security posture across heterogeneous device populations. Managed services within the service type dimension leads current revenue capture as enterprises outsource operational complexity, while professional services shows the fastest expansion as organizations require bespoke integration for legacy OT-IT convergence. Cellular technology within the technology dimension commands premium pricing due to licensed spectrum reliability, whereas LPWAN occupies the high-volume, low-margin tier for rural asset tracking and utility metering.
FCC spectrum allocations in the United States, ETSI standards under the European Electronic Communications Code, and ISO/IEC 27001 security frameworks collectively shape product certification requirements and cross-border deployment feasibility. GDPR and sector-specific national cybersecurity directives in Germany and France impose data residency and breach notification obligations that directly influence platform architecture decisions. Stakeholders must monitor evolving radio equipment certification timelines and interoperability mandates as deterministic networking requirements from autonomous systems and precision agriculture redefine baseline performance expectations.
Market Dynamics
Edge computing integration with 5G backhaul is compressing latency requirements below 50 milliseconds for industrial automation, forcing platform vendors to rearchitect orchestration layers around distributed compute nodes rather than centralized cloud cores.
Growth Catalysts
- Industrie 4.0 compliance mandates:Germany's manufacturing corridors require real-time device orchestration as an operational prerequisite, pulling advanced network management platforms into brownfield industrial sites.
- FCC spectrum allocations:Licensed spectrum reliability for cellular IoT backhaul is accelerating municipal smart city deployments across United States urban centers.
- LPWAN volume economics:Rural asset tracking and utility metering applications are driving high-volume sensor deployments that demand lightweight, low-power network management protocols.
Market Restraints
- Silicon supply concentration:Semiconductor fabrication for edge gateway chipsets remains concentrated in East Asian foundries, exposing procurement timelines to geopolitical friction.
- GDPR data residency costs:European breach notification and localization obligations impose architectural constraints that inflate platform deployment expenditures by 15-30% versus non-compliant architectures.
- Legacy OT protocol fragmentation:Proprietary industrial fieldbus standards in aging manufacturing plants resist seamless integration with IP-based management overlays.
Strategic Opportunities
- Precision agriculture expansion:Deterministic networking requirements for autonomous irrigation and crop monitoring systems are opening greenfield deployments in Midwestern United States farming cooperatives.
- South Korean smart infrastructure:National digital twin initiatives for urban traffic and energy grids are creating dedicated procurement channels for integrated network management suites.
- AI-driven predictive maintenance convergence:Machine learning model deployment at the edge is forcing bundling of network visibility tools with analytics platforms.
Industry Challenges
- OT-IT integration expertise scarcity:Organizations lack personnel fluent in both operational technology protocols and cloud-native security postures, delaying deployment timelines.
- ISO/IEC 27001 certification timelines:Security framework compliance for cross-border deployments requires 12-18 month validation cycles that stall revenue recognition.
- Multi-vendor interoperability testing:Heterogeneous device populations demand extensive pre-deployment validation, consuming professional services capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IoT Network Management Market |
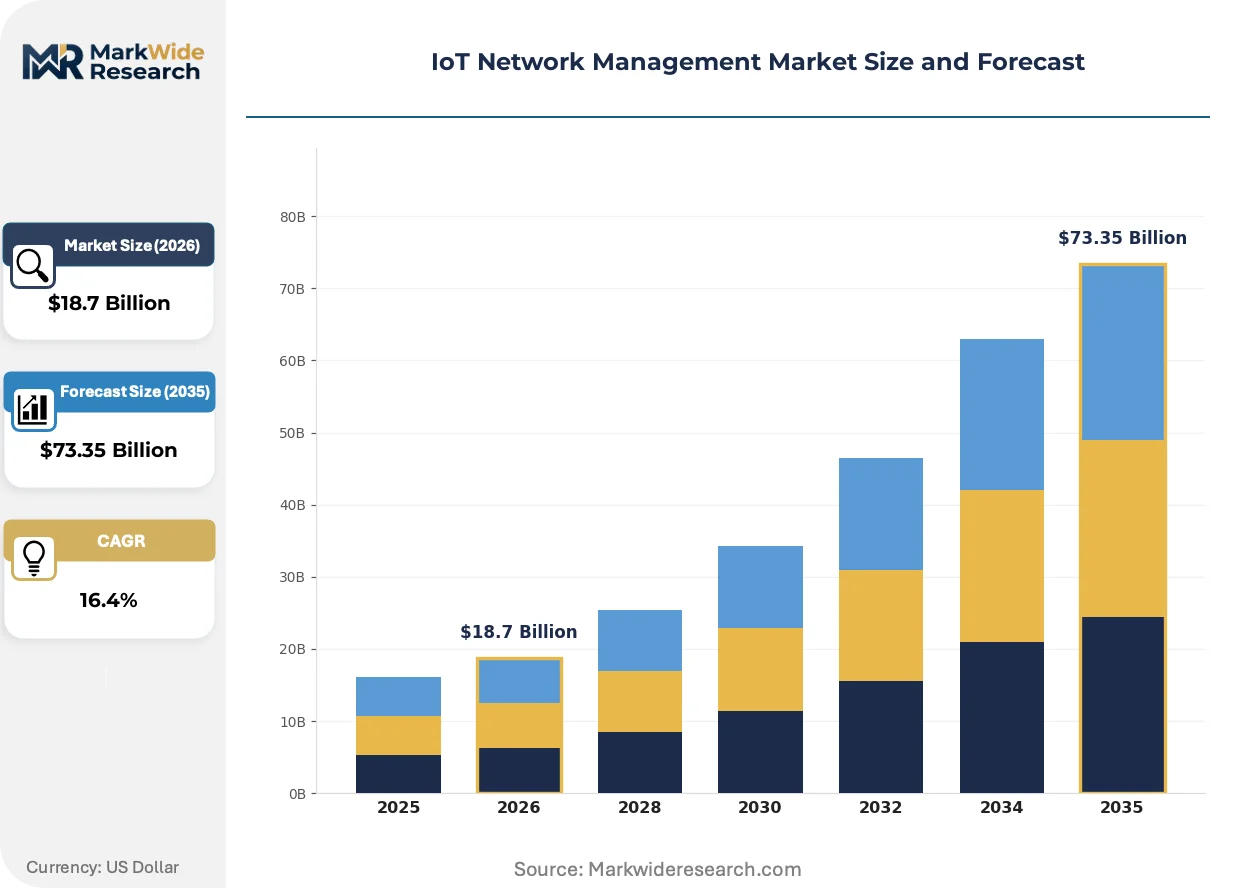
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises Service Type: Managed Services, Professional Services, Consulting Services, Maintenance Services End User: Manufacturing, Healthcare, Transportation, Smart Cities Technology: LPWAN, Zigbee, Wi-Fi, Cellular |
| Companies Covered | Cisco Systems, IBM Corporation, Microsoft Corporation, Hewlett Packard Enterprise, Oracle Corporation, Siemens AG, Honeywell International, Intel Corporation, SAP SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IoT Network Management Market Shifts & Advancements
Software-defined networking is collapsing the historical boundary between cloud-native specialists and legacy hardware vendors, compressing procurement criteria around unified control planes rather than discrete equipment categories.
Containerized network functions are fragmenting the traditional appliance market. Manufacturing facilities in Germany's Ruhr region are deploying microservices-based management agents directly onto edge gateways. This architecture is fragmenting vendor lock-in patterns by enabling modular substitution of individual control plane components.
GDPR and sector-specific national cybersecurity directives in France are mandating breach notification windows under 72 hours. Industrial operators must now embed automated anomaly detection into network management stacks. Heavy process industries in the Rhine-Ruhr corridor are prioritizing platforms with built-in SIEM integration to satisfy CNIL audit requirements.
Managed service contracts are displacing perpetual license purchases among municipal buyers. Smart city procurement offices in South Korea's Songdo and Sejong clusters now favor operational expenditure models with guaranteed uptime SLAs. This preference shift is compressing upfront revenue recognition for platform vendors while elongating customer lifetime value horizons.
IoT Network Management Market Segmentation
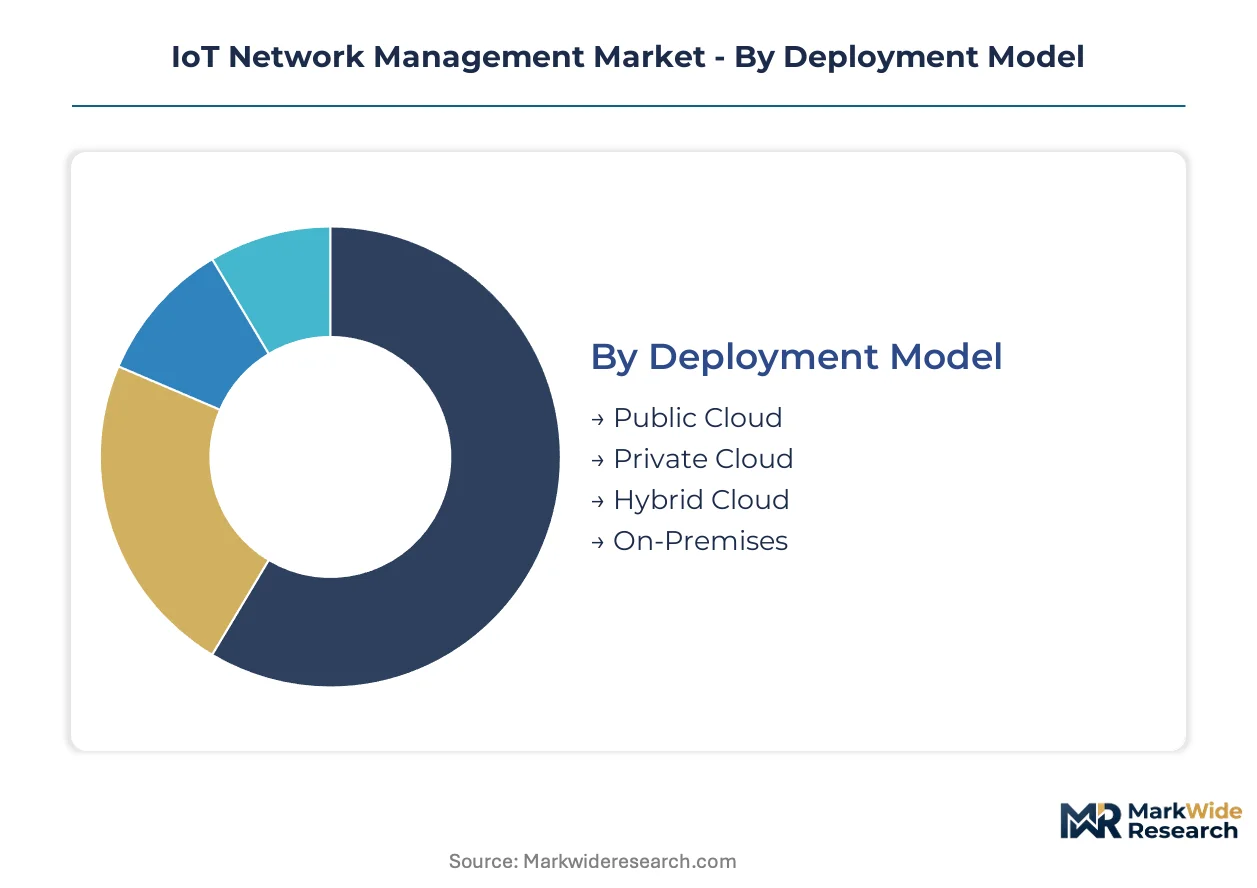
IoT network management platforms must align deployment architecture, service delivery, and connectivity protocols with distinct operational constraints across industrial and municipal environments. Procurement patterns diverge sharply between latency-sensitive manufacturing corridors and bandwidth-constrained rural utility networks. Understanding segment substitution pressures enables vendors to anticipate where software-defined alternatives displace legacy hardware stacks.
Deployment Model:
Substitution pressure from cloud-native orchestration tools is collapsing the traditional boundary between on-premises appliance vendors and SaaS platform providers.
- Public Cloud:Multi-tenant infrastructure delivers elastic compute for seasonal sensor deployments without capital expenditure. Smart city procurement offices in South Korea's Sejong cluster favor operational expenditure models with guaranteed uptime SLAs over perpetual licenses. Public cloud retains volume leadership; hybrid cloud holds the steepest expansion curve.
- Private Cloud:Dedicated tenant isolation satisfies GDPR data residency mandates in Germany's Rhine-Ruhr manufacturing belt. Heavy process industries embed automated anomaly detection to satisfy CNIL audit requirements for breach notification windows under 72 hours.
- Hybrid Cloud:Split orchestration layers place real-time control at the edge while archiving telemetry to centralized repositories. Precision agriculture cooperatives in the Midwestern United States deploy deterministic networking for autonomous irrigation systems.
- On-Premises:Air-gapped installations persist in defense-adjacent facilities and critical infrastructure with sovereign data requirements. Aging manufacturing plants with proprietary fieldbus standards resist seamless IP-based management overlays.
Public cloud retains volume leadership; hybrid cloud holds the steepest expansion curve.
Service Type:
Margin compression in commoditized maintenance contracts is pushing vendors toward outcome-based pricing for integrated managed services.
- Managed Services:Outsourced operational complexity dominates municipal smart city deployments across United States urban centers. FCC spectrum allocations for licensed cellular backhaul accelerate platform adoption where internal IT capacity is constrained.
- Professional Services:Bespoke integration for legacy OT-IT convergence commands premium billing rates in Germany's Industrie 4.0 corridors. Brownfield industrial sites require real-time device orchestration as a compliance-linked operational prerequisite.
- Consulting Services:Architecture advisory for multi-vendor interoperability testing consumes 12-18 month validation cycles before revenue recognition. ISO/IEC 27001 security framework compliance for cross-border deployments stalls procurement timelines.
- Maintenance Services:Break-fix and patch management contracts face displacement by predictive analytics bundled into managed service tiers. Edge gateway semiconductor supply concentration in East Asian foundries exposes spare parts availability to geopolitical friction.
Managed services capture the largest revenue share; professional services are expanding most quickly.
End User:
Application-specific latency thresholds and regulatory exposure create divergent customer lifetime value profiles across verticals.
- Manufacturing:Real-time device orchestration below 50 milliseconds enables precision robotics in Germany's Ruhr region microservices deployments. Containerized network functions fragment traditional appliance lock-in by enabling modular control plane substitution.
- Healthcare:HIPAA compliance for connected medical devices demands encrypted telemetry pipelines with audit-grade logging. Remote patient monitoring networks require guaranteed availability SLAs that favor managed service procurement.
- Transportation:Fleet telematics and autonomous vehicle infrastructure rely on cellular backhaul reliability across interstate corridors. South Korean national digital twin initiatives for urban traffic create dedicated procurement channels for integrated suites.
- Smart Cities:Municipal buyers in Songdo and Sejong clusters displace perpetual licenses with operational expenditure models. LPWAN volume economics for rural asset tracking and utility metering drive high-volume sensor deployments.
Manufacturing leads current revenue capture; smart cities demonstrate the most rapid adoption acceleration.
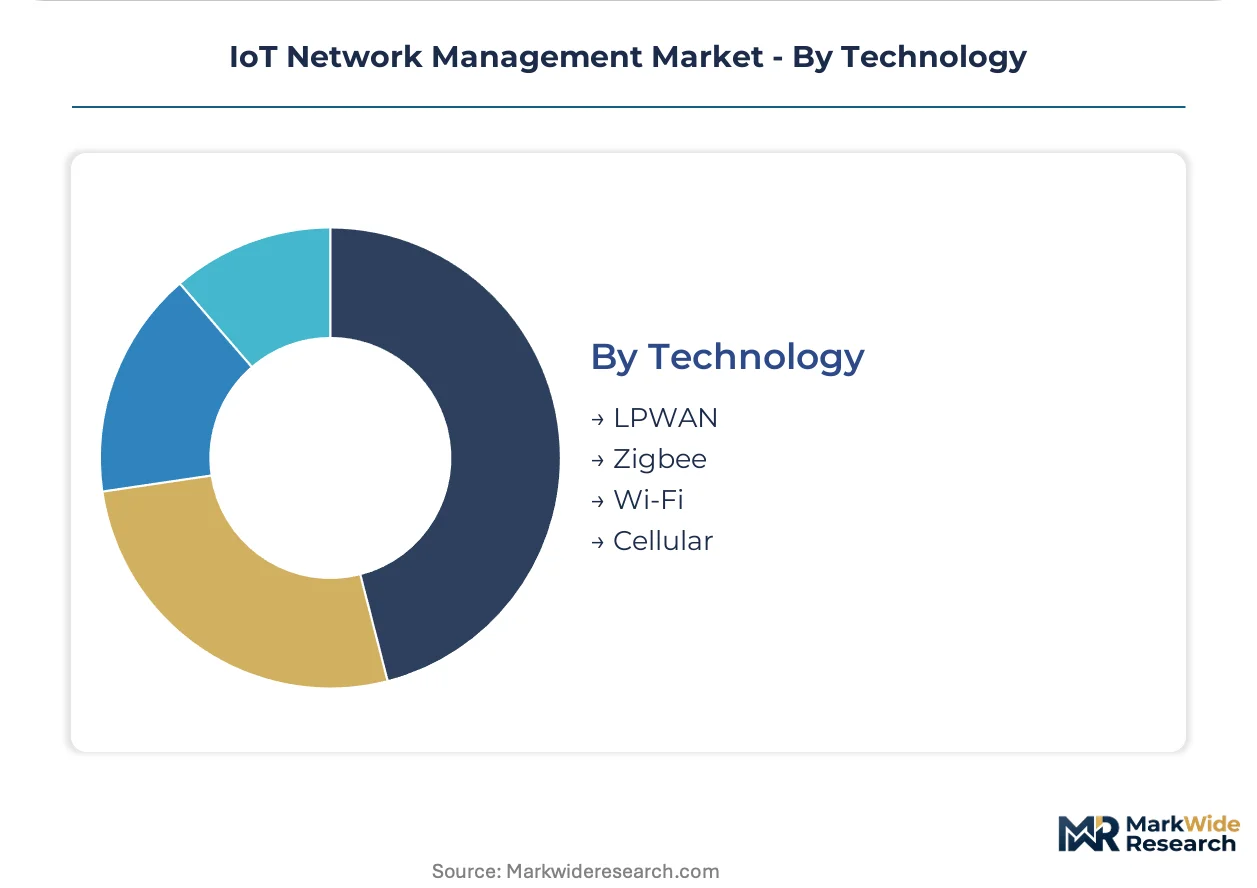
Technology:
Supply concentration in licensed spectrum chipsets is creating procurement bottlenecks that LPWAN alternatives exploit for cost-sensitive deployments.
- Cellular:Licensed spectrum reliability commands premium pricing for mission-critical industrial automation and healthcare telemetry. 5G backhaul integration compresses latency requirements below 50 milliseconds for time-critical applications.
- LPWAN:Unlicensed spectrum protocols enable high-volume, low-margin rural asset tracking and utility metering at extended range. Lightweight power requirements suit battery-constrained agricultural sensors in Midwestern farming cooperatives.
- Wi-Fi:High-throughput local area coverage dominates indoor manufacturing environments and healthcare campus networks. Existing enterprise infrastructure reduces incremental deployment costs for brownfield facility upgrades.
- Zigbee:Mesh networking protocols serve building automation and smart lighting with low-latency device-to-device communication. Proprietary stack fragmentation complicates multi-vendor interoperability testing for large-scale deployments.
Cellular technology maintains revenue dominance; LPWAN volume deployment is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany's manufacturing belt show the lowest price elasticity as compliance mandates override procurement budgets, while South Korean municipal offices and United States rural utilities exhibit acute sensitivity to total cost of ownership.
United States
FCC spectrum allocations for licensed cellular backhaul are accelerating smart city deployments across urban centers. Municipal procurement offices favor operational expenditure models with guaranteed uptime SLAs over perpetual licenses. Precision agriculture cooperatives in the Midwestern farming belt deploy deterministic networking for autonomous irrigation systems.
Germany
Industrie 4.0 compliance mandates require real-time device orchestration as an operational prerequisite in manufacturing corridors. GDPR data residency obligations impose architectural constraints that inflate platform deployment expenditures versus non-compliant architectures. Heavy process industries in the Rhine-Ruhr corridor prioritize platforms with built-in SIEM integration to satisfy CNIL audit requirements.
South Korea
National digital twin initiatives for urban traffic and energy grids are creating dedicated procurement channels for integrated network management suites. Smart city procurement offices in Songdo and Sejong clusters displace perpetual licenses with operational expenditure models. Edge computing integration with 5G backhaul is compressing latency requirements below 50 milliseconds for industrial automation.
Japan
METI industrial digitalization programs are pulling advanced network management platforms into brownfield manufacturing sites. Containerized network functions are fragmenting traditional appliance lock-in by enabling modular substitution of individual control plane components. Manufacturing facilities in the Chubu region around Nagoya deploy microservices-based management agents directly onto edge gateways.
France
CNIL-enforced breach notification windows under 72 hours mandate automated anomaly detection in network management stacks. Sector-specific national cybersecurity directives impose data residency obligations that directly influence platform architecture decisions. Industrial operators in the Île-de-France region embed predictive analytics to satisfy audit requirements for connected device ecosystems.
IoT Network Management Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the boundary between cloud-native platforms and legacy hardware incumbents collapsing as software-defined networking becomes standard procurement criteria. The competitive terrain sorts into three archetypes: infrastructure incumbents extending management capabilities from installed routing bases, hyperscale cloud providers integrating identity and security stacks, and industrial automation specialists bundling network visibility with operational technology expertise. Consolidation pressure manifests through strategic partnerships bridging IT-OT protocol gaps and portfolio diversification into edge analytics.
Within the infrastructure tier, Cisco Systems anchors competitive positioning through its installed base of routing infrastructure, while IBM Corporation exemplifies the predictive analytics convergence archetype. Microsoft Corporation occupies the platform layer by integrating enterprise identity frameworks. These three represent the dominant competitive vectors reshaping procurement criteria around unified control planes rather than discrete equipment categories.
| Leading Market Players |
|---|
| Cisco Systems |
| IBM Corporation |
| Microsoft Corporation |
| Hewlett Packard Enterprise |
| Oracle Corporation |
| Siemens AG |
| Honeywell International |
| Intel Corporation |
| SAP SE |
| Others |
Supply & Pricing Matrix
Long-term managed service contracts with guaranteed uptime SLAs lock in both supply access and price visibility for municipal buyers across South Korea's Sejong cluster and United States urban centers, compressing upfront revenue recognition while elongating customer lifetime value horizons through predictable operational expenditure models.
Pricing Analysis
Managed service renewals and edge gateway maintenance contracts drive lifetime value as perpetual license purchases face displacement. Pricing stratifies across premium cellular backhaul tiers for mission-critical industrial automation, standard hybrid cloud deployments for mid-market manufacturing, and economy LPWAN protocols for rural utility metering. Cost compression in commoditized maintenance tiers is intensifying because predictive analytics bundles are absorbing break-fix contracts. Municipal smart city offices exhibit acute price sensitivity versus Germany's Industrie 4.0 manufacturing corridors where compliance mandates override procurement budgets.
Supply Chain Analysis
Strait of Malacca transit for semiconductor fabrication equipment underwrites edge gateway chipset availability, exposing procurement timelines to geopolitical friction. Supply concentrates in Taiwan and South Korea for advanced node semiconductors, with secondary sourcing from United States fabs for sovereign defense requirements. Raw material dependencies span silicon wafers, rare earth elements for RF components, and lithium-ion cells for battery-backed edge devices. Single-source vulnerability in East Asian foundries threatens spare parts availability. Distribution runs through authorized channel partners and direct OEM relationships for large-scale industrial deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined networking platforms are substituting for legacy hardware appliances, forcing incumbents to defend integrated control plane positions against cloud-native specialists and hyperscale platform providers.
For Market Incumbents: Fortify hybrid cloud orchestration capabilities through backward integration into edge gateway manufacturing, reducing exposure to East Asian semiconductor supply concentration. Deepen SIEM integration partnerships to satisfy CNIL audit requirements for breach notification windows under 72 hours in France's heavy process industries. For New Entrants and Emerging Players: Lead with containerized microservices architectures targeting precision agriculture cooperatives in the Midwestern United States, where deterministic networking requirements for autonomous irrigation systems remain underpenetrated by established vendors. Bundle network visibility tools with AI-driven predictive maintenance to capture greenfield deployment budgets. For Investors and Strategic Acquirers: Capital is best deployed toward industrial automation specialists with OT-IT protocol fluency and existing ISO/IEC 27001 certification, positioned to capture professional services expansion in Germany's brownfield manufacturing corridors. Monitor FCC spectrum allocation timelines as an inflection indicator for cellular IoT backhaul demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies Azure IoT with enterprise identity stacks for municipal buyers in Songdo. |
| Strategic Partnership | Bridges IT-OT protocol gaps for Industrie 4.0 compliance in Rhine-Ruhr corridors. |
| Acquisition of Specialist Firm | Captures predictive analytics capabilities for edge deployment in Japanese manufacturing. |
| Geographic Expansion | Establishes GDPR-compliant private cloud infrastructure for French data residency mandates. |
| Product Launch | Introduces LPWAN-optimized management agents for Midwestern agricultural sensor networks. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with IoT platform engineers, municipal procurement officers, industrial maintenance directors, and hyperscaler solution architects; and secondary validation against SEC filings, hyperscaler capex disclosures, FCC spectrum allocation records, and ETSI standardization documents. Bottom-up unit economics triangulated against top-down market sizing.
Across the projection horizon, the analytical framework modeled deployment architecture, service type, connectivity protocol, and end-use vertical segmentation dimensions. CAGRs derived from elasticity-adjusted adoption curves incorporating 5G backhaul deployment pace and Industrie 4.0 compliance mandate timelines. Edge computing latency thresholds and LPWAN volume economics served as industry-specific forecast inputs.
Underlying assumptions cover sustained FCC spectrum allocation stability and East Asian semiconductor supply continuity, with deviation risk concentrated in GDPR enforcement intensity and geopolitical friction affecting edge gateway chipset procurement. Practitioners should keep alternative scenarios live as regulatory interoperability mandates and sovereign data requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Global Embedded Security for Internet of Things Market
Internet of Things (IoT)
Global IoT in Warehouse Market
Internet of Things (IoT)
Global Internet of Things (IoT) Defence Market
Internet of Things (IoT)
Smart Sprinkler Controller Market
Internet of Things (IoT)
Global Open IoT Platform Market
Internet of Things (IoT)
Europe IoT Device Market
Internet of Things (IoT)
IoT Software Market
Internet of Things (IoT)
Massive IoT Market
Internet of Things (IoT)
IoT Communication Technologies Market
Internet of Things (IoT)
IoT Middleware Market
Internet of Things (IoT)
IoT Lpwans Market
Internet of Things (IoT)
Industrial Internet of Things (Iiot) Market
Internet of Things (IoT)
Global IoT Devices Market
Internet of Things (IoT)
Global Internet of Things (IoT) Software Market
Internet of Things (IoT)
IoT in Chemical Industry Market
Internet of Things (IoT)
Global IoT Battery Market