
 Global IoT in Warehouse Market | 2026-2036
Global IoT in Warehouse Market Size, Share, and Industry Trends Forecast 2026-2036
Global IoT in Warehouse Market Foresight
A capital-intensity divergence between cloud-native platform providers and hardware-centric automation vendors is rotating competitive dynamics toward software-defined warehouse operations. Microsoft Corporation leverages its Azure IoT stack to anchor enterprise deployments across multi-site distribution networks. Honeywell International sustains manufacturing scale in environmental monitors and barcode scanning hardware. SSI Schaefer differentiates through integrated material handling systems that compete with pure-play software entrants.
IoT in warehouse denotes networked sensor arrays, autonomous mobile robots, and edge-computing gateways that collect real-time telemetry on inventory location, equipment health, and ambient conditions across storage facilities. These systems typically operate on sub-100-millisecond latency thresholds to enable automated picking, routing, and climate adjustment decisions. RFID Sensors and Smart Cameras dominate device-type revenue as fulfillment accuracy becomes a contractual requirement for third-party logistics providers. Wi-Fi 6 and LoRaWAN network technologies capture expanding share where dense device populations and extended range requirements coexist. Predictive Maintenance and Inventory Tracking use cases concentrate margin pools by reducing unplanned downtime and stockout penalties.
The EU AI Act and GDPR impose algorithmic transparency and data residency mandates on warehouse AI deployments across Europe. The FAA and OSHA in the United States regulate autonomous vehicle pathways and worker-safety sensor thresholds in shared human-robot environments. Stakeholders must monitor evolving liability frameworks for AI-driven inventory decisions and assess certification gaps before platform commitments.
Market Dynamics
Software-defined warehouse operations are compressing hardware margins and rotating vendor investment toward edge AI and real-time analytics platforms. This structural shift reconfigures competitive advantage around data orchestration rather than sensor manufacturing scale.
Growth Catalysts
- GDPR algorithmic transparency mandates:European fulfillment operators must deploy explainable AI for automated picking decisions, accelerating procurement of auditable IoT platforms.
- E-commerce fulfillment center expansion:Third-party logistics providers in Germany, the United States, and Japan contractually require sub-100-millisecond inventory tracking accuracy.
- Wi-Fi 6 and LoRaWAN convergence:Dense device populations in multi-site distribution networks now operate on unified connectivity stacks that reduce gateway infrastructure costs.
Market Restraints
- Silicon supply concentration:Edge-computing gateway production depends on concentrated semiconductor foundry capacity in East Asia, exposing lead time volatility.
- EU AI Act compliance friction:Algorithmic documentation requirements impose 12-18 month certification timelines for warehouse AI deployments across Europe.
- RFID tag cost floor:Passive sensor economics limit adoption in bulk commodity warehousing where unit-level tracking cannot recover hardware costs.
Strategic Opportunities
- India logistics modernization:PLI scheme incentives for electronics manufacturing are attracting IoT gateway assembly investments serving domestic warehousing demand.
- Predictive maintenance convergence:Vibration sensor data fused with thermal imaging enables failure prediction 72 hours ahead of autonomous mobile robot breakdowns.
- OSHA worker-safety sensor mandates:Shared human-robot environment regulations in the United States create mandatory upgrade cycles for legacy facilities.
Industry Challenges
- Edge AI talent scarcity:Warehouse operators compete with technology vendors for machine learning engineers capable of deploying sub-100-millisecond inference pipelines.
- Legacy WMS integration complexity:Proprietary warehouse management system APIs resist standardized data exchange with modern IoT telemetry platforms.
- FAA autonomous vehicle pathway certification:Indoor-outdoor autonomous mobile robot deployments face extended regulatory review timelines for shared airspace compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global IoT in Warehouse Market |
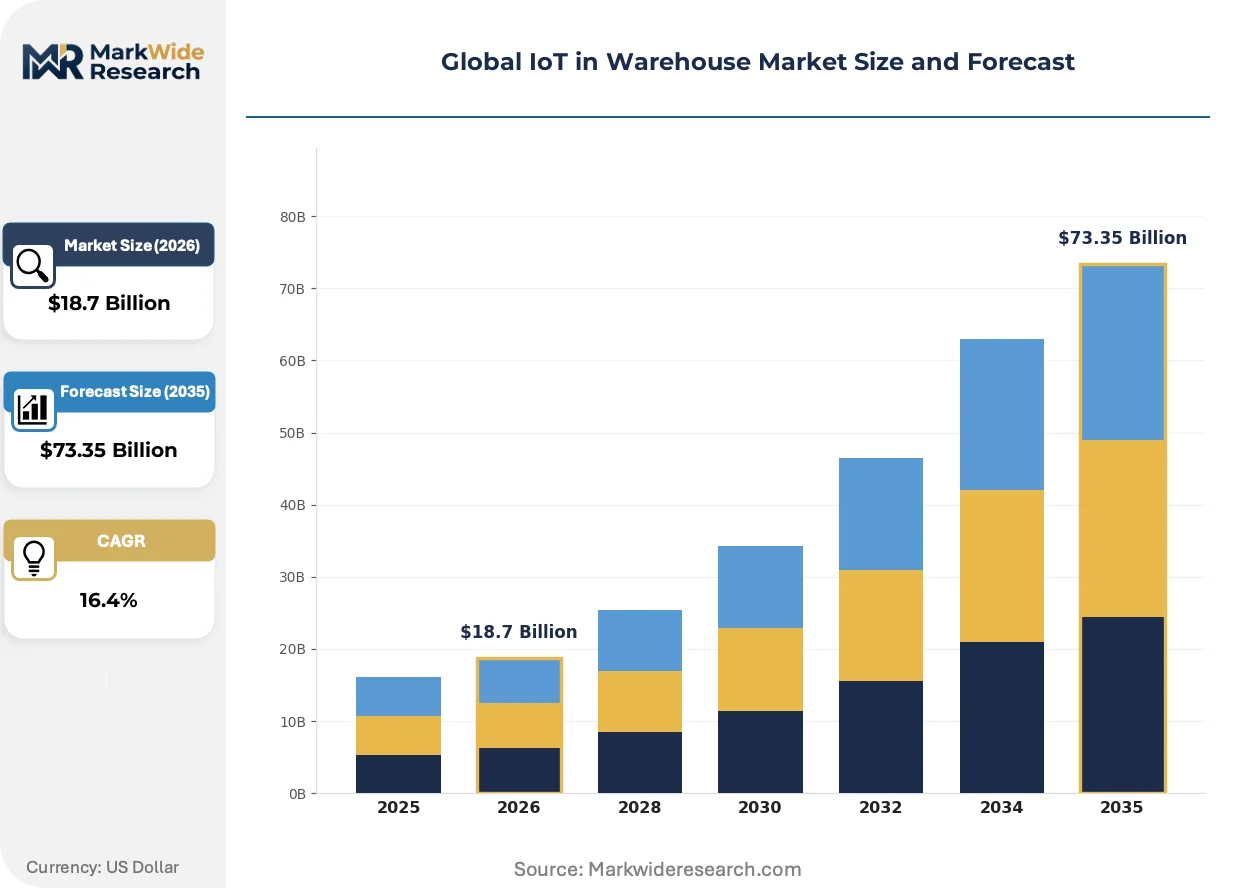
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
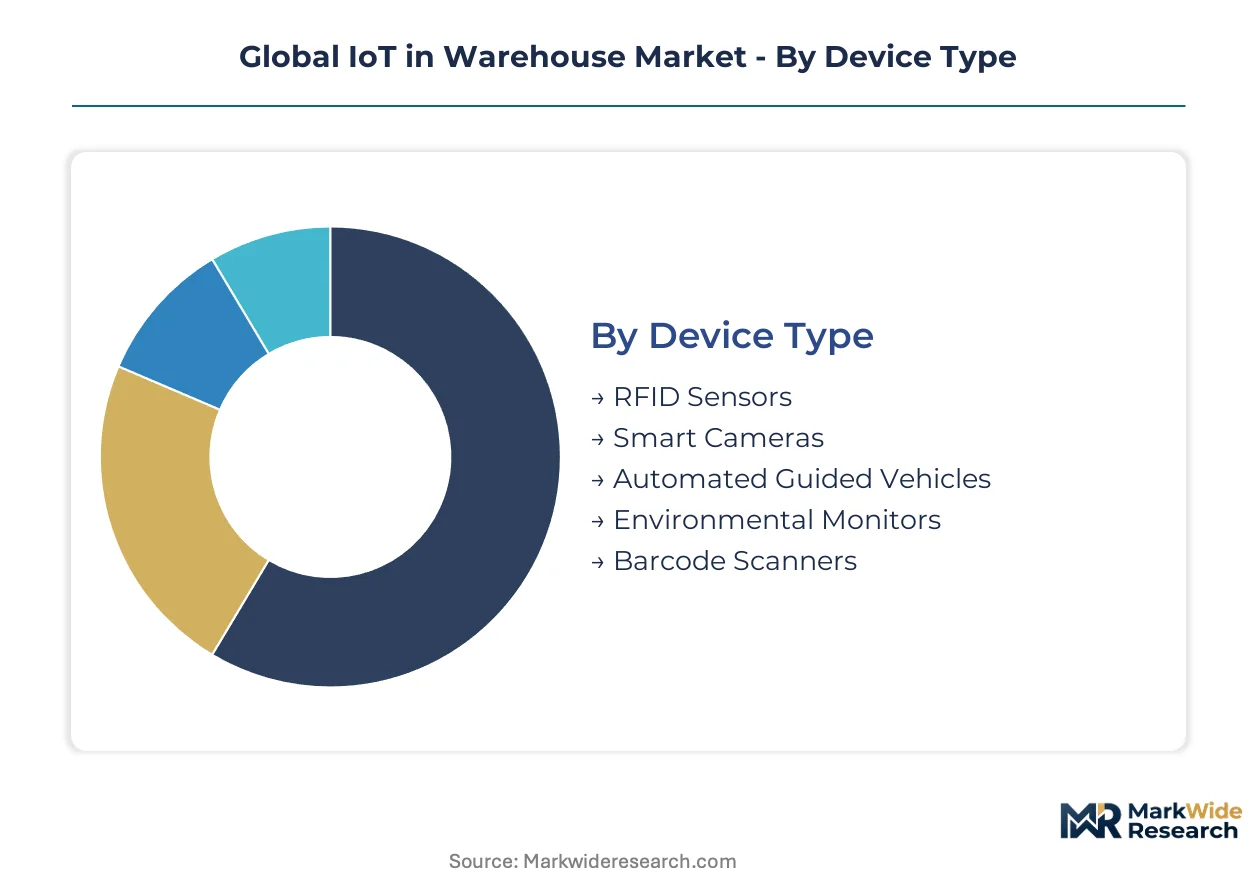
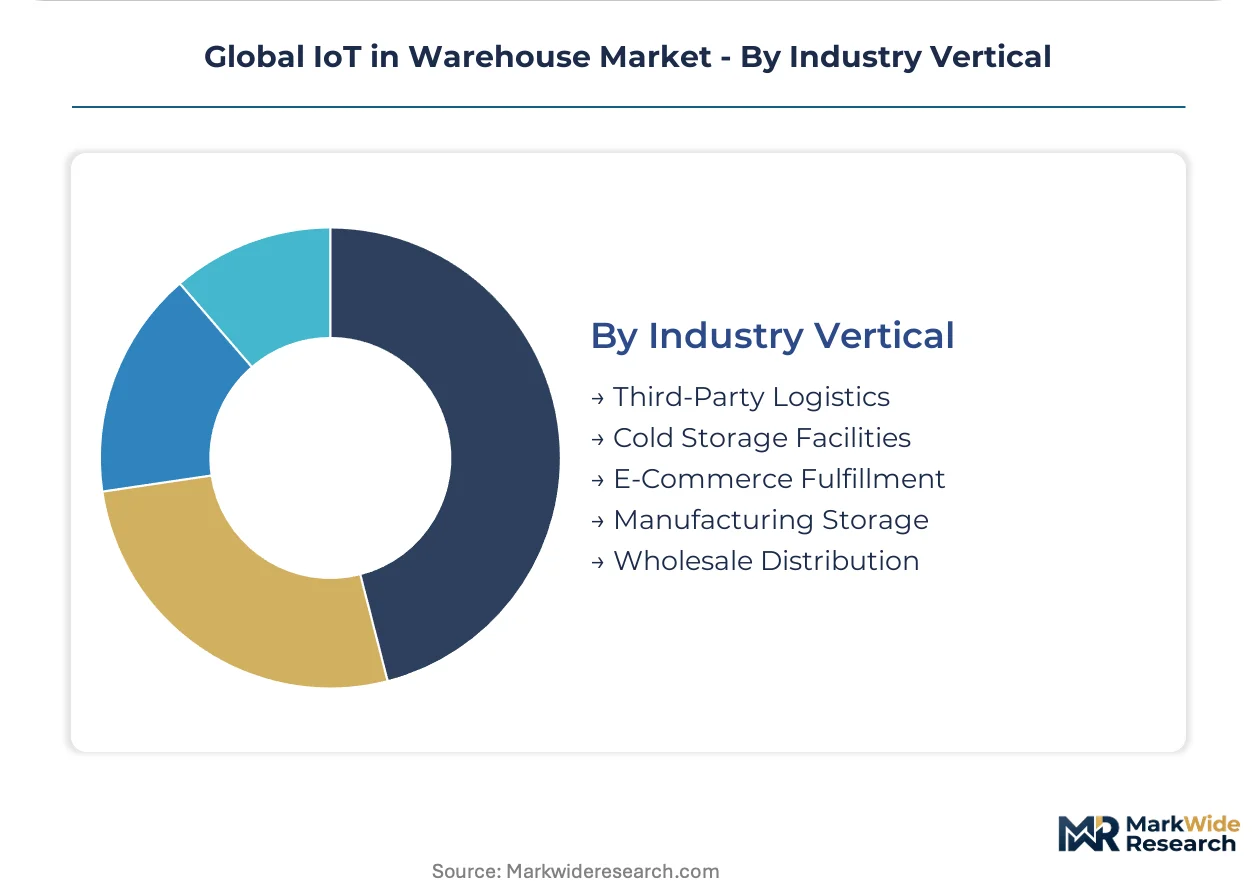
| Segmentation | Device Type: RFID Sensors, Smart Cameras, Automated Guided Vehicles, Environmental Monitors, Barcode Scanners Network Technology: LoRaWAN, NB-IoT, Zigbee, Wi-Fi 6, Bluetooth Low Energy Use Case: Inventory Tracking, Predictive Maintenance, Asset Management, Temperature Monitoring, Security Surveillance Industry Vertical: Third-Party Logistics, Cold Storage Facilities, E-Commerce Fulfillment, Manufacturing Storage, Wholesale Distribution |
| Companies Covered | Microsoft Corporation, NVIDIA Corporation, IBM Corporation, Dematic, Honeywell International, Intel Corporation, Oracle Corporation, SSI Schaefer, Amazon Web Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global IoT in Warehouse Market Shifts & Advancements
Real-time telemetry architectures are compressing decision latency from minutes to milliseconds, enabling autonomous warehouse operations that previously required human intervention. This shift demands synchronized advances in sensor miniaturization, edge processing, and regulatory alignment.
Ultra-wideband (UWB) positioning chips are miniaturizing to sub-5-millimeter form factors while maintaining centimeter-level location accuracy for high-density storage environments. Pharmaceutical cold chain operators in Switzerland and Germany are adopting these modules to track temperature-sensitive biologics through multi-zone facilities. The technology is miniaturizing cost structures that previously confined precision tracking to premium automotive applications.
The EU AI Act's risk-based classification system imposes conformity assessment requirements on automated inventory decision systems deployed across European distribution networks. Warehouse operators must maintain algorithmic audit trails and human oversight protocols for high-risk AI applications. German third-party logistics providers are restructuring procurement contracts to transfer liability compliance to platform vendors.
Outcome-based service agreements are displacing capital-intensive hardware purchases among mid-market warehouse operators in Japan and the United States. Equipment-as-a-service models bundle sensor hardware, connectivity, and predictive analytics into per-pallet pricing structures. This shift concentrates vendor risk around uptime guarantees while accelerating technology refresh cycles beyond traditional depreciation schedules.
Global IoT in Warehouse Market Segmentation
Warehouse IoT procurement decisions cluster around latency requirements, connectivity density, and regulatory compliance. Vendors structure platform architectures to capture margin pools that shift with each deployment's operational criticality and data sovereignty constraints.
Device Type:
Margin pools concentrate in sensor arrays that combine location telemetry with environmental monitoring, where bundled data streams command premium platform pricing.
- RFID Sensors:Passive and active radio-frequency identification tags transmit inventory location data through warehouse management system integrations. Third-party logistics providers in Germany deploy these at pallet and item level to meet contractual accuracy mandates for e-commerce fulfillment contracts.
- Smart Cameras:Computer-vision systems with edge-processing capabilities perform real-time object recognition and damage detection. Cold storage facilities in Japan utilize thermal-imaging variants to monitor perishable goods while maintaining FDA and local pharmaceutical regulator compliance for temperature documentation.
- Automated Guided Vehicles:Wire-guided and vision-navigation systems transport inventory across fixed routes in high-volume distribution centers.
- Environmental Monitors:Multi-sensor nodes track temperature, humidity, and particulate levels for quality assurance in climate-sensitive storage.
- Barcode Scanners:Laser and imager-based devices capture linear and 2D symbologies for legacy inventory reconciliation workflows.
RFID Sensors hold installed capacity. Smart Cameras are rotating up the share rankings.
Network Technology:
Connectivity selection hinges on device density, range requirements, and gateway infrastructure economics across multi-site deployments.
- LoRaWAN:Long-range, low-power wide-area networks enable kilometer-scale coverage with minimal gateway density for yard management and perimeter monitoring. Wholesale distribution operators in the United States deploy these for trailer tracking and outdoor asset location where cellular costs prove prohibitive.
- NB-IoT:Narrowband cellular technology provides licensed-spectrum reliability for critical sensor backhaul in facilities lacking private network infrastructure.
- Zigbee:Mesh-topology protocol supports dense indoor sensor populations with self-healing network resilience.
- Wi-Fi 6:High-throughput, low-latency standard accommodates bandwidth-intensive video streams and real-time control systems for autonomous mobile robots.
- Bluetooth Low Energy:Proximity-based protocol delivers sub-meter accuracy for indoor positioning in high-value inventory zones.
Wi-Fi 6 dominates new installation commitments. LoRaWAN is climbing the fastest in outdoor-yard extensions.
Use Case:
Application prioritization follows penalty structures—stockout fines and temperature excursions drive fastest procurement cycles.
- Inventory Tracking:Real-time location systems eliminate cycle-count labor and reduce shrinkage through continuous visibility. E-commerce fulfillment centers in the United States mandate sub-100-millisecond accuracy for same-day delivery service level agreements.
- Predictive Maintenance:Vibration, thermal, and acoustic sensors forecast equipment failures before operational disruption. Manufacturing storage facilities in Germany leverage these to minimize autonomous mobile robot downtime under EU AI Act documentation requirements.
- Asset Management:Lifecycle tracking of material handling equipment optimizes utilization rates and maintenance scheduling.
- Temperature Monitoring:Continuous cold chain documentation ensures pharmaceutical and food safety regulatory compliance.
- Security Surveillance:Perimeter and intrusion detection systems protect high-value inventory zones from unauthorized access.
Inventory Tracking commands the largest deployment base. Predictive Maintenance is gaining share fastest as equipment fleets expand.
Industry Vertical:
Vertical specialization determines sensor packaging, integration complexity, and compliance documentation intensity.
- Third-Party Logistics:Multi-tenant operators require flexible IoT platforms that adapt to diverse client requirements and contractual service levels. German providers face EU AI Act algorithmic transparency mandates for automated picking decisions.
- Cold Storage Facilities:Temperature-controlled warehouses demand redundant sensor networks with audit-trail documentation for pharmaceutical and food safety regulators.
- E-Commerce Fulfillment:High-velocity operations prioritize speed and accuracy over capital efficiency, driving dense sensor deployments.
- Manufacturing Storage:Raw materials and work-in-progress tracking integrates with production scheduling systems for just-in-time delivery.
- Wholesale Distribution:Pallet-level visibility supports bulk throughput operations with lower per-unit tracking economics.
Third-Party Logistics maintains the broadest installed base. E-Commerce Fulfillment is expanding most quickly as same-day delivery networks proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. German buyers absorb premium platform costs to meet EU AI Act compliance, while Indian operators prioritize gateway hardware economics under PLI scheme incentives. Japanese procurement concentrates on uptime-guaranteed service contracts.
United States
E-commerce fulfillment centers drive dense sensor deployments for same-day delivery accuracy. OSHA mandates worker-safety sensors in shared human-robot environments, accelerating facility upgrades. The Chicago-Milwaukee corridor hosts concentrated third-party logistics modernization programs.
Germany
Automotive and pharmaceutical storage facilities require sub-100-millisecond inventory tracking for just-in-time supply chains. The EU AI Act imposes algorithmic documentation requirements on automated picking systems. Bavarian distribution clusters near Munich and Nuremberg lead predictive maintenance adoption for autonomous mobile robot fleets.
Japan
Cold storage operators demand redundant temperature monitoring for pharmaceutical regulator compliance. METI efficiency standards push warehouse digitization in aging logistics infrastructure. The Osaka-Kobe industrial zone concentrates smart camera deployments for damage detection in high-value electronics handling.
India
Domestic e-commerce expansion creates demand for cost-optimized tracking systems in tier-2 and tier-3 cities. PLI scheme incentives attract IoT gateway assembly investments serving local warehousing demand. The Delhi-Mumbai Industrial Corridor anchors initial smart warehouse pilots for FMCG distribution.
Switzerland
Pharmaceutical cold chain operators adopt ultra-wideband positioning for biologics tracking through multi-zone facilities. Swissmedic documentation requirements shape sensor audit-trail specifications. Basel's pharmaceutical logistics cluster leads precision temperature monitoring deployments for temperature-sensitive therapeutics.
Global IoT in Warehouse Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with cloud-native platform providers commanding premium pricing against hardware-centric automation vendors. The market structure rewards data orchestration capabilities over sensor manufacturing scale. Three archetypes dominate: enterprise software stacks with IoT modules, integrated material handling system vendors, and pure-play edge analytics specialists. Competitive moves concentrate on strategic partnerships between connectivity providers and warehouse management system integrators, plus portfolio diversification into predictive maintenance software.
Within the integrated systems tier, Microsoft Corporation and SSI Schaefer occupy distinct positioning archetypes. Microsoft Corporation exemplifies the cloud-native platform approach, leveraging enterprise software relationships to anchor multi-site deployments. SSI Schaefer represents European engineering integration, bundling material handling hardware with proprietary control systems. Honeywell International sits between these models, maintaining sensor manufacturing scale while building software layer partnerships.
| Leading Market Players |
|---|
| Microsoft Corporation |
| NVIDIA Corporation |
| IBM Corporation |
| Dematic |
| Honeywell International |
| Intel Corporation |
| Oracle Corporation |
| SSI Schaefer |
| Amazon Web Services |
| Others |
Supply & Pricing Matrix
Equipment-as-a-service contracts lock in multi-year platform commitments while stabilizing unit economics for warehouse operators navigating volatile semiconductor input costs. These bundled agreements transfer hardware refresh risk to vendors and compress upfront capital requirements for mid-market buyers in Japan and the United States.
Pricing Analysis
After-sales predictive maintenance subscriptions now generate lifetime value multiples exceeding initial hardware margins for platform vendors. Three-tier pricing structure across premium, standard, and economy levels stratifies by algorithmic audit-trail depth required under EU AI Act compliance tiers. Cost compression in gateway hardware is intensifying because foundry capacity constraints in East Asia limit supply elasticity. Mid-market third-party logistics providers in India exhibit highest price sensitivity, while German automotive storage facilities absorb premium tiers to secure sub-100-millisecond latency guarantees.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for edge-computing processors that power real-time inventory analytics. China and Vietnam feed printed circuit board assembly and sensor module integration for cost-optimized gateway production. The supply chain draws from concentrated rare earth processing for magnet components in autonomous mobile robot motors. Single-source vulnerability in advanced node semiconductors exposes lead time volatility for AI inference chips. Distribution runs through direct vendor relationships with large third-party logistics operators and systems integrators serving multi-site fulfillment networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against pure-play edge analytics specialists that unbundle hardware-software integration and commoditize sensor manufacturing margins through API-first platforms.
For Market Incumbents: Secure algorithmic audit-trail capabilities to meet EU AI Act documentation mandates before procurement cycles lock in competitor platforms. Consolidate predictive maintenance software assets to offset hardware margin compression from outcome-based service contracts. Channel control through exclusive warehouse management system partnerships remains critical as legacy API integration complexity creates switching costs.
For New Entrants and Emerging Players: Predictive maintenance convergence gaps in tier-2 Indian logistics markets offer penetrable entry points where incumbent coverage remains thin. Target cold storage facilities in Switzerland requiring Swissmedic-compliant temperature documentation audit trails. A software-only deployment model bypassing hardware manufacturing capital requirements accelerates path to revenue.
For Investors and Strategic Acquirers: Edge AI engineering boutiques with sub-100-millisecond inference pipeline expertise represent priority acquisition targets as talent scarcity intensifies. Long-term viability hinges on platform vendors capturing data orchestration layers rather than sensor hardware commoditization. Watch FAA indoor-outdoor autonomous mobile robot certification timelines as inflection indicator for regulatory-constrained deployment velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Azure IoT stack anchoring multi-site distribution networks reduces WMS migration friction. |
| Strategic Partnership | Connectivity provider alliances with warehouse management system integrators compress deployment cycles. |
| Acquisition of Specialist Firm | Edge AI boutiques with inference pipeline expertise address talent scarcity constraining latency targets. |
| Geographic Expansion | Gateway assembly investments under India's PLI scheme capture domestic e-commerce logistics demand. |
| Product Launch | Ultra-wideband positioning modules miniaturized for pharmaceutical cold chain biologics tracking. |
Research Methodology
Cross-validation between primary interviews with warehouse operations directors and secondary regulatory filings anchors the qualitative findings on compliance-driven procurement patterns. Discussions with IoT platform engineers, third-party logistics procurement managers, and autonomous mobile robot fleet supervisors informed deployment constraint assessments. Bottom-up triangulation against customs data for sensor hardware trade flows and hyperscaler capex disclosures for cloud infrastructure investments validated market sizing. Top-down reconciliation with EU AI Act implementation timelines and OSHA rulemaking dockets ensured regulatory scenario alignment.
Sensitivity analysis across device-type adoption curves, network technology substitution rates, and vertical-specific compliance deadlines shaped the analytical framework. Segmentation dimensions modeled include connectivity protocol, latency requirement tier, regulatory jurisdiction cluster, and facility automation maturity level. CAGRs were derived from logistic diffusion curves fitted to historical deployment velocities and policy-mandated upgrade cycles. Forecast inputs incorporated EU AI Act conformity assessment timeline distributions and Wi-Fi 6 infrastructure refresh patterns across multi-site distribution networks.
Forecasts assume regulatory continuity in EU AI Act enforcement and OSHA worker-safety sensor mandates; material policy shifts would require re-modeling deployment acceleration scenarios. Semiconductor foundry capacity constraints and FAA autonomous vehicle pathway certification bottlenecks represent specific revision triggers. Recalibration cycles align with material shifts in e-commerce fulfillment service level agreement structures and algorithmic transparency enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Non-Terrestrial IoT Gateway Hardware and Software Market
Internet of Things (IoT)
Internet of Things (IoT) in Utilities Market
Internet of Things (IoT)
IoT for Cold Chain Monitoring Market
Internet of Things (IoT)
IoT Device Management Platform Market
Internet of Things (IoT)
Europe IoT Market
Internet of Things (IoT)
IoT Connected Machines Market
Internet of Things (IoT)
IoT Integration Market
Internet of Things (IoT)
Smart Tracker Market
Internet of Things (IoT)
Cellular IoT Module Market
Internet of Things (IoT)
5G IIOT Market
Internet of Things (IoT)
Satellite IoT Market
Internet of Things (IoT)
IOT in Aviation Market
Internet of Things (IoT)
Internet of Things (IoT) Market
Internet of Things (IoT)
Internet of Everything Market
Internet of Things (IoT)
Global IOT Gateway Market
Internet of Things (IoT)
North America Industrial IoT Market