
 Global Internet of Things Technology Market | 2026-2036
Global Internet of Things Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Global Internet of Things Technology Market Foresight
The EU Green Deal is hardening carbon-accounting requirements for connected infrastructure across European industrial zones. Intel Corporation leverages its foundry scale to supply low-power silicon for edge-node deployments. Qualcomm Technologies anchors cellular IoT modem design through integrated RF front-end specialization. Texas Instruments competes on precision analog-to-digital conversion for sensor interfaces in factory automation.
Internet of Things Technology encompasses networked sensor-actuator systems, embedded microcontrollers, wireless communication protocols, and cloud-native data platforms that enable machine-to-machine coordination without human intermediation. The technology stack processes telemetry at latency thresholds below ten milliseconds for closed-loop industrial control. Cloud-based deployment captures the largest installed base as enterprises migrate legacy SCADA workloads. Edge computing represents the fastest-expanding segment because manufacturers require localized inference for predictive maintenance. Application enablement platforms concentrate margin pools by abstracting hardware complexity into subscription software layers.
FCC spectrum allocations in the United States shape unlicensed-band availability for IoT radio modules, while ETSI harmonization across Europe reduces cross-border certification friction for device vendors. China's MIIT enforces domestic cryptography standards that condition market access for foreign connectivity chipsets. Stakeholders must monitor evolving radio-frequency regulations and data-sovereignty mandates to align product roadmaps with jurisdictional compliance architectures.
Market Dynamics
The EU Green Deal's carbon-accounting mandates are compressing deployment timelines for sensor-actuator networks across European industrial zones, forcing operators to accelerate procurement of telemetry infrastructure that can deliver sub-ten-millisecond latency for closed-loop control.
Growth Catalysts
- EU Green Deal compliance deadlines:German smart building operators are expanding sensor deployments to meet hardened carbon-accounting requirements for connected infrastructure.
- Edge computing architectures:South Korean manufacturing conglomerates are modernizing plant floors with localized inference capabilities for predictive maintenance workloads.
- FCC spectrum allocations:United States unlicensed-band availability for IoT radio modules is enabling denser device deployments without licensed-fee burdens.
Market Restraints
- MIIT cryptography mandates:China's domestic standards condition market access for foreign connectivity chipsets, creating regulatory friction for non-domestic vendors.
- Analog-to-digital precision costs:Factory automation sensor interfaces require high-precision conversion components that carry premium input pricing.
- Cloud migration inertia:Legacy SCADA workload transitions face integration complexity with brownfield control systems.
Strategic Opportunities
- ETSI harmonization:Cross-border certification friction reduction across Europe creates expansion pathways for device vendors seeking multi-country scale.
- Application enablement platforms:Subscription software layers abstracting hardware complexity concentrate margin pools for platform operators.
- Data sovereignty architectures:Jurisdictional compliance requirements are driving demand for region-specific cloud-native data platforms.
Industry Challenges
- RF regulatory fragmentation:Evolving radio-frequency allocations across multiple jurisdictions force product roadmap bifurcation.
- Embedded systems talent scarcity:Shortage of engineers proficient in wireless protocol stacks and real-time operating systems constrains deployment velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Internet of Things Technology Market |
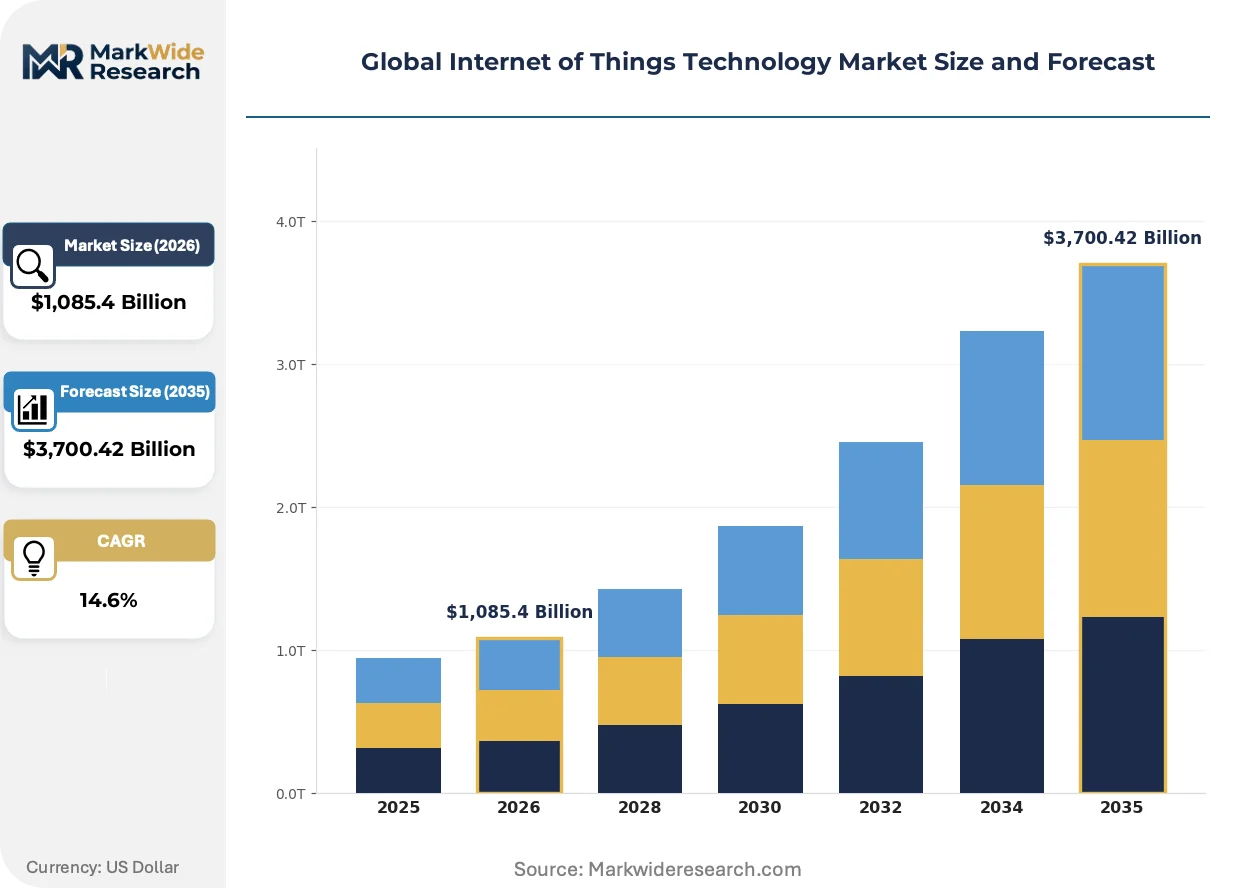
| Market Size in 2026 | $1,085.4 Billion |
| Market Size in 2035 | $3,700.42 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing, Fog Computing Solution Offering: Device Management, Data Analytics, Connectivity Management, Security, Application Enablement Use Case: Smart Cities, Precision Agriculture, Industrial Automation, Connected Vehicles, Energy Management End User Industry: Manufacturing, Transportation, Agriculture, Utilities, Smart Buildings |
| Companies Covered | Intel Corporation, Qualcomm Technologies, Texas Instruments, Cisco Systems, IBM, Microsoft, Amazon Web Services, STMicroelectronics, Huawei Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Internet of Things Technology Market Shifts & Advancements
Three distinct vectors are reshaping competitive positioning in connected infrastructure: silicon specialization for edge-node power constraints, regulatory harmonization creating cross-border scale economies, and procurement model evolution toward subscription-based platform abstraction.
Ultra-low-power silicon designs are expanding into telemetry nodes that must operate on harvested energy or decade-long battery lifecycles. Industrial operators in Germany and South Korea are adopting these architectures at accelerated pace to satisfy EU Green Deal carbon-accounting mandates. The technology is expanding into predictive maintenance applications that previously required wired power infrastructure.
REACH and RoHS substance restrictions are tightening material compliance requirements for IoT device manufacturing. Component suppliers must now certify against restricted substance lists that cover the full bill of materials for radio modules and sensor housings. European industrial zones face the steepest compliance burden, with vendors reconfiguring supply chains to maintain CE marking eligibility.
Platform procurement is displacing discrete hardware purchasing for enterprise IoT deployments. Manufacturing conglomerates in South Korea now subscribe to application enablement layers rather than building in-house integration stacks. This behavioral shift concentrates vendor relationships and recurring revenue streams with platform operators who abstract underlying hardware complexity.
Global Internet of Things Technology Market Segmentation
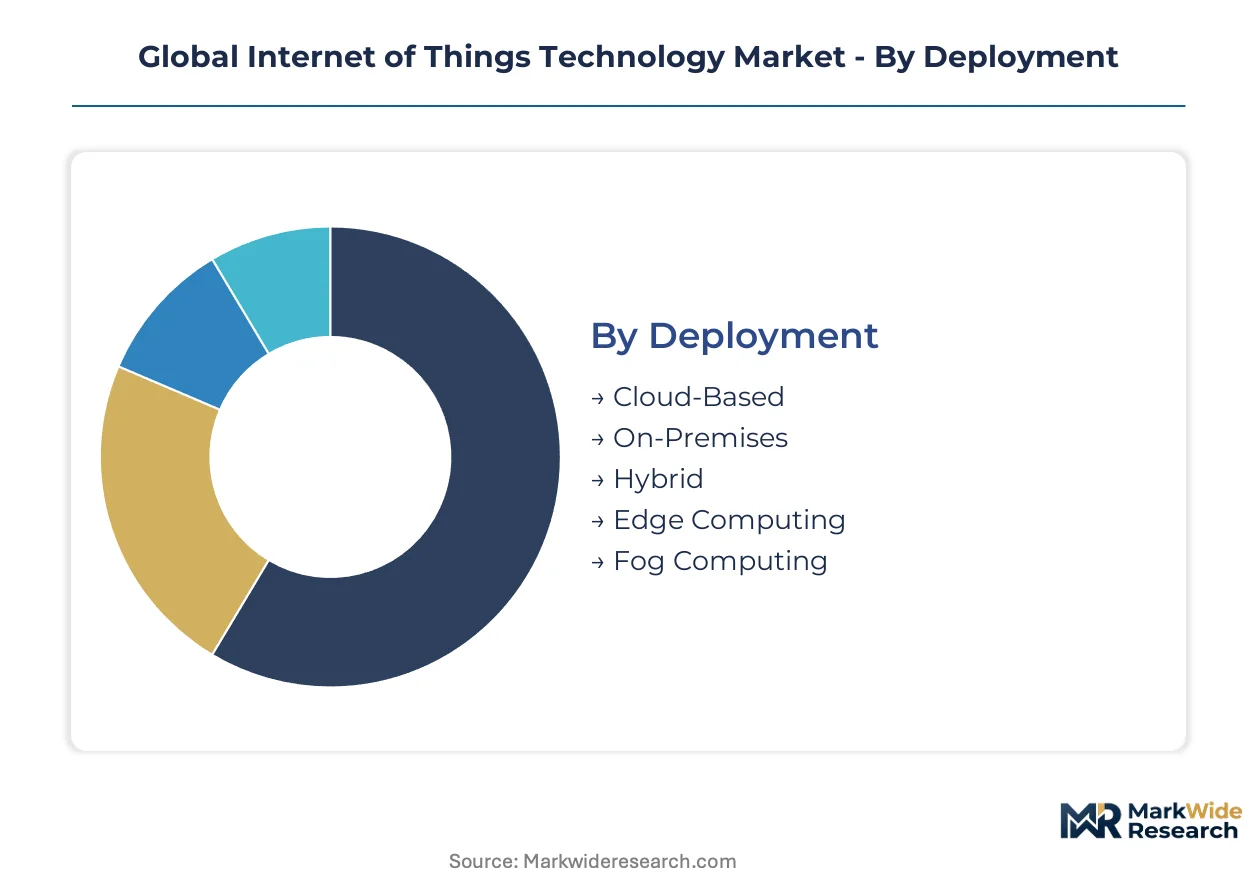
Deployment architecture determines latency thresholds and data sovereignty compliance for connected infrastructure. Solution abstraction layers concentrate vendor margins by masking hardware complexity. Use case specialization drives divergent radio protocol and power requirements across vertical applications.
Deployment:
Latency tolerance and data gravity dictate architectural selection across industrial control environments.
- Cloud-Based:Centralized telemetry processing supports enterprise SCADA migration workloads with elastic compute scaling. German smart building operators leverage cloud-native platforms to aggregate carbon-accounting telemetry across distributed portfolios under EU Green Deal mandates.
- Edge Computing:Localized inference nodes process sensor streams below ten-millisecond thresholds for closed-loop factory automation. South Korean manufacturing conglomerates deploy edge architectures at accelerated pace to enable predictive maintenance without cloud round-trip latency.
- On-Premises:Air-gapped data processing satisfies critical infrastructure cybersecurity requirements in utility and defense applications.
- Hybrid:Tiered processing splits telemetry between local filtering and cloud aggregation for bandwidth-constrained deployments.
- Fog Computing:Distributed compute nodes between edge and cloud enable collaborative processing across geographically dispersed sensor networks.
Cloud-based deployment leads on scale; edge computing leads on momentum.
Solution Offering:
Platform abstraction layers convert hardware procurement into recurring subscription relationships.
- Application Enablement:Middleware platforms abstract protocol translation and device onboarding into standardized APIs. Manufacturing conglomerates in South Korea subscribe to these layers rather than building in-house integration stacks, concentrating vendor relationships with platform operators.
- Device Management:Lifecycle orchestration tools handle firmware updates, certificate rotation, and anomaly detection across heterogeneous sensor fleets. German industrial zones deploy these capabilities to maintain CE marking eligibility under tightening REACH substance-tracking requirements.
- Data Analytics:Time-series processing and predictive modeling engines transform raw telemetry into operational intelligence.
- Connectivity Management:Multi-protocol orchestration balances cellular, LPWAN, and mesh radio costs across deployment footprints.
- Security:Cryptographic key management and zero-trust network segmentation address MIIT domestic standards in China and GDPR data-sovereignty mandates in Europe.
Application enablement leads on margin capture; device management leads on deployment velocity.
Use Case:
Vertical specialization forces divergent radio power budgets and regulatory certification pathways.
- Industrial Automation:Sensor-actuator networks coordinate machine tools and material handling systems with deterministic latency guarantees. FCC unlicensed-band allocations in the United States enable denser device deployments without licensed-fee burdens for factory floor modernization.
- Smart Cities:Municipal infrastructure networks integrate traffic signaling, environmental monitoring, and public safety telemetry. EU Green Deal carbon-accounting mandates compress deployment timelines for connected streetlight and building management systems across European urban zones.
- Precision Agriculture:Soil moisture and crop health sensors optimize irrigation and fertilization with satellite-linked telemetry.
- Connected Vehicles:V2X communication modules require automotive-grade reliability certification and spectrum harmonization across jurisdictions.
- Energy Management:Grid-edge sensors and distributed generation controllers balance load and renewable intermittency.
Industrial automation leads on revenue concentration; smart cities leads on policy tailwinds.
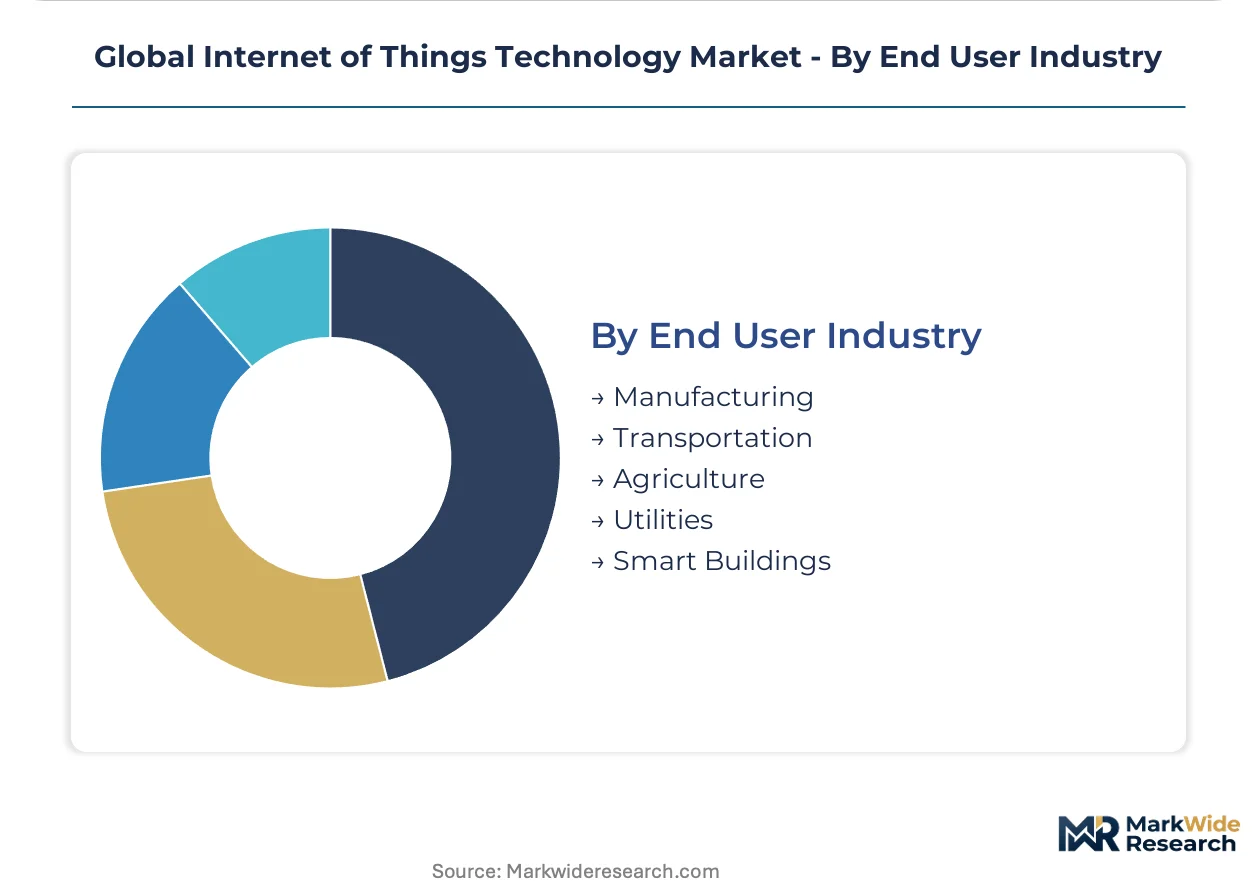
End User Industry:
Operational technology maturity shapes procurement sophistication and integration complexity tolerance.
- Manufacturing:Brownfield automation retrofits demand protocol gateways bridging legacy SCADA with modern IP-based sensor networks. South Korean conglomerates modernize plant floors with edge-native architectures that localize inference for equipment health monitoring.
- Smart Buildings:HVAC and lighting control systems integrate occupancy sensing with energy optimization algorithms. German operators expand sensor deployments to satisfy hardened EU Green Deal compliance timelines for commercial real estate carbon disclosure.
- Transportation:Fleet telematics and logistics tracking require cellular modem reliability across roaming agreements.
- Utilities:Critical infrastructure operators prioritize air-gapped or cryptographically segmented networks over cloud connectivity.
- Agriculture:Low-power wide-area networks extend coverage to remote cultivation zones with minimal infrastructure investment.
Manufacturing leads on technology absorption; smart buildings leads on regulatory compulsion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Embedded systems engineers cluster in Germany's industrial corridor, South Korea's semiconductor belt, and California's Bay Area, anchoring IoT innovation hubs that shape hardware roadmaps and deployment velocity across connected infrastructure markets.
United States
Cloud hyperscalers and enterprise software vendors drive demand for application enablement platforms that abstract sensor-network complexity. FCC spectrum allocations for unlicensed bands enable denser radio module deployments without licensed-fee burdens. The Bay Area concentrates venture-backed IoT startups developing edge-native architectures for industrial automation.
Germany
Smart building operators and automotive suppliers expand sensor deployments to satisfy hardened EU Green Deal carbon-accounting timelines. REACH and RoHS substance restrictions tighten material compliance requirements for radio modules and sensor housings. The Ruhr industrial corridor retrofits brownfield manufacturing facilities with predictive maintenance telemetry networks.
South Korea
Manufacturing conglomerates modernize plant floors with localized inference capabilities for equipment health monitoring. METI-aligned industrial policy accelerates edge computing procurement for semiconductor and display fabrication facilities. The Gyeonggi-do province hosts concentrated deployments of ultra-low-power silicon for decade-long battery lifecycle requirements.
China
Domestic demand for connected infrastructure scales under dual carbon goals and smart city mandates. MIIT cryptography standards condition market access for foreign connectivity chipsets, creating regulatory friction for non-domestic vendors. The Yangtze River Delta concentrates module manufacturing and protocol stack development for export markets.
Japan
Precision manufacturing and robotics integrators drive demand for deterministic latency guarantees in sensor-actuator networks. METI standardization efforts harmonize industrial IoT protocols across automotive and electronics supply chains. The Chubu region around Nagoya anchors deployments of predictive maintenance systems in automotive component fabrication.
Global Internet of Things Technology Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the silicon-to-software stack, creating a tiered structure where foundry-scale chipmakers, RF specialists, and cloud platform operators occupy distinct margin pools. The vendor base separates into three strategic archetypes: integrated device manufacturers with captive fabrication, fabless semiconductor designers leveraging external foundries, and platform operators monetizing subscription abstraction layers. Dominant competitive moves include strategic partnerships bridging hardware and cloud domains, and capacity expansion in edge-native silicon geometries.
Within the integrated device manufacturer tier, Intel Corporation exemplifies foundry-scale supply of low-power silicon for edge-node deployments. Qualcomm Technologies occupies a position anchoring cellular IoT modem design through RF front-end specialization. Texas Instruments represents the precision analog-to-digital conversion segment serving factory automation sensor interfaces.
| Leading Market Players |
|---|
| Intel Corporation |
| Qualcomm Technologies |
| Texas Instruments |
| Cisco Systems |
| IBM |
| Microsoft |
| Amazon Web Services |
| STMicroelectronics |
| Huawei Technologies |
| Others |
Supply & Pricing Matrix
Silicon wafer costs cascade through three pricing tiers for IoT radio modules, with premium sub-ten-millisecond edge nodes commanding markup multiples over standard cloud-tethered sensors as German smart building operators and South Korean manufacturers face divergent procurement budgets under EU Green Deal and METI-aligned compliance timelines.
Pricing Analysis
Bundled subscription platforms abstract hardware into recurring SaaS tiers, while unbundled per-unit transactional sales persist for brownfield SCADA retrofits. Price differentiation separates CE-marked precision analog components from uncertified commodity sensors. Cost compression in cellular modem tiers is intensifying because Qualcomm's RF front-end specialization and Intel's foundry scale are concentrating supply. Municipal smart city procurement teams exhibit highest price sensitivity; defense and utility buyers demonstrate lowest.
Supply Chain Analysis
Photoresist supply rests on Japanese specialty chemical producers, while advanced node silicon fabrication concentrates in Taiwan and South Korea. Raw material dependencies span rare earth elements for magnetics, high-purity silicon substrates, and lithium compounds for battery-backed telemetry nodes. Single-source vulnerability in 7nm and below edge-node chipsets threatens deployment velocity. Distribution runs through authorized component distributors serving OEMs and direct platform subscriptions for enterprise application enablement layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory tailwinds, with EU Green Deal carbon-accounting mandates hardening compliance timelines that compress procurement cycles for connected infrastructure across European industrial zones.
For Market Incumbents: Lock in sensor-actuator network deployments through captive edge-node silicon supply and CE marking certification investments that create switching costs. Defend against fabless RF specialists encroaching on cellular modem tiers by deepening foundry partnerships for low-power geometries. Prioritize backward integration into precision analog-to-digital conversion components serving German factory automation demand.
For New Entrants and Emerging Players: FCC unlicensed-band allocations in the United States open a window for radio module vendors targeting denser industrial automation deployments without licensed-fee burdens. White-space exists in application enablement platforms for mid-tier manufacturing conglomerates seeking alternatives to hyperscaler subscriptions. Penetrate through vertical-specific protocol gateways bridging legacy SCADA with IP-based sensor networks.
For Investors and Strategic Acquirers: Consolidation pressure builds where application enablement platform operators lack captive edge hardware supply. Long-term viability favors vendors controlling both silicon roadmaps and subscription software layers. Target acquisition archetypes include fabless RF specialists with MIIT-compliant cryptography stacks and regional platform operators with concentrated smart building customer bases in Germany. Watch ETSI harmonization progress as inflection indicator for cross-border certification scale economies.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Native Silicon Capacity Expansion | Intel's foundry investments address sub-ten-millisecond latency requirements for South Korean predictive maintenance workloads. |
| Application Enablement Platform Integration | Subscription abstraction layers concentrate recurring revenue with operators masking hardware complexity from German building managers. |
| RF Front-End Specialization Partnership | Qualcomm's cellular modem design anchors connectivity for FCC-unlicensed industrial automation deployments. |
| MIIT Cryptography Compliance Investment | Domestic standards adherence conditions market access for foreign chipset vendors serving China's smart city mandates. |
| ETSI Harmonization Certification Pathway | Cross-border friction reduction enables multi-country scale for device vendors targeting EU Green Deal compliance timelines. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with IoT platform engineers, semiconductor procurement leads at manufacturing conglomerates, smart building operators, and regulatory affairs specialists with secondary validation through FCC spectrum allocation records, ETSI harmonization documentation, MIIT cryptography standard filings, and hyperscaler capex disclosures. Bottom-up sensor deployment tallies and top-down platform revenue estimates undergo triangulation.
Granularity-level modeling distinguishes cloud-based from edge computing from on-premises deployment architectures, application enablement from device management solution offerings, and industrial automation from smart cities use cases across the projection horizon. CAGRs derive from segment-specific adoption curves calibrated against EU Green Deal compliance deadlines and METI-aligned industrial policy milestones. Forecast inputs incorporate REACH substance restriction compliance costs and FCC unlicensed-band availability expansions.
Revisions become necessary when MIIT cryptography mandates tighten market access conditions, ETSI harmonization stalls, or FCC spectrum reallocations disrupt unlicensed-band availability. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Global Internet of Things (IoT) Defence Market
Internet of Things (IoT)
IoT Application Development Services Market
Internet of Things (IoT)
IoT Platform Market
Internet of Things (IoT)
IoT Communication Technologies Market
Internet of Things (IoT)
Internet of Everything Market
Internet of Things (IoT)
Global IoT Managed Services Market
Internet of Things (IoT)
Industrial IoT Market
Internet of Things (IoT)
Satellite IoT Communication Market
Internet of Things (IoT)
IoT Cloud Platform Market
Internet of Things (IoT)
North America Narrowband-Internet of Things (NB-IoT) Market
Internet of Things (IoT)
IoT Microcontroller Market
Internet of Things (IoT)
M2M Communication Market
Internet of Things (IoT)
Europe IoT Services Market
Internet of Things (IoT)
Airport Internet of Things Market
Internet of Things (IoT)
Global IoT Battery Market
Internet of Things (IoT)
Cellular IoT Module Market