
 Global Internet of Behaviors Market | 2026-2036
Global Internet of Behaviors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Internet of Behaviors Market Foresight
Buyer concentration among financial services institutions is hardening as tier-one banks consolidate vendor relationships for fraud detection and authentication platforms. Google leverages its cloud infrastructure and search data reservoirs to dominate behavioral signal aggregation. IBM sustains enterprise credibility through Watson-powered risk analytics and regulatory consulting capacity. Meta Platforms competes in identity verification by integrating behavioral cues across its messaging and commerce ecosystems.
The Internet of Behaviors denotes the systematic capture, analysis, and operationalization of human behavioral data from digital and physical touchpoints to predict, influence, or secure outcomes; core technical specifications include real-time event streaming at sub-100-millisecond latency, multi-modal sensor fusion, and federated learning architectures that preserve data locality. Behavioral Analytics and Predictive Modeling within the Solution Offering dimension anchor current revenue pools because financial institutions pay premium rates for transaction anomaly detection. Cloud-Based deployment modes are expanding fastest as hyperscalers integrate IoB toolchains into existing SaaS marketplaces, while On-Premises installations retain share among government agencies with data sovereignty mandates.
The EU AI Act, GDPR, and the US FTC's commercial surveillance frameworks are reshaping product architecture by mandating explainability in automated profiling and restricting cross-border behavioral data flows. Japan's METI has issued soft-law guidance on human-centric AI that influences vendor design choices even without binding extraterritorial force. Stakeholders must monitor whether emerging sector-specific codes of conduct in Brazil and India will fragment compliance obligations or converge toward the Brussels effect.
Market Dynamics
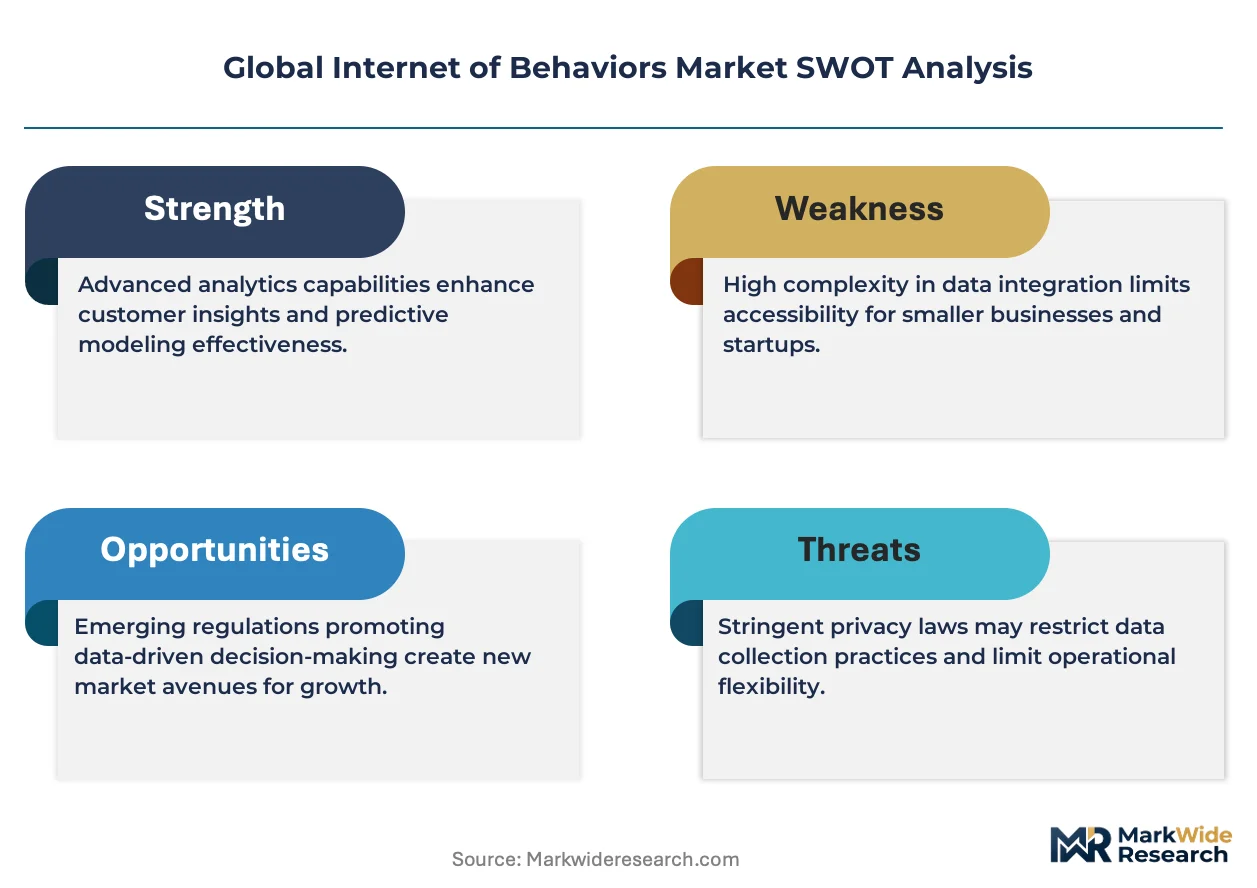
The Internet of Behaviors market is fundamentally restructuring around real-time behavioral signal processing as financial institutions demand sub-100-millisecond fraud detection latency. This technical threshold is compressing vendor consolidation timelines and forcing architectural bets on edge-cloud hybrid deployments.
Growth Catalysts
- Behavioral Biometrics Mandates:Financial services regulators in the United States are requiring multi-factor authentication that incorporates behavioral signals for high-risk transactions. Tier-one banks are consolidating vendor relationships to meet these standards.
- EU AI Act Compliance:Automated decision-making systems must now provide explainability for profiling outputs. Vendors are engineering federated learning architectures that preserve data locality while enabling cross-border analytics.
- Cloud-Native Infrastructure:Hyperscalers are embedding IoB toolchains into existing SaaS marketplaces. Enterprise procurement teams are accelerating cloud-based deployment decisions to reduce capital intensity.
Market Restraints
- Cross-Border Data Friction:GDPR restrictions on behavioral data transfers between the European Union and third countries are fragmenting operational architectures. Vendors must maintain redundant processing infrastructure.
- Sensor Fusion Complexity:Multi-modal data integration from biometric, device, and environmental sensors requires specialized engineering talent. Labor scarcity in signal processing and machine learning engineering is elevating implementation costs.
- Sovereignty Requirements:Government agencies in Germany, France, and Japan are mandating on-premises deployments for sensitive behavioral analytics. This limits addressable market for pure-cloud vendors.
Strategic Opportunities
- Brazilian Regulatory Convergence:Emerging sector-specific codes of conduct for artificial intelligence in Brazil may align with Brussels standards. Early compliance positioning creates first-mover advantage in Latin America's largest economy.
- Healthcare Behavioral Analytics:Patient adherence monitoring and clinical trial participant tracking represent underpenetrated applications. HIPAA-compliant architectures are being adapted from financial services fraud models.
- Edge-Device Inference:Convergence of lightweight neural networks with smartphone secure enclaves is enabling on-device behavioral analysis without cloud transmission. This addresses privacy concerns while reducing latency.
Industry Challenges
- Federated Learning Engineering Shortage:Distributed machine learning expertise remains scarce relative to demand. Vendors struggle to hire engineers capable of optimizing model performance across heterogeneous device fleets.
- Legacy System Integration:Core banking and government IT infrastructure built on decades-old architectures requires expensive middleware development. Behavioral analytics platforms must accommodate COBOL-era transaction processing systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Internet of Behaviors Market |
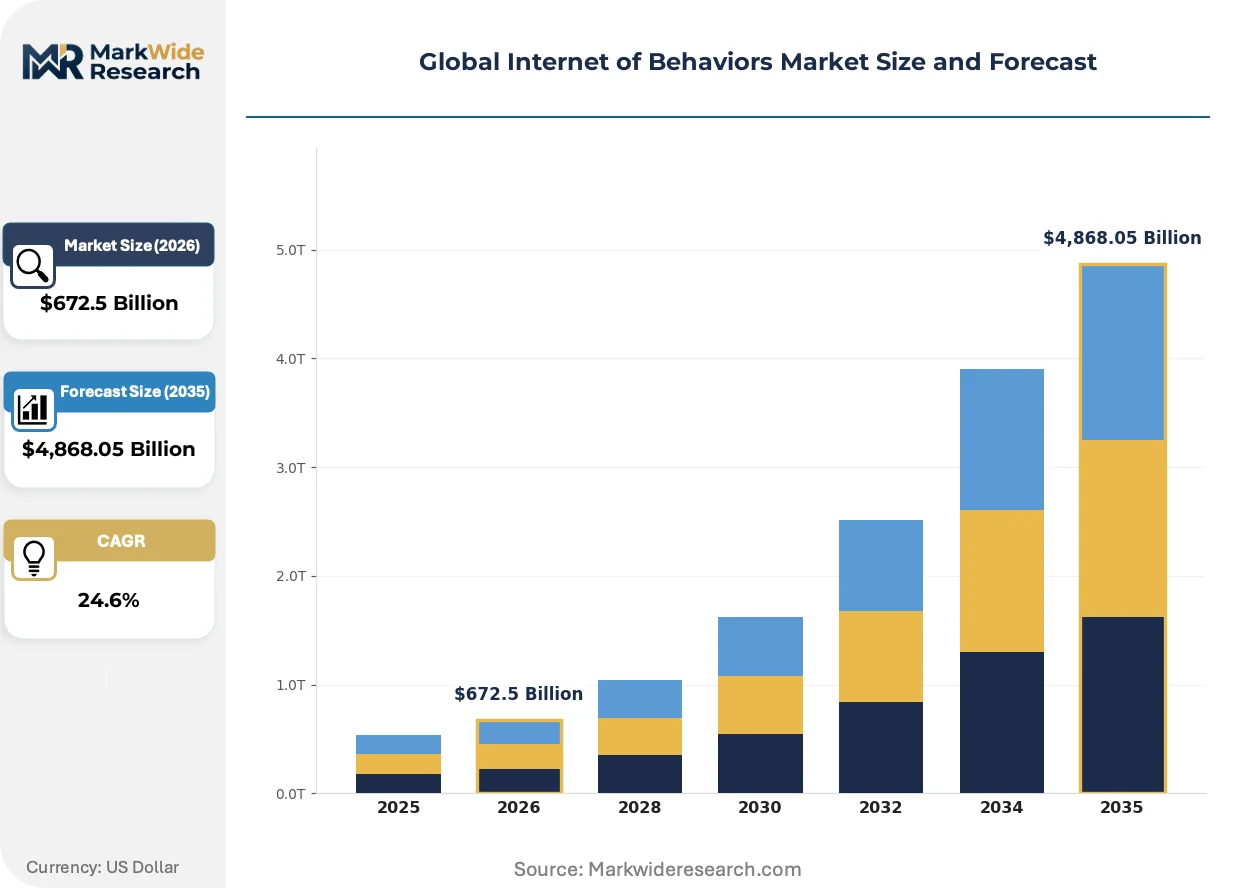
| Market Size in 2026 | $672.5 Billion |
| Market Size in 2035 | $4,868.05 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Offering: Behavioral Analytics, Predictive Modeling, Data Integration, User Profiling, Risk Assessment Application: Customer Experience Management, Fraud Detection, Workplace Safety, Health & Wellness, Supply Chain Optimization End User: Telecommunications, Financial Services, Retail Chains, Government Agencies, Education Providers Deployment Mode: Cloud-Based, On-Premises, Hybrid, Edge Computing, SaaS Models |
| Companies Covered | Google (Alphabet Inc.), Meta Platforms (Facebook), Amazon, Microsoft, IBM, Aware Inc., Trifacta (Alteryx), Vertica Systems (OpenText), NuData Security (Mastercard), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Internet of Behaviors Market Shifts & Advancements
Behavioral signal processing architectures are converging with privacy-preserving computation techniques. This fusion is redefining competitive differentiation around data minimization rather than data accumulation.
Edge-based behavioral inference is integrating on-device machine learning with secure enclave processing. Smartphone manufacturers are adopting this architecture for authentication and fraud prevention. Financial institutions are compressing vendor evaluation cycles to secure early access, which is integrating privacy-by-design as a default procurement requirement rather than optional feature.
The EU AI Act's risk-based classification system is mandating human oversight for high-risk behavioral profiling applications. Automated decision systems must now maintain audit trails for every inference. Financial services firms in Germany and France are restructuring product development workflows to embed compliance checkpoints, which is elevating regulatory consulting as a core vendor capability.
Enterprise procurement of behavioral analytics is consolidating around outcome-based performance contracts. Buyers are unbundling software licenses from implementation services and linking payments to fraud reduction metrics. This shift is most visible among United States-based credit card issuers, who are replacing perpetual licenses with annual recurring arrangements tied to detection accuracy thresholds.
Global Internet of Behaviors Market Segmentation
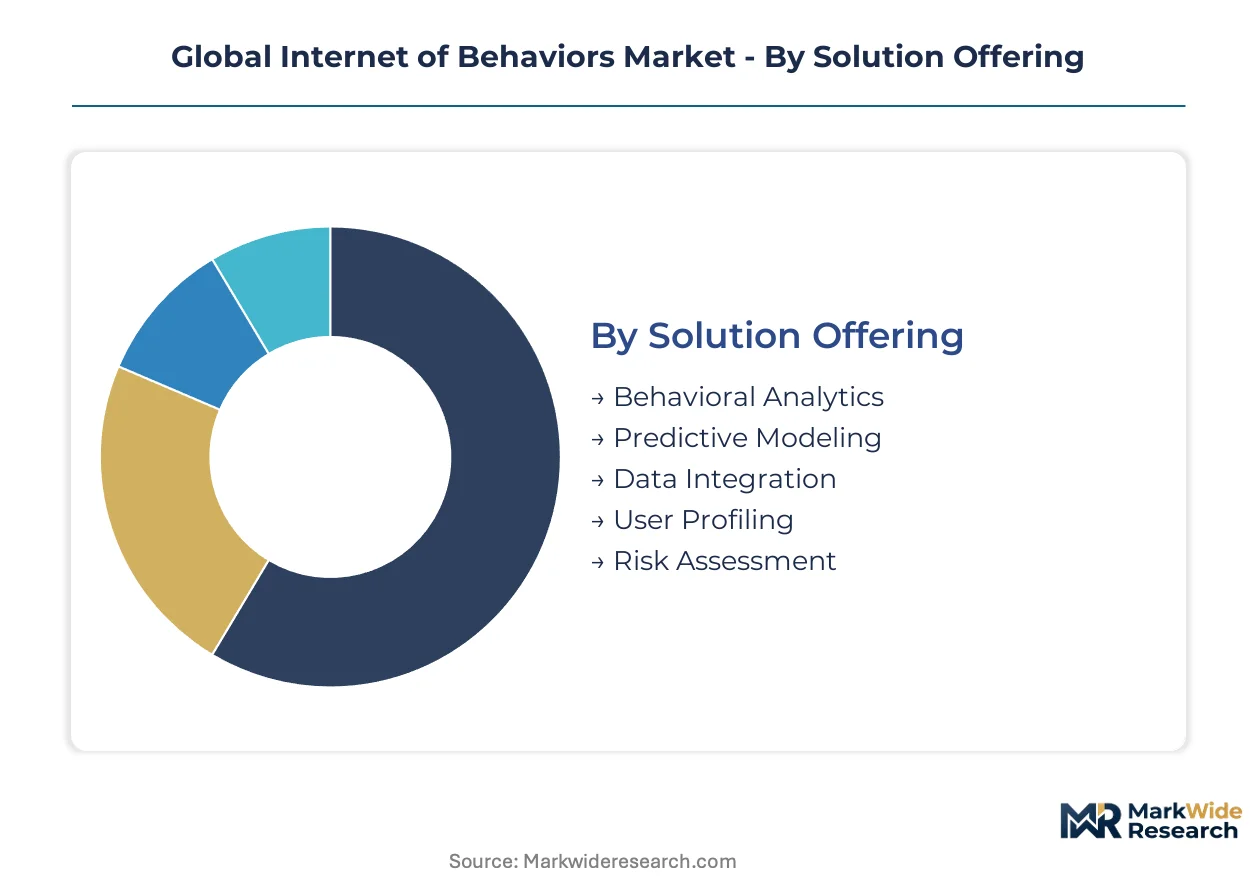
Segmentation in the Internet of Behaviors market reveals how behavioral data architectures map to distinct operational requirements. Each dimension exposes different integration depths, from embedded transaction monitoring to standalone analytics platforms.
Solution Offering:
Standalone behavioral engines dominate premium deployments, while embedded modules penetrate mass-market SaaS stacks through API-first delivery.
- Behavioral Analytics:Real-time event streaming platforms process multi-modal sensor inputs at sub-100-millisecond latency. Financial services institutions in the United States pay premium rates for transaction anomaly detection capabilities that satisfy regulatory mandates.
- Predictive Modeling:Machine learning frameworks forecast behavioral outcomes from historical pattern repositories. Tier-one banks consolidate vendor relationships around these tools to reduce false-positive rates in fraud detection workflows.
- Data Integration:Pipeline architectures normalize behavioral signals from disparate source systems. Demand concentrates among retail chains unifying online and in-store customer journey data.
- User Profiling:Identity resolution engines construct persistent behavioral identifiers across device graphs. Telecommunications carriers deploy these for churn prediction and personalized service recommendations.
- Risk Assessment:Scoring algorithms quantify behavioral deviation from established baselines. Government agencies in Germany mandate on-premises deployments for sensitive applications.
Volume placements concentrate in Behavioral Analytics; the faster expansion belongs to Predictive Modeling.
Application:
Cost tier stratification separates compliance-mandated deployments from discretionary optimization investments, with regulatory pressure driving premium spending.
- Customer Experience Management:Journey orchestration platforms personalize interactions based on real-time behavioral cues. Retail chains in Japan leverage METI human-centric AI guidance to design transparent profiling systems.
- Fraud Detection:Behavioral biometrics authenticate users through keystroke dynamics, mouse movements, and touchscreen gestures. United States credit card issuers link procurement contracts to detection accuracy thresholds.
- Workplace Safety:Computer vision systems monitor compliance with personal protective equipment protocols. Manufacturing facilities in Brazil pilot sector-specific AI codes of conduct ahead of formal regulation.
- Health & Wellness:Adherence tracking platforms monitor patient medication compliance through smartphone sensors. HIPAA-compliant architectures adapt financial services fraud models for clinical trial participant monitoring.
- Supply Chain Optimization:Driver behavior analytics reduce logistics risk through fatigue detection and route efficiency scoring. Fleet operators integrate these with existing telematics infrastructure.
Revenue concentration sits with Fraud Detection; Health & Wellness is climbing the fastest as healthcare providers digitize patient engagement.
End User:
Customer type differentiation separates regulated entities with compliance-driven procurement from commercial buyers optimizing operational metrics.
- Telecommunications:Network operators analyze subscriber behavioral patterns to predict churn and optimize spectrum allocation. Indian carriers face TRAI data localization requirements that shape vendor selection criteria.
- Financial Services:Banks, insurers, and payment processors deploy behavioral biometrics for authentication and transaction monitoring. EU AI Act explainability mandates restructure product development workflows for German and French institutions.
- Retail Chains:Merchants unify online and physical store behavioral data for inventory optimization and personalized marketing. Cloud-native deployments reduce capital intensity for mid-market operators.
- Government Agencies:Public sector entities mandate on-premises installations for sensitive behavioral analytics. French CNIL guidance influences procurement specifications for automated profiling systems.
- Education Providers:Institutions track student engagement patterns to predict at-risk learners and optimize curriculum delivery. Privacy concerns limit deployment scale relative to commercial sectors.
Procurement volume clusters in Financial Services; Education Providers are gaining share fastest as learning analytics platforms mature.
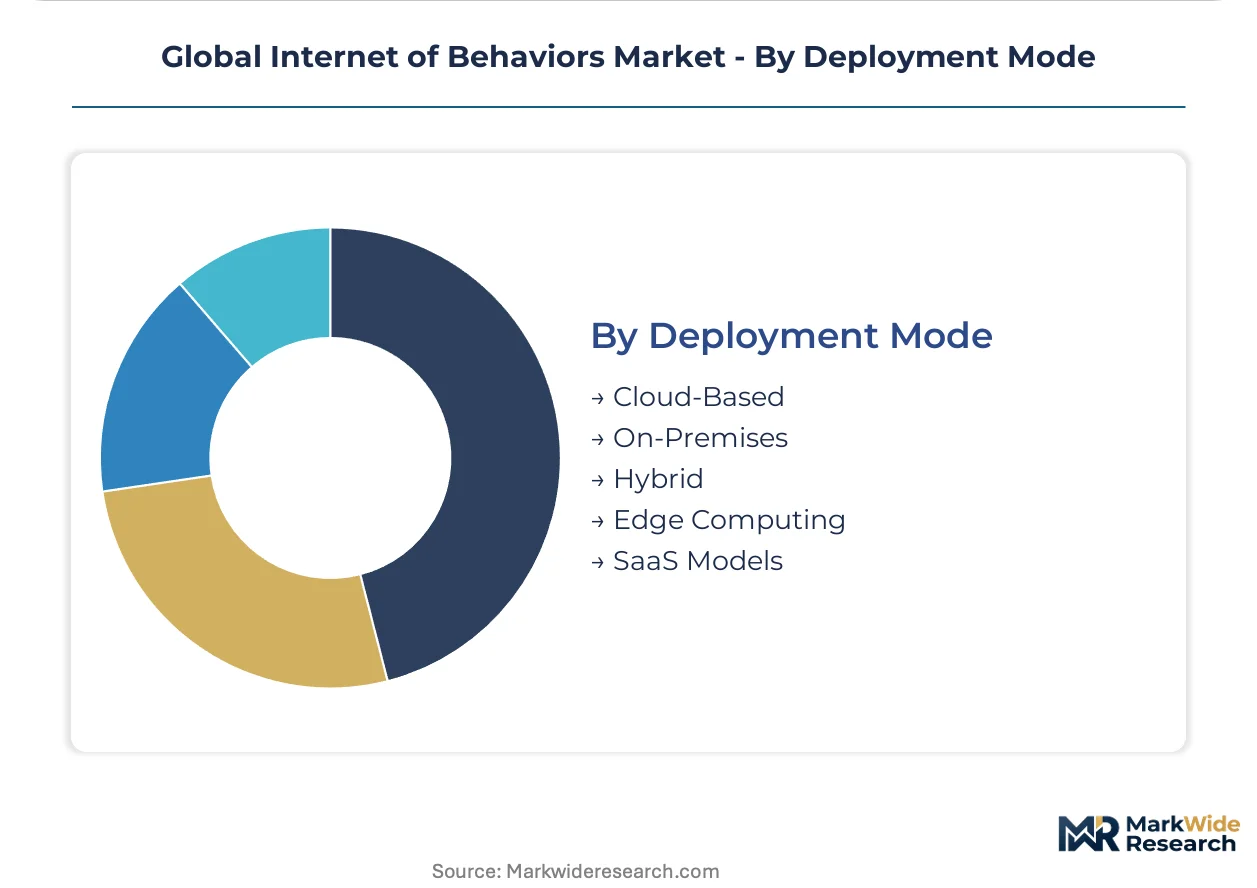
Deployment Mode:
Margin structure varies dramatically across deployment architectures, with hybrid and edge configurations commanding implementation premiums over standardized cloud offerings.
- Cloud-Based:Hyperscaler marketplaces embed IoB toolchains into existing SaaS procurement channels. Enterprise buyers accelerate these decisions to reduce data center capital expenditure.
- On-Premises:Sovereignty-compliant installations satisfy government mandates in Germany, France, and Japan. Redundant processing infrastructure elevates total cost of ownership.
- Hybrid:Edge-cloud orchestration balances latency-sensitive inference with centralized model training. Financial institutions demand sub-100-millisecond fraud detection response times.
- Edge Computing:On-device neural networks execute behavioral analysis within smartphone secure enclaves. This architecture addresses GDPR cross-border data transfer restrictions.
- SaaS Models:Outcome-based performance contracts link payments to fraud reduction metrics. United States credit card issuers replace perpetual licenses with annual recurring arrangements.
Deployment volume concentrates in Cloud-Based; Edge Computing shows the steepest expansion trajectory as privacy-preserving computation techniques mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Financial institutions in the United States are driving the steepest demand acceleration for behavioral biometrics and fraud detection platforms. Enterprise procurement concentrates among tier-one banks consolidating vendor relationships to meet regulatory mandates.
United States
Credit card issuers and payment processors anchor demand for sub-100-millisecond fraud detection latency. The FTC's commercial surveillance frameworks and state-level biometric privacy laws reshape product architecture requirements. New York and San Francisco financial technology clusters host the densest concentrations of behavioral analytics procurement teams.
Germany
Automotive and industrial conglomerates deploy behavioral analytics for supply chain workforce safety and predictive maintenance. The EU AI Act and Bundesdatenschutzgesetz mandate explainability in automated profiling systems. Munich and Stuttgart engineering hubs concentrate vendor development partnerships for sovereign-compliant on-premises installations.
Japan
Telecommunications carriers and retail chains adopt human-centric AI guidance for transparent customer profiling. METI soft-law standards influence design choices even without binding extraterritorial force. Tokyo and Osaka metropolitan areas concentrate enterprise digital identity investments and edge-device inference pilots.
Brazil
Manufacturing facilities and financial institutions pilot behavioral monitoring ahead of formal AI sector regulation. Emerging sector-specific codes of conduct may align with Brussels standards, creating first-mover positioning opportunities. São Paulo anchors Latin American procurement volume for fraud prevention platforms.
India
Telecommunications operators and digital payment platforms scale behavioral analytics under TRAI data localization requirements. RBI guidelines on digital lending and authentication drive compliance-driven procurement. Bangalore and Mumbai technology corridors concentrate engineering talent for federated learning and edge inference development.
Global Internet of Behaviors Market Competitive Landscape
United States technology conglomerates anchor the hyperscaler tier; European and Asian specialists hold positions in regulatory consulting and sovereign-compliant deployments. Market structure consolidates around cloud-native platform providers with embedded AI capabilities, while fragmented boutique vendors serve niche compliance requirements. Three archetypes dominate: infrastructure-integrated aggregators, regulatory-consulting hybrids, and edge-device inference specialists. Competitive moves concentrate on strategic partnerships with financial institutions and geographic expansion through compliance-first market entry.
Within the infrastructure-integrated tier, Google and Meta Platforms represent behavioral signal aggregation at scale, leveraging cloud infrastructure and messaging ecosystem data reservoirs respectively. IBM occupies a position bridging enterprise risk analytics with regulatory consulting capacity for EU AI Act compliance workflows. These three anchors exemplify how vendor differentiation increasingly depends on privacy-preserving computation architectures rather than raw data accumulation.
| Leading Market Players |
|---|
| Google (Alphabet Inc.) |
| Meta Platforms (Facebook) |
| Amazon |
| Microsoft |
| IBM |
| Aware Inc. |
| Trifacta (Alteryx) |
| Vertica Systems (OpenText) |
| NuData Security (Mastercard) |
| Others |
Supply & Pricing Matrix
EU AI Act explainability mandates gate qualified supply access for behavioral analytics platforms, restricting premium-tier pricing to vendors with federated learning architectures and audit-trail capabilities. Tier-one banks in the United States pay subscription premiums for sub-100-millisecond latency guarantees, while government agencies in Germany and France absorb elevated total cost of ownership for on-premises sovereignty-compliant installations.
Pricing Analysis
Volume placements concentrate in standardized SaaS tiers, while margin capture belongs to outcome-based performance contracts. Three-tier pricing structure across premium, standard, and economy levels separates latency-optimized fraud detection from basic behavioral profiling and open-source toolkit deployments. Pricing pressure stems from hyperscaler marketplace integration compressing standalone vendor margins. Mid-market retail chains exhibit highest price sensitivity; tier-one financial institutions prioritize detection accuracy over license cost.
Supply Chain Analysis
India's TRAI data localization rules and Brazil's emerging AI sector codes are reshaping sourcing decisions for behavioral data infrastructure. Engineering talent concentrates in the United States, India, and Germany for federated learning and edge inference development. Component dependencies include GPU clusters for model training, secure enclave processors for on-device analysis, and optical sensors for biometric capture. Single-source vulnerability runs through Taiwan semiconductor fabrication for edge inference chips. Distribution runs through hyperscaler marketplaces and direct enterprise sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Federated learning engineering scarcity props pricing for qualified behavioral analytics deployments. Capacity bottlenecks in distributed machine learning talent constrain vendor expansion timelines.
For Market Incumbents: Acquire specialized federated learning engineering teams to fortify EU AI Act compliance workflows against boutique regulatory consultants. Consolidate vendor relationships through outcome-based performance contracts that lock in tier-one bank procurement. Defend against hyperscaler marketplace encroachment by embedding compliance consulting into platform subscriptions. For New Entrants and Emerging Players: Mid-market healthcare providers in the United States represent an underserved buyer archetype adapting HIPAA-compliant architectures from financial fraud models. Brazilian manufacturing facilities piloting sector-specific AI codes of conduct ahead of formal regulation offer first-mover positioning. Channel partnerships with electronic health record vendors provide the most penetrable go-to-market path. For Investors and Strategic Acquirers: Tier-one bank consolidation of vendor relationships for fraud detection platforms is the leading indicator that horizontal platform plays are displacing point solutions. Long-term viability centers on privacy-preserving computation architectures rather than raw data accumulation. Acquisition targets should demonstrate edge-device inference capabilities and regulatory consulting capacity. Watch for hyperscaler marketplace embedding announcements as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Federated Learning Architecture Development | EU AI Act explainability mandates require distributed training that preserves data locality across German and French installations. |
| Edge-Device Inference Partnership | Smartphone secure enclave integration addresses GDPR cross-border transfer restrictions for European financial institutions. |
| Regulatory Consulting Capability Buildout | Bundled compliance workflows capture premium pricing from tier-one banks restructuring procurement around outcome-based contracts. |
| Healthcare Vertical Expansion | HIPAA-compliant behavioral monitoring adapts financial fraud models for patient adherence tracking in United States health systems. |
| Hyperscaler Marketplace Integration | Embedded IoB toolchains in cloud SaaS channels reduce customer acquisition costs for mid-market retail and telecommunications buyers. |
Research Methodology
Document review covered SEC filings from behavioral analytics vendors, EU AI Act implementation guidance, and TRAI data localization circulars, complemented by interviews with fraud detection executives at tier-one banks, regulatory affairs leads at cloud infrastructure providers, and procurement officers at United States credit card issuers. Secondary validation drew from FTC commercial surveillance framework documents, METI human-centric AI guidance, and RBI digital lending guidelines. Bottom-up deployment estimates triangulated against top-down market sizing across solution offerings and end-user verticals.
Segment-level outputs reflect modeling across solution offering, application, end user, and deployment mode dimensions, with additional granularity for regulatory framework clusters. CAGRs derive from historical trajectory analysis adjusted for mandate-driven procurement acceleration and technology diffusion curves. Forecast inputs incorporate latency requirement tightening at United States financial institutions and sovereign deployment mandates in Germany, France, and Japan.
Revisions become necessary when cross-border data transfer restrictions tighten beyond current GDPR frameworks or when edge-device inference capabilities commoditize faster than projected. Forecasts reflect assumptions about regulatory implementation timelines and engineering talent availability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Non-Terrestrial IoT Gateway Hardware and Software Market
Internet of Things (IoT)
Internet of Things (IoT) in Utilities Market
Internet of Things (IoT)
Marine Internet of Things Market
Internet of Things (IoT)
Asia-Pacific Massive IoT Market
Internet of Things (IoT)
Global IOT Connectivity Management Platform (CMP) Market
Internet of Things (IoT)
Global Pervasive Computing Technology Market
Internet of Things (IoT)
IoT in Chemical Industry Market
Internet of Things (IoT)
Bluetooth Smart Plugs Market
Internet of Things (IoT)
Internet of Things (IoT) in Manufacturing Market
Internet of Things (IoT)
IoT Development Kit Market
Internet of Things (IoT)
Global IoT Connectivity Market
Internet of Things (IoT)
Global IoT in Aerospace and Defense Market
Internet of Things (IoT)
Consumer Internet of Things (IoT) Market
Internet of Things (IoT)
Global IOT Gateway Market
Internet of Things (IoT)
IIOT Gateway for Utility Market
Internet of Things (IoT)
5G Internet of Things Market