
 Internet of Everything Market | 2026-2036
Internet of Everything Market Size, Share, and Industry Trends Forecast 2026-2036
Internet of Everything Market Intelligence
Asset-light network-as-a-service financing is narrowing the competitive field for legacy hardware vendors. Cisco Systems leverages its installed base of routing infrastructure to extend subscription-based IoE platforms. Huawei Technologies anchors its position through integrated silicon-to-cloud stacks across emerging markets. Microsoft competes by embedding IoE analytics within enterprise cloud contracts.
The Internet of Everything denotes the networked interconnection of people, processes, data, and things through embedded sensors, edge processors, and protocol stacks enabling real-time telemetry and automated actuation. Industrial Automation applications sustain premium margin pools where latency requirements below 10 milliseconds mandate edge-native architectures. Smart City deployments lead in absolute connection volume but operate on municipal procurement cycles that compress vendor margins. Cloud deployment models dominate enterprise budgets while Fog Computing segments capture specialized demand from utilities requiring localized failover.
The FCC in the United States governs spectrum allocation for unlicensed IoT bands, directly shaping device certification pathways and market access timelines. ETSI and the EU AI Act impose interoperability and algorithmic transparency mandates that elevate compliance costs for platform providers. Stakeholders must monitor how national spectrum auctions and cross-border data localization rules redistribute competitive advantage across vendor ecosystems.
Market Dynamics
Asset-light network-as-a-service financing is compressing capital deployment timelines for municipal infrastructure buyers while fragmenting vendor revenue recognition models across the Internet of Everything ecosystem.
Growth Catalysts
- EU AI Act compliance mandates:Algorithmic transparency requirements for connected systems are accelerating platform consolidation as buyers seek pre-certified vendors.
- Smart city sensor densification:Municipal procurement for traffic management and environmental monitoring is pulling edge-native architectures into standard RFP specifications.
- Industrial automation latency requirements:Sub-10 millisecond response thresholds are mandating fog computing deployments in German and US manufacturing clusters.
Market Restraints
- Silicon supply concentration:Edge processor fabrication depends on concentrated advanced node capacity in Taiwan and South Korea, exposing IoE hardware vendors to allocation risk.
- Cross-border data localization rules:China's PIPL and Russia's data sovereignty laws fragment cloud architecture economics for multinational platform operators.
- Radio spectrum auction costs:Unlicensed band congestion in dense urban deployments is forcing premium licensed spectrum commitments that erode municipal budget elasticity.
Strategic Opportunities
- India national broadband expansion:The BharatNet fiber backbone is creating first-mile infrastructure for rural IoE connectivity previously uneconomical for private capital.
- Digital twin convergence with physics engines:Real-time sensor telemetry fused with simulation software is opening predictive maintenance contracts in US utilities.
- Utility microgrid autonomy mandates:FERC Order 2222 in the United States is requiring distributed energy resource aggregation that favors localized edge control systems.
Industry Challenges
- Embedded systems security certification:IEC 62443 compliance timelines for industrial IoT devices average 14-18 months, delaying product launches.
- Legacy SCADA integration complexity:Brownfield manufacturing sites in Germany and Japan require protocol translation layers that inflate deployment costs.
- Edge AI talent scarcity:Shortage of engineers proficient in both embedded systems and machine learning model optimization is constraining R&D velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Internet of Everything Market |
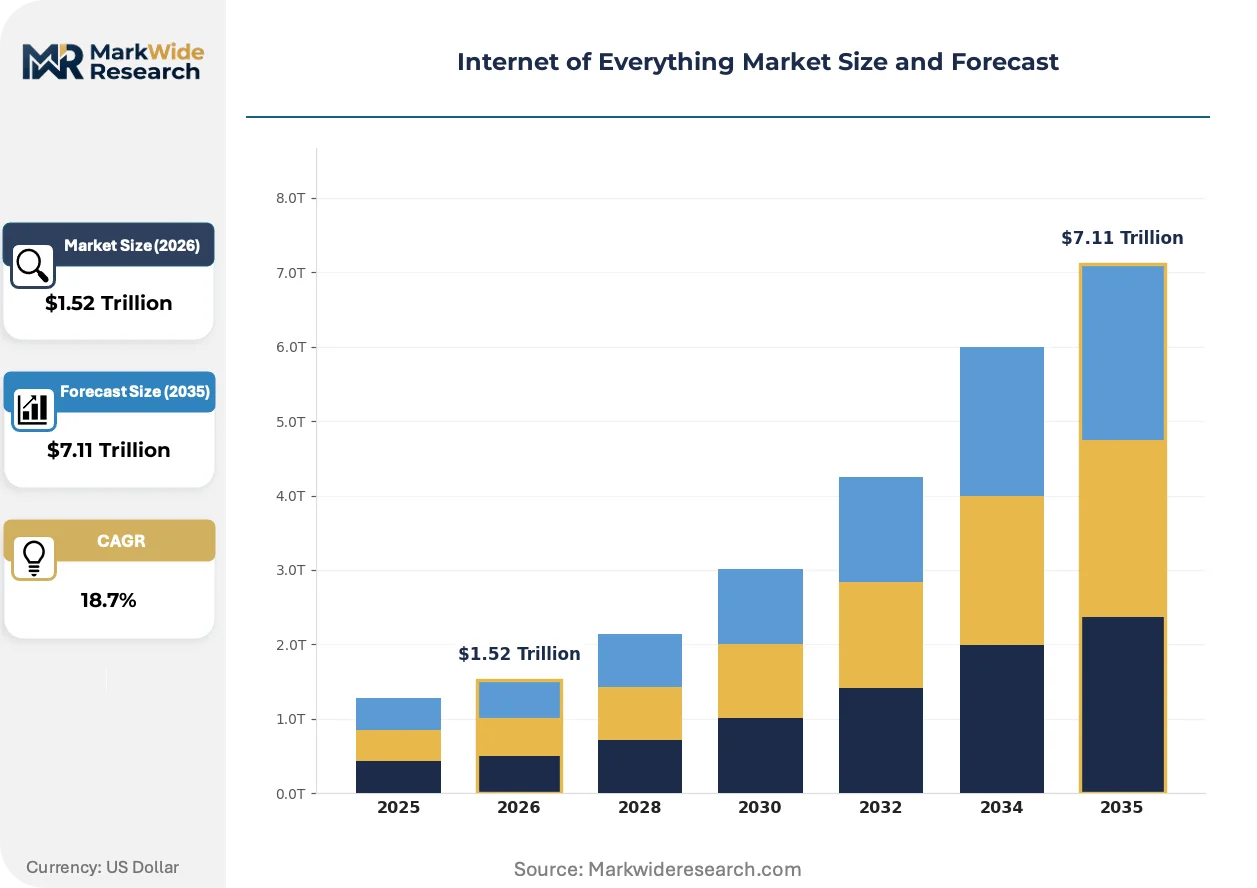
| Market Size in 2026 | $1.52 Trillion |
| Market Size in 2035 | $7.11 Trillion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: 5G, Wi-Fi 6, LPWAN, Bluetooth, Zigbee, NFC Application: Smart City, Connected Transportation, Precision Agriculture, Industrial Automation, Smart Retail, Energy Management End User: Manufacturing Plants, Logistics Providers, Public Utilities, Agriculture Enterprises, Retail Chains, Education Institutes Deployment Model: Cloud, Edge Computing, Fog Computing, Hybrid, On-Premises |
| Companies Covered | Cisco Systems, Microsoft, IBM, General Electric, Intel, Huawei Technologies, Oracle, Siemens, Google, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Internet of Everything Market Strategic Shifts & Innovations
Software-defined networking principles are migrating from enterprise data centers into distributed IoE infrastructure, collapsing the distinction between connectivity hardware and orchestration layers.
Digital twin platforms are virtualizing physical asset monitoring by creating real-time mirrored environments for predictive simulation. Heavy industrial operators in Germany and the United States are deploying these systems for supply chain and manufacturing optimization. This virtualization is compressing the traditional hardware-software boundary in industrial IoE procurement.
The EU AI Act's risk-based classification system is mandating conformity assessments for high-risk connected applications including critical infrastructure and biometric identification. Platform providers must now maintain technical documentation and human oversight protocols that elevate operational overhead. Smart city vendors targeting European municipal buyers are restructuring product architectures to embed these compliance features natively.
Subscription-based consumption models are displacing perpetual license structures in enterprise IoE procurement. Industrial buyers in China and the United States are favoring metered edge analytics over capital-intensive sensor deployments. This shift is most pronounced in manufacturing verticals where CFOs prioritize operational expenditure classification for automation investments.
Internet of Everything Market Segmentation
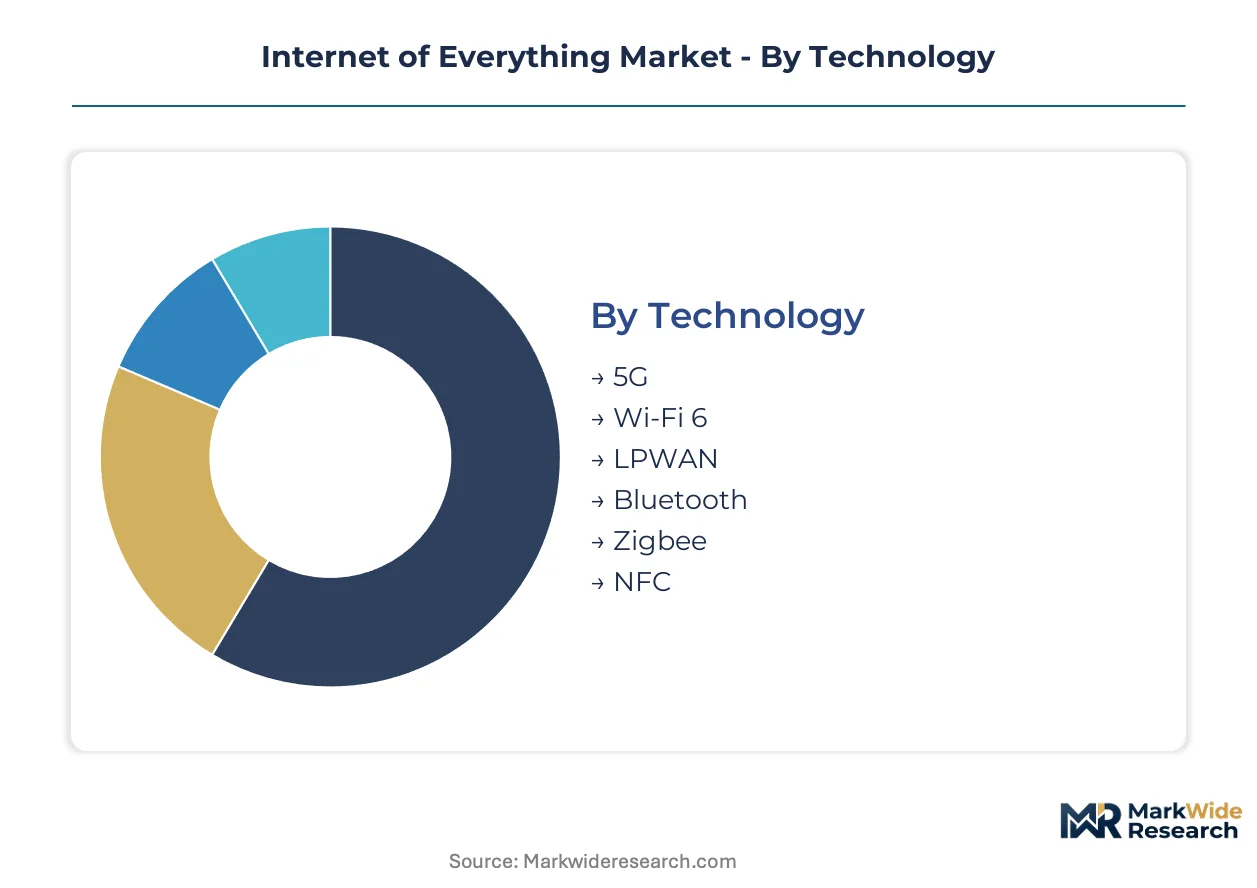
Technology heterogeneity across the Internet of Everything creates divergent procurement patterns where connectivity choices cascade into architecture decisions. Buyers segment their investments by latency tolerance, data sovereignty requirements, and existing infrastructure legacy.
Technology:
Mature wireless protocols coexist with emerging cellular standards across deployment portfolios.
- 5G:Ultra-reliable low-latency communication enables factory-floor robotics and autonomous vehicle coordination. German automotive clusters and Chinese port automation projects are concentrating procurement for private network slices.
- Wi-Fi 6:OFDMA scheduling and target wake time mechanisms support high-density sensor environments. US healthcare systems and Japanese commercial real estate operators are standardizing on Wi-Fi 6E for indoor asset tracking.
- LPWAN:Narrowband-IoT and LoRaWAN protocols serve battery-constrained remote monitoring in agriculture and utilities.
- Bluetooth:Mesh networking extensions support proximity-based retail analytics and indoor navigation.
- Zigbee:Low-power cluster-tree topologies dominate residential and light commercial building automation.
- NFC:Contactless pairing and authentication secures device provisioning in field service operations.
5G retains volume leadership; LPWAN holds the steepest expansion curve.
Application:
Cost tier differentiation separates capital-intensive infrastructure from operational technology deployments.
- Smart City:Integrated traffic signal control, environmental sensing, and public safety networks require municipal bond financing. Procurement cycles in the United States and Germany are accelerating as federal infrastructure grants flow to metropolitan authorities.
- Industrial Automation:Predictive maintenance and quality inspection systems command premium pricing where downtime costs exceed connectivity investments. Manufacturing plants in Japan and South Korea are mandating edge-native architectures for sub-10 millisecond response.
- Connected Transportation:Fleet telematics and vehicle-to-infrastructure communication serve logistics optimization.
- Precision Agriculture:Soil moisture and crop health monitoring supports variable-rate irrigation decisions.
- Smart Retail:Inventory visibility and customer flow analytics compress working capital requirements.
- Energy Management:Demand response and distributed generation coordination stabilizes grid-edge operations.
Smart City captures the largest absolute connection volumes; Industrial Automation delivers the highest margin realization per endpoint.
End User:
Customer type determines procurement authority structures and budget classification.
- Manufacturing Plants:Operational technology teams control automation spending separate from IT capital budgets. Discrete manufacturers in Germany and process industries in the United States are consolidating sensor platforms under chief digital officer mandates.
- Public Utilities:Regulated rate-base treatment favors infrastructure investments with 20-year depreciation horizons. Electric utilities in California and Texas are deploying distribution automation under state renewable integration mandates.
- Logistics Providers:Third-party warehousing and freight operators prioritize asset visibility across multimodal networks.
- Agriculture Enterprises:Large-scale farming cooperatives in the US Midwest and Brazilian soy belt are piloting autonomous machinery coordination.
- Retail Chains:Loss prevention and supply chain transparency drive loss-ratio improvements.
- Education Institutes:Campus safety and facilities management applications serve administrative efficiency goals.
Manufacturing Plants dominate enterprise connectivity spending; Public Utilities are expanding most quickly under grid modernization mandates.
Deployment Model:
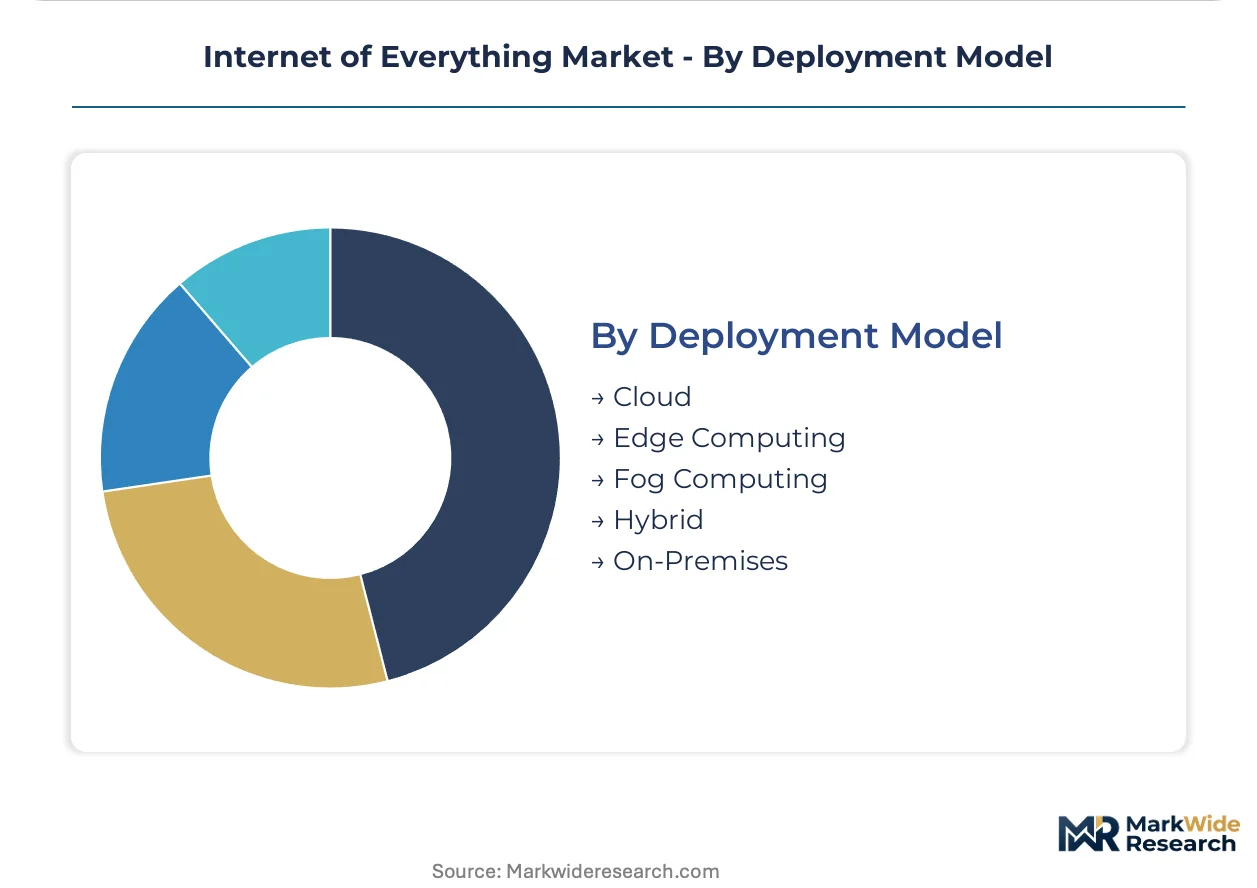
Supply concentration in hyperscale cloud infrastructure shapes hybrid architecture economics.
- Cloud:Centralized data lakes and model training pipelines aggregate telemetry from dispersed endpoints. Enterprise buyers in the United States and United Kingdom are negotiating multi-year consumption commitments with hyperscale providers.
- Edge Computing:Localized inference and actuation satisfies latency and privacy constraints. German manufacturing clusters and Japanese semiconductor fabs are deploying on-premise GPU clusters for quality inspection.
- Fog Computing:Hierarchical processing between edge and cloud layers supports utility microgrid coordination.
- Hybrid:Workload portability across on-premise and cloud infrastructure serves regulatory flexibility requirements.
- On-Premises:Air-gapped deployments satisfy defense and critical infrastructure security mandates.
Cloud retains deployment volume leadership; Edge Computing is gaining share fastest as latency requirements harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal infrastructure grants and national broadband programs are accelerating municipal IoE deployments across concentrated industrial clusters. Germany's Industrie 4.0 framework and the United States' BEAD program exemplify how policy incentives reshape procurement patterns. Smart city sensor networks and manufacturing automation dominate capital allocation in these priority markets.
United States
Utility microgrid mandates under FERC Order 2222 drive distributed energy resource aggregation investments. The FCC governs unlicensed IoT spectrum allocation, directly shaping device certification pathways. Texas and California utilities deploy distribution automation under state renewable integration requirements.
Germany
Automotive and discrete manufacturing clusters demand sub-10 millisecond edge-native architectures for quality inspection. The EU AI Act imposes algorithmic transparency mandates that elevate compliance costs for platform providers. Bavarian automotive plants and Baden-Württemberg industrial zones concentrate private 5G network procurement.
China
Port automation and logistics optimization projects concentrate demand for ultra-reliable low-latency communication. The Personal Information Protection Law fragments cloud architecture economics for multinational operators. Yangtze River Delta manufacturing hubs anchor integrated silicon-to-cloud deployment models.
India
BharatNet fiber backbone expansion creates first-mile infrastructure for rural IoE connectivity previously uneconomical for private capital. TRAI spectrum allocation decisions shape unlicensed band availability for agricultural sensor networks. Maharashtra and Gujarat industrial corridors pilot autonomous machinery coordination in large-scale farming cooperatives.
Japan
Semiconductor fabrication facilities mandate edge-native GPU clusters for sub-10 millisecond quality inspection response. METI industrial digitization programs accelerate brownfield SCADA integration investments. Kyushu and Chubu manufacturing zones concentrate predictive maintenance platform deployments.
Internet of Everything Market Key Industry Players
Channel-controlling players compete with product-specialist players across tiered procurement segments. The vendor ecosystem organizes around three strategic archetypes: integrated infrastructure providers extending subscription platforms, cloud-native analytics vendors embedding IoE capabilities within enterprise contracts, and silicon-to-stack specialists capturing emerging market deployments. Consolidation pressures favor pre-certified vendors under EU AI Act compliance mandates, while municipal procurement cycles fragment revenue recognition timelines.
Within the integrated infrastructure tier, Cisco Systems and Huawei Technologies exemplify divergent geographic positioning strategies. Cisco leverages its installed base of routing infrastructure across North American and European enterprise accounts. Huawei anchors integrated silicon-to-cloud stacks across emerging market municipalities. Microsoft occupies a distinct position by embedding IoE analytics within hyperscale cloud consumption contracts, competing through workload integration rather than standalone hardware procurement.
| Leading Market Players |
|---|
| Cisco Systems |
| Microsoft |
| IBM |
| General Electric |
| Intel |
| Huawei Technologies |
| Oracle |
| Siemens |
| Others |
Cost & Logistics Intelligence
Single-source dependency on Taiwan Semiconductor Manufacturing and Samsung Foundry for advanced-node edge processors determines both pricing tier spreads and supply chain shape across the Internet of Everything ecosystem. Municipal buyers face elongated procurement cycles while industrial automation customers absorb premium pricing for guaranteed allocation.
Pricing Analysis
Certification level creates the primary spread between EU AI Act-compliant platforms and uncertified alternatives. Subscription-based SaaS tiers dominate enterprise procurement, with price differentiation resting on latency guarantees and data residency controls. Cost compression in smart city segments intensifies as federal infrastructure grants constrain municipal budget elasticity. Manufacturing plants exhibit lowest price sensitivity due to downtime cost thresholds exceeding connectivity investments.
Supply Chain Analysis
Contract manufacturing concentration at Foxconn, Jabil, and Flex anchors hardware production across the Internet of Everything value chain. Geographic supply concentrates in Taiwan, South Korea, and China for advanced semiconductors, with Mexico and Vietnam emerging for final assembly. Raw material dependencies span silicon wafers, rare earth magnets, and lithium-ion cells. Tariff exposure on Chinese-manufactured sensors threatens margin structures. Distribution runs through systems integrators and hyperscale cloud marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Internet of Everything market functions as a defensive-moat story where switching costs lock industrial buyers into integrated platform ecosystems. Regulatory entrenchment through EU AI Act pre-certification creates durable competitive barriers.
For Market Incumbents: Pre-empt emerging entrant challenges by embedding edge-native compliance features natively into subscription platforms. Deepen backward integration into silicon design to secure allocation priority at Taiwan and South Korea foundries. Capture municipal procurement channel control through certified partner ecosystems. For New Entrants and Emerging Players: Pursue white-space opportunities in India's BharatNet-connected rural agriculture and utility microgrid segments where incumbent presence remains thin. Target precision agriculture applications with LPWAN-based sensor bundles priced below municipal smart city tiers. Deploy through regional systems integrators lacking hyperscale cloud partnerships. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors EU AI Act pre-certified platform providers with recurring revenue bases. Long-term viability hinges on subscription retention in industrial automation verticals where switching costs compound. Acquisition target archetype: edge-native analytics specialists with IEC 62443 certification pipelines. Monitor FERC Order 2222 implementation velocity and EU AI Act enforcement cadence as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Pre-Certification Investment | Accelerates municipal procurement timelines in Germany and France. |
| Edge-Native Silicon Design Partnership | Secures allocation priority at TSMC and Samsung foundries. |
| Subscription Platform Migration | Shifts revenue recognition from project-based to recurring. |
| Utility Microgrid Control Integration | Captures FERC Order 2222-mandated distributed energy aggregation. |
| India Rural Connectivity Partnership | Leverages BharatNet fiber backbone for agricultural sensor deployment. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FCC spectrum allocation records, EU AI Act implementation guidance, hyperscaler capex disclosures, and industrial automation procurement databases. Primary interviews engaged chief digital officers at German manufacturing clusters, municipal IT directors in Texas and California, platform engineering leads at cloud providers, and channel partners distributing edge hardware. Bottom-up endpoint deployment estimates triangulate against top-down infrastructure spending projections.
Forecast inputs span technology adoption curves across 5G, Wi-Fi 6, and LPWAN protocols; application penetration rates in smart city, industrial automation, and precision agriculture segments; and deployment model shifts between cloud, edge, and fog computing architectures. Segmentation dimensions include connectivity protocol, latency tolerance tier, data sovereignty requirement, and end-user procurement authority. CAGRs derive from infrastructure investment trajectories and regulatory compliance timelines.
Sensitivities concentrate around Taiwan semiconductor supply disruptions, EU AI Act enforcement intensity, and municipal bond market conditions affecting smart city financing. Forecasts reflect assumptions on spectrum allocation timelines and foundry capacity expansion. Quarterly review of FCC auction results, EU conformity assessment body throughput, and BharatNet deployment milestones is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Industrial IoT Market
Internet of Things (IoT)
Smart Sprinkler Controller Market
Internet of Things (IoT)
LPWAN in the Consumer IoT Market
Internet of Things (IoT)
IoT Middleware Market
Internet of Things (IoT)
Smart Sound and Gateway Market
Internet of Things (IoT)
LTE IoT Market
Internet of Things (IoT)
Smart Home M2M Market
Internet of Things (IoT)
Global IoT Based Asset Tracking and Monitoring Market
Internet of Things (IoT)
IoT Gateway Devices Market
Internet of Things (IoT)
IoT Technology Market
Internet of Things (IoT)
IoT in Manufacturing Market
Internet of Things (IoT)
Cellular Internet of Things (IoT) Devices Market
Internet of Things (IoT)
Global Residential Smart Thermostats Market
Internet of Things (IoT)
Asia-Pacific IoT Device Market
Internet of Things (IoT)
IoT Microcontroller Market
Internet of Things (IoT)
IoT in Chemical Industry Market