
 Procurement Outsourcing Services Market | 2026-2036
Procurement Outsourcing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Procurement Outsourcing Services Market Outlook
Indian IT services providers is shifting procurement outsourcing capacity toward cloud-native delivery platforms. GEP leverages its AI-powered sourcing engines to anchor enterprise spend management contracts across North America. IBM sustains a hybrid consulting-technology model that competes for complex multi-country procurement transformations. Coupa differentiates through network effects in its business-spend management ecosystem, occupying a dominant position in mid-market SaaS procurement.
Procurement outsourcing services encompass the delegation of sourcing, supplier negotiation, purchase order management, and spend analytics to third-party specialists operating under service-level agreements with defined cost-reduction targets and cycle-time metrics. These services reduce operational overhead while enforcing compliance through catalog-based purchasing and automated three-way matching. Direct procurement segments lead contract value due to raw material volatility in manufacturing supply chains, while cloud-based delivery models represent the fastest-growing structural category as clients abandon on-site legacy implementations. Indirect procurement retains mature margin pools in facility services and office supplies, though strategic sourcing engagements capture premium pricing through category expertise.
The EU Green Deal and CSRD mandate granular supplier emissions reporting, forcing procurement outsourcers to embed carbon accounting into sourcing workflows. FDA and HIPAA requirements in US healthcare verticals restrict vendor access to sensitive procurement data, shaping security architecture investments. Stakeholders must decide whether to build in-house ESG tracking capabilities or delegate compliance risk to specialized procurement partners as regulatory scope widens.
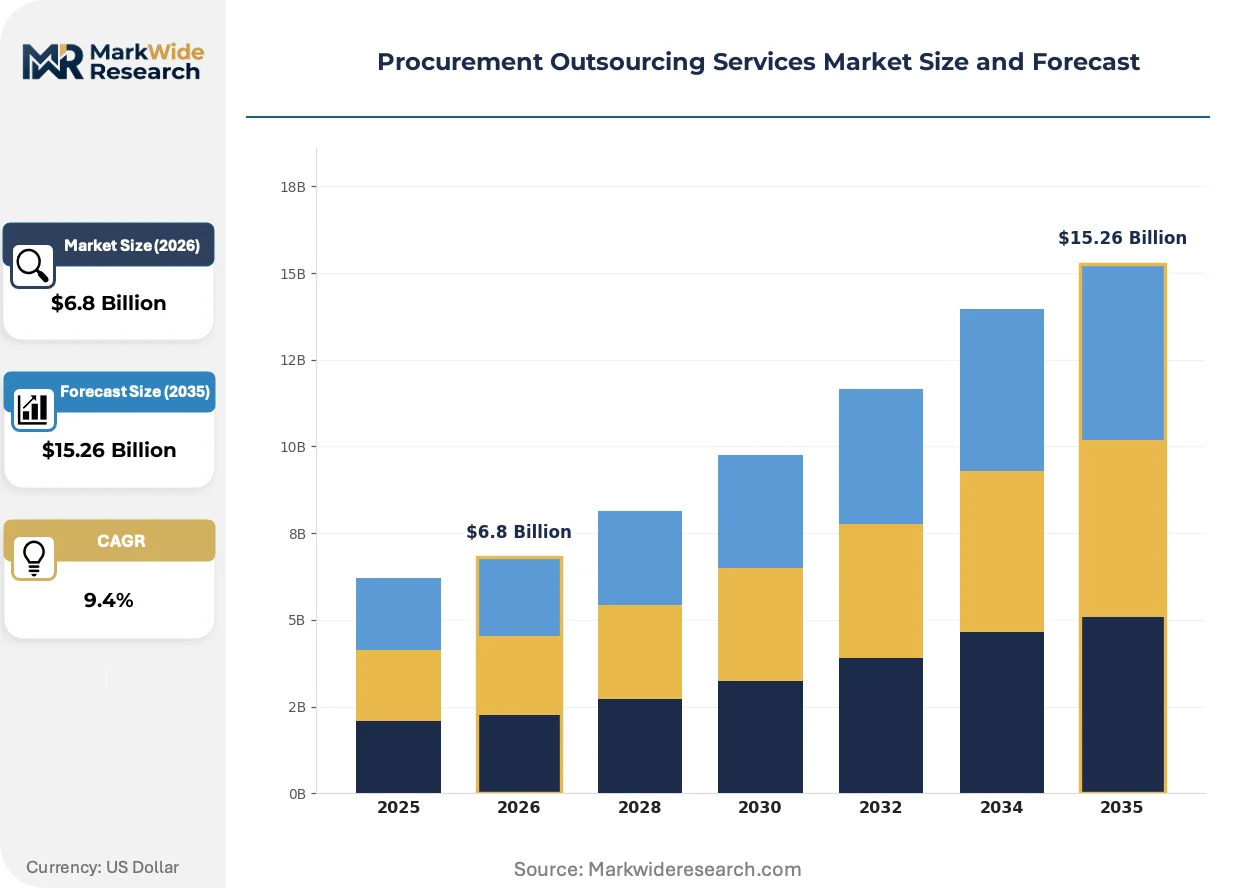
Market Dynamics
The EU Green Deal and CSRD are compressing procurement cycles by mandating real-time carbon accounting across supplier tiers, forcing outsourcers to rebuild sourcing workflows around emissions traceability rather than cost alone.
Growth Catalysts
- CSRD disclosure mandates:The EU's Corporate Sustainability Reporting Directive requires granular supplier emissions data, compelling Fortune 500 firms to delegate compliance-heavy sourcing to specialized providers with embedded carbon tracking capabilities.
- Cloud-native delivery platforms:Indian IT services providers are migrating procurement infrastructure to scalable architectures, reducing implementation timelines and enabling real-time spend analytics for mid-market clients.
- Raw material volatility:Manufacturing supply chains in Germany face unpredictable commodity swings, driving demand for managed procurement services that hedge price exposure through forward contracts and supplier diversification.
Market Restraints
- HIPAA data restrictions:US healthcare verticals limit vendor access to sensitive procurement records, forcing outsourcers to maintain costly segregated security architectures that inflate service delivery costs.
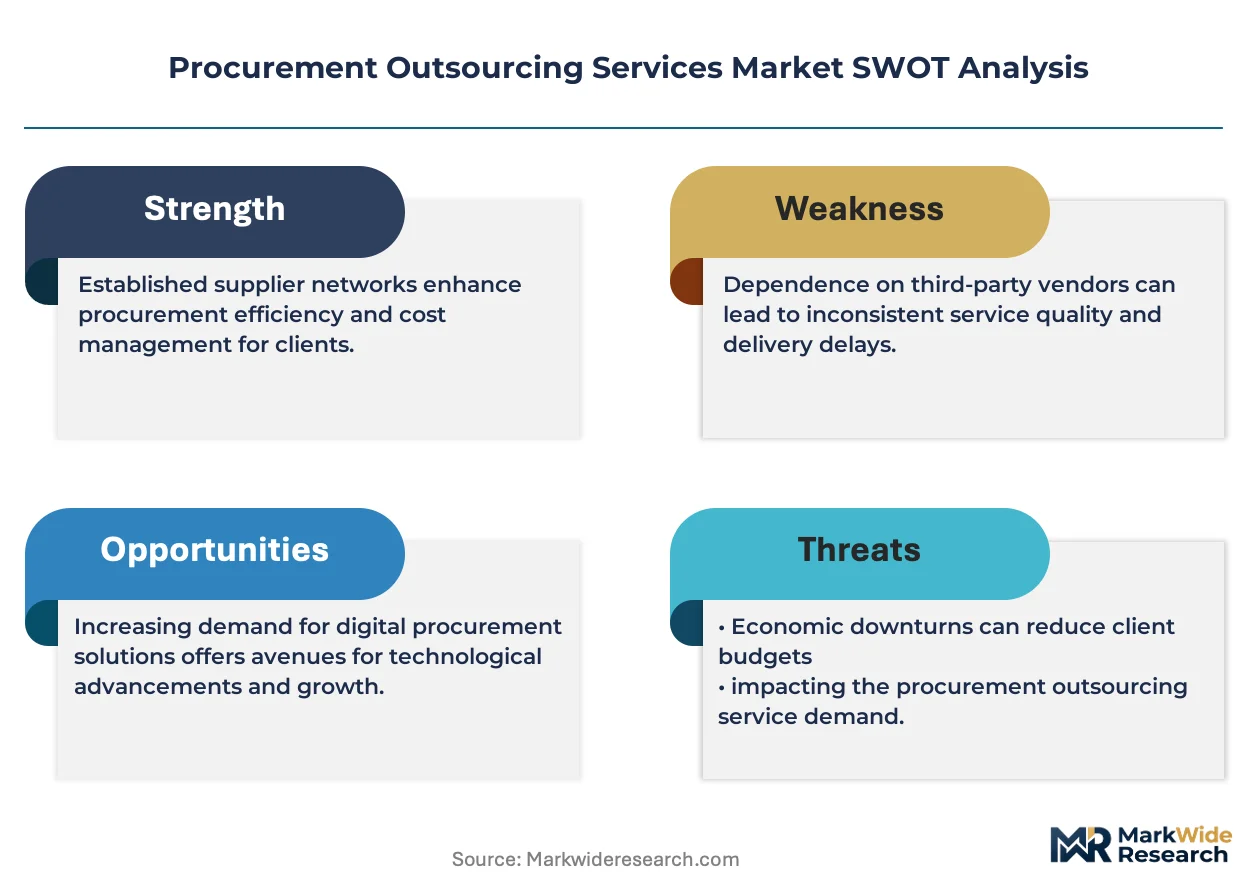
- Supplier concentration risk:Cloud infrastructure for procurement platforms concentrates among three hyperscale providers, creating single-point-of-failure exposure and limiting negotiation leverage for outsourcing vendors.
- Legacy system entrenchment:SAP Ariba and Oracle procurement installations persist in 60% of Global 2000 firms, locking data in proprietary formats that resist API-based integration with modern outsourcing platforms.
Strategic Opportunities
- Mid-market SaaS penetration:Business-spend management ecosystems with network effects are capturing procurement outsourcing contracts from firms with $50M-$500M annual indirect spend previously served by manual processes.
- AI-powered sourcing engines:Machine learning algorithms that predict supplier financial distress and optimize award scenarios are converging with robotic process automation to automate complex multi-criteria sourcing decisions.
- IRA clean energy incentives:The US Inflation Reduction Act's domestic content requirements are creating demand for procurement outsourcers capable of tracing component origin through tier-three suppliers for tax credit qualification.
Industry Challenges
- Category expertise scarcity:Strategic sourcing engagements for specialized direct materials require procurement professionals with 10+ years of commodity-specific experience, a talent pool that outsourcing vendors struggle to staff at scale.
- Three-way matching automation:Legacy ERP systems lack standardized data formats for purchase orders, receipts, and invoices, forcing outsourcers to maintain expensive exception-handling teams that erode margin targets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Procurement Outsourcing Services Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Direct Procurement, Indirect Procurement, Strategic Sourcing, Supplier Management Industry Vertical: Healthcare, Manufacturing, Retail, Financial Services Delivery Model: On-site, Off-site, Hybrid, Cloud-based Engagement Type: Project-based, Retainer-based, Managed Services, Outsourcing |
| Companies Covered | Ivalua, Amazon Business, GEP, CDW, Basware, Coupa, Corcentric, IBM, SHI International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Procurement Outsourcing Services Market Strategic Shifts
Artificial intelligence is restructuring how procurement outsourcers deliver value, compressing the gap between data ingestion and sourcing execution while regulatory pressure forces embedding of compliance tools directly into workflow automation.
Generative AI for supplier negotiation is absorbing contract analysis and redlining tasks previously handled by junior procurement staff. Mid-market manufacturing firms in the US Midwest are piloting these tools for indirect spend categories, reducing cycle times from weeks to days. The technology is absorbing routine legal review work, allowing human category managers to focus on supplier relationship strategy and risk mitigation.
The EU AI Act's risk-based classification system is imposing documentation burdens on automated procurement decision tools. Providers must now maintain algorithmic audit trails for high-risk applications involving vendor selection, forcing investments in explainable AI architectures. Healthcare and public sector procurement in Germany faces the strictest compliance timelines, with outsourcers racing to retrofit sourcing engines with human-in-the-loop override capabilities.
Enterprise buyers are consolidating fragmented point solutions into unified business-spend management platforms. Procurement departments that previously operated separate tools for sourcing, contracting, and invoice processing are demanding integrated workflows from outsourcing partners. This consolidation is most visible among US-based technology and professional services firms with distributed global procurement operations seeking single-pane visibility.
Procurement Outsourcing Services Market Segmentation
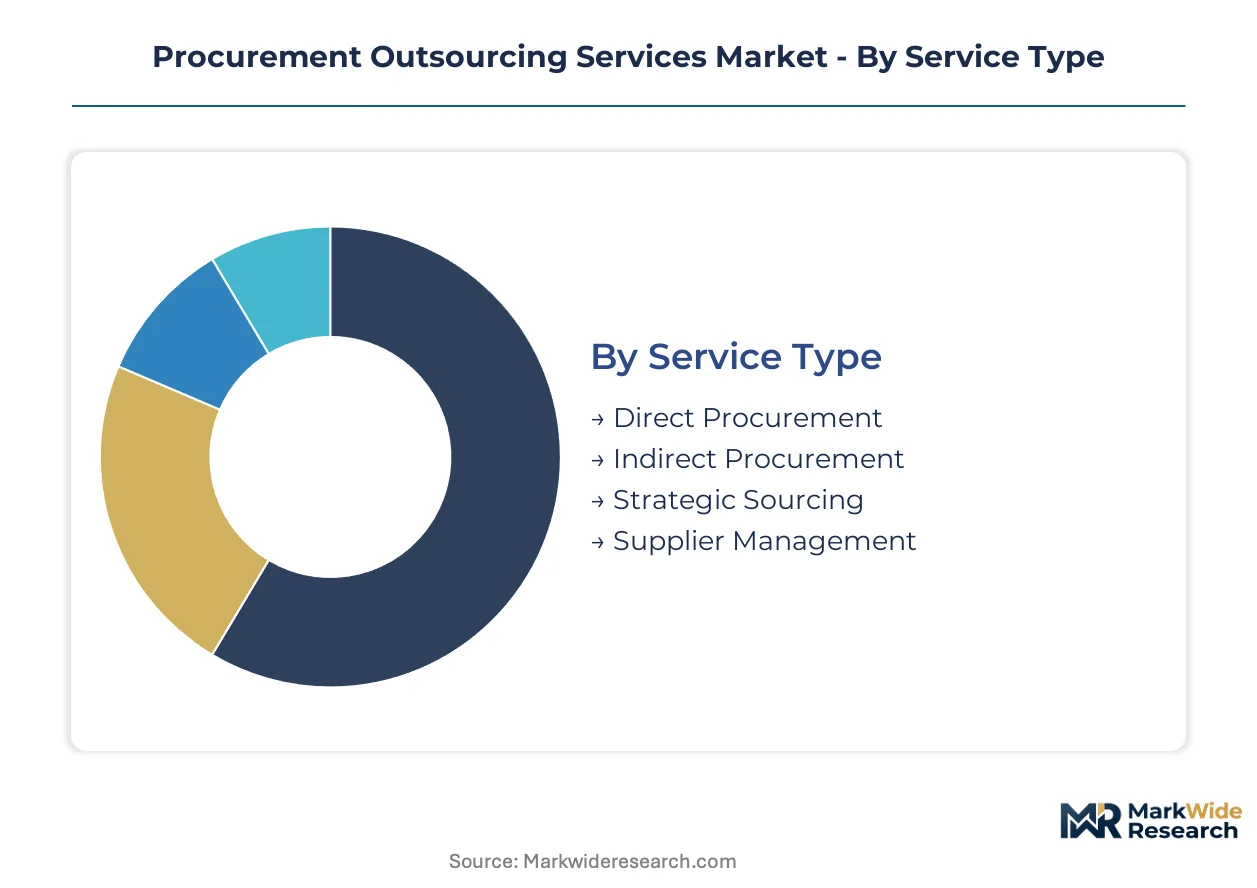
Procurement outsourcing segments diverge sharply in compliance architecture. Direct materials sourcing demands REACH and RoHS traceability in European manufacturing supply chains, while healthcare procurement carries HIPAA data segregation requirements that reshape service delivery economics.
Service Type:
Certification burdens vary by procurement category. Direct materials require chemical compliance documentation under EU regulations, while strategic sourcing engagements face lighter disclosure standards but heavier category expertise demands.
- Direct Procurement:Raw material and component sourcing governed by REACH substance restrictions and conflict mineral reporting rules. German automotive and industrial manufacturers concentrate contract value here, driven by commodity price volatility and tier-three supplier traceability mandates under the EU Green Deal.
- Indirect Procurement:Facility services, IT equipment, and office supply categories with mature margin pools. US Fortune 500 firms delegate these high-transaction, low-visibility spend categories to capture catalog-based compliance and automated three-way matching.
- Strategic Sourcing:Complex category management requiring 10+ year commodity expertise. Premium pricing reflects embedded market intelligence and supplier financial risk modeling.
- Supplier Management:Ongoing vendor performance monitoring and ESG scorecard administration. CSRD carbon disclosure requirements are forcing real-time emissions data integration into these workflows.
Direct Procurement sits at the top of the volume ranking, with Strategic Sourcing climbing the fastest.
Industry Vertical:
Vertical-specific regulations fragment service delivery models. Healthcare and financial services impose data residency and audit trail requirements that inflate infrastructure costs compared to manufacturing clients.
- Healthcare:HIPAA and FDA 21 CFR Part 11 restrictions limit vendor data access and mandate encrypted procurement record storage. US hospital systems and pharmaceutical manufacturers drive demand for segregated security architectures.
- Manufacturing:EU Green Deal supply chain due diligence and CSRD emissions reporting dominate sourcing workflows. German industrial firms anchor contract volume in this vertical.
- Retail:High SKU complexity and seasonal demand volatility require agile sourcing engines. Private label procurement and direct-to-consumer fulfillment networks shape service requirements.
- Financial Services:SOX audit trail mandates and vendor risk management frameworks from US banking regulators concentrate demand among asset managers and insurers.
Manufacturing captures the largest revenue share, though Healthcare is expanding most quickly as compliance burdens deepen.
Delivery Model:
Infrastructure choices determine scalability and margin structure. Cloud-native platforms enable mid-market penetration while hybrid models retain traction in regulated verticals requiring data sovereignty.
- Cloud-based:Scalable multi-tenant architectures with API-first integration. Indian IT services providers are migrating capacity here to compress implementation timelines and enable real-time spend analytics.
- Hybrid:Split processing with sensitive data on-premise and analytics in cloud. Financial services and healthcare clients in Germany and the US prefer this model for regulatory comfort.
- On-site:Legacy implementations persisting in SAP Ariba and Oracle environments. Data lock-in and proprietary formats resist migration.
- Off-site:Dedicated delivery centers with client-specific infrastructure. Declining share as cloud security certifications mature.
Cloud-based delivery leads by new contract value, with Hybrid models holding steady in regulated segments.
Engagement Type:
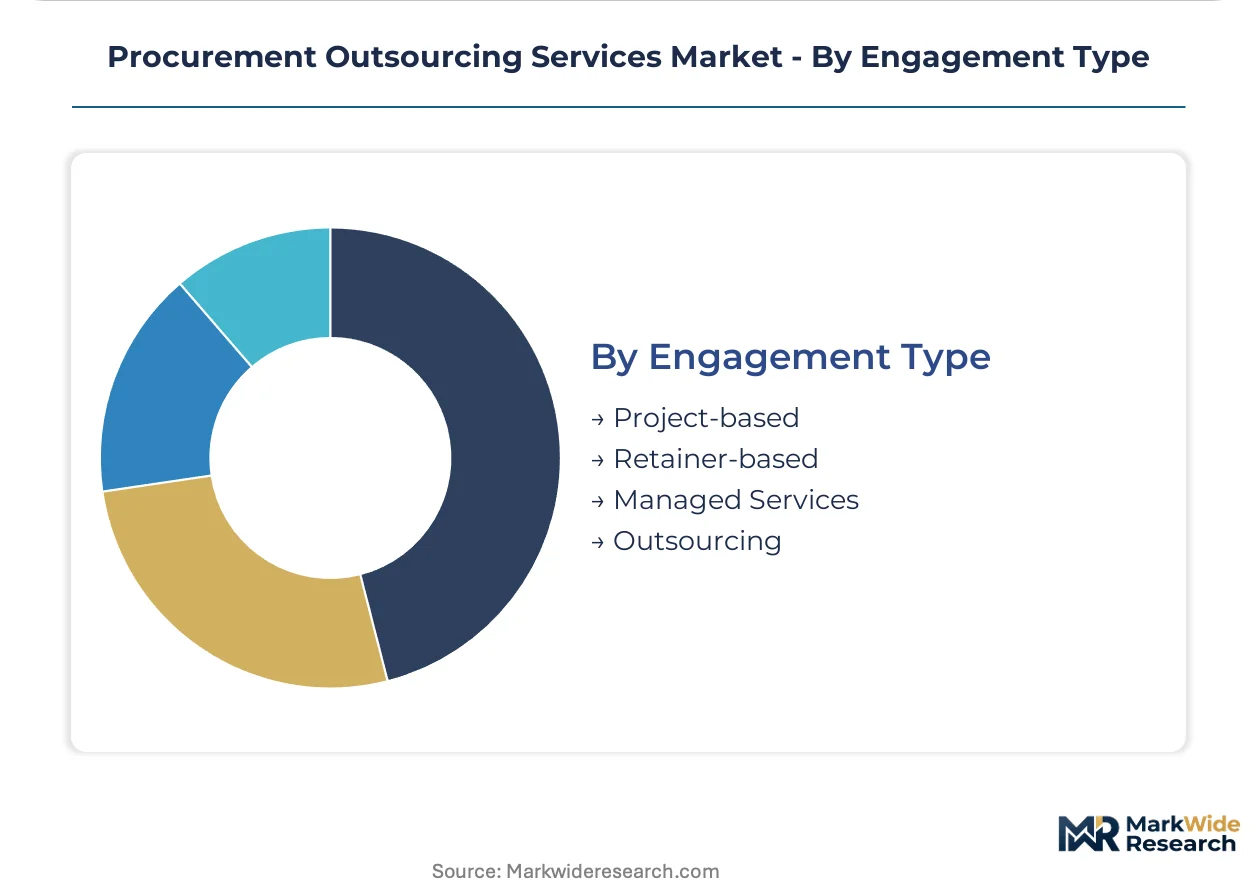
Contract structures align risk allocation with outcome measurability. Managed services dominate complex transformations while project-based engagements serve point solution needs.
- Managed Services:Multi-year agreements with SLA-defined cost reduction targets and cycle-time metrics. Fortune 500 manufacturing firms in the US and Germany anchor this segment.
- Outsourcing:Full function delegation with gain-sharing arrangements. Strategic sourcing and supplier management modules commonly bundle here.
- Retainer-based:Fixed-fee advisory access for category expertise and market intelligence. Professional services firms and mid-market manufacturers favor this structure.
- Project-based:Defined-scope engagements for sourcing events or system implementations. Common entry point for cloud platform adoption.
Managed Services commands the highest contract value, with Outsourcing gaining traction as ESG compliance burdens deepen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial manufacturers anchor procurement outsourcing contract value in Europe, while United States Fortune 500 firms drive demand for indirect spend optimization through managed services engagements.
United States
HIPAA restrictions shape healthcare procurement outsourcing architectures, forcing segregated security investments from hospital systems and pharmaceutical manufacturers. The IRA's domestic content requirements create demand for tier-three supplier traceability services. Chicago and Boston healthcare clusters delegate compliance-heavy sourcing to specialized providers.
Germany
Automotive and industrial manufacturers concentrate managed procurement contracts in Bavaria and Baden-Württemberg. The EU Green Deal and CSRD mandate real-time carbon accounting across supplier tiers. Stuttgart's automotive engineering corridor outsources direct materials sourcing to hedge commodity volatility.
India
IT services providers migrate procurement infrastructure to cloud-native platforms from delivery centers in Bangalore and Hyderabad. The PLI scheme incentivizes domestic manufacturing procurement transformation. Mumbai-Pune manufacturing belt adopts scalable architectures for mid-market spend analytics.
United Kingdom
Financial services procurement carries SOX-equivalent audit trail mandates from UK banking regulators. London's asset management and insurance clusters demand vendor risk management frameworks. The FCA's operational resilience requirements reshape outsourcing contract structures for critical supplier dependencies.
Japan
METI supply chain resilience initiatives accelerate procurement outsourcing adoption among precision manufacturers. Tokyo-Osaka industrial corridors seek supplier diversification services. Automotive and electronics clusters in Aichi and Kanagawa prefectures delegate strategic sourcing for rare earth components.
Procurement Outsourcing Services Market Competitive Environment
United States technology providers anchor the cloud-native tier; Indian IT services specialists hold the implementation and delivery tier. The market structures around three strategic archetypes: AI-powered sourcing engine developers, business-spend management platform operators, and hybrid consulting-technology integrators. Consolidation pressure intensifies through M&A activity targeting mid-market SaaS penetration, while strategic partnerships between hyperscale cloud providers and procurement vendors reshape delivery economics.
Within the AI-powered sourcing tier, GEP and Coupa exemplify divergent approaches to enterprise spend management. GEP occupies a position among North American providers leveraging machine learning for sourcing optimization, while Coupa anchors the network-effects-driven business-spend management ecosystem. IBM sits within the hybrid consulting-technology archetype, competing for complex multi-country procurement transformations where regulatory fragmentation demands integrated advisory and platform capabilities.
| Leading Market Players |
|---|
| Ivalua |
| Amazon Business |
| GEP |
| CDW |
| Basware |
| Coupa |
| Corcentric |
| IBM |
| SHI International |
| Others |
Value Chain & Pricing Dynamics
Certification-tier divergence between CSRD-compliant carbon accounting platforms and legacy compliance-lite systems splits pricing power along supply chain sophistication. German automotive manufacturers pay premium rates for tier-three emissions traceability while US mid-market firms absorb standard SaaS tiers with limited supplier visibility, compressing margins for providers lacking embedded ESG tooling.
Pricing Analysis
Distributor margins for cloud-native procurement platforms compress as hyperscale providers bypass channel layers with direct enterprise sales. Three-tier pricing structure across premium, standard, and economy levels aligns with CSRD readiness, API integration depth, and dedicated account management. Cost compression in the economy tier intensifies because Indian IT services providers compete on implementation velocity. Fortune 500 manufacturing firms show least price sensitivity for strategic sourcing modules with embedded commodity risk modeling.
Supply Chain Analysis
Regional distribution centers in Bangalore, Hyderabad, and Pune anchor cloud infrastructure delivery for procurement platforms serving mid-market clients. Provider capacity draws from hyperscale data centers in the United States, Ireland, and Singapore, with compute resources resting on semiconductor supply from Taiwan and South Korea. Single-source vulnerability concentrates among three cloud infrastructure providers. Distribution runs through API-first integration layers rather than traditional value-added reseller networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German CSRD compliance costs run three to four times higher than equivalent US HIPAA infrastructure investments, creating arbitrage for providers with modular regulatory architectures.
For Market Incumbents: Acquire specialized ESG data aggregation assets to embed carbon accounting into sourcing workflows before CSRD disclosure mandates expand beyond the EU. IBM and GEP should consolidate mid-market SaaS specialists facing margin pressure from Coupa's network effects. Vertical integration into tier-three supplier databases addresses the category expertise scarcity threatening strategic sourcing margins. For New Entrants and Emerging Players: API-first marketplace routes offer lowest friction entry for procurement automation tools targeting US Midwest manufacturing clusters with $50M-$500M indirect spend. White-space concentrates in IRA clean energy incentive compliance services requiring domestic content traceability. Partner with existing business-spend management platforms rather than building full-stack alternatives. For Investors and Strategic Acquirers: Consolidation pressure builds where cloud-native delivery platforms overlap with legacy SAP Ariba integration specialists. Long-term viability favors providers with AI-powered sourcing engines and explainable AI architectures compliant with the EU AI Act. Acquisition target archetype: mid-market SaaS procurement vendors with healthcare or financial services vertical penetration. Watch for FDA 21 CFR Part 11 compliance investments as inflection signal for healthcare procurement outsourcing demand.| Strategic Initiative | Industry Significance |
|---|---|
| CSRD Compliance Module Development | Embedded carbon accounting captures German automotive contracts under EU Green Deal mandates. |
| AI-Powered Sourcing Engine Acquisition | Machine learning for supplier financial distress prediction differentiates strategic sourcing engagements. |
| Mid-Market SaaS Platform Integration | Network effects from business-spend management ecosystems displace manual procurement processes. |
| Healthcare Security Architecture Investment | HIPAA-compliant segregated infrastructure opens US hospital system outsourcing contracts. |
| Hyperscale Cloud Partnership | Direct AWS, Azure, or GCP alliances reduce infrastructure costs and accelerate implementation timelines. |
Study Parameters
Direct dialogue with procurement outsourcing executives, cloud platform engineers, ESG compliance officers, and Fortune 500 category managers grounded qualitative findings. Secondary validation drew from SEC 10-K filings, EU CSRD disclosure databases, SAP and Oracle partner ecosystem directories, and hyperscaler capex reports. Bottom-up contract value estimates triangulated against top-down market sizing from trade associations and regulatory filing analysis.
Bottom-up modeling of service type, delivery model, and engagement type dimensions combined with top-down regulatory cluster analysis across the analysis window. CAGRs derived from weighted average of historical contract growth rates and projected CSRD implementation timelines. Forecast inputs included EU Green Deal supply chain due diligence expansion schedules and US IRA domestic content requirement phase-ins.
The model assumes a particular technology adoption path; alternative pathways for generative AI supplier negotiation tools would alter the outlook for human-in-the-loop sourcing decisions. Forecasts reflect assumptions about CSRD enforcement consistency and hyperscale cloud pricing stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Business Process Outsourcing (BPO)
Asia-Pacific Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
North America Business Process-As-A-Service (Bpaas) Market
Business Process Outsourcing (BPO)
Back Office Outsourcing Market
Business Process Outsourcing (BPO)
Asia-Pacific Business Process As a Service (Bpaas) Market
Business Process Outsourcing (BPO)
Global Outsourced Sales Service Market
Business Process Outsourcing (BPO)
Payroll Outsourcing Services Market
Business Process Outsourcing (BPO)
Business Processing Outsourcing Market
Business Process Outsourcing (BPO)
Desktop Outsourcing Market
Business Process Outsourcing (BPO)
Service Bureau Market
Business Process Outsourcing (BPO)
Legal Process Outsourcing (LPO) Market
Business Process Outsourcing (BPO)
UAE Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Business Process As a Service (Bpaas) Market
Business Process Outsourcing (BPO)
Indonesia Business Process Outsourcing Services Market
Business Process Outsourcing (BPO)
BFSI BPO Services Market
Business Process Outsourcing (BPO)
Business Process Automation (BPA) Market
Business Process Outsourcing (BPO)
Cloud Based BPO Market