
 Cellular IoT Module Market | 2026-2036
Cellular IoT Module Market Size, Share, and Industry Trends Forecast 2026-2036
Cellular IoT Module Market Outlook
Chinese module manufacturers is restructuring capacity allocation toward integrated chipset-module platforms. Quectel Wireless Solutions anchors global volume through manufacturing scale across multiple cellular standards. Nordic Semiconductor ASA specializes in ultra-low-power LTE-M designs for battery-constrained deployments. Qualcomm Incorporated leverages its Snapdragon modem portfolio to dominate premium 5G module tiers.
A cellular IoT module combines a baseband processor, RF transceiver, power management unit, and antenna interface into a compact surface-mount package typically operating between 700 MHz and 3.5 GHz with receive sensitivities below -110 dBm, enabling bidirectional data exchange over licensed cellular networks for remote asset monitoring and control. NB-IoT modules command margin pools in utility metering where decade-long battery life justifies premium positioning, while 5G modules represent the fastest-growing product type as RedCap specifications unlock mid-tier industrial automation demand. Smart metering and asset tracking applications together absorb the majority of annual module shipments.
3GPP Release 17 RedCap specifications, FCC Part 15 and Part 27 equipment authorization rules, and CE marking under the EU Radio Equipment Directive collectively define certification barriers that shape regional product roadmaps and market access timelines. ETSI harmonized standards for cybersecurity resilience add compliance layers for European deployments. Stakeholders must monitor spectrum auction outcomes and national cybersecurity labeling programs to anticipate module qualification bottlenecks.
Market Dynamics
3GPP Release 17 RedCap standardization is compressing 5G module cost curves and unlocking mid-tier industrial automation demand previously blocked by premium pricing tiers.
Growth Catalysts
- Smart Metering Mandates:Utility regulators in Germany and China are accelerating AMI deployment timelines, creating sustained module procurement pipelines for NB-IoT and LTE-M platforms.
- 5G RedCap Standardization:The 3GPP Release 17 framework enables reduced capability 5G devices that trade peak throughput for cost efficiency, expanding addressable market into industrial sensors and wearables.
- Battery Chemistry Gains:Solid-state and lithium thionyl chloride advances are extending cellular IoT device autonomy beyond ten years, justifying premium module positioning in remote asset monitoring.
Market Restraints
- RF Front-End Concentration:Filter and power amplifier supply concentrates among Japanese and US component specialists, creating input cost volatility when capacity tightens.
- Carrier Certification Friction:FCC Part 27 and CE marking under the EU Radio Equipment Directive impose twelve-to-eighteen month qualification timelines that delay product launches and freeze working capital.
- Satellite IoT Substitution:Low-earth-orbit constellations from SpaceX and others are capturing remote monitoring applications previously served by cellular NB-IoT, particularly in maritime and agriculture.
Strategic Opportunities
- India Manufacturing Localization:PLI scheme incentives and TRAI spectrum allocations are drawing module assembly capacity toward domestic production for South Asian smart grid and fleet management demand.
- Healthcare Wearables Convergence:FDA breakthrough device designation pathways for continuous glucose monitors and cardiac patches are creating certified module demand that commands pricing premiums.
- Cybersecurity Labeling Tailwinds:ETSI harmonized standards for cyber resilience and emerging US FCC cybersecurity labeling programs are creating compliance-based differentiation for hardened module variants.
Industry Challenges
- RF Engineering Talent Scarcity:mmWave antenna design and carrier aggregation optimization require specialized expertise concentrated among semiconductor veterans, constraining product development velocity.
- Multi-Region Certification Burden:Simultaneous FCC, CE, and MIIT qualification campaigns for global product lines strain regulatory affairs teams and extend time-to-revenue.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cellular IoT Module Market |
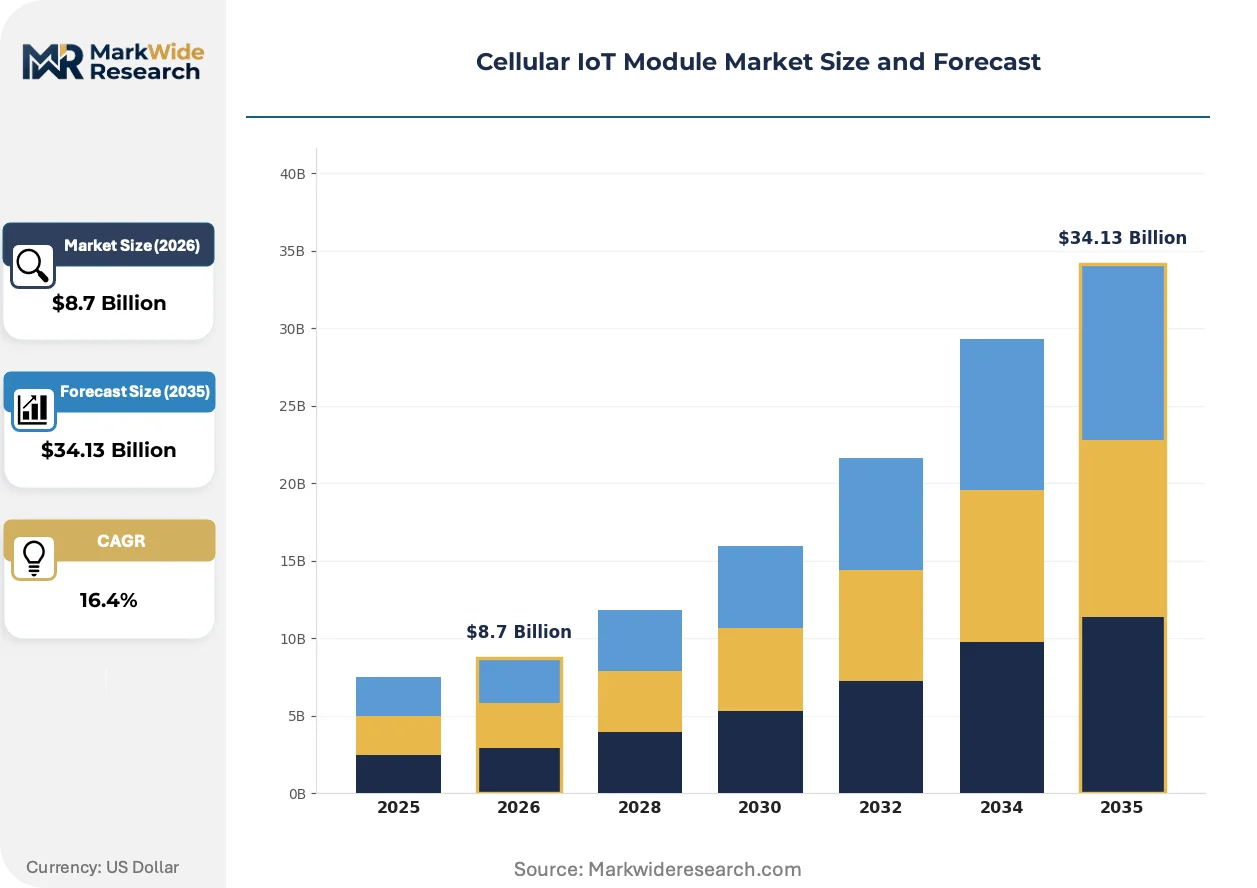
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LTE, NB-IoT, HSPA, 5G End User: Smart Cities, Automotive, Agriculture, Healthcare Deployment: On-Premise, Cloud, Hybrid, Managed Application: Asset Tracking, Smart Metering, Wearable Devices, Industrial Automation |
| Companies Covered | Nordic Semiconductor ASA, Quectel Wireless Solutions, Qualcomm Incorporated, Thales DIS, u-blox, Sierra Wireless, Semtech Corporation, MeiG, Telit Communications, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cellular IoT Module Market Strategic Shifts
Module architecture is fragmenting across integrated versus discrete chipset strategies as manufacturers balance cost, flexibility, and certification control in diverging ways.
System-in-package designs are modularizing baseband, RF transceiver, and memory components into single-die or multi-chip modules that slash board area and simplify antenna matching. Industrial automation OEMs in Germany and Japan are adopting these platforms for compact motor controllers and robotic edge nodes. The consolidation is modularizing supply chain relationships, pressuring standalone RF component vendors to integrate or exit.
ETSI cybersecurity resilience standards and the EU Cyber Resilience Act are mandating secure boot, firmware signing, and vulnerability disclosure for radio equipment placed on the European market. Module vendors must embed hardware security elements and maintain decade-long software update commitments. Smart metering and healthcare verticals are responding earliest, building security certification into procurement specifications ahead of formal deadlines.
Buyers are consolidating vendor relationships around module suppliers offering integrated cloud connectivity platforms and device management tools rather than standalone hardware. Agricultural fleet operators and logistics providers are shifting procurement toward subscription bundles that include SIM management, firmware over-the-air services, and analytics dashboards. This bundling is most advanced in the United States, where carrier-direct channel partnerships are displacing traditional distribution for enterprise-scale deployments.
Cellular IoT Module Market Segmentation
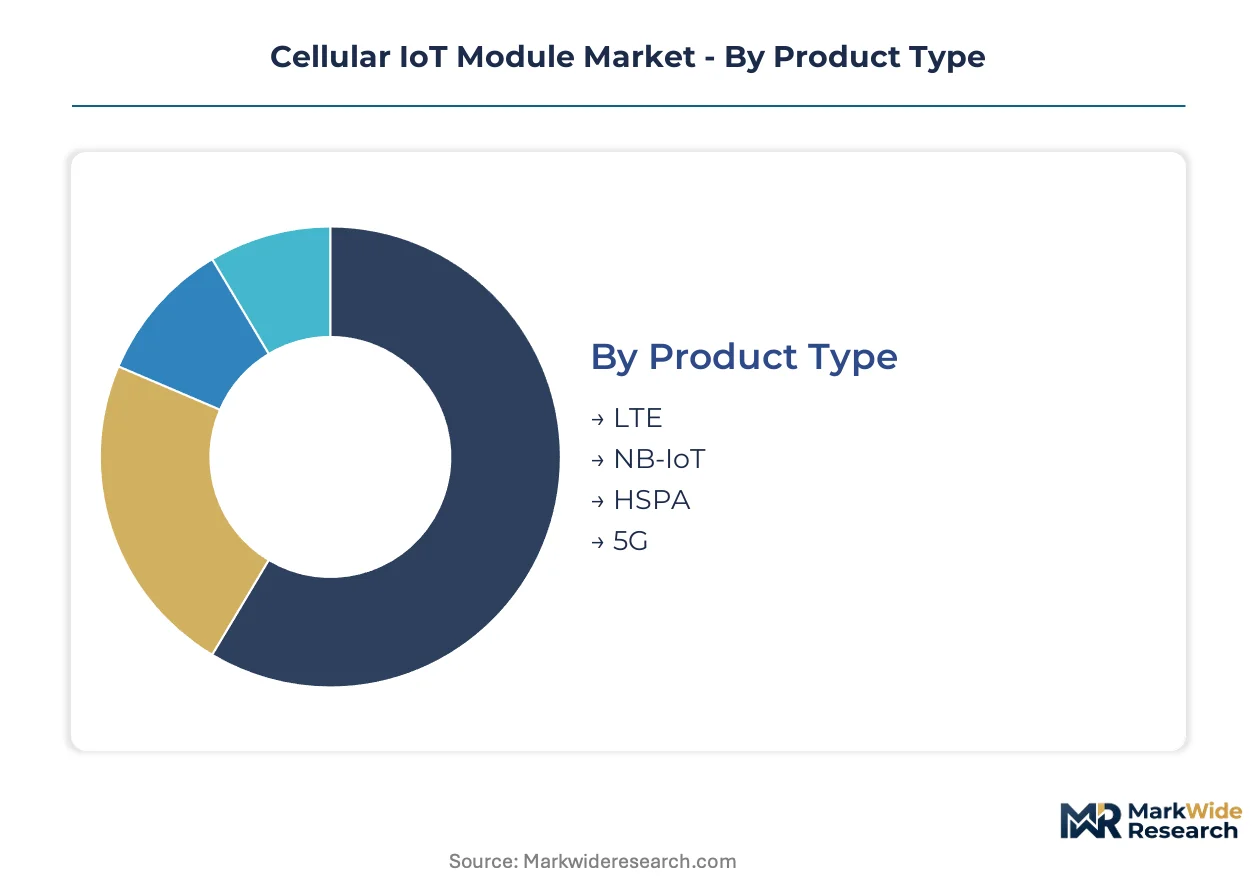
Cellular IoT module procurement decisions hinge on integration depth, with standalone modules serving rapid prototyping while embedded chipsets dominate high-volume OEM programs. Understanding how segments map to these deployment models clarifies margin structures and vendor selection criteria.
Product Type:
Integration depth varies sharply across cellular standards, with legacy platforms supporting discrete module procurement and 5G designs increasingly embedding into system-on-chip architectures.
- 5G:RedCap specifications enable mid-tier industrial sensors by trading peak throughput for cost efficiency. German automotive suppliers and Chinese robotics OEMs are consolidating procurement around these platforms for predictive maintenance endpoints.
- NB-IoT:Narrowband designs prioritize decade-long battery autonomy through extended discontinuous reception cycles. Utility regulators in China and Germany mandate these modules for advanced metering infrastructure where cellular penetration must reach underground vaults.
- LTE:Cat-1 and Cat-4 variants anchor fleet telematics and payment terminals requiring voice fallback and higher data rates.
- HSPA:Legacy 3G modules persist in cost-constrained agricultural monitoring where 4G coverage remains uneven.
NB-IoT leads volumes today; 5G is gaining share fastest.
End User:
Customer procurement maturity determines whether modules ship as certified standalone units or as bare chipsets for vertical integration.
- Smart Cities:Municipal infrastructure deployments demand pre-certified modules with decade-long supply guarantees. Streetlight controllers and waste bin sensors in Germany and the United States specify NB-IoT for low-power wide-area coverage.
- Automotive:Telematics control units integrate cellular modules for emergency calling and over-the-air firmware updates. NHTSA mandates and EU eCall regulations drive qualification rigor that favors established modem suppliers.
- Agriculture:Soil moisture and livestock trackers favor low-cost LTE-M modules with solar harvesting.
- Healthcare:FDA breakthrough device pathways for continuous glucose monitors create demand for modules with hardware security elements and encrypted boot chains.
Smart Cities dominates procurement scale; Healthcare shows the steepest expansion trajectory.
Deployment:
Operational control preferences split buyers between self-managed infrastructure and carrier-integrated service bundles.
- Managed:Third-party operators handle SIM provisioning, firmware updates, and SLA monitoring. Logistics providers in the United States are shifting procurement toward these subscription bundles that include analytics dashboards.
- Cloud:Hyperscaler IoT platforms from AWS and Azure absorb module connectivity into broader edge computing contracts. Industrial automation OEMs in Germany favor this model for predictive maintenance rollouts.
- Hybrid:Split architectures keep sensitive control plane traffic on-premise while offloading telemetry to public cloud.
- On-Premise:Air-gapped deployments serve defense and critical infrastructure with private LTE networks.
Cloud deployments lead new contract value; Managed services are climbing the fastest.
Application:
Use-case power budgets and mobility requirements dictate module selection between stationary narrowband and mobile broadband platforms.
- Smart Metering:Electric, gas, and water utilities specify NB-IoT for 15-year battery life in meter pits and basements. Regulators in China and Germany compress AMI deployment timelines, creating sustained procurement pipelines.
- Asset Tracking:Container and trailer monitoring demands LTE Cat-1 with GPS convergence for geofencing and route optimization. Maritime operators are evaluating satellite-cellular hybrid modules as LEO coverage expands.
- Industrial Automation:Motor controllers and robotic edge nodes adopt 5G RedCap for deterministic latency without premium module pricing.
- Wearable Devices:Healthcare patches and worker safety badges prioritize compact system-in-package designs with biometric sensor fusion.
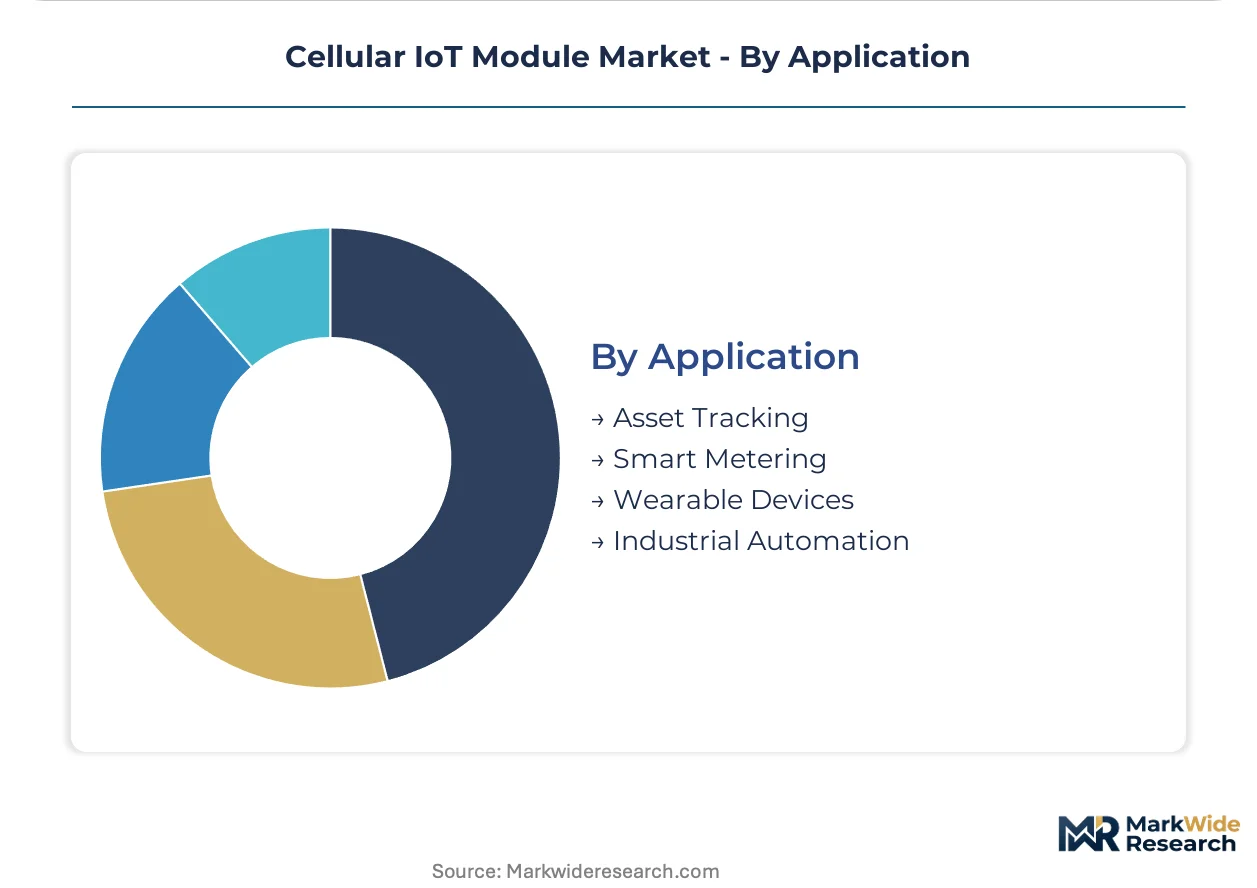
Smart Metering leads shipment volumes; Industrial Automation is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China compresses module cost curves through manufacturing scale while Germany enforces certification rigor that extends qualification timelines. The United States channels enterprise demand through carrier-direct partnerships. India and Japan represent emerging procurement centers with diverging regulatory frameworks.
China
Smart grid mandates and robotics OEM procurement drive volume demand for NB-IoT and 5G RedCap platforms. MIIT certification requirements and GB standards govern module qualification for domestic networks. Shenzhen and Shanghai manufacturing clusters concentrate integrated chipset-module production for export markets.
Germany
Utility regulators compress AMI deployment timelines, creating sustained procurement pipelines for decade-life metering modules. CE marking under the EU Radio Equipment Directive and ETSI cybersecurity resilience standards impose compliance layers. Bavarian industrial automation OEMs adopt system-in-package designs for compact motor controllers.
United States
Logistics providers and agricultural fleet operators shift procurement toward managed connectivity bundles with analytics dashboards. FCC Part 15 and Part 27 equipment authorization rules impose twelve-to-eighteen month qualification timelines. Carrier-direct channel partnerships in enterprise-scale deployments displace traditional distribution.
India
PLI scheme incentives and TRAI spectrum allocations draw module assembly capacity toward domestic production. CEA smart grid roadmaps mandate cellular connectivity for distribution automation. Tamil Nadu and Gujarat electronics manufacturing zones attract chipset integration facilities for South Asian demand.
Japan
Industrial automation OEMs and automotive telematics suppliers drive demand for compact, high-reliability modules. METI standards and JIS certification frameworks govern radio equipment market access. Nagoya and Osaka industrial clusters specialize in robotic edge node integration with deterministic latency requirements.
Cellular IoT Module Market Competitive Environment
Chinese producers anchor one tier through manufacturing scale across multiple cellular standards; European specialists hold premium positioning through certification expertise and security-hardened designs. The vendor base stratifies into three tiers: integrated chipset-module platforms, ultra-low-power specialists, and premium 5G modem suppliers. Dominant competitive moves include strategic partnerships with cloud hyperscalers and geographic expansion into India through PLI-aligned manufacturing.
Within the scale-driven tier, Quectel Wireless Solutions and MeiG exemplify volume manufacturing archetypes. Nordic Semiconductor ASA occupies a specialist position in ultra-low-power LTE-M designs. Qualcomm Incorporated anchors premium-tier positioning through modem portfolio leverage. These three represent distinct strategic postures: manufacturing scale, power optimization specialization, and premium chipset integration.
| Leading Market Players |
|---|
| Nordic Semiconductor ASA |
| Quectel Wireless Solutions |
| Qualcomm Incorporated |
| Thales DIS |
| u-blox |
| Sierra Wireless |
| Semtech Corporation |
| MeiG |
| Telit Communications |
| Others |
Value Chain & Pricing Dynamics
5G RedCap standardization is compressing manufacturing cost curves while simultaneously concentrating production among integrated chipset-module platforms in China and Germany. This technology transition rewards suppliers with captive modem capabilities while squeezing margins for discrete component vendors unable to absorb certification overhead.
Pricing Analysis
Capacity additions in China are reshaping price floors for NB-IoT and LTE-M modules, forcing established suppliers to compete on decade-long supply guarantees rather than unit economics alone. Three-tier pricing structure across premium 5G, standard LTE, and economy NB-IoT levels reflects certification grade and volume scale differentiation. Cost compression in the NB-IoT tier is intensifying because Chinese manufacturers are flooding utility metering procurement pipelines. Agricultural fleet operators show highest price sensitivity; healthcare OEMs purchasing FDA breakthrough pathway modules demonstrate least sensitivity due to security-hardened specification requirements.
Supply Chain Analysis
Carrier certification timelines spanning FCC Part 27, CE marking, and MIIT protocols create gating bottlenecks that favor vertically integrated suppliers with dedicated regulatory affairs teams. Manufacturing concentrates in China, Germany, and the United States, with raw material dependencies spanning RF front-end components from Japanese filter specialists, power amplifiers from US semiconductor vendors, and substrate materials from Taiwanese packaging houses. Single-source vulnerability in mmWave antenna design talent constrains product development velocity across tier-two suppliers. Distribution runs through carrier-direct partnerships for enterprise-scale deployments in North America, while European and Asian markets retain traditional electronics distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cellular IoT module procurement is shifting toward premium specifications as ETSI cybersecurity resilience standards and emerging FCC labeling programs harden compliance baselines. This quality migration favors suppliers with decade-long software update commitments and hardware security element integration.
For Market Incumbents: Deepen backward integration into RF front-end components to insulate margin structures from Japanese and US supplier concentration. Fortify certification expertise across simultaneous FCC, CE, and MIIT qualification campaigns to compress time-to-revenue for global product lines. Satellite IoT substitution from LEO constellations threatens remote monitoring applications; defend positioning through cellular-satellite hybrid module development. For New Entrants and Emerging Players: Ultra-low-power system-in-package designs for healthcare wearables offer technology-first entry with pricing premiums attached to FDA breakthrough device pathways. Target India's PLI-aligned manufacturing zones where domestic assembly capacity for South Asian smart grid demand remains underdeveloped. Lead with integrated cloud connectivity platforms bundling SIM management and firmware over-the-air services rather than standalone hardware. For Investors and Strategic Acquirers: Valuations sit cheapest among discrete RF component vendors facing consolidation pressure from integrated chipset-module platforms. Five-to-ten year viability hinges on capturing share in 5G RedCap industrial automation rollouts where deterministic latency requirements favor established modem suppliers. Monitor TRAI spectrum allocation announcements and CEA smart grid procurement timelines as inflection indicators for Indian manufacturing localization plays.| Strategic Initiative | Industry Significance |
|---|---|
| Carrier-Direct Partnership Formation | AWS and Azure hyperscaler integrations displace traditional distribution for US enterprise logistics deployments. |
| System-in-Package Design Adoption | Bavarian motor controller OEMs consolidate procurement around compact modules slashing board area requirements. |
| Cybersecurity Certification Investment | ETSI harmonized standards and EU Cyber Resilience Act mandate decade-long firmware update commitments. |
| India PLI Manufacturing Localization | Tamil Nadu and Gujarat zones attract chipset integration facilities for CEA-mandated distribution automation. |
| Healthcare Wearables Convergence | FDA breakthrough pathways for cardiac patches create demand for encrypted boot chain modules. |
Study Parameters
Direct dialogue with cellular module procurement directors, RF engineering leads at industrial automation OEMs, carrier certification specialists, and utility smart grid planners grounds qualitative assessment in operational reality. Secondary validation draws from FCC equipment authorization databases, ETSI harmonized standard publications, MIIT certification registries, 3GPP release documentation, and semiconductor vendor SEC disclosures. Bottom-up shipment estimates by product type and application triangulate against top-down market value reconstructions.
Bottom-up modeling aggregates module shipment projections across NB-IoT, LTE-M, LTE Cat-1, and 5G RedCap standards, with value calculations incorporating average selling price trajectories by certification tier. Segmentation dimensions span cellular standard, end-use vertical, deployment model, and geographic regulatory cluster. CAGRs derive from fitted growth curves calibrated to historical adoption patterns in utility metering and asset tracking verticals. Key inputs include 3GPP Release 17 RedCap commercialization timelines, national AMI deployment mandates, and spectrum auction outcomes.
The model holds under stable carrier certification timelines and continued 3GPP standardization momentum; deviation in geopolitical trade restrictions or LEO satellite coverage expansion would shift volume forecasts materially. A model refresh is warranted upon material change in FCC cybersecurity labeling program implementation or major TRAI spectrum reallocation decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Wireless Smart Plug Market
Internet of Things (IoT)
GCC Indoor LBS Market
Internet of Things (IoT)
IoT Lpwans Market
Internet of Things (IoT)
IoT Application Development Services Market
Internet of Things (IoT)
Smart Pool Systems Market
Internet of Things (IoT)
AI in IoT Market
Internet of Things (IoT)
IoT Communication Protocol Market
Internet of Things (IoT)
IoT Software Market
Internet of Things (IoT)
Global Military IoT Market
Internet of Things (IoT)
IoT Cellular Market
Internet of Things (IoT)
Internet of Things (IoT) Connected Cars Market
Internet of Things (IoT)
IoT Utilities Market
Internet of Things (IoT)
5G IIOT Market
Internet of Things (IoT)
Europe IoT Device Market
Internet of Things (IoT)
Narrow Band IoT Tracker Market
Internet of Things (IoT)
IoT Microcontroller Market