
 AI in IoT Market | 2026-2036
AI in IoT Market Size, Share, and Industry Trends Forecast 2026-2036
AI in IoT Market Analysis
Embedded systems engineering talent scarcity is reorganizing how vendors allocate R&D resources across the AI in IoT landscape. Cisco anchors its position through extensive channel control in enterprise networking infrastructure. Arm specializes in semiconductor IP licensing that powers edge inference workloads across billions of connected endpoints. Samsara dominates fleet telematics by sustaining hardware-software integration in transportation IoT deployments.
AI in IoT denotes the integration of machine learning algorithms with networked sensor ecosystems to enable autonomous decision-making at the edge without persistent cloud dependency, typically operating on sub-10-watt microcontrollers with latency thresholds under 50 milliseconds for real-time industrial control. The primary commercial purpose centers on transforming raw telemetry streams into actionable operational intelligence across distributed physical assets. Predictive analytics solutions command the largest revenue share as manufacturers prioritize uptime optimization over capex-heavy sensor hardware refreshes. Edge computing technology is expanding fastest where 5G connectivity backhaul remains uneconomical for remote asset monitoring in mining and agriculture.
The EU AI Act and GDPR impose algorithmic transparency mandates on automated decision systems processing personal data from connected health and home devices. The FCC in the United States governs spectrum allocation for unlicensed IoT radio protocols, directly constraining device density and transmission power in dense urban sensor deployments. ISO/IEC standards for AI risk management provide baseline conformity pathways for vendors seeking cross-border market access. Stakeholders must weigh regulatory fragmentation against the cost of region-specific compliance architectures as enforcement timelines solidify.
Market Dynamics
Embedded systems engineering talent scarcity is compressing R&D timelines across the AI in IoT landscape, forcing vendors to consolidate around pre-certified hardware-software stacks rather than custom silicon development.
Growth Catalysts
- EU AI Act compliance mandates:The EU AI Act's risk-based classification system for connected devices is accelerating procurement of certified edge inference modules among European healthcare and smart home manufacturers seeking market access.
- Predictive maintenance adoption:German automotive and industrial machinery operators are deploying vibration-sensor-plus-ML pipelines to minimize unplanned downtime, creating sustained demand for sub-50-millisecond latency edge compute.
- 5G network slicing:Telecommunications infrastructure investments in South Korea and Japan are enabling guaranteed-quality connectivity for mission-critical IoT control loops in remote mining and port automation.
Market Restraints
- Semiconductor foundry concentration:Advanced node capacity at TSMC and Samsung Foundry remains constrained, extending lead times for AI-optimized microcontrollers below 7 nanometers.
- GDPR algorithmic transparency requirements:The EU's mandated explainability for automated decision systems processing personal telemetry increases firmware development costs for health and residential IoT vendors.
- Legacy OT-IT integration friction:Brownfield industrial sites running decades-old SCADA architectures face prohibitive retrofit costs to accommodate modern edge AI inference engines.
Strategic Opportunities
- India manufacturing incentives:The country's PLI scheme for electronics and semiconductors is attracting module assembly and test operations previously concentrated in coastal China.
- Agricultural drone autonomy:Computer-vision-enabled crop monitoring systems represent an underpenetrated application where 5G backhaul economics remain unfavorable for cloud-dependent alternatives.
- Fleet electrification telemetry:Battery state-of-health prediction algorithms are creating new attach rates for telematics hardware in commercial vehicle transitions across North American logistics operators.
Industry Challenges
- Embedded ML engineering scarcity:The intersection of signal processing, quantization-aware training, and real-time operating systems expertise remains critically undersupplied, inflating compensation premiums.
- ISO/IEC 42001 certification timelines:First-party conformity assessment for AI management systems is extending product launch schedules by six to nine months for vendors targeting multinational industrial accounts.
- Interoperability standard fragmentation:Competing consortium specifications from the Connectivity Standards Alliance, OPC Foundation, and fieldbus legacy bodies are forcing multi-protocol hardware designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI in IoT Market |
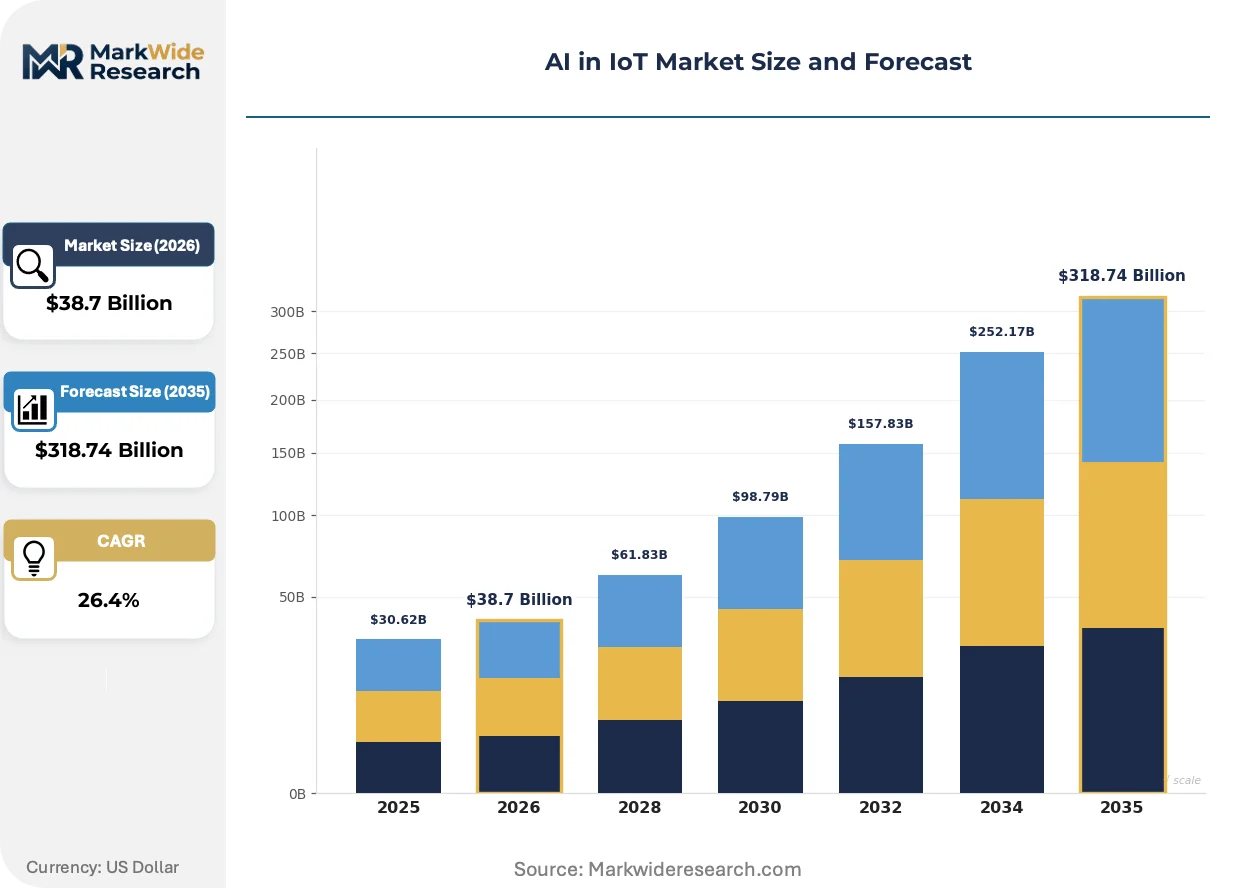
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $318.74 Billion |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Predictive Analytics, Machine Learning Platforms, Intelligent Edge Computing, Smart Sensors Application: Smart Home Automation, Industrial IoT, Healthcare Monitoring, Connected Vehicles End User: Consumer Electronics, Manufacturing Sector, Healthcare Providers, Transportation Companies Technology: Cloud Computing, Edge Computing, 5G Connectivity, Blockchain |
| Companies Covered | Samsara, Azilen Technologies, Arm, SumaSoft, LeewayHertz, Cisco, Sierra Wireless, Innowise, PTC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI in IoT Market Emerging Trajectories
Edge AI deployment architectures are splitting between ultra-low-power microcontroller inference and gateway-aggregated processing, with vendor strategies diverging based on latency requirements and connectivity economics rather than converging on a single dominant topology.
Neural architecture search (NAS) automation for resource-constrained targets is bifurcating the competitive landscape. Semiconductor IP vendors are embedding NAS tools directly into SDKs, enabling OEMs without dedicated ML teams to deploy optimized models. Automotive Tier 1s are adopting these flows fastest, compressing the traditional six-month model optimization cycle into weeks. This capability is compressing margins for boutique edge AI consultancies that previously commanded premium fees for manual quantization and pruning.
The EU AI Act's high-risk system registration requirements are reshaping product development roadmaps for connected health monitors and biometric access control. Manufacturers must now maintain technical documentation and human oversight protocols from design inception, not as aftermarket compliance patches. German and French medical device vendors are responding by segregating EU-bound SKUs from lower-obligation export variants, fragmenting their hardware-software release trains.
Industrial buyers are consolidating vendor relationships around full-stack platform providers capable of hardware, connectivity management, and model lifecycle operations. Discrete component procurement from separate sensor, gateway, and analytics suppliers is retreating among mid-sized manufacturers lacking internal integration capabilities. This pattern is most pronounced in US food processing and cold chain logistics, where uptime guarantees now override unit cost minimization in sourcing criteria.
AI in IoT Market Segmentation
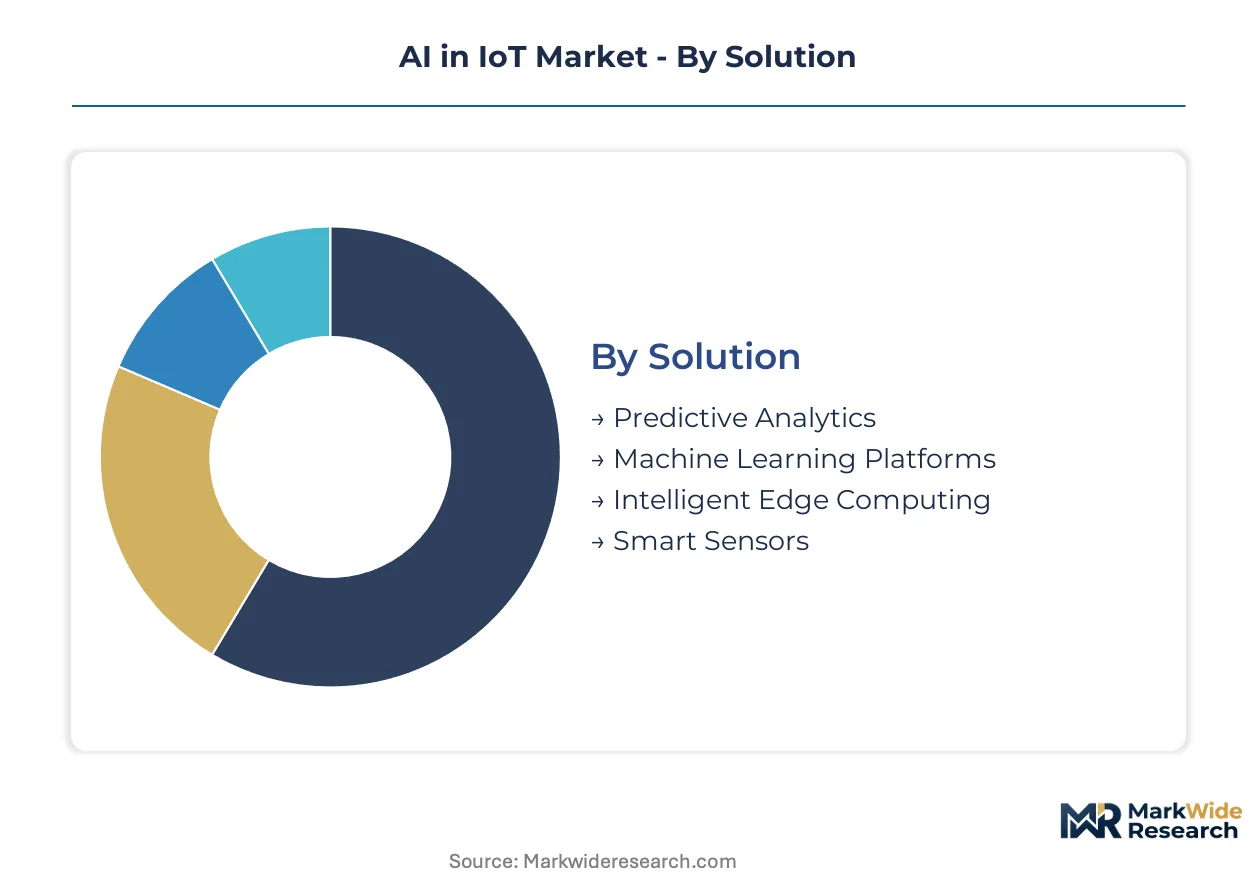
Segmentation in AI in IoT reveals where substitution pressure reshapes procurement priorities. Vendors must align solution architectures with the specific latency, connectivity, and compliance requirements of each slice.
Solution:
Predictive Analytics faces intensifying substitution pressure from Intelligent Edge Computing as manufacturers prioritize real-time inference over cloud-dependent batch processing.
- Predictive Analytics:Cloud-hosted statistical models process historical telemetry to forecast equipment failures and demand patterns. German automotive suppliers and US food processors dominate procurement, driven by uptime guarantee contracts that penalize unplanned downtime.
- Intelligent Edge Computing:Sub-10-watt microcontrollers execute quantized neural networks locally without persistent connectivity. Mining operations in Western Australia and agricultural deployments in Brazil's Cerrado region adopt these systems where cellular backhaul remains uneconomical.
- Machine Learning Platforms:SDKs and training pipelines enabling OEMs to develop custom models without dedicated ML engineering teams.
- Smart Sensors:MEMS devices with embedded inference accelerators for vibration, acoustic, and environmental monitoring.
Predictive Analytics retains volume leadership; Intelligent Edge Computing holds the steepest expansion curve.
Application:
Cost tier differentiation separates capex-heavy Industrial IoT deployments from subscription-model Smart Home Automation.
- Industrial IoT:SCADA-integrated edge AI systems for process optimization and safety monitoring. German machinery operators and South Korean semiconductor fabs concentrate demand, compelled by EU AI Act transparency mandates for high-risk automated decision systems.
- Smart Home Automation:Voice-controlled and occupancy-aware residential energy management. US utility rebate programs and Japan's ZEH (Net Zero Energy House) subsidies accelerate thermostat and lighting controller adoption.
- Healthcare Monitoring:Continuous glucose monitors and cardiac telemetry with FDA and EMA algorithmic validation requirements.
- Connected Vehicles:Fleet telematics and battery state-of-health prediction for commercial electrification transitions.
Industrial IoT commands premium pricing; Smart Home Automation achieves the widest household penetration.
End User:
Customer type determines procurement complexity, with Manufacturing Sector buyers demanding ISO/IEC 42001 certification that Consumer Electronics markets rarely require.
- Manufacturing Sector:Brownfield industrial sites requiring OT-IT integration and legacy protocol translation. German Mittelstand firms and US metal fabricators prioritize vendors offering full-stack platform guarantees over discrete component sourcing.
- Healthcare Providers:Hospitals and clinics deploying FDA-cleared diagnostic algorithms on connected devices. EU AI Act high-risk system registration extends product launch timelines by six to nine months.
- Consumer Electronics:Smartphone and wearable OEMs integrating voice assistants and health sensors.
- Transportation Companies:Logistics operators attaching telematics hardware to commercial vehicle fleets for route optimization and compliance logging.
Manufacturing Sector generates the highest contract values; Healthcare Providers impose the most stringent compliance barriers.
Technology:
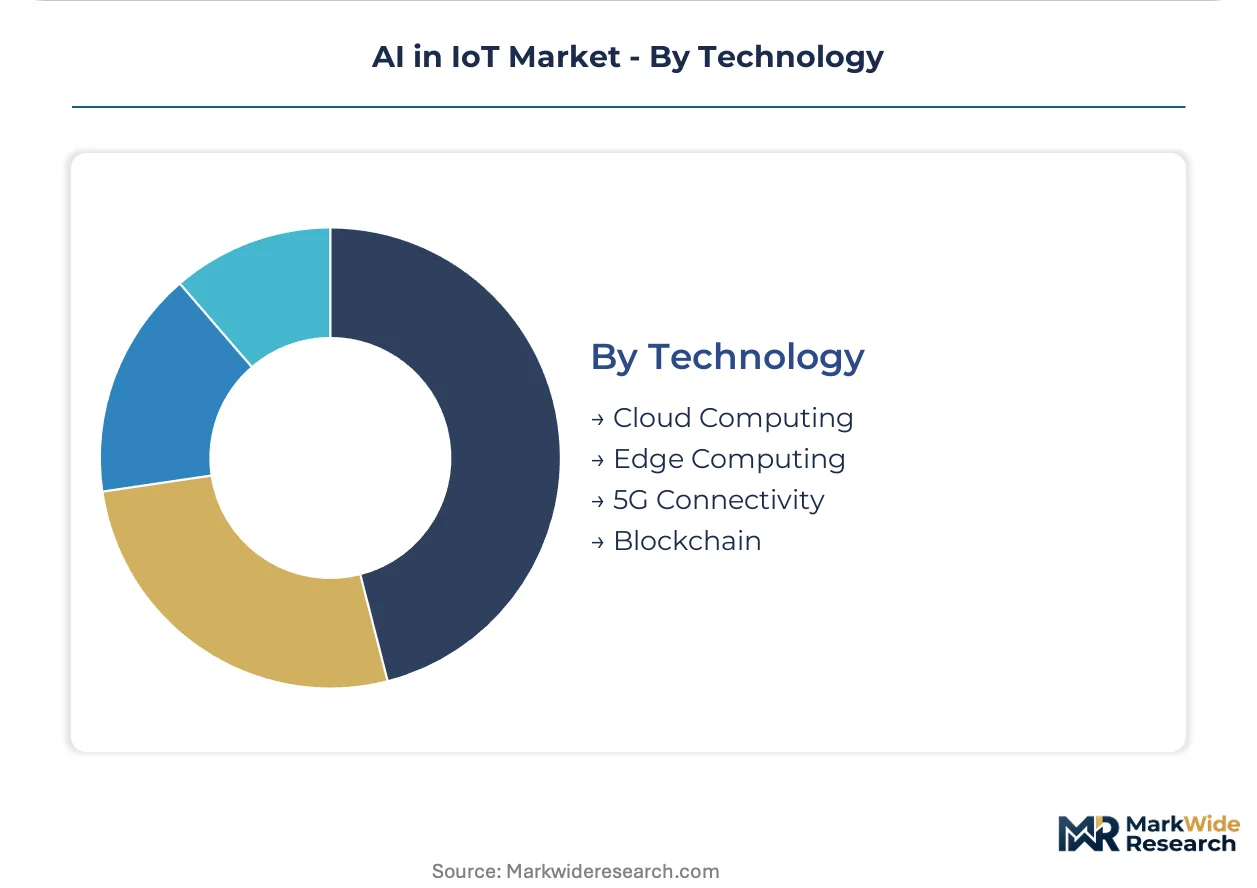
Supply concentration in advanced semiconductor foundries constrains deployment options for Cloud Computing and Edge Computing alike.
- Edge Computing:Distributed inference architectures processing data at the network periphery. 5G network slicing in South Korea and Japan enables guaranteed-latency control loops for port automation and remote mining.
- 5G Connectivity:Licensed spectrum deployments supporting device density and mobility requirements. FCC spectrum allocation decisions directly constrain transmission power in dense US urban sensor networks.
- Cloud Computing:Centralized model training and batch analytics for non-time-critical workloads.
- Blockchain:Distributed ledger applications for supply chain provenance and device identity verification.
Edge Computing captures the steepest investment trajectory; Cloud Computing maintains the largest installed analytics base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU AI Act anchors European demand for certified edge inference modules, while FCC spectrum decisions shape device density limits in United States urban deployments. Procurement concentrates in industrial corridors where regulatory clarity and manufacturing depth overlap.
Germany
Automotive suppliers and Mittelstand machinery operators drive demand for sub-50-millisecond latency edge compute under uptime guarantee contracts. The EU AI Act's high-risk system registration mandates algorithmic transparency documentation from design inception. Industrial clusters in Baden-Württemberg and Bavaria host vibration-sensor-plus-ML pipeline deployments for predictive maintenance.
United States
Food processors and cold chain logistics operators consolidate vendor relationships around full-stack platform providers offering uptime guarantees. FCC spectrum allocation governs transmission power for unlicensed IoT radio protocols in dense urban sensor networks. The Midwest manufacturing belt and Southeast logistics corridors anchor fleet telematics hardware attach rates for commercial vehicle electrification.
South Korea
Telecommunications infrastructure investments enable guaranteed-quality 5G network slicing for mission-critical IoT control loops. The national regulator enforces device certification standards for industrial automation systems. Port automation clusters in Busan-Ulsan and semiconductor fabs in the Seoul Capital Area concentrate edge AI deployment for remote monitoring.
India
Electronics and semiconductor assembly operations migrate under the PLI scheme for module test and packaging previously concentrated in coastal China. The Bureau of Indian Standards and TRAI shape connectivity and safety mandates for connected device ecosystems. Karnataka and Telangana host R&D centers addressing embedded ML engineering scarcity through specialized training pipelines.
Japan
Net Zero Energy House subsidies accelerate thermostat and lighting controller adoption in residential energy management. METI governs industrial IoT interoperability standards and AI risk management conformity pathways. The Kanto region around Tokyo and Chubu manufacturing belt around Nagoya concentrate smart factory edge inference deployments.
AI in IoT Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with semiconductor IP vendors and enterprise networking incumbents occupying distinct competitive territories. The vendor base organizes around three strategic archetypes: full-stack platform providers bundling hardware-software-connectivity, specialized edge AI consultancies offering model optimization services, and component suppliers licensing pre-certified inference modules. Dominant competitive moves include strategic partnerships between cloud hyperscalers and industrial automation vendors, plus geographic expansion through regional system integrator channels.
Within the networking infrastructure tier, Cisco Systems, Inc. and Sierra Wireless, Inc. exemplify scale-driven platform consolidation. Arm Holdings plc occupies a position as the dominant semiconductor IP licensor powering edge inference workloads across billions of connected endpoints. Samsara Inc. represents the hardware-software integration archetype in fleet telematics, anchoring transportation IoT deployments through sustained vertical integration of sensors, connectivity, and analytics layers.
| Leading Market Players |
|---|
| Samsara |
| Azilen Technologies |
| Arm |
| SumaSoft |
| LeewayHertz |
| Cisco |
| Sierra Wireless |
| Innowise |
| PTC |
| Others |
Supply Flow & Price Mechanics
Long-term capacity reservation contracts with TSMC and Samsung Foundry lock in wafer supply and price visibility for edge AI microcontroller vendors serving automotive and industrial accounts. These arrangements transfer foundry pricing volatility risk to buyers while securing allocation priority during semiconductor shortage cycles.
Pricing Analysis
Price spreads between German automotive suppliers and Indian module assemblers exceed forty percent for equivalent inference accelerators. The dominant model is tiered subscription licensing bundled with hardware, where pricing stratifies across premium certified tiers for EU AI Act compliance, standard industrial grades, and economy unlicensed variants. Cost compression in economy tiers is intensifying because of India's PLI scheme attracting test and packaging migration from coastal China. Healthcare providers exhibit the least price sensitivity due to FDA and EMA validation requirements, while consumer electronics OEMs drive the hardest unit-cost negotiations.
Supply Chain Analysis
Inventory buffers for AI-optimized microcontrollers below seven nanometers have thinned to twelve weeks at key distributors. Supply concentrates in Taiwan, South Korea, and the United States for advanced node fabrication, while Malaysia and Vietnam handle backend assembly and test operations. Raw material dependencies span silicon wafers, rare earth elements for MEMS sensors, and high-purity gases for etching processes. Single-source vulnerability at TSMC for sub-five-nanometer AI accelerators represents the dominant structural risk. Distribution runs through authorized component distributors serving industrial automation OEMs and direct enterprise contracts for fleet telematics operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among mid-sized German manufacturers and US food processors demanding full-stack platform guarantees, squeezing margins for discrete component vendors unable to integrate hardware, connectivity, and analytics layers.
For Market Incumbents: Fortify channel control through exclusive distribution partnerships with industrial system integrators in Baden-Württemberg and the US Midwest manufacturing belt. Deepen backward integration into pre-certified edge inference module design to offset embedded ML engineering scarcity. The threat of neural architecture search automation embedded in semiconductor IP vendor SDKs is displacing boutique optimization consultancies; certification investment in ISO/IEC 42001 conformity pathways remains the priority lever for multinational industrial account retention. For New Entrants and Emerging Players: Lead with agricultural drone autonomy in Brazil's Cerrado and Western Australian mining regions where cellular backhaul economics prevent cloud-dependent alternatives. Battery state-of-health prediction for North American commercial fleet electrification represents the most penetrable attach-rate expansion opportunity. A channel partnership strategy with regional telematics distributors avoids direct confrontation with Samsara's vertically integrated transportation IoT stack. For Investors and Strategic Acquirers: Edge AI consultancies with quantization-aware training expertise and automotive Tier 1 relationships present the most defensible acquisition targets against NAS automation margin compression. Long-term viability hinges on differentiation through regulatory compliance depth rather than model optimization speed alone. The signal to monitor is EU AI Act enforcement timelines solidifying six-to-nine-month product launch extensions for high-risk system registrations.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Certification Investment | Accelerates market access for German medical device vendors facing high-risk system registration mandates. |
| Neural Architecture Search SDK Integration | Compresses model optimization cycles from months to weeks for automotive Tier 1 suppliers. |
| India PLI Scheme Manufacturing Migration | Attracts module assembly and test operations from coastal China to Karnataka and Telangana. |
| 5G Network Slicing Partnership | Enables guaranteed-latency control loops for South Korean port automation and remote mining. |
| Full-Stack Platform Consolidation | Meets uptime guarantee demands from US food processors and cold chain logistics operators. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with embedded systems engineers, industrial automation procurement leads, fleet telematics operators, and semiconductor IP licensing executives; and secondary validation through SEC filings from networking infrastructure vendors, hyperscaler capex disclosures, EU AI Act regulatory texts, and ISO/IEC standards documentation. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators anchored volume and value estimates.
Across the projection horizon, the analytical framework modeled solution type, application vertical, end-user procurement complexity, and technology deployment architecture. CAGRs were derived from segment-level growth trajectory analysis incorporating foundry capacity expansion timelines, regulatory enforcement phase-ins, and 5G infrastructure investment patterns. Edge inference latency requirements and EU AI Act compliance cost burdens served as primary forecast sensitivity inputs.
Forecasts assume regulatory continuity in EU AI Act implementation and FCC spectrum allocation regimes; material policy shifts would require re-modeling. Semiconductor foundry concentration risk, embedded ML engineering scarcity, and legacy OT-IT integration friction constitute specific revision triggers. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Smart Tracker Market
Internet of Things (IoT)
Airport Internet of Things Market
Internet of Things (IoT)
Indonesia IoT Market
Internet of Things (IoT)
North America IoT Node and Gateway Market
Internet of Things (IoT)
Airline IoT Market
Internet of Things (IoT)
Intelligent IoT Market
Internet of Things (IoT)
Cellular Internet of Things (IoT) Devices Market
Internet of Things (IoT)
Europe IoT Device Market
Internet of Things (IoT)
Industrial IoT Platform Market
Internet of Things (IoT)
IoT Gateway Devices Market
Internet of Things (IoT)
Narrowband-Internet of Things (NB-IoT) Market
Internet of Things (IoT)
LAMEA Bluetooth 5.0 Market
Internet of Things (IoT)
Global 5G Industrial IOT Market
Internet of Things (IoT)
IoT Technology Market
Internet of Things (IoT)
Smart Home M2M Market
Internet of Things (IoT)
Smart Connected Device Market