
 Smart Sound and Gateway Market | 2026-2036
Smart Sound and Gateway Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Sound and Gateway Market Intelligence
Hi-resolution audio certification is collapsing the boundary between premium and mass-tier smart sound hardware. Sonos Inc. anchors its position through proprietary mesh networking architecture that extends room-to-room synchronization capabilities. Amazon.com Inc. leverages Alexa Voice Service integration to dominate voice-first gateway interfaces across third-party hardware ecosystems. Bose Corporation specializes in acoustic engineering differentiation that sustains pricing power in home entertainment configurations.
Smart sound and gateway systems encompass networked audio endpoints and protocol translation hubs that enable interoperability between heterogeneous IoT devices, typically incorporating DSP chipsets with sub-10ms latency thresholds and multi-standard radio front-ends for seamless handoff between Bluetooth LE, Wi-Fi 6, and 802.15.4-based mesh networks. These systems serve commercial and residential environments by consolidating fragmented device control planes into unified voice and app-driven interfaces. Smart speakers lead volume deployment due to their dual function as audio output and command hub, while Thread-enabled gateways represent the fastest-expanding technology segment as Matter compliance becomes mandatory for ecosystem certification. Soundbars capture disproportionate margin pools in entertainment systems where Dolby Atmos decoding and HDMI 2.1 eARC connectivity command hardware premiums.
FCC Part 15 emissions rules in the United States and CE marking under the EU Radio Equipment Directive shape hardware certification timelines and radio spectrum allocation for multi-protocol gateways. ETSI EN 303 645 cybersecurity standards and California's SB-327 IoT security law are forcing firmware update mandates and password hardening across supply chains. Stakeholders must monitor regulatory divergence between regional cybersecurity frameworks and protocol certification requirements when planning multi-country product rollouts.
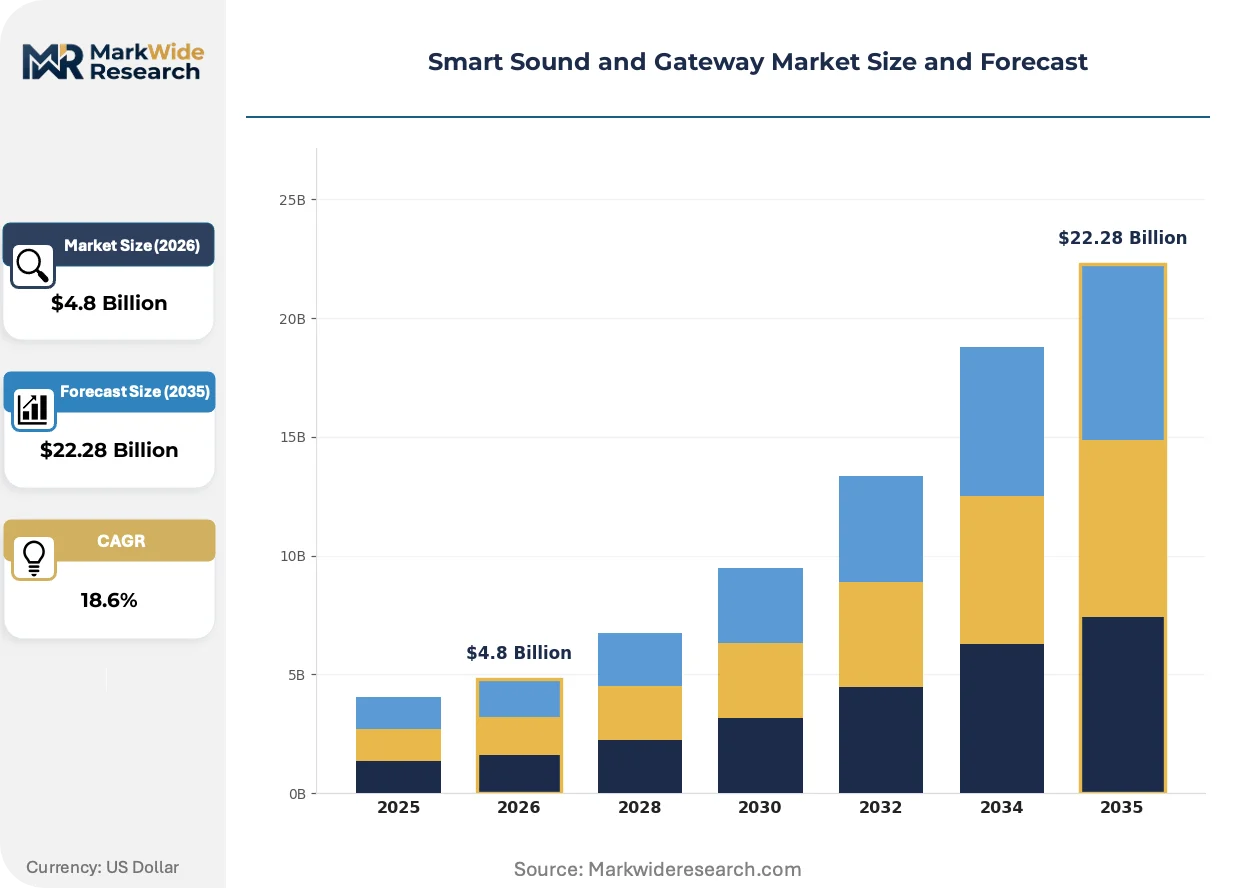
Market Dynamics
Matter protocol standardization is collapsing compatibility barriers across smart home ecosystems, forcing gateway manufacturers to consolidate multi-protocol radio architectures into unified hardware platforms that simultaneously support Thread, Zigbee, and Wi-Fi 6 handoff.
Growth Catalysts
- MIIT IoT Infrastructure Mandates:China's Ministry of Industry and Information Technology has accelerated gateway deployment through national broadband expansion programs targeting residential fiber penetration thresholds.
- Hi-Resolution Audio Certification:Consumer electronics buyers now demand studio-grade playback specifications that compress the performance gap between mass-tier and premium smart speaker hardware.
- Residential System Integrator Channel:Professional installation networks across the United States and Germany are bundling multi-room audio with gateway control layers, expanding average project values.
Market Restraints
- DSP Chipset Supply Concentration:Taiwan-based foundry capacity constraints for sub-10ms latency audio processors create procurement bottlenecks for gateway OEMs.
- FCC Part 15 Certification Timelines:Multi-protocol radio emissions testing for simultaneous Bluetooth LE, Wi-Fi 6, and 802.15.4 operation extends hardware launch cycles by four to six months.
- HDMI 2.1 eARC Component Costs:Dolby Atmos decoding chipsets and enhanced audio return channel controllers inflate bill-of-materials for soundbar-integrated gateway configurations.
Strategic Opportunities
- India Smart Home Underpenetration:Sub-5% residential automation adoption rates in Tier-2 and Tier-3 cities create first-mover positioning for voice-first gateway bundles.
- CE Marking Cybersecurity Convergence:ETSI EN 303 645 compliance is becoming a procurement filter for European retail channels, rewarding early firmware hardening investments.
- Commercial Hospitality Integration:Thread-enabled room control systems are displacing proprietary hotel automation backbones in premium property renovation cycles.
Industry Challenges
- Embedded Systems Talent Scarcity:Firmware engineering for real-time audio DSP pipeline optimization commands salary premiums that compress R&D budgets at mid-tier hardware vendors.
- Multi-Protocol Interoperability Testing:Certification complexity across Matter, Zigbee 3.0, and proprietary mesh stacks strains quality assurance timelines before mass production ramps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Sound and Gateway Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Speakers, Audio Interfaces, Soundbars, Wireless Transmitters Technology: Bluetooth, Wi-Fi, Zigbee, Thread Application: Home Automation, Entertainment Systems, Smart Appliances, Personal Devices Customer Type: Consumer Electronics Retailers, Direct Consumers, System Integrators, OEMs |
| Companies Covered | Alibaba Group Holding Limited, Sonos Inc., Amazon.com Inc., Sony Corporation, Samsung Electronics, Google LLC (Alphabet Inc.), Baidu Inc., Bose Corporation, Apple Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Sound and Gateway Market Strategic Shifts & Innovations
Audio endpoint hardware and protocol translation layers are undergoing simultaneous transformation as semiconductor integration enables single-chip solutions that previously required discrete radio modules and dedicated DSP coprocessors.
Edge AI inference engines for local voice command processing are bifurcating smart speaker architectures into cloud-dependent and cloud-optional tiers. Premium residential buyers in Germany and Japan now specify on-device natural language understanding that eliminates latency from round-trip server communication. This capability compression is enabling offline operation during network outages while reducing ongoing API licensing costs for hardware OEMs.
California's SB-327 IoT security law is mandating unique password generation and firmware update capabilities for all connected devices sold in the state. Hardware manufacturers serving the US market must now embed secure boot architectures and over-the-air update pipelines from initial design phases. Soundbar and gateway vendors with existing CE marking infrastructure are adapting ETSI EN 303 645 frameworks to satisfy both regulatory regimes through unified engineering investments.
Professional installation channels are consolidating procurement authority for whole-home audio and automation systems. Residential system integrators in the United States now specify gateway platforms based on centralized fleet management APIs rather than end-user feature differentiation. This specification shift compresses hardware margins while elevating software licensing and recurring service revenue components in vendor P&L structures.
Smart Sound and Gateway Market Segmentation
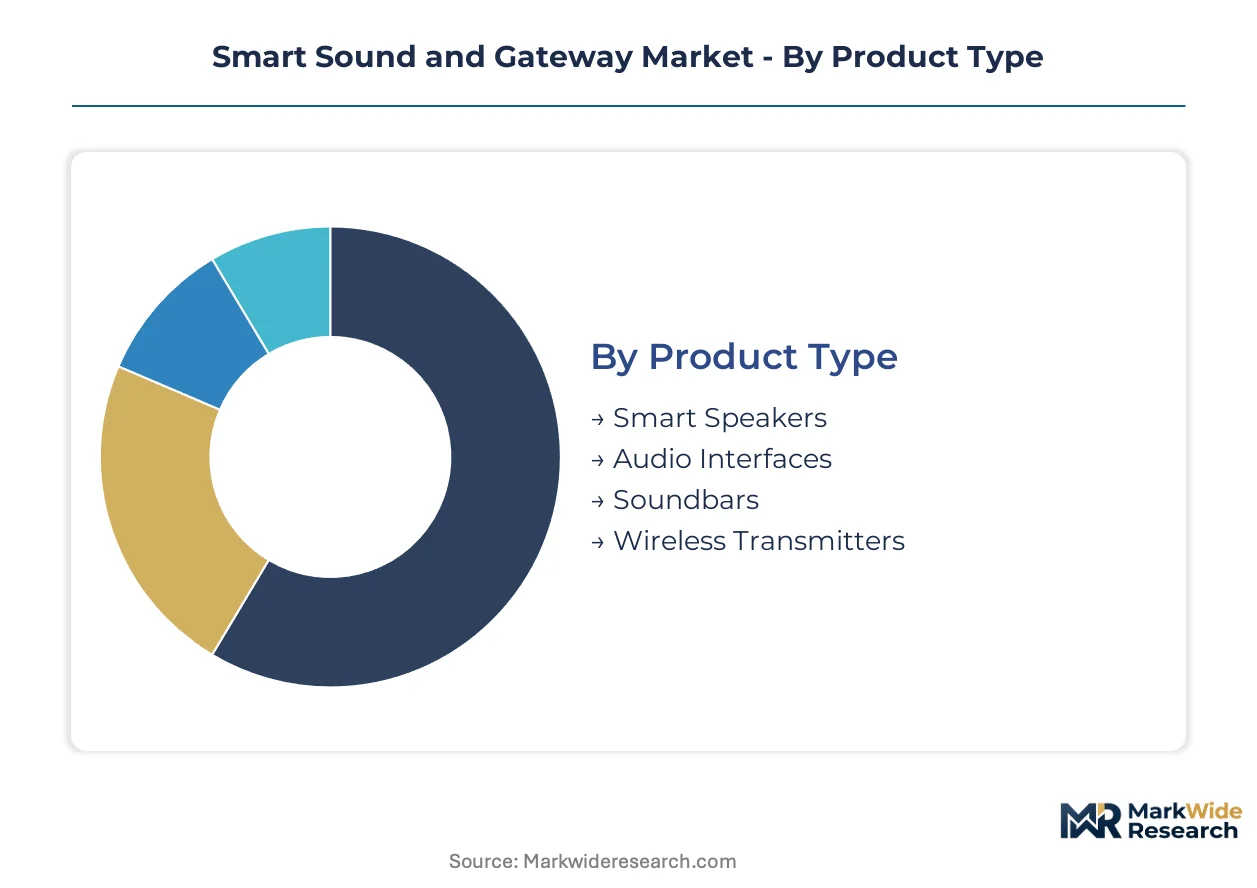
Smart sound and gateway hardware fragments across multiple technical dimensions that reshape procurement priorities. Product architecture, radio protocol, deployment context, and channel structure each create distinct margin profiles and certification requirements.
Product Type:
Soundbars face the most acute substitution pressure from television-integrated audio systems that bypass external hardware entirely.
- Smart Speakers:Dual-function endpoints combining far-field microphone arrays with full-range drivers and protocol translation hubs. Demand concentrates in China's Tier-1 cities where MIIT broadband mandates accelerate whole-home voice control deployment.
- Soundbars:Multi-channel audio systems with HDMI 2.1 eARC connectivity and Dolby Atmos decoding chipsets. Residential system integrators in Germany bundle these with gateway control layers, expanding average project values despite component cost inflation.
- Audio Interfaces:Professional-grade DAC and ADC modules bridging analog audio sources with networked distribution systems.
- Wireless Transmitters:Compact radio modules enabling retrofit connectivity for legacy speaker installations.
Smart Speakers retain volume leadership; Soundbars hold the steepest expansion curve.
Technology:
Protocol selection now pivots on Matter certification timelines rather than standalone technical merit.
- Thread:Low-power mesh networking built on 802.15.4 radio with IPv6 native addressing and sub-250ms network join times. Gateway OEMs in Shenzhen prioritize Thread radio front-ends to satisfy CSA certification requirements for ecosystem interoperability.
- Wi-Fi:High-throughput connectivity leveraging 6GHz spectrum and WPA3 encryption for bandwidth-intensive audio streaming. Smart speaker manufacturers source Wi-Fi 6 chipsets from Taiwan-based foundries facing capacity constraints for sub-10ms latency processors.
- Bluetooth:Point-to-point audio transport with LE Audio and Auracast broadcast capabilities.
- Zigbee:Mature mesh protocol retaining installed base in legacy home automation deployments.
Wi-Fi dominates current shipment volumes; Thread captures the most aggressive deployment momentum.
Application:
Entertainment Systems command the highest average selling prices but face cyclical pressure from residential construction volatility.
- Home Automation:Centralized control layers unifying lighting, climate, and security through voice and app interfaces. System integrators in the United States specify gateway platforms based on fleet management API capabilities rather than end-user feature differentiation.
- Entertainment Systems:Multi-room audio distribution with synchronized playback across spatially distributed endpoints. Premium property renovations in Dubai and Riyadh displace proprietary hotel automation backbones with Thread-enabled room control systems.
- Smart Appliances:Voice-enabled interaction surfaces for kitchen and laundry equipment.
- Personal Devices:Portable audio endpoints with embedded assistant functionality.
Home Automation anchors current revenue concentration; Entertainment Systems generate the highest margin per unit.
Customer Type:
System Integrators are consolidating procurement authority and compressing hardware margins while elevating software licensing components.
- System Integrators:Professional installation networks specifying multi-protocol gateway platforms for whole-home automation. These channels in Germany and the United States now require centralized fleet management APIs and over-the-air update pipelines from initial design phases.
- Consumer Electronics Retailers:Mass-market distribution through big-box and e-commerce channels with CE marking and FCC Part 15 certification as procurement filters.
- Direct Consumers:End-user purchases through manufacturer direct-to-consumer platforms.
- OEMs:White-label and component supply relationships for third-party brand integration.
System Integrators drive premium segment specification; Consumer Electronics Retailers move the highest unit volumes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundry capacity for DSP chipsets clusters in Taiwan, while gateway assembly scales through Shenzhen and Dongguan electronics corridors. MIIT broadband mandates in China and FCC certification requirements in the United States create divergent hardware launch timelines across major demand centers.
United States
Residential system integrators in California and Texas specify gateway platforms with centralized fleet management APIs. FCC Part 15 emissions testing for multi-protocol radios extends hardware certification cycles by four to six months. Greater Boston and Pacific Northwest metro areas concentrate smart speaker demand among early-adopter demographics.
China
MIIT's national broadband expansion targets residential fiber penetration thresholds that accelerate whole-home voice control deployment. Baidu's DuerOS platform reshapes gateway specification patterns across Tier-1 cities. Shenzhen and Dongguan electronics manufacturing corridors scale Thread-enabled gateway production for Matter certification compliance.
Germany
Professional installation networks bundle multi-room audio with gateway control layers, expanding average project values. ETSI EN 303 645 cybersecurity standards filter European retail procurement, rewarding early firmware hardening investments. Bavaria and North Rhine-Westphalia anchor system integrator channel concentration.
India
Sub-5% residential automation adoption in Tier-2 and Tier-3 cities creates first-mover positioning for voice-first gateway bundles. TRAI's broadband infrastructure directives support fiber deployment in Maharashtra and Karnataka. Bangalore and Hyderabad electronics clusters incubate local gateway OEM capacity.
Japan
Premium residential buyers specify on-device natural language understanding that eliminates latency from round-trip server communication. METI's IoT security guidelines align with ETSI frameworks for unified engineering investments. Tokyo and Osaka metro areas concentrate demand for hi-resolution audio certification in entertainment systems.
Smart Sound and Gateway Market Key Industry Players
Concentration sits with cloud-platform operators and acoustic engineering specialists that anchor opposing ends of the value chain. The vendor base spans three distinct tiers: voice-service platforms, audio hardware purists, and diversified consumer electronics conglomerates. Strategic moves center on protocol certification races for Matter compliance and embedded AI inference capabilities for local command processing.
Among voice-service platform operators, Amazon.com Inc. and Google LLC exemplify the cloud-first archetype that dominates third-party hardware integration. Sonos Inc. and Bose Corporation occupy positions within the acoustic engineering tier that sustains pricing power through differentiated hardware. Samsung Electronics and Sony Corporation represent diversified conglomerates leveraging display and entertainment ecosystem synergies.
| Leading Market Players |
|---|
| Alibaba Group Holding Limited |
| Sonos Inc. |
| Amazon.com Inc. |
| Sony Corporation |
| Samsung Electronics |
| Google LLC (Alphabet Inc.) |
| Baidu Inc. |
| Bose Corporation |
| Apple Inc. |
| Others |
Cost & Logistics Intelligence
Thread radio front-ends substituting for discrete Zigbee and Wi-Fi modules are compressing hardware costs while concentrating procurement leverage among Shenzhen gateway OEMs serving Matter certification timelines. This substitution dynamic simultaneously accelerates supply chain consolidation in China's electronics manufacturing corridors and compresses pricing premiums previously captured by multi-protocol discrete architectures.
Pricing Analysis
FCC Part 15 certification dictates the pricing tier structure across smart sound and gateway hardware, with CE marking under ETSI EN 303 645 adding parallel compliance premiums for European-bound shipments. Pricing stratifies across Matter-certified premium tiers, legacy protocol standard tiers, and unbundled economy tiers lacking integrated voice processing. Cost compression in mass-tier smart speakers is intensifying because Taiwan foundry constraints on sub-10ms latency DSP chipsets force allocation priority toward premium soundbar configurations. Residential system integrators exhibit the lowest price sensitivity due to project-based procurement, while direct consumer channels face acute margin pressure from e-commerce price transparency.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for low-latency audio processors, while Shenzhen and Dongguan electronics corridors handle gateway assembly and Thread radio module integration. The supply chain draws from Taiwan-based DSP foundry output, Korean memory components, and Chinese PCB substrate capacity. Single-source vulnerability concentrates in Taiwan's sub-10ms audio processor foundry capacity, where allocation queues extend hardware launch timelines. Distribution runs through professional system integrator channels in Germany and the United States, with consumer electronics retailers handling mass-market smart speaker volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating around residential system integrators and professional installation networks, fragmenting procurement authority away from end-user feature preferences toward centralized fleet management API specifications.
For Market Incumbents: Shield market position through backward integration into Taiwan DSP foundry allocation contracts, securing sub-10ms latency processor priority amid capacity constraints. Accelerate Matter certification completion ahead of Connectivity Standards Alliance compliance deadlines to lock in ecosystem interoperability positioning. Channel control through exclusive system integrator fleet management API partnerships represents the critical defensive lever against cloud-platform operators expanding third-party hardware integration. For New Entrants and Emerging Players: Lead with white-space targeting of India's Tier-2 and Tier-3 cities where sub-5% residential automation penetration offers first-mover positioning for voice-first gateway bundles. Pursue commercial hospitality integration in Middle East premium property renovation cycles, where Thread-enabled room control systems displace proprietary automation backbones. A direct-to-installer go-to-market angle bypasses established retail channel gatekeepers and aligns with system integrator procurement consolidation trends. For Investors and Strategic Acquirers: The market sits at a protocol standardization phase that favors embedded AI inference capability holders over cloud-dependent voice service licensors. Long-term viability over the next decade hinges on on-device natural language understanding differentiation that eliminates latency-dependent server round-trips. Acquisition targets should display firmware hardening investments satisfying both California SB-327 and ETSI EN 303 645 frameworks. The signal to monitor is Matter certification completion rates among mid-tier gateway OEMs, which indicates ecosystem interoperability positioning and retail channel access viability.| Strategic Initiative | Industry Significance |
|---|---|
| Matter Certification Completion | Connectivity Standards Alliance compliance unlocks ecosystem interoperability and retail channel placement. |
| Embedded AI Inference Integration | On-device voice processing eliminates cloud latency and reduces ongoing API licensing cost exposure. |
| Taiwan Foundry Allocation Contracts | Sub-10ms DSP processor priority secures supply chain positioning amid Taiwan capacity constraints. |
| System Integrator API Partnership | Fleet management platform integration captures procurement authority consolidating among professional installers. |
| Dual-Regime Firmware Hardening | Unified engineering for California SB-327 and ETSI EN 303 645 accelerates multi-country rollout timelines. |
Research Approach
Two parallel data streams informed the analysis: primary field engagement with residential system integrators, gateway OEM procurement leads, Taiwan foundry planning officers, and connectivity protocol engineers; and secondary validation through FCC equipment authorization databases, MIIT broadband infrastructure disclosures, Connectivity Standards Alliance certification registries, and ETSI cybersecurity framework documentation. Bottom-up shipment estimates triangulated against top-down market sizing across product type, radio protocol, and deployment context segmentation dimensions.
Across the analysis window, volume and value projections modeled smart speaker, soundbar, and gateway hardware shipments by Thread, Wi-Fi 6, and legacy protocol adoption curves. Segmentation dimensions included product architecture, radio technology, application context, and customer channel structure. CAGRs derived from installed base replacement cycles, broadband infrastructure deployment trajectories, and protocol migration elasticity parameters. Forecast inputs incorporated MIIT fiber penetration mandates, Matter compliance deadline effects, and DSP foundry capacity utilization assumptions.
Forecasts assume regulatory continuity in FCC Part 15 emissions frameworks, CE marking under EU Radio Equipment Directive, and California SB-327 IoT security enforcement; material policy shifts in cybersecurity certification timelines or radio spectrum allocation would require re-modeling. Supply chain disruption scenarios including Taiwan foundry capacity constraints or protocol certification delays represent specific risk factors that could revise trajectory assumptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Asia-Pacific IoT Device Market
Internet of Things (IoT)
Solar Based Internet of Things (IoT) Market
Internet of Things (IoT)
IoT Platform Market
Internet of Things (IoT)
Cellular IoT Module Market
Internet of Things (IoT)
Smart Sprinkler Controller Market
Internet of Things (IoT)
North America Narrowband-Internet of Things (NB-IoT) Market
Internet of Things (IoT)
Qatar Internet of Things (IoT) Market
Internet of Things (IoT)
Europe Industrial IoT Market
Internet of Things (IoT)
IoT Lpwans Market
Internet of Things (IoT)
5G Internet of Things Market
Internet of Things (IoT)
Europe IoT Device Market
Internet of Things (IoT)
Global IoT Engineering Services Market
Internet of Things (IoT)
Bluetooth Smart Plugs Market
Internet of Things (IoT)
Internet of Everything Market
Internet of Things (IoT)
Internet of Things (IoT) in Manufacturing Market
Internet of Things (IoT)
Smart Tracker Market