
 Europe IoT Market | 2026-2036
Europe IoT Market Size, Share, and Industry Trends Forecast 2026-2036
Europe IoT Market Insights
Buyer concentration among European manufacturing conglomerates is hardening as large-scale industrial users consolidate vendor relationships around full-stack platform providers. Siemens leverages its digital twin portfolio to anchor long-term contracts with German automotive OEMs. Schneider Electric competes through edge-to-cloud integration expertise in French energy and building automation sectors.
Europe IoT encompasses networked sensor arrays, embedded microcontrollers, and low-power wireless protocols that transmit operational data to centralized or distributed analytics platforms. Devices typically integrate ARM Cortex-M cores with sub-gigahertz radio modules to achieve sub-milliwatt standby consumption for decade-long battery deployments. Industrial automation dominates value capture as manufacturers prioritize predictive maintenance and OEE optimization over consumer smart home installations. LPWAN connectivity is displacing legacy cellular in agricultural and utility metering deployments across Spain and Italy due to lower per-node connectivity costs. Edge computing architectures are gaining share in transportation and retail where sub-100-millisecond latency requirements exclude pure cloud routing.
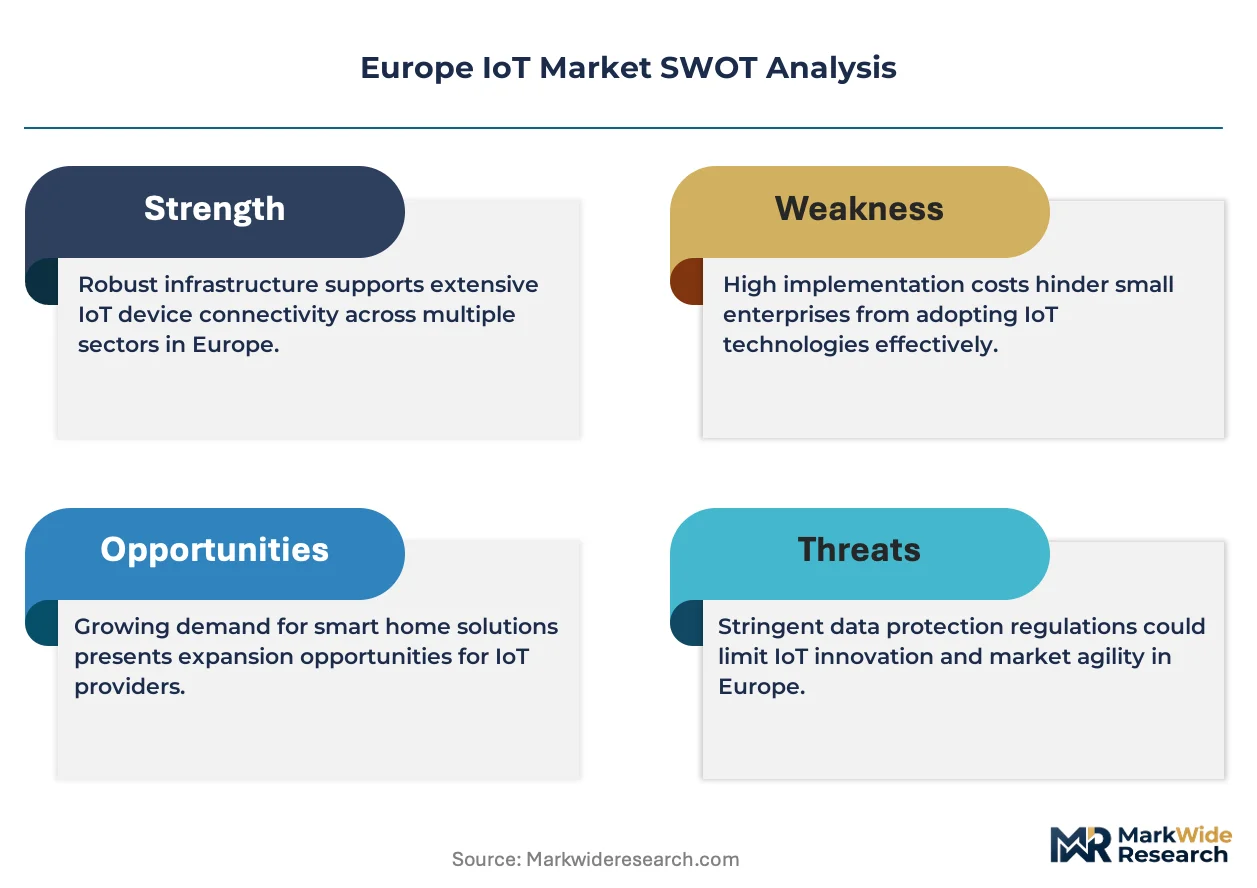
GDPR data sovereignty rules, the EU AI Act risk classification framework, and ETSI cybersecurity standards for consumer IoT collectively raise compliance barriers for non-European hardware vendors. ETSI EN 303 645 mandates baseline encryption and vulnerability disclosure, while the EU Green Deal drives energy-harvesting sensor demand in building management. Stakeholders must evaluate whether their certification roadmaps align with the Cyber Resilience Act's forthcoming hardware security requirements before committing to regional manufacturing partnerships.
Market Dynamics
The EU AI Act's risk classification framework and CSRD reporting mandates are hardening procurement requirements, forcing industrial buyers to consolidate vendor relationships around full-stack platform providers capable of demonstrating end-to-end compliance.
Growth Catalysts
- CSRD Mandates:Corporate Sustainability Reporting Directive requirements drive sensor deployments for emissions monitoring and energy optimization across German and French manufacturing facilities.
- Industrial Predictive Maintenance:German automotive OEMs expand vibration and thermal sensor arrays to minimize unplanned downtime and optimize Overall Equipment Effectiveness metrics.
- LPWAN Cost Advantage:Agricultural and utility metering operators in Spain and Italy replace legacy cellular with sub-gigahertz networks to cut per-node connectivity expenditures.
Market Restraints
- Semiconductor Supply Concentration:ARM Cortex-M microcontroller fabrication concentrates in East Asian foundries, exposing European device manufacturers to geopolitical supply disruptions.
- GDPR Compliance Friction:Data sovereignty requirements and cross-border transfer restrictions complicate cloud analytics architectures for multi-national industrial deployments.
- Battery Chemistry Volatility:Lithium-ion cell price fluctuations and raw material sourcing constraints affect decade-long deployment economics for energy-harvesting sensor alternatives.
Strategic Opportunities
- Edge-to-Cloud Convergence:Transportation and retail operators in the Netherlands deploy sub-100-millisecond latency architectures that exclude pure cloud routing, creating demand for hybrid compute nodes.
- Building Energy Harvesting:EU Green Deal incentives accelerate photovoltaic and thermoelectric-powered sensor demand for smart building management across Nordic markets.
- Cyber Resilience Act Preparation:Hardware vendors aligning certification roadmaps with forthcoming security requirements gain first-mover advantage in procurement cycles before mandatory enforcement.
Industry Challenges
- Embedded Security Engineering Shortage:ETSI EN 303 645 compliance requires specialized firmware cryptography expertise that European labor markets currently undersupply.
- Legacy System Integration Complexity:Brownfield manufacturing environments with proprietary industrial protocols demand costly gateway development to enable IoT connectivity.
- Multi-Standard Certification Timelines:Simultaneous CE marking, GDPR conformity assessment, and sector-specific safety approvals extend product launch schedules by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe IoT Market |
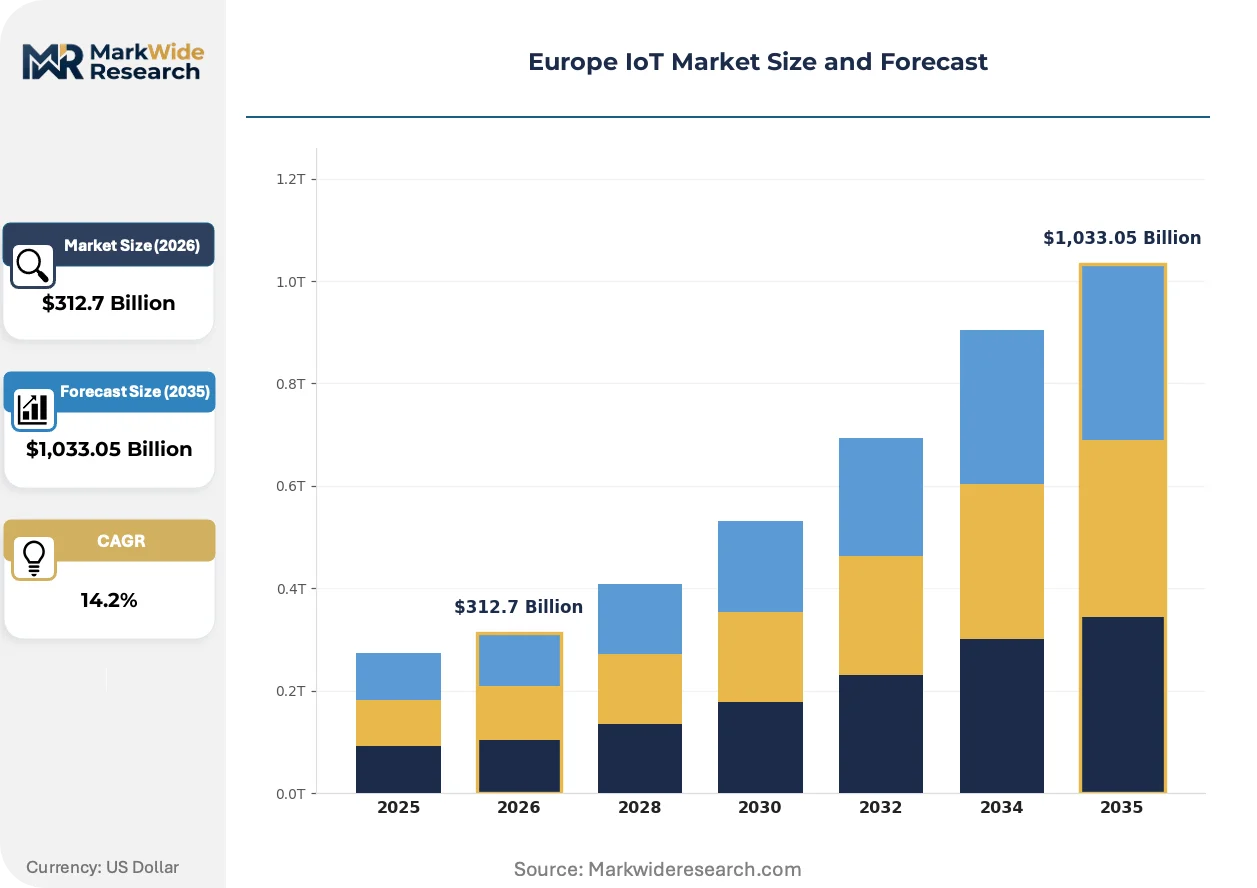
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $1,033.05 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Smart Home, Industrial Automation, Healthcare Monitoring, Asset Tracking Technology: LPWAN, Sigfox, Zigbee, Bluetooth End User: Manufacturing, Retail, Transportation, Agriculture Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | Siemens, Robert Bosch GmbH, Schneider Electric, SAP SE, STMicroelectronics, ABB Group, NXP Semiconductors, Infineon, Arm Limited, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe IoT Market Trends and Innovations
Edge computing architectures and energy-harvesting sensor designs are reconfiguring deployment economics, while regulatory compliance frameworks reshape competitive positioning around demonstrated security credentials rather than unit cost alone.
Digital twin platforms is consolidating around integrated sensor-to-simulation workflows that compress commissioning cycles for German automotive and French energy automation buyers. Siemens and Schneider Electric anchor multi-year service contracts by bundling hardware, edge analytics, and predictive algorithms into single-vendor relationships. This consolidation pressures standalone sensor manufacturers to embed software layers or accept margin compression in component-only sales.
The EU AI Act's high-risk system classification triggers mandatory conformity assessments for industrial IoT deployments incorporating automated decision-making. German machinery builders now require documented risk management systems and human oversight capabilities before qualifying vendors. French building automation integrators face expanded technical documentation burdens for HVAC optimization algorithms that directly affect occupant safety.
Consolidated procurement functions at European manufacturing conglomerates now mandate vendor cybersecurity audits and ETSI EN 303 645 certification as table stakes for RFP participation. Dutch logistics operators unbundle after-sales service contracts from hardware purchases, selecting specialized maintenance providers based on mean-time-to-repair metrics rather than OEM affiliation. This behavioral shift fragments traditional full-stack vendor economics and elevates independent service organizations in transportation and retail verticals.
Europe IoT Market Segmentation
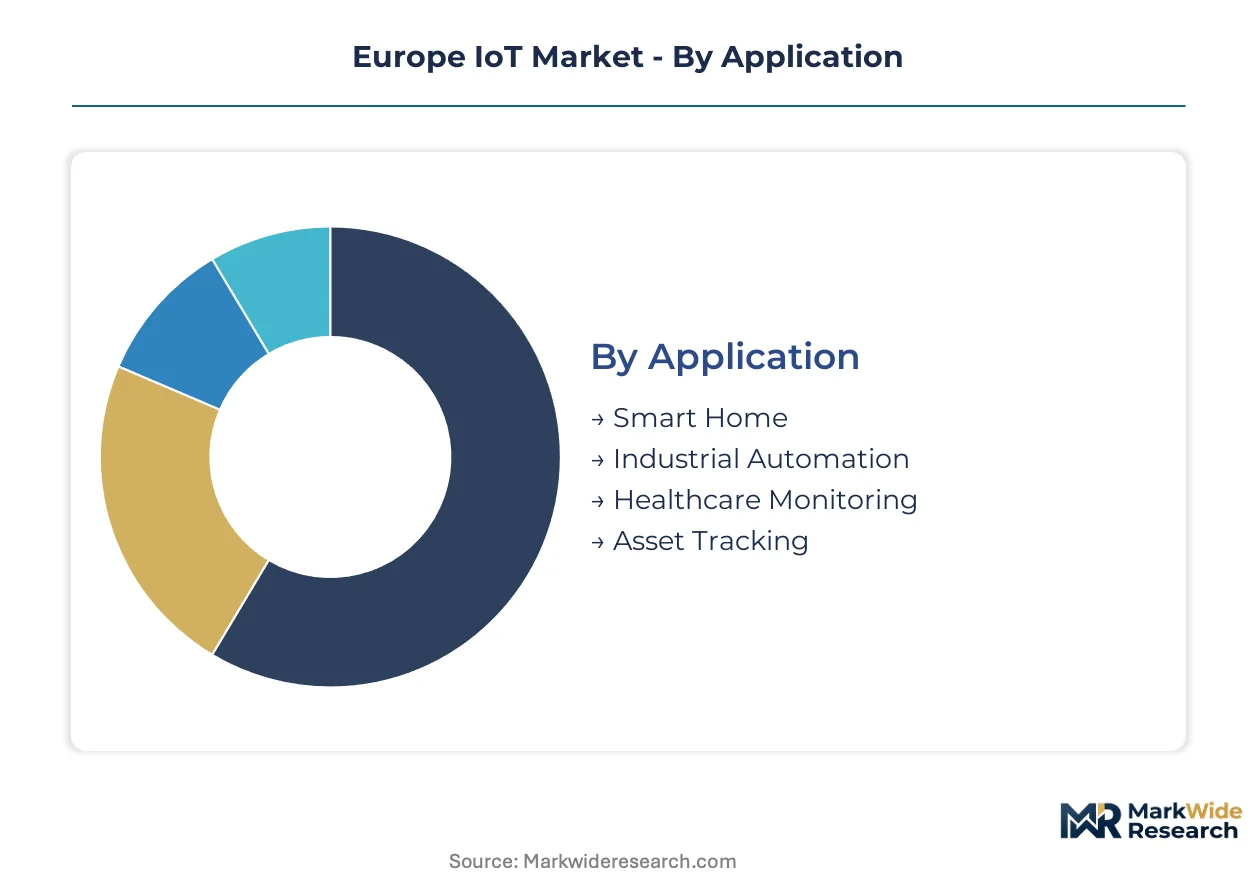
Segmentation across the Europe IoT Market reveals how compliance mandates and deployment economics fragment procurement patterns. German automotive buyers prioritize industrial automation bundles, while French energy operators demand edge-to-cloud hybrid architectures that satisfy GDPR sovereignty requirements.
Application:
Standardization dominates consumer-facing deployments, whereas industrial buyers demand extensive customization around legacy protocol integration and predictive algorithm configuration.
- Smart Home:Consumer devices integrate ARM Cortex-M microcontrollers with sub-gigahertz radios for decade-long battery life. German and French utility operators deploy smart thermostats and lighting controls to meet CSRD energy reporting mandates, though GDPR consent management adds firmware complexity.
- Industrial Automation:Vibration, thermal, and acoustic sensor arrays feed digital twin platforms for predictive maintenance. German automotive OEMs consolidate vendor relationships around full-stack providers capable of documenting EU AI Act conformity assessments for automated decision-making systems.
- Healthcare Monitoring:Wearable biosensors and remote patient monitoring devices require MDR certification and ETSI EN 303 645 cybersecurity compliance.
- Asset Tracking:GPS and LPWAN-enabled tags monitor fleet and inventory across Dutch logistics networks and Nordic shipping corridors.
Most installed capacity flows through Industrial Automation. Expansion is steepest in Healthcare Monitoring.
Technology:
Cost per node and coverage radius determine technology selection, with agricultural and utility operators prioritizing lowest-connectivity-expenditure options over bandwidth.
- LPWAN:LoRaWAN and NB-IoT protocols achieve sub-milliwatt standby consumption for agricultural soil monitors and utility smart meters. Spanish and Italian operators displace legacy cellular to cut per-node connectivity costs across vast rural coverage areas.
- Sigfox:Ultra-narrowband technology serves low-data-rate applications with minimal infrastructure investment. French building automation integrators leverage existing Sigfox coverage for HVAC sensor networks in commercial real estate.
- Zigbee:Mesh networking protocol clusters smart home and building management devices. Nordic markets deploy Zigbee 3.0 for interoperable lighting and climate controls under EU Green Deal efficiency programs.
- Bluetooth:Short-range protocol dominates wearable health monitors and retail beacon deployments. German healthcare providers specify Bluetooth Low Energy 5.3 for patient tracking with encrypted proximity detection.
Volume concentrates in LPWAN deployments. Bluetooth climbs the fastest in healthcare and retail proximity applications.
End User:
Customer maturity and procurement centralization create diverging margin profiles, with conglomerate manufacturing buyers extracting service bundling concessions unavailable to fragmented agricultural purchasers.
- Manufacturing:German automotive and machinery builders mandate ETSI EN 303 645 certification and documented risk management systems for IoT-enabled predictive maintenance. EU AI Act high-risk system classifications trigger mandatory conformity assessments for automated quality control deployments.
- Retail:Dutch and French operators deploy edge computing nodes for sub-100-millisecond inventory tracking and customer analytics. Hybrid architectures satisfy GDPR data sovereignty while enabling real-time shelf monitoring.
- Transportation:Fleet telematics and cargo condition monitoring span road, rail, and maritime corridors. Logistics operators unbundle after-sales service contracts from hardware purchases, selecting maintenance providers based on mean-time-to-repair metrics.
- Agriculture:Spanish and Italian vineyard and olive grove operators deploy soil moisture and weather sensors over LPWAN networks. Lower per-node connectivity costs justify coverage across dispersed rural terrain.
Revenue tilts toward Manufacturing. Agricultural sensor deployment is gaining share fastest as LPWAN coverage expands.
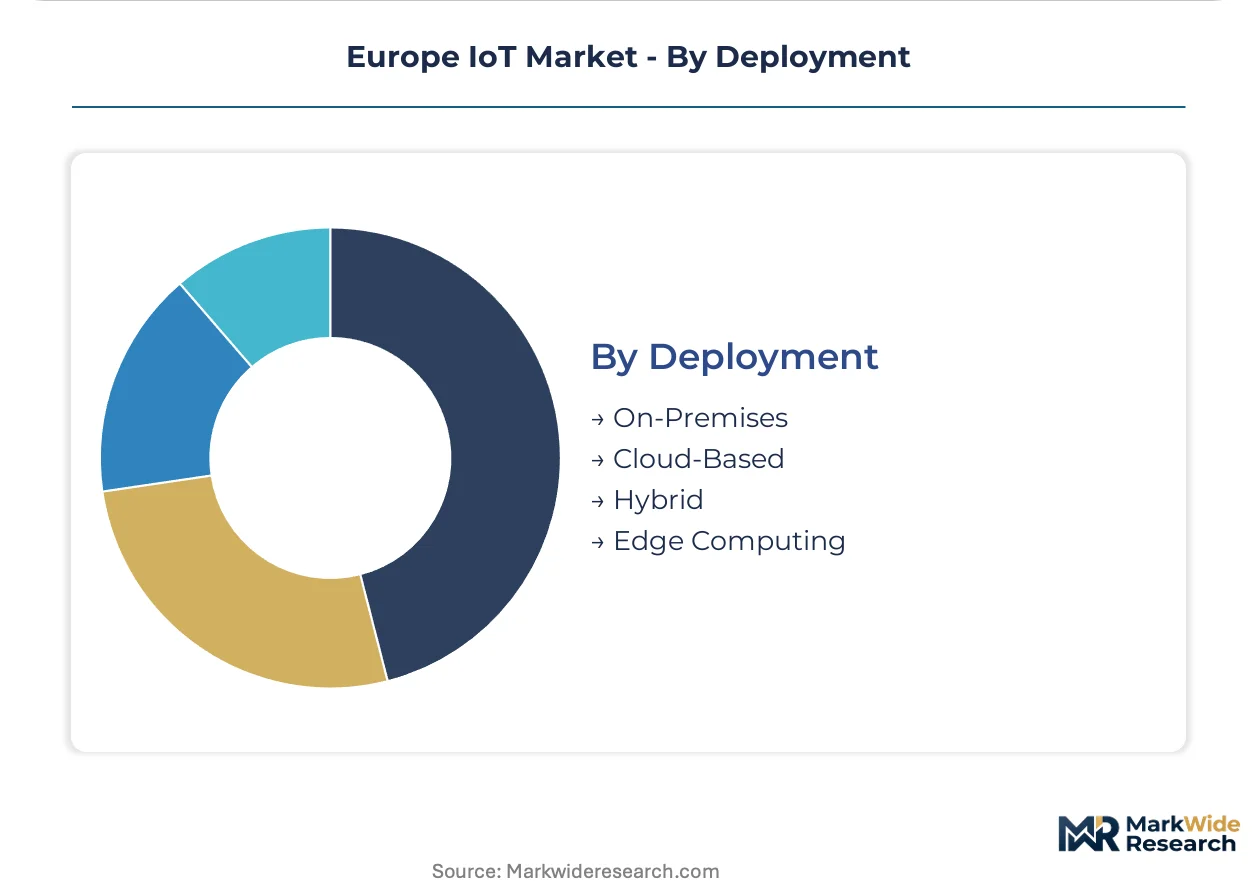
Deployment:
Latency requirements and data sovereignty rules fragment architecture selection, with transportation and retail operators rejecting pure cloud routing while building management tolerates centralized analytics.
- On-Premises:Dedicated server installations host sensitive manufacturing data within facility boundaries. German automotive OEMs retain vibration and thermal sensor data on-site to satisfy GDPR localization requirements and minimize external attack surfaces.
- Cloud-Based:Centralized analytics platforms aggregate data from distributed sensor networks. French smart building operators leverage cloud routing for non-time-critical HVAC optimization algorithms.
- Hybrid:Split architectures process sensitive data locally while transmitting aggregated insights to centralized platforms. Healthcare monitoring deployments balance real-time alerting at the edge with longitudinal analytics in compliant cloud environments.
- Edge Computing:Sub-100-millisecond latency architectures deploy compute nodes adjacent to sensor arrays. Dutch transportation hubs and French retail distribution centers exclude pure cloud routing for automated sorting and safety-critical applications.
Hybrid configurations carry the majority of new installations. Edge Computing is expanding most quickly as latency-sensitive applications multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates industrial IoT deployments while France leads edge-to-cloud integration adoption, creating divergent procurement patterns across the region.
Germany
Automotive OEMs and machinery builders drive sensor deployments for predictive maintenance and Overall Equipment Effectiveness optimization. The EU AI Act's high-risk system classification triggers mandatory conformity assessments for automated quality control systems. Stuttgart and Munich anchor digital twin platform adoption, with Siemens leveraging its portfolio to secure multi-year service contracts.
France
Energy and building automation sectors demand hybrid architectures satisfying GDPR data sovereignty requirements. The CSRD reporting mandates accelerate sensor deployments for emissions monitoring across manufacturing facilities. Lyon and Paris clusters concentrate edge-to-cloud integration expertise, with Schneider Electric competing through specialized infrastructure solutions.
Netherlands
Transportation hubs and retail distribution centers deploy sub-100-millisecond latency architectures that exclude pure cloud routing. ETSI EN 303 645 cybersecurity standards shape procurement requirements for logistics operators. Rotterdam's port infrastructure drives fleet telematics and cargo condition monitoring deployments across maritime corridors.
Spain
Agricultural operators replace legacy cellular with LPWAN networks to cut per-node connectivity costs across vast rural coverage areas. The EU Green Deal drives photovoltaic-powered sensor demand for irrigation and soil monitoring systems. Andalusian olive groves and Catalan vineyards concentrate sub-gigahertz radio deployments for decade-long battery operations.
Italy
Utility metering operators leverage LoRaWAN and NB-IoT protocols for smart grid infrastructure spanning dispersed terrain. REACH and RoHS compliance requirements filter hardware vendor selection for European device manufacturers. Northern industrial districts around Milan and Turin integrate vibration sensor arrays into legacy manufacturing equipment through costly gateway development.
Europe IoT Market Competitive Landscape
German producers anchor one tier; French and Dutch specialists hold differentiated positions in energy and logistics verticals. The vendor base concentrates around full-stack platform providers capable of documenting end-to-end regulatory compliance. Three archetypes dominate: diversified industrial conglomerates bundling hardware and software, semiconductor specialists supplying ARM Cortex-M cores and radio modules, and edge computing integrators serving latency-sensitive applications. Consolidation through long-term service contracts and vertical integration into predictive algorithm development represent the dominant competitive moves.
Within the diversified industrial tier, Siemens and Schneider Electric exemplify platform consolidation strategies. STMicroelectronics and NXP Semiconductors occupy positions as component specialists supplying microcontroller and connectivity modules to device manufacturers. Robert Bosch GmbH anchors a middle position bridging automotive sensor production with industrial automation applications.
| Leading Market Players |
|---|
| Siemens |
| Robert Bosch GmbH |
| Schneider Electric |
| SAP SE |
| STMicroelectronics |
| ABB Group |
| NXP Semiconductors |
| Infineon |
| Arm Limited |
| Others |
Pricing and Supply Chain Analysis
Embedded security engineering talent concentrates in southern Germany and eastern France, where labor-cost differentials between these clusters and peripheral European regions widen pricing-tier spreads for ETSI EN 303 645-certified versus uncertified IoT modules.
Pricing Analysis
Capacity additions in East Asian foundries are reshaping price floors for ARM Cortex-M microcontrollers, compressing margins on standard-tier sensor modules while premium-tier providers defend spreads through EU AI Act documentation services and predictive algorithm bundling. Price differentiation separates full-stack platform providers from component-only vendors, with German automotive OEMs least sensitive to unit costs and Spanish agricultural operators most responsive to per-node connectivity expenditures. Cost compression in LPWAN radio modules intensifies as LoRaWAN and NB-IoT silicon volumes scale.
Supply Chain Analysis
Freight cost volatility from East Asian semiconductor hubs to European assembly plants elevates landed costs for microcontroller and radio module shipments, incentivizing buffer inventory positions among German device manufacturers. Supply concentrates in Taiwan for advanced node fabrication, South Korea for memory components, and China for passive components and battery cells. The chain draws from lithium carbonate, rare earth magnets, and FR-4 substrate laminates as critical inputs. Single-source vulnerability concentrates in ARM Cortex-M core licensing. Distribution runs through authorized distributors serving industrial OEMs and direct procurement relationships with automotive tier-1 suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe IoT Market reads as a late-cycle quality story, with procurement consolidation around full-stack providers accelerating as CSRD mandates and EU AI Act conformity documentation become non-negotiable selection criteria.
For Market Incumbents: Anticipate margin compression in standalone hardware sales by deepening software layer integration and predictive algorithm development. Secure multi-year service contracts with German automotive OEMs before mandatory Cyber Resilience Act enforcement hardens vendor qualification barriers. Prioritize ETSI EN 303 645 certification maintenance as table stakes for RFP participation. For New Entrants and Emerging Players: Launch via independent service organization partnerships targeting Dutch logistics operators who have unbundled maintenance contracts from hardware purchases. Agricultural sensor deployments across Spanish and Italian LPWAN networks offer the most penetrable entry point, with lower incumbent loyalty and price-sensitive procurement functions. Emphasize mean-time-to-repair metrics and localized technical support capabilities. For Investors and Strategic Acquirers: Valuations sit cheapest among component-specialist semiconductor suppliers lacking software differentiation, while edge-to-cloud integration specialists command scarcity premiums. The five-to-ten year viability window favors targets with demonstrated EU regulatory compliance roadmaps and established relationships with French energy or German automotive verticals. Monitor CSRD implementation timelines as an inflection indicator for emissions monitoring sensor demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Full-stack providers bundle edge analytics and predictive algorithms to anchor German automotive multi-year contracts. |
| Certification Pre-Positioning | Hardware vendors aligning with Cyber Resilience Act requirements gain first-mover advantage before mandatory enforcement. |
| Edge-to-Cloud Convergence | Hybrid compute nodes address sub-100-millisecond latency requirements in Dutch transportation and French retail verticals. |
| Energy Harvesting Development | Photovoltaic and thermoelectric-powered sensors capture EU Green Deal incentives across Nordic building management markets. |
| Geographic Manufacturing Footprint | Regional assembly partnerships mitigate GDPR data sovereignty friction and reduce exposure to East Asian supply disruptions. |
Research Methodology
Multiple input streams — primary interviews with IoT platform executives, semiconductor procurement leads, and industrial automation engineers; secondary validation through ETSI standards documentation, EU regulatory filings, and customs trade data; plus bottom-up device shipment analysis and top-down market sizing — were reconciled to construct segment-level estimates across the Europe IoT Market.
Historical volume trajectories were cross-referenced against panel input from solution architects and regulatory affairs specialists to anchor growth assumptions across the projection horizon. The analytical framework modeled technology protocol, end-user vertical, deployment architecture, and application segmentation dimensions. CAGRs were derived from fitted trend analysis adjusted for regulatory implementation schedules and LPWAN network coverage expansion curves, with semiconductor supply constraints and battery chemistry cost volatility incorporated as scenario variables.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained East Asian foundry disruption or accelerated Cyber Resilience Act enforcement timelines. Stakeholders should weight assumptions against their own operating context and supply chain exposure profiles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
IoT Software Market
Internet of Things (IoT)
Global IoT Engineering Services Market
Internet of Things (IoT)
IoT Integration Services Market
Internet of Things (IoT)
Mobile-Connecting Smart Objects Market
Internet of Things (IoT)
Internet of Things (IoT) in Utilities Market
Internet of Things (IoT)
IoT in Automotive Market
Internet of Things (IoT)
Europe Massive IoT Market
Internet of Things (IoT)
Iot-Enabled Devices Market
Internet of Things (IoT)
Global IOT Gateway Market
Internet of Things (IoT)
Global Narrowband IoT Market
Internet of Things (IoT)
Healthcare M2M Market
Internet of Things (IoT)
Location of Things Market
Internet of Things (IoT)
IoT Data Management Market
Internet of Things (IoT)
IoT Services Market
Internet of Things (IoT)
Automotive Internet of Things (IoT) Market
Internet of Things (IoT)
Global Internet of Things (IoT) Defence Market