
 Internet of Things (IoT) in Utilities Market | 2026-2036
Internet of Things (IoT) in Utilities Market Size, Share, and Industry Trends Forecast 2026-2036
Internet of Things (IoT) in Utilities Market Foresight
Edge-to-cloud integration is narrowing the latency window for real-time grid decisions. Siemens AG leverages deep automation heritage to anchor European smart metering rollouts. Cisco Systems, Inc. competes through hardened networking gear purpose-built for substation environments. Huawei Technologies dominates utility-scale IoT deployments across Asian markets with integrated communications layers.
Internet of Things in Utilities refers to networked sensor and actuator systems embedded across generation, transmission, and distribution infrastructure, typically operating at sub-second telemetry intervals with IP-based backhaul to centralized or distributed control platforms. These systems enable automated demand response, predictive asset failure detection, and dynamic load balancing across heterogeneous energy and water networks. Smart Meters constitute the most mature product category with established replacement cycles, while Data Analytics Platforms capture expanding margin pools as utilities shift from connectivity investments toward operational intelligence. Machine Learning within the technology stack represents the fastest-growing capability layer as vendors embed inference models directly into grid edge devices.
The US Federal Energy Regulatory Commission and the EPA shape demand through mandatory reliability standards and emissions reporting requirements that compel telemetry upgrades. European regulators enforce the CSRD and GDPR, forcing utilities to reconcile granular consumption data collection with strict privacy governance. Stakeholders must weigh interoperability commitments against proprietary platform lock-in as vendor consolidation accelerates across the stack.
Market Dynamics
Smart grid sensor density is accelerating as electric utilities retrofit legacy distribution infrastructure with networked monitoring systems to satisfy tightening emissions accountability and reliability mandates.
Growth Catalysts
- EU Green Deal mandates:The EU Green Deal and F-Gas Regulation compel European energy operators to deploy granular emissions monitoring across transmission and distribution networks, forcing telemetry upgrades.
- Industrial retrofit demand:German industrial utility operators are systematically replacing analog infrastructure with connected monitoring systems to meet operational efficiency targets and carbon disclosure requirements.
- Edge inference capability:Machine learning embedded directly into grid edge devices enables sub-second automated demand response without cloud round-trip latency, accelerating deployment economics.
Market Restraints
- Silicon supply concentration:Semiconductor fabrication for industrial-grade sensor controllers concentrates in East Asian foundries, exposing utilities to geopolitical disruption risk and extended lead times.
- GDPR compliance friction:GDPR requirements create structural barriers to granular consumption data collection, forcing utilities to architect expensive privacy-preserving telemetry architectures.
- Legacy protocol fragmentation:Proprietary SCADA communication standards from incumbent automation vendors resist interoperability, locking operators into single-source maintenance contracts.
Strategic Opportunities
- Water network digitization:Municipal water utilities in France and Spain remain underpenetrated for smart metering relative to electricity, presenting first-mover expansion potential for integrated platform vendors.
- CSRD reporting convergence:The CSRD mandates granular sustainability disclosures that utility IoT data streams can automate, creating subscription revenue for analytics platform providers.
- 5G private network integration:Convergence of 5G standalone slicing with time-synchronized grid control enables new ultra-reliable low-latency applications in substation automation previously unreachable with unlicensed spectrum.
Industry Challenges
- Cyber-physical security expertise scarcity:Utilities face acute shortages of engineers capable of securing operational technology networks against targeted intrusion while maintaining real-time control system availability.
- Multi-vendor integration complexity:Field teams struggle to harmonize telemetry from heterogeneous sensor generations, communication modules, and cloud platforms into unified operational dashboards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Internet of Things (IoT) in Utilities Market |
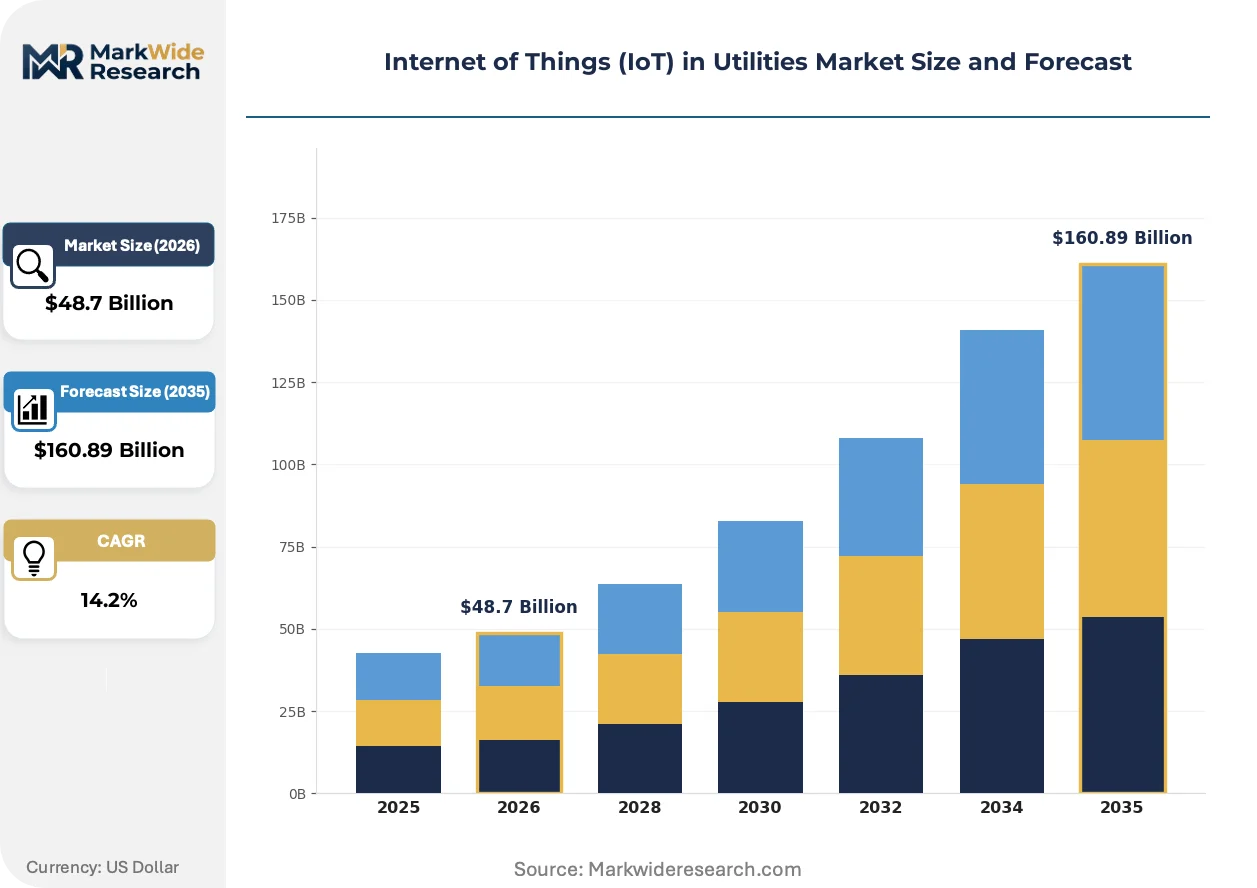
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $160.89 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Meters, IoT Sensors, Automated Control Systems, Data Analytics Platforms Technology: Wireless Communication, Cloud Computing, Edge Computing, Machine Learning Application: Energy Management, Water Quality Monitoring, Asset Tracking, Predictive Maintenance End User: Utility Companies, Environmental Agencies, Industrial Facilities, Consumers |
| Companies Covered | IBM Corporation, Cisco Systems, Inc., General Electric Company, Siemens AG, Honeywell International Inc., Schneider Electric, ABB Ltd, Microsoft Corporation, Huawei Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Internet of Things (IoT) in Utilities Market Shifts & Advancements
Edge-native intelligence is collapsing the traditional separation between data collection and automated response, compressing decision loops from minutes to milliseconds across distributed energy resources.
Digital twin architectures for substation assets are collapsing the cost structure of predictive maintenance by enabling continuous simulation of equipment degradation without physical inspection. European transmission system operators including TenneT and RTE are deploying these models at scale. The structural consequence is a shift from scheduled replacement to condition-based asset management, extending capital cycles and reducing emergency outage frequency.
The EU AI Act creates binding conformity requirements for machine learning systems deployed in critical infrastructure, including energy grid control applications. Utilities must now document training data provenance and algorithmic interpretability for regulatory audit. German distribution network operators are responding by demanding vendor-provided model cards and bias assessment documentation as standard procurement terms.
Outcome-based service contracts are displacing capital-intensive hardware purchases among municipal utilities with constrained balance sheets. Vendors now offer availability-guaranteed sensor networks with performance-linked payment structures. This procurement evolution is most visible in Italian and Polish water utilities, where operators prioritize operational expenditure flexibility over asset ownership to satisfy municipal debt limits.
Internet of Things (IoT) in Utilities Market Segmentation
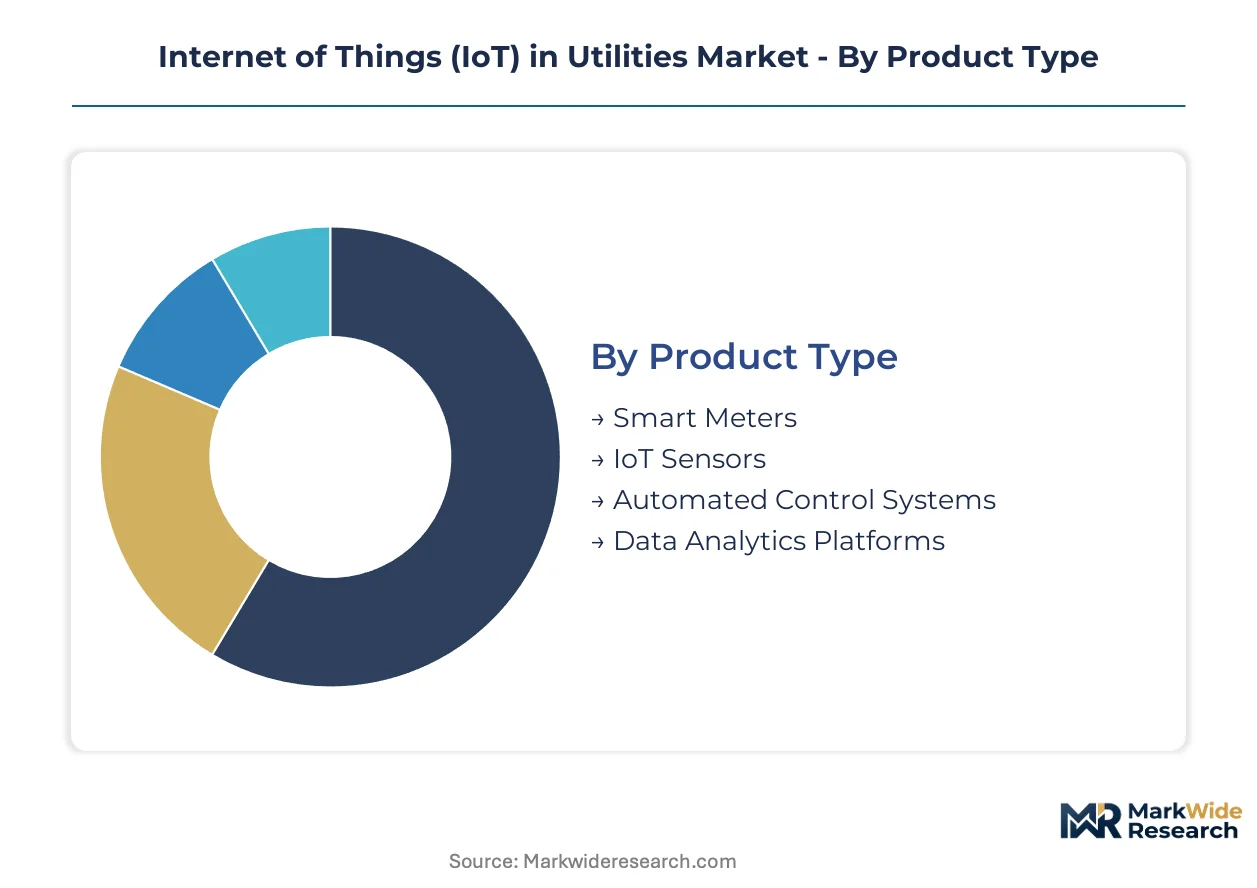
IoT in utilities spans heterogeneous hardware, software, and service layers with divergent margin profiles and deployment timelines. Vendors must align portfolio depth against specific utility operational priorities rather than pursuing horizontal coverage. The following categories capture the structural fault lines governing procurement decisions and technology roadmaps.
Product Type:
Cost tier stratification separates mature hardware commodities from high-margin software platforms with recurring revenue characteristics.
- Smart Meters:These devices measure consumption at sub-minute intervals with integrated communication modules for automated billing and demand response. German distribution network operators are replacing analog meters at scale under EU Green Deal mandates, driving replacement cycle concentration.
- IoT Sensors:Temperature, pressure, and emissions sensors embed across transmission and distribution infrastructure with IP-based telemetry backhaul. Industrial facilities in the US Midwest are deploying dense sensor networks to satisfy EPA emissions reporting requirements.
- Automated Control Systems:SCADA-integrated actuators enable remote switching and load balancing.
- Data Analytics Platforms:Cloud-native software aggregates telemetry streams for predictive modeling and operational dashboards.
Smart Meters commands the established base. The steepest expansion runs through Data Analytics Platforms.
Technology:
Application context determines whether latency-tolerant cloud architectures or sub-second edge inference delivers superior economics.
- Wireless Communication:LPWAN, cellular, and mesh protocols transmit sensor data across geographically dispersed infrastructure. French water utilities are selecting LoRaWAN for smart metering deployments to minimize licensed spectrum costs.
- Cloud Computing:Centralized data lakes enable historical pattern analysis and cross-fleet benchmarking. Environmental agencies in California leverage cloud platforms to aggregate emissions data across heterogeneous utility footprints.
- Edge Computing:Distributed processing nodes collapse decision latency for real-time grid control.
- Machine Learning:Embedded inference models automate anomaly detection without human intervention.
Wireless Communication underpins connectivity economics. Machine Learning is gaining share fastest as vendors embed intelligence at the grid edge.
Application:
Operational maturity varies sharply across utility functions, with energy applications leading and water digitization trailing by several replacement cycles.
- Energy Management:Automated demand response and distributed resource coordination optimize generation-load balance. Italian industrial facilities are deploying these systems to reduce peak demand charges and carbon intensity metrics.
- Water Quality Monitoring:Multi-parameter sensors track contamination, pressure, and flow in distribution networks. Spanish municipal utilities are piloting smart water grids with EU funding support for leakage reduction targets.
- Asset Tracking:Geolocation and condition monitoring for mobile and fixed infrastructure.
- Predictive Maintenance:Algorithmic failure forecasting extends asset life and prevents emergency outages.
Energy Management captures current deployment volume. Water Quality Monitoring presents the largest untapped expansion opportunity.
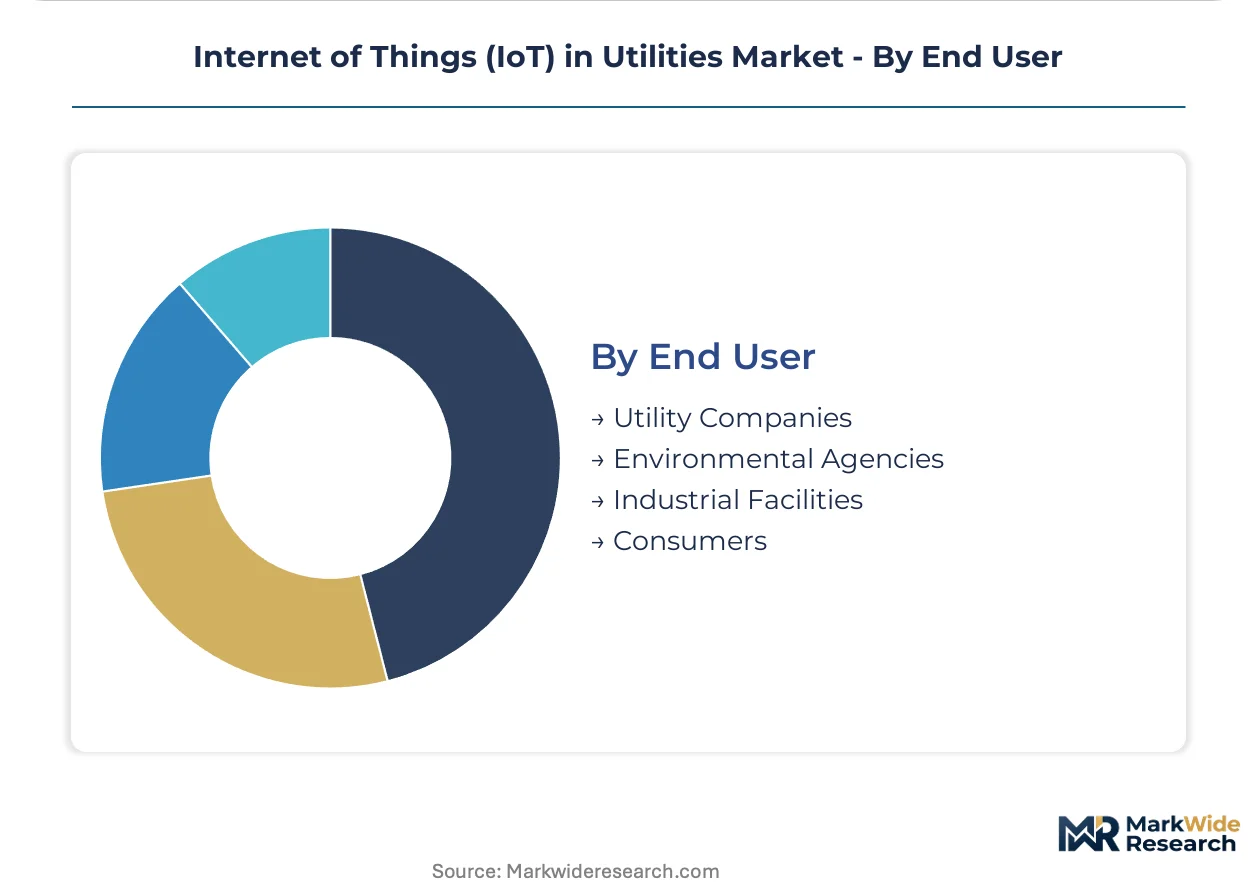
End User:
Customer type dictates procurement sophistication, with regulated utilities favoring proven vendors and industrial facilities accepting emerging technology risk.
- Utility Companies:Electric, gas, and water operators deploy IoT systems for network optimization and regulatory compliance. German transmission system operators are mandating vendor interoperability certifications under national grid codes.
- Environmental Agencies:Government bodies monitor emissions and resource consumption across jurisdictional boundaries. The EPA requires granular telemetry from major emitters under mandatory reporting rules.
- Industrial Facilities:Energy-intensive manufacturers pursue operational efficiency and carbon disclosure automation.
- Consumers:Residential and commercial building operators access consumption data through utility-provided portals.
Utility Companies anchor procurement volume. Industrial Facilities are climbing the fastest as manufacturing decarbonization tightens operational requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German distribution network operators anchor procurement volume for smart metering infrastructure, while US electric utilities drive sensor density upgrades under tightening emissions accountability mandates.
United States
Electric utilities deploy dense sensor networks across transmission corridors to satisfy EPA emissions reporting requirements and FERC reliability standards. The Inflation Reduction Act accelerates grid modernization funding for rural cooperatives. Texas and California transmission operators are replacing legacy SCADA systems with IP-based telemetry architectures.
Germany
Industrial utility operators retrofit analog infrastructure with connected monitoring systems to meet operational efficiency targets and carbon disclosure requirements. The EU Green Deal and F-Gas Regulation compel granular emissions monitoring across distribution networks. Bavarian and North Rhine-Westphalian grid operators mandate vendor interoperability certifications under national grid codes.
China
State-owned grid operators pursue utility-scale IoT deployments with integrated communications layers for substation automation and demand response coordination. MIIT standards govern industrial-grade sensor controller specifications. Yangtze River Delta utilities are deploying edge-native intelligence systems for real-time load balancing across distributed energy resources.
France
Municipal water utilities pilot smart water grids with EU funding support for leakage reduction targets, presenting expansion potential for integrated platform vendors. The CSRD mandates granular sustainability disclosures that utility IoT data streams can automate. Paris and Lyon metropolitan operators are selecting LoRaWAN protocols to minimize licensed spectrum costs for smart metering deployments.
Japan
Industrial facilities deploy automated demand response systems to reduce peak demand charges and carbon intensity metrics under METI efficiency directives. JIS standards shape sensor controller procurement specifications. Kanto and Kansai regional utilities are integrating digital twin architectures for substation predictive maintenance at scale.
Internet of Things (IoT) in Utilities Market Competitive Landscape
Channel-controlling players compete with product-specialist players across hardware, software, and integrated service layers. The vendor base organizes around three strategic archetypes: automation heritage conglomerates with deep utility relationships, networking equipment specialists with hardened infrastructure portfolios, and cloud-native analytics platforms with recurring revenue models. Consolidation pressures intensify as utilities demand unified operational dashboards spanning heterogeneous sensor generations. Dominant competitive moves include strategic partnerships for multi-vendor integration capabilities and geographic expansion through outcome-based service contract offerings.
Among automation heritage conglomerates, Siemens AG and ABB Ltd occupy positions anchored in European smart metering rollouts and substation control systems. Cisco Systems, Inc. exemplifies the networking equipment specialist archetype with purpose-built gear for utility environments. IBM Corporation and Microsoft Corporation represent the cloud-native analytics tier, capturing expanding margin pools as utilities shift connectivity investments toward operational intelligence platforms.
| Leading Market Players |
|---|
| IBM Corporation |
| Cisco Systems, Inc. |
| General Electric Company |
| Siemens AG |
| Honeywell International Inc. |
| Schneider Electric |
| ABB Ltd |
| Microsoft Corporation |
| Huawei Technologies |
| Others |
Supply & Pricing Matrix
East Asian foundry concentration for industrial-grade sensor controllers feeds directly into margin compression for European smart meter OEMs and data analytics platform vendors. Semiconductor fabrication bottlenecks translate into extended lead times that shift procurement power toward buyers with multi-year visibility.
Pricing Analysis
Cost-plus contracts indexed to silicon wafer spot markets dominate hardware procurement between German distribution network operators and sensor OEMs. Three-tier pricing structure across premium, standard, and economy levels separates IEC 61850-certified devices from basic metering units and unbranded white-label alternatives. Pricing pressure stems from municipal utility budget constraints in Southern Europe, where outcome-based service contracts displace capital purchases. Industrial facilities demonstrate lowest price sensitivity, prioritizing interoperability certifications over unit cost.
Supply Chain Analysis
Contract manufacturing capacity for utility-grade IoT sensors concentrates with Foxconn Industrial Internet, Jabil, and Flex in Taiwan, Malaysia, and Mexico. Raw material dependencies span silicon wafers, lithium-ion cells for backup power, and rare earth elements for magnetic components in substation equipment. Single-source vulnerability runs through advanced node semiconductor fabrication, exposing utilities to geopolitical disruption risk. Distribution runs through authorized systems integrators with utility-specific certification credentials, limiting direct vendor access to end customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vendor fragmentation across hardware, software, and service layers creates white-space opportunities as utilities demand unified operational dashboards. The shift from connectivity investments toward operational intelligence platforms fragments procurement decisions across multiple buyer committees.
For Market Incumbents: Pre-empt platform consolidation by acquiring cloud-native analytics specialists with CSRD reporting automation capabilities. Incumbent automation conglomerates face margin erosion from outcome-based service contracts displacing hardware purchases. Vertical integration into edge-native machine learning silicon preserves differentiation against networking equipment specialists expanding into grid control applications.
For New Entrants and Emerging Players: Build out water network digitization capabilities in French and Spanish municipal utilities, where smart metering penetration trails electricity by multiple replacement cycles. LoRaWAN protocol expertise offers a technical wedge for spectrum-constrained deployments. Target outcome-based contracting structures that align vendor economics with leakage reduction KPIs.
For Investors and Strategic Acquirers: Capital is best deployed toward cloud-native analytics platforms with recurring revenue models and CSRD-aligned sustainability disclosure automation. Long-term viability hinges on regulatory data mandate expansion across European energy and water infrastructure. Monitor EU AI Act conformity assessment timelines as an inflection signal for vendor compliance cost structures.
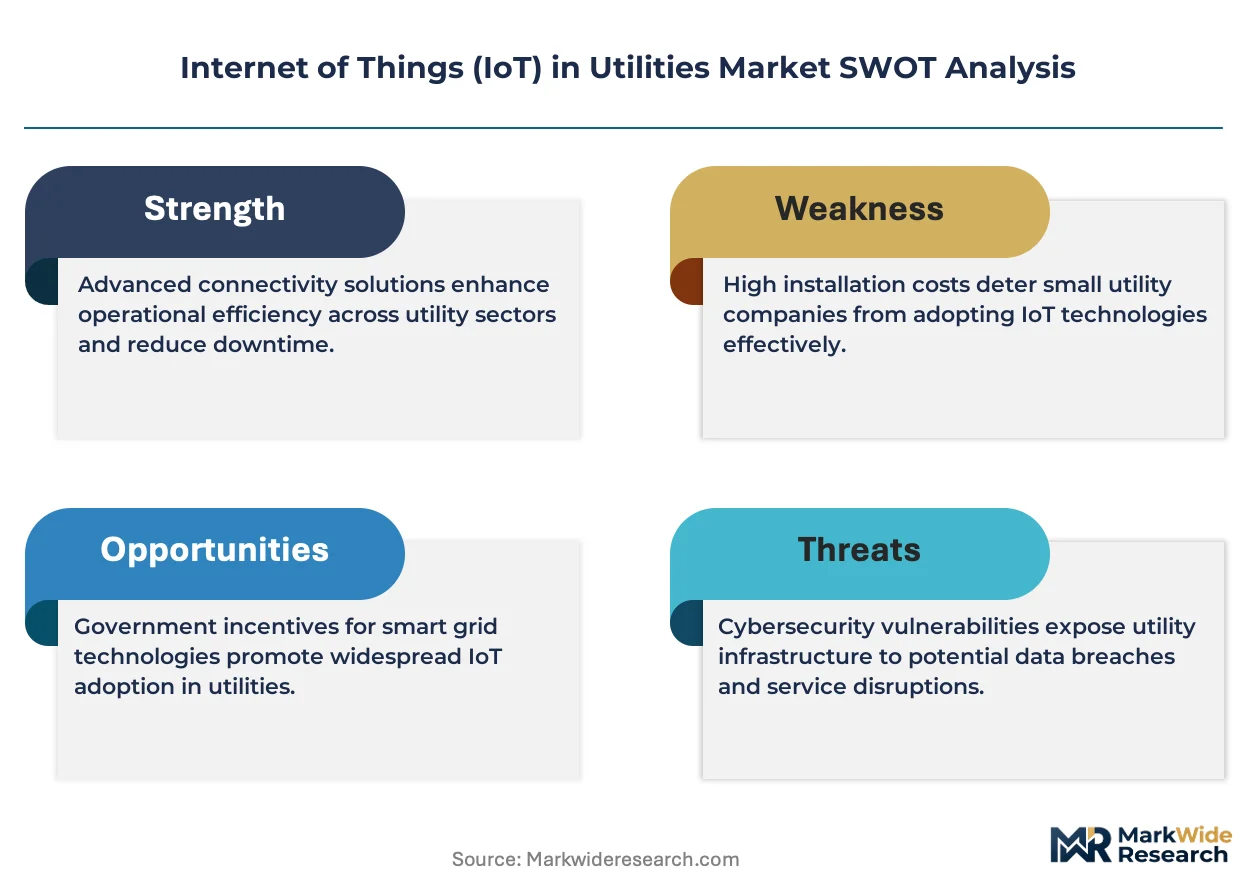
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies telemetry from heterogeneous sensor generations into single operational dashboards for German grid operators. |
| Acquisition of Specialist Firm | Cloud-native analytics vendors capture CSRD reporting subscription revenue from disclosure-mandated utilities. |
| Geographic Expansion | Outcome-based service contracts enable vendor entry into Italian and Polish municipal water utilities with debt constraints. |
| Strategic Partnership | 5G private network slicing partnerships unlock ultra-reliable low-latency substation automation applications. |
| Product Launch | Edge-native machine learning devices enable sub-second automated demand response without cloud dependency. |
Research Methodology
The analysis maps smart metering infrastructure, IoT sensors, data analytics platforms, and automated control systems, each validated through utility planning officers, grid operators, EPC contractors, and systems integration specialists. Primary interview data triangulates against FERC filings, EIA grid modernization databases, EU Green Deal implementation reports, and EPA emissions reporting requirements. Bottom-up deployment tracking across named transmission and distribution operators reconciles with top-down market sizing across the analysis window.
Fixed assumptions include sustained EU Green Deal enforcement, continued FERC reliability standard tightening, and stable semiconductor supply chain normalization trajectories. Segmentation models incorporate product type, technology layer, application function, and end-user procurement sophistication. CAGRs derive from replacement cycle analysis, regulatory mandate implementation timelines, and vendor pipeline conversion rates across hardware and software revenue streams.
Stress conditions across silicon supply disruption severity, GDPR enforcement intensity, and EU AI Act compliance cost inflation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these bounded assumptions and may require revision upon material shifts in regulatory implementation schedules or geopolitical trade policy. Quarterly review of vendor interoperability certification progress and municipal utility outcome-based contract adoption rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Europe Massive IoT Market
Internet of Things (IoT)
IoT in Energy Market
Internet of Things (IoT)
IoT Lpwans Market
Internet of Things (IoT)
UK IoT Software Market
Internet of Things (IoT)
Airport Internet of Things Market
Internet of Things (IoT)
Global IoT Battery Market
Internet of Things (IoT)
LPWAN in the Consumer IoT Market
Internet of Things (IoT)
IoT Market
Internet of Things (IoT)
Intelligent IoT Market
Internet of Things (IoT)
IoT Infrastructure Market
Internet of Things (IoT)
IoT Application Development Services Market
Internet of Things (IoT)
IoT Middleware Market
Internet of Things (IoT)
Consumer IoT Market
Internet of Things (IoT)
5G IIOT Market
Internet of Things (IoT)
IoT IAM Market
Internet of Things (IoT)
South Africa IoT Market