
 Semiconductor Fabrication Software Market | 2026-2036
Semiconductor Fabrication Software Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Fabrication Software Market Outlook
Multi-source procurement of process control modules is realigning how foundries manage vendor relationships across their fabrication ecosystems. Synopsys leverages its design automation portfolio to anchor relationships with leading-edge logic manufacturers. Applied Materials competes through integrated yield management platforms that bridge hardware and software workflows. Siemens EDA differentiates via cloud-ready verification tools that extend its reach beyond traditional on-premises installations.
Semiconductor fabrication software encompasses the specialized programs that orchestrate wafer processing, photolithography alignment, etch control, and final testing across semiconductor manufacturing facilities, typically interfacing with equipment through SECS/GEM protocols and real-time statistical process control algorithms. The primary commercial purpose centers on maximizing die yield while minimizing cycle time across billion-dollar cleanroom operations. Design automation and verification tools command the largest revenue share as transistor complexity at advanced nodes explodes engineering hours. Process control software represents the fastest-expanding category as AI-driven anomaly detection displaces rule-based systems in 300mm fabs. Yield management solutions occupy concentrated margin pools among memory manufacturers facing atomic-scale defect sensitivity.
The EU Chips Act and US CHIPS and Science Act are reshaping market access requirements by mandating domestic software supply chain audits for subsidized fabrication facilities. Japan's METI coordinates national standards for semiconductor manufacturing equipment interfaces through its JIS framework, directly influencing software interoperability specifications. South Korea's K-Belt strategy channels tax incentives toward indigenous process control development. Stakeholders must monitor how divergent national subsidy compliance rules fragment previously unified software procurement standards.
Market Dynamics
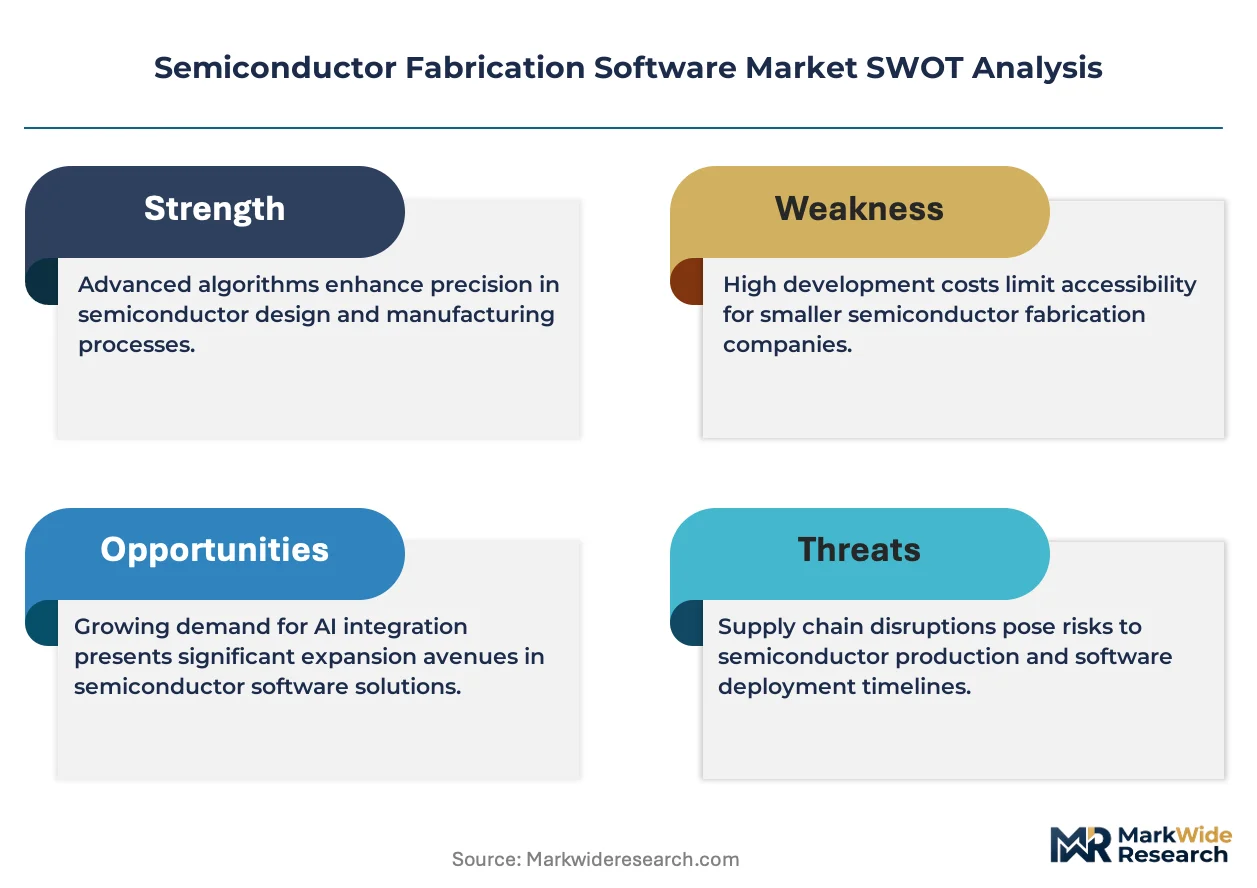
AI-driven process control algorithms are compressing defect detection cycles from hours to seconds in 300mm fabrication facilities, forcing incumbent software vendors to rearchitect their statistical process control engines or cede position to specialized machine learning suppliers.
Growth Catalysts
- Advanced node complexity:Transistor scaling below 3nm multiplies the number of process steps requiring software-controlled metrology, expanding the addressable license base for design-for-manufacturing tools.
- US CHIPS and Science Act:Subsidy disbursement mandates domestic software supply chain verification, redirecting procurement toward qualified North American vendors for new Arizona and Texas fabs.
- High-bandwidth memory packaging:3D stacking architectures multiply the number of bond-and-test cycles per wafer, increasing demand for yield management software in South Korean memory clusters.
Market Restraints
- Specialized engineering talent scarcity:The pool of professionals fluent in both semiconductor physics and machine learning model deployment remains concentrated in Taiwan and South Korea, constraining vendor expansion.
- Equipment interface lock-in:Proprietary SECS/GEM protocol implementations by dominant lithography and deposition tool vendors create switching costs that freeze out alternative software providers.
- Fab construction cost inflation:A single advanced node facility now exceeds $20 billion in capital requirements, stretching customer balance sheets and compressing software procurement timelines.
Strategic Opportunities
- European captive capacity buildout:The EU Chips Act is funding new fabrication facilities in Germany, France, and Italy, creating first-mover advantages for software vendors establishing local support infrastructure.
- Digital twin convergence:Integration of physics-based simulation with live fab sensor streams enables predictive maintenance contracts that extend vendor revenue beyond perpetual licenses.
- Cloud-native verification workloads:Elastic compute architectures allow fabless semiconductor designers to burst simulation capacity during tape-out windows, opening subscription revenue models previously blocked by on-premises hardware requirements.
Industry Challenges
- Legacy system integration friction:Brownfield fabs running 200mm equipment with decades-old control software require costly middleware development to interface with modern AI-driven analytics platforms.
- Cross-border data governance:Real-time process optimization depends on wafer-level telemetry flows that conflict with China's data localization requirements and Europe's GDPR restrictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Fabrication Software Market |
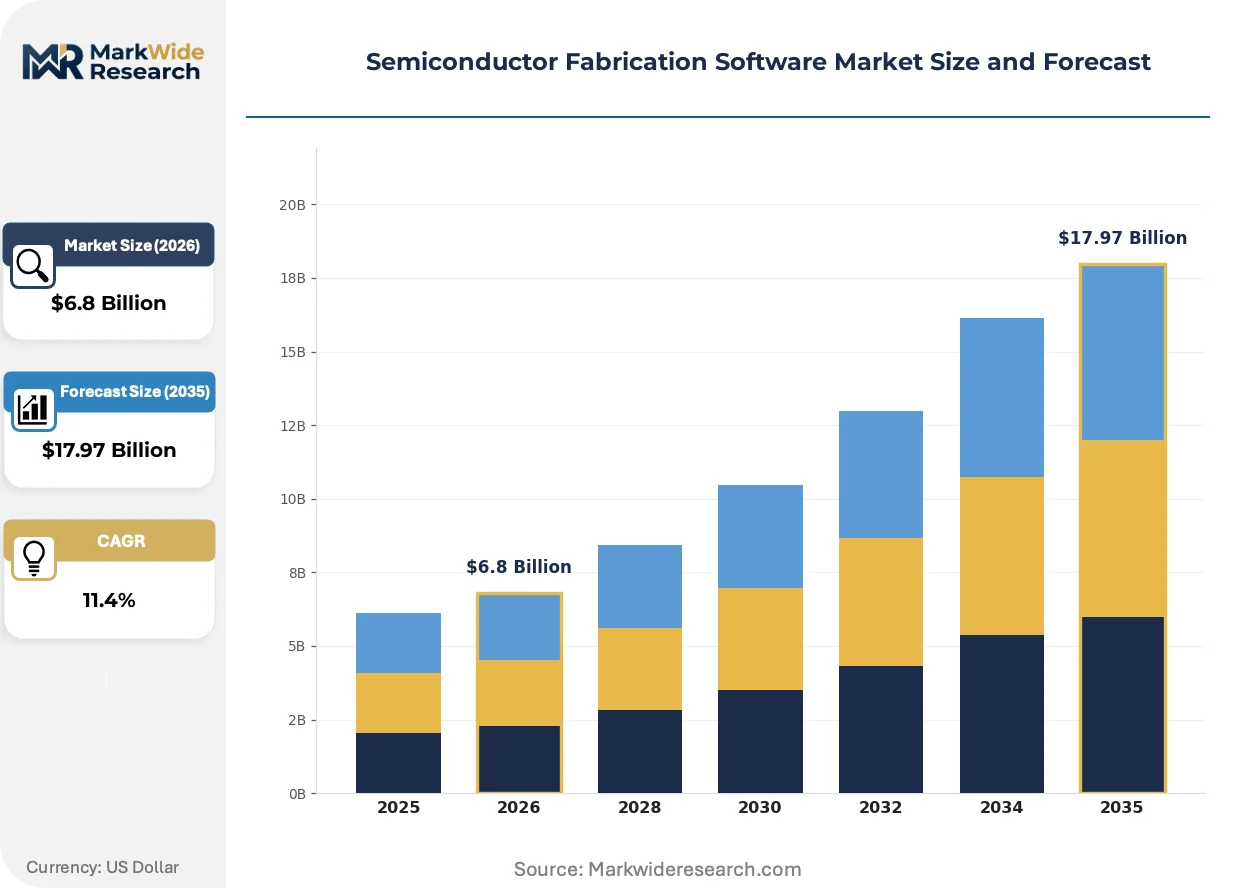
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Software Type: Design Automation, Verification Tools, Yield Management, Process Control Application: Wafer Fabrication, Photolithography, Etching, Testing End User: Foundries, Integrated Device Manufacturers, Research Institutions, OEMs Deployment Model: On-Premises, Cloud-Based, Hybrid, Open Source |
| Companies Covered | Teradyne, Synopsys, Applied Materials, Ansys, Cadence Design Systems, ASML, Siemens EDA, Mentor Graphics, Lam Research, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Fabrication Software Market Strategic Shifts
Computational lithography and inverse design algorithms are compressing the traditional boundaries between electronic design automation and process control software, creating integrated workflows that span from transistor architecture to wafer inspection.
Computational lithography platforms now embed physics-based etch and deposition models directly into the mask synthesis workflow. Leading-edge logic manufacturers in Taiwan and South Korea are deploying these unified pipelines for production runs at 2nm and below. This convergence is unifying previously separate vendor relationships into single-source procurement decisions that favor integrated design-to-silicon portfolios.
Japan's METI has accelerated JIS standardization for equipment data interfaces to reduce vendor-specific protocol fragmentation. The framework mandates open APIs for process parameter logging across lithography, etch, and metrology tools. Equipment-heavy segments including deposition and ion implantation are reengineering control architectures to comply, with compliance deadlines concentrating vendor development resources through 2027.
Foundry customers are consolidating software procurement under multi-year enterprise agreements that bundle design, verification, and manufacturing execution licenses. The traditional pattern of point-tool acquisition by individual engineering teams is yielding to centralized vendor management offices that negotiate consolidated pricing. This behavioral shift is most pronounced among North American fabless semiconductor designers expanding their foundry commitments at Taiwan Semiconductor Manufacturing facilities.
Semiconductor Fabrication Software Market Segmentation
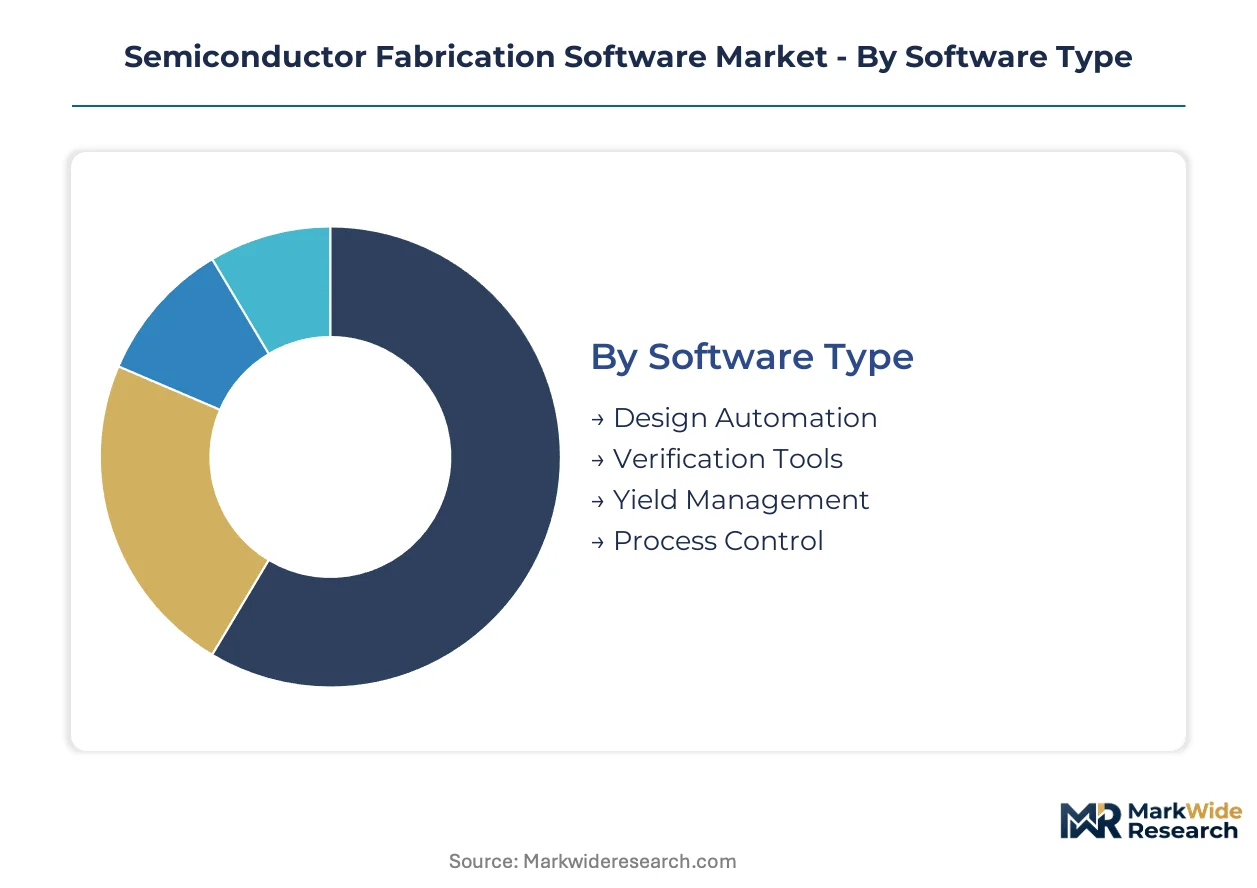
Segmentation in semiconductor fabrication software reveals how vendor portfolios align with distinct technical workflows and capital deployment patterns across the manufacturing value chain. Each category exposes different purchasing authority structures and integration complexity thresholds that shape competitive positioning.
Software Type:
Volume licensing concentrates in process control modules purchased by high-throughput memory fabs, while premium pricing anchors design automation suites serving leading-edge logic development.
- Design Automation:Electronic design automation platforms synthesize transistor layouts and physical verification checks for advanced node development. Taiwan-based foundry customers drive procurement volumes as 2nm tape-out cycles compress design schedules.
- Verification Tools:Functional and formal verification software validates logic correctness before mask generation. Cloud-native deployments are gaining traction fastest among fabless semiconductor designers in North America facing elastic compute demands during tape-out windows.
- Yield Management:Defect classification and binning analytics optimize die recovery rates.
- Process Control:Real-time statistical process control and fault detection systems govern wafer-level manufacturing parameters.
Mature deployment sits with design automation. Newer deployment is concentrated in process control.
Application:
Customer type determines margin structure, with captive integrated device manufacturers accepting higher per-seat costs than merchant foundries negotiating enterprise-wide discounts.
- Wafer Fabrication:Manufacturing execution systems orchestrate lot tracking, equipment dispatch, and recipe management across diffusion and implant areas. South Korean memory clusters represent the densest installed base as 3D NAND layer counts multiply process step complexity.
- Photolithography:Computational lithography and overlay control software calibrate scanner illumination and mask alignment. Sub-3nm logic manufacturers in Taiwan deploy the most sophisticated inverse lithography technology stacks.
- Etching:Plasma etch endpoint detection and profile control algorithms manage critical dimension uniformity.
- Testing:Automated test equipment programming and data analytics streamline final wafer sort and package test operations.
Established procurement patterns dominate wafer fabrication. Photolithography commands the steepest expansion trajectory as resolution enhancement techniques multiply computational requirements.
End User:
Supply concentration varies by buyer sophistication, with foundries consolidating vendor relationships under multi-year agreements while research institutions maintain fragmented point-tool acquisitions.
- Foundries:Merchant semiconductor manufacturers license integrated design-to-manufacturing platforms spanning multiple process nodes. Taiwan Semiconductor Manufacturing and Samsung Foundry anchor global procurement volumes through consolidated enterprise agreements.
- Integrated Device Manufacturers:Captive fab operators at Intel and Texas Instruments prioritize yield management software for mature node cost optimization. Memory-focused IDMs in South Korea represent concentrated demand for defect detection analytics.
- Research Institutions:University cleanrooms and national laboratories license specialized modules for exploratory process development.
- OEMs:Original equipment manufacturers embed control software into lithography, deposition, and metrology tools.
Procurement maturity clusters with integrated device manufacturers. Foundries are expanding licensing fastest as multi-node manufacturing portfolios broaden software footprints.
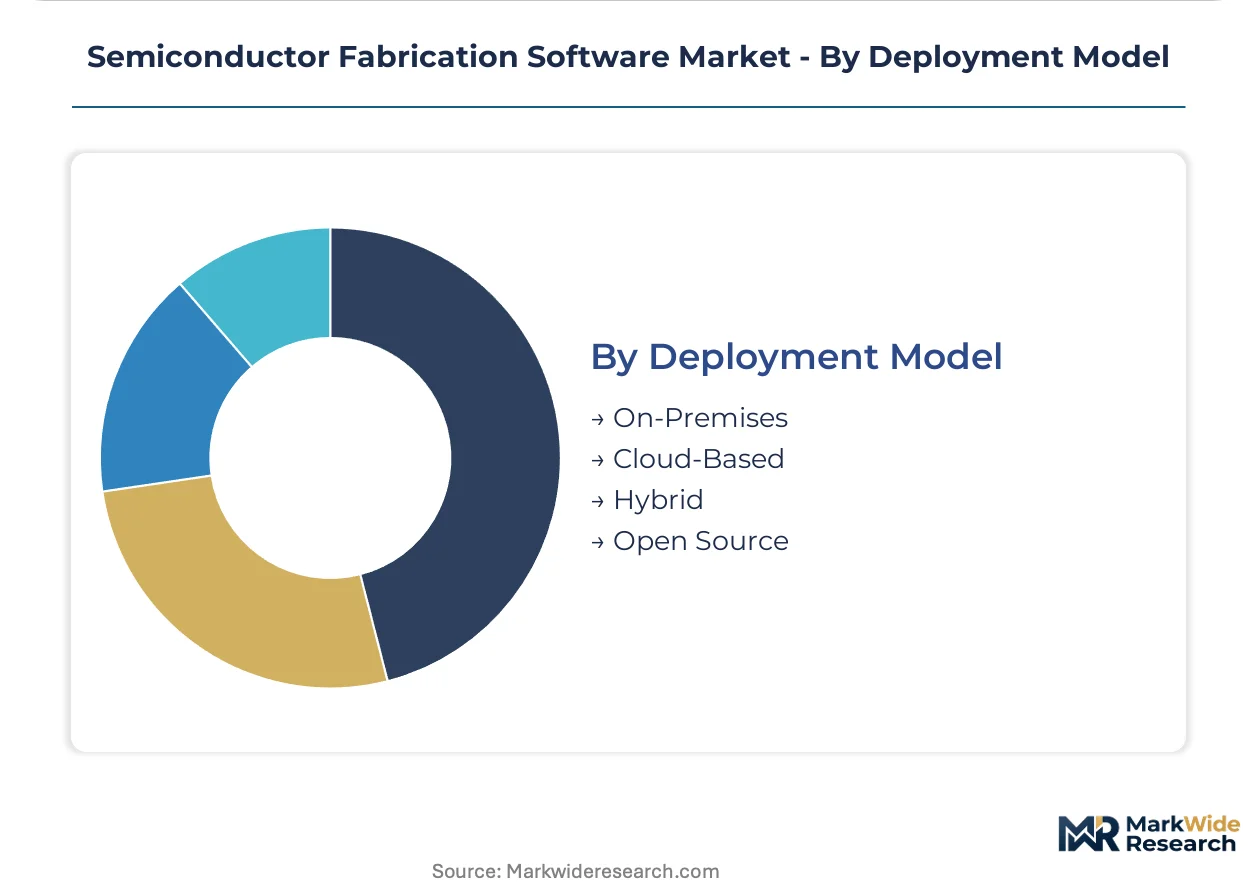
Deployment Model:
Integration burden separates segments, with on-premises installations requiring substantial professional services while cloud deployments shift operational responsibility to vendors.
- On-Premises:Perpetually licensed software running on customer-managed hardware dominates classified and ITAR-controlled facilities. US CHIPS Act subsidy recipients in Arizona and Texas default to this model for supply chain audit compliance.
- Cloud-Based:SaaS delivery of verification and design collaboration tools eliminates capital expenditure for fabless designers. Elastic burst capacity during tape-out windows attracts North American semiconductor startups.
- Hybrid:Split architectures keep sensitive process data on-premises while bursting simulation workloads to cloud infrastructure.
- Open Source:Community-developed tools for standard cell characterization and parasitic extraction reduce licensing costs for academic and early-stage commercial users.
Legacy dominance rests with on-premises deployment. Cloud-based delivery is climbing the fastest as foundry customers relax data residency requirements for non-proprietary design blocks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon feedstock from the Hsinchu Science Park anchors Taiwan's dominance in advanced node manufacturing software procurement. Foundry concentration in Taichung and Tainan drives license volumes for design automation and process control platforms. Government-backed expansion in Kaohsiung is redirecting vendor support infrastructure southward.
United States
CHIPS Act subsidies are accelerating software procurement for new fabrication facilities in Arizona and Texas. The Department of Commerce mandates domestic supply chain verification for subsidy recipients, favoring North American vendors. Intel's expansion in Chandler and TSMC's project in Phoenix are concentrating demand for manufacturing execution systems.
South Korea
Memory-focused fabrication clusters in Yongin and Icheon are driving defect detection analytics procurement. The Ministry of Trade, Industry and Energy channels tax incentives through the K-Belt strategy toward indigenous process control development. Samsung's Pyeongtaek complex anchors global demand for yield management software as 3D NAND layer counts multiply.
Japan
Equipment vendors in Tokyo and Osaka are reengineering control architectures for METI's JIS standardization deadlines. The framework mandates open APIs for process parameter logging across lithography and metrology tools. Yokohama-based lithography specialists are concentrating development resources to comply by 2027.
Germany
The EU Chips Act is funding new fabrication capacity in Dresden and Magdeburg, creating first-mover opportunities for software vendors establishing local support. Germany's Federal Ministry for Economic Affairs coordinates subsidy disbursement with domestic procurement requirements. Infineon's expansion in Dresden is driving demand for power semiconductor process control modules.
China
Domestic foundry construction in Shanghai and Beijing is expanding license volumes for manufacturing execution systems despite equipment access constraints. MIIT coordinates national standards for semiconductor equipment interfaces that diverge from SECS/GEM protocols. SMIC's expansion in Shanghai's Zhangjiang Hi-Tech Park is concentrating indigenous software development efforts.
Semiconductor Fabrication Software Market Competitive Environment
Multi-year enterprise agreement consolidation dominates the current landscape as foundries bundle design, verification, and manufacturing execution licenses under centralized procurement offices. The market structure tilts toward integrated portfolios that span design-to-silicon workflows, with point-tool specialists facing margin compression. Three archetypes occupy distinct positions: full-stack design automation houses, equipment-integrated software providers, and cloud-native verification specialists. Strategic partnerships between foundries and software vendors are displacing transactional licensing, while geographic expansion into subsidy-backed European facilities is accelerating vendor resource allocation.
Within the integrated portfolio tier, Synopsys, Applied Materials, and Siemens EDA exemplify the convergence pressure reshaping vendor relationships. Synopsys occupies a position anchoring design automation relationships with leading-edge logic manufacturers. Applied Materials represents the equipment-integrated archetype bridging hardware and software workflows through yield management platforms. Siemens EDA sits within the cloud-ready verification segment, extending reach beyond traditional on-premises installations through elastic compute architectures.
| Leading Market Players |
|---|
| Teradyne |
| Synopsys |
| Applied Materials |
| Ansys |
| Cadence Design Systems |
| ASML |
| Siemens EDA |
| Mentor Graphics |
| Lam Research |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up process control specialists anchor supply concentration in Taiwan and South Korea, translating equipment interface lock-in into pricing discipline that resists unbundling pressure from fabless designers in North America.
Pricing Analysis
Warranty and professional services bundling separates enterprise-grade process control platforms from stripped-down verification tools sold to academic institutions. Perpetual licensing with annual maintenance contracts dominates foundry procurement, though cloud-native verification tools are gaining traction through subscription tiers. Price differentiation hinges on SECS/GEM protocol certification depth and the geographic density of vendor field engineering teams. Cost compression in mature node yield management software is intensifying as memory manufacturers consolidate vendor relationships under multi-year agreements. Research institutions exhibit the highest price sensitivity, while Taiwan-based foundries prioritize integration reliability over license cost.
Supply Chain Analysis
Photoresist supply rests on Japanese specialty chemical producers concentrated in Tokyo and Osaka, while extreme ultraviolet lithography source components draw from Dutch and German precision engineering clusters. Advanced node software development feeds from Taiwan's Hsinchu Science Park talent density and South Korea's K-Belt research consortia. Single-source vulnerability concentrates in computational lithography algorithms patented by a handful of design automation houses. Distribution runs through direct enterprise sales teams for foundry customers and value-added resellers serving mid-tier integrated device manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The semiconductor fabrication software market sits in a technology-transition phase as AI-driven anomaly detection displaces rule-based statistical process control systems in 300mm fabrication facilities.
For Market Incumbents: Hedge against cloud-native verification specialists by embedding machine learning inference engines directly into on-premises process control installations. Acquire field engineering capabilities in Germany and Arizona to secure CHIPS Act and EU Chips Act subsidy compliance relationships. The threat of open-source EDA tools gaining traction among academic users demands preemptive certification investment in JIS and MIIT standards. For New Entrants and Emerging Players: Launch via hybrid deployment models targeting European captive capacity buildouts in Dresden and Magdeburg where incumbent support infrastructure remains underdeveloped. White-space opportunities concentrate in brownfield 200mm fab middleware development and GDPR-compliant process data analytics for automotive semiconductor suppliers. A direct sales approach to power semiconductor integrated device manufacturers bypasses foundry procurement consolidation. For Investors and Strategic Acquirers: Distressed-cycle entries favor cloud-native verification specialists with established elastic compute architectures in North America. Long-term viability over a multi-year horizon hinges on regulatory compliance moats around US and European subsidy disbursement requirements. The signal to watch is foundry consolidation of software procurement under single-vendor enterprise agreements, which would accelerate point-tool specialist margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Native Process Control Platform Launch | Machine learning inference at the edge displaces rule-based SPC in Samsung and TSMC fabs. |
| European Support Infrastructure Expansion | Local engineering presence in Dresden captures Infineon and Intel subsidy-backed procurement. |
| SECS/GEM Protocol Certification Investment | JIS and MIIT compliance opens equipment-integrated software procurement in Japan and China. |
| Cloud Verification Partnership with Hyperscalers | Elastic burst capacity attracts North American fabless designers during tape-out windows. |
| Digital Twin Convergence Development | Predictive maintenance contracts extend revenue beyond perpetual licenses at memory manufacturers. |
Study Parameters
SEC filings from publicly traded design automation vendors, hyperscaler capex disclosures, and foundry equipment procurement databases formed the secondary backbone. Primary interviews with fab operations directors, EDA platform engineers, and semiconductor equipment procurement managers validated bottom-up license volume estimates against top-down wafer capacity expansion projections.
Historical trendline analysis of software procurement intensity per 1000 wafer starts informed the projection framework across the analysis window. Segmentation dimensions modeled include deployment architecture, end-user fab type, and process node complexity tier. CAGRs derived from vendor-reported license growth rates and foundry capital expenditure patterns. Forecast inputs incorporated AI adoption curves in process control and cloud migration velocity among fabless designers.
The model assumes a particular technology adoption path; alternative pathways for EUV-enabled computational lithography would alter the outlook. Forecasts reflect assumptions about subsidy disbursement timelines and equipment access constraints in specific geographies. A small set of named triggers—foundry consolidation events, protocol standardization deadlines, and sovereign data localization enforcement—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Sales Engagement Platform Market
Software & Services
HACCP Software Market
Software & Services
Lab Automation Software Market
Software & Services
App Development Software Market
Software & Services
Photo Editor App Market
Software & Services
Global Mindfulness Meditation Apps Market
Software & Services
Lighting Control Software Market
Software & Services
Middle East HR Payroll Software Market
Software & Services
Global Membership Management Software Market
Software & Services
Global Pharmaceutical Manufacturing Software Market
Software & Services
Global Proposal Management Software Market
Software & Services
Audio and Video Editing Software Market
Software & Services
Global Big Data Software Market
Software & Services
Global Order Management Software Market
Software & Services
Computer Assisted Translation Software Market
Software & Services
Performing Arts Software Market