
 Europe IoT Services Market | 2026-2036
Europe IoT Services Market Size, Share, and Industry Trends Forecast 2026-2036
Europe IoT Services Market Intelligence
A transition from single-vendor lock-in to multi-source service integration is restructuring the competitive landscape for IoT services in Europe. Siemens leverages its deep industrial domain expertise to offer vertically-focused solutions for manufacturing and infrastructure clients. Telecommunication firms like Vodafone Group Plc and Deutsche Telekom AG compete on connectivity management and platform-as-a-service offerings, capitalizing on their extensive network assets across the continent.
Europe IoT services encompass the professional and managed support required to design, deploy, and operate interconnected device networks. This includes initial consulting on technology stacks and ensuring low-latency communication for real-time industrial applications. Among service types, managed services and complex integration projects are gaining share over basic support and maintenance contracts. For applications, industrial automation and smart city initiatives represent the largest investment areas, while connected healthcare shows high growth potential.
The European Union's General Data Protection Regulation (GDPR) and the upcoming EU AI Act establish strict rules for data handling and algorithmic transparency. These regulations directly influence service design, requiring providers to build privacy and security into their platforms from the outset, often using CE marking as a benchmark for device compliance. Service providers must now decide whether to specialize in high-compliance sectors or focus on less regulated commercial applications.
Market Dynamics
The imperative to comply with European Union regulations on sustainability and data governance is the central force shaping the IoT services market. Mandates like the CSRD and GDPR are compelling enterprises to adopt IoT for monitoring and reporting, directly influencing service design and vendor selection.
Growth Catalysts
- Corporate Sustainability Reporting Directive (CSRD):This EU directive compels large companies to report on sustainability metrics, driving demand for IoT services to monitor energy consumption, resource use, and emissions in industrial and commercial buildings.
- Industrie 4.0 Initiatives:Germany's leadership in Industrie 4.0 and advanced manufacturing creates a concentrated demand for sophisticated IoT integration services that connect production machinery, supply chains, and enterprise resource planning systems.
- Smart City Investments:Public sector investment across Europe in smart city projects for traffic management, public safety, and utility monitoring requires large-scale, professionally managed IoT service deployments to operate and maintain the underlying infrastructure.
Market Restraints
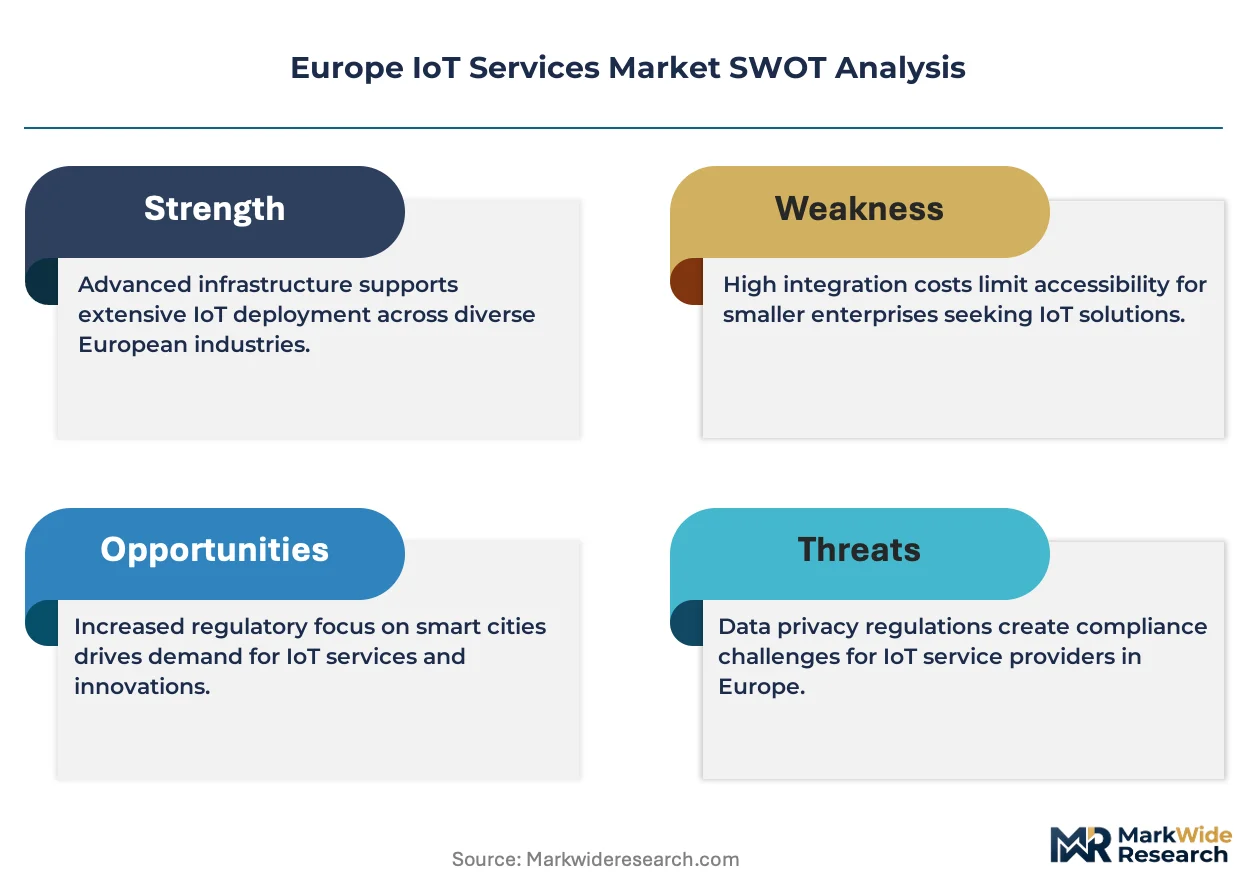
- Protocol Fragmentation:The lack of a single, universally adopted communication standard for IoT devices creates significant interoperability issues, complicating integration projects and increasing deployment costs for service providers.
- GDPR Compliance Burden:The strict data protection and residency requirements of the General Data Protection Regulation add complexity and cost to designing and operating IoT services, particularly for cross-border applications within the EU.
- Legacy System Inertia:The prevalence of older, proprietary operational technology (OT) systems in Europe's established industrial base presents a significant technical barrier to integrating modern IoT solutions without extensive and costly retrofitting.
Strategic Opportunities
- Connected Healthcare Services:Europe's aging population and focus on healthcare efficiency create a substantial opportunity for specialized IoT services in remote patient monitoring, hospital asset tracking, and pharmaceutical cold chain logistics.
- Edge-AI Service Models:The convergence of 5G and edge computing enables new service opportunities for real-time industrial process control, autonomous vehicle systems, and augmented reality for field technicians, where low latency is critical.
- Regulatory Specialization:Service providers can develop premium offerings focused on high-compliance sectors, building expertise in navigating the EU AI Act and GDPR to serve clients in critical infrastructure, finance, and healthcare.
Industry Challenges
- OT and IT Skill Gaps:A persistent shortage of professionals with combined expertise in both operational technology (OT) environments and IT cybersecurity creates a major challenge in securely deploying and managing industrial IoT systems.
- Complex System Integration:Service providers face significant technical hurdles when integrating new IoT platforms with a client's disparate legacy enterprise systems, such as ERP and MES, which often lack modern APIs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe IoT Services Market |
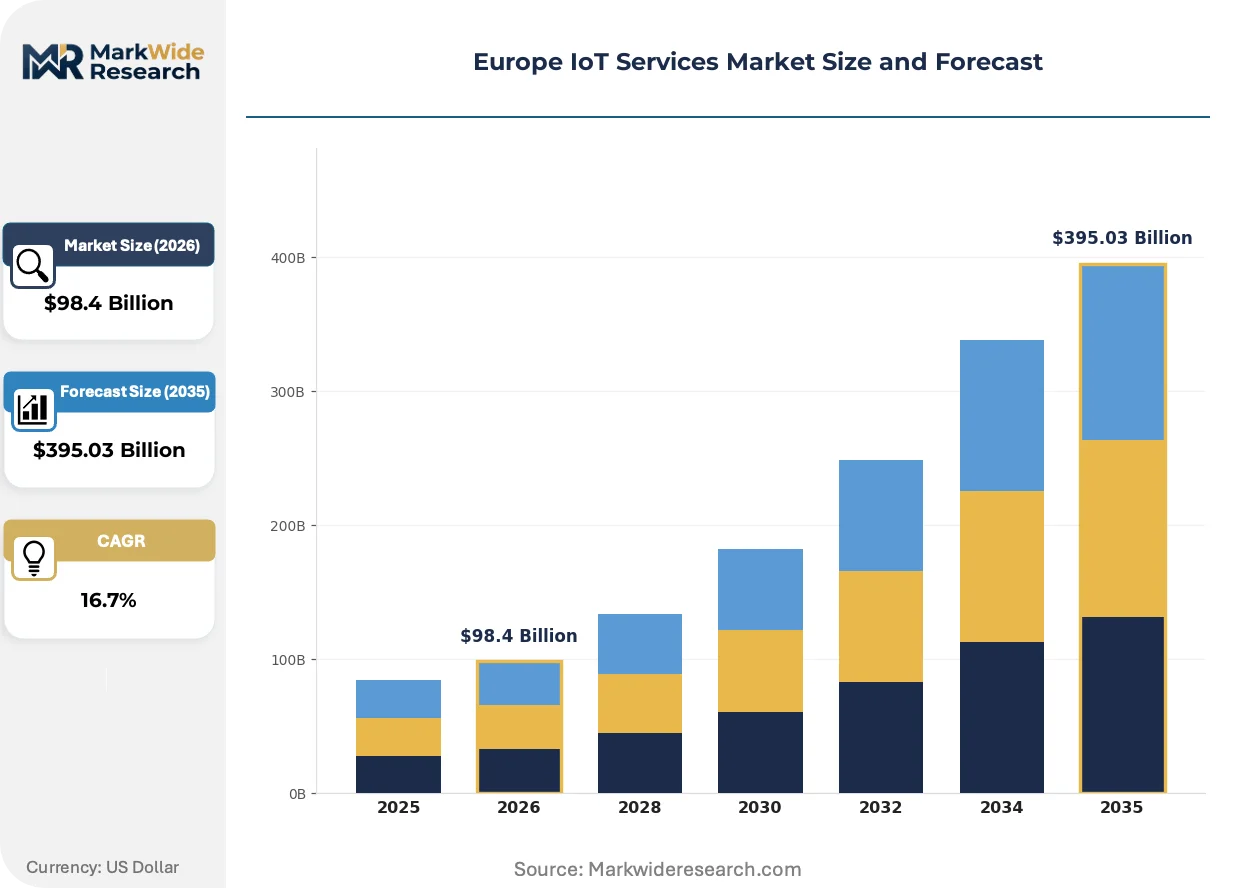
| Market Size in 2026 | $98.4 Billion |
| Market Size in 2035 | $395.03 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consulting, Managed Services, Integration, Support & Maintenance, Training Application: Smart Cities, Connected Healthcare, Industrial Automation, Fleet Management, Energy Monitoring Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Edge Computing, On-Premise End User Industry: Manufacturing, Transportation, Utilities, Agriculture, Telecommunications |
| Companies Covered | SAP SE, Schneider Electric, Siemens, Vodafone Group Plc, Ericsson, IBM Corporation, Robert Bosch GmbH, Deutsche Telekom AG, Cisco Systems, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe IoT Services Market Strategic Shifts & Innovations
The market's evolution is defined by a push toward more intelligent and compliant service architectures. Service providers are moving beyond basic connectivity to deliver vertically-integrated solutions that embed data processing and regulatory adherence directly into the network fabric.
Edge computing provides local data processing capabilities on or near IoT devices, reducing the need to send all raw data to a central cloud. Industrial automation and smart city operators are adopting this technology to enable faster decision-making and real-time control. As a result, the network edge is absorbing many of the data analytics and event-processing functions that were previously exclusive to centralized cloud platforms.
The European Union's forthcoming AI Act establishes risk-based requirements for artificial intelligence systems, directly impacting IoT services that use machine learning. This legislation mandates transparency and human oversight for AI applications deemed high-risk. Consequently, service providers targeting sectors like critical infrastructure and medical devices are proactively redesigning their platforms to ensure algorithmic accountability and auditable compliance.
A notable behavioral shift sees enterprise clients moving away from purchasing discrete components like connectivity and platforms. They now demand end-to-end, outcome-based services tailored to specific business problems, disrupting the model for pure-play telecommunication firms. This procurement pattern is most visible within Germany’s manufacturing sector, where customers expect IoT services to be fully integrated into production workflows and deliver measurable efficiency gains.
Europe IoT Services Market Segmentation
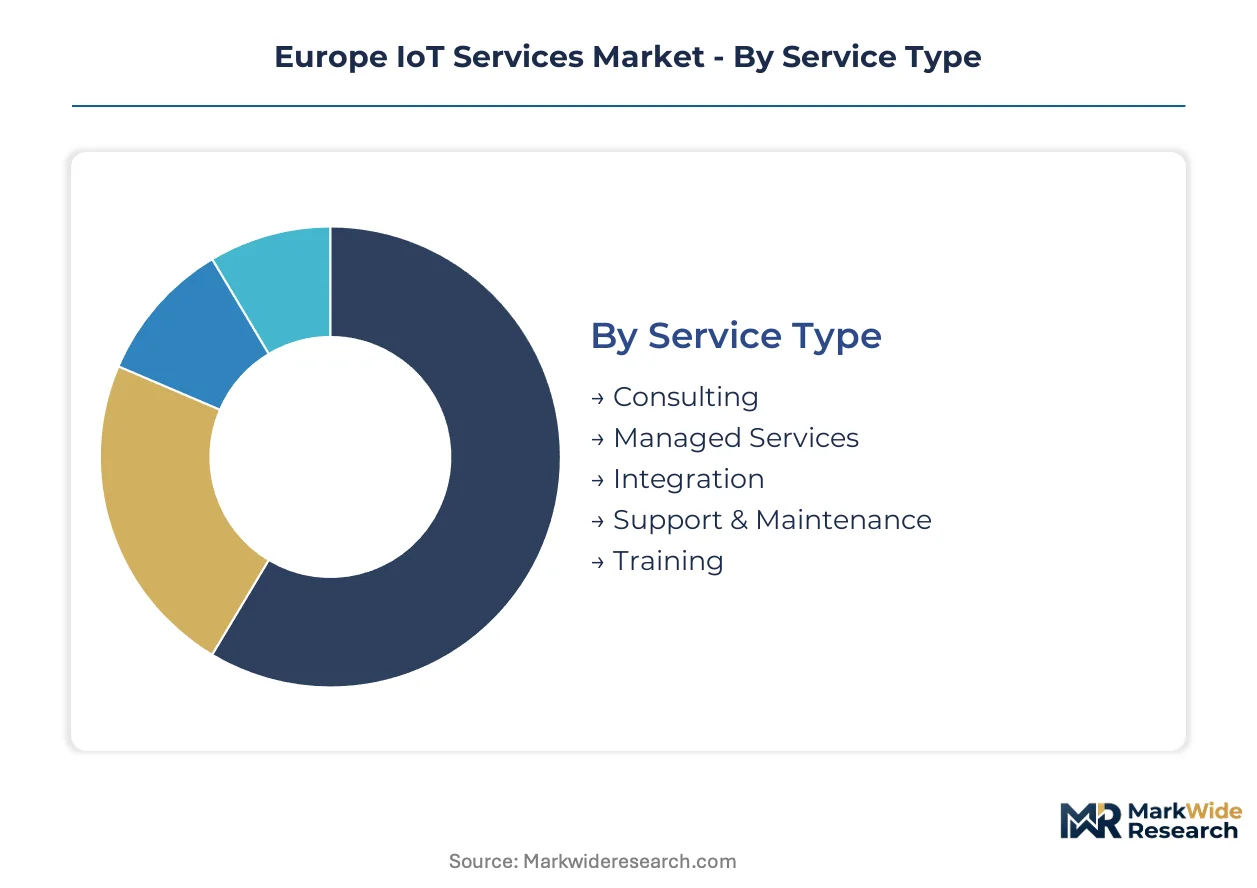
The Europe IoT services market is segmented to reflect the diverse operational requirements and technological maturity across various industries. Understanding these distinctions helps service providers tailor offerings to specific client needs, from foundational infrastructure to complex data analytics. This granular view highlights where investment is concentrated and where specialized expertise drives value.
Service Type:
Buyers in the European IoT services market differentiate based on the level of ongoing support and strategic input required for their interconnected systems. Some seek comprehensive, long-term operational management, while others require specialized, project-based assistance.
- Managed Services:Providers remotely monitor, maintain, and optimize client IoT infrastructure and applications, ensuring operational continuity and performance. European enterprises increasingly outsource these functions to reduce internal IT burden and leverage specialized vendor expertise.
- Integration:This involves connecting new IoT devices and platforms with existing enterprise systems like ERP or MES, often requiring custom development and API management. Complex integration projects are particularly prevalent in Germany's advanced manufacturing sector, where legacy systems are common.
- Consulting:Strategic advice on IoT technology adoption, use case identification, vendor selection, and regulatory compliance, including GDPR and the EU AI Act. European businesses seek expert guidance to navigate complex technological and legal landscapes.
- Support & Maintenance:Basic technical assistance, troubleshooting, and routine updates for deployed IoT devices and software. This service ensures the foundational reliability of IoT deployments across the continent.
- Training:Programs designed to equip client staff with the skills necessary to operate, manage, and derive insights from IoT systems. Skill development is crucial for maximizing the return on IoT investments in European industries.
Volume sits with Managed Services; growth tilts toward Integration.
Application:
The specific operational challenges and strategic objectives of European organizations drive their investment in distinct IoT application areas. Each application addresses unique pain points, from urban efficiency to industrial productivity.
- Industrial Automation:IoT solutions deployed in manufacturing and process industries to optimize production lines, monitor machinery, and enable predictive maintenance. Germany's Industrie 4.0 initiatives heavily rely on these applications for operational efficiency.
- Smart Cities:Comprehensive IoT deployments for urban infrastructure management, including intelligent traffic systems, public safety, and environmental monitoring. Public sector investments across Europe are significant in this application area.
- Connected Healthcare:IoT devices and services for remote patient monitoring, hospital asset tracking, and chronic disease management, catering to Europe's aging population. This segment exhibits high growth potential due to healthcare efficiency mandates.
- Fleet Management:Telematics and sensor-based solutions for tracking vehicles, optimizing routes, and monitoring driver behavior in commercial transportation. European logistics companies adopt these systems for cost reduction and regulatory compliance.
- Energy Monitoring:IoT sensors and platforms used to track energy consumption in buildings, industrial facilities, and utility grids. This application supports EU sustainability directives like the CSRD by providing data for emissions reporting.
Industrial Automation applications show the steepest expansion trajectory, while Connected Healthcare is gaining share fastest.
Deployment Model:
The technical architecture and data residency requirements of European enterprises dictate their choice of IoT deployment models. Factors like data sensitivity, latency, and scalability influence these decisions.
- Edge Computing:Data processing occurs at or near the IoT devices, reducing latency and bandwidth usage, critical for real-time industrial control and autonomous systems. European industrial operators increasingly leverage edge capabilities for faster decision-making.
- Hybrid Cloud:A combination of public and private cloud environments, allowing enterprises to manage sensitive data on-premise while leveraging public cloud scalability for less critical workloads. This model offers flexibility for diverse European business needs.
- Public Cloud:IoT services hosted on third-party cloud infrastructure, offering scalability, cost-effectiveness, and broad accessibility. Many European startups and smaller enterprises utilize public cloud for rapid IoT deployment.
- Private Cloud:Dedicated cloud infrastructure for a single organization, providing enhanced security, control, and compliance with data residency regulations like GDPR. Large European corporations and government entities often prefer private cloud solutions.
- On-Premise:IoT infrastructure and applications hosted entirely within the client's physical data centers, offering maximum control and security for highly sensitive operations. This model is common in critical infrastructure sectors across Europe.
The market's technical architecture is largely defined by Edge Computing and Hybrid Cloud adoption.
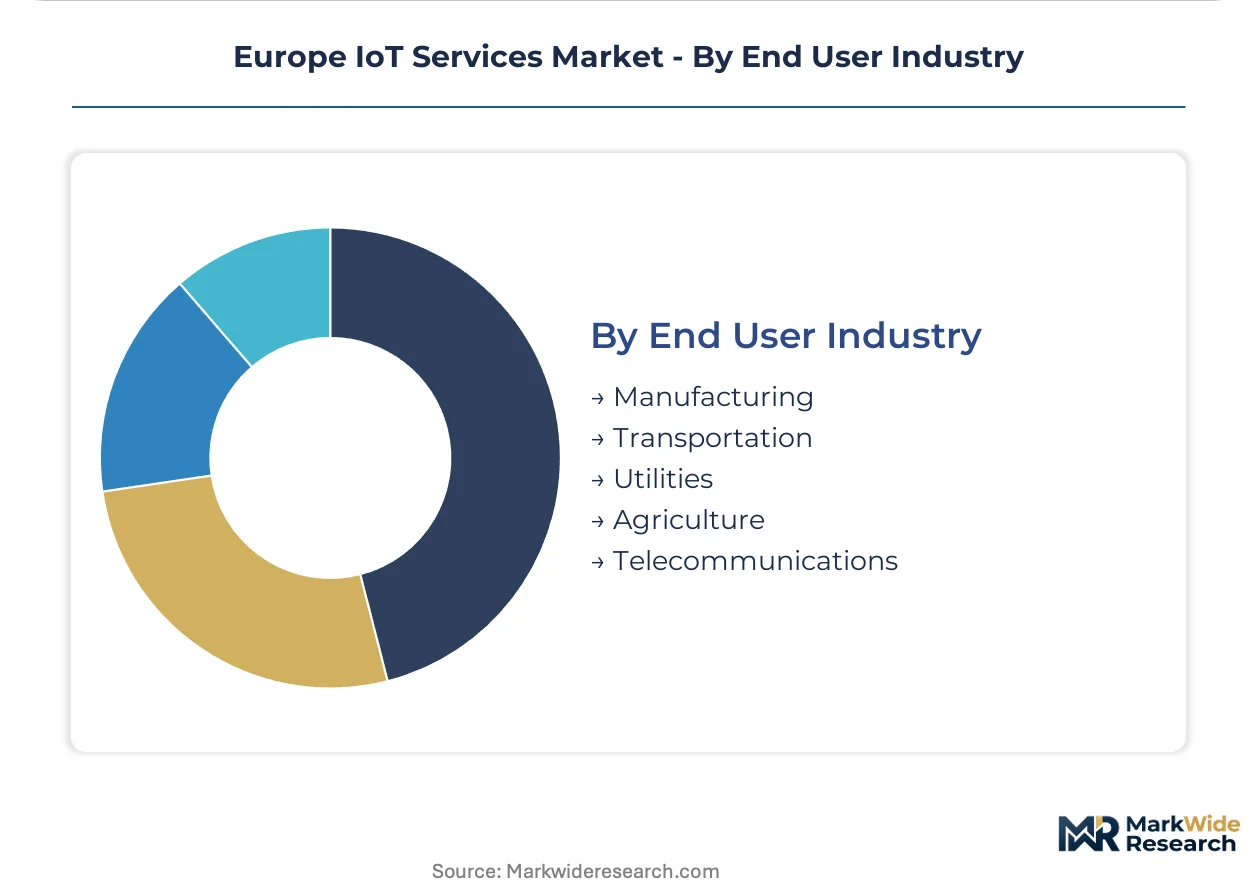
End User Industry:
The distinct operational environments and regulatory frameworks of various industries across Europe shape their specific demand for IoT services. Each sector presents unique challenges and opportunities for technology deployment.
- Manufacturing:Industries such as automotive, machinery, and electronics leverage IoT for smart factories, predictive maintenance, and supply chain optimization. Germany's manufacturing sector is a primary adopter of advanced IoT services.
- Transportation:This sector uses IoT for fleet management, smart logistics, and intelligent public transport systems, improving efficiency and safety across European networks. Real-time tracking and monitoring are central to these operations.
- Utilities:Energy, water, and waste management companies deploy IoT for smart grids, remote asset monitoring, and resource optimization. European utilities are driven by sustainability goals and efficiency mandates.
- Agriculture:IoT applications for precision farming, livestock monitoring, and crop management, optimizing resource use and increasing yields. Adoption is growing in European agricultural regions seeking improved productivity.
- Telecommunications:Telcos deploy IoT for network optimization, infrastructure monitoring, and offering IoT connectivity and platform services to other industries. These firms capitalize on their extensive network assets across the continent.
Regulatory compliance shapes demand within Manufacturing and Utilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's advanced manufacturing base anchors the European IoT services market, driving innovation and substantial investment across the continent. This region's diverse economies and stringent regulatory environment compel enterprises to adopt advanced IoT solutions for efficiency, sustainability, and data governance. European Union directives significantly shape deployment priorities, pushing for compliant and integrated service architectures.
Germany
Demand for IoT services in Germany stems from its robust Industrie 4.0 initiatives and advanced manufacturing sector. The EU's Corporate Sustainability Reporting Directive (CSRD) compels German firms to implement IoT for environmental monitoring and reporting. Bavaria, a hub for automotive and machinery manufacturing, sees concentrated demand for predictive maintenance and smart factory solutions.
United Kingdom
The United Kingdom's digital economy and smart city investments generate significant demand for IoT services, particularly in urban infrastructure and logistics. While outside the EU, UK GDPR still mandates strict data protection, influencing service design for data residency. London's vibrant tech ecosystem drives adoption in smart buildings and public safety applications.
France
France prioritizes smart city development and industrial digitalization, creating a strong market for IoT services in public utilities and transportation. The forthcoming EU AI Act will directly impact AI-driven IoT applications, requiring transparency and accountability. The Île-de-France region, with its dense urban areas, leads in smart mobility and environmental sensing deployments.
Netherlands
The Netherlands shows strong demand for IoT in logistics, port automation, and precision agriculture, leveraging its strategic geographic position. Adherence to GDPR is a critical factor for Dutch enterprises handling sensitive operational data. The Port of Rotterdam exemplifies large-scale IoT integration for efficient cargo handling and supply chain optimization.
Italy
Italian manufacturing, particularly in automotive and machinery, drives demand for IoT services focused on production optimization and asset tracking. The EU's focus on digital transformation encourages Italian companies to invest in compliant IoT platforms. Lombardy, a major industrial region, sees significant adoption of industrial IoT for factory automation and quality control.
Europe IoT Services Market Key Industry Players
Strategic partnerships dominate the current landscape, as service providers combine specialized capabilities to offer comprehensive IoT solutions. The market exhibits a transition from fragmented point solutions to integrated, outcome-based offerings. Key archetypes include vertically-focused industrial specialists, broad-based telecommunication providers, and emerging regulatory compliance experts. Portfolio diversification and geographic expansion represent significant competitive moves among market participants.
Among vertically-focused providers, Siemens exemplifies deep industrial domain expertise, offering specialized IoT solutions for manufacturing and infrastructure clients across Europe. Telecommunication firms like Vodafone Group Plc and Deutsche Telekom AG anchor the connectivity and platform-as-a-service segments. These companies leverage their extensive network assets to provide foundational IoT infrastructure and managed services.
| Leading Market Players |
|---|
| SAP SE |
| Schneider Electric |
| Siemens |
| Vodafone Group Plc |
| Ericsson |
| IBM Corporation |
| Robert Bosch GmbH |
| Deutsche Telekom AG |
| Cisco Systems |
| Others |
Cost & Logistics Intelligence
The cost of secure data transmission, a key component in IoT services, influences pricing structures from foundational connectivity to complex integration projects across European industries.
Pricing Analysis
Service bundling options, from basic support to full managed services, define the initial pricing conversation for European IoT clients. The dominant pricing model is a hybrid of subscription-based managed services and project-based integration fees. Price differentiation stems from the level of customization required for legacy system integration and the compliance assurance provided for GDPR and the EU AI Act. Pricing softness affects basic connectivity offerings due to increasing competition from telecommunication firms. Public sector smart city initiatives exhibit higher price sensitivity compared to critical infrastructure operators in manufacturing and utilities.
Supply Chain Analysis
Direct sales channels and specialized system integrators manage the distribution of complex IoT service solutions to European enterprises. Component supply for IoT devices draws heavily from Asian manufacturers, particularly for semiconductor chips and specialized sensors. Cloud infrastructure, essential for IoT platforms, relies on a concentrated base of hyperscalers with data centers located across Germany, Ireland, and the Netherlands. A structural risk involves geopolitical tensions impacting semiconductor component availability, which can delay hardware deployments. Channel partners often provide last-mile integration and support for regional clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The European IoT services market is becoming a vertical-integration race, with providers pursuing deeper control over specialized software stacks and regulatory compliance frameworks.
For Market Incumbents: Lock in long-term contracts with critical infrastructure clients by embedding compliance guarantees for the EU AI Act and GDPR. Deepen vertical integration into edge computing capabilities to counter the threat of commoditized cloud offerings. Invest in specialized OT/IT cybersecurity talent to address persistent skill gaps and secure industrial deployments. Leverage existing customer relationships in Germany's manufacturing sector to cross-sell advanced predictive maintenance solutions.
For New Entrants and Emerging Players: The EU AI Act in Europe opens a window for specialized providers to offer AI auditing and transparency services for high-risk IoT applications. Target underpenetrated sectors like precision agriculture in the Netherlands or connected healthcare across the continent. Develop outcome-based service models focused on measurable sustainability improvements to appeal to CSRD-mandated enterprises. A go-to-market angle involves partnering with local system integrators to navigate regional market nuances and build trust.
For Investors and Strategic Acquirers: The widespread adoption of 5G private networks in industrial zones is the leading indicator that edge-AI service models are reaching commercial maturity. Long-term viability favors providers with deep vertical expertise in high-compliance sectors like critical infrastructure and healthcare. Acquisition targets should be specialized firms offering proprietary data analytics platforms or niche regulatory compliance solutions. Watch for consolidation among smaller regional players as they seek scale to compete with larger telecommunication firms.
| Strategic Initiative | Industry Significance |
|---|---|
| Strategic Partnership | Combines specialized capabilities to deliver comprehensive, end-to-end IoT solutions for European clients. |
| Edge Computing R&D | Enables real-time industrial control and autonomous systems, reducing latency for critical applications. |
| Regulatory Compliance Specialization | Builds trust and differentiation in high-compliance sectors like healthcare and critical infrastructure. |
| Talent Development Programs | Addresses the critical OT and IT skill gaps necessary for secure industrial IoT deployments. |
| Outcome-Based Service Models | Aligns provider incentives with client business objectives, driving measurable efficiency gains. |
Research Approach
EU Commission reports, national statistical offices, and industry association publications formed the secondary backbone, validated by primary interviews. This involved discussions with IoT solution architects, industrial automation engineers, smart city planners, and data privacy officers across Europe. Data was triangulated using both bottom-up market sizing from individual deployments and top-down validation against macroeconomic indicators and enterprise IT spending.
A bottom-up analytical framework aggregated granular data from various service types and applications, then reconciled through top-down macroeconomic factors across the analysis window. Segmentation dimensions modeled included service type, application, deployment model, end-user industry, and regional regulatory adherence. CAGRs were derived by projecting adoption rates, average contract values, and technology penetration across different European countries. Key forecast inputs included enterprise digital transformation budgets and public sector infrastructure spending trends.
The model assumes a particular technology adoption path; alternative pathways for quantum computing or advanced neuromorphic chips would alter the outlook for edge-AI services. Forecasts reflect assumptions regarding regulatory stability and sustained investment in digital infrastructure. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Global Internet of Things (IoT) Software Market
Internet of Things (IoT)
Bluetooth Smart Plugs Market
Internet of Things (IoT)
IoT Microcontroller Market
Internet of Things (IoT)
Consumer IoT Market
Internet of Things (IoT)
Internet of Things (IoT) in Manufacturing Market
Internet of Things (IoT)
Smart Pool Systems Market
Internet of Things (IoT)
LPWAN in the Consumer IoT Market
Internet of Things (IoT)
IoT Smart Poles Market
Internet of Things (IoT)
IoT Gateway Devices Market
Internet of Things (IoT)
IoT Middleware Market
Internet of Things (IoT)
North America Internet of Things Devices Market
Internet of Things (IoT)
Global IoT Managed Services Market
Internet of Things (IoT)
Cellular IoT Module Market
Internet of Things (IoT)
IoT Cellular Market
Internet of Things (IoT)
South Africa IoT Market
Internet of Things (IoT)
IoT Gateway Hardware and Software Market