
 AI Text Generator Market | 2026-2036
AI Text Generator Market Size, Share, and Industry Trends Forecast 2026-2036
AI Text Generator Market Intelligence
Market Dynamics and Strategic Positioning
Fragmentation across new buyer segments is repositioning vendor priorities toward SMEs and individual content creators. Jasper dominates brand storytelling workflows for mid-market agencies. Writesonic leverages aggressive freemium distribution to capture solo entrepreneurs and startup teams. Anyword anchors performance marketing use cases with predictive copy-scoring capabilities.
Technology Definition and Segment Structure
AI text generators are neural language models, typically transformer architectures with billions of parameters, trained on curated corpora to produce human-like prose, code, or structured documentation for commercial publishing and enterprise communication. Cloud-based solutions lead deployment mode as organizations prioritize scalable inference without infrastructure overhead; API integration represents the fastest-expanding segment as developers embed generative capabilities into existing martech stacks. Standalone software retains margin concentration among creative professionals seeking curated user experiences.
Regulatory Environment and Strategic Outlook
The EU AI Act classifies generative text systems as general-purpose AI with transparency mandates, while the US FTC scrutinizes deceptive automated content under consumer protection statutes and China's SAMR imposes algorithmic recommendation regulations. Compliance costs are diverting R&D budgets toward watermarking, provenance tracking, and audit trail architectures. Stakeholders must monitor divergence between Brussels-style ex-ante rules and Washington's enforcement-driven posture to anticipate market access conditions.
Market Dynamics
Transformer architectures with parameter counts exceeding 100 billion are compressing content production timelines from weeks to hours, forcing enterprise marketing departments to restructure creative workflows around human-AI collaboration rather than traditional copywriting hierarchies.
Growth Catalysts
- EU AI Act transparency mandates:Automated content disclosure requirements are accelerating procurement of compliant generative tools by European publishers and advertising networks seeking to preempt enforcement actions.
- Mid-market agency expansion:Brand storytelling workflows are absorbing AI copywriting subscriptions as creative directors prioritize volume scalability over headcount growth.
- API-first embedding:Developers are weaving generative text capabilities into martech stacks through REST endpoints, reducing friction for enterprise software vendors adding native AI features.
Market Restraints
- Compute cost volatility:GPU cluster pricing fluctuations and NVIDIA supply constraints are compressing vendor margins and forcing tiered access models for high-volume inference.
- Training data licensing friction:Copyright disputes over scraped corpora are generating legal exposure for foundation model providers and downstream commercial deployers.
- Output reliability ceilings:Hallucination rates in long-form content generation are limiting deployment for regulated industries requiring factual precision.
Strategic Opportunities
- India's SME content gap:Vernacular-language generative tools are capturing underserved regional digital marketing demand as Indian e-commerce penetration accelerates.
- Healthcare documentation convergence:Clinical note generation paired with voice recognition is expanding into hospital IT procurement budgets previously reserved for separate systems.
- ISO/IEC 42001 alignment:Early certification against emerging AI management system standards is creating differentiation for enterprise vendors in RFP evaluation criteria.
Industry Challenges
- Prompt engineering talent scarcity:Organizations struggle to hire specialists capable of optimizing chain-of-thought workflows for production-grade output consistency.
- Legacy CMS integration complexity:Decade-old content management architectures require middleware development to accommodate real-time generative API calls.
- Attribution audit trail construction:Marketing teams face operational burdens documenting human versus AI contribution ratios for client transparency requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI Text Generator Market |
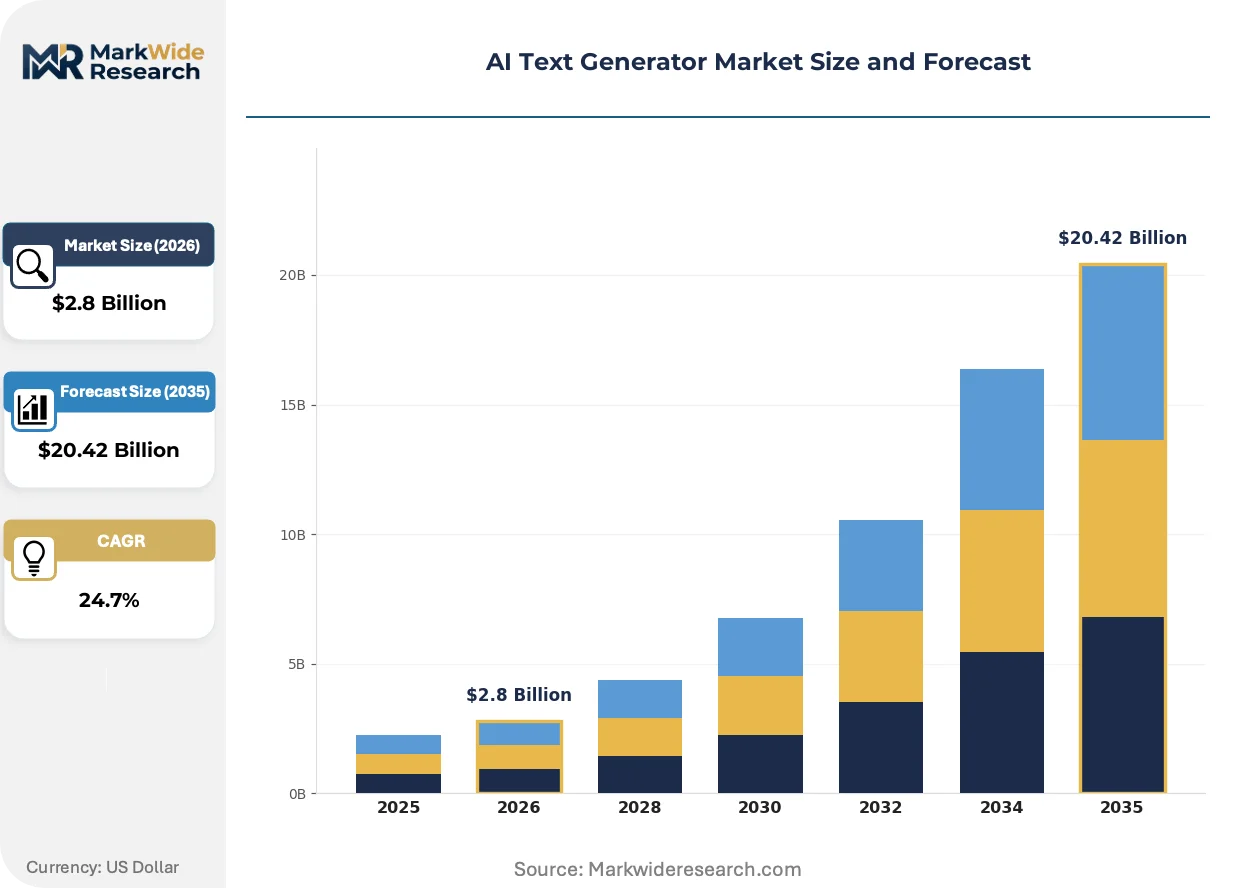
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $20.42 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Software, API Integration, Cloud-based Solutions, On-premise Solutions End User: Enterprises, SMEs, Educational Institutions, Content Creators Application: Marketing Content, Social Media Management, Blogging, Technical Documentation Integration Level: Full Integration, Partial Integration, No Integration, Custom Solutions |
| Companies Covered | Rytr, Writer, Jasper, BlueLabel, Neoteric, Writesonic, Sudowrite, Quytech, Anyword, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI Text Generator Market Strategic Shifts & Innovations
Multimodal foundation models are dissolving boundaries between text, image, and code generation, compelling vendors to reposition around unified creative suites rather than single-modality point solutions.
Retrieval-augmented generation architectures are expanding into enterprise knowledge management by grounding LLM outputs in proprietary document corpora. Financial services compliance teams and legal research departments are adopting these systems fastest, drawn by source-citation capabilities that plain fine-tuning cannot replicate. The technology is expanding into sectors previously blocked by hallucination liability concerns.
Washington's FTC scrutiny of deceptive automated content under Section 5 enforcement authority is tightening disclosure requirements for synthetic media. Advertisers must now label AI-generated copy in ways that satisfy both consumer protection standards and platform content policies. US-based martech vendors are rebuilding creative approval workflows to embed automated compliance checks before publication.
Subscription fatigue among solo entrepreneurs and startup teams is compressing willingness-to-pay for standalone copywriting tools. Freemium conversion rates are deteriorating as users stack multiple narrow-purpose generators rather than consolidating on premium tiers. This behavioral shift is most visible in North American and Western European micro-SME segments where tool proliferation has outstripped actual content production needs.
AI Text Generator Market Segmentation
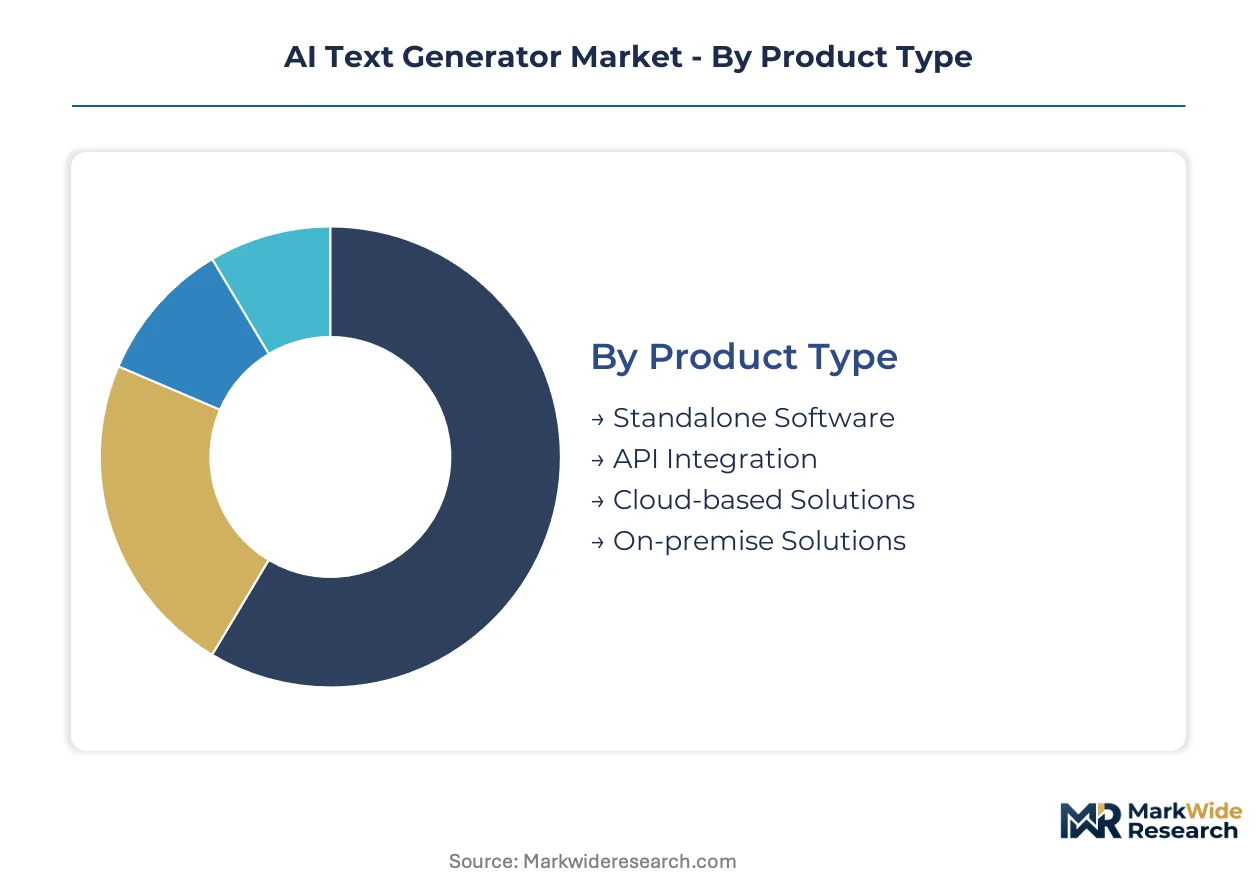
Segmentation in the AI text generator market reveals how procurement patterns diverge between infrastructure-heavy enterprises and agile creative teams. Upgrade cycles vary dramatically: cloud-based deployments refresh quarterly through API versioning, while on-premise installations lock organizations into multi-year hardware amortization schedules.
Product Type:
Replacement cycles in this category stretch from weeks for API tiers to years for captive infrastructure, creating distinct vendor engagement rhythms and margin profiles.
- Cloud-based Solutions:Transformer models hosted on managed GPU clusters deliver inference through browser interfaces and mobile applications. Marketing departments at technology firms in the United States drive procurement here, prioritizing zero-install deployment and automatic model updates over customization depth.
- API Integration:REST and GraphQL endpoints embed generative capabilities into existing martech stacks, CRM platforms, and content management systems. Developer teams at advertising agencies and SaaS vendors concentrate demand, drawn by per-token pricing and rapid feature iteration without frontend redevelopment.
- Standalone Software:Desktop applications with curated user experiences target creative professionals seeking offline capability and persistent local storage.
- On-premise Solutions:Air-gapped deployments serve defense contractors, financial institutions, and healthcare systems with data sovereignty requirements.
Cloud-based Solutions sits at the top of the volume ranking, with API Integration climbing the fastest.
End User:
Customer maturity in this category spans from experimental individual adopters to procurement-governed enterprise rollouts, with contract values scaling accordingly.
- Enterprises:Fortune 500 marketing divisions and technology product teams deploy generative text systems at scale, often negotiating custom SLAs and dedicated support tiers. Compliance teams at these organizations mandate watermarking and audit trail features to satisfy EU AI Act transparency obligations.
- SMEs:Mid-market agencies and regional e-commerce operators subscribe to tiered SaaS plans, balancing output volume against headcount constraints. Solo entrepreneurs and startup teams in North America and Western Europe show deteriorating freemium conversion rates as tool proliferation outstrips actual production needs.
- Content Creators:Independent writers, journalists, and social media influencers purchase individual licenses for brand voice consistency and deadline acceleration.
- Educational Institutions:Universities and research libraries evaluate generative tools for curriculum development, academic integrity policy enforcement, and student writing assistance.
Enterprises commands the largest contract values, while SMEs expand most quickly in absolute seat count.
Application:
Use case specificity in this category determines integration complexity, with marketing workflows demanding the tightest martech coupling and technical documentation requiring the most rigorous fact-checking protocols.
- Marketing Content:Email sequences, landing page copy, and advertisement variants consume the majority of commercial inference volume. Brand storytelling workflows at mid-market agencies absorb subscriptions as creative directors prioritize volume scalability.
- Technical Documentation:API references, user manuals, and code comments demand hallucination-resistant output, limiting deployment to retrieval-augmented architectures with source citation capabilities. Financial services compliance teams and legal research departments adopt these systems fastest.
- Social Media Management:Short-form posts, hashtag generation, and engagement-optimized captions target platform-native content velocity.
- Blogging:Long-form articles and SEO-optimized web content balance search performance against editorial voice consistency.
Marketing Content holds the dominant share of commercial inference volume, with Technical Documentation gaining share fastest among risk-averse sectors.
Integration Level:
Technical debt in legacy content management architectures shapes adoption pathways, with full integration requiring middleware development that partial or no-integration deployments avoid.
- Full Integration:Native embedding within Adobe Creative Cloud, Salesforce Marketing Cloud, and WordPress Gutenberg eliminates context-switching friction. Enterprise software vendors adding generative features drive demand here, rebuilding creative approval workflows to embed automated compliance checks before publication.
- Custom Solutions:Bespoke middleware connects decade-old content management architectures to modern inference APIs. Hospital IT procurement budgets previously reserved for separate clinical note and voice recognition systems now converge here.
- Partial Integration:Browser extensions and clipboard-based workflows bridge standalone generators with target publishing platforms.
- No Integration:Manual copy-paste from dedicated generator interfaces persists among freelancers and small teams with heterogeneous tool stacks.
Full Integration leads current deployment mode, with Custom Solutions expanding most steeply as regulated industries retrofit legacy infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States technology firms outpace German advertising agencies in commercial AI text generator procurement, while India's vernacular-language startups capture underserved SME demand faster than Japanese enterprise software vendors.
United States
Silicon Valley marketing departments and New York advertising agencies drive commercial adoption through API-first embedding strategies. FTC scrutiny of deceptive automated content under Section 5 enforcement authority tightens disclosure requirements for synthetic media. Austin and Seattle clusters host martech vendors rebuilding creative approval workflows to embed automated compliance checks.
Germany
Mid-market agencies in Berlin and Hamburg prioritize brand storytelling workflows with volume scalability over headcount growth. EU AI Act transparency mandates accelerate procurement of compliant generative tools by publishers seeking to preempt enforcement actions. Munich's enterprise software corridor concentrates procurement budgets for ISO/IEC 42001-aligned vendors.
India
Vernacular-language generative tools capture regional digital marketing demand as e-commerce penetration accelerates across Maharashtra and Karnataka. BIS standards for AI systems create compliance frameworks for domestic deployment. Bangalore's SaaS corridor and Delhi-NCR's startup ecosystem anchor developer teams weaving generative capabilities into local martech stacks.
United Kingdom
London's financial services compliance teams adopt retrieval-augmented generation systems for source-citation capabilities in legal research. GDPR alignment shapes procurement criteria for enterprise marketing divisions. Manchester and Edinburgh clusters concentrate mid-market agency subscriptions balancing output volume against budget constraints.
Japan
Tokyo enterprise software vendors integrate generative text into legacy content management architectures requiring middleware development. METI guidelines on AI utilization influence corporate procurement standards. Osaka's industrial automation sector and Fukuoka's startup ecosystem diverge in adoption timelines for human-AI collaboration workflows.
AI Text Generator Market Key Industry Players
United States producers anchor the API-first and cloud-native tier; European specialists hold positions in compliance-forward deployments. The vendor base compresses into three strategic groupings: foundation model providers licensing inference capacity, application-layer vendors curating user experiences, and enterprise platforms embedding generative features into existing stacks. Competitive moves concentrate on strategic partnerships with martech incumbents and portfolio diversification into multimodal creative suites.
Within the application-layer tier, Jasper and Writesonic occupy positions representing alternative distribution philosophies—one targeting mid-market agency workflows, the other leveraging freemium acquisition for solo entrepreneurs. Anyword anchors the performance-marketing specialization vector with predictive copy-scoring capabilities. These three exemplify how vendor archetypes diverge on customer acquisition cost tolerance versus average revenue per user optimization.
| Leading Market Players |
|---|
| Rytr |
| Writer |
| Jasper |
| BlueLabel |
| Neoteric |
| Writesonic |
| Sudowrite |
| Quytech |
| Anyword |
| Others |
Cost & Logistics Intelligence
EU AI Act transparency mandates are forcing foundation model providers to redirect R&D budgets toward watermarking and audit trail architectures, compressing margins and accelerating tiered access models for high-volume inference.
Pricing Analysis
Capacity additions in the United States are reshaping price floors for cloud-based inference as hyperscaler GPU cluster expansions compete with specialized inference providers. Three-tier pricing structure across premium, standard, and economy levels dominates, with differentiation driven by output volume thresholds and ISO/IEC 42001 certification status. Pricing pressure stems from NVIDIA supply constraints and GPU cluster pricing volatility. SMEs and solo entrepreneurs exhibit highest price sensitivity, while Fortune 500 enterprises absorb premium tiers for dedicated SLAs and compliance features.
Supply Chain Analysis
ISO/IEC 42001 certification and EU AI Act compliance documentation are emerging as gating factors for vendor qualification in enterprise procurement cycles. Supply concentrates in the United States, Taiwan, and South Korea for advanced GPU fabrication and cloud infrastructure. Raw material dependencies center on NVIDIA H100/H200 accelerators, high-bandwidth memory modules, and specialized cooling systems. Single-source vulnerability around TSMC's advanced packaging creates chokepoint exposure. Distribution runs through hyperscaler marketplaces and direct API provisioning, with enterprise software vendors embedding generative capabilities via REST endpoints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The AI text generator market functions as a geographic-arbitrage play where vendors can capture margin by locating inference infrastructure in jurisdictions with lower energy costs while selling into EU markets with stricter compliance premiums.
For Market Incumbents: Anchor defensive positioning through backward integration into proprietary training data pipelines and captive GPU cluster reservations. Consolidate API-first partnerships with Adobe Creative Cloud and Salesforce Marketing Cloud to lock out challenger embedding strategies. Invest aggressively in ISO/IEC 42001 certification to create procurement friction against uncertified rivals in EU RFP processes.
For New Entrants and Emerging Players: Freemium distribution through mobile-first interfaces offers the lowest CAC pathway into India's vernacular-language SME segment. Target healthcare documentation convergence where hospital IT procurement budgets remain undersupplied by incumbent clinical note generators. Build retrieval-augmented generation architectures with source-citation capabilities to differentiate in financial services and legal research verticals blocked by hallucination liability concerns.
For Investors and Strategic Acquirers: Asymmetric upside sits with application-layer vendors curating specialized user experiences rather than foundation model providers facing compute cost volatility and copyright litigation exposure. Long-term viability favors vendors with demonstrated enterprise retention and compliance-forward feature roadmaps. Monitor EU AI Act enforcement actions as the critical inflection signal for market access conditions and vendor consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Embedding via REST endpoints captures martech stack real estate at Adobe and Salesforce. |
| ISO/IEC 42001 Certification | Early compliance creates procurement differentiation against uncertified rivals in EU RFPs. |
| Retrieval-Augmented Generation Deployment | Source-citation capabilities unlock financial services and legal research verticals previously blocked by hallucination risk. |
| Vernacular Language Expansion | Regional Indian language support captures underserved SME demand as e-commerce penetration accelerates. |
| Healthcare Documentation Convergence | Clinical note generation paired with voice recognition penetrates hospital IT budgets previously reserved for separate systems. |
Research Approach
Bottom-up enterprise procurement modeling reconciled against top-down cloud inference capacity tracking forms the analytical core. Primary interviews with CTOs at mid-market advertising agencies, martech platform engineers, compliance officers at financial services firms, and procurement leads at hospital systems combined with secondary validation against SEC filings from hyperscaler capex disclosures, EU AI Act implementation guidance, and ISO/IEC 42001 draft standards. Triangulation across these sources ensures demand-side adoption signals align with supply-side infrastructure commitments.
Input-output matrices connect deployment model, organization size, integration complexity, application use case, and regional regulatory cluster to project inference volume and subscription revenue across the analysis window. CAGRs derive from segment-level adoption curves weighted by procurement cycle timing and compliance mandate effective dates. Model inputs include GPU cluster pricing indices, training data licensing friction indicators, and freemium conversion rate trajectories by geography.
The model assumes a particular technology adoption path; alternative pathways for multimodal foundation models would alter the outlook if text-only generators face displacement. Forecasts reflect assumptions about EU AI Act enforcement intensity and FTC Section 5 disclosure requirement expansion. A model refresh is warranted upon material change in hyperscaler GPU supply allocation or major copyright litigation settlement affecting training data licensing norms.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Latin America Artificial Intelligence Market
Artificial Intelligence (AI)
Global Artificial Intelligence SAAS Market
Artificial Intelligence (AI)
Mlops Market
Artificial Intelligence (AI)
Global Conversational Computing Platform Market
Artificial Intelligence (AI)
Artificial Intelligence in Workspace Market
Artificial Intelligence (AI)
AI Industrial Defect Detection Market
Artificial Intelligence (AI)
Affective Computing Market
Artificial Intelligence (AI)
Model Validation and Automation Market
Artificial Intelligence (AI)
Global Ambient Intelligence Market
Artificial Intelligence (AI)
Asia-Pacific Natural Language Processing in BFSI Market
Artificial Intelligence (AI)
Human-Computer Interaction (HCI) Market
Artificial Intelligence (AI)
Europe Artificial Intelligence Market
Artificial Intelligence (AI)
Intelligent Virtual Assistant Market
Artificial Intelligence (AI)
AI Watermarking Market
Artificial Intelligence (AI)
Asia-Pacific Generative AI Market
Artificial Intelligence (AI)
Adaptive AI Market