
 Europe IoT in Smart Cities Market | 2026-2036
Europe IoT in Smart Cities Market Size, Share, and Industry Trends Forecast 2026-2036
Europe IoT in Smart Cities Market Intelligence
The talent pool for IoT systems integration is bifurcating project development between large-scale telecommunication providers and specialized engineering firms. Siemens leverages its deep industrial engineering expertise for complex energy management projects. Vodafone competes on the strength of its expansive NB-IoT and 5G network infrastructure across the continent. Schneider Electric differentiates with its focus on integrated smart building and grid management platforms for urban districts.
Europe's IoT in smart cities market involves deploying networks of interconnected sensors and devices to collect real-time urban data. These systems utilize low-power wide-area networks (LPWAN) like LoRaWAN to transmit small data packets over long distances, enabling long battery life for remote sensors. The primary purpose is to optimize municipal operations, improve public services, and enhance resource efficiency. Traffic management and energy management solutions command significant investment from municipal authorities, while the adoption of 5G represents the fastest-growing technology segment for high-bandwidth applications.
The General Data Protection Regulation (GDPR) imposes strict rules on how personal data from citizen-facing applications is collected and processed by urban planners. Concurrently, the EU AI Act will establish risk-based requirements for algorithms used in public safety and transport management. These regulations shape system architecture and data governance protocols for all new deployments. Stakeholder decisions will hinge on balancing innovation in citizen engagement with evolving data privacy and ethical AI compliance mandates.
Market Dynamics
The imperative to balance large-scale data collection with stringent regulatory frameworks like the General Data Protection Regulation (GDPR) and the EU AI Act is the central force shaping Europe's smart city IoT market, dictating system architecture and data governance protocols.
Growth Catalysts
- EU Green Deal Mandates:Policy directives focused on carbon neutrality and environmental protection are compelling municipalities to invest in IoT for energy management, waste reduction, and air quality monitoring systems.
- LPWAN Technology Maturation:The widespread availability and cost-effectiveness of Low-Power Wide-Area Networks, including LoRaWAN and NB-IoT, enable economically viable, large-scale deployments of battery-operated sensors across urban areas.
- Concentrated Urban Demand:Major metropolitan areas in Germany and France show significant demand for IoT solutions to address traffic congestion, enhance public safety, and optimize resource allocation in densely populated zones.
Market Restraints
- High Initial Capital Outlay:The substantial upfront investment required for city-wide sensor networks, communication infrastructure, and backend data platforms presents a significant barrier for many municipal budgets.
- Regulatory Compliance Burden:Navigating the complexities of the GDPR and preparing for the EU AI Act adds significant cost, time, and legal risk to project development, particularly for citizen-facing applications.
- Interoperability and Standardization Gaps:A fragmented landscape of competing IoT platforms and communication protocols creates vendor lock-in risks and complicates the integration of solutions from different suppliers into a cohesive system.
Strategic Opportunities
- Digital Twin Integration:Combining real-time IoT sensor data with 3D city models to create dynamic digital twins offers new opportunities for advanced predictive analysis in urban planning, traffic simulation, and emergency response.
- Expansion into Public Health:Deploying environmental sensor networks to monitor hyperlocal air quality and noise pollution provides actionable data for public health authorities to mitigate environmental health risks in urban communities.
- Eastern Europe Market Entry:Cities across Eastern Europe represent an underpenetrated market, offering a significant growth opportunity for vendors to deploy proven smart city solutions developed in more mature Western European markets.
Industry Challenges
- Specialized Talent Scarcity:A persistent shortage of data scientists, IoT security specialists, and systems integration engineers capable of designing, deploying, and managing complex urban-scale IoT projects hampers market growth.
- Legacy System Integration:The operational challenge of integrating modern IoT platforms with aging, disparate IT systems within municipal governments often leads to project delays, cost overruns, and functional limitations.
- Building Public Trust:Overcoming citizen concerns regarding data privacy and surveillance in public spaces is a critical hurdle for gaining the social license needed to implement and scale smart city initiatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe IoT in Smart Cities Market |
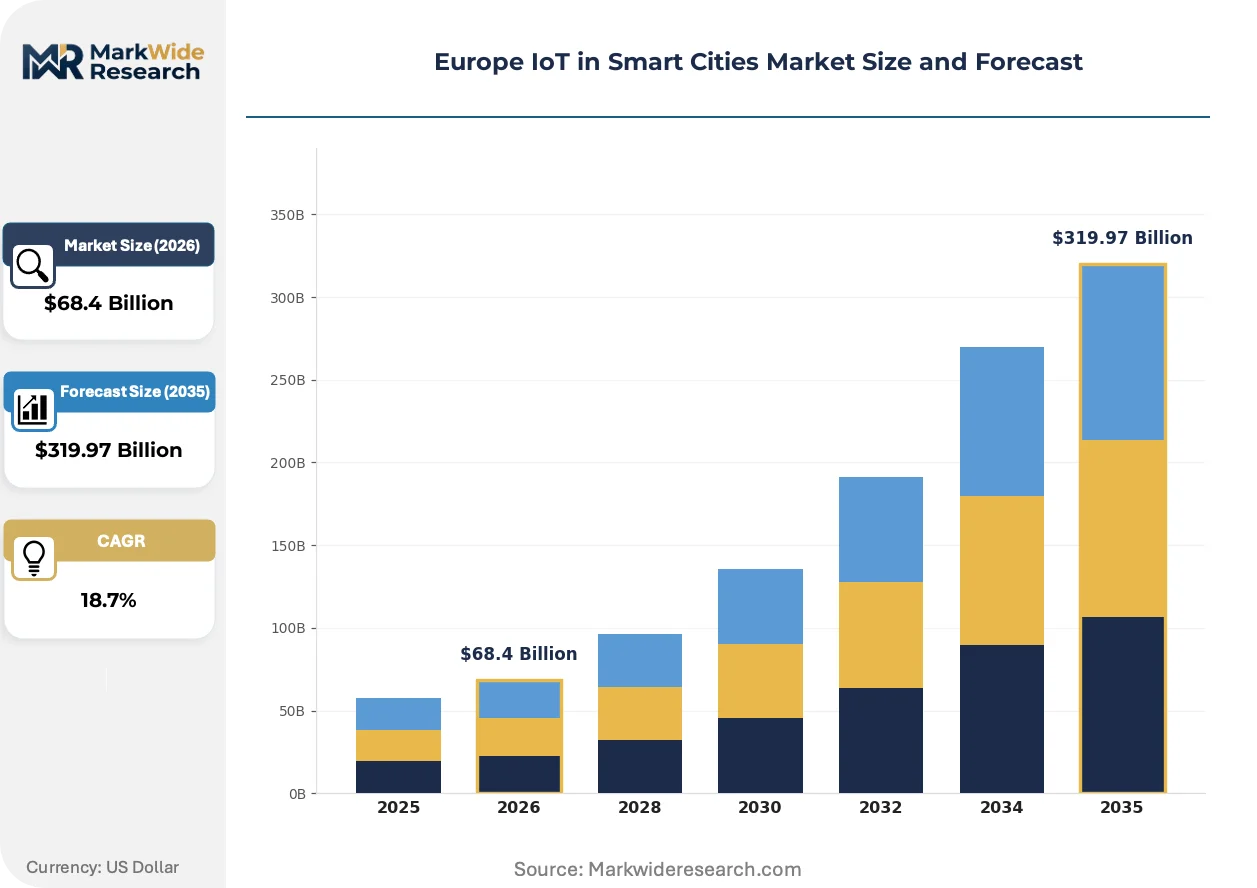
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $319.97 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
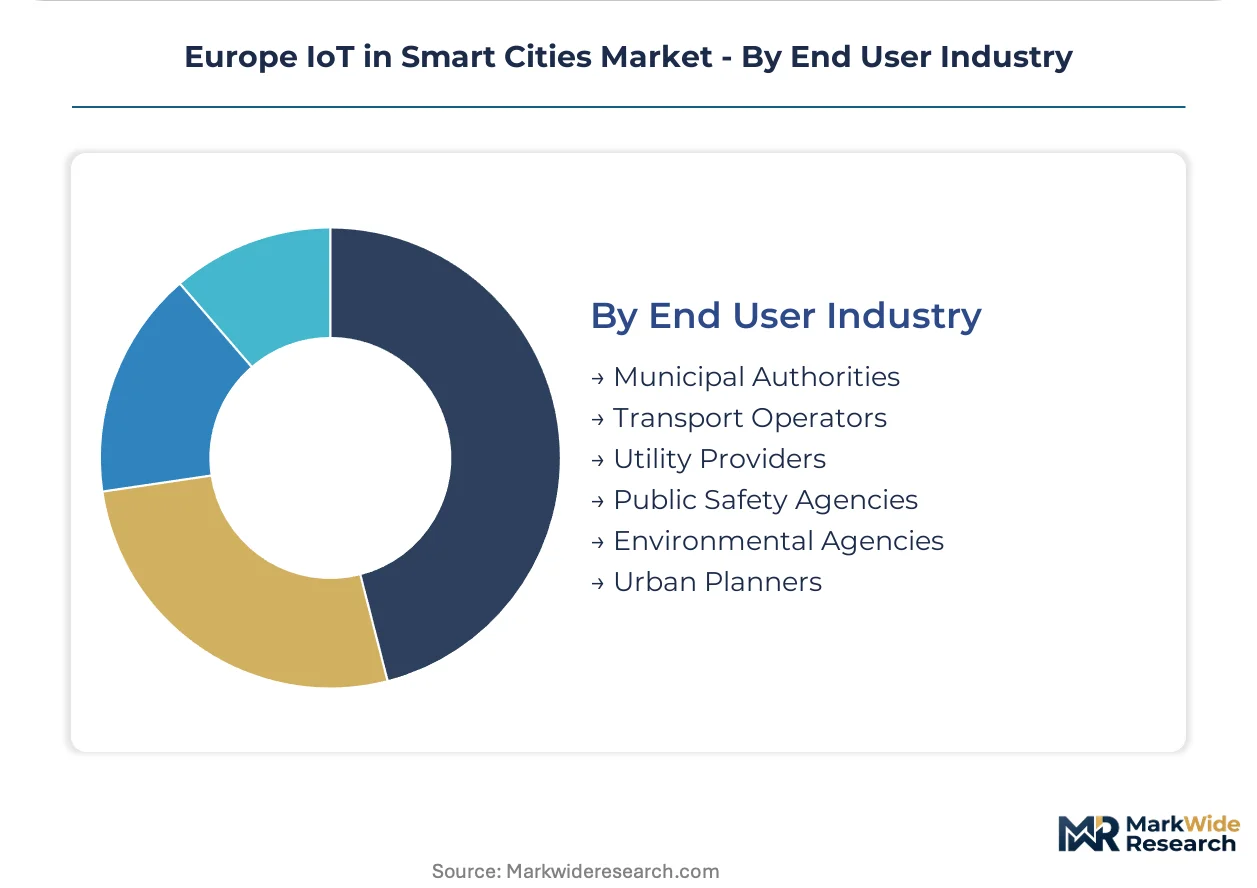
| Segmentation | Solution Offering: Smart Lighting, Traffic Management, Waste Management, Environmental Monitoring, Public Safety, Energy Management Technology: LoRaWAN, NB-IoT, Zigbee, 5G, Wi-Fi 6, Bluetooth Low Energy Application Use Case: Smart Parking, Air Quality Monitoring, Water Management, Intelligent Transportation, Smart Metering, Citizen Engagement End User Industry: Municipal Authorities, Transport Operators, Utility Providers, Public Safety Agencies, Environmental Agencies, Urban Planners |
| Companies Covered | Nokia, Vodafone, Siemens, Orange, Deutsche Telekom, Schneider Electric, Ericsson, Bosch, ABB, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe IoT in Smart Cities Market Strategic Shifts & Innovations
A fundamental shift is occurring from siloed, single-purpose sensor deployments toward integrated, platform-driven ecosystems. This evolution is driven by technological advancements in distributed computing and a regulatory environment that increasingly prioritizes data privacy and algorithmic transparency.
Edge computing hardware processes data locally on or near the sensor, which reduces network latency and data backhaul costs. Municipal authorities are adopting edge devices for real-time applications such as intelligent traffic management and automated public safety alerts. This move toward distributed intelligence is decomposing the traditional, centralized cloud-only data processing model for smart city architectures.
The EU AI Act establishes a risk-based framework for regulating artificial intelligence systems used within the single market. This legislation imposes stringent transparency and conformity assessment requirements on high-risk applications, including AI used in critical infrastructure management and law enforcement. System providers for intelligent transportation are most affected, now re-architecting algorithms for compliance and explainability.
Municipalities are increasingly adopting subscription-based service models instead of making large upfront capital expenditures for hardware. This trend displaces traditional one-time equipment sales with long-term "Smart City-as-a-Service" contracts that bundle hardware, connectivity, software, and ongoing maintenance. This procurement shift is most evident in German and French cities for services like smart street lighting and environmental monitoring.
Europe IoT in Smart Cities Market Segmentation
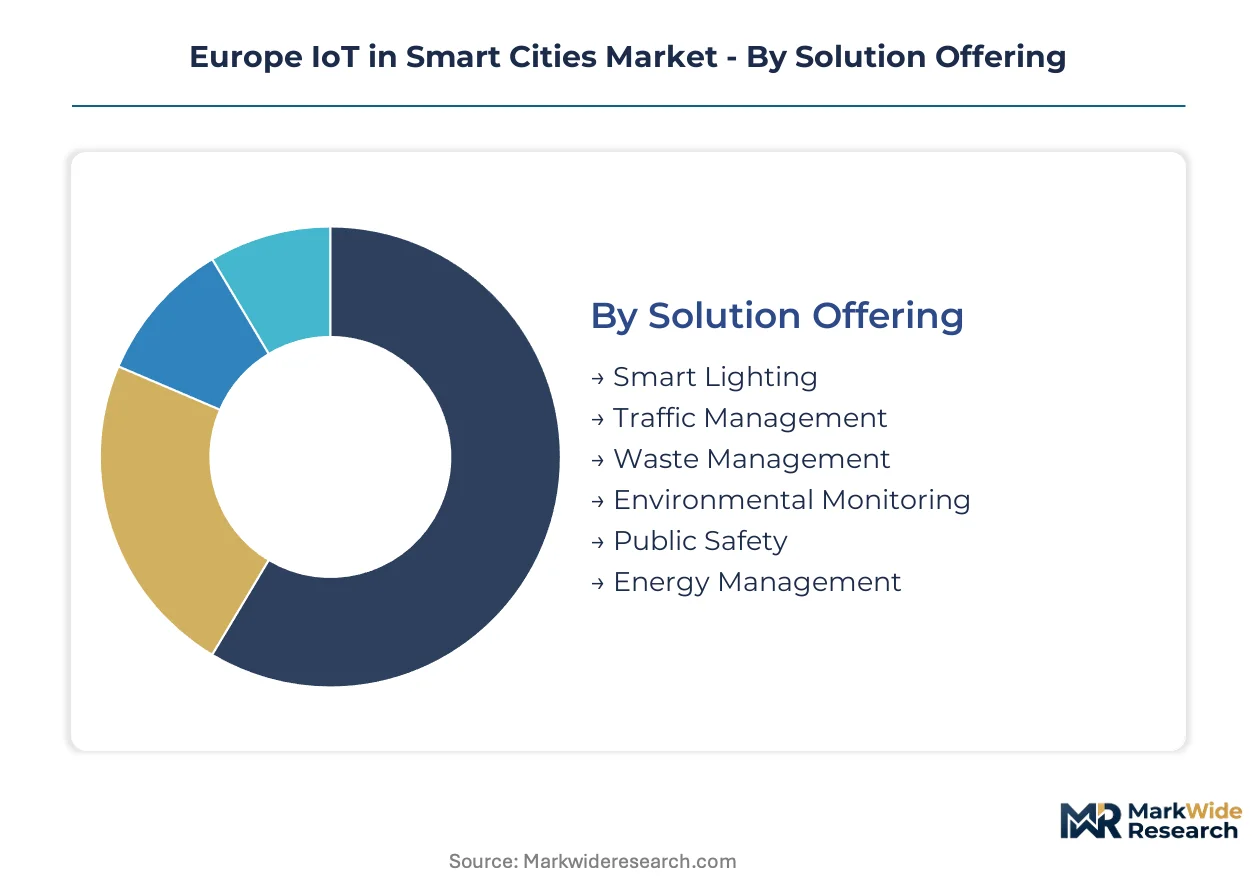
Understanding the segmentation within the Europe IoT in Smart Cities market is crucial for identifying where investment is concentrated and how different solutions and technologies are being deployed across the continent. This analysis highlights the specific areas of innovation and demand within urban environments.
Solution Offering:
The deployment of IoT solutions across Europe's smart cities often flows through a mix of direct municipal procurement and public-private partnerships, influencing the uptake of various offerings.
- Traffic Management:Traffic management systems integrate sensors, cameras, and data analytics to optimize urban mobility and reduce congestion in European metropolitan areas. Demand is concentrating in major German and French cities, driven by the imperative to improve transit efficiency and air quality.
- Energy Management:Energy management solutions leverage IoT sensors for real-time monitoring and control of public energy consumption, including smart grids and building automation. Municipal authorities across Europe are investing in these solutions to meet EU Green Deal mandates and reduce operational costs.
- Smart Lighting:Smart lighting systems incorporate IoT for adaptive street illumination, optimizing energy use and reducing maintenance costs across European cities.
- Waste Management:IoT-enabled waste management optimizes collection routes and schedules through sensor-equipped bins, enhancing urban cleanliness and resource efficiency.
- Environmental Monitoring:Environmental monitoring deploys sensor networks to track air quality, noise levels, and water parameters, supporting public health initiatives in European urban centers.
- Public Safety:Public safety solutions utilize connected devices for surveillance, emergency response coordination, and infrastructure monitoring to enhance urban security.
By volume, Traffic Management solutions lead deployments. By growth pace, Energy Management is ahead, driven by sustainability mandates.
Technology:
The underlying communication technologies determine the range, power consumption, and data throughput capabilities essential for diverse smart city applications.
- 5G:5G technology provides ultra-low latency and high-bandwidth connectivity, essential for real-time applications like autonomous vehicles and high-definition public safety video. This technology represents the fastest-growing segment for high-bandwidth applications across European urban infrastructure.
- LoRaWAN:LoRaWAN is a low-power wide-area network protocol designed for long-range, low-data-rate communication, ideal for battery-operated sensors. Its cost-effectiveness and widespread availability enable large-scale deployments for environmental monitoring and smart metering in European cities.
- NB-IoT:NB-IoT offers robust connectivity for low-power devices requiring deeper indoor penetration, supporting applications like smart utilities in Europe.
- Zigbee:Zigbee provides short-range, low-power mesh networking, commonly used for smart home devices and building automation within localized urban environments.
- Wi-Fi 6:Wi-Fi 6 delivers high-speed, high-capacity local wireless connectivity, crucial for public Wi-Fi hotspots and data-intensive applications in urban areas.
- Bluetooth Low Energy:Bluetooth Low Energy facilitates short-range wireless communication for asset tracking and proximity services, particularly in public transport and retail.
Adoption of LPWAN technologies like LoRaWAN and NB-IoT is widespread for foundational sensor networks, while 5G is gaining share for high-bandwidth critical services.
Application Use Case:
These application use cases directly translate IoT capabilities into tangible improvements for urban residents, enhancing daily life and public services.
- Intelligent Transportation:Intelligent Transportation Systems integrate real-time data from sensors and cameras to optimize traffic flow, public transit, and parking availability. Municipal authorities in European cities are making significant investments to alleviate congestion and improve multimodal transport efficiency.
- Smart Metering:Smart metering involves deploying connected devices to monitor utility consumption (electricity, water, gas) in real-time, enabling efficient billing and resource management. Utility providers across Europe are driving these deployments to achieve greater operational efficiency and support sustainability goals.
- Smart Parking:Smart parking systems use sensors to guide drivers to available spaces, reducing congestion and improving urban mobility in European centers.
- Air Quality Monitoring:Air quality monitoring networks collect hyperlocal pollution data, providing critical insights for public health authorities and environmental agencies.
- Water Management:IoT in water management optimizes distribution, detects leaks, and monitors water quality, ensuring sustainable resource use for urban populations.
- Citizen Engagement:Citizen engagement platforms leverage IoT data to provide real-time information and feedback channels, fostering transparency and participation in urban governance.
Intelligent Transportation and Smart Metering remain high-priority investments for European municipalities due to their direct operational and environmental benefits.
End User Industry:
The ultimate beneficiaries and decision-makers for smart city IoT deployments span various public sector entities, each with distinct operational needs and procurement processes.
- Municipal Authorities:Municipal authorities act as the primary drivers and integrators of smart city initiatives, overseeing urban planning, public services, and infrastructure development. These entities command significant investment for traffic management and energy management solutions across German and French metropolitan areas.
- Utility Providers:Utility providers manage critical infrastructure for electricity, water, and gas, deploying IoT for smart grids, leak detection, and consumption monitoring. These providers are crucial for implementing smart metering and energy management solutions to enhance efficiency and meet regulatory mandates in Europe.
- Transport Operators:Transport operators use IoT for real-time fleet management, route optimization, and passenger information systems to enhance urban mobility.
- Public Safety Agencies:Public safety agencies leverage IoT for surveillance, emergency response, and crime prevention, improving urban security and citizen well-being.
- Environmental Agencies:Environmental agencies deploy IoT for air and water quality monitoring, supporting regulatory compliance and public health initiatives across Europe.
- Urban Planners:Urban planners utilize IoT data for predictive analysis and dynamic modeling, informing sustainable development and infrastructure decisions for future cities.
Effective smart city implementation increasingly relies on collaboration between municipal authorities and specialized utility providers to deliver integrated solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the European IoT in smart cities market shows a distinct asymmetry, with established Western European economies like Germany commanding premium solutions, while Eastern European nations prioritize cost-effectiveness for foundational deployments. This dynamic influences procurement strategies and solution complexity across the continent.
Germany
German metropolitan areas drive significant demand for advanced environmental monitoring and energy management solutions. The EU Green Deal mandates compel municipalities to invest heavily in sustainable urban infrastructure and carbon neutrality initiatives. Cities like Berlin and Hamburg are actively implementing integrated smart city platforms, focusing on smart grids and intelligent building management for resource optimization.
France
French cities prioritize intelligent transportation systems and public safety applications. The upcoming EU AI Act establishes stringent compliance frameworks for algorithmic decision-making in public services, impacting new deployments. Paris and Lyon are key centers for piloting autonomous vehicle infrastructure and advanced traffic management solutions.
Netherlands
Dutch cities focus on water management and smart port logistics, driven by unique geographical challenges. National sustainability goals encourage the deployment of sensor networks for flood prediction and resource efficiency. Amsterdam and Rotterdam are pioneering integrated urban data platforms that combine IoT with digital twin technologies.
Sweden
Swedish municipalities prioritize public health initiatives through air quality monitoring and waste management optimization. Strict GDPR regulations shape data governance protocols for all citizen-facing smart city applications. Stockholm and Malmö are developing advanced citizen engagement platforms, emphasizing transparency and data privacy in urban services.
Poland
Polish cities exhibit growing demand for public safety solutions and traffic optimization technologies. EU cohesion funds support digital transformation initiatives, enabling significant investment in smart infrastructure. Warsaw and Krakow are actively deploying foundational smart city systems, including smart lighting and waste management solutions.
Europe IoT in Smart Cities Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the European IoT in smart cities market. The landscape exhibits a tiered structure, with large telecommunication providers and established industrial engineering firms at the top, alongside numerous niche software and integration specialists. Dominant competitive moves include strategic partnerships to bundle services and continuous portfolio diversification into new urban applications.
Large telecommunication providers like Vodafone exemplify the infrastructure-centric archetype, leveraging their expansive 5G and NB-IoT network capabilities across the continent. Siemens, a German industrial engineering firm, represents the deep industrial expertise archetype, focusing on complex energy management and smart grid projects. Schneider Electric occupies a position as a specialist in integrated smart building and grid management platforms for urban districts.
| Leading Market Players |
|---|
| Nokia |
| Vodafone |
| Siemens |
| Orange |
| Deutsche Telekom |
| Schneider Electric |
| Ericsson |
| Bosch |
| ABB |
| Others |
Cost & Logistics Intelligence
Extended lead times for specialized IoT sensors directly influence the pricing power of component manufacturers and shape the overall supply chain for European smart city deployments. This dynamic extends to system integrators, who must balance component availability with project delivery timelines.
Pricing Analysis
Pricing power for smart city IoT solutions varies significantly across European regions. Project-based contracts dominate for large infrastructure deployments, while subscription-based "Smart City-as-a-Service" models gain traction for ongoing environmental monitoring. Customization level for urban planning and after-sales service for ongoing maintenance are key price differentiation drivers. Regulatory compliance burden from GDPR and the EU AI Act increases development costs, leading to upward pressure on prices for compliant solutions. Municipal authorities in Eastern Europe are most price-sensitive, while German metropolitan areas prioritize advanced functionality.
Supply Chain Analysis
Inventory levels for specialized IoT hardware are influenced by global chip availability and localized demand spikes. Germany, France, and the Netherlands are key manufacturing hubs for advanced IoT components and system integration within Europe. Microcontrollers, communication modules (NB-IoT/LoRaWAN), and secure data processing units are critical inputs. Regulatory restrictions on data sovereignty within the EU pose a structural risk for cross-border data platform providers. Distribution runs through a network of specialized system integrators and telecommunication providers directly to municipal clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe IoT in smart cities market represents a significant service-attach opportunity, with recurring revenue from data analytics platforms expanding faster than initial hardware sales. This shift favors long-term engagement and value creation.
For Market Incumbents: Compound existing network infrastructure advantages by integrating advanced AI-driven analytics capabilities to counter emerging specialized software providers. Acquire niche AI software firms to enhance platform intelligence and standardize on secure, open data platforms for diverse sensor data integration. Talent scarcity for integration and fragmented regulatory landscapes (EU AI Act) pose a threat. R&D into explainable AI for public safety applications represents a critical lever.
For New Entrants and Emerging Players: Lead with specialized, outcome-based solutions targeting underpenetrated municipal services in Eastern European cities. Public health monitoring (air quality) and smart waste management in cities like Warsaw offer white-space targets. Small-to-medium municipalities seeking cost-effective, easily deployable solutions represent the most penetrable segment. Offer "Smart City-as-a-Service" models with minimal upfront capital outlay as a key go-to-market angle.
For Investors and Strategic Acquirers: Long-term, this sits as a digital infrastructure upgrade play because urban environments continuously demand efficiency and sustainability improvements. Target vertically integrated software and platform providers with strong data governance expertise. Rapid adoption of digital twin technologies by major European municipalities serves as a key signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Strategic Partnership | Integrates specialized IoT hardware with comprehensive software platforms, enhancing solution breadth for municipal clients. |
| Platform Integration | Unifies disparate urban data sources into a single, actionable dashboard, improving operational efficiency for city managers. |
| Talent Acquisition | Secures critical expertise in AI, cybersecurity, and systems integration, addressing industry-wide skill shortages. |
| Geographic Expansion | Targets underpenetrated Eastern European markets, leveraging proven solutions from Western European deployments. |
| Regulatory Compliance Investment | Ensures adherence to GDPR and EU AI Act, building public trust and enabling broader citizen-facing application rollouts. |
Research Approach
A standing panel of smart city administrators, IoT solution architects, data privacy officers, and telecommunication infrastructure leads provided ongoing calibration for primary insights. This included in-depth interviews combined with validation against secondary sources like EU policy documents, national statistical office reports, and industry association publications. Bottom-up data aggregation from specific project deployments was triangulated with top-down market sizing estimates.
Outputs were consistently validated against external benchmarks from leading technology analysts and European municipal investment reports over the projection horizon. The analytical framework modeled market dynamics across solution offerings, technology types, application use cases, and end-user industries. Compound annual growth rates were derived from historical data trends and projected adoption curves. Key forecast inputs included public infrastructure spending and regulatory compliance timelines for the EU AI Act.
The analysis sits within stated boundaries; outcomes outside significant shifts in EU regulatory enforcement or major technological breakthroughs would require recalibration. Forecasts reflect assumptions on current investment patterns and technology maturation. Geopolitical instability in Eastern Europe and unforeseen economic downturns represent specific risk factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Global IoT Connectivity Market
Internet of Things (IoT)
Global IOT Connectivity Management Platform (CMP) Market
Internet of Things (IoT)
IoT Development Kit Market
Internet of Things (IoT)
Telecom Internet of Things (IoT) Market
Internet of Things (IoT)
IoT in Automotive Market
Internet of Things (IoT)
Global IoT Solutions and Services Market
Internet of Things (IoT)
Cellular IoT Module Market
Internet of Things (IoT)
Smart Connected Device Market
Internet of Things (IoT)
Global IoT Elevators Market
Internet of Things (IoT)
Intelligent IoT Market
Internet of Things (IoT)
Healthcare M2M Market
Internet of Things (IoT)
Wireless Connected Devices Market
Internet of Things (IoT)
IoT for Cold Chain Monitoring Market
Internet of Things (IoT)
North America Narrowband-Internet of Things (NB-IoT) Market
Internet of Things (IoT)
IoT in Retail Market
Internet of Things (IoT)
Internet of Things (IoT) in Healthcare Market