
 Industrial Cyclohexylamine Market | 2026-2036
Industrial Cyclohexylamine Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Cyclohexylamine Market Intelligence
Pharmaceutical-grade cyclohexylamine is bifurcating the competitive landscape as purity thresholds tighten across regulated end uses. BASF SE leverages integrated amine production networks to sustain cost discipline in European supply chains. Sinopec Nanjing Chemical Industries Co., Ltd. anchors volume throughput through captive feedstock access at its Yangtze River complex. Alkyl Amines Chemicals Ltd differentiates via specialized logistics for Indian pharmaceutical contract manufacturers.
Industrial cyclohexylamine is a secondary aliphatic amine produced through catalytic hydrogenation of aniline, typically supplied at purities ranging from 98.5% to 99.9% depending on end-use requirements, functioning primarily as a corrosion inhibitor, rubber accelerator, and intermediate in pharmaceutical and agrochemical synthesis. Industrial grade formulations dominate volume throughput in rubber processing and boiler water treatment, while pharmaceutical grade commands margin concentration due to stringent impurity profiling demanded by drug master file submissions. Chemical synthesis applications absorb the largest share of offtake, though agriculture-directed demand for pesticide intermediates exhibits the fastest structural expansion as growers adopt systemic fungicide programs.
EPA effluent limitation guidelines and OSHA permissible exposure limits shape product formulation standards and handling infrastructure investments across US manufacturing facilities. REACH registration requirements and ECHA substance evaluation protocols govern market access for European suppliers, while China's MEE emission standards tighten production licensing for domestic hydrogenation operations. Stakeholders must monitor evolving pharmaceutical-grade certification requirements as regulatory divergence between FDA drug master file expectations and EMA active substance master file protocols intensifies supply chain qualification burdens.
Market Dynamics
Pharmaceutical-grade purity thresholds are bifurcating the industrial cyclohexylamine value chain, forcing capital reallocation toward dedicated hydrogenation trains and impurity profiling infrastructure as regulatory divergence between FDA and EMA protocols intensifies.
Growth Catalysts
- EPA Effluent Limitation Guidelines:Tightening discharge standards for boiler water treatment chemicals drive replacement cycles in US power generation and manufacturing facilities, expanding corrosion inhibitor offtake.
- Systemic Fungicide Adoption:Agricultural growers in Brazil and India pivot toward systemic crop protection programs, accelerating demand for cyclohexylamine-derived pesticide intermediates.
- Yangtze River Chemical Cluster:Captive aniline feedstock access at integrated Chinese petrochemical complexes sustains cost-competitive hydrogenation capacity serving Asian rubber processing markets.
Market Restraints
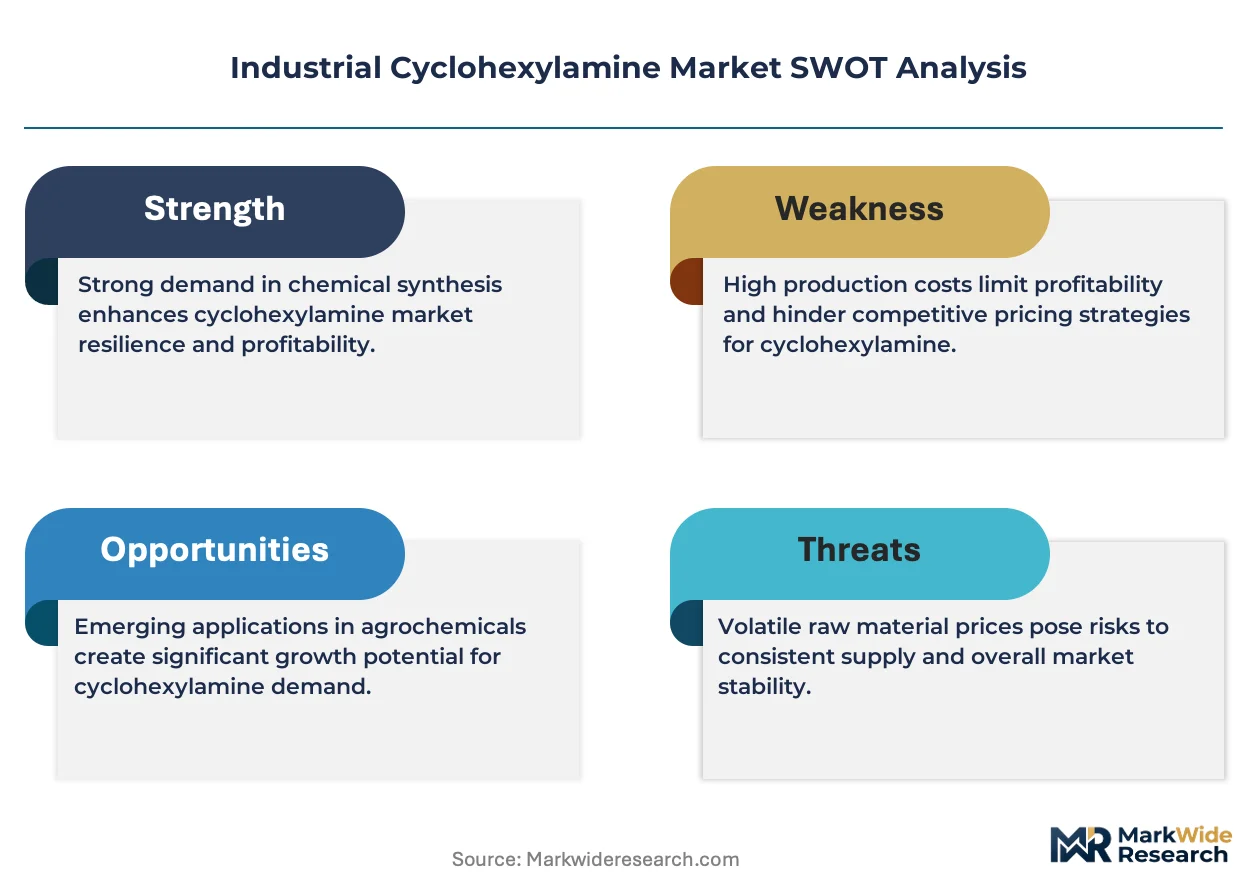
- Aniline Feedstock Volatility:Benzene-nitrobenzene price swings transmit directly to cyclohexylamine production economics, compressing margin buffers for non-integrated manufacturers.
- REACH Registration Burden:ECHA substance evaluation protocols and extended safety data requirements impose fixed compliance costs that disproportionately constrain European specialty chemical entrants.
- Morpholine Substitution:Alternative amine corrosion inhibitors gain traction in closed-loop cooling systems where lower toxicity profiles satisfy occupational exposure limits.
Strategic Opportunities
- Indian Pharmaceutical Contract Manufacturing:CDMO expansion under the country's PLI scheme creates dedicated demand for pharmaceutical-grade amine intermediates with documented supply chain traceability.
- Green Hydrogen Integration:Renewable hydrogen feedstock substitution in catalytic hydrogenation operations aligns with EU Green Deal carbon intensity benchmarks for chemical production.
- Direct-to-Formulator Distribution:Bypassing traditional chemical distributor networks enables margin capture and technical service relationships with specialized agrochemical synthesis houses.
Industry Challenges
- Drug Master File Synchronization:Misalignment between FDA Type II DMF and EMA ASMF documentation requirements forces redundant stability studies and analytical method validation, extending qualification timelines for pharmaceutical-grade suppliers.
- Hydrogenation Train Retrofit Capital:Legacy fixed-bed catalytic reactors require substantial modification to achieve the impurity thresholds demanded by active pharmaceutical ingredient manufacturers, straining mid-cap balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Cyclohexylamine Market |
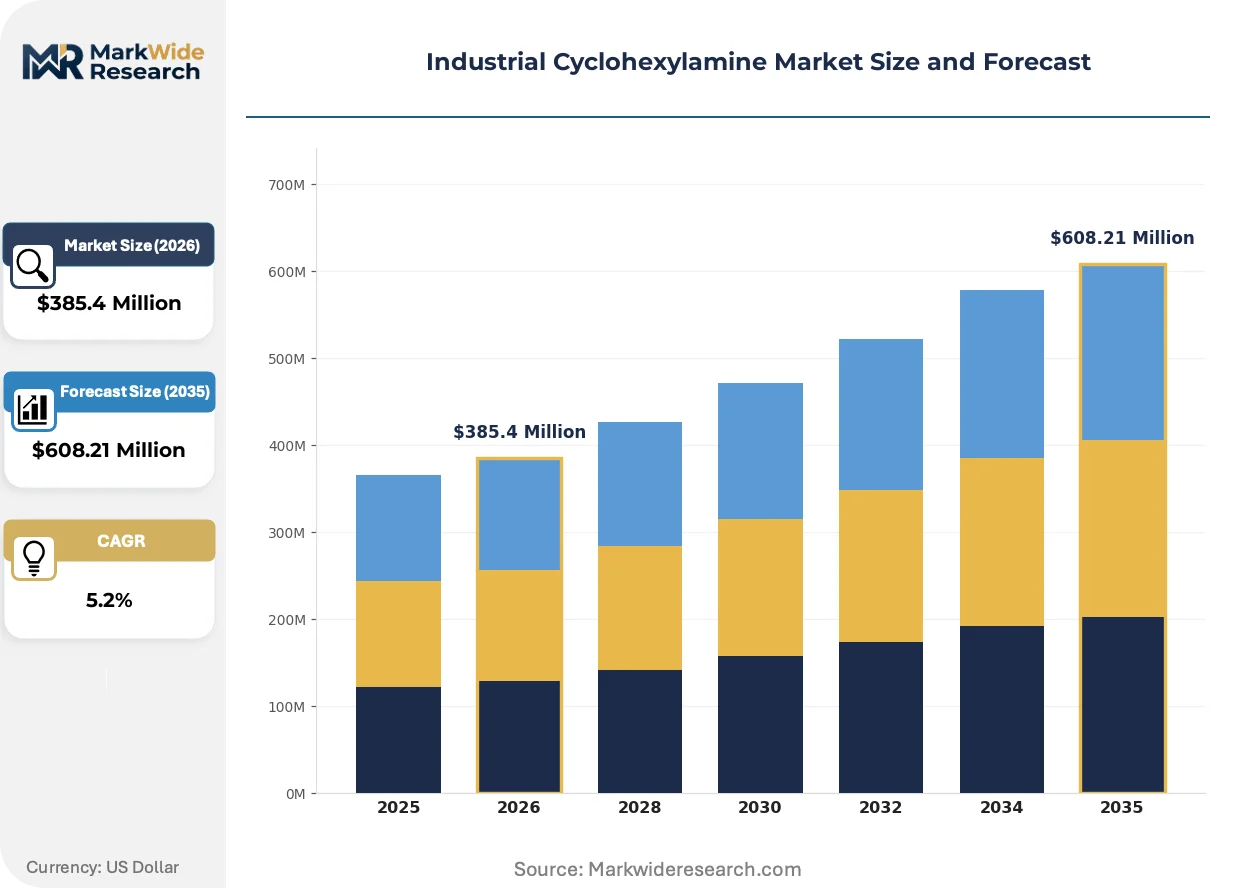
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $608.21 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Pharmaceutical Grade, Research Grade, Specialty Grade Application: Chemical Synthesis, Rubber Processing, Agriculture, Pharmaceuticals End User: Chemical Manufacturers, Pharmaceutical Companies, Agrochemical Firms, Research Institutions Delivery Mode: Bulk Supply, Packaged Supply, On-site Delivery, Custom Orders |
| Companies Covered | Alkyl Amines Chemicals Ltd, Sinopec Nanjing Chemical Industries Co., Ltd., BASF SE, Lanxess, Evonik Industries, Huntsman Corporation, Arkema Group, Shandong Yufeng Chemical Co., Ltd., Eastman Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Cyclohexylamine Market Strategic Shifts & Innovations
Continuous flow hydrogenation technology is compressing batch cycle times and impurity variance in cyclohexylamine production, while regulatory data integrity mandates and buyer consolidation in agrochemical formulators reshape competitive requirements.
Modular skid-mounted catalytic reactors are miniaturizing production footprints for pharmaceutical-grade cyclohexylamine. European fine chemical contractors adopt these systems to isolate dedicated trains from commodity operations. The technology is miniaturizing capital deployment thresholds, enabling regional suppliers to contest quality-sensitive segments without full-scale integrated complexes.
REACH registration dossier updates under ECHA substance evaluation protocols now mandate extended aquatic toxicity data for aliphatic amines. German and Dutch chemical manufacturers face reformulation deadlines for water treatment applications. Rubber accelerators directed toward tire production encounter the most intensive downstream disclosure obligations as automotive OEMs enforce supply chain transparency.
Agrochemical formulators in Brazil and India now specify certificate-of-analysis documentation with every lot, displacing spot-market spot-checking. Distributor relationships fragment as technical buyers demand direct supplier auditing and locked-in impurity specifications. The shift concentrates procurement authority among the largest systemic fungicide manufacturers, squeezing spot-market liquidity for standard-grade material.
Industrial Cyclohexylamine Market Segmentation
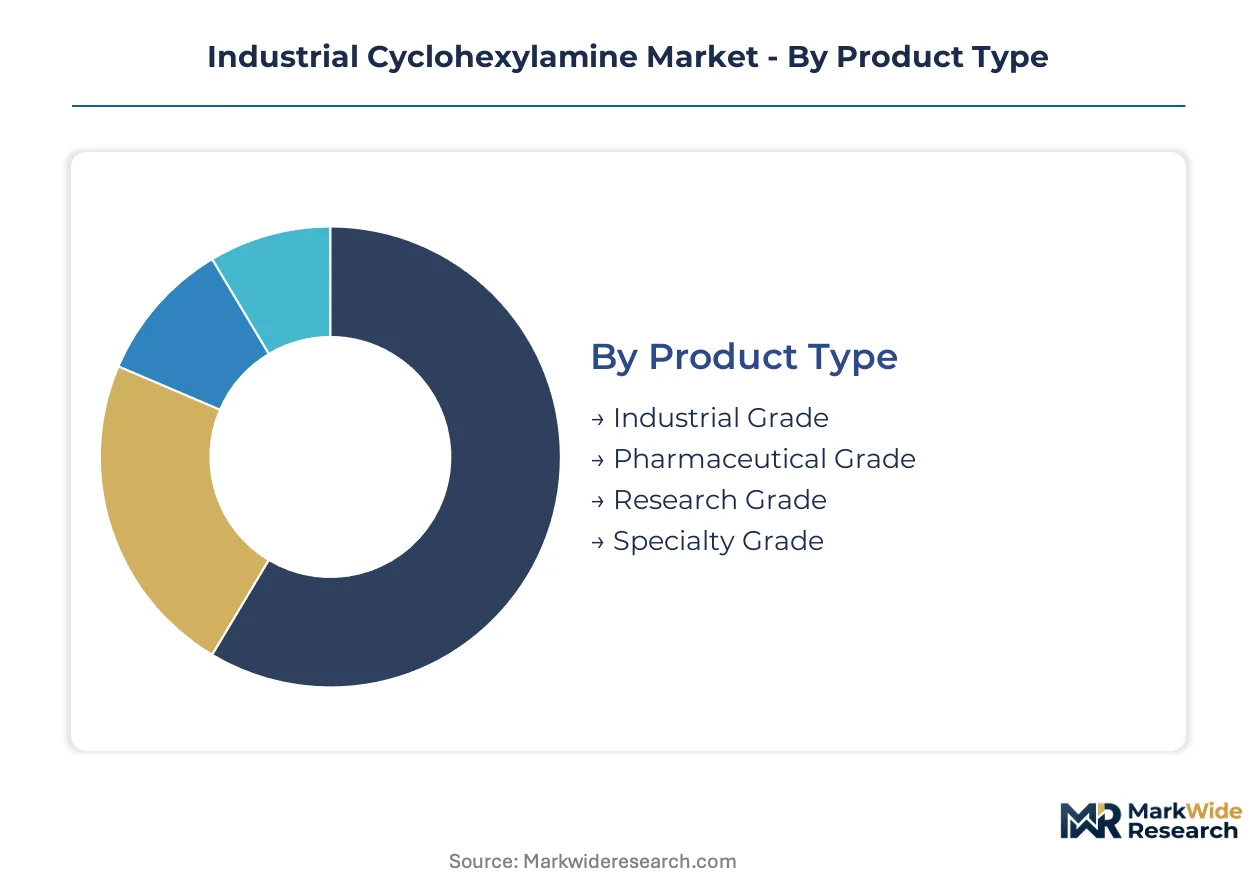
Industrial cyclohexylamine segments fracture along purity thresholds that determine regulatory qualification pathways and margin structures. Pharmaceutical-grade specifications impose analytical burdens that reshape production economics across each category.
Product Type:
EPA effluent guidelines and ECHA REACH protocols enforce divergent purity benchmarks that stratify manufacturing investment requirements across grades.
- Industrial Grade:Supplied at 98.5% to 99.5% purity, this grade absorbs volume throughput in boiler water treatment and rubber accelerator manufacturing where corrosion inhibition performance tolerates higher impurity ceilings. US power generation facilities under tightening EPA discharge standards drive replacement demand for industrial-grade corrosion inhibitor formulations.
- Pharmaceutical Grade:Meeting 99.9% purity with documented impurity profiling for drug master file submissions, this grade commands dedicated hydrogenation trains and certificate-of-analysis documentation per lot. CDMO expansion in India under the PLI scheme accelerates procurement of pharmaceutical-grade material with locked-in specifications.
- Research Grade:Small-batch production serving analytical laboratories and method development protocols.
- Specialty Grade:Custom-formulated variants for Germany's industrial chemical corridor with tailored handling specifications.
Established volume favors Industrial Grade; emerging adoption favors Pharmaceutical Grade.
Application:
Cost tier differentiation separates commodity-scale operations from margin-concentrated synthesis activities.
- Chemical Synthesis:The largest application by volume, absorbing cyclohexylamine as an intermediate in agrochemical and pharmaceutical active ingredient production. Systemic fungicide adoption in Brazil and India propels demand for pesticide intermediate synthesis.
- Rubber Processing:Functions as an accelerator in tire manufacturing and vulcanization processes. REACH registration dossier updates impose aquatic toxicity disclosure obligations on rubber accelerators directed toward automotive OEM supply chains.
- Agriculture:Expanding most quickly as growers pivot toward systemic crop protection programs requiring cyclohexylamine-derived intermediates.
- Pharmaceuticals:Active pharmaceutical ingredient manufacturing with FDA Type II DMF and EMA ASMF qualification requirements.
Margin concentration sits with Pharmaceuticals; volume throughput dominates Chemical Synthesis.
End User:
Customer type determines procurement authority and technical service intensity across the value chain.
- Chemical Manufacturers:Integrated hydrogenation operators and downstream formulators purchasing standard-grade material for corrosion inhibitor blending and intermediate production. Sinopec Nanjing Chemical Industries anchors volume throughput through captive aniline feedstock access.
- Pharmaceutical Companies:Active pharmaceutical ingredient manufacturers and CDMOs demanding pharmaceutical-grade material with supply chain traceability. Direct-to-formulator distribution bypasses traditional chemical distributor networks for this segment.
- Agrochemical Firms:Systemic fungicide formulators in Brazil and India specifying certificate-of-analysis documentation with every lot.
- Research Institutions:Academic and government laboratories requiring research-grade material in small quantities.
Procurement consolidation favors Pharmaceutical Companies; spot-market liquidity persists for Chemical Manufacturers.
Delivery Mode:
Supply concentration patterns dictate logistics infrastructure requirements and working capital intensity.
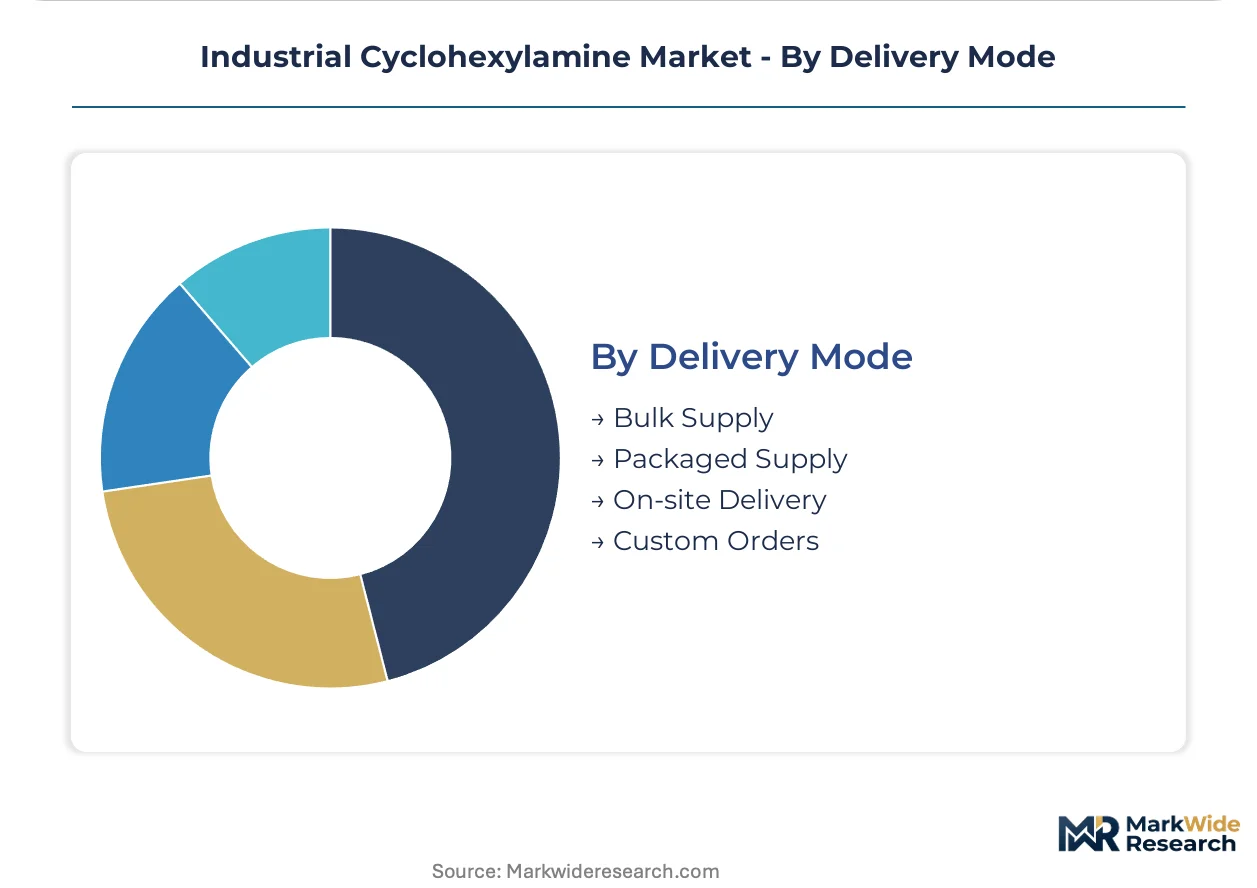
- Bulk Supply:Tanker and railcar delivery to integrated chemical complexes and large-scale rubber processing facilities. The Yangtze River chemical cluster sustains cost-competitive bulk supply through captive feedstock integration.
- Packaged Supply:Drum and tote configurations for mid-scale chemical manufacturers and agrochemical formulators. Alkyl Amines Chemicals Ltd differentiates via specialized logistics for Indian pharmaceutical contract manufacturers.
- On-site Delivery:Dedicated pipeline or tank farm arrangements for continuous process industries with steady consumption profiles.
- Custom Orders:Tailored packaging, labeling, and documentation for qualified pharmaceutical and research applications.
Volume scale favors Bulk Supply; margin capture favors Custom Orders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated petrochemical corridors in China and Germany anchor cyclohexylamine supply capacity, while regulatory divergence between FDA and EMA protocols fragments pharmaceutical-grade qualification pathways across manufacturing geographies.
China
Sinopec Nanjing Chemical Industries leverages captive aniline feedstock at its Yangtze River complex to sustain cost-competitive hydrogenation throughput for Asian rubber processing markets. MEE emission standards tighten production licensing for domestic hydrogenation operations, forcing facility upgrades. The Yangtze River Delta chemical cluster concentrates specialty-grade capacity serving pharmaceutical contract manufacturers.
Germany
BASF SE anchors European supply through integrated amine production networks spanning Ludwigshafen and Leverkusen sites. REACH registration dossier updates under ECHA substance evaluation protocols mandate extended aquatic toxicity data for aliphatic amines. The industrial chemical corridor between North Rhine-Westphalia and Hesse hosts dedicated hydrogenation trains for pharmaceutical-grade formulations.
United States
Eastman Chemical Company and Huntsman Corporation serve corrosion inhibitor demand from power generation facilities under tightening EPA effluent limitation guidelines. OSHA permissible exposure limits shape product formulation standards and handling infrastructure investments across US manufacturing facilities. The Gulf Coast petrochemical corridor maintains bulk supply infrastructure for boiler water treatment applications.
India
Alkyl Amines Chemicals Ltd differentiates via specialized logistics for pharmaceutical contract manufacturers operating under the country's PLI scheme. CDSCO pharmaceutical-grade certification requirements intensify supply chain qualification burdens for active pharmaceutical ingredient manufacturers. Maharashtra and Gujarat industrial zones concentrate agrochemical formulator demand for systemic fungicide intermediates.
Brazil
Systemic fungicide adoption among agricultural growers accelerates demand for cyclohexylamine-derived pesticide intermediates. ANVISA import regulations govern active substance master file protocols for pharmaceutical applications. São Paulo state anchors agrochemical formulation capacity serving Latin American crop protection markets.
Industrial Cyclohexylamine Market Key Industry Players
Concentration sits with integrated petrochemical conglomerates possessing captive aniline feedstock access and dedicated pharmaceutical-grade hydrogenation infrastructure. The competitive structure stratifies across three archetypes: multinational chemical conglomerates with integrated amine platforms, regional specialists leveraging geographic proximity to end-use markets, and contract manufacturers serving pharmaceutical qualification requirements. Capacity expansion and strategic partnerships dominate competitive moves, with players prioritizing backward integration into nitrobenzene-aniline value chains and technology licensing for continuous flow hydrogenation systems.
Among multinational chemical conglomerates, BASF SE exemplifies the integrated amine production archetype through its European network spanning feedstock through formulated derivatives. Sinopec Nanjing Chemical Industries Co., Ltd. represents the captive feedstock model, anchoring volume throughput through Yangtze River complex integration. Alkyl Amines Chemicals Ltd occupies a position within the regional specialist tier, differentiating via logistics infrastructure tailored to Indian pharmaceutical contract manufacturing demand.
| Leading Market Players |
|---|
| Alkyl Amines Chemicals Ltd |
| Sinopec Nanjing Chemical Industries Co., Ltd. |
| BASF SE |
| Lanxess |
| Evonik Industries |
| Huntsman Corporation |
| Arkema Group |
| Shandong Yufeng Chemical Co., Ltd. |
| Eastman Chemical Company |
| Others |
Cost & Logistics Intelligence
Sixty-day inventory cycles at European pharmaceutical-grade hydrogenation facilities compress working capital exposure while amplifying price premiums for certificate-of-analysis documentation. This lead-time discipline concentrates procurement authority among CDMOs with locked-in specifications, forcing spot-market buyers to absorb volatility from aniline feedstock swings.
Pricing Analysis
REACH registration dossier updates dictate the pricing tier structure across pharmaceutical, industrial, and research grades. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade material with drug master file documentation from industrial-grade corrosion inhibitor formulations. Price differentiation stems from impurity profiling burden and captive aniline integration. Cost compression in standard-grade material is intensifying because Brazilian agrochemical formulators now demand per-lot certificates previously reserved for pharmaceutical buyers. Rubber processing facilities demonstrate highest price sensitivity; pharmaceutical CDMOs exhibit lowest sensitivity due to qualification lock-in costs.
Supply Chain Analysis
Strategic stockpiling of aniline feedstock dominates inventory strategy among non-integrated hydrogenation operators facing benzene-nitrobenzene volatility. Supply concentrates in China, Germany, and India, with the Yangtze River Delta and North Rhine-Westphalia corridors anchoring integrated capacity. Raw material dependencies center on aniline, hydrogen, and specialized nickel-based catalysts. Single-source vulnerability from concentrated aniline production in Chinese petrochemical complexes exposes downstream formulators to MEE emission standard enforcement disruptions. Distribution runs through bulk tanker and railcar networks for integrated chemical manufacturers, with specialized drum logistics serving Indian pharmaceutical contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory divergence between FDA and EMA pharmaceutical-grade protocols fragments qualification requirements, creating specialized niches for regional hydrogenation specialists with dedicated impurity profiling infrastructure.
For Market Incumbents: Secure captive aniline feedstock access through backward integration or long-term offtake agreements with nitrobenzene operators to defend margin buffers against benzene price volatility. Lock in pharmaceutical-grade certification investments ahead of evolving CDSCO and ANVISA master file synchronization requirements to preempt mid-cap competitors from qualifying for Indian and Brazilian CDMO procurement. For New Entrants and Emerging Players: Differentiate on continuous flow hydrogenation technology to compress batch cycle times and impurity variance for pharmaceutical-grade segments. Target modular skid-mounted reactor deployments in European fine chemical contracting corridors where legacy fixed-bed retrofits strain incumbent balance sheets. Pursue direct-to-formulator distribution relationships with Brazilian systemic fungicide manufacturers displacing traditional chemical distributor networks. For Investors and Strategic Acquirers: Long-term, this sits as a specialty chemical consolidation play because pharmaceutical-grade qualification barriers compound with regulatory divergence to entrench incumbent positions. Acquisition target archetype: mid-cap regional hydrogenation operators with existing impurity profiling infrastructure and untapped CDMO channel relationships. Signal to watch: ECHA substance evaluation protocol enforcement intensity against German and Dutch rubber accelerator manufacturers triggering forced reformulation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aniline Feedstock | Captive nitrobenzene-aniline supply shields margin buffers from benzene price volatility at Sinopec-scale complexes. |
| Continuous Flow Hydrogenation Technology Licensing | Modular skid-mounted reactors enable regional pharmaceutical-grade contestation without full-scale integrated petrochemical investments. |
| Pharmaceutical-Grade Certification Investment | FDA Type II DMF and EMA ASMF documentation lock-in creates multi-year procurement relationships with CDMO expansion under India's PLI scheme. |
| Direct-to-Formulator Distribution Buildout | Bypassing traditional chemical distributors captures margin and enables technical service relationships with Brazilian agrochemical synthesis houses. |
| Green Hydrogen Feedstock Substitution | Renewable hydrogen integration aligns catalytic hydrogenation operations with EU Green Deal carbon intensity benchmarks for chemical production. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across hydrogenation facility managers, pharmaceutical CDMO procurement leads, agrochemical formulator technical buyers, and specialty chemical distribution channel partners. Secondary validation drew from ECHA REACH registration dossiers, EPA effluent limitation guideline updates, CDSCO pharmaceutical-grade certification protocols, customs trade data for aniline-cyclohexylamine value chains, and SEC filings of integrated petrochemical conglomerates. Bottom-up volume estimates from hydrogenation capacity utilization were triangulated against top-down demand aggregation from end-use application consumption.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning purity grade tier, end-use industry application, delivery mode format, and regional production hub concentration. CAGRs were derived from trend extrapolation of hydrogenation capacity expansion announcements, regulatory compliance cost trajectories, and substitution elasticity estimates for morpholine corrosion inhibitors. Forecast inputs incorporated EPA discharge standard enforcement intensity, systemic fungicide adoption curves in Brazilian and Indian agriculture, and pharmaceutical contract manufacturing expansion under India's PLI scheme.
The analysis sits within stated boundaries; outcomes outside sustained aniline feedstock availability, stable regulatory divergence between FDA and EMA protocols, or continued CDMO procurement consolidation would require recalibration. Forecasts reflect documented assumptions regarding hydrogenation technology diffusion rates and regional emission standard enforcement intensity. Specific risk factors include REACH substance evaluation protocol acceleration, MEE production licensing restrictions in China, and morpholine substitution penetration in closed-loop cooling systems. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Rodenticides Market
Industrial Chemicals
US Anhydrous Hydrogen Fluoride Market
Industrial Chemicals
Mass Transfer Trays Market
Industrial Chemicals
Global Chemical Mechanical Planarization Market
Industrial Chemicals
Plant-Based Hydraulic Oil Market
Industrial Chemicals
Bleaching Clay Market
Industrial Chemicals
India Precipitated Silica Market
Industrial Chemicals
Mining Explosives Consumables Market
Industrial Chemicals
Global Flow Chemistry Market
Industrial Chemicals
Wire Compound and Cable Compound Market
Industrial Chemicals
Silicates Market
Industrial Chemicals
Pulp and Paper Enzymes Market
Industrial Chemicals
Permeate Market
Industrial Chemicals
Electroelutor Market
Industrial Chemicals
Emulsion Explosive Market
Industrial Chemicals
Ethoxy Propanol Market