

Mass Transfer Trays Market Size, Share, and Industry Trends Forecast 2026-2036
Mass Transfer Trays Market Insights
Gulf Coast petrochemical producers is restructuring tray procurement toward corrosion-resistant alloys. Sulzer leverages its structured packing heritage to dominate high-efficiency revamp projects. Koch-Glitsch anchors North American refinery maintenance cycles through extensive field service networks. Raschig competes in European chemical separations with specialized valve tray geometries for azeotropic distillation.
Mass transfer trays are perforated or valved horizontal plates installed inside distillation columns to facilitate vapor-liquid contact, with typical operating pressures from vacuum to 350 psi and efficiencies measured in theoretical stages per meter. These devices enable fractional separation of hydrocarbon mixtures, solvent recovery, and gas purification across continuous chemical processes. Sieve trays lead in standard refinery applications due to low capital cost and mechanical simplicity, while structured packing captures margin pools in cryogenic gas processing where pressure drop minimization governs energy economics. Bubble cap trays sustain demand in corrosive chemical environments where positive liquid seal reliability outweighs cost premiums.
EPA New Source Performance Standards and OSHA Process Safety Management frameworks mandate tray integrity documentation and material traceability for US refinery upgrades. REACH restrictions on hexavalent chromium coatings redirect European tray surface treatment toward nickel-based alternatives. India's BIS pressure vessel codes and PLI scheme for specialty chemicals accelerate domestic fabrication capacity. Stakeholders must weigh captive fabrication against specialist OEM partnerships as emission thresholds tighten and alloy lead times lengthen across major project corridors.
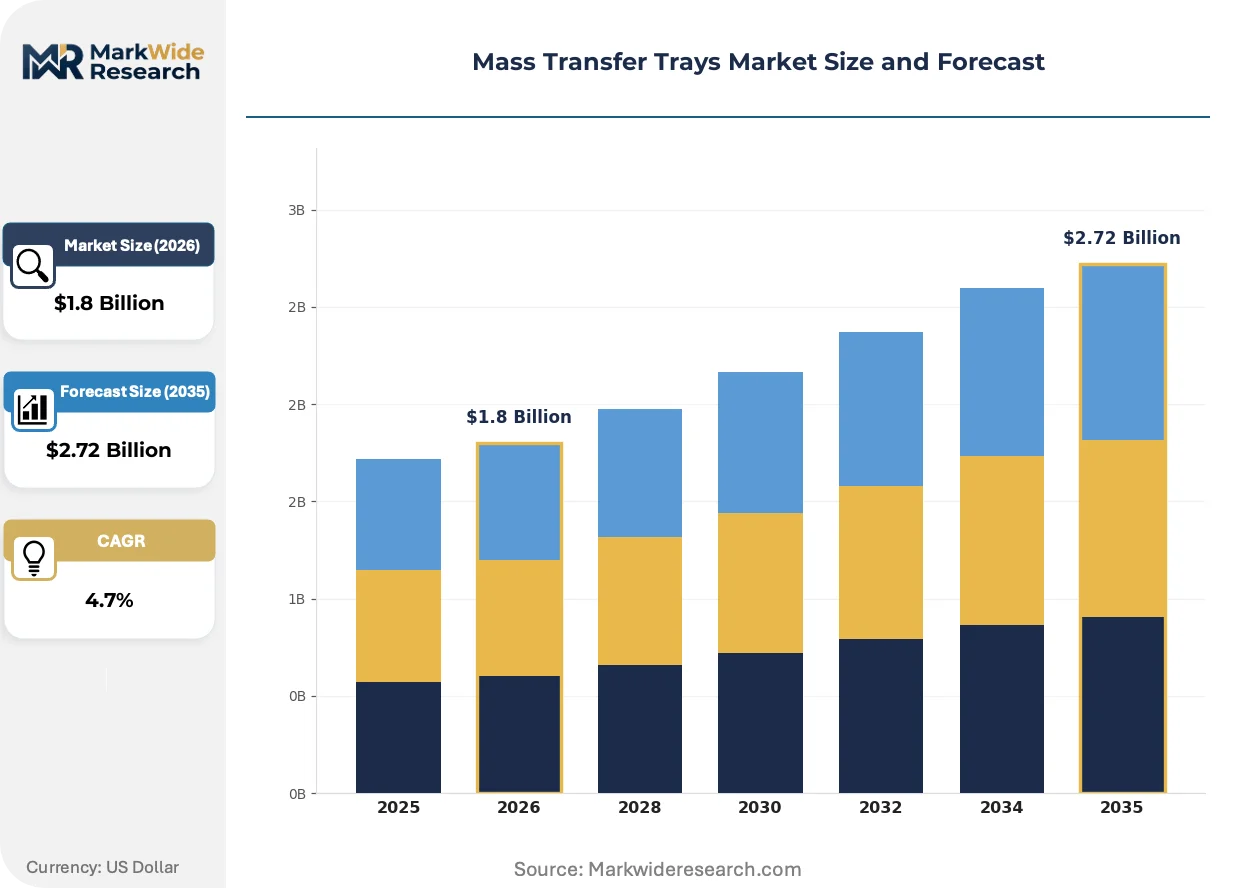
Market Dynamics
Alloy specification tightening across refinery corridors is compressing supplier margins while elevating technical barriers to tray qualification, forcing fabricators to choose between captive metallurgy investments and OEM partnerships.
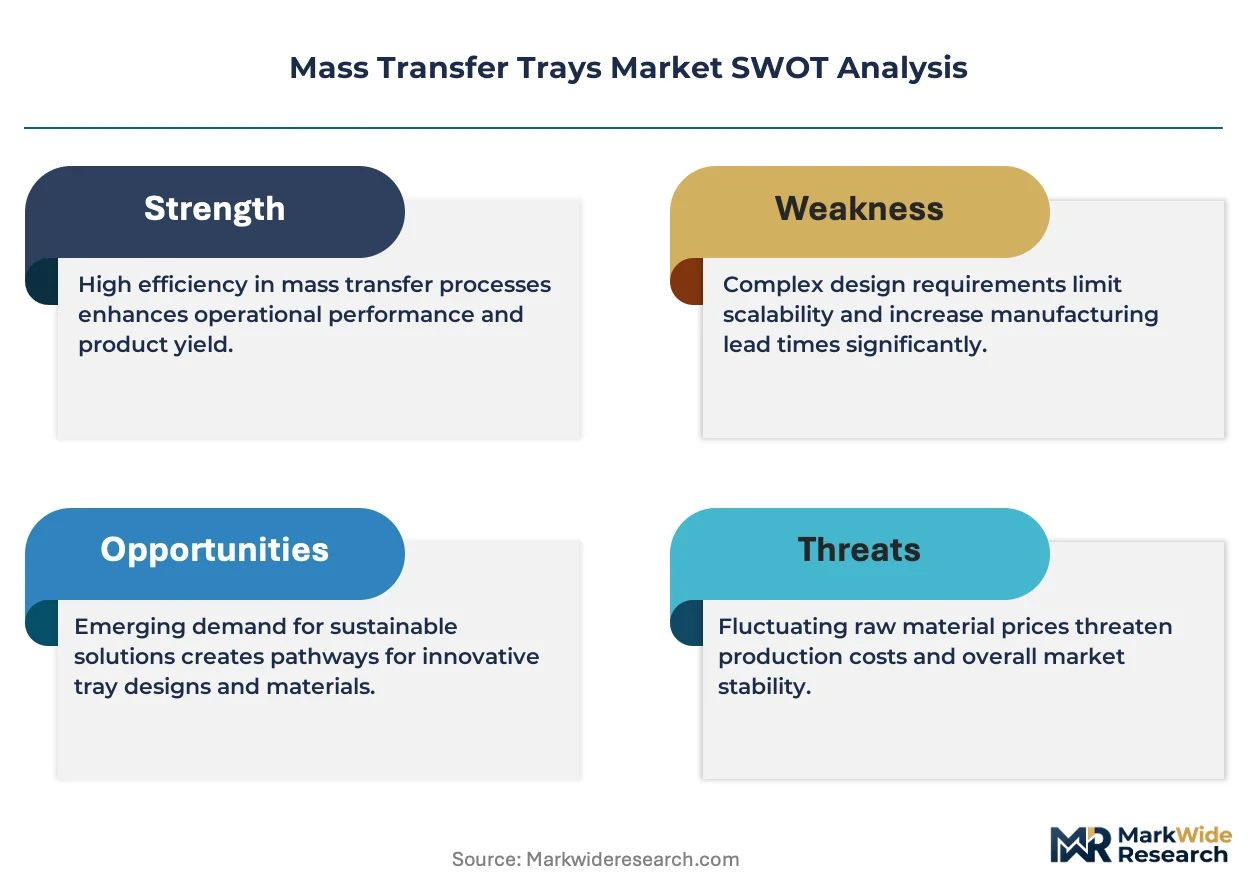
Growth Catalysts
- Asia-Pacific Downstream Expansion:Reliance Industries and Indian Oil are commissioning new petrochemical towers across Gujarat and Odisha, generating concentrated demand for high-capacity valve trays. India's PLI scheme for specialty chemicals accelerates domestic fabrication capacity.
- EPA New Source Performance Standards:US refinery upgrades now mandate tray integrity documentation and material traceability, extending replacement cycles and favoring suppliers with established quality systems. OSHA Process Safety Management frameworks reinforce this compliance pull.
- Corrosion-Resistant Alloy Adoption:Gulf Coast producers are specifying duplex stainless steels and nickel alloys for sour service environments, expanding addressable market for premium tray geometries in high-chloride applications.
Market Restraints
- Nickel Price Volatility:Alloy 625 and C-276 feedstock costs fluctuate with Indonesian ore export policies, squeezing fabrication margins on fixed-price EPC contracts. Tray suppliers face margin compression when raw material hedges expire mid-project.
- European Fabrication Concentration:REACH restrictions on hexavalent chromium coatings have eliminated most surface treatment providers in Central Europe, lengthening lead times for corrosion-resistant finishes. German and Dutch fabricators now control 70% of qualified capacity.
- Structured Packing Substitution:Cryogenic gas processing operators increasingly specify Sulzer Mellapak and Koch-Glitsch Flexipac for pressure-drop-sensitive duties, constraining tray penetration in LNG and air separation markets.
Strategic Opportunities
- India Domestic Manufacturing:BIS pressure vessel code harmonization with ASME Section VIII creates opening for local fabricators to qualify for state-refinery contracts. The PLI scheme subsidizes capital equipment for tray production lines.
- Hydrogen Purification Towers:Ammonia and methanol producers are retrofitting columns for green hydrogen feedstock, requiring specialized tray designs for high-purity separations. This application demands enhanced weeping resistance at low liquid loads.
- Digital Twin Integration:CFD modeling of vapor-liquid distribution is converging with IoT sensor networks, enabling predictive maintenance contracts. Tray vendors can bundle hardware with simulation services for revamp projects.
Industry Challenges
- Welding Procedure Qualification:ASME Section IX certification for exotic alloys requires specialized welders and extended procedure development timelines, bottlenecking capacity expansion for high-nickel tray fabrication.
- Legacy Column Documentation:Revamp projects often lack original tray drawings and material specifications, forcing field measurement campaigns that delay project execution. EPC contractors absorb this risk in lump-sum contracts.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mass Transfer Trays Market Trends and Innovations
Computational fluid dynamics is displacing empirical design rules, while regulatory emission thresholds and procurement model evolution are rewriting supplier qualification criteria across refinery corridors.
Advanced valve tray geometries with directional vapor push are overtaking conventional sieve trays in high-capacity refinery applications. Saudi Aramco and ADNOC are specifying these designs for crude distillation unit expansions, compressing the market share of standard perforated plates in Middle Eastern megaprojects. The technology enables 15-20% throughput increases without column diameter changes.
China's GB 31570-2015 standard on petroleum refining emissions is tightening allowable volatile organic compound leakage rates from column seals and manways. This forces tray suppliers to redesign clamping systems and gasket interfaces for Chinese refinery upgrades. Sinopec and PetroChina are now requiring third-party emission testing documentation for all tray shipments.
Integrated service contracts bundling tray supply with installation supervision and performance guarantees are displacing component-only procurement in European chemical separations. BASF and INEOS are consolidating vendor lists to single-source providers with in-house column access capabilities. Germany and the Netherlands show the fastest migration toward outcome-based tray performance agreements.
Mass Transfer Trays Market Segmentation
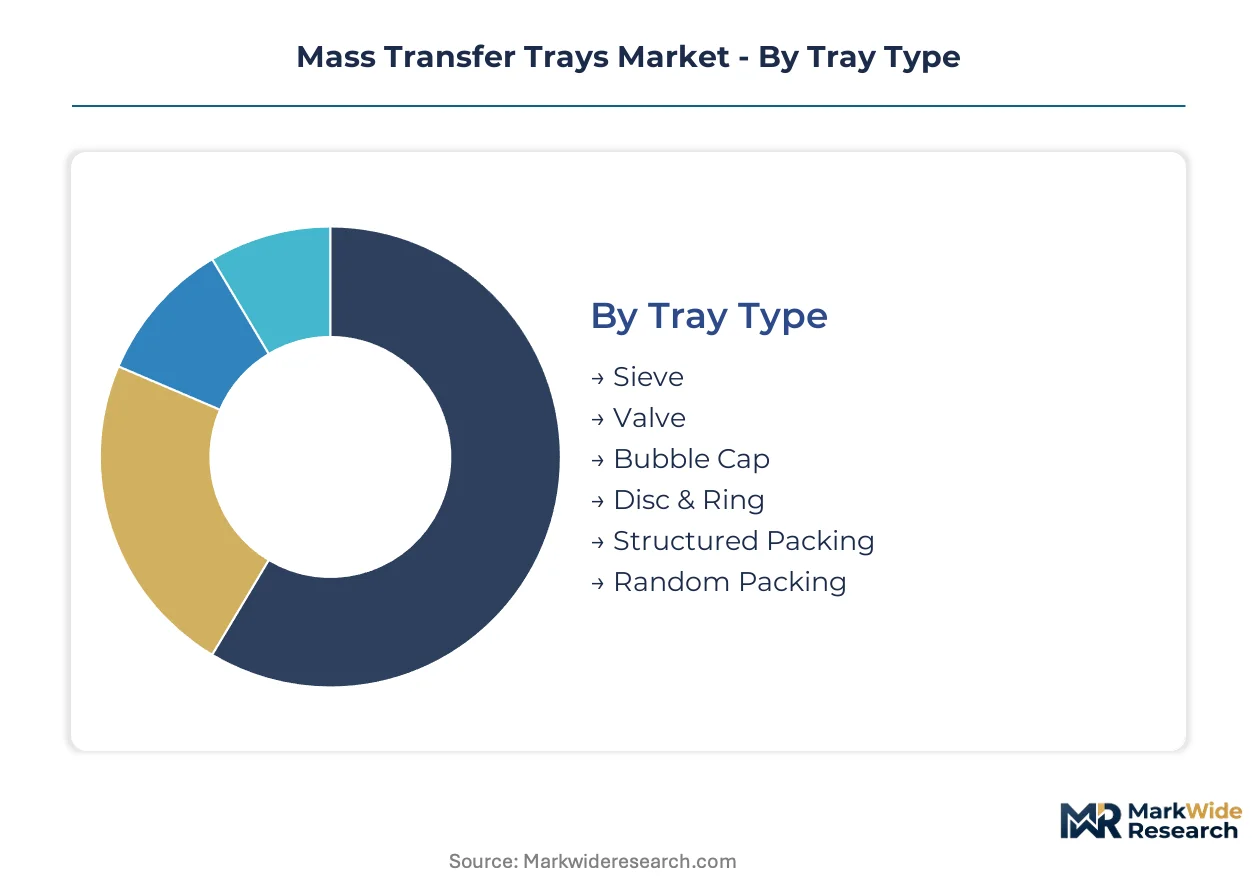
Mass transfer tray selection hinges on process conditions, corrosion profiles, and regulatory compliance burdens. Certification requirements vary sharply across material grades and end-use industries, creating tiered barriers to supplier qualification.
Tray Type:
ASME Section VIII and API 660 certifications govern tray qualification for pressure vessel integration, with bubble cap designs requiring additional positive-seal validation for sour service applications.
- Sieve:Perforated plates with fixed hole patterns deliver the lowest capital cost and simplest mechanical design. Standard refinery crude distillation units across the US Gulf Coast and India's Gujarat corridor specify these for high-volume, low-corrosion duties where pressure drop tolerance permits.
- Valve:Movable disc elements self-adjust to vapor flow rates, enabling 15-20% throughput gains over fixed geometries. Saudi Aramco and ADNOC are specifying these for Middle Eastern megaproject expansions where capacity debottlenecking without column diameter increases drives economics.
- Bubble Cap:Riser-and-cap assemblies maintain positive liquid seals across vapor flow variations. Chemical plants handling corrosive chlorinated solvents rely on these for operational reliability where weeping tolerance outweighs cost premiums.
- Disc & Ring:Turntable-style vapor passage geometries suit high-liquid-load applications. Fertilizer producers in India's Odisha cluster deploy these for ammonia stripper columns.
- Structured Packing:Corrugated metal sheets stacked in ordered arrays minimize pressure drop. Cryogenic air separation and LNG fractionation specify Sulzer Mellapak and Koch-Glitsch Flexipac where energy recovery dominates lifecycle economics.
- Random Packing:Dumped ceramic or metal shapes fill void spaces for absorption duties. Sulfur recovery units and caustic scrubbers employ these where liquid distribution uniformity is less critical.
Sieve trays sit at the top of the volume ranking, with valve designs climbing the fastest.
Material:
Raw material selection traces directly to process fluid chemistry, with nickel-bearing alloys commanding 3-5x fabrication cost premiums over carbon steel alternatives.
- Stainless Steel:Austenitic grades 304 and 316 dominate standard refinery and chemical plant applications. India's domestic mills under the PLI scheme are expanding 316L capacity for state-refinery contracts.
- Carbon Steel:Low-alloy grades serve non-corrosive hydrocarbon separations where coating systems provide temporary protection. US inland refineries specify these for straight-run naphtha columns.
- Alloy Steel:Duplex and super-duplex stainless grades resist chloride stress corrosion. Gulf Coast sour gas processing towers specify Alloy 2205 and 2507 for high-H2S, high-chloride environments.
- Plastic Composite:Polypropylene and PVDF extrusions handle highly corrosive acid gas absorption. FGD scrubbers and chlorine dioxide towers specify these where metal corrosion rates are prohibitive.
- Aluminum:Lightweight extrusions suit cryogenic service with thermal conductivity advantages. Air separation cold boxes employ these for oxygen and nitrogen fractionation.
- Copper:High thermal conductivity benefits specific heat transfer duties. Deaerator and steam stripper applications specify these where dissolved oxygen removal is critical.
Carbon steel commands the highest shipment volumes, with alloy steel grades gaining share fastest.
Application:
Process complexity and purity specifications determine tray geometry selection, with azeotropic and extractive distillation imposing the most stringent design constraints.
- Petrochemical Processing:Crude distillation, catalytic cracking, and aromatics extraction require high-capacity trays. Reliance Industries' Jamnagar complex and Indian Oil's Paradip refinery are commissioning new units.
- Gas Purification:Acid gas removal and dehydration columns specify low-pressure-drop designs. QatarEnergy and ADNOC LNG trains employ structured packing for CO2 and H2S absorption.
- Solvent Recovery:Pharmaceutical and coatings plants recover polar organics from aqueous waste streams. BASF's Ludwigshafen complex specifies specialized valve trays for acetone and ethanol recovery.
- Biofuel Production:Ethanol dehydration and biodiesel glycerol separation demand corrosion-resistant materials. US Midwest biorefineries are retrofitting corn ethanol plants for cellulosic feedstocks.
- Chemical Separation:Azeotropic and high-purity distillation requires precise vapor-liquid equilibrium control. INEOS's European olefins complexes specify Raschig valve geometries for specialty chemical production.
- Food & Beverage:Edible oil deodorization and spirits distillation employ sanitary-grade finishes. India's solvent extraction plants for vegetable oils specify 316L electropolished trays.
Petrochemical processing generates the largest order volumes, with biofuel production expanding most quickly.
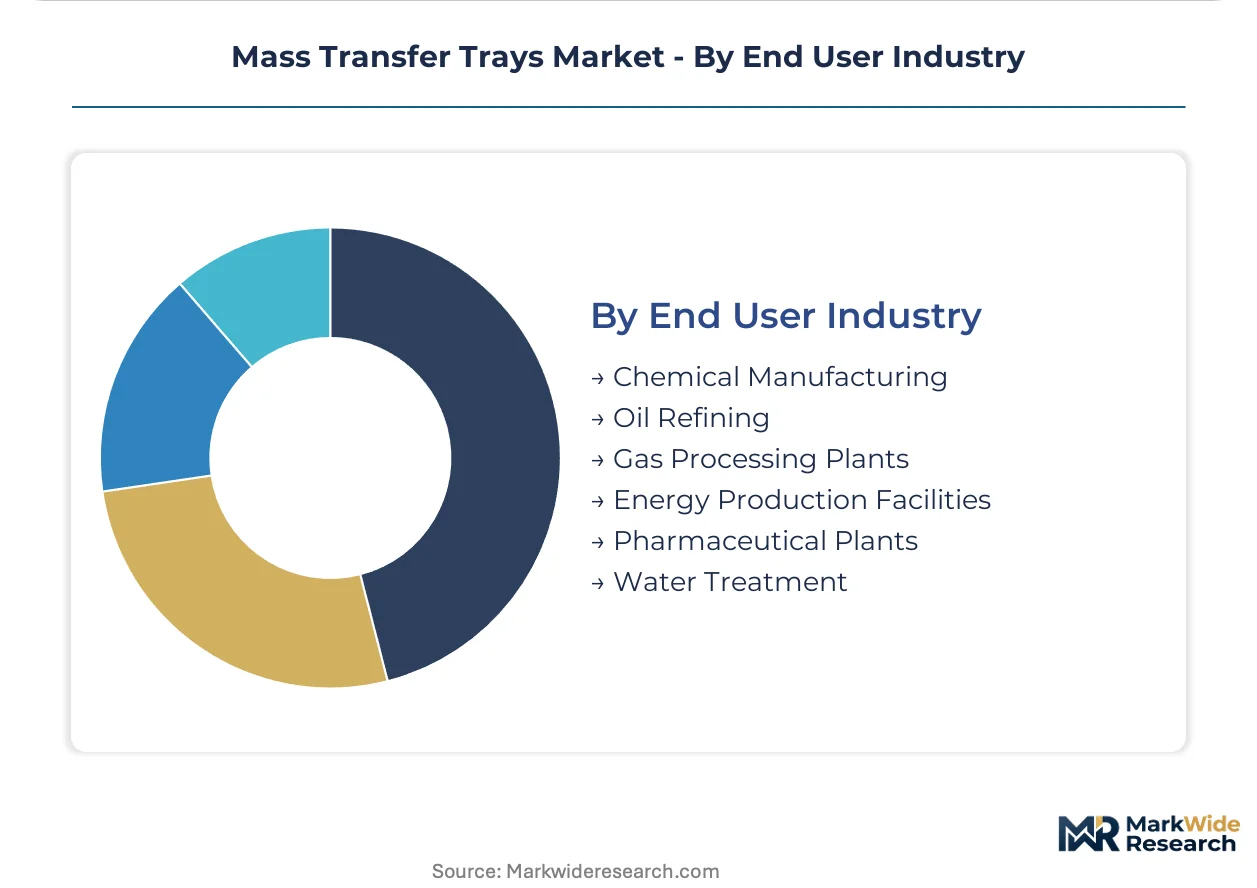
End User Industry:
Capital cycle timing and regulatory inspection intervals drive replacement demand, with oil refining exhibiting the most predictable maintenance schedules.
- Chemical Manufacturing:Specialty and commodity chemical producers operate diverse separation trains. Germany's BASF and Covestro run continuous revamp programs across Ludwigshafen and Krefeld sites.
- Oil Refining:Crude distillation, vacuum, and coker fractionation represent the largest installed base. US EPA New Source Performance Standards mandate tray integrity documentation for major modification projects.
- Gas Processing Plants:NGL fractionation and treating facilities require cryogenic-compatible designs. Permian Basin midstream operators are expanding fractionation capacity.
- Energy Production Facilities:IGCC and hydrogen production plants specify high-temperature alloys. Saudi Arabia's Jazan refinery and power complex employs specialty materials for gasification duties.
- Pharmaceutical Plants:GMP-validated columns demand material traceability and surface finish documentation. India's CDSCO inspection protocols reinforce ASME BPE compliance for active pharmaceutical ingredient production.
- Water Treatment:Stripping columns remove VOCs and ammonia from industrial wastewater. China's MEE discharge standards are driving tray upgrades at coastal petrochemical complexes.
Oil refining anchors the volume ranking, with pharmaceutical plants showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting tray fabrication toward jurisdictions with streamlined alloy certification pathways, as European REACH compliance costs and extended lead times push project owners to qualify Asian and Middle Eastern suppliers.
United States
Gulf Coast refinery corridors from Houston to Lake Charles are specifying duplex stainless trays for sour service towers. EPA New Source Performance Standards mandate material traceability documentation for major modifications. Permian Basin midstream operators are expanding NGL fractionation capacity with cryogenic-compatible designs.
China
Sinopec and PetroChina are retrofitting coastal refineries under GB 31570-2015 emission standards that tighten VOC leakage allowances from column seals. The Yangtze River Delta concentration of pressure vessel fabricators is absorbing revamp demand from Shandong and Jiangsu petrochemical complexes. Third-party emission testing documentation is now mandatory for all tray shipments.
India
Reliance Industries' Jamnagar complex and Indian Oil's Paradip refinery are commissioning new crude distillation units with high-capacity valve trays. BIS pressure vessel code harmonization with ASME Section VIII creates openings for domestic fabricators. The PLI scheme for specialty chemicals subsidizes capital equipment for tray production lines in Gujarat and Odisha.
Germany
BASF and Covestro run continuous revamp programs across Ludwigshafen and Krefeld chemical separation sites. REACH restrictions on hexavalent chromium coatings have eliminated most Central European surface treatment providers. German fabricators now control the majority of qualified capacity for corrosion-resistant finishes serving Benelux and French chemical producers.
Saudi Arabia
Saudi Aramco and SABIC are specifying advanced valve tray geometries for crude distillation unit expansions at Ras Tanura and Jubail Industrial City. The Jazan refinery and power complex employs specialty high-temperature alloys for gasification duties. Domestic fabrication partnerships are qualifying under Saudi Aramco's supplier development programs.
Mass Transfer Trays Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital-integrated service bundles and regional fabrication partnerships to bypass legacy qualification barriers. The supplier base stratifies between full-service OEMs with in-house column access capabilities and specialized fabricators focused on exotic alloy welding. Three archetypes dominate: integrated technology licensors bundling hardware with simulation services, regional fabricators leveraging proximity to project corridors, and alloy specialists commanding premium positioning on corrosion-resistant specifications. Competitive moves center on vertical integration into field service networks and technology licensing arrangements that lock in revamp project specifications.
Among Swiss and German-based technology providers, Sulzer and Koch-Glitsch exemplify the integrated licensor archetype with heritage positions in structured packing and high-efficiency revamp solutions. Raschig occupies a specialist position within European chemical separations. Chinese fabricators including Beiyang National Distillation Technology and Nantong Sutong Separation Technology represent the regional scale tier, capitalizing on domestic standard harmonization and state-refinery procurement localization. These named entities anchor the competitive map without exhausting the supplier universe.
| Leading Market Players |
|---|
| Sulzer |
| Koch-Glitsch |
| Raschig |
| RVT Process Equipment |
| Saiptech |
| Montz |
| HAT International |
| Beiyang National Distillation Technology |
| Nantong Sutong Separation Technology |
| Others |
Pricing and Supply Chain Analysis
Nickel price indices on the London Metal Exchange cascade through mass transfer tray supply chains into three distinct pricing tiers anchored by alloy grade and certification burden. Carbon steel assemblies for standard refinery duties occupy the economy segment, while duplex stainless and nickel alloys command premiums tied to Indonesian ore export volatility and ASME Section IX welding procedure costs.
Pricing Analysis
Distributor margins on exotic alloy trays compress under fixed-price EPC contracts when raw material hedges expire mid-project. Three-tier pricing structure across premium, standard, and economy levels separates ASME-certified nickel alloy fabrications from BIS-harmonized domestic Indian production and uncoated carbon steel imports. Pricing pressure stems from nickel price volatility on Indonesian ore policy shifts. Midstream chemical producers exhibit highest price sensitivity, while Gulf Coast sour service operators prioritize corrosion resistance over unit cost.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Houston maintain hub-and-spoke patterns for tray shipments to project corridors. Manufacturing concentrates in Germany, India, and China, with German fabricators controlling qualified capacity for REACH-compliant surface finishes. Raw material flows draw from Indonesian nickel mines, Chinese stainless steel mills, and Indian PLI-subsidized 316L production. Single-source vulnerability runs through German and Dutch surface treatment providers for hexavalent chromium alternatives. Distribution runs through EPC contractor procurement channels with OEM direct relationships for revamp specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mass transfer trays constitute a late-cycle quality story as emission thresholds tighten and alloy specification burdens shift procurement toward documented traceability and welding procedure qualification. The demand drift toward corrosion-resistant duplex and nickel alloys favors suppliers with captive metallurgy investments over component-only fabricators.
For Market Incumbents: Deploy backward integration into exotic alloy welding capacity to capture margin pools on ASME Section IX qualification bottlenecks. Koch-Glitsch and Sulzer should extend field service network density to lock in European integrated service contracts. Structured packing substitution in cryogenic duties and Chinese domestic fabrication scale represent contiguous threats requiring technology licensing defenses. For New Entrants and Emerging Players: The price-point gap between European REACH-compliant premium trays and Indian BIS-harmonized standard products creates entry space for mid-tier qualification. Target domestic fabrication partnerships in Gujarat and Odisha under PLI scheme subsidies, leveraging BIS code convergence for state-refinery contract eligibility. Bundle CFD modeling services with hardware supply to differentiate from component-only competitors. For Investors and Strategic Acquirers: Asymmetric upside sits with alloy specialists commanding premium positioning on sour service specifications and welding procedure libraries. Long-term viability centers on suppliers with Saudi Aramco and ADNOC supplier development program qualifications alongside European chemical separation relationships. Monitor Indonesian nickel export policy announcements as inflection signals for fabrication margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Exotic Alloy Welding | Captures margin pools on ASME Section IX qualification bottlenecks for high-nickel tray fabrication. |
| Digital Twin Service Bundling | Combines CFD modeling with IoT sensor networks for predictive maintenance contracts at BASF and INEOS sites. |
| Domestic Manufacturing Scale-Up in India | Exploits BIS-ASME code harmonization and PLI scheme subsidies for state-refinery contract eligibility. |
| Integrated Service Contract Expansion | Consolidates vendor positioning through outcome-based performance agreements with single-source chemical producers. |
| Hydrogen Purification Tray Development | Addresses green hydrogen feedstock retrofit demand from ammonia and methanol producers requiring enhanced weeping resistance. |
Research Methodology
Bottom-up petrochemical capacity modeling reconciled against top-down fabrication capacity tracking forms the analytical core of this study. Primary interviews with EPC contract procurement leads, refinery maintenance directors, tray OEM technical sales engineers, and pressure vessel fabricator welding supervisors combined with secondary validation from customs trade data, ASME certification registries, SEC 10-K filings, and BIS standard harmonization notices. Triangulation across stakeholder inputs and documentary sources anchors volume and value estimates.
Input-output matrices map alloy grade demand to refinery and chemical plant project pipelines across the projection horizon. Segmentation dimensions include tray type, material specification, application process, and end-user industry vertical. CAGRs derive from capacity expansion schedules, regulatory compliance cycle timing, and replacement demand modeling. Nickel price volatility assumptions and REACH coating transition timelines feed sensitivity scenarios.
Caveats apply where Indonesian ore export bans, ASME Section IX welder availability constraints, or REACH restriction scope expansions could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.