
 Bleaching Clay Market | 2026-2036
Bleaching Clay Market Size, Share, and Industry Trends Forecast 2026-2036
Bleaching Clay Market Analysis
Edible oil refining is pivoting toward higher-grade bleaching protocols as processors respond to stricter contaminant limits. Clariant AG leverages its European manufacturing base to supply activated bleaching earth for premium oil applications. Oil-Dri Corporation of America anchors North American supply through its captive bentonite reserves in Mississippi and Georgia. Ashapura Group dominates Indian and Middle Eastern markets with its integrated mining-to-processing operations across Gujarat.
Bleaching clay denotes a family of adsorptive aluminosilicate minerals, primarily bentonites and fuller's earth, acid-activated or thermally treated to achieve surface areas of 200-400 m²/g for pigment and contaminant removal in oils and fats. Activated bleaching earth commands the largest value share due to its superior decolorization efficiency in palm and soybean oil refining, while sodium bentonite segments see faster growth in wastewater treatment applications where flocculation demand is expanding. Oil refining applications generate the deepest margin pools because processors accept premium pricing for batch-specific performance guarantees.
EPA regulations on spent clay disposal and FDA food-contact substance notifications shape product formulation and end-use certification requirements in the United States. REACH registration and EFSA purity criteria in Europe impose parallel compliance burdens on exporters serving both markets. Stakeholders must monitor evolving biofuel mandates, as renewable diesel expansion could redirect feedstock flows and alter bleaching clay specification requirements across refinery customers.
Market Dynamics
Edible oil processors are accelerating bleaching clay consumption to meet tightening contaminant limits in refined oils, while acid-activation capacity expansion in Indonesia and India strains bentonite feedstock availability across Southeast Asian supply chains.
Growth Catalysts
- REACH purity mandates:ECHA registration requirements for food-contact substances force European refiners toward higher-grade activated bleaching earth, compressing acceptance of standard-grade alternatives.
- Palm oil refining clusters:Indonesia's Riau and North Sumatra provinces are adding continuous deodorizer capacity that multiplies bleaching clay throughput per ton of crude palm oil processed.
- Renewable diesel qualification:ASTM D975 and EN 590 specifications for hydrotreated vegetable oils extend bleaching protocols to biofuel feedstock pretreatment, opening parallel demand channels.
Market Restraints
- Bentonite deposit concentration:Premium calcium bentonite reserves concentrate in Wyoming's Bighorn Basin and Gujarat's Kutch district, exposing processors to single-source geopolitical and logistics risks.
- Sulfuric acid cost volatility:Acid-activation requires 15-20% concentrated sulfuric acid by weight; fertilizer sector demand swings and phosphate rock supply disruptions transmit directly to bleaching clay production economics.
- Silica gel substitution:Synthetic amorphous silica adsorbents achieve comparable chlorophyll removal in specialty oil applications, threatening premium bleaching earth volumes in olive and avocado oil segments.
Strategic Opportunities
- PLI scheme alignment:India's production-linked incentive scheme for food processing infrastructure subsidizes integrated refining complexes in Andhra Pradesh and Maharashtra, embedding bleaching clay demand in greenfield capex.
- Spent clay regeneration:Thermal reactivation technologies recover 60-70% of adsorptive capacity, enabling circular service models that bypass landfill disposal constraints under EPA subtitle D regulations.
- Wastewater treatment crossover:Sodium bentonite flocculation demand from textile and tannery effluent treatment in Bangladesh and Vietnam offers volume diversification beyond edible oil dependence.
Industry Challenges
- Acid-activation expertise scarcity:Process optimization for specific oil chemistries requires specialized mineralogists; Southeast Asian processors struggle to recruit talent familiar with both bentonite mineralogy and refining engineering.
- EFSA re-certification timelines:Novel activation protocols face 18-24 month safety evaluation windows, delaying product launches and freezing formulation innovation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bleaching Clay Market |
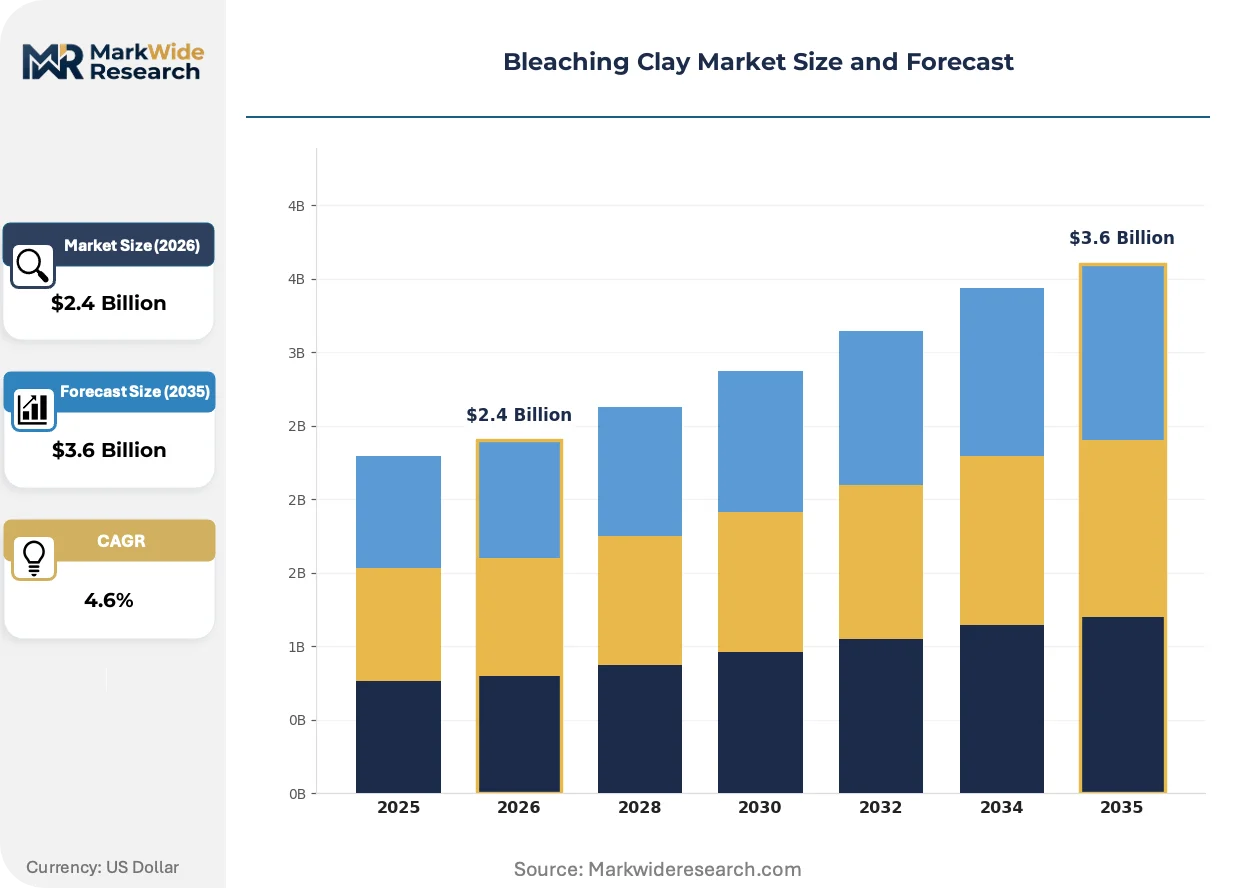
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.6 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Activated Bleaching Earth, Sodium Bentonite, Calcium Bentonite, Fuller’s Earth Application: Oil Refining, Food Processing, Cosmetic Products, Wastewater Treatment End User: Food and Beverage, Pharmaceuticals, Personal Care, Industrial Distribution Channel: Direct Sales, Online Retail, Distributors, Agents |
| Companies Covered | Clariant AG, Oil-Dri Corporation of America, Ashapura Group, Taiko Group of Companies, Musim Mas Holdings, AMC (UK) Ltd., Refoil Earth Pvt. Ltd., EP Minerals LLC, Manek Active Clay Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bleaching Clay Market Emerging Trajectories
Surface chemistry engineering and digital process control are compressing the gap between commodity bentonite and performance-guaranteed activated grades, while regulatory fragmentation forces parallel certification tracks.
Engineered nanopore architectures in acid-activated bleaching earth is rewriting performance benchmarks for chlorophyll and carotenoid removal. Malaysian palm oil refiners are retrofitting continuous bleaching systems with these materials, accepting 12-15% price premiums for batch-specific color guarantee contracts that eliminate downstream rework.
REACH authorization timelines for acid-activated substances are compressing supplier registration windows. ECHA's 2024 updated guidance on nanomaterial characterization forces reformulation of fine-particle bleaching grades, with German and Dutch edible oil processors accelerating audits of supplier dossier completeness to avoid supply interruption.
Refiners are consolidating bleaching clay procurement under multi-year performance contracts that unbundle product supply from technical service. Indonesian palm oil majors now specify decolorization efficiency guarantees rather than tonnage orders, shifting supplier relationships toward outcome-based partnerships visible across Sumatra and Kalimantan processing hubs.
Bleaching Clay Market Segmentation
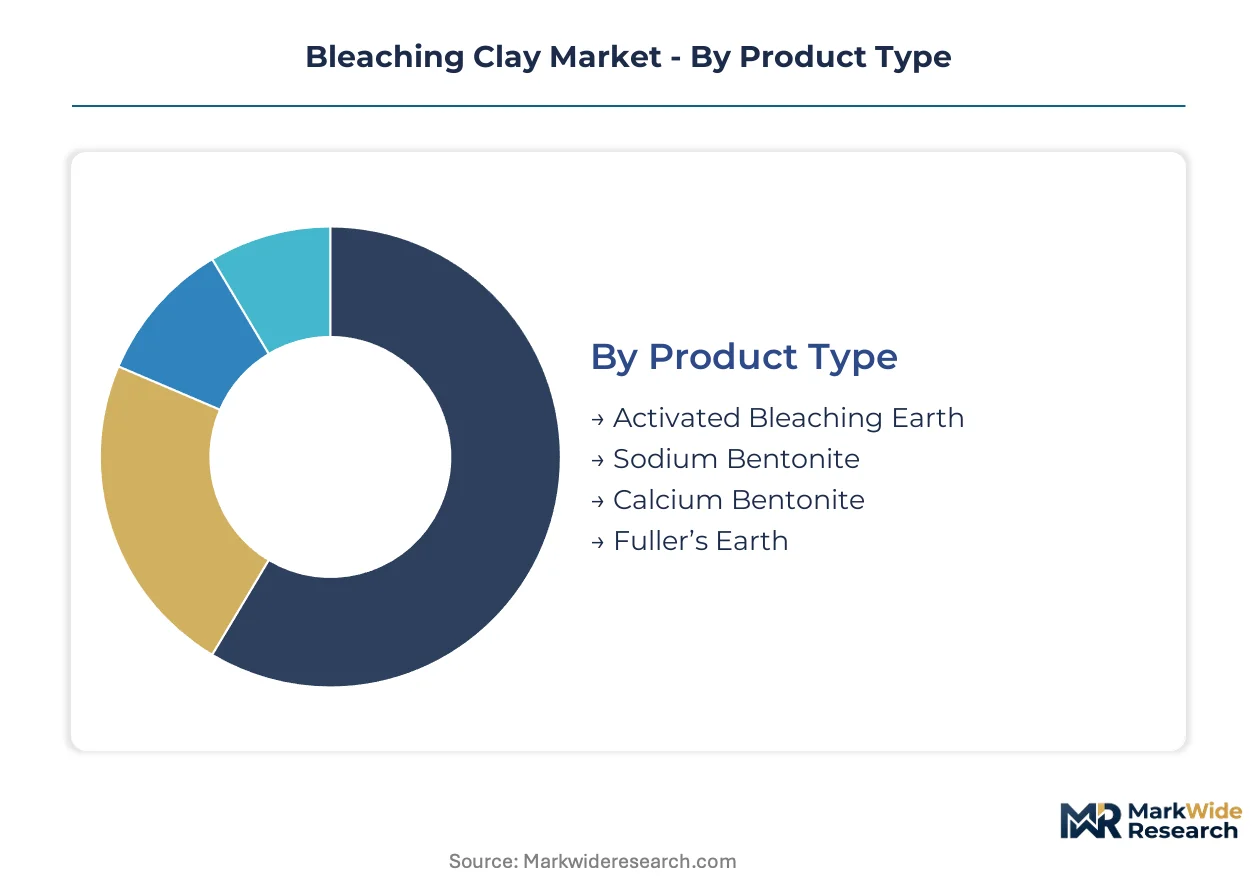
Bleaching clay segmentation reflects divergent capital requirements across activation technologies and end-use certification standards. Product type stratification separates acid-activation infrastructure investments from raw bentonite mining outlays, while application segments demand differentiated purity protocols.
Product Type:
Acid-activation facilities require sulfuric acid handling infrastructure and thermal treatment systems that multiply upfront capital versus raw bentonite processing.
- Activated Bleaching Earth:Acid-activated calcium bentonite with engineered surface areas of 200-400 m²/g achieves superior chlorophyll adsorption in palm oil refining. Indonesian processors in Riau province specify these grades for continuous deodorizer systems that process rising crude palm oil volumes.
- Sodium Bentonite:Naturally swelling aluminosilicate with high cation exchange capacity serves wastewater flocculation and drilling mud applications. Textile effluent treatment plants in Bangladesh and Vietnam drive volume expansion for this lower-cost, non-activated grade.
- Calcium Bentonite:Non-swelling smectite clay with intermediate adsorptive properties bridges cost-performance requirements in standard edible oil refining.
- Fuller's Earth:Naturally active attapulgite and sepiolite clays with inherent porosity serve cosmetic and mineral oil purification without chemical activation.
Activated bleaching earth absorbs the bulk of installed capacity; sodium bentonite is expanding most quickly.
Application:
Margin structures diverge sharply between commodity-scale oil refining and specialized cosmetic formulations requiring batch certification.
- Oil Refining:Decolorization of palm, soybean, and sunflower oils demands high-performance activated grades with guaranteed pigment removal rates. Malaysian and Indonesian refiners specify performance contracts tied to Lovibond color reduction rather than tonnage.
- Wastewater Treatment:Sodium bentonite flocculation of textile dyes and heavy metals offers volume diversification beyond edible oil dependence. Bangladeshi tannery clusters and Vietnamese dye houses are embedding clay-based primary treatment in effluent compliance upgrades.
- Food Processing:Bleaching of animal fats and specialty oils for bakery and confectionery applications requires food-grade certification under FDA and EFSA frameworks.
- Cosmetic Products:Fuller's earth serves facial mask and exfoliant formulations where mineral purity and particle size distribution determine cosmetic-grade pricing.
Oil refining commands the deepest margin pools; wastewater treatment is climbing the fastest.
End User:
Procurement sophistication separates pharmaceutical-grade certification requirements from industrial bulk purchasing.
- Food and Beverage:Integrated palm oil majors in Indonesia and Malaysia negotiate multi-year supply agreements with technical service bundling. These processors demand batch-specific decolorization guarantees and REACH-compliant documentation.
- Industrial:Lubricant rerefiners and petrochemical processors purchase standard-grade fuller's earth in bulk without activation, prioritizing cost over performance optimization.
- Pharmaceuticals:Mineral oil purification for topical formulations and excipient applications requires USP-grade certification and low heavy metal content.
- Personal Care:Cosmetic manufacturers specify particle size distributions and microbial limits that command premium pricing over technical grades.
Food and beverage concentrates procurement volume; pharmaceuticals is gaining share fastest.
Distribution Channel:
Channel economics reflect the tradeoff between technical service intensity and logistics efficiency across customer segments.
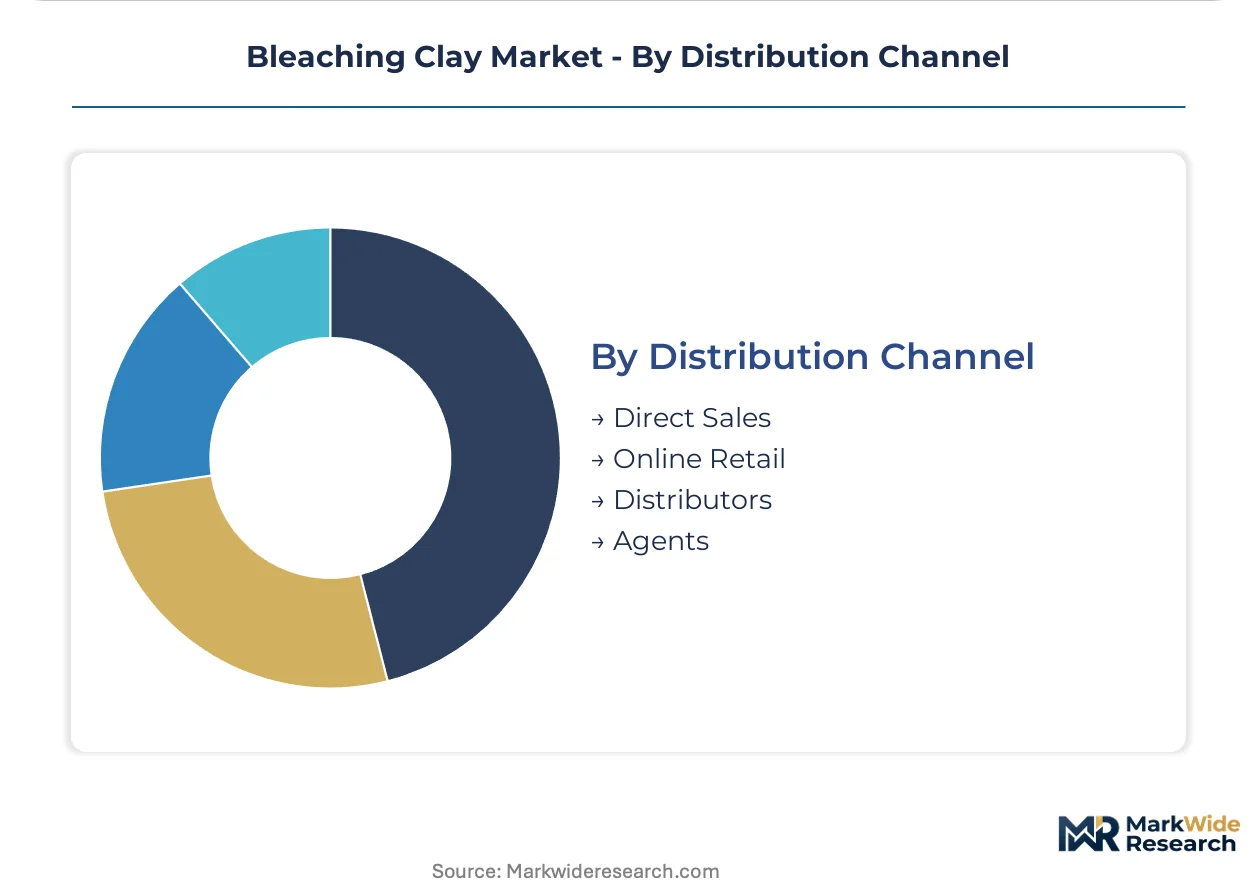
- Direct Sales:Major refiners in Indonesia and Malaysia procure through technical partnerships with activation plant operators. Clariant AG and Ashapura Group deploy field engineers to optimize bleaching protocols at customer facilities.
- Distributors:Regional chemical distributors serve mid-scale processors in India and Southeast Asia with standardized grades and local inventory.
- Agents:Commission-based representatives bridge language and regulatory gaps for exporters entering new markets.
- Online Retail:E-commerce platforms serve small cosmetic formulators and research laboratories with packaged quantities.
Direct sales captures the largest contract value; distributors is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bleaching clay production clusters in Wyoming's Bighorn Basin and Gujarat's Kutch district, while consumption concentrates in Southeast Asian palm oil refining corridors and European edible oil processing hubs.
Indonesia
Riau and North Sumatra provinces drive activated bleaching earth demand as palm oil refiners expand continuous deodorizer capacity. The country's national food safety regulator enforces stricter contaminant limits on refined oils. Medan-based processing clusters now specify performance-based procurement contracts tied to Lovibond color reduction guarantees rather than tonnage orders.
United States
Mississippi and Georgia bentonite reserves anchor North American supply for domestic oil refiners and lubricant rerefiners. EPA regulations on spent clay disposal under Subtitle D shape product formulation and end-use certification requirements. Gulf Coast renewable diesel facilities are extending bleaching protocols to hydrotreated vegetable oil feedstock pretreatment.
India
Gujarat's integrated mining-to-processing operations dominate supply for domestic edible oil refiners and Middle Eastern export markets. The Production-Linked Incentive scheme for food processing infrastructure subsidizes integrated refining complexes in Andhra Pradesh and Maharashtra. Kutch district calcium bentonite deposits face mounting pressure from acid-activation capacity expansion across Southeast Asian supply chains.
Germany
REACH registration requirements for food-contact substances force European refiners toward higher-grade activated bleaching earth. ECHA's updated guidance on nanomaterial characterization compels reformulation of fine-particle grades. German edible oil processors accelerate supplier dossier audits to avoid supply interruption from authorization timeline compression.
Malaysia
Port Klang and Pasir Gudang refining hubs retrofit continuous bleaching systems with engineered nanopore architectures for chlorophyll and carotenoid removal. The country's national standards body aligns with EFSA purity criteria for export-oriented processors. Johor-based palm oil majors now unbundle product supply from technical service under multi-year performance contracts.
Bleaching Clay Market Vendor Landscape
Top-tier vendors anchor premium activated bleaching earth supply, while regional bentonite miners and acid-activation specialists occupy mid-market and commodity tiers. The competitive map splits between integrated mining-to-activation conglomerates with captive reserves and independent processors purchasing third-party feedstock. Three archetypes dominate: Wyoming-based reserve holders with North American distribution, Gujarat-integrated operators serving Indian and Middle Eastern markets, and European chemical multinationals leveraging REACH-compliant manufacturing. Capacity expansion in Indonesia and India strains feedstock availability, while spent clay regeneration technologies enable circular service models that bypass landfill constraints.
Among European chemical multinationals, Clariant AG exemplifies the premium-tier activation specialist archetype. Oil-Dri Corporation of America represents the reserve-integrated North American supplier model. Ashapura Group occupies a position within the mining-to-processing integrated operator tier. These three anchors illustrate how geographic feedstock control, regulatory compliance infrastructure, and technical service bundling separate competitive positions across edible oil refining and industrial applications.
| Leading Market Players |
|---|
| Clariant AG |
| Oil-Dri Corporation of America |
| Ashapura Group |
| Taiko Group of Companies |
| Musim Mas Holdings |
| AMC (UK) Ltd. |
| Refoil Earth Pvt. Ltd. |
| EP Minerals LLC |
| Manek Active Clay Pvt. Ltd. |
| Others |
Supply Flow & Price Mechanics
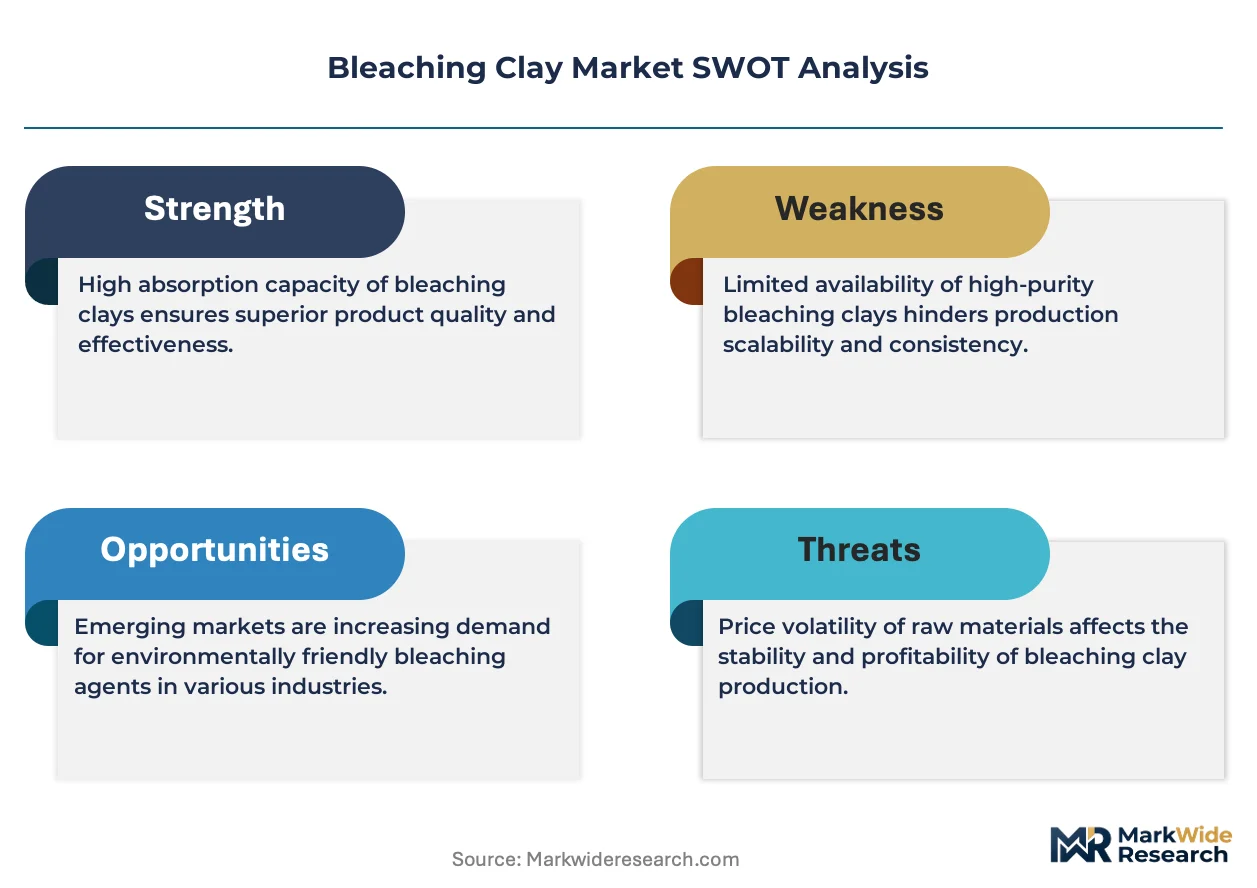
Family-owned bentonite mining operations across Gujarat and Wyoming anchor feedstock ownership patterns that translate directly into pricing discipline at the activation plant level. These entrenched ownership structures limit price transparency and compress margin flexibility for independent processors lacking captive reserves.
Pricing Analysis
Margin tightening in standard-grade activated bleaching earth reflects sulfuric acid cost volatility and Indonesian processor consolidation. Three-tier pricing structure across performance-guaranteed, certified-standard, and bulk-economy levels separates oil majors from mid-scale refiners and industrial buyers. Cost compression accelerates as Riau-based palm oil processors shift from tonnage orders to Lovibond color-outcome contracts. Food and beverage majors show least price sensitivity; textile effluent treatment operators in Bangladesh exhibit highest.
Supply Chain Analysis
Freight cost differentials between Wyoming's Bighorn Basin and Gujarat's Kutch district determine competitive reach for activation plants serving Southeast Asian refiners. Supply concentrates in the United States, India, and Indonesia, with raw bentonite draws from calcium-rich deposits, sulfuric acid for acid-activation, and thermal treatment fuels. Single-source vulnerability in Wyoming premium reserves exposes processors to logistics disruption. Distribution runs through direct technical partnerships for major refiners and regional chemical distributors for mid-scale buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where REACH registration and EFSA purity criteria erect regulatory moats that favor incumbent players with dossier infrastructure and European manufacturing footprints.
For Market Incumbents: Acquire acid-activation expertise through specialist mineralogist teams and process engineering capabilities. Secure backward integration into Gujarat or Wyoming bentonite reserves to insulate against feedstock competition from Indonesian capacity expansion. Defend against silica gel substitution in specialty oil segments by embedding performance guarantees into multi-year technical service contracts. For New Entrants and Emerging Players: Wastewater treatment operators in Bangladesh and Vietnam represent an underserved buyer archetype with flocculation demand growth and lower certification barriers. Enter through sodium bentonite supply partnerships with textile clusters before expanding to activated grades. Leverage India's PLI-subsidized refining complexes as anchor customers for greenfield activation capacity. For Investors and Strategic Acquirers: Distressed-cycle entries favor European activation specialists with REACH-compliant dossiers and stranded manufacturing assets. Long-term viability hinges on renewable diesel qualification pipelines and spent clay regeneration service models. Monitor ASTM D975 and EN 590 specification evolution as inflection signal for biofuel feedstock pretreatment demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bentonite Reserves | Gujarat and Wyoming captive deposits insulate processors from Southeast Asian feedstock competition. |
| Spent Clay Regeneration Technology Deployment | Thermal reactivation services bypass EPA Subtitle D landfill constraints for US refiners. |
| REACH Dossier Expansion | ECHA registration completion secures European food-contact substance market access. |
| Performance-Based Contracting | Lovibond color guarantee contracts shift Indonesian palm oil procurement from tonnage to outcomes. |
| Wastewater Treatment Crossover | Bangladeshi tannery and Vietnamese textile effluent demand diversifies beyond edible oil dependence. |
Methodological Framework
Independent corroboration across activation plant technical directors, edible oil refinery procurement leads, and sulfuric acid supply specialists underwrites the qualitative findings. Primary interviews with bentonite mining operators, REACH compliance consultants, and Indonesian palm oil processing engineers combined with secondary validation from customs trade data, ECHA registration databases, SEC filings of listed clay processors, and FSSAI food safety notifications. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates.
Rate-of-change decomposition across product type, application, end user, and regional regulatory cluster dimensions structures the analytical framework. CAGRs derive from segment-specific volume trajectories and value-per-ton adjustments for performance-guaranteed versus commodity grades. Forecast inputs include Indonesian palm oil refining capacity expansion schedules and renewable diesel facility commissioning timelines across the analysis window.
Revisions become necessary when EFSA re-certification timelines extend beyond standard windows or sulfuric acid supply disruptions from phosphate rock volatility materialize. Forecasts reflect documented assumptions on REACH authorization progression and biofuel mandate evolution. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Process Chromatography Market
Industrial Chemicals
Global Metalworking Fluids Market
Industrial Chemicals
Global Chemical Mechanical Planarization Market
Industrial Chemicals
Drag Reducing Agents Market
Industrial Chemicals
Explosive Chargers Market
Industrial Chemicals
Welding Electrodes Market
Industrial Chemicals
High Pressure Roll Compactor Market
Industrial Chemicals
Global Refrigerants Market
Industrial Chemicals
Liquid Electrolyte Market
Industrial Chemicals
Global Bio Based Isoprene Market
Industrial Chemicals
Europe and Middle East Lime Market
Industrial Chemicals
Tall Oil Fatty Acid Market
Industrial Chemicals
Fluidizers in Plasterboard Market
Industrial Chemicals
Bulk Explosives Market
Industrial Chemicals
Biobased Degreaser Market
Industrial Chemicals
Global High Throughput Process Development Market