
 Water Treatment Polymers Market | 2026-2036
Water Treatment Polymers Market Size, Share, and Industry Trends Forecast 2026-2036
Water Treatment Polymers Market Outlook
Performance-based polymer dosing subscriptions is realigning procurement from bulk chemical purchases to guaranteed-output service contracts. Kemira leverages its digital water chemistry platform to anchor long-term municipal partnerships across Nordic utilities. SNF Group sustains manufacturing scale through backward integration into acrylamide monomer production, controlling feedstock costs across its global powder and emulsion network. BASF SE differentiates through bio-based flocculant R&D, positioning its portfolio for regulatory thresholds on synthetic polymer persistence.
Water treatment polymers are high-molecular-weight synthetic or natural compounds, typically polyacrylamide-based or polysaccharide-derived, engineered to destabilize colloidal suspensions through charge neutralization and interparticle bridging at dosages measured in parts per million. Their primary industrial purpose is solids-liquid separation in clarification, thickening, and dewatering operations across municipal and process water circuits. Flocculants command the dominant value share due to their irreplaceable role in sludge dewatering, where polymer selection directly determines cake dryness and disposal economics. Coagulants face margin compression from inorganic alternatives but retain structural importance in pre-treatment trains ahead of membrane systems. Oil & gas end users represent a concentrated growth pocket, as produced water volumes from shale and conventional operations require tailored high-salinity polymer formulations.
EPA effluent limitation guidelines and EU REACH restrictions on acrylamide monomer residuals are reshaping product registration requirements and reformulation timelines on both sides of the Atlantic. China's MEE surface water quality standards and zero-liquid-discharge mandates for coal-chemical and textile clusters are forcing polymer suppliers to qualify temperature- and salinity-tolerant molecular architectures for industrial reuse circuits. Stakeholders must monitor how bio-based feedstock certification schemes and carbon border adjustments redefine competitive access for synthetic versus renewable polymer platforms.
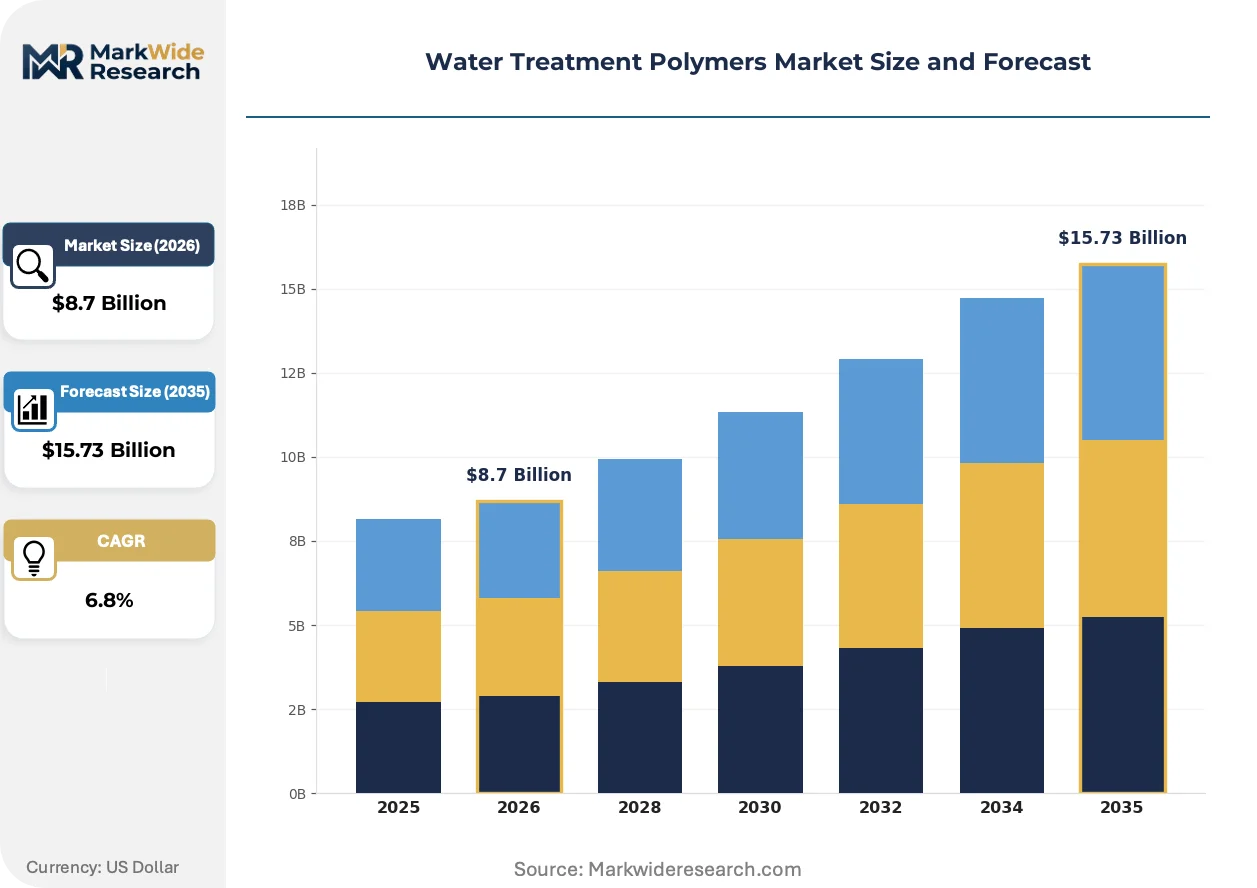
Market Dynamics
REACH compliance deadlines on acrylamide monomer residuals are forcing reformulation cycles across European polymer portfolios, while China's zero-liquid-discharge mandates for coal-chemical clusters pull demand toward temperature-tolerant molecular architectures.
Growth Catalysts
- EU Urban Wastewater Treatment Directive:German municipal facilities are expanding polymer dosing capacity to meet stricter effluent standards, pulling demand for high-performance flocculants into public procurement pipelines.
- Shale produced water volumes:Oil and gas operators in the Permian Basin require tailored high-salinity polymer formulations, creating a concentrated growth pocket for specialty emulsion chemistry.
- Industrial water reuse corridors:Provincial discharge limits in China's heavy manufacturing zones now mandate tertiary polymer treatment, anchoring demand in steel, textile, and petrochemical clusters.
Market Restraints
- Acrylamide monomer price volatility:Feedstock costs swing with propylene and natural gas benchmarks, compressing margin visibility for non-integrated polymer manufacturers.
- SNF Group's acrylamide dominance:Backward integration into monomer production by the leading supplier creates supply concentration risk for independent compounders.
- Chitosan and starch derivative substitution:Bio-based flocculants gain technical qualification in low-salinity municipal applications, threatening synthetic polymer volume in sensitive segments.
Strategic Opportunities
- India's Smart Cities Mission:Urban wastewater infrastructure buildout in secondary cities lacks qualified polymer suppliers, opening first-mover positioning for technical service providers.
- Carbon border adjustment mechanisms:EU CBAM phase-in creates preference asymmetry for bio-based feedstock certification, rewarding renewable polymer platforms with market access advantages.
- Digital dosing platforms:Real-time turbidity feedback loops integrated with automated polymer injection systems are displacing manual dosing in Nordic utilities, creating SaaS-like revenue streams.
Industry Challenges
- Polymer chemist talent scarcity:Formulation expertise bridging organic synthesis and colloidal physics concentrates in aging specialist pools, constraining R&D throughput for mid-tier suppliers.
- REACH registration timelines:Multi-year dossier preparation for new molecular architectures delays product launch windows, freezing capital in pre-revenue development phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Treatment Polymers Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flocculants, Coagulants, Disinfectants, Antiscalants End User: Municipalities, Industrial Facilities, Oil & Gas, Agricultural Application: Water Treatment, Wastewater Treatment, Drinking Water, Boiler Water Delivery Mode: Liquid, Powder, Granular, Solid |
| Companies Covered | Kemira, SNF Group, Ashland, Arkema, BASF SE, DuPont, Ecolab Inc., Solenis LLC, Kuraray Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Treatment Polymers Market Strategic Shifts
Polymer architecture is converging with sensor networks and predictive dosing algorithms, collapsing the traditional separation between chemical supply and process control.
Hybrid cationic-anionic block copolymers are unifying charge neutralization and bridging functions in single-molecule designs. Mining tailings operators in Chile and Australia are piloting these architectures for high-solids dewatering. The technology is unifying what previously required sequential coagulant-flocculant dosing, compressing capex and footprint for thickening circuits.
EPA effluent limitation guidelines on per- and polyfluoroalkyl substances are tightening analytical detection thresholds for polymer processing aids. Industrial dischargers in the US Great Lakes basin must now validate that flocculant formulations contain no fluorinated surfactant residuals. Powder polymer suppliers are accelerating defoamer reformulation to maintain qualification status with municipal procurement authorities.
Subscription-based dosing contracts are displacing bulk chemical tenders in Scandinavian water utilities. Kemira anchors multi-year partnerships through guaranteed output metrics rather than volume commitments. Finland and Sweden host the most advanced adopters, where digital water chemistry platforms enable real-time polymer optimization against variable influent loads.
Water Treatment Polymers Market Segmentation
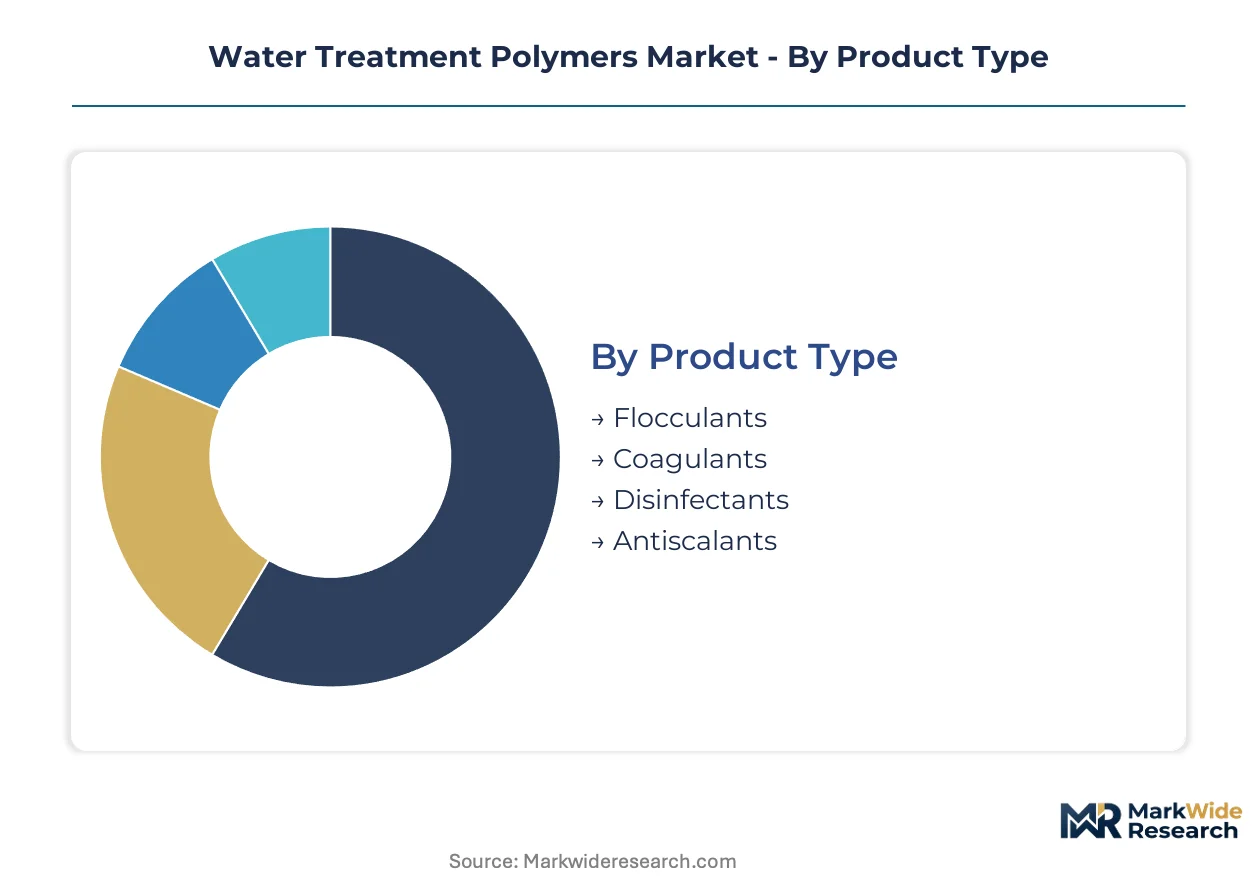
Water treatment polymers serve distinct functional roles across municipal, industrial, and specialized extraction environments. Segmentation by product chemistry, end-use intensity, and physical delivery form reveals where formulation premiums concentrate versus where commodity substitution pressures operate.
Product Type:
Integration depth varies sharply: flocculants and coagulants embed directly into continuous process trains, while disinfectants and antiscalants often deploy as point-of-use or maintenance dosing.
- Flocculants:High-molecular-weight polyacrylamide chains engineered for charge neutralization and interparticle bridging dominate sludge dewatering economics. Demand concentrates in German municipal facilities expanding under EU Urban Wastewater Treatment Directive mandates, where polymer selection directly determines cake dryness and disposal cost trajectories.
- Coagulants:Cationic polymers and inorganic alternatives destabilize colloidal suspensions ahead of clarification or membrane pre-treatment. China's zero-liquid-discharge mandates for coal-chemical clusters pull procurement toward temperature-tolerant molecular architectures capable of sustaining performance across variable industrial reuse circuits.
- Disinfectants:Polymeric biocides and quaternary ammonium compounds supplement chlorine-based regimes in cooling towers and recirculating systems.
- Antiscalants:Threshold inhibitors and dispersant polymers prevent mineral precipitation in boiler feedwater and reverse osmosis membranes.
Volume placements concentrate in Flocculants; the faster expansion belongs to Coagulants as pre-treatment intensity rises ahead of membrane asset protection.
End User:
Customer procurement maturity separates subscription-ready municipal utilities from price-sensitive agricultural distributors, with industrial and oil & gas operators occupying intermediate contract sophistication tiers.
- Municipalities:Public wastewater treatment authorities operate long-term framework agreements prioritizing guaranteed output metrics over unit pricing. Nordic utilities in Finland and Sweden anchor the most advanced adoption of digital dosing platforms with real-time turbidity feedback loops.
- Industrial Facilities:Steel, textile, and petrochemical clusters in China's heavy manufacturing zones drive tertiary polymer treatment mandates under provincial discharge limits. Temperature and salinity tolerance specifications dominate technical qualification requirements.
- Oil & Gas:Permian Basin shale operators require tailored high-salinity emulsion formulations for produced water management. Produced water volumes from conventional and unconventional operations create a concentrated growth pocket for specialty polymer chemistry.
- Agricultural:Irrigation system maintenance and livestock wastewater treatment represent fragmented, price-sensitive demand with limited technical service attachment.
Municipalities anchor current volume commitments; Oil & Gas generates the steepest expansion trajectory as produced water regulation tightens across North American extraction basins.
Application:
Process stage positioning determines polymer architecture complexity, with wastewater and boiler water applications demanding higher molecular specificity than primary drinking water treatment.
- Water Treatment:Raw water clarification for industrial process intake employs coagulant-flocculant sequences in surface water and groundwater remediation.
- Wastewater Treatment:Activated sludge dewatering and tertiary polishing represent the most polymer-intensive process stage. Sludge cake dryness targets directly link to landfill or incineration economics, elevating flocculant selection to strategic procurement priority.
- Drinking Water:Potable water certification requirements constrain polymer chemistry to approved monomer residual limits under EPA and EU REACH frameworks.
- Boiler Water:High-pressure steam systems require antiscalant and dispersant polymers capable of operating at elevated temperatures without thermal degradation.
Volume placements concentrate in Wastewater Treatment; Drinking Water is climbing the fastest as regulatory detection thresholds for acrylamide monomer residuals tighten on both sides of the Atlantic.
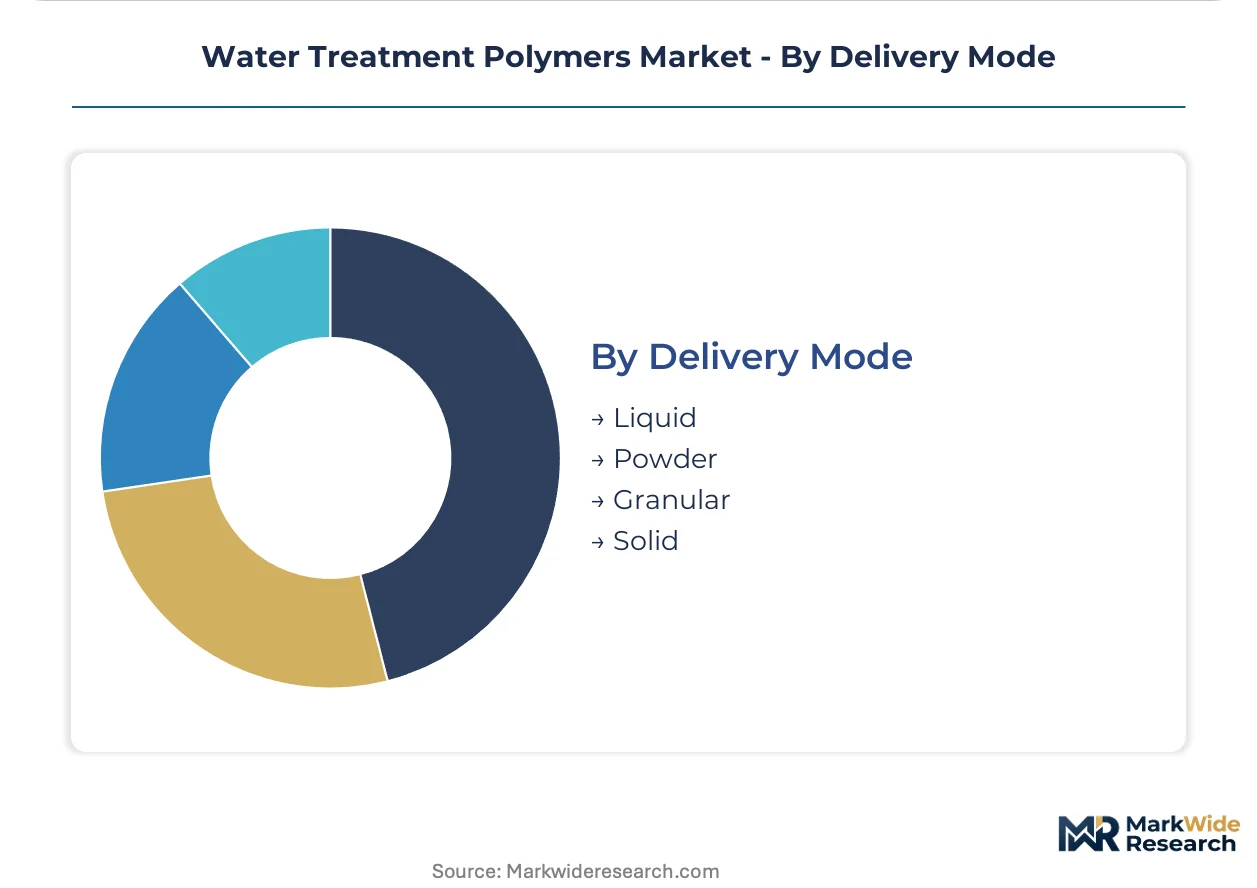
Delivery Mode:
Physical form factor trade-offs between concentrated activity, storage footprint, and dissolution equipment capital shape regional supply chain configurations.
- Liquid:Emulsion and solution polymers offer immediate dosing readiness without dry handling equipment. Oil & gas field operations and automated municipal systems favor liquid delivery for remote site logistics compatibility.
- Powder:High-activity polyacrylamide powders minimize transport cost per active kilogram but require dedicated dissolution and aging systems. Powder suppliers are accelerating defoamer reformulation to maintain EPA qualification status as fluorinated surfactant scrutiny intensifies.
- Granular:Intermediate particle size reduces dust generation versus fine powders while retaining higher activity than emulsion alternatives.
- Solid:Tablet and block formulations serve niche cooling tower and small-scale agricultural applications with minimal equipment requirements.
Volume placements concentrate in Liquid; Powder is gaining share fastest as backward-integrated manufacturers optimize global distribution networks for high-activity dry products.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ruhr industrial corridor in Germany anchors European polymer demand as municipal utilities retrofit dewatering capacity under tightened EU discharge standards. This concentration pattern repeats across four additional national markets where regulatory stringency and industrial water reuse intersect.
Germany
Municipal wastewater authorities in North Rhine-Westphalia and Bavaria are expanding flocculant dosing systems to comply with revised EU Urban Wastewater Treatment Directive limits. ECHA REACH compliance deadlines on acrylamide monomer residuals are forcing reformulation cycles across domestic polymer portfolios. The Rhine-Ruhr metropolitan region hosts the densest concentration of tertiary treatment upgrades, with Essen and Düsseldorf utilities tendering for high-performance emulsion chemistry.
China
Provincial discharge limits in Jiangsu and Shandong provinces now mandate tertiary polymer treatment for steel, textile, and petrochemical clusters. MEE surface water quality standards and zero-liquid-discharge mandates for coal-chemical operations pull demand toward temperature-tolerant molecular architectures. The Yangtze River Delta industrial corridor around Shanghai and Ningbo represents the fastest-expanding qualified polymer consumption zone for high-salinity reuse circuits.
United States
Permian Basin shale operators in Texas and New Mexico require tailored high-salinity emulsion formulations for produced water management volumes. EPA effluent limitation guidelines on per- and polyfluoroalkyl substances are tightening analytical detection thresholds for polymer processing aids. The Great Lakes basin industrial dischargers must now validate flocculant formulations contain no fluorinated surfactant residuals, accelerating defoamer reformulation among powder suppliers.
India
Urban wastewater infrastructure buildout under the Smart Cities Mission lacks qualified polymer suppliers across secondary cities in Maharashtra and Gujarat. The Central Pollution Control Board's tightening effluent standards for industrial clusters are creating first-mover positioning opportunities for technical service providers. The Delhi-Mumbai Industrial Corridor petrochemical and textile zones are emerging as priority qualification targets for temperature-stable flocculant architectures.
Finland
Nordic utilities in Helsinki and Tampere anchor the most advanced adoption of digital dosing platforms with real-time turbidity feedback loops. Subscription-based dosing contracts are displacing bulk chemical tenders as Kemira anchors multi-year partnerships through guaranteed output metrics. The country's municipal procurement frameworks prioritize performance-based service contracts over volume commitments, compressing traditional chemical supply margins.
Water Treatment Polymers Market Competitive Environment
Capital-heavy producers compete with asset-light designers across a bifurcated structure where backward-integrated monomer manufacturers hold feedstock cost advantages over independent compounders. The vendor base concentrates around three strategic archetypes: integrated chemical conglomerates with captive acrylamide supply, specialty water treatment houses with digital dosing platforms, and regional compounders serving price-sensitive municipal tenders. Dominant competitive moves include upstream integration into monomer production and the shift from bulk chemical sales to outcome-based service contracts anchored by sensor networks.
Within the integrated chemical tier, BASF SE and SNF Group represent contrasting scale positions, with the latter exemplifying upstream control over acrylamide feedstock economics. Kemira occupies a distinctive position among specialty water treatment providers, its digital water chemistry platform serving as an anchor for long-term municipal partnerships. These three companies collectively illustrate the competitive tension between manufacturing scale and service-led differentiation that defines current procurement realignment.
| Leading Market Players |
|---|
| Kemira |
| SNF Group |
| Ashland |
| Arkema |
| BASF SE |
| DuPont |
| Ecolab Inc. |
| Solenis LLC |
| Kuraray Co. Ltd |
| Others |
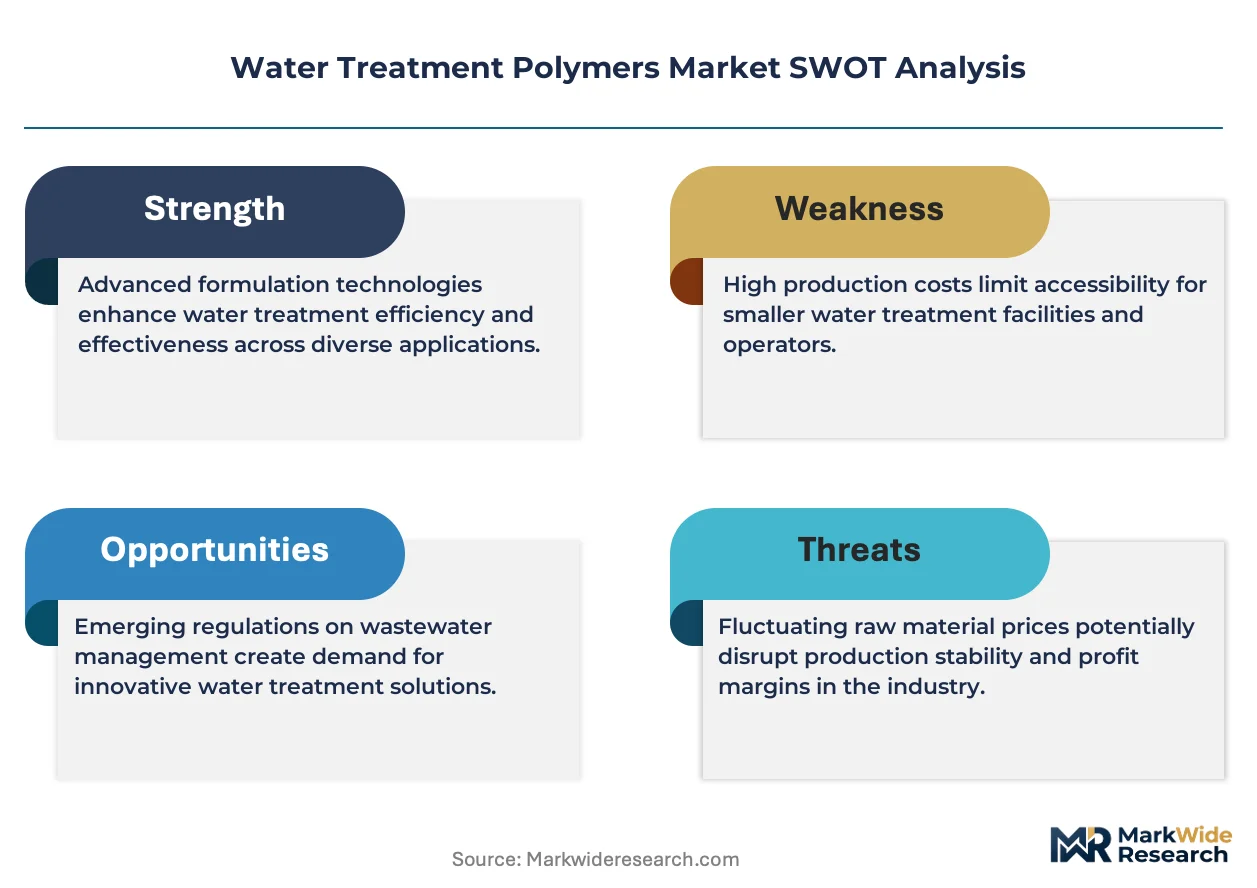
Value Chain & Pricing Dynamics
EU REACH acrylamide monomer residual limits gate qualified supply and premium-tier pricing access, compressing margin structures for non-integrated compounders while rewarding backward-integrated manufacturers with feedstock cost control.
Pricing Analysis
Outcome-based subscription contracts anchor value-based pricing in Nordic municipal utilities, where Kemira guarantees dewatering performance rather than selling bulk polymer volumes. Pricing stratifies across premium certified grades, standard industrial formulations, and economy bulk tenders, with differentiation driven by REACH registration status and digital dosing platform bundling. Cost compression in economy powder segments intensifies as Chinese manufacturers expand export capacity. Agricultural distributors exhibit highest price sensitivity; oil and gas operators show lowest sensitivity due to produced water disposal economics.
Supply Chain Analysis
Direct-to-municipality channels handle framework agreement volumes in Germany and Finland, while distributor networks serve fragmented industrial accounts across India and China's provincial manufacturing zones. Manufacturing concentrates in France, China, and the United States, with acrylamide monomer production anchoring cost structures. Feedstock draws from propylene derivatives and natural gas feedstocks, with bio-based starch and chitosan alternatives emerging. Single-source vulnerability concentrates around SNF Group's acrylamide dominance, creating qualification risk for independent compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into acrylamide monomer production represents the decisive upstream lever in this vertical-integration race, separating cost-competitive scale players from margin-compressed compounders.
For Market Incumbents: Deploy digital dosing platform subscriptions to lock in municipal utility relationships against emerging bio-based substitute threats. Capture backward integration into acrylamide monomer production to defend feedstock margins against propylene price volatility. Expand REACH registration dossiers ahead of compliance deadlines to freeze out mid-tier competitors with multi-year preparation burdens. For New Entrants and Emerging Players: Digital-channel routes through SaaS-enabled dosing platforms offer low-capital entry into India's Smart Cities Mission procurement pipelines. Target secondary city wastewater infrastructure in Maharashtra and Gujarat where qualified polymer suppliers remain scarce. Qualify temperature-tolerant molecular architectures for China's zero-liquid-discharge coal-chemical clusters as the most penetrable industrial segment. For Investors and Strategic Acquirers: Kemira's municipal subscription contract expansions in Helsinki and Tampere are the leading indicator that outcome-based pricing models are achieving procurement preference over bulk chemical tenders. Five-to-ten year viability favors specialty water treatment houses with digital platform assets over pure-play commodity manufacturers. Watch for ECHA registration timeline delays as the inflection signal for distressed acquisition opportunities among mid-tier European compounders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylamide Monomer | SNF Group's captive feedstock supply locks in cost advantage across global powder and emulsion networks. |
| Digital Dosing Platform Deployment | Kemira's real-time turbidity feedback systems in Nordic utilities create SaaS-like recurring revenue streams. |
| REACH Registration Dossier Expansion | Multi-year preparation timelines for new molecular architectures freeze capital in pre-revenue development phases. |
| Bio-Based Flocculant R&D Investment | BASF SE positions portfolio for EU carbon border adjustment preference asymmetry favoring renewable feedstocks. |
| Zero-Liquid-Discharge Qualification | Temperature-tolerant architectures secure technical approval for China's Jiangsu and Shandong coal-chemical clusters. |
Study Parameters
Independent corroboration across polymer plant managers, municipal procurement officers, and oilfield chemical specialists underwrites the qualitative findings, with secondary validation drawing from ECHA registration databases, EU customs trade flows, and SEC filings of listed chemical conglomerates. Bottom-up segmentation modeling triangulates against top-down macroeconomic drivers across the analysis window.
Historical reference periods anchor volume and value projections across the modeling period, with segmentation dimensions spanning product chemistry tier, end-use intensity, physical delivery form, and regional regulatory cluster. CAGRs derive from slope-consistent trajectory analysis incorporating acrylamide feedstock cost curves and municipal capital expenditure cycles as industry-specific inputs.
The model holds under stable REACH enforcement timelines and continued shale production volumes; deviation in EU carbon border adjustment phase-in schedules or Chinese zero-liquid-discharge mandate enforcement would shift demand trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Hypochlorous Acid Water Generator Market
Water & Sludge Treatment
Asia-Pacific Water Treatment Chemicals Market
Water & Sludge Treatment
India Water Treatment Market
Water & Sludge Treatment
India Water and Wastewater Treatment (WWT) Technology Market
Water & Sludge Treatment
Slurry Homogenizer Tank Market
Water & Sludge Treatment
Process Chemicals for Water Treatment Market
Water & Sludge Treatment
North America Water Treatment Chemicals Market
Water & Sludge Treatment
Oil and Gas Water Treatment Chemicals Market
Water & Sludge Treatment
Global Liquid Waste Management Market
Water & Sludge Treatment
Global Water Clarifiers Market
Water & Sludge Treatment
Africa Water Treatment Chemicals Market
Water & Sludge Treatment
Aquarium Water Treatment Market
Water & Sludge Treatment
Global Valves in Water and Wastewater Market
Water & Sludge Treatment
Water and Wastewater Treatment Technologies Market
Water & Sludge Treatment
Process Water Treatment Market
Water & Sludge Treatment
South America Water Treatment Chemicals Market