
 Global Flow Chemistry Market | 2026-2036
Global Flow Chemistry Market Size, Share, and Industry Trends Forecast 2026-2036
Global Flow Chemistry Market Foresight
Specialty chemical manufacturers are bifurcating from traditional pharmaceutical buyers as the fastest-growing demand archetype in flow chemistry procurement. Evonik leverages its integrated specialty chemicals portfolio to anchor European demand for modular flow systems. Corning Incorporated dominates advanced glass microreactor manufacturing through proprietary materials science capabilities. Syrris Ltd. specializes in bench-scale continuous flow instrumentation for academic and contract research markets.
Flow chemistry employs continuous reactor architectures—microreactors, mesoreactors, and millireactors with channel dimensions from 10 to 500 micrometers—to execute reactions under precisely controlled temperature, pressure, and residence time parameters, primarily enabling safer, more efficient chemical synthesis across industrial applications. Continuous flow technology leads commercial adoption due to established engineering protocols and scalable heat transfer advantages, while photochemical flow represents the fastest-expanding segment driven by green chemistry mandates and energy-efficient activation methods. Modular flow systems concentrate margin pools through turnkey integration services that reduce customer capital deployment risk.
The EPA enforces Risk Management Plan requirements that incentivize continuous processing to minimize hazardous inventory thresholds, while REACH compliance in Europe restricts batch-byproduct discharge and favors closed-loop flow architectures. ISO standards for process analytical technology further shape equipment interoperability and data integrity expectations. Stakeholders must monitor regulatory divergence between jurisdictions to align reactor certification and control system investments.
Market Dynamics
Specialty chemical manufacturers are displacing pharmaceutical incumbents as the primary demand engine, driven by EPA Risk Management Plan thresholds that penalize hazardous batch inventories and reward continuous flow architectures with reduced on-site chemical storage.
Growth Catalysts
- REACH discharge restrictions:ECHA enforcement against batch-byproduct effluent pushes European producers toward closed-loop microreactor systems with integrated solvent recovery loops.
- Photochemical activation methods:Energy-efficient radical generation under visible-light irradiation enables room-temperature bond formations previously requiring thermal hazards.
- German R&D clustering:Concentrated flow chemistry expertise around Ludwigshafen and Darmstadt creates knowledge spillovers accelerating modular system adoption across Central European contract manufacturers.
Market Restraints
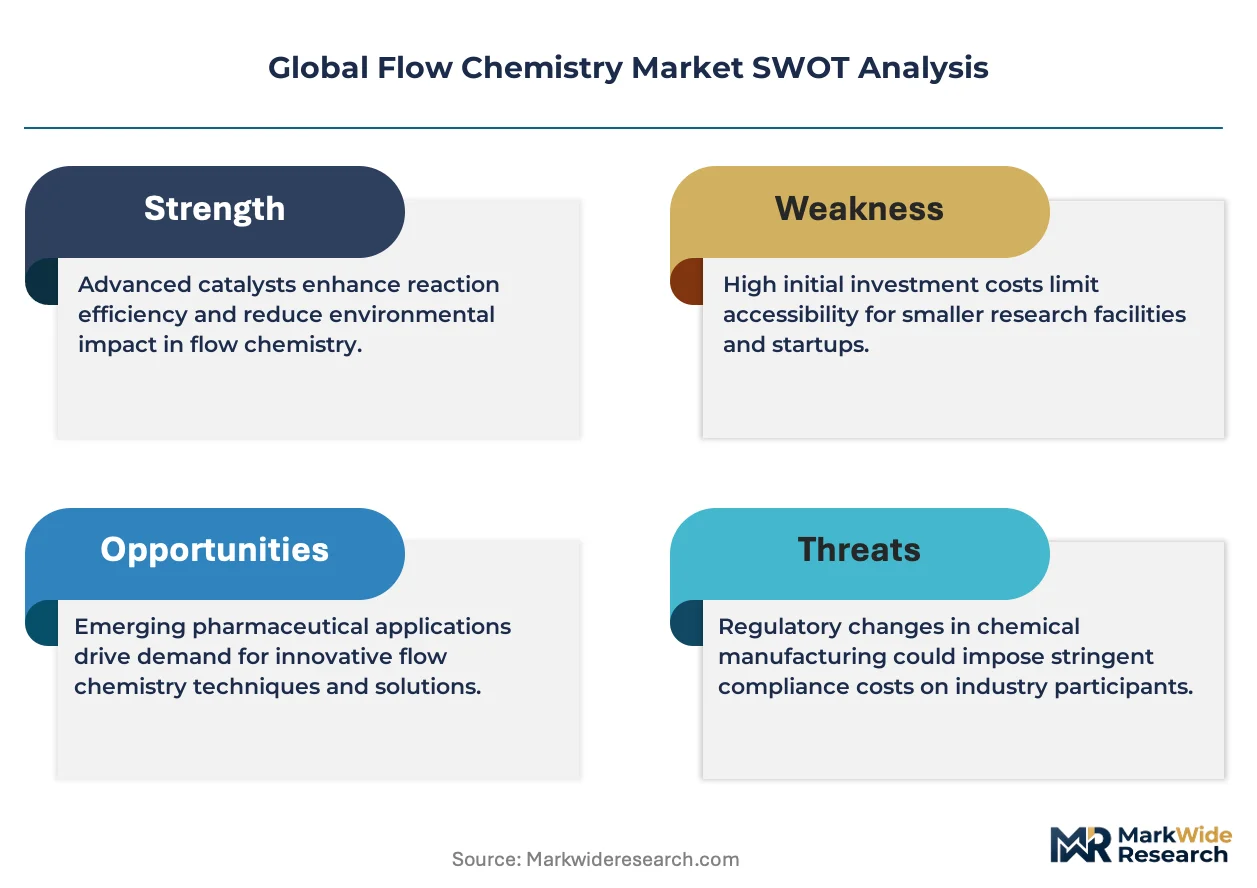
- High-purity borosilicate glass supply:Corning Incorporated maintains captive control over advanced microreactor substrate manufacturing, creating single-source dependency for sub-100 micrometer channel architectures.
- Specialized control engineering talent:Scarcity of process analytical technology programmers familiar with ISO 11339 data integrity protocols extends commissioning timelines for multi-step continuous trains.
- Fluoropolymer gasket cost volatility:Perfluoroelastomer seal prices fluctuate with semiconductor industry demand cycles, pressuring maintenance budgets for high-pressure flow systems.
Strategic Opportunities
- Indian pharmaceutical API synthesis:CDSCO's tightened environmental compliance deadlines for bulk drug manufacturing create retrofit demand for continuous processing among Hyderabad and Ahmedabad producers.
- Electrochemical-photochemical convergence:Paired electrolysis and LED irradiation in single microreactor platforms unlocks C-H functionalization routes inaccessible to thermal methods alone.
- Equipment-as-a-service channels:Modular flow system vendors are piloting performance-based leasing models that transfer scale-up risk from specialty chemical SMEs to technology providers.
Industry Challenges
- Legacy DCS integration complexity:Batch plant distributed control systems lack native protocols for real-time residence time adjustment, forcing expensive middleware development for hybrid facilities.
- Process safety certification timelines:ATEX and IECEx approvals for customized reactor geometries extend 14-18 months, delaying revenue recognition on bespoke pharmaceutical projects.
- Residence time distribution validation:Demonstrating narrow RTD for regulatory filings requires tracer studies that consume scarce engineering hours at contract research organizations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Flow Chemistry Market |
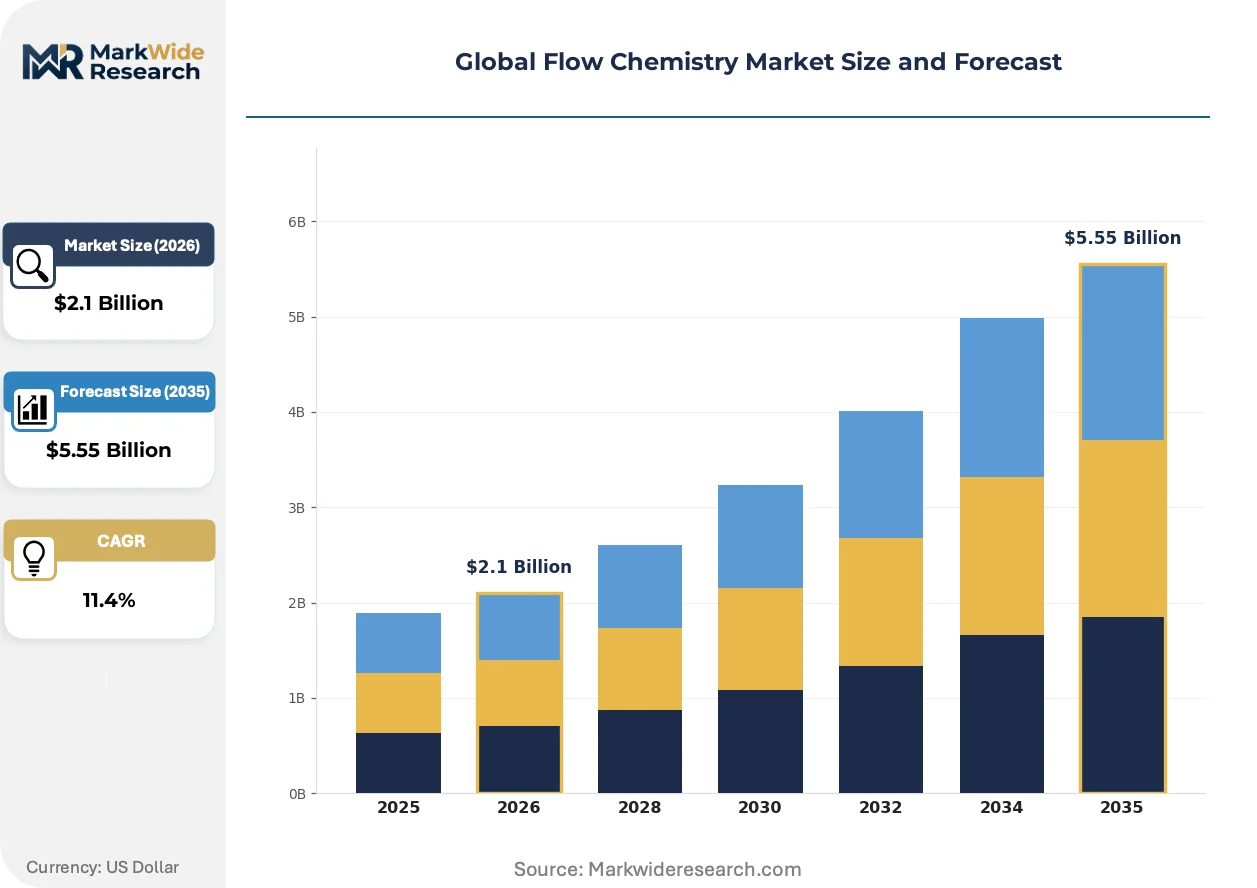
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $5.55 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microreactors, Mesoreactors, Millireactors, Nanoreactors, Modular Flow Systems Application: Pharmaceutical Synthesis, Agrochemical Production, Specialty Chemicals, Fine Chemicals, Petrochemical Processes Technology: Continuous Flow, Segmented Flow, Droplet Flow, Photochemical Flow, Electrochemical Flow End User: Contract Research Organizations, Chemical Manufacturers, Biotech Firms, Academic Institutions |
| Companies Covered | Evonik, Syrris Ltd., Corning Incorporated, Chemtrix BV, Vapourtec Ltd., Thermo Fisher Scientific, ThalesNano Inc., AM Technology, GMM Pfaudler, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Flow Chemistry Market Shifts & Advancements
Flow chemistry equipment architectures are bifurcating between standardized modular platforms and application-specific integrated systems, with vendor business models diverging accordingly. This structural split is compressing margins on commodity microreactors while concentrating value capture in turnkey process development services.
Photochemical flow reactors are fragmenting the thermal activation monopoly in fine chemical synthesis. Pharmaceutical manufacturers are adopting LED-irradiated microchannels for photoredox catalysis at pilot scale. This technology is fragmenting traditional batch photochemistry into distributed, intensity-controlled unit operations that eliminate scale-up artifacts from light penetration limitations.
EPA enforcement of Risk Management Plan amendments is tightening hazardous inventory thresholds for highly toxic gases. Chemical producers are responding by substituting on-demand generation via continuous flow for bulk storage of phosgene and diazomethane precursors. The specialty chemical segment bears the heaviest compliance burden, with Texas and Louisiana facilities leading retrofit investments.
Contract research organizations are unbundling equipment procurement from process development services. Sponsors now engage separate vendors for reactor hardware and for route scouting, compressing traditional system supplier margins. This disintermediation is most advanced in the Boston-Cambridge biotech cluster, where dedicated flow chemistry CROs have captured method development workflows from integrated equipment vendors.
Global Flow Chemistry Market Segmentation
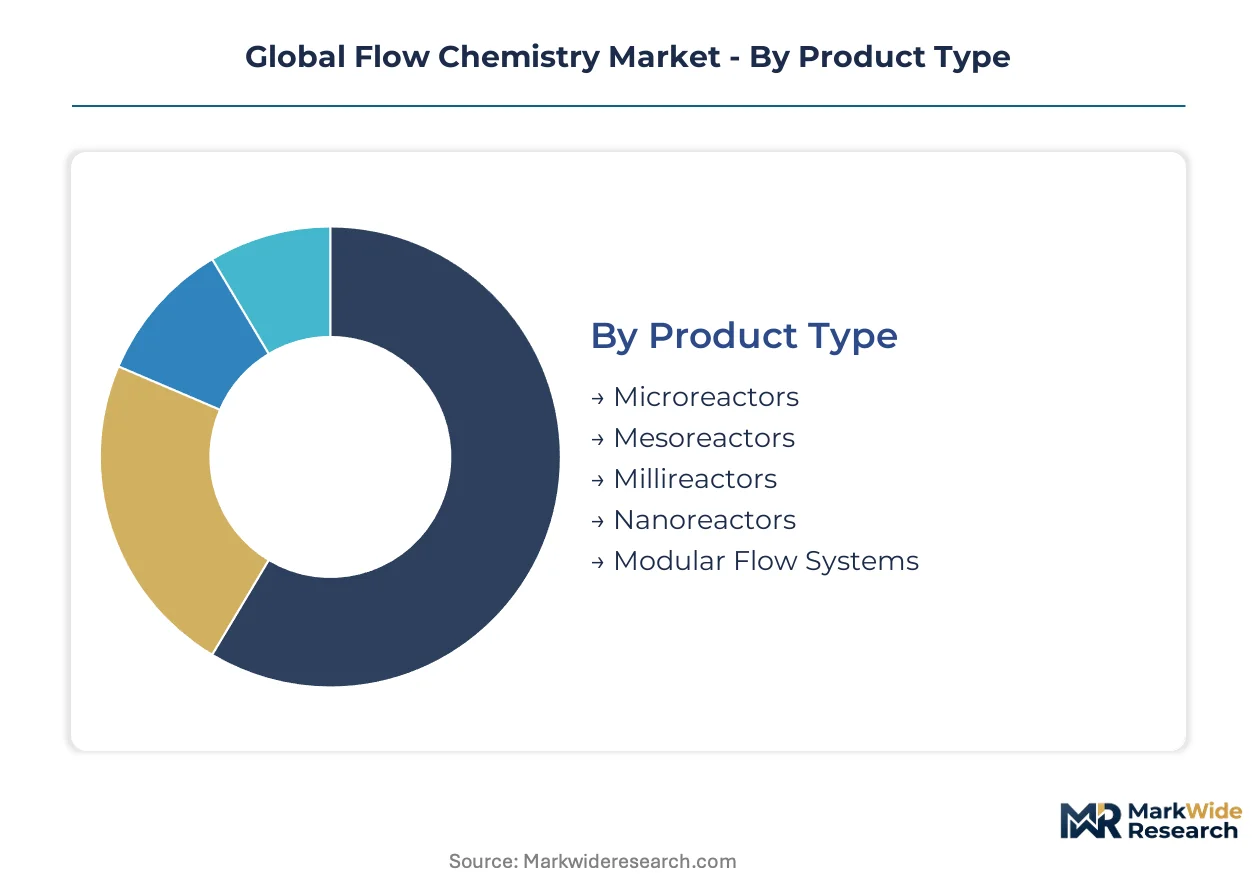
Flow chemistry market segmentation reveals how reactor architecture, activation method, and customer procurement patterns concentrate margin pools differently. Understanding these splits enables vendors to align R&D investment with where buyers actually pay premiums versus where commoditization pressures dominate.
Product Type:
Margin pools concentrate in systems that reduce customer capital deployment risk and accelerate regulatory qualification timelines.
- Microreactors:Glass or metal microfabricated channels below 1 millimeter enable precise thermal control for highly exothermic reactions. Pharmaceutical manufacturers in Germany and Switzerland deploy these for GMP-compliant API synthesis where batch safety margins prove inadequate. EPA Risk Management Plan thresholds for toxic gas inventory directly incentivize microreactor adoption over conventional stirred tanks.
- Modular Flow Systems:Turnkey skid-mounted configurations integrate pumps, heat exchangers, and in-line analytics for rapid deployment. Specialty chemical producers in Texas and Louisiana favor these for retrofitting existing batch plants without full greenfield construction. Equipment-as-a-service leasing models are emerging to transfer scale-up risk from SME buyers to technology providers.
- Mesoreactors:Intermediate channel dimensions bridge laboratory development and production scale.
- Millireactors:Larger bore diameters accommodate slurry-phase chemistry and solid handling.
- Nanoreactors:Sub-micron channel architectures serve analytical and high-throughput screening applications.
Microreactors hold installed capacity. Modular Flow Systems is rotating up the share rankings.
Application:
Application segmentation tracks where regulatory enforcement intensity and process safety liability create procurement urgency.
- Specialty Chemicals:Continuous processing replaces batch operations for intermediates, catalysts, and performance materials. Evonik and BASF deploy flow systems for polymer additives and electronic-grade solvents where REACH discharge restrictions penalize effluent variability. The segment leads retrofit demand as legacy plants face ECHA enforcement actions.
- Pharmaceutical Synthesis:GMP-validated continuous manufacturing enables real-time release testing and reduced quality control hold times. FDA's emerging guidance on continuous manufacturing harmonizes with ICH Q13 standards, accelerating pilot investments by Boston-Cambridge biotech firms and Swiss pharmaceutical manufacturers.
- Agrochemical Production:High-volume herbicide and fungicide intermediates benefit from improved heat transfer at scale.
- Fine Chemicals:Custom synthesis for flavors, fragrances, and photographic chemicals employs flow for hazardous nitrations.
- Petrochemical Processes:Steam cracking and partial oxidation pilots test flow architectures for selectivity gains.
Pharmaceutical Synthesis commands qualification premiums. Specialty Chemicals is climbing the fastest on volume.
Technology:
Technology segmentation distinguishes between mature thermal methods and emerging activation modes reshaping synthetic route possibilities.
- Photochemical Flow:LED-irradiated microchannels enable visible-light photoredox catalysis at ambient temperature. Energy-efficient radical generation aligns with EU Green Deal decarbonization targets and eliminates thermal hazard classification for sensitive substrates. Pharmaceutical route scouting in Basel and Cambridge clusters increasingly defaults to photochemical conditions.
- Continuous Flow:Established thermal activation with precise residence time control dominates commercial installations. Engineering protocols for heat and mass transfer scaling are codified in ISO standards, reducing technical risk for conservative chemical manufacturers.
- Electrochemical Flow:Paired electrolysis in flow cells unlocks C-H functionalization without stoichiometric oxidants.
- Segmented Flow:Gas-liquid or liquid-liquid slug flow enhances mixing in multiphase reactions.
- Droplet Flow:Picoliter-scale compartmentalization serves high-throughput experimentation and digital microfluidics.
Continuous Flow holds installed capacity. Photochemical Flow is gaining share fastest.
End User:
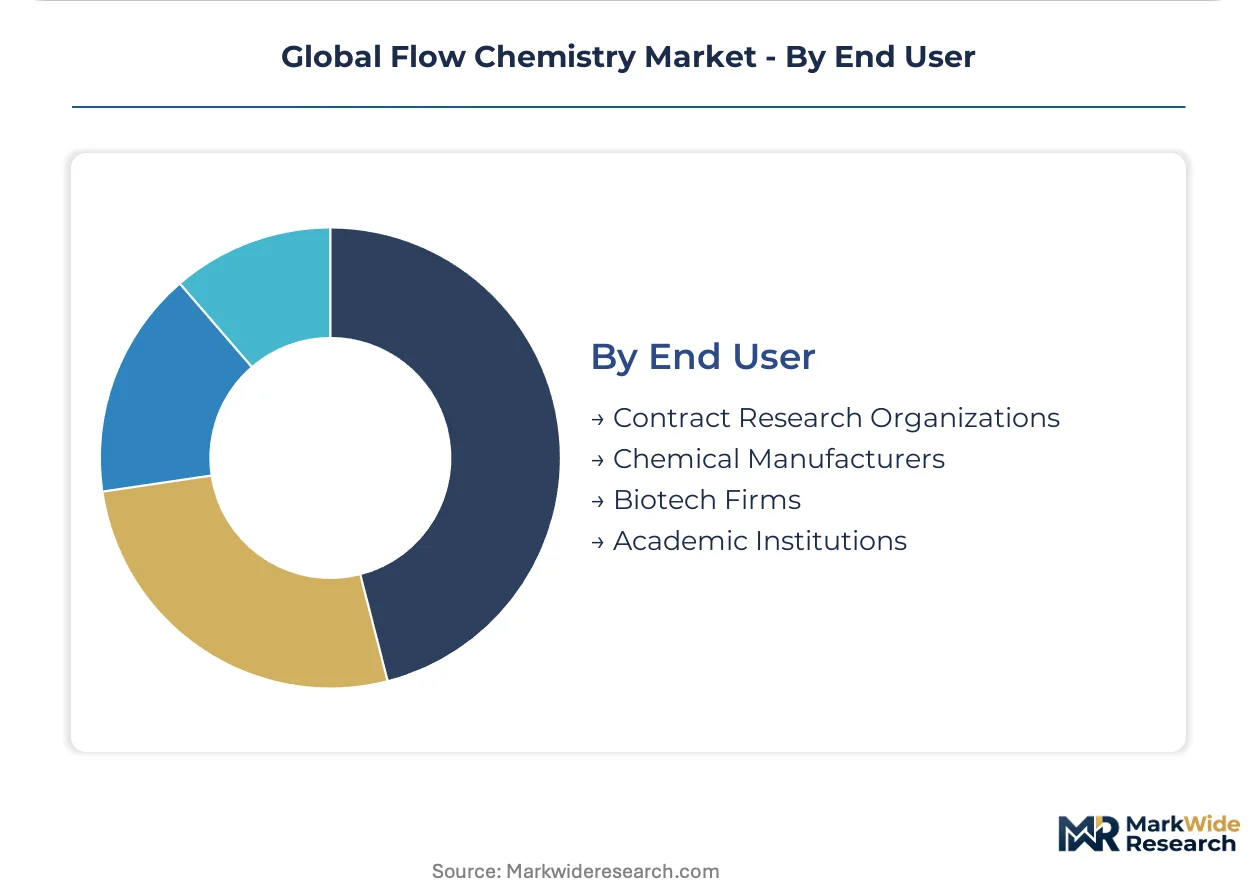
End user segmentation captures diverging procurement sophistication between research-driven and production-scale buyers.
- Chemical Manufacturers:Integrated producers and contract manufacturers drive volume demand with multi-reactor continuous trains. BASF's Ludwigshafen complex and Merck KGaA's Darmstadt facilities anchor European adoption, while Reliance and SABIC evaluate flow for Middle Eastern petrochemical expansion.
- Contract Research Organizations:Method development and route scouting services unbundle equipment from process expertise. Boston-Cambridge CROs now capture pharmaceutical flow chemistry workflows previously retained by integrated equipment vendors.
- Biotech Firms:Virtual pharmaceutical companies outsource manufacturing but retain process development in-house.
- Academic Institutions:Bench-scale instrumentation supports graduate training and fundamental mechanistic studies.
Chemical Manufacturers hold installed capacity. Contract Research Organizations is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German flow chemistry equipment exports supply pharmaceutical and specialty chemical producers across Switzerland, the United Kingdom, and the Netherlands. This trade corridor channels precision microreactor technology toward Basel's API synthesis cluster and Rotterdam's petrochemical hub.
United States
Texas and Louisiana specialty chemical facilities drive retrofit demand as EPA Risk Management Plan amendments tighten hazardous inventory thresholds for phosgene and diazomethane precursors. Houston-area producers substitute on-demand continuous flow generation for bulk storage. The Boston-Cambridge biotech corridor unbundles equipment procurement from process development services.
Germany
BASF's Ludwigshafen complex and Merck KGaA's Darmstadt facilities anchor European flow chemistry R&D concentration. REACH discharge restrictions penalize batch-byproduct effluent variability, pushing producers toward closed-loop microreactor architectures. Baden-Württemberg's contract manufacturers absorb knowledge spillovers from neighboring R&D centers.
Switzerland
Basel's pharmaceutical cluster deploys GMP-validated continuous manufacturing for real-time release testing. Swissmedic harmonizes with FDA and EMA guidance on continuous process validation. The Lake Geneva region concentrates photoredox catalysis route scouting for complex API intermediates.
India
Hyderabad and Ahmedabad bulk drug manufacturers face CDSCO environmental compliance deadlines for API synthesis operations. Continuous processing retrofits address effluent discharge restrictions at legacy fermentation and chemical synthesis plants. The Telangana-Andhra Pradesh corridor attracts modular flow system vendors piloting equipment-as-a-service models.
China
Yangtze River Delta pharmaceutical producers evaluate continuous manufacturing for export-oriented API production. NMPA alignment with ICH Q13 standards accelerates pilot investments at Shanghai and Suzhou facilities. Domestic microreactor fabricators challenge imported glass and metal channel architectures on cost.
Global Flow Chemistry Market Competitive Landscape
Player mix skews toward materials-science specialists and modular system integrators with divergent margin capture models. Market structure concentrates around captive substrate control and turnkey process development services. Two strategic archetypes dominate: proprietary microreactor substrate manufacturers and unbundled method development service providers. Competitive moves center on performance-based leasing pilots and middleware partnerships for legacy DCS integration.
Within the materials-science archetype, Corning Incorporated represents captive control over advanced borosilicate glass microreactor manufacturing. Among European modular system specialists, Syrris Ltd. and Chemtrix BV occupy positions serving bench-scale academic and contract research markets. Evonik exemplifies integrated specialty chemical producers leveraging internal demand to anchor technology adoption. These named entities illustrate how vendor business models diverge between standardized platform sales and application-specific integrated systems.
| Leading Market Players |
|---|
| Evonik |
| Syrris Ltd. |
| Corning Incorporated |
| Chemtrix BV |
| Vapourtec Ltd. |
| Thermo Fisher Scientific |
| ThalesNano Inc. |
| AM Technology |
| GMM Pfaudler |
| Others |
Supply & Pricing Matrix
ISO 11339 data integrity certification gates both microreactor supplier qualification and price differentiation simultaneously, with compliant vendors commanding premiums for GMP-validated continuous manufacturing systems while non-certified competitors compete on equipment-only economics.
Pricing Analysis
Current-generation photochemical flow reactors with integrated LED arrays command 40-60% premiums over prior-generation thermal microreactors, while next-generation electrochemical-photochemical hybrid platforms remain in pilot pricing. Three-tier pricing structure across premium GMP-validated, standard industrial-grade, and economy bench-scale levels separates pharmaceutical manufacturers from specialty chemical producers from academic buyers. Cost compression in economy-tier glass microreactors is intensifying because Chinese fabricators challenge Corning's captive borosilicate substrate control. Academic and contract research organizations exhibit highest price sensitivity, while GMP-validated pharmaceutical buyers prioritize qualification timelines over unit economics.
Supply Chain Analysis
Strategic stockpiling of high-purity borosilicate glass substrates and perfluoroelastomer gaskets dominates inventory strategy over just-in-time approaches, given Corning's single-source control over sub-100 micrometer channel architectures and semiconductor-industry demand cycles for fluoropolymer seals. Manufacturing concentration centers on Germany for precision microfabrication, the United States for modular system integration, and China for cost-competitive glass and metal channel production. Raw material dependencies draw from specialty glass precursors, high-performance fluoropolymers, and precision pump components. Single-source vulnerability for advanced microreactor substrates constitutes the primary structural risk. Distribution runs through direct vendor relationships for large chemical manufacturers and specialized laboratory distributors for academic and CRO segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flow chemistry sits in early-cycle expansion as EPA Risk Management Plan amendments and REACH discharge restrictions simultaneously tighten hazardous inventory thresholds across multiple jurisdictions, accelerating retrofit demand from legacy batch facilities.
For Market Incumbents: Secure captive control over advanced borosilicate glass microreactor substrate manufacturing through backward integration into materials science capabilities, defending against Chinese fabricator cost challenges. Lock in long-term perfluoroelastomer supply agreements to buffer semiconductor-industry demand cycle volatility for gasket components. Prioritize middleware partnerships for legacy DCS integration to capture hybrid facility retrofit demand.
For New Entrants and Emerging Players: Differentiate on equipment-as-a-service leasing models that transfer scale-up risk from specialty chemical SMEs to technology providers, capturing price-sensitive segments incumbents ignore. Target Indian pharmaceutical API manufacturers facing CDSCO environmental compliance deadlines in Hyderabad and Ahmedabad as the most penetrable geography. Lead with turnkey process development services rather than hardware-only sales to unbundle procurement patterns.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across modular flow system segments as performance-based leasing models reduce customer capital deployment requirements and compress working capital needs. Five-to-ten-year viability favors vendors with integrated materials-science capabilities and regulatory qualification expertise rather than commodity equipment fabricators. Monitor CDSCO enforcement action intensity in India and EPA Risk Management Plan amendment implementation timelines as primary inflection indicators for retrofit demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Borosilicate Substrate Manufacturing | Corning's captive materials science capabilities create defensive moats against Chinese cost competition in microreactor channels. |
| Equipment-as-a-Service Leasing Models | Performance-based contracts transfer scale-up risk from SME buyers to technology providers in specialty chemical segments. |
| Middleware Partnerships for Legacy DCS Integration | Hybrid batch-flow facilities require protocol translation layers that extend vendor relationship lock-in and service revenue. |
| Photochemical Flow Platform Development | LED-irradiated microchannels align with EU Green Deal decarbonization targets and unlock ambient-temperature synthesis routes. |
| Indian Market Localization | CDSCO compliance deadlines for Hyderabad and Ahmedabad bulk drug manufacturers create immediate retrofit demand for continuous processing. |
Research Methodology
Initial hypotheses were tested against primary input from plant managers at specialty chemical facilities, procurement leads at pharmaceutical manufacturers, technical R&D directors at modular system vendors, and regulatory affairs specialists familiar with EPA Risk Management Plan and REACH compliance, and refined through secondary validation against SEC 10-K filings, customs and trade data from Germany and United States, ECHA enforcement action records, and ACC and Cefic industry reports. Bottom-up equipment shipment analysis triangulated against top-down chemical industry capital expenditure surveys.
Variance-decomposition across reactor architecture, activation method, end-use industry, and geographic regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macro chemical production indices. Industry-specific forecast inputs incorporated EPA enforcement timeline assumptions for Risk Management Plan amendments and ECHA discharge restriction implementation patterns.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement intensity or accelerated Chinese fabricator market entry would require recalibration. Forecasts reflect documented assumptions regarding specialty chemical retrofit propensity and pharmaceutical continuous manufacturing adoption curves. Revision becomes warranted when CDSCO enforcement action intensity or EPA penalty structure modifications cross thresholds that alter buyer procurement urgency.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Non-Corrosive Fluxes Market
Industrial Chemicals
Anti-Corrosive Agents Market
Industrial Chemicals
Calciner Market
Industrial Chemicals
Cooling Tower Chemicals Market
Industrial Chemicals
South Africa Gypsum Plaster Market
Industrial Chemicals
Swimming Pool Salt Chlorinator Market
Industrial Chemicals
Glycidyl Ether Market
Industrial Chemicals
N-Ethyl-2-Pyrrolidone Market
Industrial Chemicals
Tall Oil Fatty Acid Market
Industrial Chemicals
Global Substrate Market
Industrial Chemicals
Wire Compound and Cable Compound Market
Industrial Chemicals
1,3-Propanediol (PDO) Market
Industrial Chemicals
India Precipitated Silica Market
Industrial Chemicals
Global High Throughput Process Development Market
Industrial Chemicals
Diesel Exhaust Fluid Market
Industrial Chemicals
Pulp and Paper Enzymes Market