
 2,6-Dichloro Aniline Market | 2026-2036
2,6-Dichloro Aniline Market Size, Share, and Industry Trends Forecast 2026-2036
2,6-Dichloro Aniline Market Analytics
Specialized chlorination chemist availability is collapsing across Western manufacturing bases, forcing agrochemical and dye makers to recalibrate supplier geography. Aarti Industries leverages its Gujarat-based integrated chlor-alkali complex to sustain captive aniline derivative output. BASF SE anchors European supply through Ludwigshafen infrastructure, while Wanhua Chemical Group Co., Ltd. dominates Chinese volume through Yantai operations.
2,6-Dichloro Aniline denotes an aromatic amine with chlorine substituents at the ortho positions relative to the amino group, typically manufactured via catalytic chlorination of aniline or reduction of 2,6-dichloronitrobenzene with specifications demanding minimum purity thresholds for downstream pharmaceutical and crop protection synthesis. Industrial Grade material leads volume throughput for bulk dye and agrochemical intermediates, while Reagent Grade commands concentrated margin pools from pharmaceutical API developers requiring sub-ppm impurity profiles. Application demand in Agrochemicals outpaces Dyes as herbicide resistance management intensifies multi-site active ingredient development.
EPA oversight of chlorinated aromatic discharge under TSCA shapes US market access requirements, while REACH registration obligations in Europe elevate analytical documentation burdens for importers. China's MEE enforces wastewater COD limits that filter smaller chlorination shops from the supplier base. Stakeholders must weigh regulatory compliance cost trajectories against regional manufacturing labor constraints when siting new derivative capacity.
Market Dynamics
Specialized chlorination chemist scarcity across Western manufacturing bases is forcing agrochemical and dye makers to recalibrate supplier geography and consolidate procurement relationships with integrated producers.
Growth Catalysts
- Herbicide resistance management protocols:Multi-site active ingredient development is accelerating demand from crop protection formulators seeking alternatives to single-mode herbicides.
- REACH and RoHS compliance tightening:European purity specifications are elevating analytical documentation burdens that filter out marginal suppliers and concentrate volume with qualified producers.
- India's PLI scheme for chemicals:Domestic agrochemical intermediate manufacturing incentives are anchoring regional procurement patterns around Gujarat and Maharashtra chemical clusters.
Market Restraints
- Aniline feedstock volatility:Benzene and chlorine input cost swings compress margin predictability for non-integrated chlorination operators.
- China supply concentration:Yantai and Jiangsu-based producers control disproportionate global volume, creating single-source vulnerability for European and North American formulators.
- Fluorinated aromatic substitution:Trifluralin and related fluorinated herbicides are displacing chlorinated aniline derivatives in certain soil-applied applications.
Strategic Opportunities
- Brazilian agrochemical formulation expansion:ANVISA registration streamlining for generic crop protection products is opening import channels for certified intermediate suppliers.
- Continuous flow chlorination technology:Microreactor-based production is enabling smaller-batch pharmaceutical-grade output with sub-ppm impurity profiles.
- EU Green Deal sustainable chemistry incentives:Bio-based aniline feedstock development programs are creating qualification pathways for low-carbon footprint derivatives.
Industry Challenges
- Specialized chlorination workforce attrition:Experienced aromatic substitution chemists are retiring faster than training programs replace them in Germany and the United States.
- Multi-jurisdiction REACH-TSCA registration synchronization:Divergent data requirements between ECHA and EPA are extending commercialization timelines for new derivative specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 2,6-Dichloro Aniline Market |
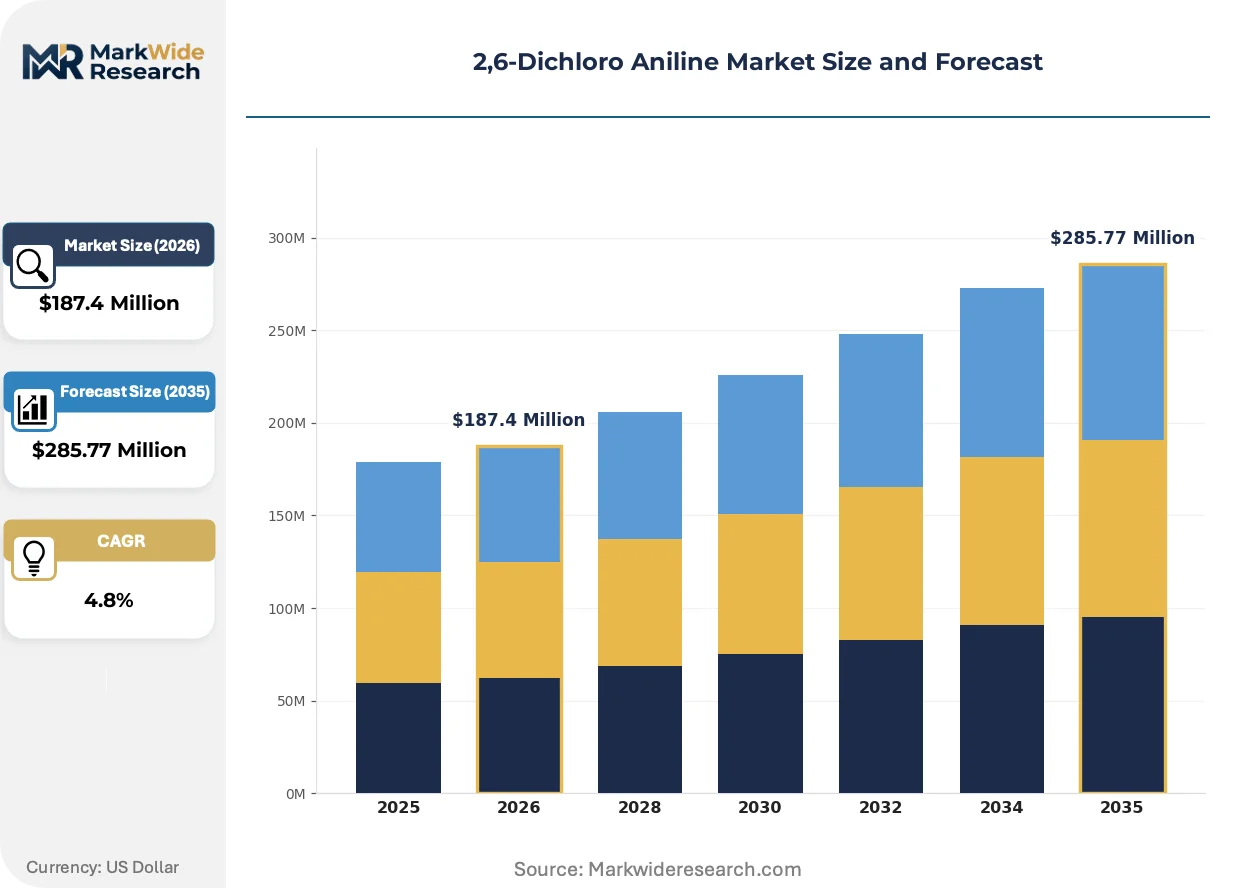
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Laboratory Grade, Reagent Grade, Research Grade Application: Dyes, Pharmaceuticals, Agrochemicals, Chemicals End User: Chemical Manufacturers, Pharmaceutical Companies, Research Institutions, Agriculture Sector Form: Liquid, Powder, Crystalline, Granular |
| Companies Covered | Huangshan Basihui Chemical Auxiliary, Aarti Industries, Shiva Pharmachem Ltd, Suzhou Hualun Chemical, Sinopec Shanghai Petrochemical Company Limited, Wanhua Chemical Group Co., Ltd., BASF SE, Huntsman International LLC, Covestro AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
2,6-Dichloro Aniline Market Evolving Landscape
Process intensification and regulatory data harmonization are actively compressing the viable producer set while opening technical pathways for differentiated purity grades in pharmaceutical applications.
Continuous flow microreactor chlorination is decomposing the traditional batch-reactor paradigm for high-purity 2,6-Dichloro Aniline synthesis. Pharmaceutical API developers in Basel and Boston are adopting this technology for sub-500 kg campaigns requiring sub-ppm chlorinated byproduct control. The shift is decomposing capital barriers for boutique producers while concentrating bulk agrochemical volume with large-scale integrated operators.
ECHA's REACH substance evaluation roadmap is extending compliance documentation requirements for chlorinated aromatic amines through 2027. Downstream formulators now demand full analytical datasets covering persistent organic pollutant screening and endocrine disruption potential. Agrochemical end-uses face the steepest re-registration burdens, pushing several European dye intermediates toward Asian manufacturing bases.
Certification-driven supplier consolidation is restructuring procurement relationships around qualified producer lists rather than spot-market purchasing. Tier-one agrochemical multinationals in Ludwigshafen and Basel are narrowing approved vendor pools to three to five integrated chlor-alkali operators. This pattern is most visible in herbicide active ingredient supply chains serving Latin American soybean protection markets.
2,6-Dichloro Aniline Market Segmentation
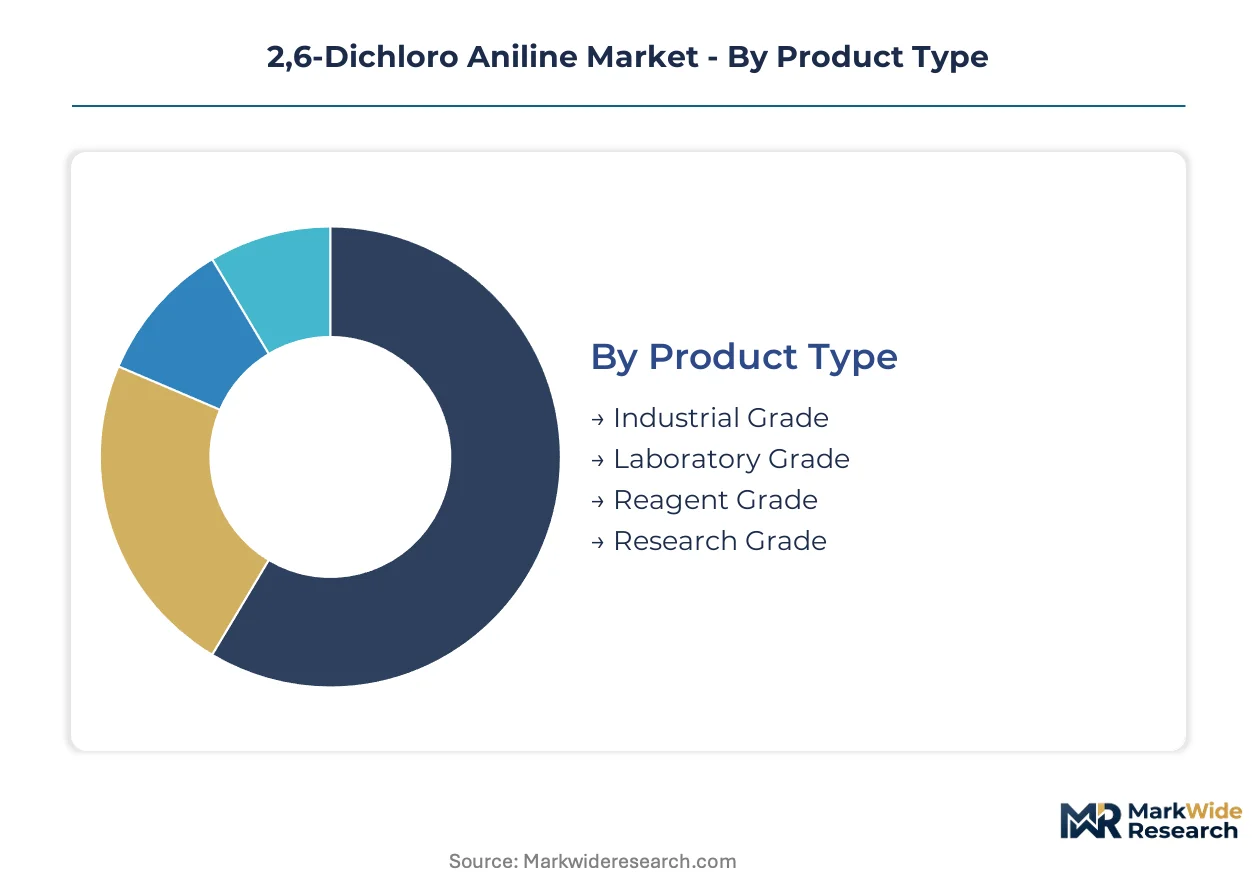
Segmentation in 2,6-Dichloro Aniline markets separates captive industrial consumption from export-oriented specialty grades. Procurement patterns diverge sharply between bulk agrochemical formulators and pharmaceutical API developers with divergent purity requirements.
Product Type:
Industrial Grade shipments dominate domestic consumption within integrated chemical clusters. Laboratory and Reagent grades flow disproportionately to export channels serving regulated pharmaceutical markets.
- Industrial Grade:Specifications typically specify 98-99% purity with controlled moisture content for bulk dye and agrochemical intermediate synthesis. Demand concentrates in Gujarat and Jiangsu province chemical parks where captive chlor-alkali integration supports continuous multi-tonne campaigns for herbicide active ingredient manufacturers.
- Reagent Grade:Sub-ppm impurity thresholds characterize this tier, with full analytical documentation for persistent organic pollutant screening and endocrine disruption potential. Basel and Boston pharmaceutical API developers drive procurement through qualified supplier lists rather than spot-market purchasing, with ECHA REACH compliance documentation extending through 2027.
- Laboratory Grade:Mid-tier purity specifications serve analytical calibration and method development in university and government research facilities.
- Research Grade:Small-batch output for exploratory chemistry programs with flexible specification tolerances and minimal regulatory documentation burdens.
Industrial Grade commands the established base. The steepest expansion runs through Reagent Grade.
Application:
Cost tier separation distinguishes commodity intermediate consumption from premium active ingredient development. Agrochemical formulators prioritize scale economies while pharmaceutical developers absorb purity premiums.
- Agrochemicals:Herbicide resistance management protocols accelerate multi-site active ingredient development. Brazilian soybean protection markets and Indian rice cultivation drive volume concentration, with ANVISA registration streamlining opening import channels for certified intermediate suppliers.
- Dyes:Azo and anthraquinone intermediate synthesis consumes bulk chlorinated aniline derivatives. European dye manufacturers face steepest REACH re-registration burdens, pushing several intermediate lines toward Asian manufacturing bases in Yantai and Jiangsu.
- Pharmaceuticals:API synthesis for anti-inflammatory and antimicrobial compounds requires sub-ppm chlorinated byproduct control.
- Chemicals:General organic synthesis and custom manufacturing applications span diverse purity requirements without sector-specific regulatory overlays.
Dyes retain volume leadership. Agrochemicals gain share fastest.
End User:
Customer type determines procurement relationship structure. Integrated chemical manufacturers favor long-term contracts while research institutions operate through distributor channels.
- Chemical Manufacturers:Captive chlorination capacity at Aarti Industries and Wanhua Chemical anchors procurement around backward-integrated supply chains. Ludwigshafen and Yantai operations concentrate volume with three to five approved vendor pools per multinational formulator.
- Pharmaceutical Companies:FDA and EMA filing requirements enforce supplier qualification rigor. Continuous flow microreactor technology is decomposing capital barriers for boutique producers serving sub-500 kg campaigns.
- Research Institutions:Fragmented demand across university and government laboratories with minimal volume concentration.
- Agriculture Sector:Direct procurement by large-scale farming cooperatives remains limited; intermediates flow through formulated product channels.
Chemical Manufacturers anchor procurement volume. Pharmaceutical Companies expand most quickly.
Form:
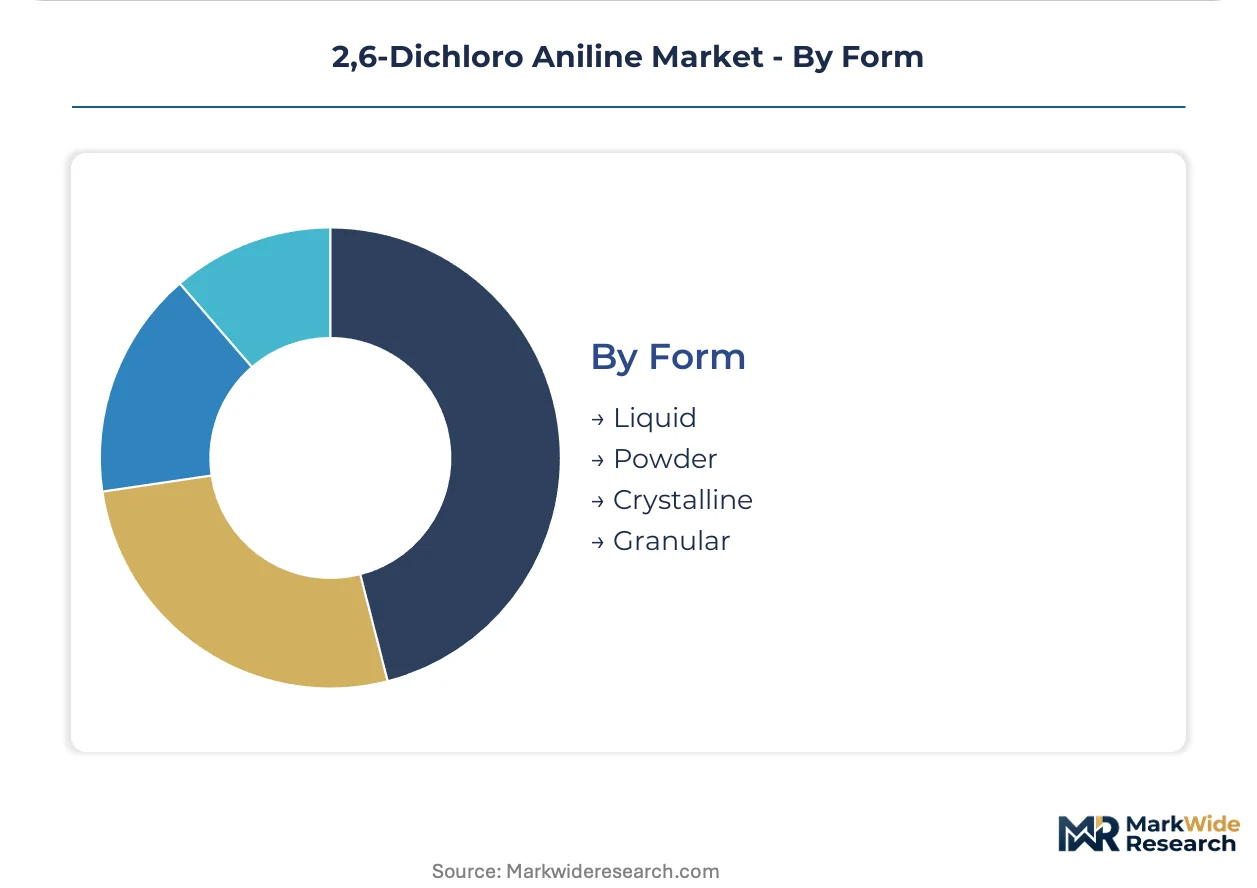
Supply concentration favors liquid and powder outputs from continuous production infrastructure. Crystalline and granular forms require secondary processing with limited producer participation.
- Liquid:Molten or dissolved states facilitate pipeline transfer within integrated chemical complexes. Gujarat chlor-alkali clusters favor liquid handling for direct downstream chlorination sequences.
- Powder:Spray-dried output serves bulk dye intermediate and agrochemical technical manufacturing with standardized packaging for containerized shipment.
- Crystalline:Purified solid state for pharmaceutical API synthesis with defined particle size distribution and polymorph control.
- Granular:Low-dust formulation for specialized handling requirements in automated manufacturing lines.
Liquid and Powder dominate throughput. Crystalline commands premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MEE enforces wastewater COD limits that filter smaller chlorination shops from the supplier base. Demand concentrates in integrated chemical clusters where captive chlor-alkali capacity anchors regional procurement.
China
Yantai and Jiangsu province operations dominate volume throughput for bulk agrochemical intermediates. MEE wastewater discharge standards are eliminating marginal producers without tertiary treatment infrastructure. The Yangtze River Delta chemical parks concentrate backward-integrated capacity serving herbicide active ingredient manufacturers.
India
Gujarat-based chlor-alkali complexes sustain captive aniline derivative output for domestic formulators. The PLI scheme for chemicals provides manufacturing incentives anchoring regional procurement around Gujarat and Maharashtra clusters. CDSCO registration requirements are tightening documentation standards for pharmaceutical-grade exports.
Germany
Ludwigshafen infrastructure anchors European supply through REACH-compliant integrated operations. ECHA substance evaluation roadmaps are extending compliance documentation requirements through 2027. The BASF SE complex maintains qualified supplier status for tier-one agrochemical multinationals.
United States
EPA oversight of chlorinated aromatic discharge under TSCA shapes market access requirements for importers. The Gulf Coast petrochemical corridor offers feedstock integration for chlorination operators. FDA filing requirements enforce supplier qualification rigor for pharmaceutical API developers in Greater Boston.
Brazil
Soybean protection markets drive import demand for certified intermediate suppliers. ANVISA registration streamlining for generic crop protection products is opening import channels. The São Paulo formulation hub concentrates procurement relationships with Asian and European producers.
2,6-Dichloro Aniline Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the 2,6-Dichloro Aniline competitive structure. Chlor-alkali integration distinguishes volume players from toll manufacturers dependent on merchant feedstock. Three archetypes populate the landscape: backward-integrated chemical conglomerates, regional specialty intermediates producers, and pharmaceutical-grade boutique operators. Consolidation pressures favor capacity expansion and strategic partnerships over standalone R&D investments.
Among Indian integrated producers, Aarti Industries exemplifies the captive chlorination model with Gujarat-based infrastructure. Wanhua Chemical Group Co., Ltd. anchors Chinese volume positioning through Yantai operations. BASF SE occupies the European qualified supplier tier with Ludwigshafen REACH compliance infrastructure.
| Leading Market Players |
|---|
| Huangshan Basihui Chemical Auxiliary |
| Aarti Industries |
| Shiva Pharmachem Ltd |
| Suzhou Hualun Chemical |
| Sinopec Shanghai Petrochemical Company Limited |
| Wanhua Chemical Group Co., Ltd. |
| BASF SE |
| Huntsman International LLC |
| Covestro AG |
| Others |
Value Network & Pricing Analysis
Captive chlor-alkali scale at Yantai and Gujarat facilities anchors price floors for bulk agrochemical intermediates while filtering marginal toll manufacturers from viable supplier pools. REACH documentation burdens and MEE wastewater compliance costs stratify the market into qualified integrated producers commanding premium contract terms versus spot-market participants facing margin compression from benzene and chlorine feedstock volatility.
Pricing Analysis
Chinese export quotations for Industrial Grade material undercut European qualified-supplier pricing by substantial spreads, reflecting differential compliance cost burdens between MEE-monitored Yangtze River Delta operations and ECHA-registered Ludwigshafen infrastructure. Three-tier pricing structure across Reagent, Industrial, and Laboratory grades tracks certification depth and analytical documentation completeness. Cost compression in spot-market Industrial Grade transactions is intensifying because Indian PLI-supported domestic capacity is displacing import dependency for Gujarat-based formulators. Agrochemical technical manufacturers exhibit highest price sensitivity, while Basel and Boston pharmaceutical API developers absorb purity premiums for sub-ppm impurity profiles.
Supply Chain Analysis
Strait of Malacca transit underwrites containerized shipment economics for Chinese powder exports serving Brazilian soybean protection markets. Supply concentrates in China, India, and Germany, with Yantai and Jiangsu province operations feeding bulk agrochemical channels while Ludwigshafen infrastructure serves REACH-compliant European formulators. Raw material dependencies rest on merchant benzene, chlorine gas, and nitrobenzene reduction catalysts. Single-source vulnerability runs through Yantai-based volume concentration for non-integrated European and North American buyers. Distribution runs through long-term offtake contracts with approved vendor pools rather than spot-market purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certification-driven supplier consolidation is transforming procurement relationships into platform economics where interoperability with ECHA and EPA registration systems determines market access. REACH-TSCA data harmonization initiatives are reshaping competitive moats around documentation infrastructure rather than manufacturing scale alone.
For Market Incumbents: Shield qualified supplier status by accelerating REACH dossier updates ahead of ECHA substance evaluation roadmaps. Deepen captive chlorination capacity in Gujarat or Yantai chemical parks to offset benzene feedstock volatility. Fluorinated aromatic substitution in soil-applied herbicides poses direct displacement risk to chlorinated aniline derivative demand. For New Entrants and Emerging Players: Lead with continuous flow microreactor technology to serve sub-500 kg pharmaceutical campaigns requiring sub-ppm chlorinated byproduct control. Brazilian ANVISA registration streamlining for generic crop protection products represents the most penetrable geography for certified intermediate suppliers. Target qualification support services as a differentiated go-to-market angle for European formulators facing ECHA documentation burdens. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated chlor-alkali operators with captive aniline derivative output serving multi-year agrochemical supply agreements. Long-term viability across the projection horizon favors backward-integrated producers with MEE-compliant wastewater infrastructure over toll-dependent manufacturers. Signal to monitor: ECHA substance evaluation outcomes for chlorinated aromatic amines and their downstream impact on qualified supplier pool size.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlor-Alkali Capacity | Gujarat and Yantai chemical parks anchor margin control against benzene volatility. |
| Continuous Flow Microreactor Deployment | Basel and Boston pharmaceutical developers adopt sub-ppm impurity control technology. |
| REACH-TSCA Registration Synchronization | ECHA and EPA data harmonization compresses commercialization timelines for new specifications. |
| Long-Term Supply Agreement Structuring | Tier-one agrochemical multinationals narrow approved vendor pools to three to five operators. |
| Green Manufacturing Transition | EU Green Deal bio-based aniline programs create qualification pathways for low-carbon derivatives. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC filings, and ECHA registration databases with cross-validation against ACC and Cefic industry reports. Primary interviews engaged plant managers at chlor-alkali complexes, procurement leads at downstream agrochemical formulators, technical R&D directors in pharmaceutical API development, and distribution channel partners serving research institutions. Bottom-up volume modeling triangulates against top-down value estimates derived from trade flow analysis and capacity utilization assessments across integrated chemical clusters.
Segmentation dimensions modeled span grade tier (Industrial, Reagent, Laboratory, Research), end-use industry (Agrochemicals, Dyes, Pharmaceuticals, Chemicals), packaging format (liquid, powder, crystalline, granular), and regional production hub concentration. CAGRs derive from regression analysis of historical trade volumes against projected downstream demand from herbicide resistance management protocols and pharmaceutical pipeline advancement. Industry-specific forecast inputs incorporate MEE wastewater compliance cost trajectories and ECHA substance evaluation timeline assumptions.
Underlying assumptions cover sustained benzene-chlorine feedstock availability, REACH registration continuity for existing qualified suppliers, and ANVISA registration streamlining pace in Brazil, with deviation risk concentrated in fluorinated aromatic substitution rates and ECHA regulatory stringency escalations. Practitioners should keep alternative scenarios live as multi-jurisdiction registration synchronization and bio-based feedstock qualification pathways evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Chloro -Dimethylsilane (CAS 1066-35-9) Market
Organic Chemicals
2-Iodophenol Market
Organic Chemicals
Aliphatic Amines Market
Organic Chemicals
Cyclopentanone Market
Organic Chemicals
Europe Lactic Acid Market
Organic Chemicals
Synthetic and Bio-Based Aniline Market
Organic Chemicals
N-Hexanol Market
Organic Chemicals
Organic Rheological Modifiers Market
Organic Chemicals
Global Glycolic Acid Market
Organic Chemicals
Chlorocyclopentane Market
Organic Chemicals
DMDM Hydantoin Market
Organic Chemicals
Asia-Pacific Organic Acid Market
Organic Chemicals
Anisole Derivatives Market
Organic Chemicals
2-Methylbutanoic Acid Market
Organic Chemicals
Organic Polysulfide Market
Organic Chemicals
Dioctyl Maleate (DOM) Market