
 Oral Care Chemicals Market | 2026-2036
Oral Care Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Oral Care Chemicals Market Outlook
The EU Green Deal is restructuring procurement criteria for oral care chemical suppliers across European personal care value chains. Colgate-Palmolive Company leverages its captive formulation labs to pre-certify active ingredients against REACH amendments. Procter & Gamble Company anchors its surfactant sourcing through backward integration into North American oleochemical supply. Unilever PLC differentiates its oral care portfolio through dedicated R&D spending on enzymatic whitening precursors.
Oral care chemicals encompass active and auxiliary ingredients formulated into toothpaste, mouthwash, and dental gel preparations, including fluoride salts at 1,000–1,500 ppm therapeutic concentrations, peroxide-based bleaching agents, cationic antimicrobials, and encapsulated flavoring systems. These compounds function to prevent caries, reduce plaque accumulation, and deliver sensory acceptance in consumer and professional dental applications. Fluoride and whitening agents dominate volume demand, though antimicrobial segments capture disproportionate margin pools due to clinical validation requirements. Breath freshener applications represent the fastest-expanding application category, propelled by on-the-go consumption habits and portable format innovation.
FDA oversight of over-the-counter oral health products, EPA antimicrobial efficacy standards, and EU REACH chemical registration collectively determine market access and reformulation costs for active ingredient suppliers. The EU Medical Device Regulation and ISO 9001 quality management standards further constrain manufacturing site qualification for dental clinic-grade products. Stakeholders must monitor regulatory divergence between FDA monograph updates and EMA-style centralized assessments, as this gap will dictate where next-generation probiotic and prebiotic oral care chemicals receive first commercial approval.
Market Dynamics
The EU Green Deal's chemical sustainability targets are forcing wholesale reformulation across oral care supply chains, compressing timelines for bio-based surfactant qualification and tightening purity thresholds for fluoride salt imports.
Growth Catalysts
- EU REACH Amendment 2024:Tighter registration requirements for antimicrobial actives are accelerating investment in pre-certified manufacturing capacity across German and Dutch chemical parks.
- Enzymatic Whitening Precursors:Patent-protected peroxide alternatives are capturing professional dental clinic procurement in India's tier-1 urban markets.
- North American Oleochemical Supply:Captive backward integration into palm kernel and coconut oil derivatives is insulating major formulators from surfactant price volatility.
Market Restraints
- Fluoride Raw Material Concentration:Over 70% of sodium fluoride and sodium monofluorophosphate feedstock originates from Chinese industrial chemical zones, creating single-source vulnerability.
- EPA Antimicrobial Efficacy Standards:Extended validation timelines for cationic biocides delay new mouthwash ingredient commercialization by 18-24 months.
- Silica Abrasive Substitution:Synthetic amorphous silica faces displacement pressure from precipitated calcium carbonate in economy toothpaste tiers.
Strategic Opportunities
- Probiotic Oral Care Formulations:Lactobacillus and Bifidobacterium strain integration represents unclaimed white space in professional dental prophylaxis products.
- EU Medical Device Regulation (MDR) Certification:Clinic-grade fluoride gels with device-class designation command 40-60% price premiums over cosmetic-category competitors.
- Direct-to-Dental-Practice Distribution:Bypassing traditional pharmaceutical wholesalers through dedicated e-procurement platforms is compressing channel margins in Germany's dental clinic chains.
Industry Challenges
- Formulation Chemist Talent Scarcity:Cross-disciplinary expertise spanning cosmetic chemistry, microbiology, and regulatory affairs commands premium compensation and constrains R&D scaling.
- ISO 9001 Manufacturing Site Qualification:Dental clinic-grade production requires separate cleanroom infrastructure and quality management systems, doubling capital intensity versus consumer-grade facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oral Care Chemicals Market |
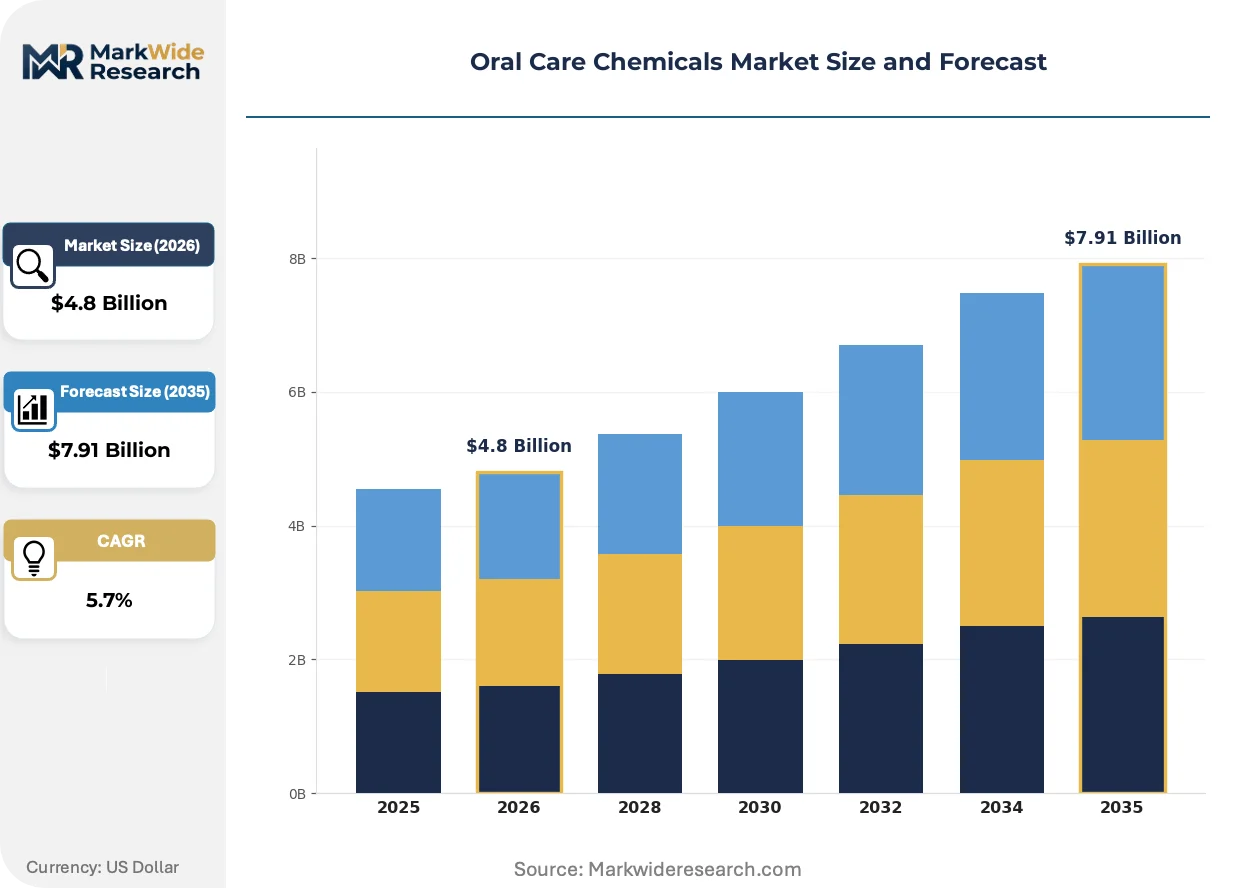
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fluoride, Whitening Agents, Antimicrobial, Flavoring Agents Application: Toothpaste, Mouthwash, Dental Gel, Breath Fresheners End User: Adults, Children, Seniors, Dental Clinics Distribution Channel: Online Retail, Supermarkets, Pharmacies, Specialty Stores |
| Companies Covered | Colgate-Palmolive Company, Procter & Gamble Company, Unilever PLC, Johnson & Johnson Services, Inc., GlaxoSmithKline plc, Church & Dwight Co., Inc., Henkel AG & Co. KGaA, Lion Corporation, Sunstar Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oral Care Chemicals Market Strategic Shifts
Biotechnology and enzymatic systems are displacing conventional peroxide chemistry across whitening applications, while regulatory fragmentation between FDA monograph and EMA assessment pathways is creating divergent product development tracks.
Encapsulated flavoring systems with time-release functionality are decentralizing sensory formulation from centralized flavor houses to in-house oral care R&D labs. Colgate-Palmolive and Unilever have established captive microencapsulation pilot lines in New Jersey and Rotterdam facilities. This technology is decentralizing procurement relationships that historically concentrated flavor development with Givaudan and Firmenich.
REACH authorization requirements for zinc-containing antimicrobial compounds are forcing substitution toward copper-based and quaternary ammonium alternatives. The industrial consequence is a 12-18 month reformulation cycle for existing mouthwash portfolios. Professional dental rinse products in Germany and France face the steepest compliance costs, with manufacturers pre-registering copper gluconate variants ahead of 2026 sunset dates.
Dental clinic chains in India are consolidating chemical procurement through centralized tendering platforms, displacing traditional distributor networks. Axiss Dental and Clove Dental now negotiate directly with Gujarat-based fluoride and surfactant manufacturers. This concentration is most visible in Mumbai and Bangalore, where clinic network expansion has compressed supplier margins by 15-20 percentage points versus independent practice channels.
Oral Care Chemicals Market Segmentation
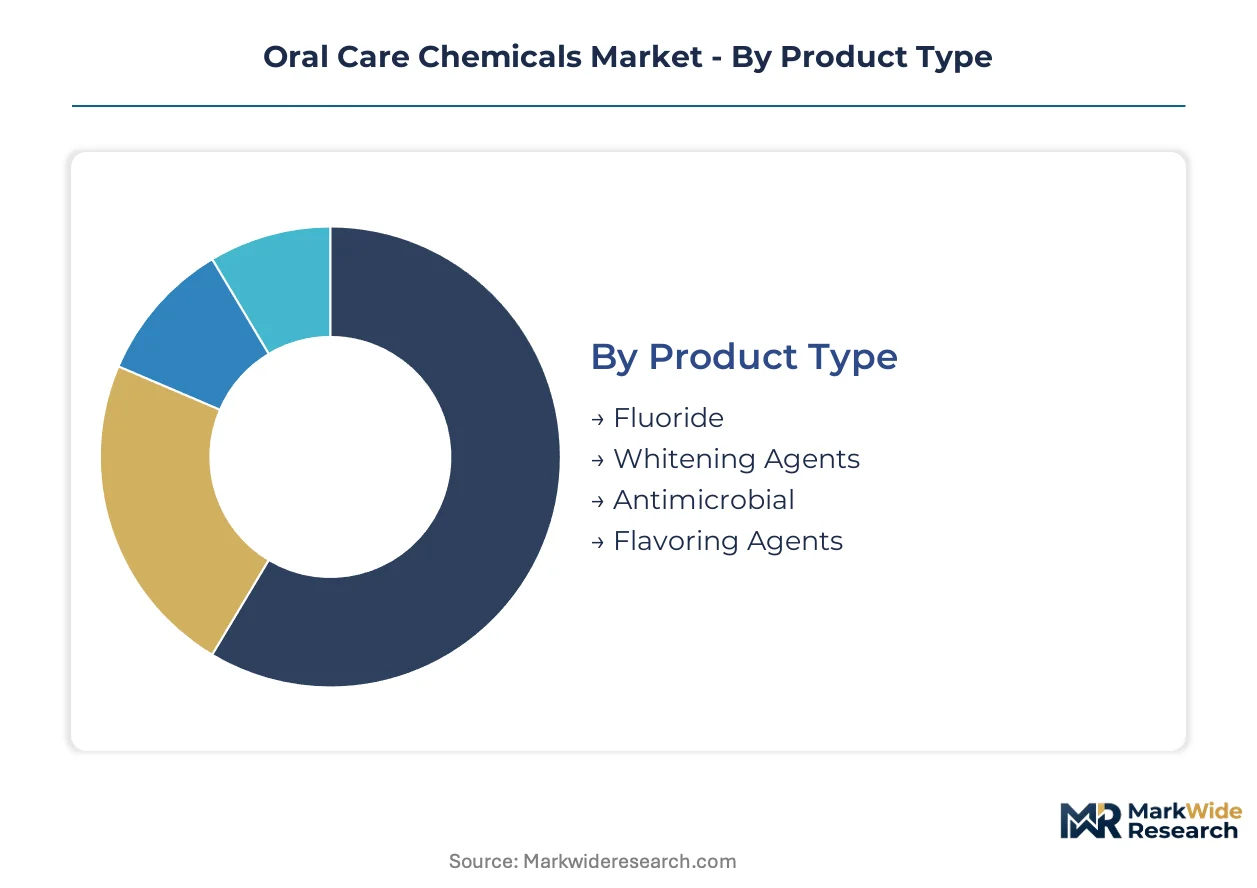
Oral care chemicals fragment across four distinct taxonomies that determine procurement patterns, margin structures, and regulatory exposure. Each segmentation axis reveals different competitive dynamics: product type governs R&D intensity, application dictates formulation complexity, end user shapes clinical validation requirements, and distribution channel determines pricing power.
Product Type:
Supply concentration for active ingredients varies dramatically by chemistry class, with fluoride salts showing the tightest upstream control.
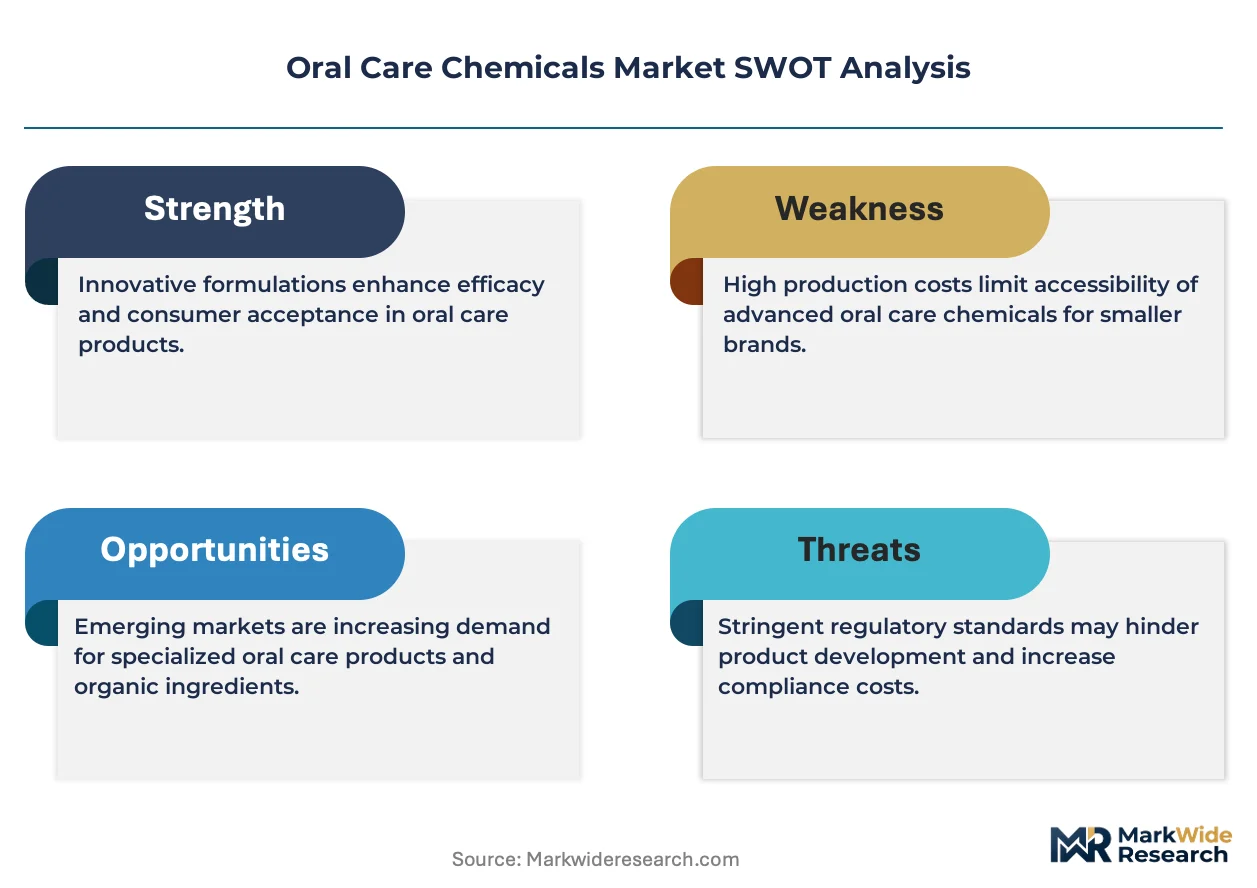
- Fluoride:Sodium fluoride and sodium monofluorophosphate dominate therapeutic formulations at 1,000–1,500 ppm concentrations. Chinese industrial zones control over 70% of global feedstock, creating single-source vulnerability for European and North American formulators.
- Whitening Agents:Peroxide-based bleaching compounds face displacement pressure from enzymatic precursors. Patent-protected alternatives are capturing professional dental clinic procurement in India's tier-1 urban markets.
- Antimicrobial:Cationic biocides and quaternary ammonium compounds require EPA efficacy validation cycles extending 18–24 months. REACH authorization pressures on zinc-based actives are accelerating copper gluconate substitution.
- Flavoring Agents:Encapsulated time-release systems are decentralizing procurement from traditional flavor houses toward captive oral care R&D labs.
Today's leader: Fluoride. Tomorrow's challenger: Whitening Agents.
Application:
Formulation sophistication escalates from mass-market toothpaste through professional dental gels, with margin pools inversely correlated to volume scale.
- Toothpaste:Volume-dominant segment where synthetic amorphous silica abrasives face displacement from precipitated calcium carbonate in economy tiers. German specialty manufacturers are expanding bio-based surfactant procurement.
- Mouthwash:Cationic antimicrobial integration drives regulatory complexity. EU REACH Amendment 2024 is accelerating pre-certified manufacturing investment across German and Dutch chemical parks.
- Dental Gel:Clinic-grade formulations with EU Medical Device Regulation certification command 40–60% price premiums over cosmetic-category competitors.
- Breath Fresheners:Portable format innovation and on-the-go consumption habits are expanding most quickly. This segment is gaining share fastest through convenience retail and travel channels.
Volume concentrates in toothpaste. Value concentrates in dental gel.
End User:
Clinical versus consumer end-use bifurcation determines quality management infrastructure requirements and regulatory pathway selection.
- Adults:Therapeutic concentration compliance and sensory acceptance drive formulation priorities. Whitening and antimicrobial claims dominate marketing differentiation.
- Children:Lower fluoride thresholds and flavor profile restrictions constrain chemistry selection. Safety documentation requirements exceed adult formulations.
- Seniors:Dry mouth and gingival sensitivity indications are expanding specialized product development. Enzymatic systems show particular compatibility with age-related oral conditions.
- Dental Clinics:ISO 9001 manufacturing site qualification and separate cleanroom infrastructure double capital intensity versus consumer-grade facilities. India's clinic chains are consolidating procurement through centralized tendering platforms.
Consumer segments drive volume. Dental clinics drive margin.
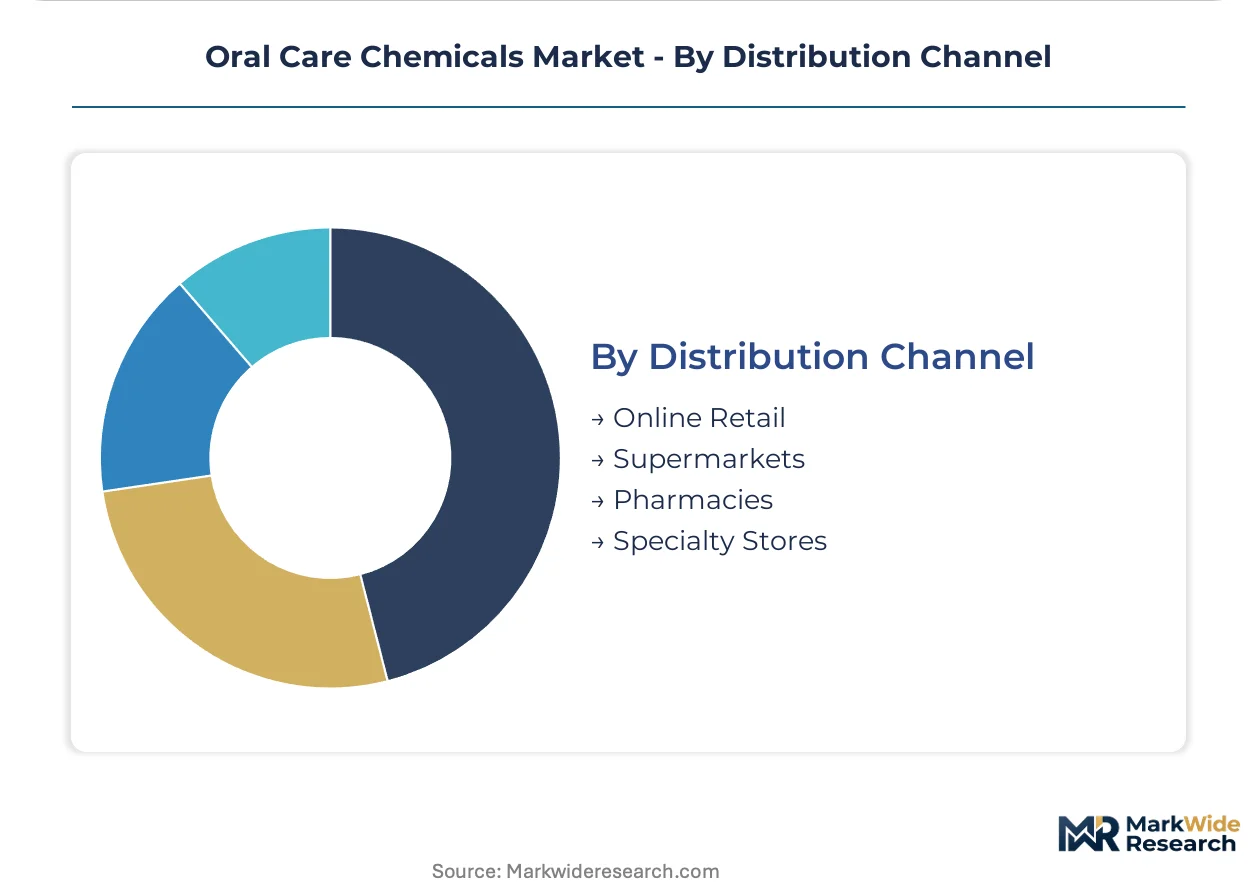
Distribution Channel:
Channel selection determines pricing architecture and brand control, with direct models compressing traditional pharmaceutical wholesaler margins.
- Online Retail:Subscription models and direct-to-consumer formats are reshaping replenishment patterns. E-procurement platforms enable dental clinic chains to bypass traditional distributors.
- Supermarkets:Mass-market toothpaste and mouthwash volume concentrates here. Private label expansion is pressuring branded formulation differentiation.
- Pharmacies:Therapeutic claims and clinical endorsement carry disproportionate weight. Regulatory compliance documentation requirements exceed general retail channels.
- Specialty Stores:Premium positioning and ingredient transparency dominate purchase decisions. Natural and bio-based surfactant formulations show channel-concentrated demand.
Scale concentrates in supermarkets. Margin concentrates in specialty stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation chemist talent pools concentrate in Germany's Rhine-Ruhr chemical corridor and India's Gujarat industrial belt, anchoring oral care chemical development across two hemispheres.
Germany
Specialty toothpaste manufacturers in the Rhine-Ruhr region are expanding procurement of bio-based surfactants to meet EU Green Deal chemical sustainability targets. REACH Amendment 2024 is tightening registration requirements for antimicrobial actives and accelerating pre-certified manufacturing investment across German chemical parks. Cologne and Düsseldorf host captive formulation labs serving pan-European personal care value chains.
United States
FDA oversight of over-the-counter oral health products shapes therapeutic formulation priorities for fluoride and whitening agent suppliers. EPA antimicrobial efficacy standards extend validation timelines for cationic biocides by 18-24 months. New Jersey's captive microencapsulation pilot lines are decentralizing flavor procurement from traditional flavor houses toward in-house oral care R&D operations.
India
Dental clinic chains in Mumbai and Bangalore drive bulk chemical offtake through centralized tendering platforms, displacing traditional distributor networks. CDSCO regulatory pathways govern clinical-grade product registration for professional dental applications. Gujarat-based fluoride and surfactant manufacturers now negotiate directly with Axiss Dental and Clove Dental, compressing supplier margins by 15-20 percentage points versus independent practice channels.
China
Over 70% of sodium fluoride and sodium monofluorophosphate feedstock originates from Chinese industrial chemical zones, creating single-source vulnerability for European and North American formulators. NMPA oversight of cosmetic-grade oral care products runs parallel to stricter medical device pathways for clinic-grade formulations. The Yangtze River Delta concentration of fluorochemical production faces displacement pressure as formulators diversify sourcing.
Japan
PMDA assessment pathways for next-generation probiotic and prebiotic oral care chemicals diverge from FDA monograph approaches, creating distinct product development tracks. METI industrial policy supports enzymatic whitening precursor development as patent-protected peroxide alternatives. Osaka-based suppliers anchor professional dental clinic procurement across East Asian tier-1 urban markets.
Oral Care Chemicals Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the oral care chemicals value chain, with integrated formulators controlling upstream surfactant supply while specialty chemical houses concentrate on patent-protected active development. The market structure tilts toward consolidation among consumer-facing brands, while upstream active ingredient supply shows greater fragmentation across regional chemical manufacturers. Three archetypes dominate: integrated personal care conglomerates with captive formulation labs, regional chemical specialists supplying fluoride and antimicrobial feedstocks, and biotechnology entrants developing enzymatic whitening alternatives. Competitive intensity centers on backward integration into oleochemical supply and pre-certification of manufacturing capacity against REACH and FDA timelines.
Among integrated personal care conglomerates, Colgate-Palmolive Company and Unilever PLC exemplify the captive R&D archetype, each operating dedicated formulation facilities that pre-certify active ingredients against regulatory amendments. Procter & Gamble Company represents the upstream-integrated model, anchoring surfactant sourcing through controlled supply chains. These three players occupy positions that shape procurement criteria for downstream chemical suppliers across European, North American, and Asian value chains.
| Leading Market Players |
|---|
| Colgate-Palmolive Company |
| Procter & Gamble Company |
| Unilever PLC |
| Johnson & Johnson Services, Inc. |
| GlaxoSmithKline plc |
| Church & Dwight Co., Inc. |
| Henkel AG & Co. KGaA |
| Lion Corporation |
| Sunstar Group |
| Others |
Value Chain & Pricing Dynamics
Formulation chemist concentration in Germany's Rhine-Ruhr corridor and India's Gujarat belt creates labor-cost differentials that widen pricing spreads between premium clinic-grade formulations and economy consumer tiers. These regional talent pools anchor divergent cost structures across therapeutic and cosmetic product categories.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates EU Medical Device Regulation-certified dental gels from cosmetic-category competitors and mass-market toothpaste. Price differentiation hinges on ISO 9001 manufacturing certification and volume procurement scale. Pricing pressure stems from India's dental clinic chains consolidating procurement through centralized tendering platforms. Economy-tier buyers exhibit highest price sensitivity, while clinic-grade purchasers prioritize regulatory compliance over unit cost.
Supply Chain Analysis
Direct-to-dental-practice distribution through dedicated e-procurement platforms is displacing traditional pharmaceutical wholesalers in Germany's clinic chains. Raw material supply draws from Chinese industrial zones for fluoride salts, North American oleochemical operations for surfactant feedstocks, and German chemical parks for bio-based alternatives. Single-source vulnerability concentrates in Chinese sodium fluoride and sodium mononfluorophosphate production. Distribution runs through consolidated tendering platforms in India alongside conventional wholesaler networks in Europe and North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The oral care chemicals market functions as a regulatory compounder, with EU REACH Amendment 2024 accelerating pre-certified manufacturing investment and reshaping competitive positioning across European supply chains.
For Market Incumbents: Acquire captive microencapsulation capabilities to defend flavor formulation autonomy against Givaudan and Firmenich concentration. Secure backward integration into palm kernel and coconut oil derivatives to insulate surfactant supply from commodity volatility. Pre-certify active ingredients against FDA monograph updates and EMA assessment pathways to maintain dual-market access. For New Entrants and Emerging Players: Dental clinic procurement platforms in Mumbai and Bangalore offer the most penetrable channel for direct manufacturer engagement. Target probiotic oral care formulations as unclaimed white space in professional dental prophylaxis. Pursue enzymatic whitening precursor development to bypass peroxide chemistry patent thickets. For Investors and Strategic Acquirers: Valuations sit cheapest among regional fluoride and antimicrobial feedstock specialists lacking REACH pre-certification. Long-term viability centers on regulatory compliance infrastructure rather than commodity chemistry scale. Watch for REACH authorization sunset dates on zinc-based antimicrobials as inflection indicators for copper gluconate substitution demand.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Pre-Certification Investment | Accelerates market access for antimicrobial actives across German and Dutch chemical parks. |
| Backward Integration into Oleochemicals | Captive supply of palm kernel derivatives insulates formulators from surfactant price volatility. |
| Enzymatic Whitening Precursor Development | Patent-protected alternatives capture professional dental clinic procurement in India's tier-1 markets. |
| Direct-to-Clinic E-Procurement Launch | Bypasses traditional pharmaceutical wholesalers, compressing channel margins in consolidated networks. |
| Probiotic Strain Integration Partnership | Lactobacillus and Bifidobacterium formulations unlock unclaimed white space in professional prophylaxis products. |
Study Parameters
Coverage spans Germany, the United States, India, China, and Japan, with primary inputs from each market anchoring regional demand assessments. The research combines interviews with formulation chemists, procurement leads at dental clinic chains, regulatory affairs directors, and surfactant manufacturing plant managers with secondary validation from customs data, SEC filings, ECHA registration databases, and CDSCO regulatory pathways. Bottom-up segment sizing triangulates against top-down macroeconomic indicators.
Rate-of-change decomposition separates volume growth from pricing dynamics across the projection horizon. The analytical framework models product type, application, end user, and distribution channel dimensions alongside regional regulatory cluster differentiation. CAGRs derive from segment-level growth trajectories weighted by base-year contribution. Forecast inputs incorporate REACH amendment timelines, FDA monograph update schedules, and dental clinic chain expansion patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory divergence between FDA and EMA pathways, fluoride raw material supply disruption, and enzymatic whitening precursor patent litigation. Forecasts reflect assumptions about clinic chain procurement consolidation rates and bio-based surfactant qualification timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Materials
Dental Cavity Filling Material Market
Dental Materials
Global Dental Zirconia Block Market
Dental Materials
Global Zirconia Based Dental Materials Market
Dental Materials
Calcium Hydroxylapatite Fillers Market
Dental Materials
Cold Light Teeth Whitening Kit Market
Dental Materials
Solid Toothpaste Market
Dental Materials
Australia and New Zealand Dental Biomaterials Market
Dental Materials
Crack Tooth Syndrome Market
Dental Materials
Global Dental Adhesive Market
Dental Materials
Dental Fiberglass Posts Market
Dental Materials
Fluoride-Free Toothpaste Market
Dental Materials
Fluoride Mouthwash Market
Dental Materials
Dental Bleaching Materials Market
Dental Materials
Dental Bonding Agent Market
Dental Materials
Dental Polymerization Lamps Market
Dental Materials
Global Dental Membrane and Bone Graft Substitutes Market