
 India Precipitated Silica Market | 2026-2036
India Precipitated Silica Market Size, Share, and Industry Trends Forecast 2026-2036
India Precipitated Silica Market Insights
BIS certification requirements for precipitated silica purity in consumer goods and rubber applications is recalibrating the cost-of-entry calculus for new manufacturers. Madhu Silica Pvt. Ltd. leverages its integrated manufacturing base in Gujarat to sustain cost leadership across wet-process grades. Tata Chemicals Ltd. anchors its position through captive raw material access and deep relationships with domestic tire makers. Evonik Industries competes on technology leadership in high-dispersion silica for fuel-efficient tire treads.
Precipitated silica is an amorphous form of silicon dioxide produced via acid precipitation from sodium silicate solutions, with specific surface areas typically ranging from 50 to 800 square meters per gram depending on process control. The material functions primarily as a reinforcing filler, anti-caking agent, and rheology modifier across rubber compounding, coatings, and personal care formulations. Wet process silica occupies the dominant share of the product type landscape due to its superior reinforcement characteristics in tire manufacturing, while dry process grades serve cost-sensitive paints and plastics applications. The automotive OEM end-user channel commands the deepest margin pools, driven by original equipment specifications for rolling resistance and durability.
BIS standards for precipitated silica in rubber and consumer goods, coupled with CDSCO oversight for pharmaceutical-grade applications, create a multi-layered compliance environment that favors established producers with in-house testing infrastructure. The PLI scheme for specialty chemicals is channeling capital toward domestic capacity expansion, though participants must navigate evolving environmental clearances from MEE-aligned state pollution control boards. Stakeholders should monitor how tightening particulate emissions norms at state-level pollution control authorities reshape plant location economics and captive power choices.
Market Dynamics
BIS certification mandates for precipitated silica purity are compressing the viable supplier base while automotive OEMs accelerate green tire adoption, creating a bifurcated market structure where compliance capability determines competitive survival.
Growth Catalysts
- PLI scheme for specialty chemicals:Production-linked incentives are channeling domestic capital toward precipitated silica capacity expansion, reducing import dependence for tire manufacturers in Gujarat and Maharashtra.
- Automotive OEM green tire specifications:Rolling resistance mandates from domestic vehicle producers are scaling demand for high-dispersion silica grades that improve fuel efficiency metrics.
- Wet-process technology maturation:Process control advances enabling surface area precision from 50 to 800 square meters per gram are unlocking reinforcement performance previously requiring imported material.
Market Restraints
- Sodium silicate feedstock volatility:Price instability in key raw material inputs compresses margin predictability for non-integrated producers lacking captive alkali silicate supply.
- BIS certification timeline friction:Multi-stage purity testing protocols extend product qualification cycles, delaying revenue recognition for new manufacturing lines.
- Gujarat-Maharashtra supply concentration:Geographic clustering of specialty chemical infrastructure creates single-point vulnerability to state-level pollution control disruptions.
Strategic Opportunities
- Pharmaceutical-grade silica whitespace:CDSCO oversight for excipient-grade applications remains underdeveloped relative to rubber and coatings segments, offering first-mover positioning for compliant producers.
- Coatings application diversification:Rheology modifier demand from industrial paint formulators in Maharashtra is outpacing supply of appropriately specified dry-process grades.
- State pollution board alignment:MEE-emission-norm-compliant plant configurations in Tamil Nadu and Karnataka are accessing faster environmental clearances than legacy Gujarat facilities.
Industry Challenges
- Process analytical technology skill scarcity:Wet-process silica production requires specialized surface area characterization expertise that outpaces domestic technical training pipeline output.
- Legacy equipment retrofit capex burden:Particulate capture upgrades to meet tightening state pollution control board standards demand capital deployment without immediate volume uplift.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Precipitated Silica Market |
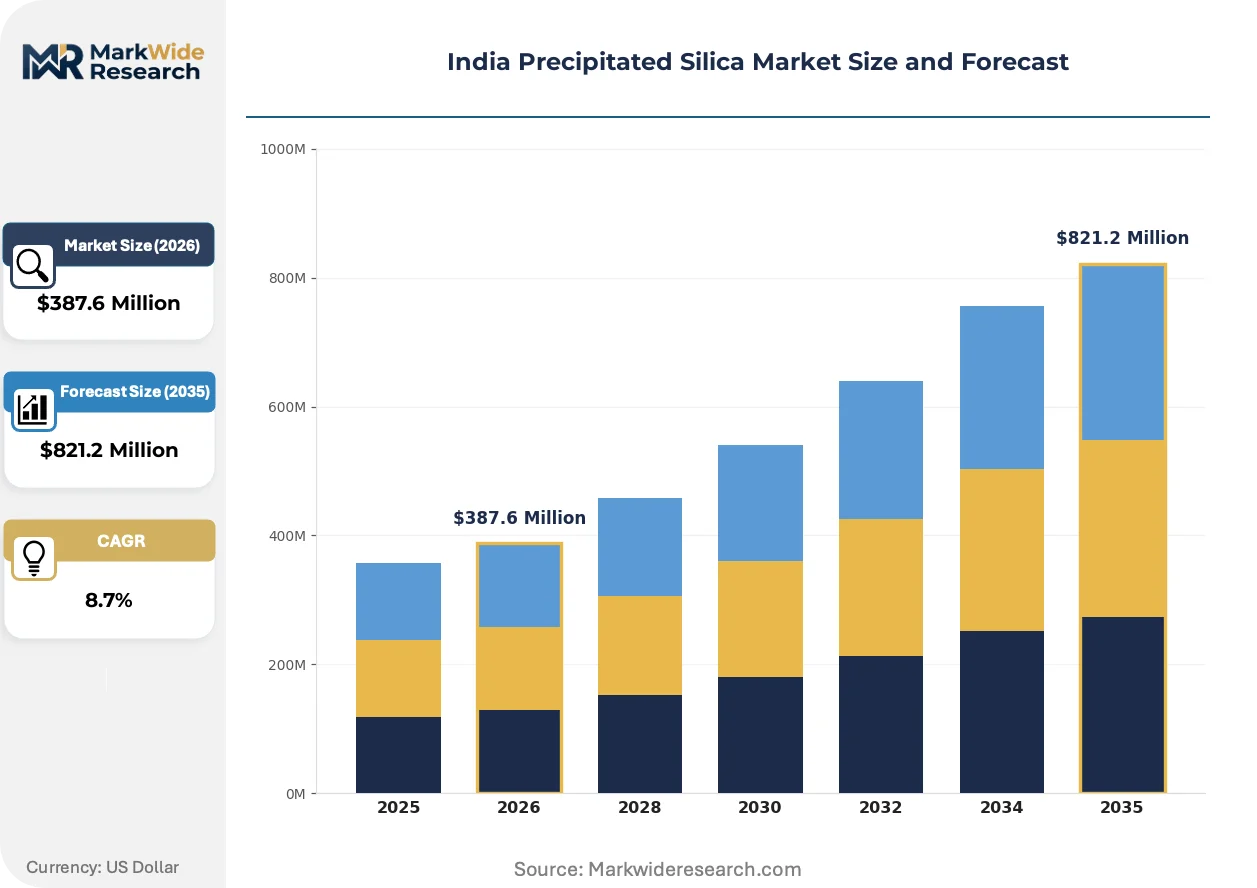
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wet Process, Dry Process, AEROSIL, Granular Application: Rubber, Paints, Coatings, Plastics End User: Manufacturers, Automotive OEMs, Consumer Goods, Construction Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | Madhu Silica Pvt. Ltd., Tata Chemicals Ltd., Supersil Chemicals (I) Pvt. Ltd., MLA Group, PPF Industries, Evonik Industries, PQ Corporation, PPG Industries, Inc., Huber Engineered Materials, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Precipitated Silica Market Trends and Innovations
Process intensification and regulatory digitization are converging to reshape how precipitated silica manufacturers qualify products and serve end-use segments across India's tire and coatings value chains.
Continuous precipitation reactor technology is decentralizing production economics by enabling smaller-scale, modular capacity deployment closer to tire manufacturing clusters. Domestic automotive OEMs are piloting these systems in Maharashtra to reduce logistics exposure and compress lead times. The technology is decentralizing the historical advantage of large-volume Gujarat producers by matching unit economics at sub-thousand-tonne annual outputs.
BIS digitization of silica purity certification documentation is compressing compliance verification cycles from months to weeks. The industrial consequence is accelerated supplier onboarding for tire manufacturers facing OEM qualification deadlines. Rubber compounders in Gujarat are responding by integrating BIS API connectivity into incoming quality control workflows, preempting documentation disputes that previously delayed shipments.
Specification-driven procurement consolidation among tier-one tire manufacturers is displacing spot-market purchasing for precipitated silica. Long-term offtake agreements with fixed purity bands and volume commitments are replacing transactional buying in the automotive OEM channel. This pattern is most visible in Maharashtra, where domestic tire producers are locking three-year supply contracts to secure BIS-certified material ahead of competing bidders.
India Precipitated Silica Market Segmentation
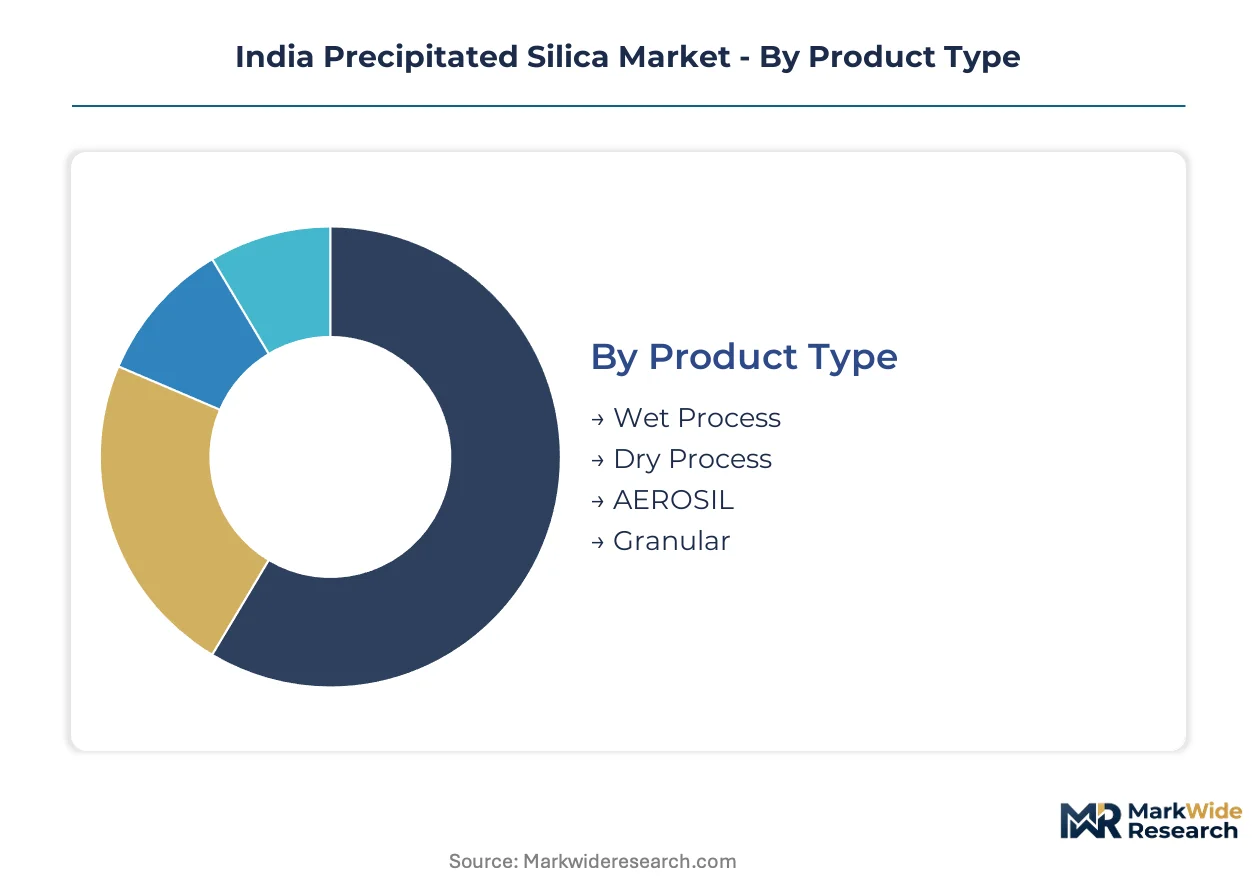
Precipitated silica demand fragments across manufacturing processes, application chemistries, and customer procurement patterns. Each segmentation axis reveals distinct margin structures and compliance requirements that reshape competitive positioning in Gujarat and Maharashtra production clusters.
Product Type:
Process technology determines surface area precision, reinforcement performance, and BIS certification pathways.
- Wet Process:Acid precipitation from sodium silicate solutions yields amorphous silica with tunable surface areas from 50 to 800 square meters per gram. Automotive OEMs in Maharashtra specify wet-process grades for green tire tread formulations demanding low rolling resistance.
- Dry Process:Thermal vapor-phase production generates fumed silica with lower moisture content and different agglomeration characteristics. Cost-sensitive coatings formulators in Gujarat prefer dry-process material for rheology modification where surface area tolerance bands are wider.
- AEROSIL:Evonik's proprietary hydrophilic and hydrophobic fumed silica grades target pharmaceutical and high-performance coatings applications requiring batch-to-batch consistency.
- Granular:Compacted, low-dust forms ease handling in automated rubber compounding lines and reduce workplace respirable silica exposure.
Wet Process leads on scale; AEROSIL leads on momentum.
Application:
End-use chemistry dictates purity thresholds, dispersion requirements, and pricing power.
- Rubber:Tire manufacturers consume precipitated silica as a reinforcing filler to replace carbon black in tread compounds, improving wet grip and fuel efficiency. Domestic automotive OEM qualification programs are consolidating procurement around BIS-certified wet-process suppliers with proven batch consistency.
- Paints:Architectural and industrial coatings employ silica as a matting agent and rheology modifier to control sag resistance and film appearance. Maharashtra paint clusters are experiencing supply tightness for appropriately specified dry-process grades.
- Coatings:Specialty industrial finishes require precise particle size distribution for optical properties and durability.
- Plastics:Polymer compounding uses precipitated silica as an anti-blocking and anti-caking additive in film and masterbatch production.
Rubber dominates volume absorption; Coatings offers the steepest expansion trajectory.
End User:
Customer scale and specification intensity create tiered margin pools across the value chain.
- Manufacturers:Specialty chemical and compounder operations purchase precipitated silica as an intermediate input for formulated products.
- Automotive OEMs:Original equipment tire specifications mandate high-dispersion silica grades with documented purity chain-of-custody. Long-term offtake agreements with fixed volume commitments are replacing spot-market purchasing among tier-one tire producers.
- Consumer Goods:Personal care and food-grade applications require CDSCO oversight and FSSAI compliance for excipient and additive uses.
- Construction:Adhesive and sealant formulators utilize precipitated silica for thixotropic control in building materials.
Automotive OEMs concentrate margin capture; Consumer Goods presents underdeveloped compliance whitespace.
Distribution Channel:
Logistics configuration shapes working capital intensity and technical service depth.
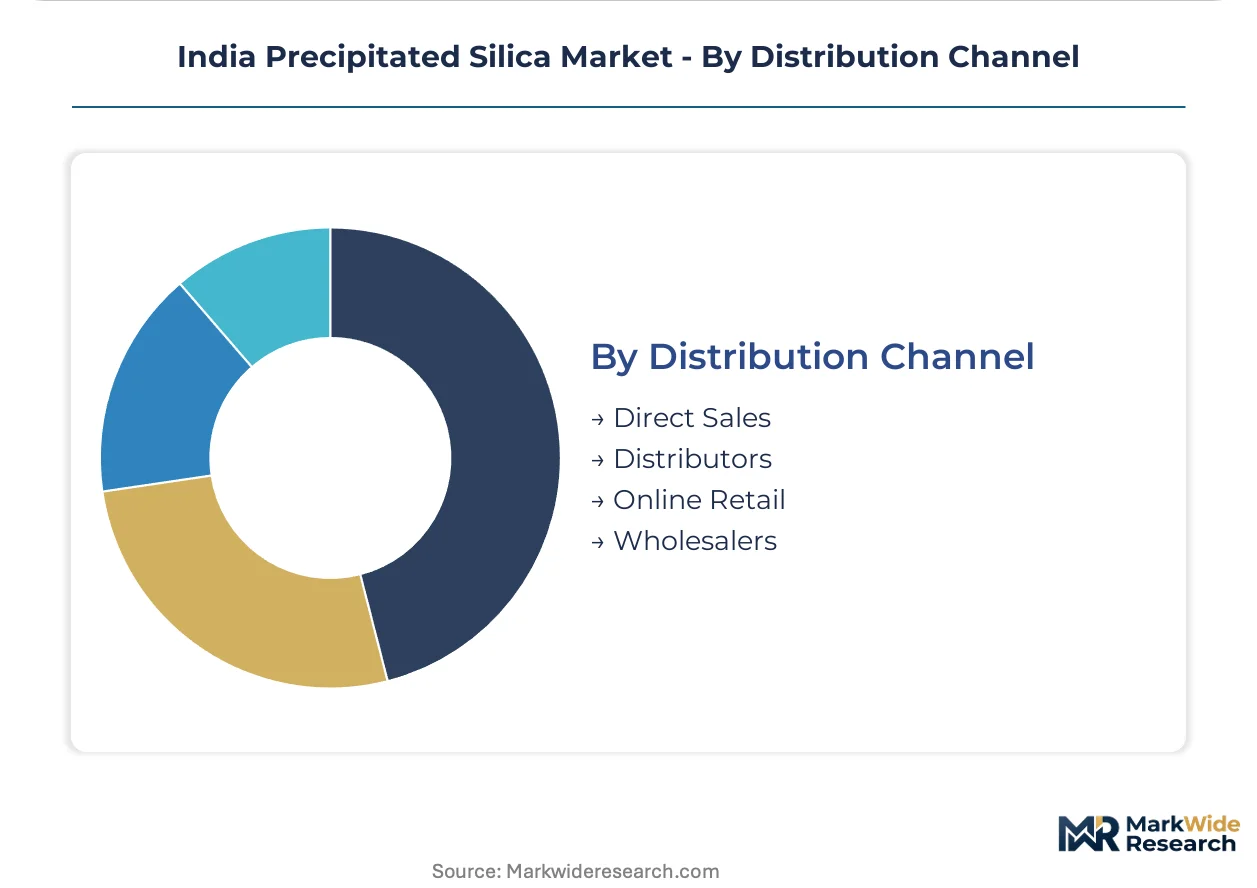
- Direct Sales:Large-volume tire manufacturers negotiate directly with precipitated silica producers for dedicated supply lines and technical support. This channel commands priority allocation during feedstock shortage periods.
- Distributors:Regional chemical distributors serve mid-tier coatings and plastics compounders with smaller order quantities and consolidated procurement.
- Online Retail:E-procurement platforms are emerging for standardized grades in research and pilot-scale quantities.
- Wholesalers:Bulk traders handle commodity-grade material for price-sensitive construction and general industrial applications.
Direct Sales anchors volume throughput; Distributors are gaining share fastest among emerging coatings formulators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized chemical engineering talent concentrates in Gujarat and Maharashtra, anchoring India's precipitated silica production base and drawing process technology investment toward these coastal manufacturing corridors.
Gujarat
Integrated sodium silicate-to-silica operations cluster around Vadodara and Bharuch, feeding tire compounders with wet-process grades. State pollution control board clearances under MEE-aligned norms are accelerating faster for greenfield projects with captive renewable power. Dahej and Mundra port zones are attracting import-substitution capacity for high-dispersion automotive grades.
Maharashtra
Pune and Mumbai automotive OEMs are consolidating procurement through three-year offtake agreements with BIS-certified suppliers. The state's PLI scheme disbursements for specialty chemicals are channeling capital toward continuous precipitation reactor installations. Thane-Belapur industrial corridor hosts the densest concentration of rubber compounding lines consuming precipitated silica.
Tamil Nadu
Coimbatore and Chennai coatings formulators are experiencing supply tightness for appropriately specified dry-process grades. MEE-emission-norm-compliant plant configurations are accessing environmental clearances faster than legacy western facilities. Sriperumbudur automotive supplier parks are scaling silica consumption for export-oriented tire production.
Karnataka
Bangalore-based industrial paint R&D centers are driving rheology modifier specification intensity upward. State pollution control authorities are enforcing particulate emissions norms that favor modern precipitation reactor technology over legacy batch operations. Peenya industrial zone compounders are qualifying new silica sources for electronics-grade applications.
Haryana
Manesar automotive component suppliers are extending silica qualification programs to tier-two compounders in the Delhi-NCR orbit. CDSCO oversight for pharmaceutical-grade excipient applications remains underdeveloped relative to western states. Bawal industrial area manufacturers are piloting granular silica forms for automated rubber handling systems.
India Precipitated Silica Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across India's precipitated silica landscape, creating a tiered structure where captive raw material access separates margin leaders from price-takers. The supplier base compresses around integrated alkali silicate producers and technology-licensed specialists with BIS certification infrastructure. Three archetypes dominate: chemical conglomerates with backward integration, regional specialists with process control expertise, and multinational technology leaders with high-dispersion IP. Competitive dynamics center on capacity expansion timed to PLI scheme windows and strategic partnerships with automotive OEM qualification programs.
Among domestic integrated producers, Madhu Silica Pvt. Ltd. and Tata Chemicals Ltd. exemplify the conglomerate archetype with captive feedstock positions. Evonik Industries occupies the multinational technology tier, representing high-dispersion silica capability for fuel-efficient tire specifications. These three anchors illustrate how certification infrastructure and raw material integration determine competitive survival under tightening BIS purity mandates.
| Leading Market Players |
|---|
| Madhu Silica Pvt. Ltd. |
| Tata Chemicals Ltd. |
| Supersil Chemicals (I) Pvt. Ltd. |
| MLA Group |
| PPF Industries |
| Evonik Industries |
| PQ Corporation |
| PPG Industries, Inc. |
| Huber Engineered Materials |
| Others |
Pricing and Supply Chain Analysis
Automotive OEM procurement consolidation in Maharashtra and Gujarat commands contract-based long-term offtake agreements as the dominant pricing mechanism, compressing spot-market liquidity and amplifying volume-scale discounts for integrated producers with captive sodium silicate supply.
Pricing Analysis
Bundled technical service contracts with BIS-certified purity guarantees command premium positioning over unbundled commodity transactions. Three-tier pricing structure across high-dispersion automotive grades, standard wet-process rubber fillers, and dry-process coatings grades reflects certification intensity and surface area precision. Cost compression in standard wet-process tiers intensifies because non-integrated producers face sodium silicate feedstock volatility. Tier-one tire manufacturers demonstrate lowest price sensitivity due to OEM qualification lock-in, while construction adhesive formulators exhibit highest sensitivity to unit cost fluctuations.
Supply Chain Analysis
Sodium silicate supply rests on alkali silicate producers concentrated in Gujarat, Maharashtra, and Tamil Nadu, with sulfuric acid and process water as secondary critical inputs. Geographic clustering around Vadodara-Bharuch and Thane-Belapur corridors creates single-point vulnerability to state pollution control board enforcement actions. Distribution runs through direct sales channels to automotive OEMs and regional distributors serving coatings compounders, with bulk rail and coastal vessel logistics dominating inter-state material flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where BIS purity digitization and PLI scheme disbursements are accelerating supplier consolidation and capital deployment toward compliant capacity.
For Market Incumbents: Deploy continuous precipitation reactor technology to defend against modular entrants targeting Maharashtra automotive clusters. Secure three-year offtake extensions with tier-one tire manufacturers before PLI scheme windows close. Backward integration into sodium silicate production anchors margin resilience against feedstock volatility threatening non-integrated competitors. For New Entrants and Emerging Players: Pharmaceutical-grade excipient buyers under CDSCO oversight represent the most penetrable whitespace, with rubber and coatings segments already locked by incumbent certification infrastructure. Target Tamil Nadu and Karnataka coatings formulators experiencing dry-process grade supply tightness. Lead with MEE-emission-norm-compliant plant configurations to accelerate environmental clearances versus legacy Gujarat facilities. For Investors and Strategic Acquirers: Specialty chemical conglomerates with captive alkali silicate positions are the most active acquirer in this space, seeking BIS-certified capacity to plug portfolio gaps. Five-to-ten year viability hinges on regulatory compliance infrastructure rather than pure scale economics. Monitor PLI scheme disbursement velocity and state pollution board enforcement intensity as inflection indicators for capacity utilization trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sodium Silicate | Captive feedstock supply insulates margin structure from alkali silicate price volatility in Gujarat. |
| Continuous Precipitation Reactor Installation | Modular capacity deployment near Maharashtra automotive OEMs compresses logistics exposure and lead times. |
| BIS Certification Infrastructure Investment | In-house testing capabilities accelerate product qualification cycles for tire manufacturer onboarding. |
| Pharmaceutical-Grade Excipient Qualification | CDSCO-compliant production unlocks underdeveloped personal care and food additive demand segments. |
| Long-Term Supply Agreement with Automotive OEMs | Fixed-volume offtake commitments secure priority allocation during sodium silicate shortage periods. |
Research Methodology
Coverage spans Gujarat, Maharashtra, Tamil Nadu, Karnataka, and Haryana, with primary inputs from each state's production clusters and downstream consumption centers. Primary interviews with plant managers at precipitated silica facilities, procurement leads at domestic tire manufacturers, technical R&D directors at coatings formulators, and distribution channel partners in specialty chemicals were triangulated against secondary sources including BIS certification records, state pollution control board filings, PLI scheme disbursement data, and customs trade statistics. Bottom-up capacity installation tracking and top-down end-use demand estimation were cross-validated to anchor volume figures.
Granularity-level modeling disaggregated the market across wet-process and dry-process technology tiers, rubber and coatings application segments, automotive OEM and consumer goods end-user channels, and direct sales versus distributor distribution pathways throughout the projection horizon. CAGRs were derived from segment-specific volume trajectories calibrated to automotive production forecasts and specialty chemicals capacity expansion pipelines. Surface area specification intensity and BIS certification penetration rates served as industry-specific forecast modifiers.
Underlying measurement precision varies by segment; automotive OEM channel data carries tighter precision than fragmented construction applications. Forecasts reflect assumptions regarding PLI scheme continuity, MEE emission norm enforcement consistency, and sodium silicate supply stability. Regulatory discontinuity, feedstock price spikes, or state-level environmental clearance delays constitute the primary revision triggers warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Polyepoxysuccinic Acid Market
Industrial Chemicals
Molecular Sieves Market
Industrial Chemicals
Volatile Organic Compounds (VOC) Concentrator Market
Industrial Chemicals
High Pressure Roll Compactor Market
Industrial Chemicals
Lithium Hexafluorophosphate Market
Industrial Chemicals
Gypsum-Free Cement Market
Industrial Chemicals
Di (2-Ethylhexyl) Phthalate Market
Industrial Chemicals
Powder Coating Guns Market
Industrial Chemicals
Asia-Pacific Activated Carbon Market
Industrial Chemicals
Process Fluid Market
Industrial Chemicals
Global Refrigerants Market
Industrial Chemicals
Swimming Pool Salt Chlorinator Market
Industrial Chemicals
Heat Transfer Fluids Market
Industrial Chemicals
Blown Oils Market
Industrial Chemicals
Global Battery Grade Lithium Hydroxide Market
Industrial Chemicals
Emulsion Explosive Market