
 Shipping Container Coatings Market | 2026-2036
Shipping Container Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Shipping Container Coatings Market Analytics
Container leasing and asset-light operating models is tilting procurement authority toward fleet managers with long-term maintenance contracts. Hempel leverages its marine coatings heritage to sustain technical credibility with major lessors. Sherwin-Williams anchors North American supply through direct distribution to container depots and repair yards. Chugoku Marine Paints dominates Asian new-build specifications through mill-applied primer relationships.
Shipping container coatings are protective film systems applied to corten steel exteriors and interiors, typically formulated with epoxy or polyurethane binders at dry film thicknesses of 100-200 microns to resist salt spray, mechanical abrasion, and cargo-induced chemical exposure. Epoxy formulations lead volume due to cost-efficient adhesion and corrosion inhibition on new containers, while polyurethane topcoats command premium positioning for gloss retention and UV stability in high-cycle leasing fleets. Spray application captures the largest share of factory throughput, though brush and roll methods persist in depot maintenance settings where field repair economics favor manual touch-up.
The International Maritime Organization enforces anti-fouling and ballast water conventions that indirectly elevate coating performance requirements for container hulls and holds. REACH and the EU Green Deal restrict volatile organic compound emissions and hazardous substance content, forcing reformulation toward waterborne and high-solids systems. China's GB standards and MEE oversight impose parallel environmental compliance on the world's dominant container production base. Stakeholders must monitor regulatory divergence between Asian manufacturing standards and European end-market restrictions when qualifying coating systems for cross-border fleet deployment.
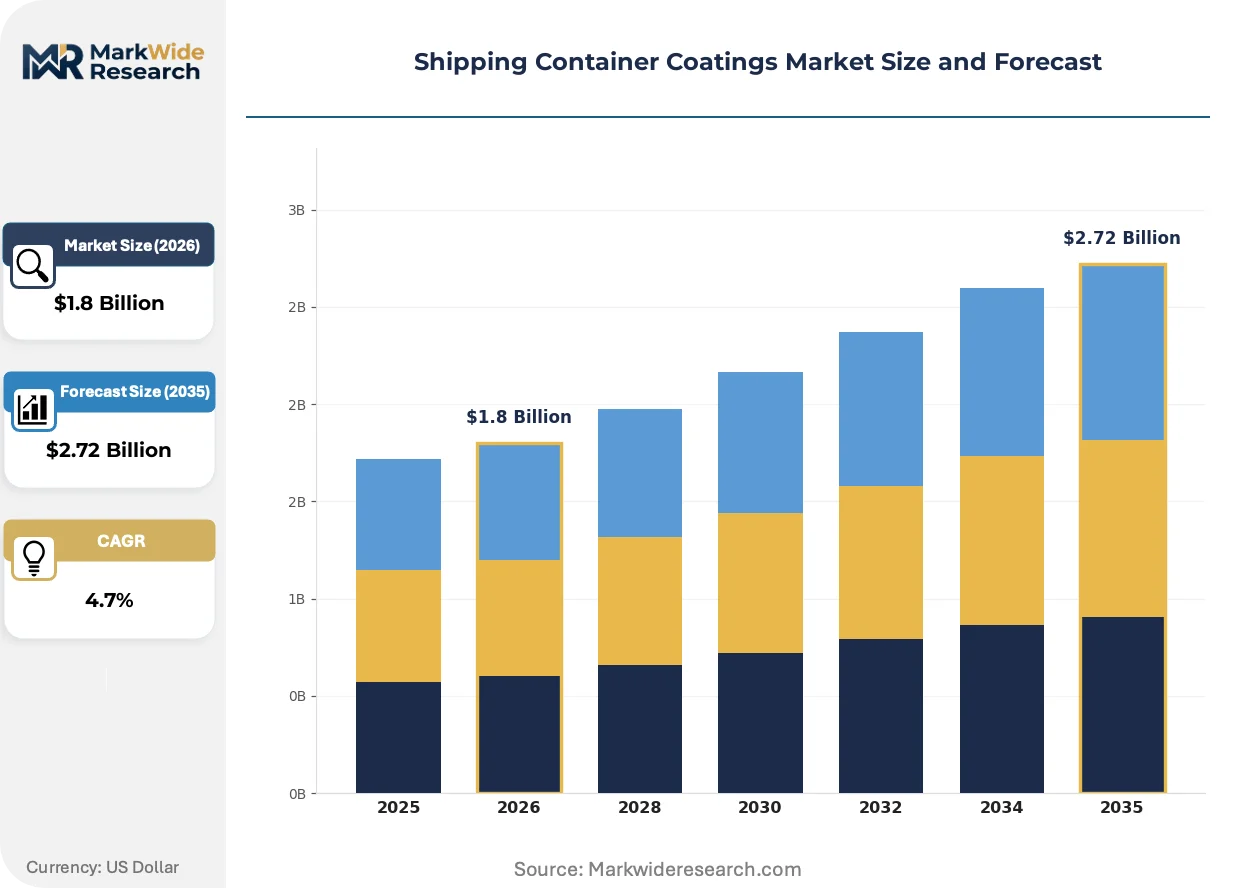
Market Dynamics
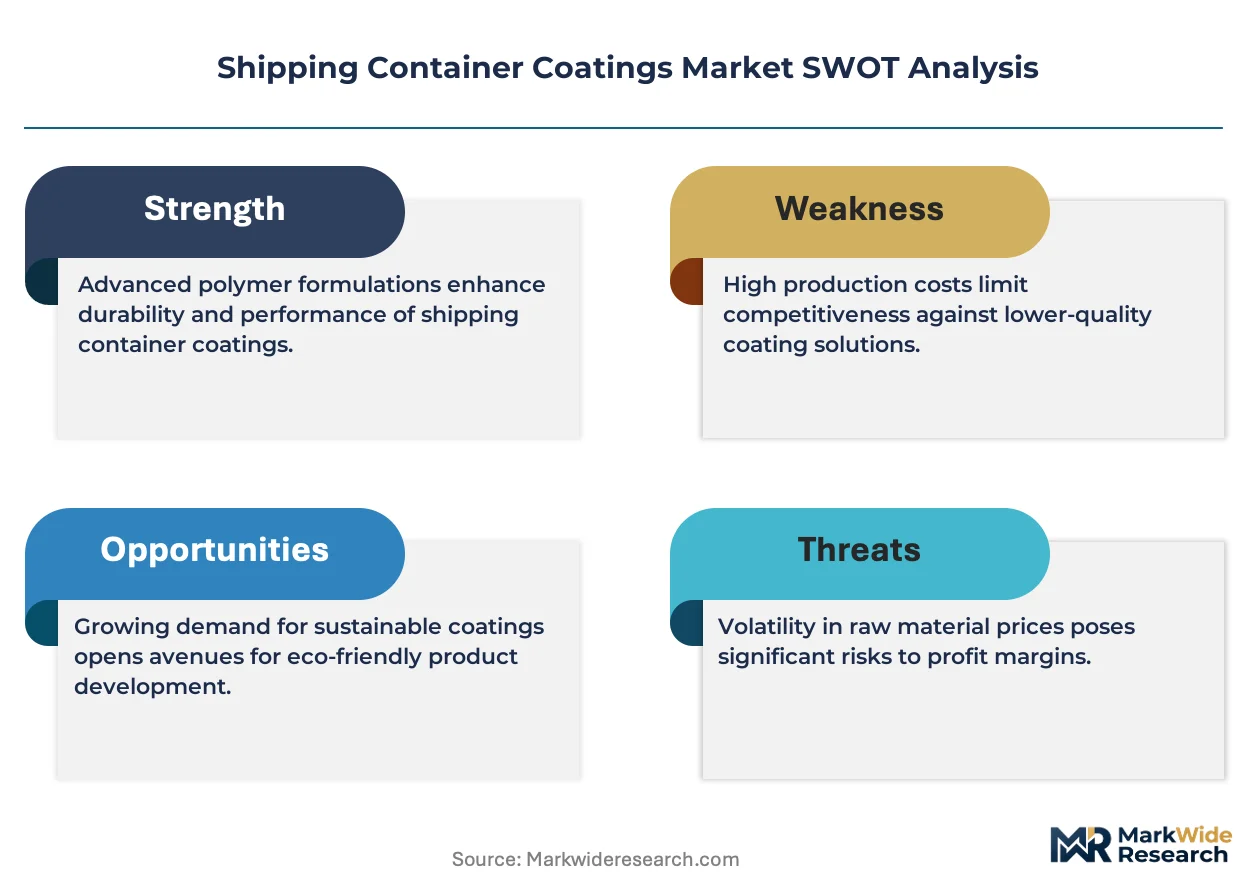
Fleet operators are consolidating procurement authority through long-term maintenance contracts, compressing coating specification decisions into fewer hands and privileging suppliers with integrated technical service capabilities.
Growth Catalysts
- IMO 2020 sulfur regulations:Stricter marine fuel standards accelerate hull coating performance requirements for corrosion resistance in high-sulfur scrubber environments.
- Corten steel substrate chemistry:Advanced weathering steel formulations demand compatible primer systems that bond to oxide-rich surfaces without surface preparation degradation.
- China's container manufacturing cluster:Concentrated production in coastal provinces creates captive demand for mill-applied coating systems at point of fabrication.
Market Restraints
- Zinc raw material volatility:Epoxy zinc-rich primers depend on zinc metal prices that fluctuate with mining supply disruptions and energy costs.
- Single-region production dependency:Over 90% of new container output originates from Chinese fabricators, creating geographic concentration risk for coating demand.
- Waterborne cure-rate limitations:High-humidity application environments in tropical ports extend drying times and reduce throughput for low-VOC formulations.
Strategic Opportunities
- EU Green Deal compliance premiums:REACH-registered high-solids systems command pricing power in European leasing fleets facing VOC emission caps.
- Reefer container interior coatings:Food-grade epoxy formulations for refrigerated units address cargo contamination protocols in pharmaceutical and protein supply chains.
- Digital coating specification platforms:Fleet managers are adopting cloud-based technical databases that bypass traditional distributor relationships for direct manufacturer engagement.
Industry Challenges
- Applicator certification bottlenecks:NACE/SSPC coating inspector credentials face shortages in Southeast Asian depot networks, delaying warranty-qualified repairs.
- Multi-jurisdiction formulation complexity:Manufacturers must maintain parallel SKUs to satisfy China's GB standards, EU REACH restrictions, and US EPA VOC rules simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shipping Container Coatings Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coating Type: Epoxy, Polyurethane, Acrylic, Aliphatic Application Method: Spray, Brush, Roll, Dip End User: Shipping Lines, Freight Forwarders, Logistics Companies, Manufacturers Durability Level: Standard, High Performance, Weather Resistant, Corrosion Resistant |
| Companies Covered | Hempel, Sherwin-Williams, Chugoku Marine Paints, KANGNAM JEVISCO, PPG Industries, Jotun, Akzo Nobel, Kansai Paint, Ultrimax Coatings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shipping Container Coatings Market Evolving Landscape
Coating formulation science is converging with digital fleet management platforms, creating integrated systems where film performance data feeds directly into asset depreciation models and maintenance scheduling algorithms.
Self-healing microcapsule technology is virtualizing maintenance economics for container operators. Major lessors in high-rotation Pacific routes are piloting polyurethane topcoats embedded with polymerase-filled capsules that autonomously seal surface scratches. This innovation compresses depot touch-up frequency and extends warranty periods beyond conventional five-year terms.
REACH authorization procedures are forcing systematic substance substitution across European-serving fleets. ECHA's sunset date scheduling for chromate-based corrosion inhibitors compels reformulation toward phosphate and silane alternatives. Container lines operating EU-flagged vessels are accelerating qualification timelines for compliant primer systems ahead of 2026 substance restrictions.
Leasing companies are consolidating coating specification authority away from shipping lines. Triton International and Textainer now mandate approved manufacturer lists for their combined 8 million TEU fleets, displacing carrier-level procurement autonomy. This concentration is most visible in Singapore and Rotterdam hub markets where lessor-preferred products dominate depot repair volumes regardless of underlying shipping line contracts.
Shipping Container Coatings Market Segmentation
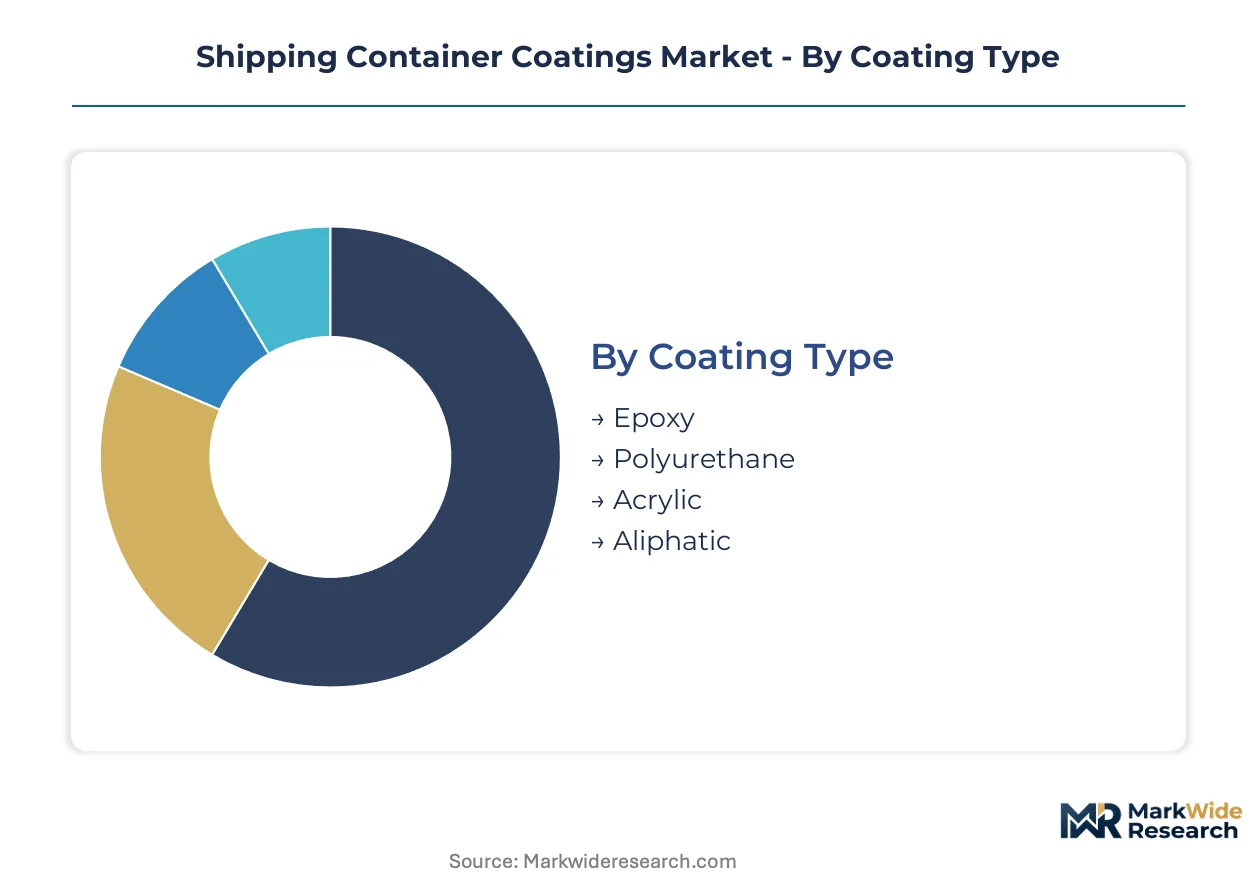
Coating specification in container fleets splits across performance tiers, application economics, and custody chain position. Each segmentation dimension carries distinct margin profiles and technical qualification barriers that reshape supplier access.
Coating Type:
Cost tier stratification separates commodity formulations from premium systems with extended warranty terms.
- Epoxy:Two-component amine-cured systems dominate new-build factory throughput with zinc-rich primer variants delivering sacrificial corrosion protection on corten steel substrates. Demand clusters at Chinese mill facilities where cost-per-liter economics govern specification. Standard epoxy holds installed capacity. Polyurethane is rotating up the share rankings.
- Polyurethane:Aliphatic isocyanate-cured topcoats provide UV-stable gloss retention for high-rotation leasing fleets requiring extended aesthetic life between depot cycles. Singapore and Rotterdam hub terminals specify these systems for premium reefer and dry container categories. Polyurethane formulations command specification authority in lessor-managed maintenance contracts.
- Acrylic:Waterborne acrylics serve interior cargo hold applications where food-grade compliance and low-VOC emission profiles satisfy EU Green Deal constraints.
- Aliphatic:Specialized isocyanate-free variants address occupational health requirements in enclosed spray booth environments at automated container fabrication lines.
Polyurethane is climbing the fastest as lessor procurement consolidation favors lifecycle cost over first-cost specification.
Application Method:
Volume throughput and labor intensity diverge sharply across technique categories.
- Spray:Airless and electrostatic spray systems achieve 100-200 micron dry film thickness at production rates exceeding 400 containers per day at Chinese manufacturing clusters. Automated reciprocating spray booths with robotic arm configuration dominate mill-applied primer and topcoat deposition. Spray application holds installed capacity. Brush methods are rotating up the share rankings.
- Brush:Manual stripe coating and touch-up operations persist in depot maintenance settings where field repair economics favor targeted spot treatment over full recoat. Southeast Asian port facilities rely on brush application for warranty-qualified repairs where NACE inspector certification shortages constrain spray booth infrastructure.
- Roll:Roller application serves interior floor coating in specialized tank containers and bulk hopper units where overspray containment costs exceed labor savings from spray methods.
- Dip:Immersion coating systems treat container hardware components—hinges, locking bars, and corner castings—at dedicated ancillary processing lines adjacent to main fabrication.
Dip coating maintains hardware subsegment dominance while brush application expands with depot network decentralization.
End User:
Customer type determines specification authority and contract structure length.
- Shipping Lines:Maersk, MSC, and CMA CGM historically controlled coating procurement through vessel-operating carrier agreements. Carrier specification autonomy is concentrating into lessor-managed frameworks.
- Freight Forwarders:DHL Global Forwarding and Kuehne+Nagel exert indirect influence through cargo condition guarantees that mandate interior coating performance standards.
- Logistics Companies:Third-party warehouse operators and intermodal terminal managers specify floor coating abrasion resistance for container handling equipment impact zones.
- Manufacturers:CIMC, COSCO Shipping Heavy Industry, and Singamas anchor demand as integrated fabricators with captive coating application facilities at production sites in Jiangsu and Guangdong provinces.
Manufacturer procurement volumes exceed shipping line direct purchases as asset-light operating models expand.
Durability Level:
Maturity gradients separate legacy specification from emerging performance tiers.
- Standard:Five-year corrosion protection systems with epoxy primer and alkyd topcoat combinations serve low-utilization storage container and one-way export box categories.
- High Performance:Ten-year warranty systems with zinc-rich epoxy, intermediate build coats, and polyurethane finish coats target premium leasing fleet deployment on Asia-Europe trunk routes.
- Weather Resistant:Enhanced UV stabilizer packages and infrared-reflective pigments reduce thermal cycling stress for containers in Middle East and Australian desert exposure zones.
- Corrosion Resistant:Modified epoxy formulations with glass flake reinforcement withstand aggressive cargo residues including sodium chloride, sulfur compounds, and acidic food processing byproducts.
Corrosion resistant specification is gaining share fastest as IMO 2020 scrubber discharge chemistry accelerates hold coating degradation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal emission caps and IMO 2020 scrubber discharge rules are redirecting coating procurement toward high-solids, low-VOC formulations. National implementation timelines vary, creating regulatory arbitrage opportunities for fleet operators qualifying systems across multiple jurisdictions.
China
GB standards from the Ministry of Ecology and Environment (MEE) enforce VOC emission limits at container fabrication facilities. The Yangtze River Delta cluster in Jiangsu province hosts CIMC and COSCO Shipping Heavy Industry mills where automated spray booths apply epoxy primer systems at throughput rates exceeding 400 units daily. Mill-applied coating demand concentrates at point of manufacture.
Germany
ECHA's REACH authorization schedule for chromate-based corrosion inhibitors compels reformulation toward phosphate alternatives by 2026. The Port of Rotterdam's hub status extends regulatory influence into German lessor operations. Hamburg depot networks are qualifying high-solids polyurethane topcoats for premium reefer fleets under extended warranty terms.
Singapore
The Maritime and Port Authority enforces ballast water management conventions that elevate hold coating performance standards. Triton International and Textainer maintenance contracts specify approved manufacturer lists for Pacific route container repair. Tuas port expansion is decentralizing depot capacity toward automated spray infrastructure.
United States
EPA VOC rules under 40 CFR Part 59 restrict coating composition for containers entering domestic intermodal service. Los Angeles and Long Beach port complexes are consolidating lessor-preferred products in depot repair yards regardless of underlying carrier contracts. Sherwin-Williams direct distribution anchors North American supply chain access.
South Korea
Korean Register classification requirements influence coating specification for EU-bound container fleets. Busan-Ulsan industrial corridor hosts KANGNAM JEVISCO manufacturing capacity serving Asian new-build and aftermarket segments. Daewoo and Hyundai Heavy Industries integration creates captive demand for marine-qualified coating systems.
Shipping Container Coatings Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic archetypes: marine heritage specialists with lessor technical service relationships, diversified coatings multinationals with direct distribution infrastructure, and regional Asian manufacturers with mill-applied primer positioning at Chinese fabrication clusters. Competitive moves center on portfolio diversification into food-grade and reefer interior formulations, plus geographic expansion through depot network certification in Singapore and Rotterdam hub markets.
Within the marine heritage tier, Hempel and Jotun occupy positions anchored to technical credibility with major lessors and classification society pre-qualification. Among diversified multinationals, Sherwin-Williams exemplifies direct distribution models bypassing traditional channel relationships. Chugoku Marine Paints sits within the Asian mill-applied specialization, representing regional dominance through fabrication-site coating relationships. Akzo Nobel and PPG Industries span multiple archetypes with marine and industrial coating portfolio breadth.
| Leading Market Players |
|---|
| Hempel |
| Sherwin-Williams |
| Chugoku Marine Paints |
| KANGNAM JEVISCO |
| PPG Industries |
| Jotun |
| Akzo Nobel |
| Kansai Paint |
| Ultrimax Coatings |
| Others |
Value Network & Pricing Analysis
The Yangtze River Delta cluster in Jiangsu province anchors global epoxy primer capacity at CIMC and COSCO Shipping Heavy Industry mills, concentrating formulation pricing power among suppliers with mill-applied relationships. This geographic concentration lets dominant players extract premiums for REACH-registered high-solids systems while Chinese fabricators compress first-cost specifications on standard epoxy tiers.
Pricing Analysis
Certification level (REACH-registered vs. GB-standard) creates the primary spread between premium polyurethane topcoats and commodity epoxy primers. Three-tier pricing structure across premium, standard, and economy levels reflects warranty duration, with ten-year high-performance systems commanding substantial premiums over five-year standard formulations. Pricing pressure stems from zinc metal volatility in sacrificial primer feedstocks. Leasing companies show lowest price sensitivity due to lifecycle cost modeling, while independent depot operators remain most exposed to spot material costs.
Supply Chain Analysis
Epoxy resin and isocyanate hardener feedstock supply concentrates in China, South Korea, and Germany, with BASF and Covestro anchoring European specialty chemical flows. Zinc metal for sacrificial primers draws from Australian mining output and Chinese smelter capacity. Single-source vulnerability runs through Jiangsu province mill-applied coating infrastructure. Distribution runs through direct manufacturer relationships with lessor-approved depot networks in Singapore and Rotterdam, displacing traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Container coatings operate as a substitution defense market where waterborne acrylic and powder coating technologies threaten incumbent solvent-borne epoxy and polyurethane systems. Incumbents must navigate reformulation investments while lessor procurement consolidation raises qualification barriers for alternative technologies.
For Market Incumbents: Pre-empt waterborne displacement by accelerating phosphate-based corrosion inhibitor qualification ahead of ECHA chromate sunset deadlines. Backward integration into zinc oxide processing secures sacrificial primer feedstock against mining supply disruptions. Certification investment in NACE inspector training programs locks in depot network warranty compliance.
For New Entrants and Emerging Players: Build out self-healing microcapsule technology partnerships with Pacific route lessors seeking extended warranty terms. The reefer container interior segment offers most penetrable white-space given food-grade compliance requirements that favor specialized formulation expertise. Go-to-market positioning through digital coating specification platforms bypasses entrenched distributor relationships.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors marine heritage specialists with lessor technical service relationships over diversified industrial coatings portfolios. Long-term viability rests on REACH compliance execution and lessor procurement consolidation capture. The signal to watch is ECHA substance restriction acceleration forcing parallel SKU consolidation among multinationals.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Reformulation Program | Phosphate and silane alternatives to chromate inhibitors secure European leasing fleet access ahead of ECHA deadlines. |
| Depot Network Certification Expansion | NACE inspector training investments in Singapore and Rotterdam hub markets lock in warranty-qualified repair volume. |
| Self-Healing Coating Technology Partnership | Microcapsule-embedded polyurethane pilots with Triton and Textainer extend maintenance intervals beyond conventional terms. |
| Digital Specification Platform Development | Cloud-based technical databases enable direct manufacturer engagement with fleet managers, displacing distributor channels. |
| Reefer Interior Food-Grade Formulation Launch | Specialized epoxy systems for pharmaceutical and protein supply chains address cargo contamination protocol requirements. |
Research Methodology
Desk research of customs trade data, SEC filings from coatings multinationals, and MEE environmental compliance records preceded structured interviews with fleet procurement managers, depot operations directors, and marine coatings R&D leads. Primary fieldwork with CIMC and Singamas fabrication engineers validated mill-applied specification practices. Secondary triangulation against ECHA authorization schedules and IMO convention implementation timelines anchored regulatory scenario modeling. Bottom-up container production forecasts and top-down coatings consumption estimates were cross-referenced for convergence.
Forecast assumptions held EU Green Deal implementation timelines and IMO 2020 scrubber discharge chemistry fixed across the projection horizon, with zinc price volatility and lessor procurement consolidation treated as scenario variables. Segmentation modeling spanned coating chemistry tier, application method, end-user custody chain position, and durability warranty level. CAGRs were derived from production volume elasticity to fleet renewal cycles and regulatory compliance cost pass-through coefficients. Reefer container penetration and digital specification platform adoption served as demand-side inflection inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by regional Asian manufacturers or accelerated waterborne technology substitution by European lessors would shift outcomes. Cross-checking against Lloyd's List container fleet data and Drewry maritime research is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Anti-Corrosion Coating Market
Coatings
Perfluoroalkoxy (PFA) Coatings Market
Coatings
Global Polyurea Coating Market
Coatings
Polyester Coatings Market
Coatings
Europe Powder Coatings Market
Coatings
Process Pipe Coating Market
Coatings
Electron Beam Curable Coating Market
Coatings
Coatings and Fillings Market
Coatings
Acrylic Surface Coating Market
Coatings
Italy Automotive OEM Coatings Market
Coatings
Japan Automotive OEM Coatings Market
Coatings
Global Heat Resistant Coatings Market
Coatings
Australia Industrial Coatings Market
Coatings
Middle-East and Africa Thermal Spray Market
Coatings
Asia-Pacific Marine Coatings Market
Coatings
Japan Protective Coatings Market