
 US Industrial Coatings Market | 2026-2036
US Industrial Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
US Industrial Coatings Market Intelligence
Aftermarket service revenue for coating reapplication and corrosion management is reshaping how suppliers capture lifetime value from industrial assets. PPG Industries sustains broad manufacturing scale across automotive and aerospace channels. Axalta Coating Systems LLC specializes in mobility-focused formulations with deep OEM integration. The Sherwin-Williams Company controls extensive distribution infrastructure that reaches maintenance operations in remote mining and oilfield locations.
Industrial coatings are protective and decorative films applied to substrates through spraying, dipping, or electrostatic deposition, typically formulated with binders, pigments, solvents, and additives to achieve thicknesses of 25–250 microns for corrosion resistance, chemical protection, or aesthetic finish. Waterborne technology leads in new facility specifications as EPA VOC limits tighten, while powder coating commands premium positioning in automotive underbody and appliance applications where zero-VOC performance and edge coverage justify capital-intensive electrostatic lines. Solvent-borne systems retain share in marine and heavy equipment segments where extreme chemical exposure demands maximum cross-link density.
EPA enforcement of VOC content limits under the National Volatile Organic Compound Emission Standards for Consumer and Commercial Products directly determines formulation eligibility for architectural and industrial maintenance coatings. OSHA Permissible Exposure Limits for hexavalent chromium and isocyanates shape workplace engineering controls and drive substitution toward compliant pretreatment and curing chemistries. Stakeholders must monitor evolving PFAS restrictions from EPA and state-level regulators, as fluoropolymer-based high-performance coatings face potential reformulation mandates that would redistribute competitive advantage toward suppliers with advanced polymer research capabilities.
Market Dynamics
EPA VOC enforcement under the National Volatile Organic Compound Emission Standards is forcing rapid formulation turnover across automotive OEM and tier supplier networks, compressing product development cycles while opening procurement pathways for waterborne and powder alternatives.
Growth Catalysts
- EV Architecture Specialization:Electric vehicle battery enclosures and thermal management systems require dielectric coatings with enhanced thermal conductivity, pulling demand from Detroit and Austin manufacturing clusters.
- REACH-Aligned State Standards:California Air Resources Board regulations mirroring EU chemical restrictions are accelerating waterborne system adoption in West Coast aerospace finishing operations.
- Great Lakes Cluster Density:Proximity of automotive, aerospace, and heavy machinery OEMs in Michigan and Ohio enables just-in-time coating supply contracts with technical service integration.
Market Restraints
- Titanium Dioxide Volatility:Pigment cost swings tied to Chinese sulfate process capacity constrain margin predictability for architectural and industrial maintenance formulations.
- Isocyanate Exposure Controls:OSHA Permissible Exposure Limits for hexamethylene diisocyanate require expensive engineering controls that disadvantage smaller applicators in rural maintenance markets.
- Fluoropolymer Regulatory Overhang:Pending EPA PFAS restrictions threaten reformulation of high-performance coatings used in chemical processing equipment, creating compliance uncertainty.
Strategic Opportunities
- Texas Gulf Petrochemical Corridor:Underpenetrated maintenance coating demand from refineries and LNG export facilities offers specialized corrosion protection contracts with multi-year scopes.
- IRA Clean Manufacturing Credits:Inflation Reduction Act incentives for domestic production facility upgrades are unlocking capital for zero-VOC powder coating line installations.
- Digital Color Matching Integration:Convergence of spectrophotometry hardware with cloud-based formulation databases enables same-day custom color delivery to automotive collision repair networks.
Industry Challenges
- Applicator Certification Bottlenecks:NACE and SSPC coating inspector credential shortages delay project startup for infrastructure and marine contracts, extending sales-to-revenue cycles.
- Legacy Solvent System Stranded Assets:Capital-intensive spray booth and curing oven configurations designed for high-VOC chemistries face accelerated obsolescence before depreciation recovery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Industrial Coatings Market |
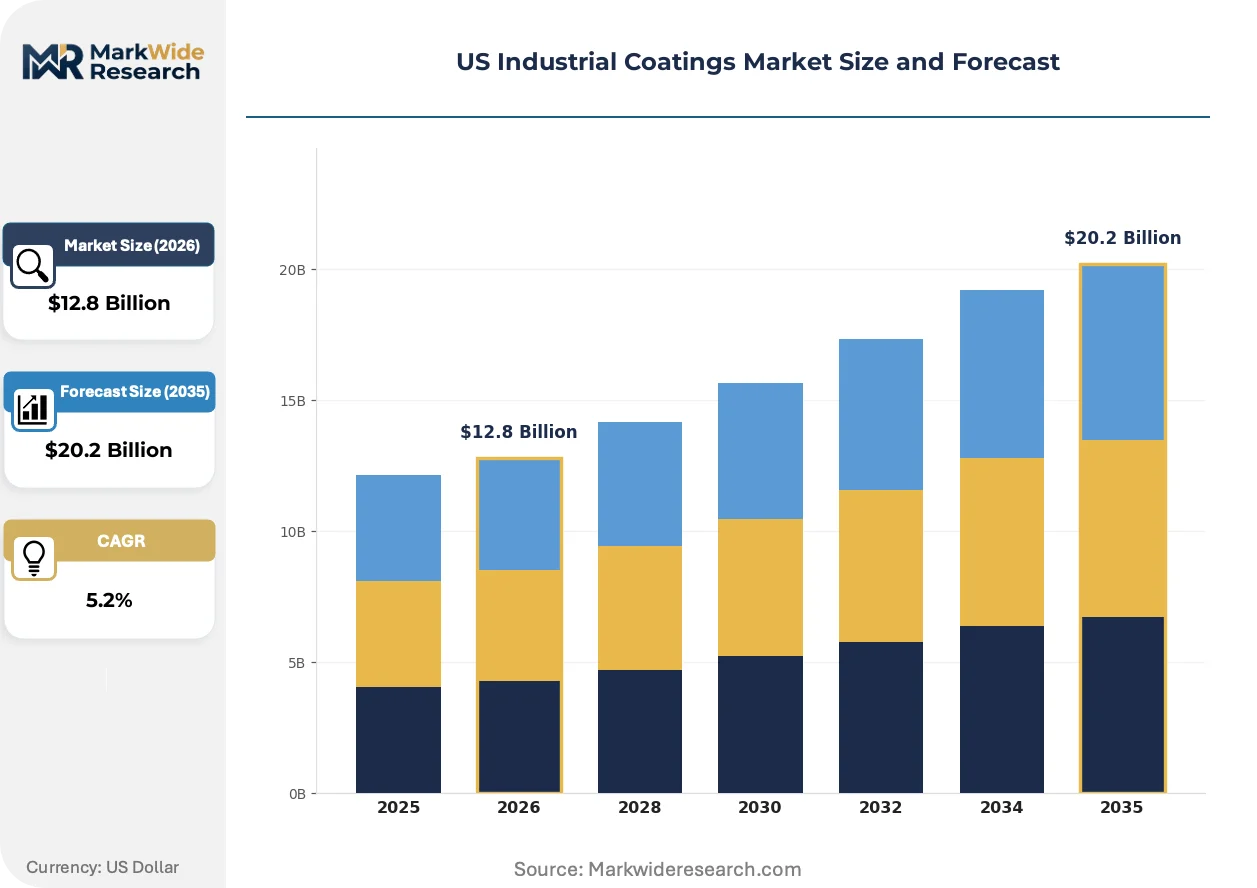
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $20.2 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Acrylic, Zinc Application: Automotive, Marine, Construction, Aerospace Technology: Waterborne, Solvent-borne, Powder Coating, UV Coating End User: Manufacturing, Infrastructure, Oil & Gas, Mining |
| Companies Covered | Axalta Coating Systems LLC, Nippon Paint Holdings Co., Ltd., PPG Industries Inc., Jotun A/S, BASF SE, The Sherwin-Williams Company, RPM International Inc., Hempel A/S, AkzoNobel N.V., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Industrial Coatings Market Strategic Shifts & Innovations
Formulation science and application technology are converging to redefine performance benchmarks across automotive, aerospace, and industrial maintenance segments, with regulatory chemistry constraints now driving rather than following product development priorities.
Self-healing coating technology utilizing microencapsulated healing agents is migrating from laboratory demonstration to qualified aerospace applications. Boeing and Lockheed Martin suppliers in the Pacific Northwest are piloting these systems on leading edge components where mechanical damage accumulation threatens structural integrity. The technology is migrating from premium military contracts toward narrow-body commercial aviation platforms as unit economics improve and FAA material qualification pathways standardize.
EPA enforcement of the National Emission Standards for Hazardous Air Pollutants for surface coating operations is eliminating solvent-borne system eligibility in new facility permits across automotive assembly plants. Tier suppliers in the Southeast and Midwest are absorbing capital costs for waterborne conversion lines while negotiating price pass-through mechanisms with OEM procurement offices. The regulatory pressure is most acute in passenger vehicle exterior body applications, where appearance standards previously blocked waterborne adoption.
Fleet maintenance departments at Class 8 trucking operators are consolidating coating procurement through national distributor agreements rather than regional job shop relationships. Ryder and Penske leasing divisions are driving this consolidation through standardized corrosion management protocols applied across pooled vehicle populations. The procurement concentration is most visible in the I-75 corridor connecting Michigan automotive supply bases with Florida distribution hubs, where high-mileage exposure accelerates reapplication cycles.
US Industrial Coatings Market Segmentation
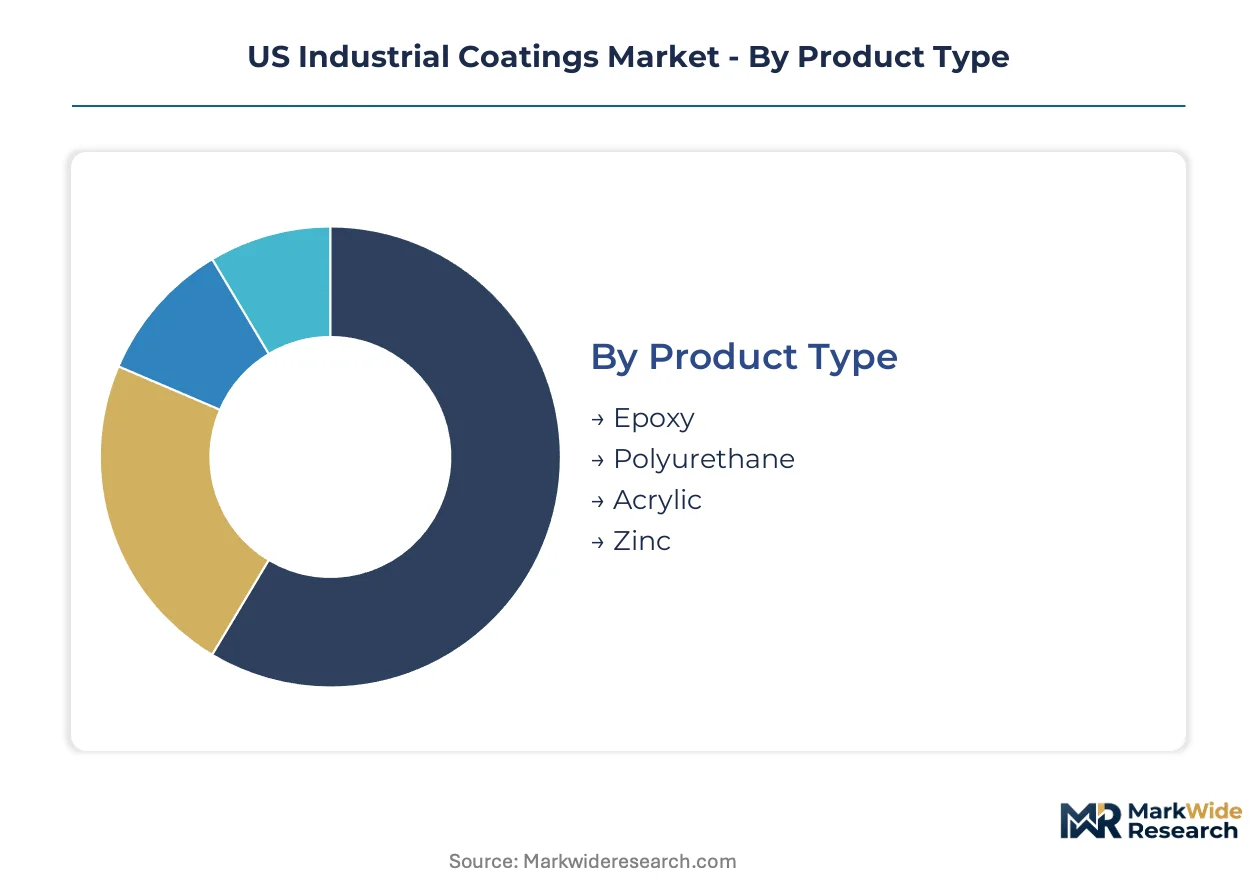
Industrial coatings segmentation reveals how formulation chemistry, application method, and end-use environment interact to determine procurement patterns across US manufacturing. Each dimension carries distinct margin profiles and regulatory exposure that shape supplier positioning strategies.
Product Type:
Mature epoxy systems dominate heavy industrial maintenance while emerging zinc-rich formulations capture share in infrastructure corrosion protection.
- Epoxy:Two-part thermosetting systems built from bisphenol-A and amine hardeners deliver chemical resistance and adhesion to metal substrates. Demand concentrates in Great Lakes petrochemical tank linings and marine ballast coatings where OSHA hexavalent chromium limits are forcing substitution away from inorganic zinc primers.
- Polyurethane:Aliphatic and aromatic isocyanate-cured films provide UV stability and gloss retention for exterior exposure. Automotive OEM clearcoats in Detroit and Chattanooga assembly plants pull volume as waterborne polyurethane dispersion technology matures for high-appearance applications.
- Acrylic:Thermoplastic and thermoset variants offer rapid dry-to-handle times for general industrial maintenance.
- Zinc:Inorganic and organic zinc-rich primers provide sacrificial cathodic protection for steel exposed to atmospheric corrosion.
Epoxy retains volume leadership; zinc holds the steepest expansion curve.
Application:
Cost tier segmentation separates capital-intensive OEM specifications from price-sensitive maintenance recoating contracts.
- Automotive:Exterior body, underbody, and plastic substrate coatings require Class-A appearance and chip resistance. Michigan and Ohio assembly plants drive specification authority as EPA VOC enforcement eliminates solvent-borne options for new facility permits.
- Marine:Antifouling, ballast tank, and topside systems face IMO 2020 sulfur compliance spillover effects on US-flag vessel maintenance budgets. Gulf Coast shipyards in Louisiana and Texas concentrate demand for MIL-PRF-24647 qualified hull coatings.
- Construction:Architectural steel and concrete protection spans commercial building and infrastructure projects.
- Aerospace:OEM and MRO coatings for commercial and military platforms require FAA qualification.
Automotive commands the premium tier; marine faces the most acute cost compression.
Technology:
Volume distribution reflects capital investment cycles as applicators retrofit spray booths for compliance.
- Waterborne:Acrylic and polyurethane dispersions with VOC content below regulatory thresholds. California Air Resources Board standards and EPA National Emission Standards are accelerating adoption in West Coast aerospace finishing and Midwest automotive plants where appearance specifications previously blocked penetration.
- Solvent-borne:High-solids alkyds and two-part epoxies retain position where chemical resistance demands maximum cross-link density. Marine and heavy equipment segments in the Gulf Coast petrochemical corridor continue procurement despite permitting restrictions on new installations.
- Powder Coating:Thermoset epoxy and polyester powders applied via electrostatic spray achieve zero-VOC performance.
- UV Coating:Photoinitiated acrylates cure instantly under ultraviolet exposure for flat-line wood and plastic applications.
Solvent-borne maintains installed base dominance; waterborne is gaining share fastest.
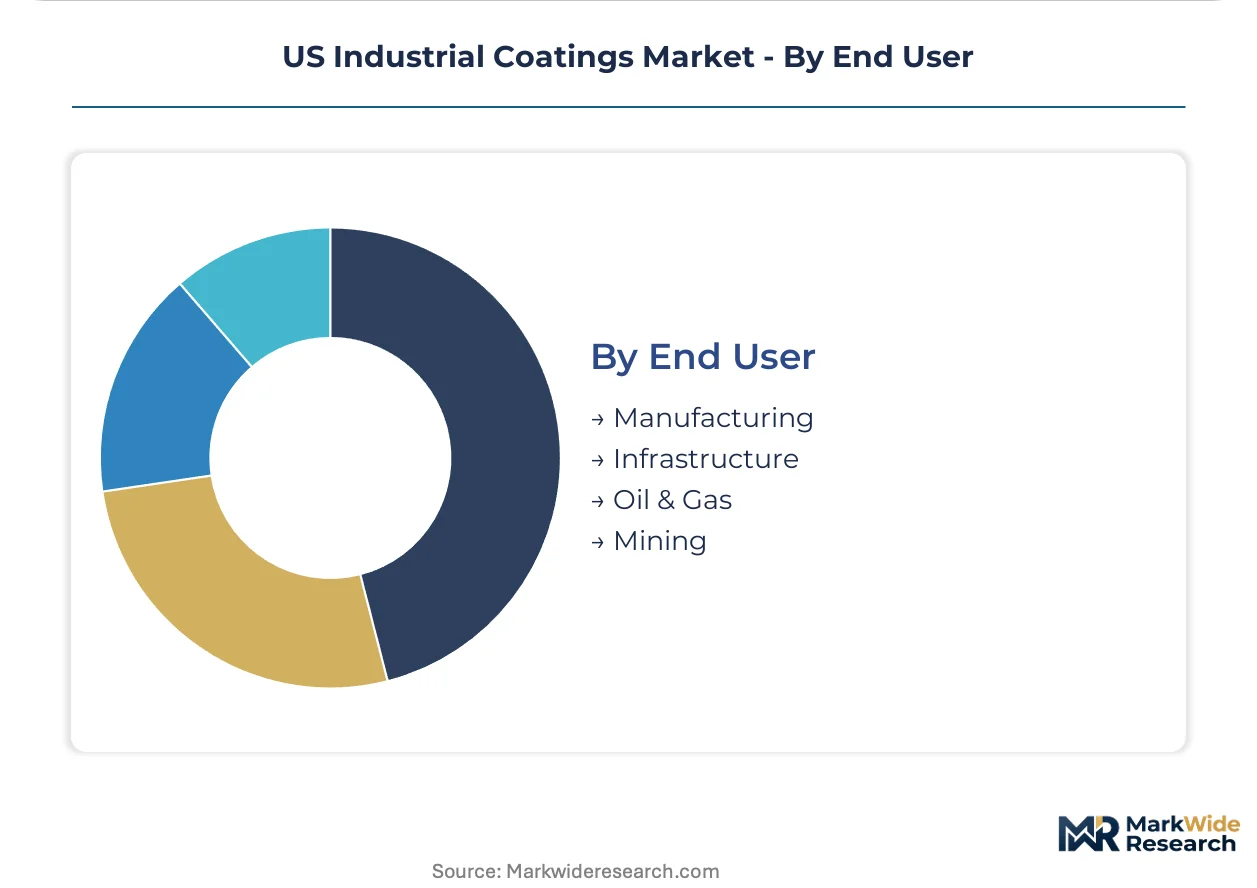
End User:
Customer type segmentation distinguishes centralized OEM procurement from fragmented maintenance contracting.
- Manufacturing:Automotive, appliance, and industrial equipment OEMs specify coatings through approved vendor lists with technical service integration. Tier supplier networks in the Southeast and Midwest absorb capital costs for waterborne conversion while negotiating price pass-through mechanisms.
- Infrastructure:Bridge, highway, and water treatment specifications follow state DOT and EPA procurement protocols. Federal infrastructure spending is concentrating demand in the Northeast and Pacific Coast where salt exposure accelerates reapplication cycles.
- Oil & Gas:Pipeline, storage tank, and offshore platform maintenance follows NACE and SSPC inspection standards.
- Mining:Haul truck, processing equipment, and facility corrosion management operates through remote site logistics.
Manufacturing captures the highest specification value; infrastructure offers the most predictable long-term contracting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coating consumption patterns diverge sharply across US sub-regions, with Great Lakes automotive OEMs driving high-specification volume while Gulf Coast petrochemical operators prioritize corrosion-resistant maintenance formulations.
Great Lakes Manufacturing Corridor
Michigan and Ohio automotive assembly plants generate concentrated demand for Class-A exterior coatings as EPA VOC enforcement eliminates solvent-borne options for new facility permits. OSHA Permissible Exposure Limits for hexavalent chromium are forcing substitution toward compliant pretreatment chemistries in Detroit-area tier supplier networks. Cleveland and Toledo industrial equipment manufacturers pull volume for epoxy and polyurethane systems serving aerospace and heavy machinery applications.
Southeast Automotive Belt
Tennessee and South Carolina vehicle assembly operations absorb capital costs for waterborne conversion lines while negotiating price pass-through mechanisms with OEM procurement offices. EPA National Emission Standards for Hazardous Air Pollutants are accelerating coating technology turnover in Chattanooga and Greenville manufacturing plants. Tier supplier density around Spartanburg and Nashville enables just-in-time supply contracts with embedded technical service integration.
Texas Gulf Petrochemical Corridor
Refinery and LNG export facility maintenance generates underpenetrated demand for specialized corrosion protection systems with multi-year contract scopes. Texas Commission on Environmental Quality regulations mirror federal EPA standards while imposing additional permitting requirements on new coating installations. Houston and Beaumont industrial service providers concentrate procurement of high-solids epoxy and zinc-rich formulations for storage tank and pipeline applications.
West Coast Aerospace Cluster
California and Washington commercial aviation finishing operations drive specification authority for advanced coating systems as Boeing and Lockheed Martin suppliers pilot self-healing technologies. California Air Resources Board regulations accelerating waterborne adoption exceed federal EPA thresholds in Los Angeles and Seattle metropolitan manufacturing zones. FAA material qualification pathways are standardizing novel chemistries for narrow-body commercial platforms.
Northeast Infrastructure Zone
Federal infrastructure spending is concentrating bridge and highway coating demand in New York and Massachusetts where salt exposure accelerates reapplication cycles. State DOT procurement protocols follow NACE and SSPC inspection standards that delay project startup due to credential shortages. Boston and Philadelphia metropolitan construction markets pull volume for architectural steel protection systems.
US Industrial Coatings Market Key Industry Players
Capability concentration sits with specialized formulation houses; scale advantage sits with diversified chemical conglomerates. The vendor base organizes into three tiers: global integrated suppliers with full technology portfolios, regional specialists with deep OEM relationships, and niche maintenance coating providers serving remote industrial sites. Consolidation pressure is intensifying as waterborne and powder technology conversion costs strain smaller applicators. Dominant competitive moves include strategic partnerships for digital color matching integration and capacity expansion for zero-VOC powder coating lines.
Among diversified coating manufacturers, PPG Industries, The Sherwin-Williams Company, and Axalta Coating Systems LLC occupy positions across automotive OEM and industrial maintenance segments. PPG exemplifies the integrated multinational archetype with broad manufacturing scale. Sherwin-Williams represents the distribution-anchored model reaching remote mining and oilfield maintenance operations. Axalta sits within the mobility-focused specialist tier with deep OEM integration capabilities. These three entities anchor competitive dynamics as regulatory chemistry constraints redistribute procurement pathways toward compliant formulation suppliers.
| Leading Market Players |
|---|
| Axalta Coating Systems LLC |
| Nippon Paint Holdings Co., Ltd. |
| PPG Industries Inc. |
| Jotun A/S |
| BASF SE |
| The Sherwin-Williams Company |
| RPM International Inc. |
| Hempel A/S |
| AkzoNobel N.V. |
| Others |
Cost & Logistics Intelligence
Chinese titanium dioxide sulfate process capacity concentrates upstream pigment supply, anchoring margin volatility for downstream formulation houses serving automotive OEMs and industrial maintenance contractors across the Great Lakes and Gulf Coast corridors.
Pricing Analysis
Long-term offtake agreements dominate procurement between automotive OEMs and tier suppliers, insulating volume commitments from spot pigment volatility while project-based contracting governs infrastructure maintenance applications. Price differentiation rests on VOC compliance certification grade and embedded technical service intensity, with EPA-compliant waterborne systems commanding premiums over legacy solvent-borne alternatives. Cost compression in standard-grade architectural formulations is intensifying because titanium dioxide feedstock swings transmit directly to bill-of-materials. Fleet maintenance departments at Class 8 trucking operators exhibit highest price sensitivity, whereas aerospace OEMs prioritize qualification continuity over unit cost.
Supply Chain Analysis
Toll manufacturing concentration sits with PPG Industries, The Sherwin-Williams Company, and Axalta Coating Systems LLC, which operate captive production networks across Michigan, Ohio, and Texas. Raw material dependencies draw from Chinese titanium dioxide, German isocyanate precursors, and domestic epoxy resin production anchored in the Texas Gulf petrochemical corridor. Single-source vulnerability concentrates in specialized zinc-rich primer formulations qualified for NACE and SSPC infrastructure specifications. Distribution runs through national distributor agreements consolidating fleet maintenance procurement, with regional job shop relationships fragmenting oilfield and mining site service.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US Industrial Coatings Market functions as a platform-economics inflection where digital color matching infrastructure and cloud-based formulation databases are redefining technical service bundling as the core interoperability layer between suppliers and collision repair networks.
For Market Incumbents: Build switching-cost moats through embedded spectrophotometry hardware integration and same-day custom color delivery guarantees to automotive collision repair networks. Defensive consolidation should prioritize backward integration into titanium dioxide sourcing alternatives to offset Chinese supply concentration, while capacity addition in zero-VOC powder coating lines captures IRA Clean Manufacturing Credit flows. Threat substitution from self-healing aerospace technologies demands R&D investment in microencapsulated healing agent platforms.
For New Entrants and Emerging Players: Build out specialized corrosion protection service capabilities targeting the underpenetrated Texas Gulf petrochemical corridor, where refinery and LNG export facility maintenance contracts carry multi-year scopes with limited incumbent technical integration. The most penetrable segment sits in remote mining site logistics, where Sherwin-Williams distribution dominance leaves price-sensitive openings for regional specialists. Go-to-market execution should anchor in NACE and SSPC certification investment to bypass applicator credential bottlenecks delaying project startup.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional maintenance coating providers serving oilfield and infrastructure applications, where fragmented ownership structures and compliance conversion capital requirements create rollup opportunities. Long-term viability over a multi-year horizon hinges on waterborne technology conversion completion and PFAS regulatory resolution. The signal to watch is EPA finalization of fluoropolymer restrictions, which would force reformulation of high-performance chemical processing equipment coatings and redistribute competitive advantage toward advanced polymer research capabilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Titanium Dioxide Sourcing | Reduces exposure to Chinese sulfate process capacity swings affecting margin predictability. |
| Zero-VOC Powder Coating Line Expansion | Captures IRA Clean Manufacturing Credits while meeting EPA National Emission Standards. |
| Digital Color Matching Platform Integration | Enables same-day custom color delivery to Ryder and Penske fleet maintenance networks. |
| Self-Healing Coating Technology Qualification | Positions suppliers for Boeing and Lockheed Martin narrow-body commercial aviation contracts. |
| Long-Term Supply Agreement with EV Battery Enclosure Manufacturers | Locks in dielectric coating demand from Detroit and Austin electric vehicle clusters. |
Research Approach
A standing panel of automotive OEM procurement directors, tier supplier plant managers, industrial maintenance contractors, and NACE-certified coating inspectors provided ongoing calibration across the research cycle. Primary interviews with these stakeholders combined with secondary validation from EPA enforcement records, OSHA Permissible Exposure Limit documentation, SEC 10-K filings from listed coating manufacturers, and American Chemistry Council trade flow data. Bottom-up volume estimates from facility-level production data triangulated against top-down market sizing derived from automotive assembly plant coating consumption rates.
Scenario-bracketing across regulatory enforcement intensity, titanium dioxide price bands, and EV production penetration shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include formulation chemistry, application method, technology type, and end-use industry vertical. CAGRs were derived from regression analysis against historical automotive production correlations and infrastructure spending authorization trajectories. Forecast inputs incorporated EPA VOC compliance deadline schedules and California Air Resources Board adoption curve assumptions.
Stress conditions across Chinese titanium dioxide export restrictions, accelerated PFAS regulatory timelines, and EV architecture transition speeds were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and raw material supply continuity. Quarterly review of EPA enforcement actions, NACE credential availability, and IRA credit utilization rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Acrylic Surface Coating Market
Coatings
Europe Waterborne Polyurethane Coatings Market
Coatings
Powder Coating Booth Market
Coatings
PU Coatings Market
Coatings
Polyester Coatings Market
Coatings
Coating Auxiliaries Market
Coatings
Global Laser Cladding Service Market
Coatings
Europe Coil Coatings Market
Coatings
Carpet Back Coatings Market
Coatings
Canada Protective Coatings Market
Coatings
Protective and Marine Coatings Market
Coatings
Acrylic Coating Market
Coatings
Solar Reflective Film Market
Coatings
US Protective Coatings Market
Coatings
Global Graphite Coatings Market
Coatings
Technical Coil Coatings Market