
 Coating Thickness Gauge Market | 2026-2036
Coating Thickness Gauge Market Size, Share, and Industry Trends Forecast 2026-2036
Coating Thickness Gauge Market Outlook
Automotive end-use is shifting toward electric vehicle battery enclosure coating inspection as OEMs tighten corrosion protection standards. Elcometer Limited leverages its electromagnetic gauge portfolio to anchor European automotive supplier relationships. DeFelsko Corporation sustains North American market presence through specialized eddy current instruments for powder coating lines. Mitutoyo Corporation dominates precision manufacturing channels with integrated digital thickness systems.
A coating thickness gauge measures dry film thickness on metallic substrates using magnetic induction, eddy current, or ultrasonic pulse-echo principles with typical resolution of 0.1 micrometers. The device verifies protective coating compliance in corrosion-critical applications across marine, infrastructure, and transportation equipment. Digital product types lead unit volume as Bluetooth-enabled data logging replaces manual recording in quality systems. Electromagnetic technology occupies the largest installed base, though eddy current instruments represent the fastest-growing category for non-ferrous substrate inspection. Aerospace end-user demand generates premium-margin pools due to NADCAP traceability requirements.
ISO 19840, SSPC-PA 2, and ASTM D7091 govern coating thickness verification across major industrial economies, with national metrology institutes in Germany, the United States, and Japan operating calibration traceability hierarchies. China's NIM and Germany's PTB enforce mutual recognition arrangements that shape cross-border gauge certification requirements. Stakeholders must monitor evolving EV battery safety standards and marine decarbonization coating rules to anticipate specification changes ahead of procurement cycles.
Market Dynamics
Automotive OEMs are consolidating coating inspection protocols around EV battery enclosures, forcing gauge suppliers to recalibrate electromagnetic sensor arrays for aluminum-intensive substrates while shipyards absorb ISO 19840 compliance costs.
Growth Catalysts
- ISO 19840 mandates:European and Asian shipyards must deploy certified digital measurement systems for marine coating verification, expanding procurement volumes for electromagnetic and eddy current gauges.
- EV battery enclosure inspection:Automotive OEMs are tightening corrosion protection standards for electric vehicle battery housings, creating dedicated coating thickness verification workflows.
- China:Infrastructure contractors along coastal provinces face accelerated bridge and port maintenance schedules, driving gauge replacement cycles for ultrasonic pulse-echo systems.
Market Restraints
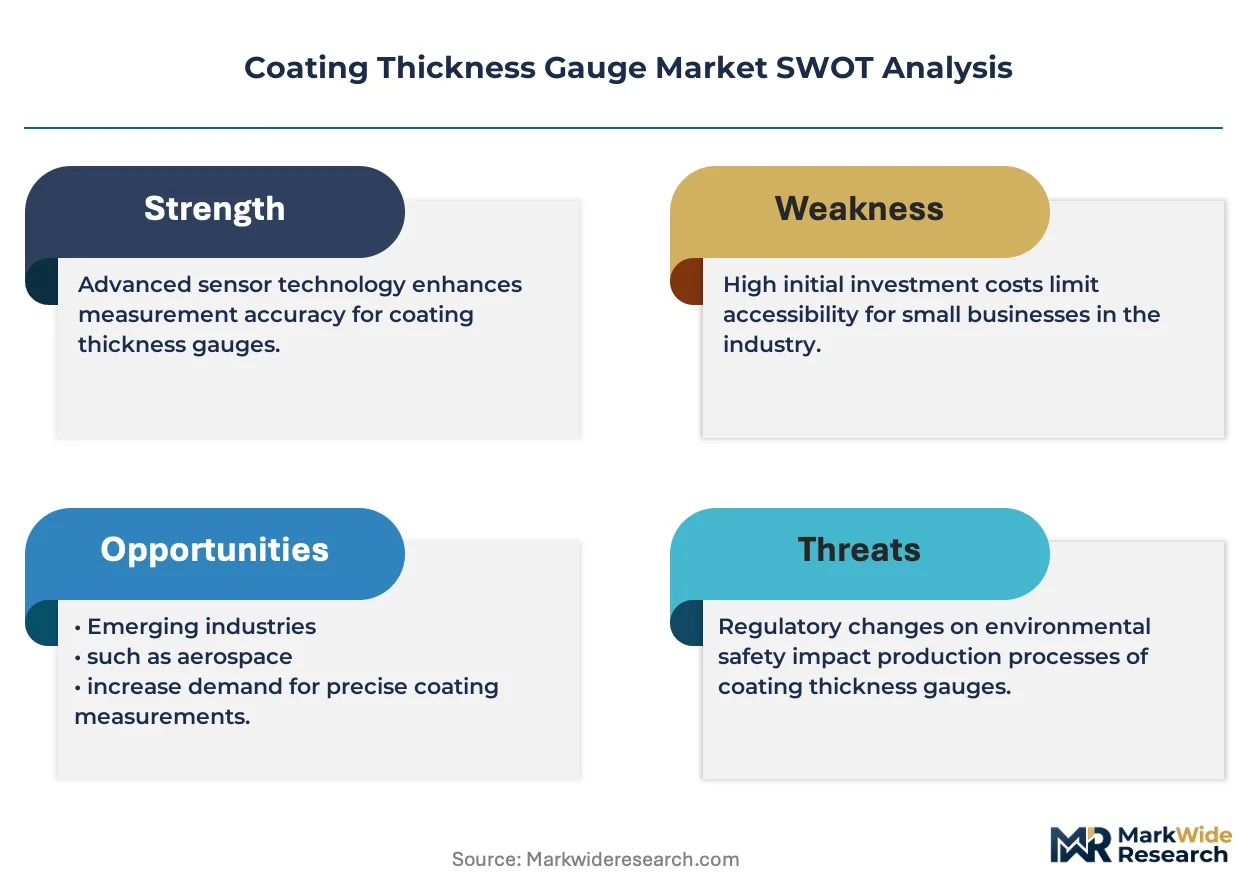
- Calibration traceability costs:National metrology institutes in Germany, the United States, and Japan operate hierarchical certification systems that inflate total cost of ownership for mid-tier gauge operators.
- Electromagnetic sensor limitations:Magnetic induction gauges face technical constraints measuring non-ferrous substrates, fragmenting procurement across multiple instrument types.
- Substitution by integrated quality systems:Inline spectroscopic coating analyzers are capturing share in high-volume automotive paint lines, compressing standalone gauge demand.
Strategic Opportunities
- India:Domestic automotive manufacturing expansion under PLI scheme incentives has outpaced local gauge calibration infrastructure, creating first-mover advantages for certified service networks.
- Bluetooth-enabled data logging:Wireless connectivity convergence with quality management software is displacing manual recording workflows, opening retrofit markets in legacy manufacturing facilities.
- Aerospace NADCAP traceability:Premium-margin inspection contracts for military and commercial aviation coatings remain underpenetrated by mainstream gauge suppliers.
Industry Challenges
- Multi-substrate certification complexity:Quality engineers must maintain proficiency across electromagnetic, eddy current, and ultrasonic measurement principles, stretching training budgets.
- Legacy system integration:Shipyards and infrastructure contractors operate decades-old coating inspection databases that resist direct data export from modern Bluetooth-enabled gauges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coating Thickness Gauge Market |
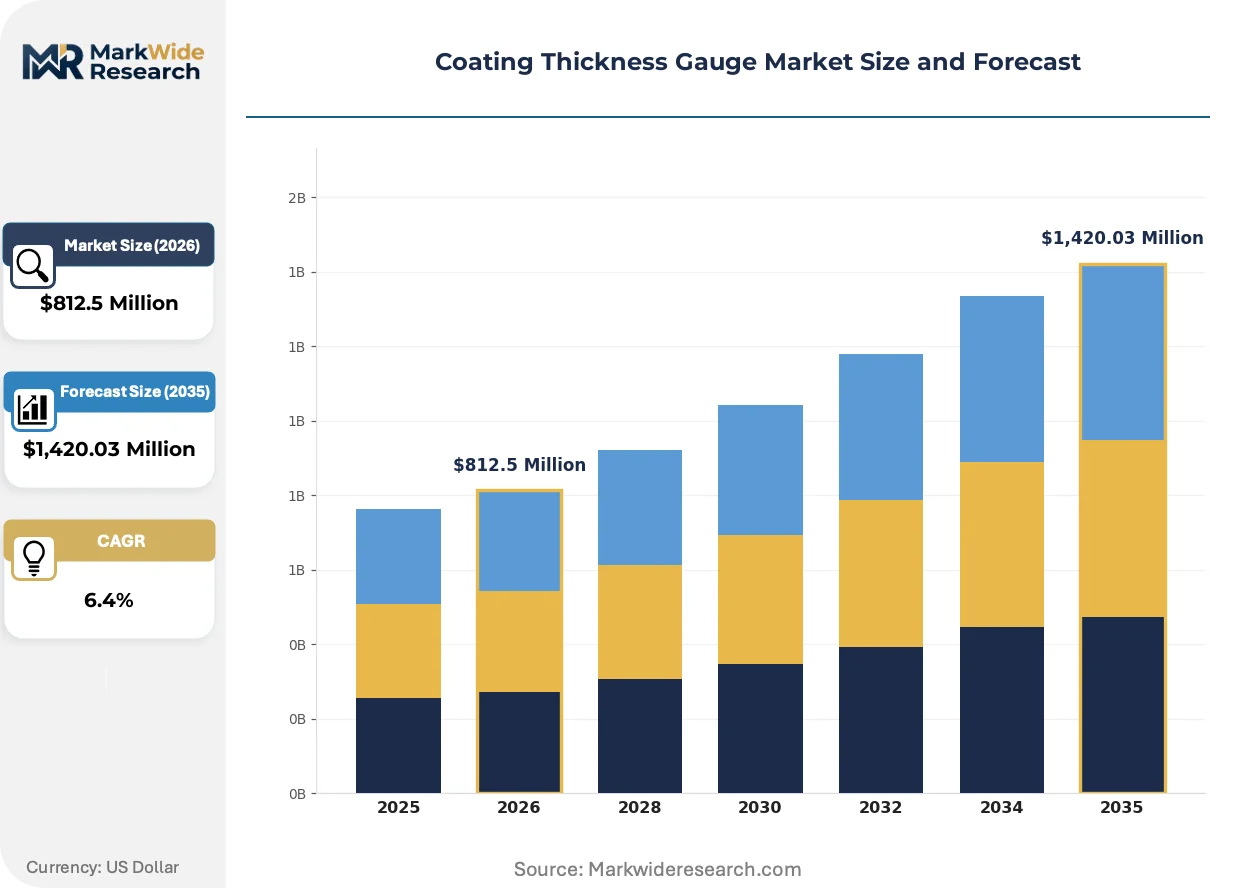
| Market Size in 2026 | $812.5 Million |
| Market Size in 2035 | $1,420.03 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital, Analog, Ultrasonic, Magnetic Technology: Electromagnetic, Laser, Eddy Current, X-Ray End User: Aerospace, Automotive, Construction, Electronics Distribution Channel: Direct Sales, Online Retail, Distributors, Resellers |
| Companies Covered | BYK-Gardner GmbH, HORIBA Ltd., Helmut Fischer GmbH, Cygnus Instruments Ltd., ElektroPhysik Dr. Steingroever GmbH & Co. KG, Elcometer Limited, Mitutoyo Corporation, Fischer Technology Inc., DeFelsko Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coating Thickness Gauge Market Strategic Shifts
Digital connectivity and substrate versatility are reshaping competitive positioning in coating measurement, with sensor fusion and regulatory harmonization compressing traditional technology silos.
Eddy current instrumentation is consolidating market presence across non-ferrous substrate applications. Aluminum-intensive EV architectures and marine superstructures demand gauges capable of operating without ferromagnetic base materials. Automotive tier-one suppliers in Germany and China are phasing out single-technology instruments, consolidating procurement around dual-purpose electromagnetic-eddy current hybrid units that reduce calibration overhead.
REACH compliance documentation requirements are extending coating thickness verification into chemical safety data management. European coating applicators must now correlate dry film thickness measurements with volatile organic compound exposure calculations, embedding gauge data into broader environmental health and safety workflows. Marine coating contractors in Rotterdam and Hamburg are responding by integrating thickness readings directly into digital substance inventories.
Certification-driven purchasing is compressing vendor selection cycles. Quality managers now prioritize gauges with pre-loaded ISO 19840, SSPC-PA 2, and ASTM D7091 test protocols, displacing general-purpose instruments that require manual standard configuration. This preference shift concentrates procurement among suppliers with embedded compliance software, particularly visible in Japanese automotive and Korean shipbuilding procurement channels.
Coating Thickness Gauge Market Segmentation
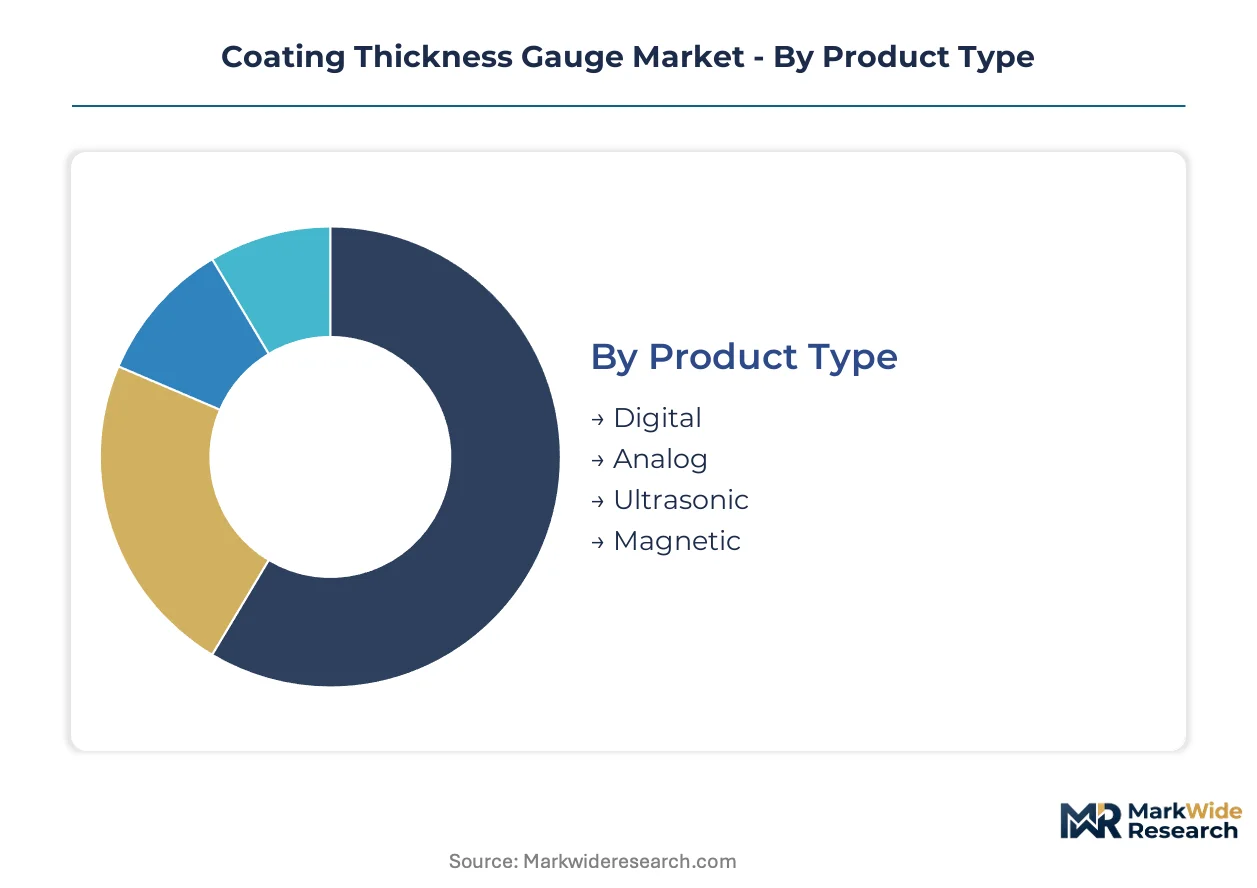
Coating thickness gauge procurement fragments across four structural dimensions. Product type and technology choices determine calibration infrastructure requirements. End-user verticals and distribution channels shape margin capture and service attach rates.
Product Type:
Digital instruments concentrate revenue in automotive and marine inspection workflows where ISO 19840 traceability mandates predominate.
- Digital:Bluetooth-enabled units with pre-loaded compliance protocols command premium positioning in German automotive supplier channels. OEM quality departments in Stuttgart and Wolfsburg specify these for EV battery enclosure verification workflows.
- Ultrasonic:Pulse-echo systems penetrate concrete and composite substrates where electromagnetic methods fail. Infrastructure contractors across China's coastal provinces deploy these for bridge maintenance programs.
- Analog:Mechanical dial gauges persist in legacy shipyard operations where digital infrastructure remains underdeveloped.
- Magnetic:Basic induction units serve cost-sensitive maintenance operations with minimal certification requirements.
Today's leader: Digital. Tomorrow's challenger: Ultrasonic.
Technology:
Electromagnetic sensors anchor the installed base while eddy current arrays unlock aluminum substrate applications.
- Electromagnetic:Magnetic induction principles dominate ferrous substrate inspection across European shipbuilding. Hamburg and Rotterdam marine contractors specify these for steel hull coating verification.
- Eddy Current:Non-ferrous measurement capability addresses aluminum-intensive EV architectures. German and Chinese tier-one suppliers are consolidating procurement around hybrid electromagnetic-eddy current units.
- Laser:Non-contact triangulation systems serve specialized electronics manufacturing where substrate damage risks exclude probe-based methods.
- X-Ray:Backscatter instruments penetrate multi-layer coatings in aerospace NADCAP environments.
Electromagnetic retains volume leadership. Eddy current gains share fastest.
End User:
Automotive quality protocols generate the densest gauge deployment per facility.
- Automotive:EV battery enclosure inspection creates dedicated coating verification stations. OEMs in Germany, China, and the United States specify multi-technology instruments for corrosion warranty compliance.
- Aerospace:NADCAP traceability requirements sustain premium-margin procurement for military and commercial aviation coatings.
- Construction:Infrastructure maintenance drives ultrasonic gauge replacement cycles across bridge and port assets.
- Electronics:Precision manufacturing channels demand integrated digital thickness systems for component protection layers.
Automotive dominates procurement volume. Aerospace commands highest unit margins.
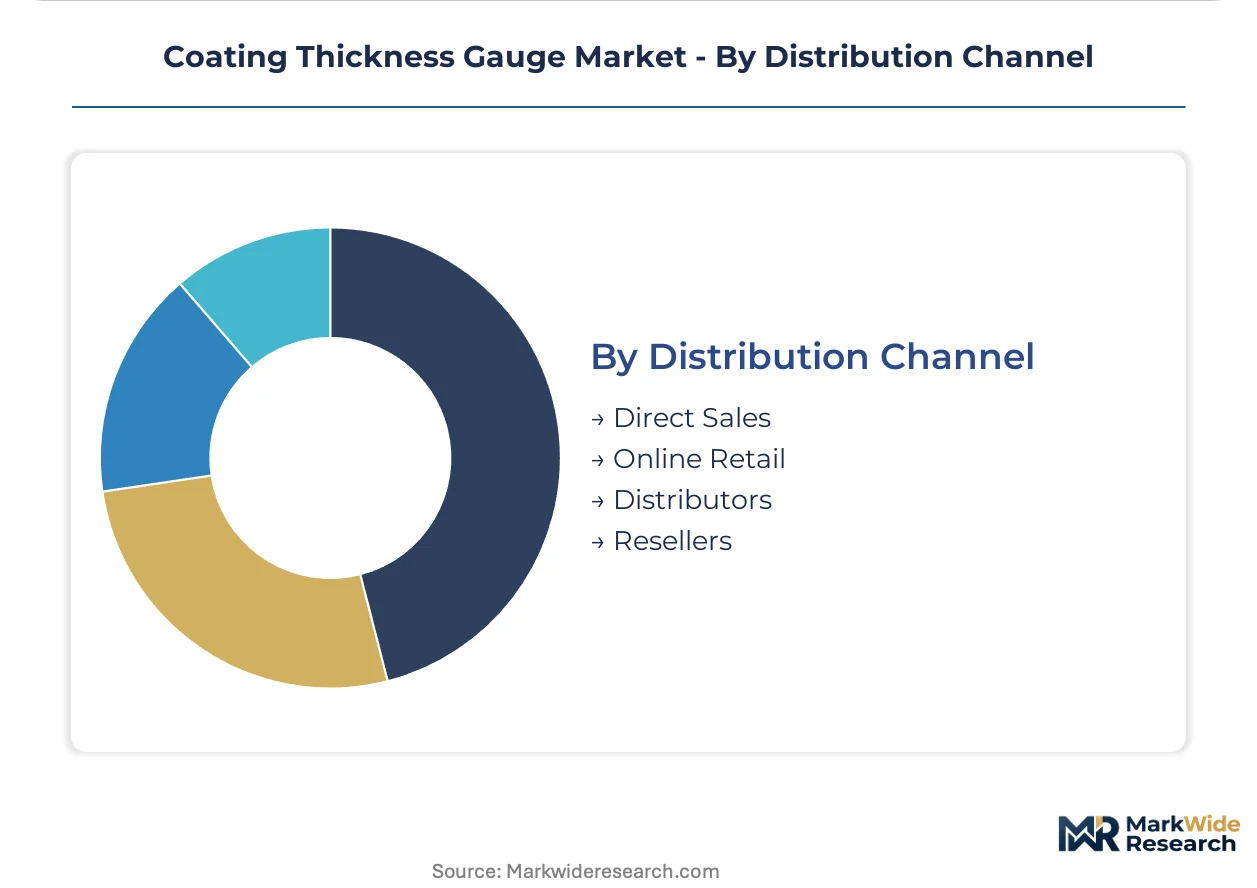
Distribution Channel:
Certified service networks determine competitive positioning in markets with immature calibration infrastructure.
- Direct Sales:Instrument manufacturers deploy technical specialists for automotive OEM specification development. Elcometer and DeFelsko maintain direct relationships with European and North American quality departments.
- Distributors:Regional stocking partners capture mid-tier gauge demand with localized calibration support.
- Online Retail:E-commerce channels serve replacement probe and consumable demand in established manufacturing bases.
- Resellers:Independent agents penetrate price-sensitive maintenance operations with limited compliance requirements.
Direct sales anchors premium positioning. Distributors expand geographic coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redistributing coating thickness gauge procurement as manufacturers relocate quality control operations to jurisdictions with streamlined calibration traceability regimes. Cost-of-compliance gaps between national metrology infrastructures are accelerating facility placement decisions in automotive and marine coating inspection.
Germany
Automotive OEMs in Stuttgart and Wolfsburg are mandating ISO 19840-certified digital gauges for EV battery enclosure workflows. PTB operates the calibration hierarchy that anchors European traceability requirements. Hamburg shipyards deploy electromagnetic instruments for steel hull verification under REACH-integrated substance inventory protocols.
China
Infrastructure contractors across coastal provinces face accelerated bridge maintenance schedules driving ultrasonic gauge replacement. NIM enforces mutual recognition arrangements with PTB that shape cross-border certification. Yangtze River Delta automotive clusters specify hybrid electromagnetic-eddy current units for aluminum-intensive EV architectures.
United States
NADCAP traceability requirements sustain premium-margin aerospace procurement in military and commercial aviation coatings. OSHA workplace safety frameworks intersect with coating verification protocols in heavy manufacturing. Michigan and Ohio automotive corridors consolidate inspection standards around multi-technology instruments for corrosion warranty compliance.
Japan
Precision manufacturing channels demand integrated digital thickness systems for component protection layers. METI oversees JIS standards that govern instrument calibration hierarchies. Kanto region electronics fabricators deploy laser triangulation systems where substrate damage risks exclude probe-based methods.
India
Domestic automotive manufacturing expansion under PLI scheme incentives has outpaced local gauge calibration infrastructure. BIS certification requirements are tightening for imported measurement instruments. Maharashtra and Gujarat industrial corridors create first-mover opportunities for certified service network deployment.
Coating Thickness Gauge Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with consolidated procurement channels in automotive OEMs contrasting fragmented maintenance operations. The vendor base organizes around three strategic archetypes: precision instrumentation conglomerates with metrology portfolios, specialized coating measurement houses with regional calibration networks, and diversified industrial testing firms with cross-application sensor platforms. M&A activity concentrates among European gauge houses acquiring digital connectivity capabilities, while Asian manufacturers expand through backward integration into sensor array production.
Among Germany-based precision instrumentation groups, Helmut Fischer GmbH and ElektroPhysik Dr. Steingroever GmbH & Co. KG occupy positions within the high-compliance tier serving PTB-traceable certification requirements. Elcometer Limited and DeFelsko Corporation exemplify the specialized coating measurement archetype with established regional service infrastructures. Mitutoyo Corporation represents the diversified industrial testing model with integrated digital thickness systems spanning precision manufacturing channels.
| Leading Market Players |
|---|
| BYK-Gardner GmbH |
| HORIBA Ltd. |
| Helmut Fischer GmbH |
| Cygnus Instruments Ltd. |
| ElektroPhysik Dr. Steingroever GmbH & Co. KG |
| Elcometer Limited |
| Mitutoyo Corporation |
| Fischer Technology Inc. |
| DeFelsko Corporation |
| Others |
Value Chain & Pricing Dynamics
REACH compliance documentation gates qualified supply and premium-tier pricing access for European coating applicators who must correlate dry film thickness with volatile organic compound exposure calculations, embedding gauge data into environmental health and safety workflows that only certified vendors can fulfill.
Pricing Analysis
Distributor margins absorb calibration infrastructure costs before instruments reach mid-tier operators. Three-tier pricing structure across premium, standard, and economy levels separates PTB-traceable certified units from general-purpose instruments and basic magnetic gauges. Cost compression in the standard tier intensifies as Asian manufacturers expand sensor array production. Maintenance operations with minimal compliance requirements exhibit highest price sensitivity, while aerospace NADCAP contracts show lowest.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Stuttgart and Wolfsburg automotive quality departments. Component sourcing draws from Germany for precision sensor arrays, Japan for integrated digital systems, and China for ultrasonic pulse-echo modules. Hall sensor and eddy current coil supply rests on rare earth processing concentrated in Chinese refining operations. Single-source vulnerability in metrology-grade magnet supply creates procurement risk. Distribution runs through certified service networks in markets with immature calibration infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Calibration cost arbitrage between Germany and India creates geographic-relocation incentives for gauge operators seeking PTB-equivalent certification at lower total cost of ownership.
For Market Incumbents: Acquire certified service network assets in Maharashtra and Gujarat industrial corridors before PLI scheme incentives attract competing infrastructure investment. Consolidate electromagnetic-eddy current hybrid sensor platforms to defend against inline spectroscopic analyzers capturing automotive paint line share. Backward integration into hall sensor production reduces rare earth supply exposure. For New Entrants and Emerging Players: ISO 19840 in European and Asian shipyards opens a window for specialized marine coating verification instruments with pre-loaded compliance protocols. Target India's domestic automotive manufacturing expansion where BIS certification requirements are tightening for imported instruments. Partner with existing distributors lacking calibration capabilities to accelerate market entry. For Investors and Strategic Acquirers: Roll-up economics work for regional calibration service providers because national metrology institute hierarchies create defensible local moats. Five-to-ten year viability hinges on EV battery enclosure inspection standardization across multiple OEMs. Watch for NADCAP traceability requirement expansion into commercial aviation sub-tier suppliers as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Production | Captive hall sensor supply insulates German manufacturers from rare earth processing bottlenecks. |
| Certified Service Network Expansion | First-mover deployment in Maharashtra and Gujarat captures PLI-driven automotive gauge demand. |
| Hybrid Instrument Platform Launch | Dual electromagnetic-eddy current units reduce calibration overhead for aluminum-intensive EV architectures. |
| Bluetooth-Enabled Data Logging Retrofit | Wireless connectivity displaces manual recording in legacy shipyard quality systems. |
| NADCAP Traceability Certification Investment | Premium-margin aerospace contracts remain underpenetrated by mainstream gauge suppliers. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions engaged quality control directors at automotive OEMs, marine coating contractors in Hamburg and Rotterdam, calibration laboratory managers at PTB-traceable facilities, and procurement leads at tier-one automotive suppliers. Secondary validation drew from ISO 19840 implementation guidelines, ASTM D7091 standard documentation, customs trade data for electromagnetic instrument shipments, and SEC filings of listed precision instrumentation groups. Bottom-up gauge deployment estimates triangulated against top-down market sizing from automotive production and shipbuilding activity.
Segment-weighting applied technology-type splits across electromagnetic, eddy current, ultrasonic, and laser principles, crossed with end-user verticals including automotive, aerospace, marine, and infrastructure. Product type differentiation between digital, analog, and hybrid instruments shaped volume assumptions. CAGRs derived from regression against automotive EV battery enclosure inspection adoption curves and ISO 19840 mandate implementation timelines. Price trajectories incorporated certification tier premiums and Bluetooth connectivity attach rates.
Revisions become necessary when EV battery safety standards expand coating verification protocols or marine decarbonization rules alter superstructure coating specifications. Forecasts reflect assumptions about regulatory harmonization pace and substitution threat from inline spectroscopic systems. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
France Protective Coatings Market
Coatings
Sol-Gel Coatings Market
Coatings
Canada Floor Coatings Market
Coatings
Plastic-Coated Wires Market
Coatings
Global Fusion Bonded Epoxy Coatings Market
Coatings
Global Graphite Coatings Market
Coatings
Protective Antimicrobial Coatings for High-Touch Surfaces Market
Coatings
United Arab Emirates Floor Coatings Market
Coatings
North America Polyimide Coating Market
Coatings
Hydrophilic Interior Glass Defogging Coatings Market
Coatings
Germany Protective Coatings Market
Coatings
Stain Resistant Coatings Market
Coatings
Conductive Polymer Coatings Market
Coatings
Asia-Pacific Floor Coatings Market
Coatings
Food Grade Ceramic Coatings Market
Coatings
Japan Protective Coatings Market