
 Global Anti-Smudge Coatings Market | 2026-2036
Global Anti-Smudge Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Anti-Smudge Coatings Market Foresight
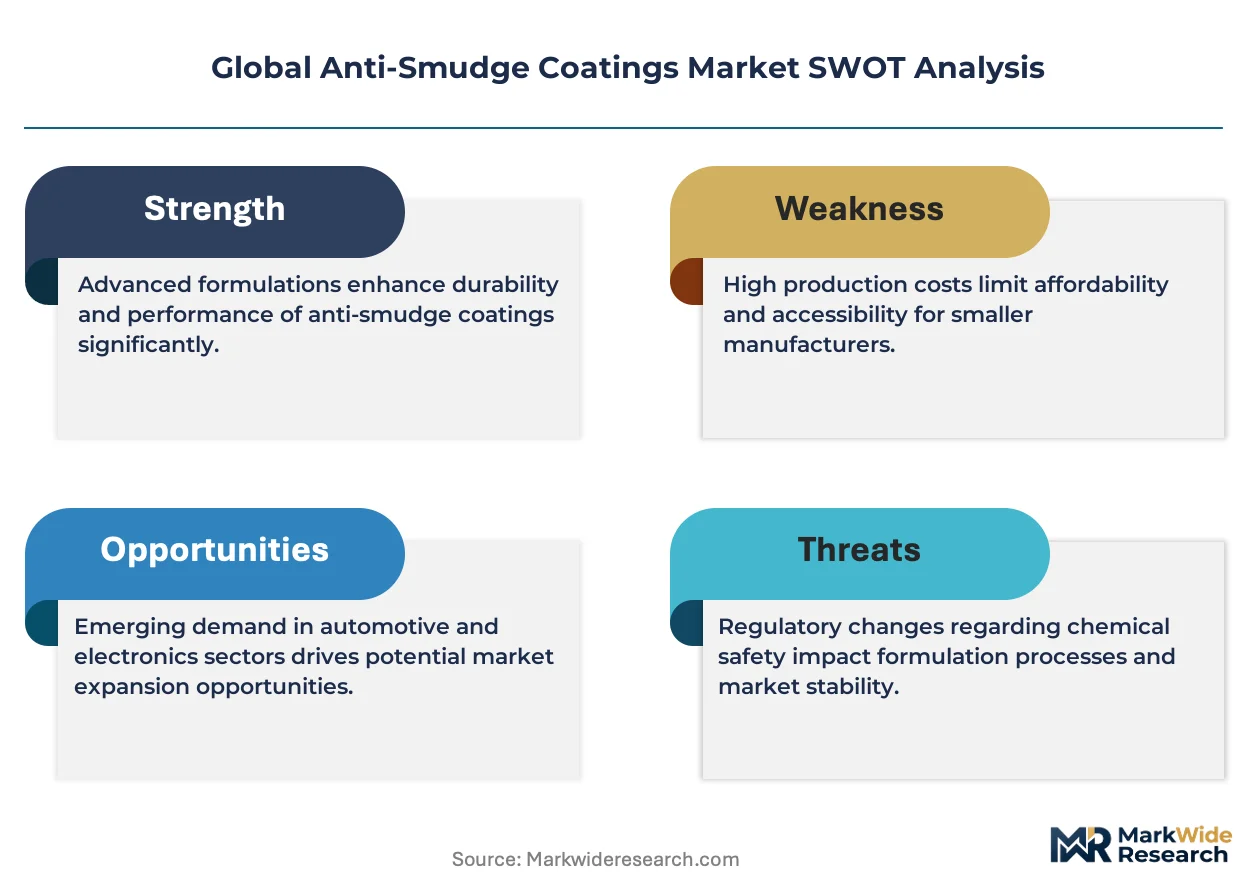
Premium-grade oleophobic specification tiers is unwinding the competitive landscape toward higher-performance formulations. AGC Chemicals leverages its fluoropolymer expertise to anchor supply relationships with major display manufacturers. Daikin Industries, Ltd. dominates fluorinated raw material streams through backward integration into tetrafluoroethylene production. PPG Industries, Inc. competes across automotive and electronics channels with urethane-acrylic hybrid platforms.
Anti-smudge coatings comprise thin-film surface treatments engineered to reduce fingerprint visibility and oleophilic residue adhesion through low surface energy chemistry, typically achieving contact angles above 110 degrees against n-hexadecane. These formulations serve primarily to preserve optical clarity and tactile responsiveness in touch-interfaced products. Fluoropolymer coatings lead value generation due to extreme oil repellency and durability under abrasion cycling, while silicone-based coatings occupy faster-growing niches where regulatory pressure on per- and polyfluoroalkyl substances constrains fluorinated chemistry deployment. Spray coating remains the dominant deployment method for repair and aftermarket applications, though spin coating controls margin pools in original equipment manufacturing of precision optics.
EPA scrutiny of long-chain perfluorinated compounds under TSCA Section 6, REACH restrictions on PFAS under the EU Green Deal framework, and Japan's METI chemical substance classification system collectively constrain formulation choices and accelerate substitution research. ECHA's ongoing PFAS restriction proposal threatens fluoropolymer coatings with market access barriers across European electronics supply chains. Stakeholders must monitor regulatory divergence between jurisdictions while building dual-track formulation portfolios that can pivot between fluorinated and non-fluorinated performance platforms.
Market Dynamics
REACH restrictions on PFAS under the EU Green Deal framework are fragmenting formulation strategies across electronics supply chains, forcing parallel development tracks for fluorinated and non-fluorinated coating platforms.
Growth Catalysts
- Touchscreen proliferation:Consumer electronics manufacturers in China, South Korea, and Taiwan are scaling oleophobic treatments for foldable displays and automotive infotainment panels.
- F-Gas Regulation phase-down:Europe's fluorinated gas controls are accelerating investment in silicone-based alternatives with comparable contact angle performance.
- Optical clarity mandates:Camera module integrators demand anti-smudge layers that preserve transmission rates above 98% for smartphone imaging arrays.
Market Restraints
- Fluoropolymer feedstock concentration:Tetrafluoroethylene supply concentrates among Japanese and Chinese chemical conglomerates, creating input vulnerability for Western formulators.
- Technical durability ceiling:Silicone-based coatings exhibit abrasion resistance below 5,000 cycles in standardized testing, limiting replacement of fluorinated systems in high-wear applications.
- ECHA restriction timeline uncertainty:The ongoing PFAS restriction proposal threatens market access for fluoropolymer coatings across European electronics supply chains.
Strategic Opportunities
- India display fabrication:Emerging panel manufacturing clusters under the country's PLI scheme create captive demand for localized coating supply.
- Automotive interior glass:HUD combiner and smart mirror applications represent unpenetrated volume pools for oleophobic treatments.
- Dual-track formulation portfolios:Technical service capabilities spanning fluorinated and silicone platforms enable rapid pivoting between regulatory jurisdictions.
Industry Challenges
- Thin-film deposition expertise:Vacuum coating and plasma-enhanced chemical vapor deposition skills remain concentrated among Japanese and German equipment specialists.
- REACH registration timelines:New substance notifications for silicone alternatives require 18-24 month validation cycles, compressing product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Anti-Smudge Coatings Market |
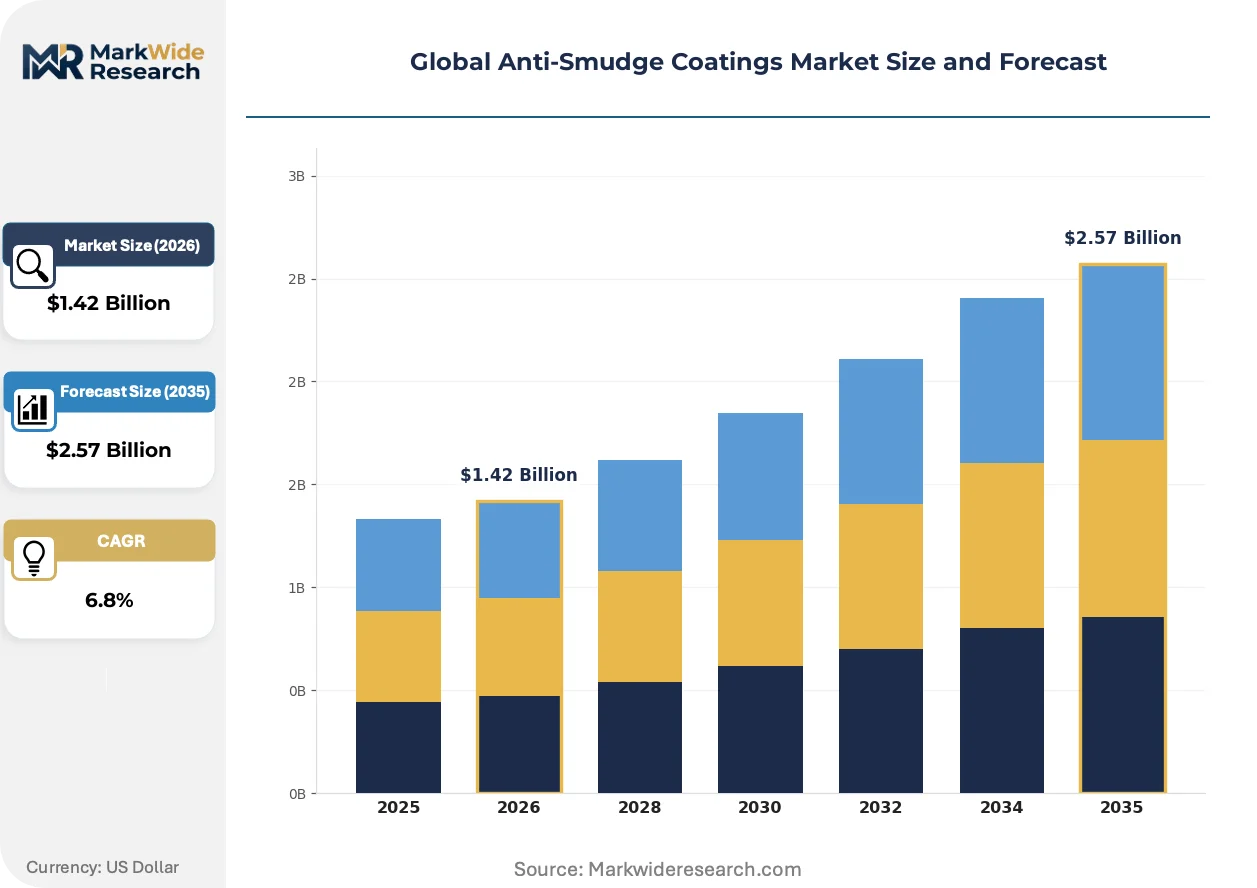
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fluoropolymer Coatings, Silicone-Based Coatings, Acrylic Coatings, Epoxy Coatings, Urethane Coatings Application: Consumer Electronics, Automotive Displays, Medical Devices, Optical Lenses, Touchscreens End User Industry: Electronics Manufacturers, Vehicle Assemblers, Healthcare Equipment Providers, Eyewear Producers, Industrial Equipment Firms Deployment Method: Spray Coating, Dip Coating, Spin Coating, Roll Coating, Chemical Vapor Deposition |
| Companies Covered | AGC Chemicals, Sumitomo Chemical Co., Ltd., PPG Industries, Inc., Evonik Industries AG, Cytonix, LLC, AkzoNobel N.V., Shin-Etsu Chemical Co., Ltd., Nippon Paint Holdings Co., Ltd., Daikin Industries, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Anti-Smudge Coatings Market Shifts & Advancements
Formulation chemistry is bifurcating under regulatory pressure, with performance parity between fluorinated and non-fluorinated platforms now determining competitive viability rather than cost alone.
Siloxane-urethane hybrid coatings are supplanting conventional fluoropolymer systems in mid-tier electronics applications. Chinese display integrators are qualifying these platforms for 2-in-1 laptop touch panels. The substitution is compressing margin pools for legacy fluorinated suppliers while opening volume opportunities for silicone chemistry specialists.
ECHA's PFAS restriction proposal threatens fluoropolymer coatings with outright market exclusion across European electronics supply chains. German automotive OEMs are pre-emptively removing long-chain perfluorinated compounds from interior glass specifications. Component suppliers are accelerating silicone alternative validation to maintain CE marking eligibility.
Certification-driven procurement is concentrating buyer power among tier-one display manufacturers with in-house testing capabilities. Smaller coating applicators in Taiwan and Vietnam are losing direct OEM relationships to integrated panel fabricators. South Korean electronics conglomerates now require full material disclosure down to 100 ppm for all surface treatment chemistries.
Global Anti-Smudge Coatings Market Segmentation
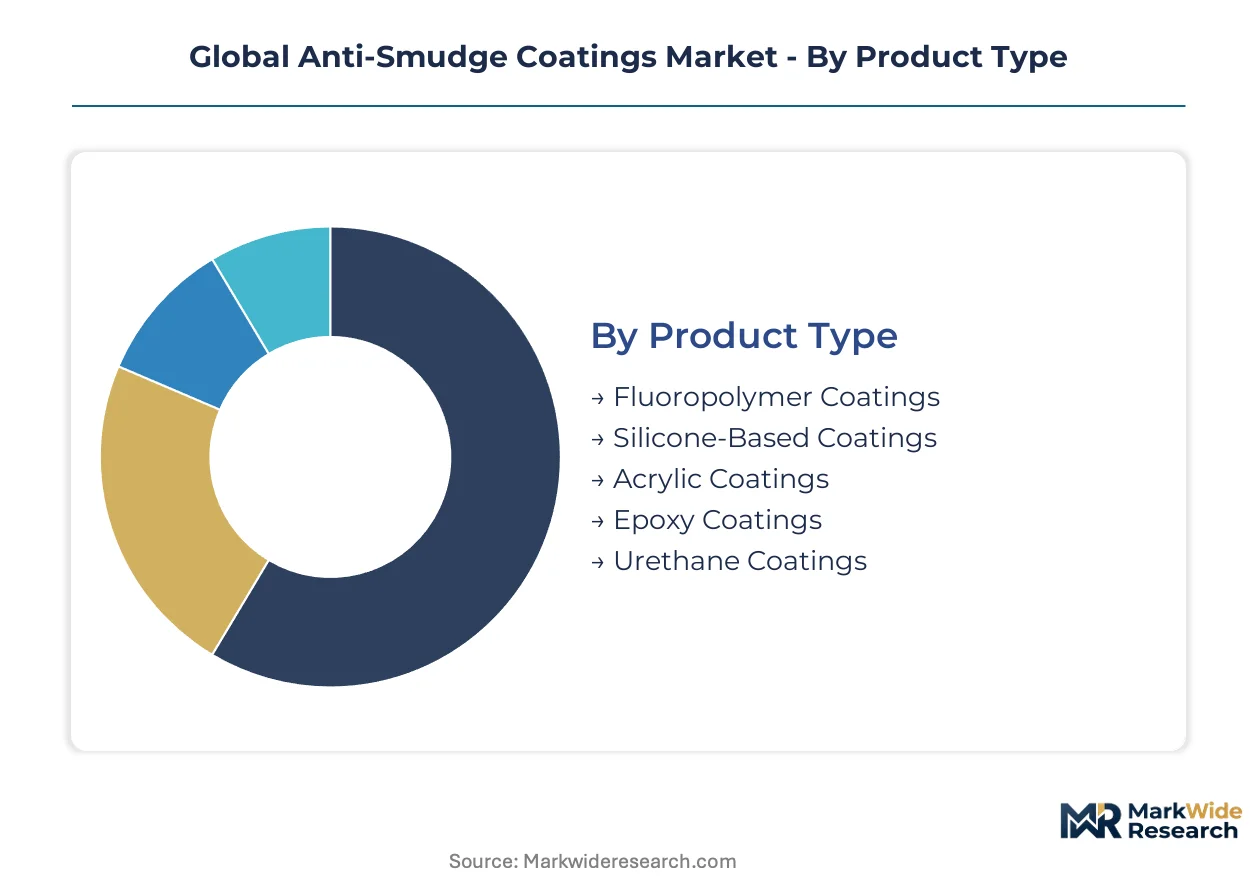
Anti-smudge coating procurement patterns diverge sharply across product chemistry, application durability requirements, and deposition method sophistication. Formulators must align segment-specific capabilities with the technical validation protocols of concentrated buyer clusters in East Asian electronics manufacturing.
Product Type:
Fluoropolymer formulations dominate export-led supply chains serving premium display manufacturers, while silicone alternatives concentrate in domestic-regional markets facing tightening PFAS restrictions.
- Fluoropolymer Coatings:Perfluorinated polymer matrices achieve contact angles exceeding 110 degrees against n-hexadecane with abrasion resistance above 10,000 cycles. Demand concentrates in South Korea and Taiwan for foldable OLED panel treatments where optical clarity mandates meet extreme mechanical flexing requirements. REACH compliance timelines in Europe are compressing qualification windows for new fluorinated substances.
- Silicone-Based Coatings:Siloxane-urethane hybrid platforms deliver oil repellency through low surface energy polydimethylsiloxane segments without perfluorinated content. Chinese display integrators are accelerating adoption for 2-in-1 laptop panels under domestic dual carbon policy pressure. ECHA's PFAS restriction proposal positions silicone as the default chemistry for European market access.
- Acrylic Coatings:Urethane-acrylic hybrids from Western formulators serve automotive interior glass with cost-positioned performance below fluoropolymer tiers.
- Epoxy Coatings:Industrial equipment applications in Germany leverage epoxy-amine systems for chemical resistance in manufacturing environments.
- Urethane Coatings:Japanese automotive HUD combiner manufacturers specify aliphatic urethane topcoats for UV stability in windshield-projection applications.
Fluoropolymer coatings hold the largest share; momentum sits with silicone-based alternatives.
Application:
Touch-interfaced applications command premium pricing tiers against passive optical components where smudge resistance competes with anti-reflective priorities.
- Consumer Electronics:Smartphone and tablet displays require sub-micron film thickness preserving capacitive touch sensitivity. South Korean conglomerates mandate full material disclosure to 100 ppm for all surface chemistries. Foldable form factors are driving qualification of flexible coating substrates.
- Automotive Displays:Infotainment and instrument cluster glass faces thermal cycling from -40°C to 85°C plus UV exposure. German OEMs are pre-emptively removing long-chain perfluorinated compounds from interior specifications ahead of ECHA restrictions. HUD combiner applications represent unpenetrated volume pools.
- Medical Devices:Diagnostic touchscreen enclosures in US healthcare settings require FDA-compliant biocompatibility testing for repeated sterilization exposure.
- Optical Lenses:Camera module arrays in Taiwanese smartphone fabrication demand transmission rates above 98% with oleophobic top layers.
- Touchscreens:Public kiosk and industrial HMI applications prioritize abrasion resistance over optical perfection in high-traffic deployments.
Consumer electronics absorbs the dominant revenue pool; automotive displays are climbing the fastest.
End User Industry:
Electronics manufacturing concentrates procurement power through integrated panel fabricators, while vehicle assemblers fragment demand across tiered supplier bases.
- Electronics Manufacturers:Samsung Display and BOE Technology operate captive coating qualification laboratories. Direct OEM relationships are displacing smaller Taiwanese applicators. Full material disclosure requirements now extend through three supply chain tiers.
- Vehicle Assemblers:BMW and Mercedes-Benz interior glass specifications are shifting toward silicone alternatives. Tier-one automotive glass suppliers in Germany maintain dual-track formulation portfolios for regulatory flexibility.
- Healthcare Equipment Providers:Siemens Healthineers and GE Healthcare specify anti-smudge layers for MRI interface panels with infection control protocols.
- Eyewear Producers:Luxottica and EssilorLuxottica integrate oleophobic treatments into premium lens coatings with AR stack compatibility.
- Industrial Equipment Firms:German automation specialists specify abrasion-resistant formulations for factory-floor HMI terminals.
Electronics manufacturers command the largest procurement volumes; vehicle assemblers are expanding specifications fastest.
Deployment Method:
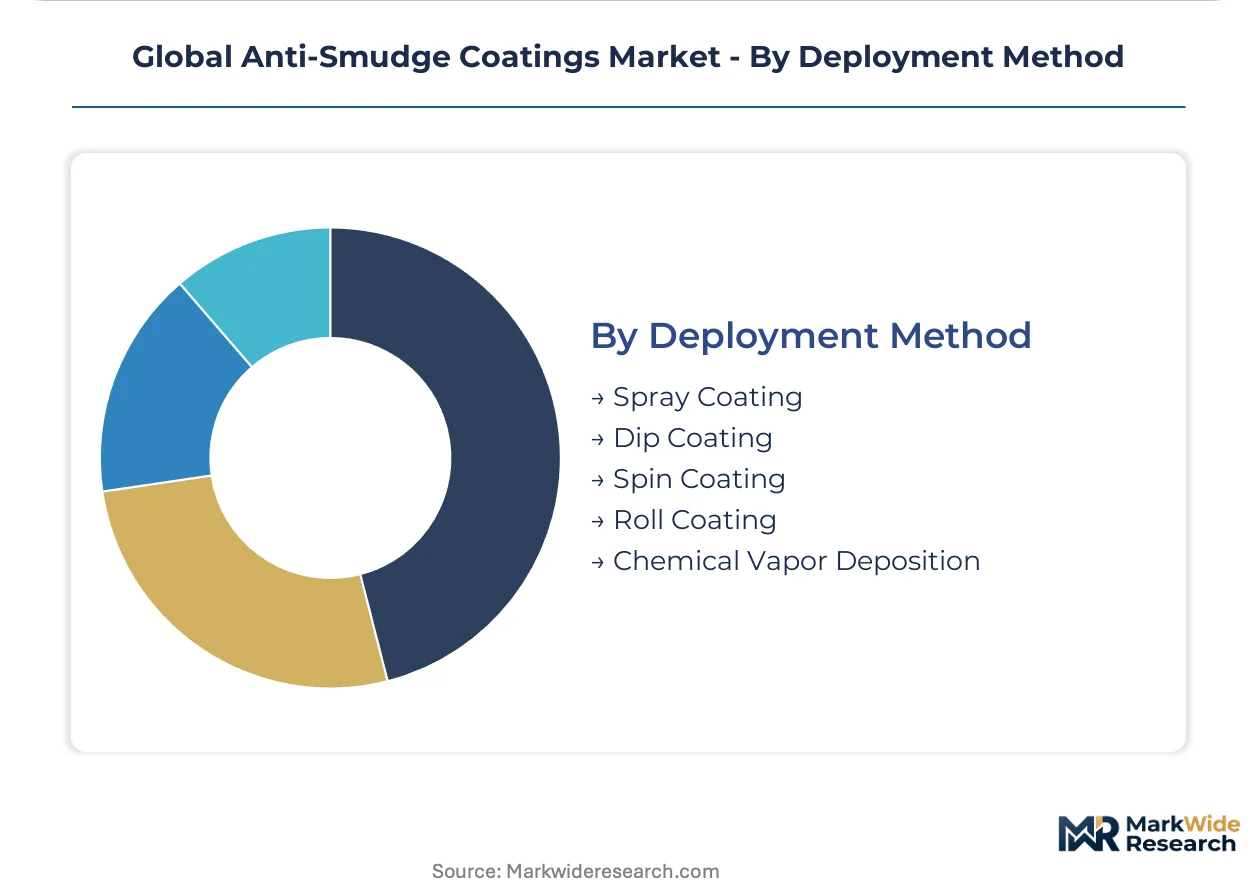
Precision deposition techniques concentrate margin capture in East Asian OEM manufacturing, while spray methods serve fragmented aftermarket repair channels.
- Spray Coating:Aerosol and airbrush methods dominate smartphone screen protector aftermarket sales. Repair shops in India and Southeast Asia represent volume opportunity with lower technical barriers to entry.
- Dip Coating:Batch immersion systems serve eyewear lens manufacturers with uniform film thickness across complex geometries.
- Spin Coating:Centrifugal deposition controls sub-micron thickness precision for camera module optics in Taiwanese and South Korean fabrication. Japanese equipment specialists maintain process expertise concentration.
- Roll Coating:Continuous web processing serves flexible display substrate manufacturers in China scaling foldable panel production.
- Chemical Vapor Deposition:Plasma-enhanced CVD enables conformal coating of micro-lens arrays with atomic-layer thickness control. Equipment and process knowledge concentrates among German and Japanese specialists.
Spin coating holds the premium margin position; roll coating is expanding most quickly with flexible display scaling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-led coating supply chains from East Asia dominate global trade flows, with import dependency structuring competitive access in Western electronics and automotive assembly markets.
China
Display panel fabrication clusters in Suzhou and Shenzhen drive oleophobic coating demand for foldable OLED production. MIIT's dual carbon policy accelerates silicone-based formulation adoption over fluorinated alternatives. BOE Technology and TCL CSOT operate captive qualification laboratories in Hefei and Guangzhou, consolidating procurement power among integrated manufacturers.
South Korea
Samsung Display and LG Display mandate full material disclosure to 100 ppm across three supply chain tiers for smartphone and tablet treatments. MFDS chemical substance classification creates parallel compliance tracks for export-bound versus domestic formulations. Gyeonggi-do province hosts concentrated spin-coating equipment specialists serving camera module integrators.
Germany
Automotive OEMs in Munich and Stuttgart pre-emptively remove long-chain perfluorinated compounds from interior glass specifications ahead of ECHA's PFAS restriction timeline. REACH registration requirements compress silicone alternative validation cycles to 18-24 months. Bavarian glass suppliers maintain dual-track formulation portfolios for regulatory flexibility across EU and export markets.
United States
EPA scrutiny of long-chain perfluorinated compounds under TSCA Section 6 constrains formulation choices for consumer electronics imports. FDA biocompatibility requirements structure coating specifications for diagnostic touchscreen enclosures in healthcare settings. Arizona and Texas host emerging repair and aftermarket distribution hubs for smartphone screen protection.
Japan
METI's chemical substance classification system governs domestic fluoropolymer production and export licensing for tetrafluoroethylene derivatives. Chubu region equipment specialists concentrate plasma-enhanced CVD expertise for micro-lens array conformal coating. Daikin Industries anchors upstream material supply through in-house tetrafluoroethylene production in Osaka prefecture.
Global Anti-Smudge Coatings Market Competitive Landscape
Listed leaders compete with private specialists across formulation chemistry and deposition method expertise, creating a tiered structure where scale-driven conglomerates face nimble technology-focused challengers. Japanese and German chemical conglomerates dominate fluoropolymer raw material streams through backward integration into perfluorinated feedstock production. Three archetypes define competitive positioning: integrated chemical conglomerates with captive raw material supply, coating formulators with application-specific expertise, and equipment-integrated service providers. Consolidation pressure concentrates among mid-tier applicators losing direct OEM relationships to qualified panel fabricators, while technology licensing agreements expand geographic reach without capital-intensive capacity builds.
Among Japanese chemical conglomerates, AGC Chemicals, Daikin Industries, Ltd., and Shin-Etsu Chemical Co., Ltd. exemplify the integrated archetype spanning fluoropolymer, silicone, and hybrid platform development. AGC Chemicals represents fluoropolymer expertise anchored in display manufacturer supply relationships. Daikin Industries, Ltd. occupies a position defined by upstream control over tetrafluoroethylene production. Shin-Etsu Chemical Co., Ltd. sits within the silicone-based alternative vector accelerating under regulatory pressure. Western formulators including PPG Industries, Inc. and Evonik Industries AG compete across automotive and electronics channels with urethane-acrylic and specialty chemical platforms.
| Leading Market Players |
|---|
| AGC Chemicals |
| Sumitomo Chemical Co., Ltd. |
| PPG Industries, Inc. |
| Evonik Industries AG |
| Cytonix, LLC |
| AkzoNobel N.V. |
| Shin-Etsu Chemical Co., Ltd. |
| Nippon Paint Holdings Co., Ltd. |
| Daikin Industries, Ltd. |
| Others |
Supply & Pricing Matrix
REACH compliance timelines in Europe gate both supplier qualification windows and price differentiation between fluoropolymer and silicone-based formulation tiers. Electronics manufacturers in South Korea and Taiwan leverage full material disclosure mandates to compress margins on non-certified applicators while rewarding validated suppliers with long-term offtake premiums.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the anti-smudge coatings market. Price differentiation stems from certification grade under REACH and FDA biocompatibility tiers alongside volume scale commitments from display panel integrators. Cost compression in mid-tier silicone alternatives is intensifying because Chinese domestic manufacturers are qualifying siloxane-urethane hybrids for 2-in-1 laptop applications. Automotive OEM procurement teams exhibit the lowest price sensitivity due to thermal cycling and UV stability specifications, while aftermarket spray coating distributors face acute margin pressure from commoditized screen protector sales.
Supply Chain Analysis
Strategic stockpiling of tetrafluoroethylene feedstock dominates Japanese and Chinese chemical conglomerate behavior, contrasting with just-in-time silicone precursor procurement among European formulators. Raw material supply concentrates in Japan, China, and Germany, with Daikin Industries anchoring upstream fluoropolymer streams through in-house tetrafluoroethylene production. Formulation chemistry draws from perfluorinated polymers, polydimethylsiloxane segments, and urethane-acrylic hybrid resins. Single-source vulnerability concentrates around Japanese plasma-enhanced CVD equipment specialists serving camera module integrators. Distribution runs through captive coating qualification laboratories at integrated panel fabricators rather than independent applicator networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among tier-one display manufacturers with in-house testing capabilities, fragmenting direct OEM access for smaller Taiwanese and Vietnamese applicators. Samsung Display and BOE Technology now mandate full material disclosure through three supply chain tiers, displacing mid-tier suppliers unable to meet validation protocols.
For Market Incumbents: Fortify supply relationships with major display manufacturers by accelerating dual-track formulation portfolios spanning fluorinated and silicone platforms. Deepen backward integration into tetrafluoroethylene production or captive silicone precursor streams to offset feedstock concentration risk among Japanese and Chinese chemical conglomerates. Invest in plasma-enhanced CVD equipment partnerships with German and Japanese specialists to defend deposition method expertise against emerging equipment-integrated service providers.
For New Entrants and Emerging Players: FDA biocompatibility fast-tracks for diagnostic touchscreen enclosures offer the most penetrable entry vector into US healthcare settings. Target automotive interior glass specifications in Germany where BMW and Mercedes-Benz are pre-emptively removing long-chain perfluorinated compounds ahead of ECHA restrictions. Pursue technical licensing agreements with established equipment specialists rather than capital-intensive capacity builds to accelerate geographic reach without direct OEM relationship barriers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across silicone-based alternative development as regulatory pressure compresses fluoropolymer qualification windows. Five-to-ten year viability favors formulators with demonstrated REACH registration capabilities and existing relationships with South Korean electronics conglomerates. Acquisition target archetypes include mid-tier silicone chemistry specialists with validated siloxane-urethane platforms and regional coating applicators in India under the country's PLI scheme for display fabrication. Monitor ECHA's PFAS restriction proposal timeline as the critical inflection signal for portfolio pivoting between fluorinated and non-fluorinated performance platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Track Formulation Portfolio | Enables rapid pivoting between fluorinated and silicone platforms under divergent REACH and EPA regulatory timelines. |
| Backward Integration into Tetrafluoroethylene | Mitigates supply vulnerability from Japanese and Chinese chemical conglomerate feedstock concentration. |
| Silicone Alternative Validation Acceleration | Positions formulators for European market access ahead of ECHA's PFAS restriction proposal implementation. |
| Plasma-Enhanced CVD Equipment Partnership | Captures margin pools in camera module optics where Japanese and German specialists concentrate process expertise. |
| India PLI Scheme Localization | Establishes captive supply relationships with emerging panel manufacturing clusters in Suzhou and Shenzhen. |
Research Methodology
Initial hypotheses were tested against primary input from coating formulator R&D directors, display manufacturer procurement leads, and automotive OEM specification engineers, then refined through secondary validation. Primary interviews incorporated technical service managers at fluoropolymer suppliers, plasma-enhanced CVD equipment specialists in Japan and Germany, and regulatory affairs leads navigating REACH and TSCA compliance. Secondary sources included ECHA restriction proposal documentation, EPA TSCA Section 6 filings, SEC 10-K disclosures from listed chemical conglomerates, and customs trade data tracking tetrafluoroethylene derivative flows. Bottom-up demand modeling from application-specific consumption patterns was triangulated against top-down market sizing from supply-side capacity assessments.
Variance decomposition across the projection horizon isolates volume drivers by chemistry type, deposition method sophistication, and end-use industry concentration. Segmentation dimensions modeled include product chemistry tier, application durability requirements, deployment method precision, and regional regulatory cluster alignment. CAGRs were derived from normalized growth rate analysis across historical consumption trajectories and forward-looking capacity expansion announcements. Industry-specific forecast inputs incorporated foldable display adoption curves from South Korean panel fabricators and automotive interior glass specification shifts from German OEMs.
Decision-makers should treat outputs as directional under assumptions of stable REACH enforcement timelines and continued touchscreen proliferation in consumer electronics; material deviation would warrant model refresh. Specific risk factors include accelerated ECHA PFAS restriction implementation, supply disruption from tetrafluoroethylene feedstock concentration, and substitution velocity of silicone alternatives in high-wear applications. Revision becomes warranted when silicone-based coating abrasion resistance crosses 10,000 cycle thresholds in standardized testing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Hull Coatings Market
Coatings
Europe Powder Coatings Market
Coatings
Germany Protective Coatings Market
Coatings
Trim Coatings Market
Coatings
Process Pipe Coating Market
Coatings
Electronic Protection Device (EPD) Coatings Market
Coatings
Asia-Pacific Floor Coatings Market
Coatings
Superhydrophobic Coatings Market
Coatings
Global Abrasion Resistant Coatings Market
Coatings
Water Based Enamel Market
Coatings
Thermal Barrier Coatings Market
Coatings
FBE Coatings Market
Coatings
Global Laser Cladding Service Market
Coatings
Yacht Coatings Market
Coatings
France Automotive OEM Coatings Market
Coatings
High Performance Coatings Market