
 High Temperature Coatings Market | 2026-2036
High Temperature Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
High Temperature Coatings Market Outlook
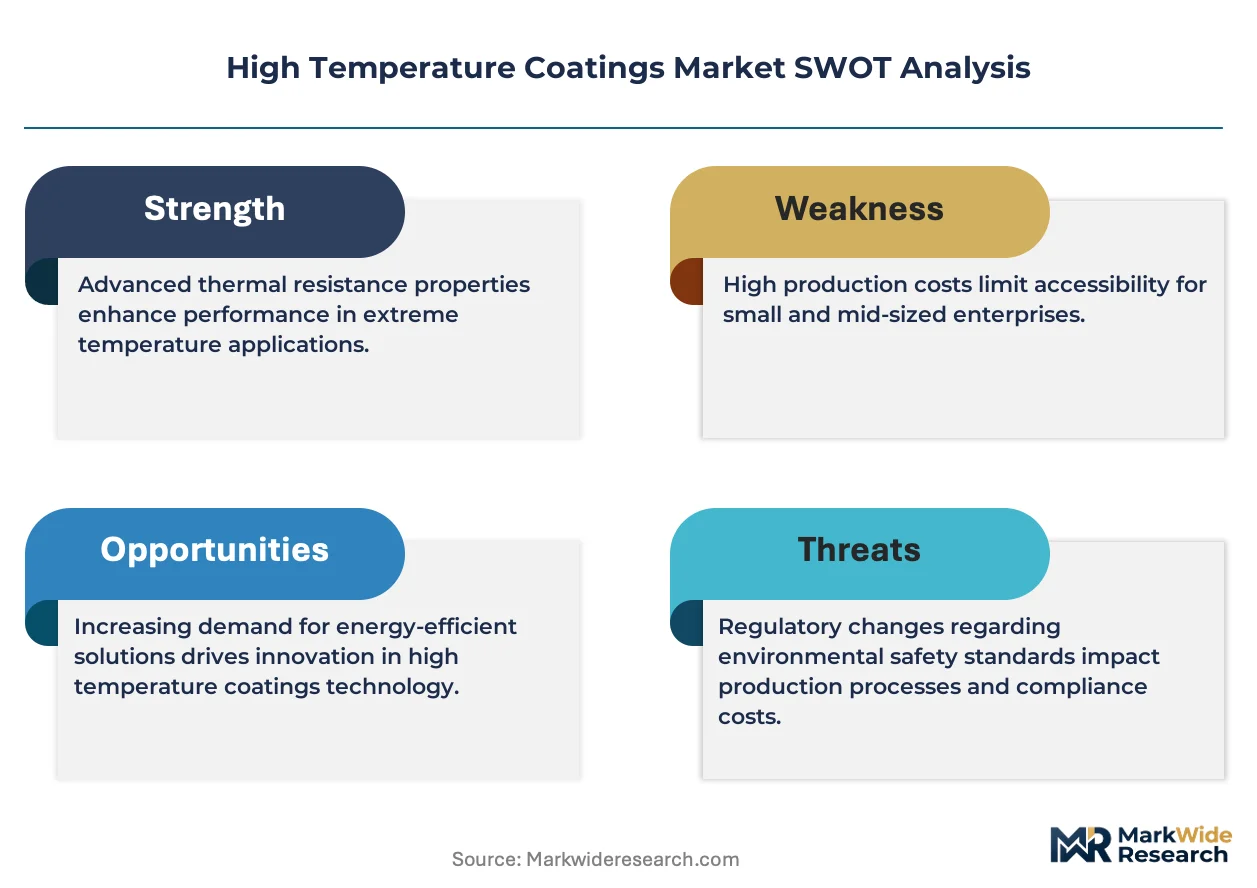
Multi-source procurement for resin feedstocks is decoupling from traditional petrochemical supply chains. PPG Industries, Inc. leverages captive silane production to insulate margin pools from silicone volatility. Akzo Nobel N.V. sustains European aerospace certification density through dedicated Hamburg testing facilities. Jotun A/S anchors marine application leadership with Bergen-based salt-spray validation protocols that competitors struggle to replicate.
High temperature coatings are formulated systems designed to maintain adhesion, color stability, and corrosion resistance at continuous service temperatures exceeding 150°C, typically incorporating ceramic fillers, silicone resins, or inorganic silicate binders applied through thermal spray or electrostatic deposition. These coatings protect exhaust systems, turbine blades, and process vessels from oxidation and thermal fatigue in continuous-duty industrial environments. Silicone formulations command premium positioning due to aerospace thermal cycling requirements, while epoxy systems dominate automotive underhood applications where cost-performance balance governs specification. Inorganic silicate coatings represent the fastest-expanding product category as power utilities adopt water-based alternatives under tightening emissions protocols.
EPA NESHAP standards and REACH Annex XVII restrictions are forcing reformulation of solvent-borne systems across North American and European supply chains. China's GB standards for industrial emissions and the EU F-Gas Regulation are converging on low-VOC and fluoropolymer-reduction mandates that reshape product registration requirements. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory in cross-border distribution networks.
Market Dynamics
EPA NESHAP standards and REACH Annex XVII restrictions are forcing wholesale solvent-borne reformulation across coating supply chains. Silicone resin volatility and ceramic filler procurement bottlenecks compound compliance costs as manufacturers scramble to certify water-based alternatives for aerospace and power generation end-uses.
Growth Catalysts
- China GB Emissions Standards:Coal and gas turbine retrofit cycles in China's power generation sector are pulling inorganic silicate coating volumes as utilities face MEE enforcement deadlines.
- Aerospace Thermal Cycling Requirements:Silicone-based formulations command specification premiums from North American OEMs expanding procurement of turbine blade protection systems.
- EU F-Gas Regulation:Fluoropolymer-reduction mandates are accelerating water-based product registration across European industrial coating distributors.
Market Restraints
- Silicone Feedstock Concentration:Silane and silicone resin supply concentrates in Chinese and German chemical clusters, exposing margin pools to petrochemical volatility and logistics disruption.
- REACH Registration Costs:ECHA compliance timelines and testing expenditures create structural barriers for mid-tier coating formulators seeking European market access.
- Epoxy Performance Ceiling:Automotive underhood applications face substitution pressure as silicone systems close cost-performance gaps in 180-220°C continuous service ranges.
Strategic Opportunities
- India Power Infrastructure:CEA-mandated efficiency upgrades at thermal plants create first-mover positioning for silicate coating suppliers establishing local formulation capacity.
- Marine Exhaust Scrubbers:IMO 2020 sulfur regulations are extending high-temperature coating demand into shipboard emission control retrofits requiring salt-spray validated systems.
- Digital Specification Platforms:Engineering procurement channels are migrating to parametric coating selection tools that compress qualification cycles for qualified suppliers.
Industry Challenges
- Thermal Spray Technician Scarcity:HVOF and plasma spray application certification programs lag demand growth in aerospace MRO facilities, constraining service throughput.
- Cross-Border Registration Divergence:EPA, REACH, and GB standard misalignment forces parallel formulation tracks that fragment R&D budgets and extend product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Temperature Coatings Market |
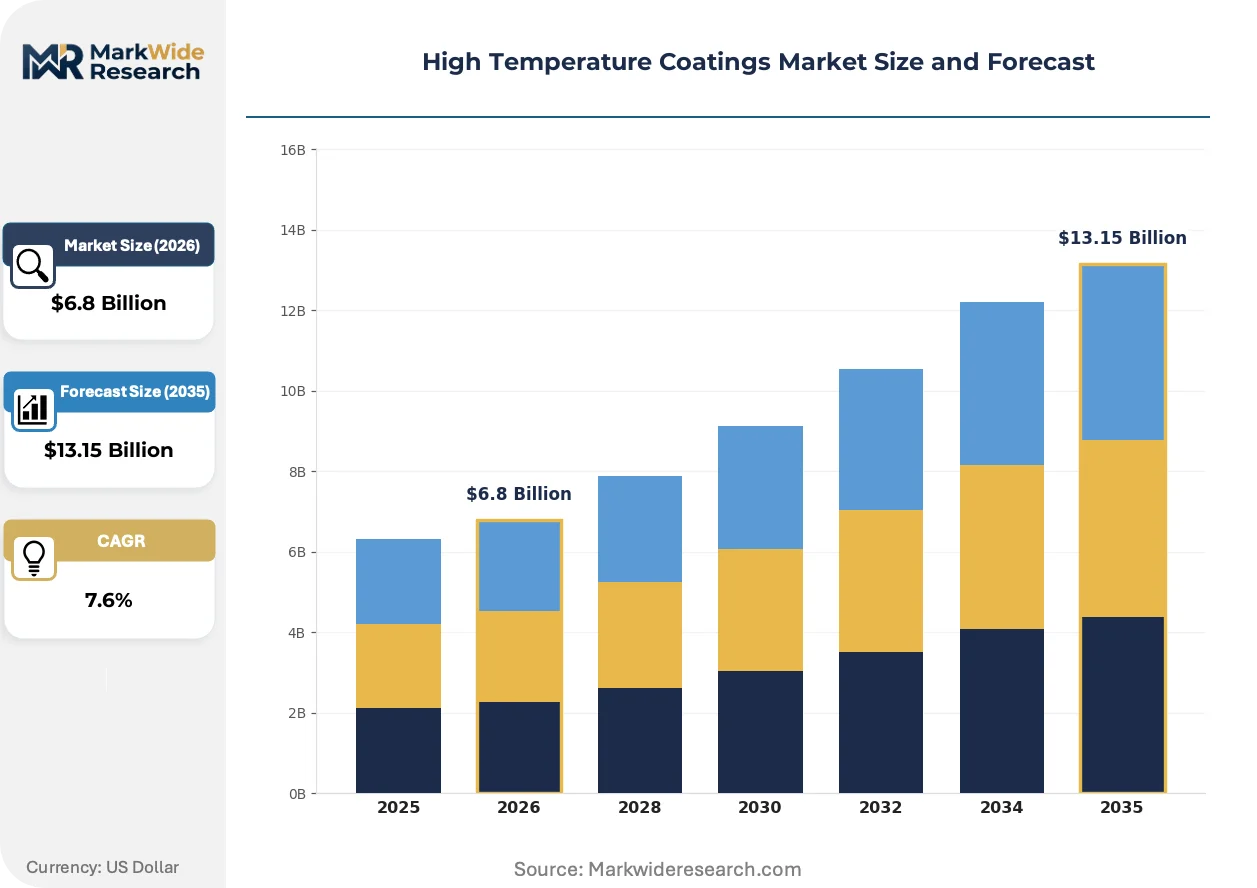
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Silicone, Polyurethane, Inorganic Application: Aerospace, Automotive, Power Generation, Marine End User: Manufacturers, Contractors, OEMs, Repair Facilities Installation Method: Brush-On, Spray, Dip Coating, Electrostatic |
| Companies Covered | PPG Industries, Inc., The Sherwin-Williams Company, Akzo Nobel N.V., Axalta Coating Systems, Jotun A/S, Hempel A/S, BASF SE, Carboline Company, Aremco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Temperature Coatings Market Strategic Shifts
Reformulation chemistry and application automation are compressing traditional coating qualification cycles. Digital specification tools and in-situ monitoring systems are rewiring how industrial buyers evaluate thermal protection performance.
Water-based inorganic silicate formulations are overtaking solvent-borne epoxy systems in power generation applications. Chinese utilities retrofitting coal turbine infrastructure specify these coatings to meet MEE emissions protocols. The shift is compressing VOC-compliant product development timelines for European suppliers seeking export positioning.
REACH Annex XVII restrictions on volatile organic compounds are forcing aerosol and solvent-borne system phaseouts. Coating formulators face dual-track registration requirements as EU F-Gas Regulation converges with national GB standards on fluoropolymer content limits. Aerospace OEMs in Germany and France are consolidating supplier lists to vendors with Hamburg and Lyon testing facility certifications.
Specification decisions are migrating to engineering procurement platforms with embedded thermal performance databases. Industrial buyers in the US and China compare continuous service temperature ratings, thermal cycling data, and salt-spray hours through parametric search tools. This channel shift favors coating suppliers with digitized certification libraries and API-accessible technical documentation over traditional distributor-dependent sales models.
High Temperature Coatings Market Segmentation
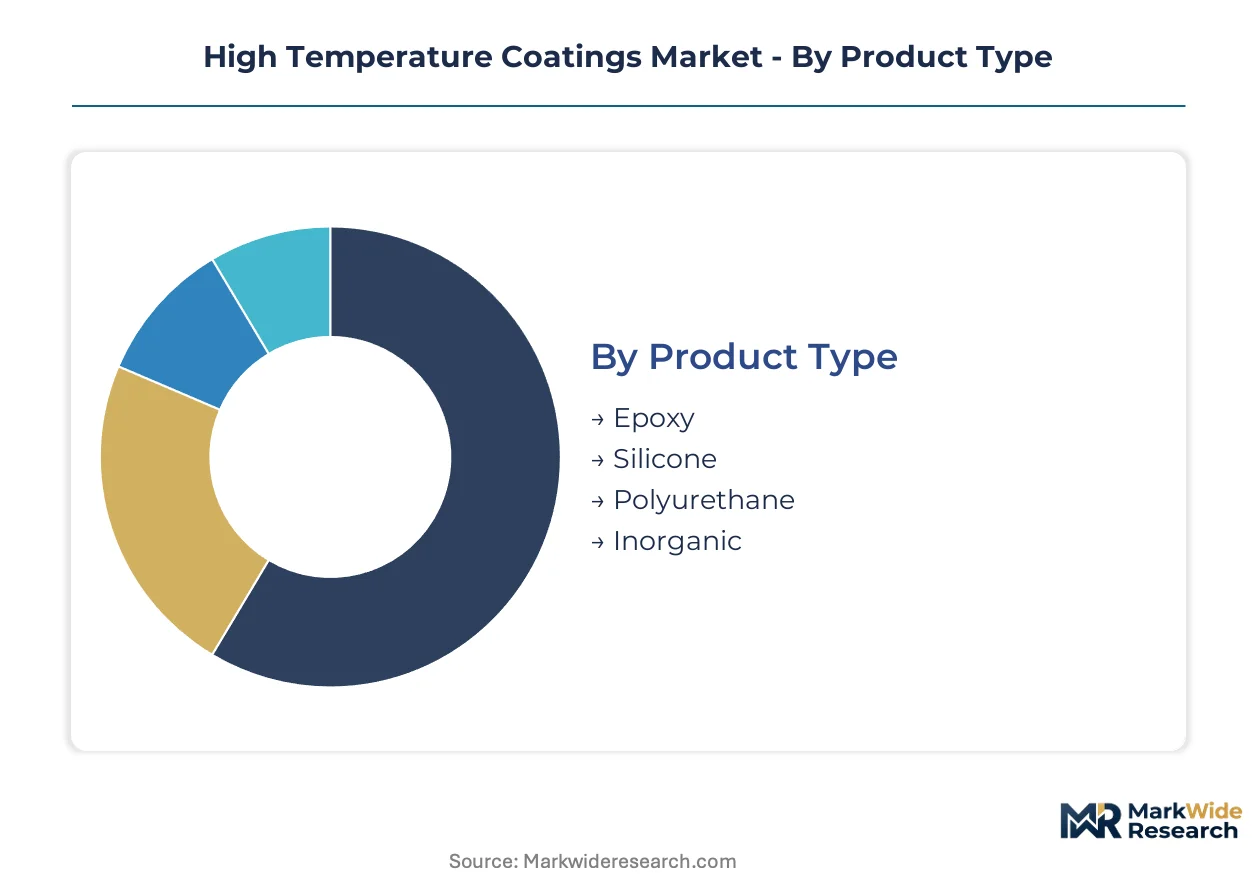
Segmentation in high temperature coatings determines specification pathways, certification requirements, and margin capture. Each dimension carries distinct regulatory burdens and procurement protocols that reshape competitive positioning across aerospace, power generation, and marine end-uses.
Product Type:
Certification intensity varies sharply across resin chemistries, with aerospace-grade silicone requiring FAA and EASA material approvals that epoxy systems for automotive underhood applications bypass entirely.
- Epoxy:Two-part thermoset systems formulated with novolac hardeners achieve 150-180°C continuous service temperatures. Automotive underhood specifications in Germany and Japan concentrate demand as OEMs balance cost-performance thresholds against silicone alternatives.
- Silicone:Organopolysiloxane resins with ceramic fillers withstand thermal cycling from -50°C to 600°C. North American aerospace OEM procurement of turbine blade protection systems commands specification premiums and locks in multi-year supply agreements.
- Polyurethane:Modified isocyanate systems bridge epoxy cost points with silicone thermal performance in 120-200°C ranges.
- Inorganic:Water-based silicate binders meet China's MEE emissions protocols without volatile organic compound content.
Leading the category by volume: Epoxy. Growing fastest: Inorganic.
Application:
End-use concentration dictates qualification complexity, with aerospace thermal cycling requirements imposing 10-year certification cycles that marine salt-spray validation compresses to 18 months.
- Aerospace:Turbine blade, exhaust nozzle, and thermal protection system coatings require HVOF or plasma spray application with NADCAP accreditation. OEM specification lock-in at Boeing and Airbus facilities in Washington State and Toulouse creates formidable switching costs.
- Automotive:Underhood exhaust manifold, turbocharger housing, and brake system coatings prioritize 500-hour salt-spray resistance. Japanese and German OEMs in Aichi and Stuttgart clusters specify silicone-epoxy hybrids for 180-220°C continuous duty.
- Power Generation:Coal and gas turbine blade protection in China's retrofit cycle specifies inorganic silicate systems.
- Marine:Exhaust scrubber and stack coatings require IMO 2020 sulfur compliance with Bergen-validated salt-spray protocols.
Volume concentrates in Power Generation. Steepest expansion trajectory: Marine.
End User:
Procurement authority determines specification control, with OEMs dictating formulations that contractors and repair facilities merely execute.
- Manufacturers:Tier-1 coating formulators with Hamburg and Lyon testing certifications capture aerospace specification authority.
- Contractors:Thermal spray application specialists face HVOF technician scarcity constraints in US MRO facilities.
- OEMs:Boeing, Airbus, and GE Aviation consolidate supplier lists to vendors with digitized certification libraries accessible through engineering procurement platforms.
- Repair Facilities:FAA Part 145 stations in Georgia and Arizona execute overhaul specifications without formulation authority.
OEMs dominate specification control. Repair Facilities are expanding most quickly.
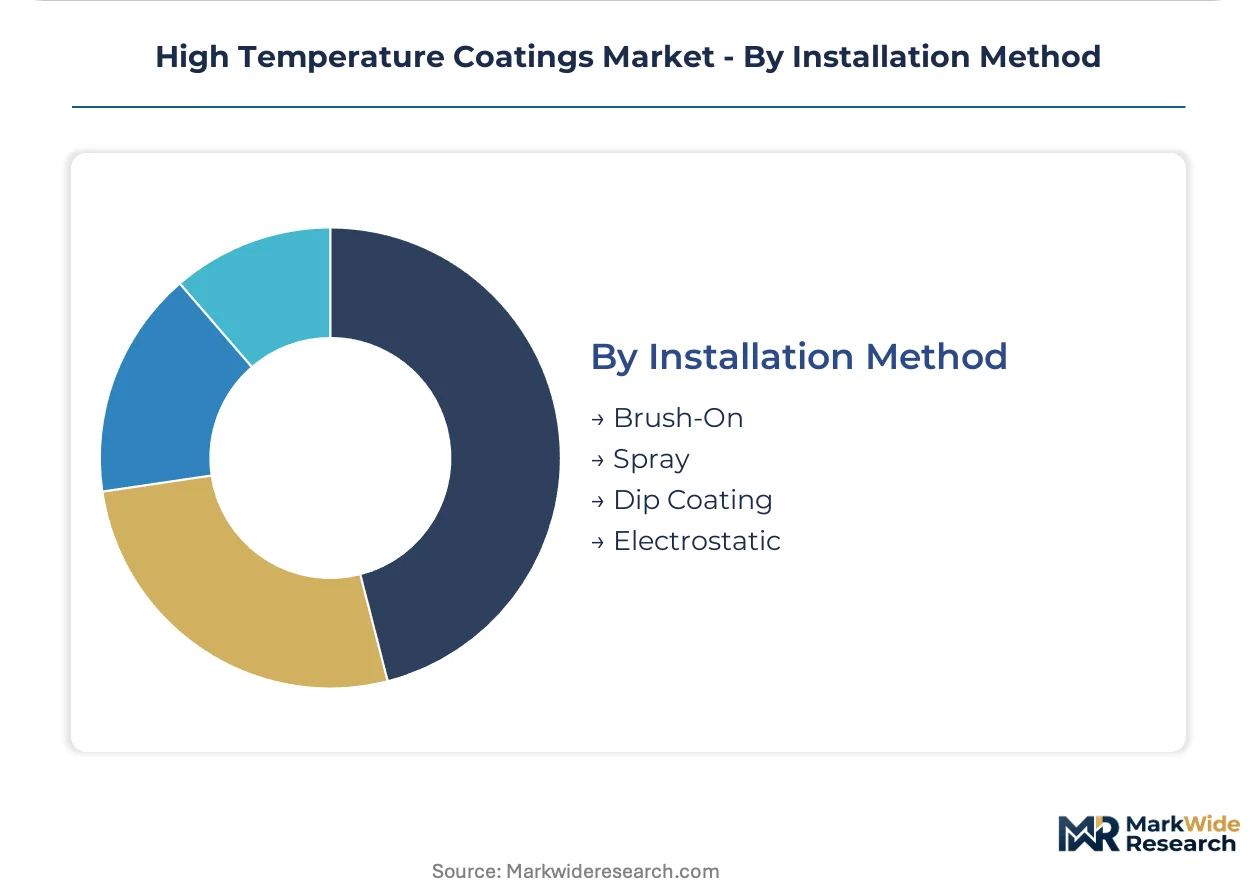
Installation Method:
Application technology separates high-volume commodity coating from precision aerospace specification, with thermal spray certification scarcity constraining service throughput.
- Brush-On:Manual application for field repair and touch-up operations in power plant maintenance cycles.
- Spray:Conventional airless and air-assisted systems dominate automotive underhood volume production in Michigan and Mexico manufacturing corridors.
- Dip Coating:Immersion systems for uniform small-part coverage in fastener and bracket manufacturing.
- Electrostatic:Charged particle deposition achieves 95% transfer efficiency in automotive and appliance coating lines, with EPA NESHAP compliance driving water-borne system conversion.
Spray leads by application volume. Electrostatic is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silane and silicone resin production clusters in Germany and China anchor regional supply dynamics for high temperature coatings. These feedstock localities shape procurement patterns and margin exposure across aerospace, power generation, and marine end-uses.
United States
Aerospace OEM procurement of turbine blade protection systems drives silicone formulation demand. EPA NESHAP standards force solvent-borne system phaseouts across coating supply chains. Washington State and Georgia host concentrated Boeing and FAA Part 145 MRO facilities where HVOF technician scarcity constrains service throughput.
Germany
Automotive underhood specifications for exhaust manifold coatings sustain epoxy-silicone hybrid volumes. ECHA REACH Annex XVII compliance timelines create structural barriers for mid-tier formulators seeking European market access. Hamburg testing facilities anchor aerospace certification density for suppliers serving Airbus Toulouse and domestic OEM clusters.
China
Coal and gas turbine retrofit cycles in power generation pull inorganic silicate coating volumes. MEE enforcement deadlines under GB emissions standards accelerate water-based product adoption. Yangtze River Delta utilities specify these systems as petrochemical clusters in Shandong and Jiangsu face volatile organic compound reduction mandates.
India
CEA-mandated efficiency upgrades at thermal plants create first-mover positioning for silicate coating suppliers. The country's national emissions regulator tightens industrial discharge protocols at coal-fired facilities. Gujarat and Maharashtra host emerging formulation capacity as domestic power infrastructure retrofit cycles accelerate.
Japan
Automotive OEM specifications in Aichi prefecture concentrate demand for 180-220°C continuous service coatings. METI industrial efficiency programs shape procurement standards for process vessel protection. Kansai and Chubu manufacturing corridors balance silicone performance premiums against epoxy cost thresholds in underhood applications.
High Temperature Coatings Market Competitive Environment
Capacity expansion dominates the current landscape as suppliers build captive silane production and regional formulation assets. The vendor base stratifies across three tiers: multinational chemical conglomerates with aerospace certification libraries, mid-cap specialists with marine salt-spray validation protocols, and regional formulators serving power generation retrofit cycles. Two strategic archetypes occupy premium positions: vertically integrated resin producers insulating margin pools from feedstock volatility, and application-technology specialists leveraging thermal spray certification scarcity. M&A activity concentrates on testing facility acquisitions and water-based formulation asset purchases, while geographic expansion targets India and Southeast Asia power infrastructure.
Among North American coating suppliers, PPG Industries, Inc. and The Sherwin-Williams Company exemplify scale-driven archetypes with diversified industrial portfolios. Akzo Nobel N.V. represents the European certification-focused tier, while Jotun A/S anchors marine application specialization. These three occupy positions defined by testing facility geography and end-use concentration rather than interchangeable commodity supply.
| Leading Market Players |
|---|
| PPG Industries, Inc. |
| The Sherwin-Williams Company |
| Akzo Nobel N.V. |
| Axalta Coating Systems |
| Jotun A/S |
| Hempel A/S |
| BASF SE |
| Carboline Company |
| Aremco |
| Others |
Value Chain & Pricing Dynamics
EPA NESHAP compliance deadlines and REACH Annex XVII VOC restrictions gate qualified supply access and premium-tier pricing power, forcing formulators to absorb certification costs or surrender aerospace specification positions to certified competitors.
Pricing Analysis
Warranty-backed thermal cycling performance separates bundled premium offerings from unbundled commodity sales. Three-tier pricing structure across premium, standard, and economy levels reflects certification density, with FAA/EASA-approved silicone formulations commanding substantial premiums over automotive-grade epoxy alternatives. Pricing pressure stems from silicone resin volatility as Chinese and German petrochemical clusters experience feedstock cost fluctuations. Tier-1 aerospace OEMs demonstrate lowest price sensitivity, while power generation contractors retrofitting coal turbines exhibit acute cost consciousness.
Supply Chain Analysis
India's CEA-mandated local-content requirements for thermal plant efficiency upgrades are reshaping sourcing patterns for silicate coating suppliers establishing Gujarat formulation assets. Silane and silicone resin production concentrates in China and Germany, with ceramic filler procurement drawing from Japanese and American specialty mineral processors. Single-source vulnerability runs through Chinese petrochemical clusters exposed to logistics disruption. Distribution feeds from regional formulation hubs into engineering procurement platforms with embedded thermal performance databases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
HVOF technician certification scarcity constrains aerospace MRO service throughput, propping pricing for qualified thermal spray application specialists across Washington State and Georgia facilities.
For Market Incumbents: Deepen backward integration into captive silane production to insulate margin pools from Chinese petrochemical volatility. Expand Hamburg and Lyon testing facility capacity to defend aerospace specification lock-in against emerging European competitors seeking EASA material approvals. Prioritize digitized certification library investments for engineering procurement platform integration. For New Entrants and Emerging Players: Launch via marine exhaust scrubber retrofits requiring Bergen-validated salt-spray protocols, a segment where Jotun's dominance remains geographically concentrated and replicable. Target India's CEA-mandated thermal plant upgrades as the most penetrable geography, leveraging local formulation partnerships to bypass REACH registration barriers. Pursue water-based inorganic silicate formulations as the entry product category. For Investors and Strategic Acquirers: MEE enforcement deadline acceleration in China's Yangtze River Delta is the leading indicator that inorganic silicate coating demand will sustain elevated levels across the projection horizon. Acquisition targets should prioritize mid-cap specialists with marine salt-spray validation protocols and regional formulation assets in India or Southeast Asia. Monitor digital specification platform adoption rates as the signal for channel power shifts favoring digitized certification libraries.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silane Production | PPG Industries captures margin insulation from Chinese petrochemical volatility through captive supply. |
| Testing Facility Certification Expansion | Akzo Nobel sustains European aerospace density via Hamburg facilities serving Airbus Toulouse. |
| Water-Based Formulation Asset Acquisition | European suppliers compress VOC-compliant development timelines for Chinese power generation exports. |
| Digital Specification Platform Integration | OEM procurement consolidation favors suppliers with API-accessible thermal performance databases. |
| Regional Formulation Capacity Buildout | Gujarat and Maharashtra assets position first-movers for CEA-mandated Indian thermal plant retrofits. |
Study Parameters
Document review covered customs and trade data, SEC 10-K filings, and ACC industry reports, complemented by interviews with plant managers at power generation facilities, procurement leads at aerospace OEMs, thermal spray application specialists, and distribution channel partners. Bottom-up volume modeling triangulated against top-down industry association estimates validated the demand assessment.
Historical volume trajectories cross-referenced against expert panel input on regulatory enforcement timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include resin chemistry tier, end-use industry, application method, and regional production hub. CAGRs derived from regression analysis of correlated industrial activity indicators, with silicone resin price indices and turbine blade replacement cycles serving as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for water-based inorganic silicate formulations would alter the outlook if MEE enforcement accelerates or relaxes. Forecasts reflect assumptions on regulatory convergence between EPA, REACH, and GB standards, with tariff exposure on Chinese ceramic fillers representing a specific revision risk. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Acrylic Surface Coating Market
Coatings
Cool Roof Coatings Market
Coatings
South Africa Automotive OEM Coatings Market
Coatings
Italy Protective Coatings Market
Coatings
Anti-Microbial Coatings Market
Coatings
Antimicrobial Coil Coating Market
Coatings
France Automotive OEM Coatings Market
Coatings
Conductive Polymer Coatings Market
Coatings
Asia-Pacific Radiation Curable Coatings Market
Coatings
Coating Auxiliaries Market
Coatings
Global Metal Coatings Market
Coatings
Europe Protective Coatings Market
Coatings
E-Coat Market
Coatings
Global Radiation Cured Coatings Market
Coatings
Glass Coatings Market
Coatings
Glazes Market