
 Global Cast Acrylic Sheet Market | 2026-2036
Global Cast Acrylic Sheet Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cast Acrylic Sheet Market Foresight
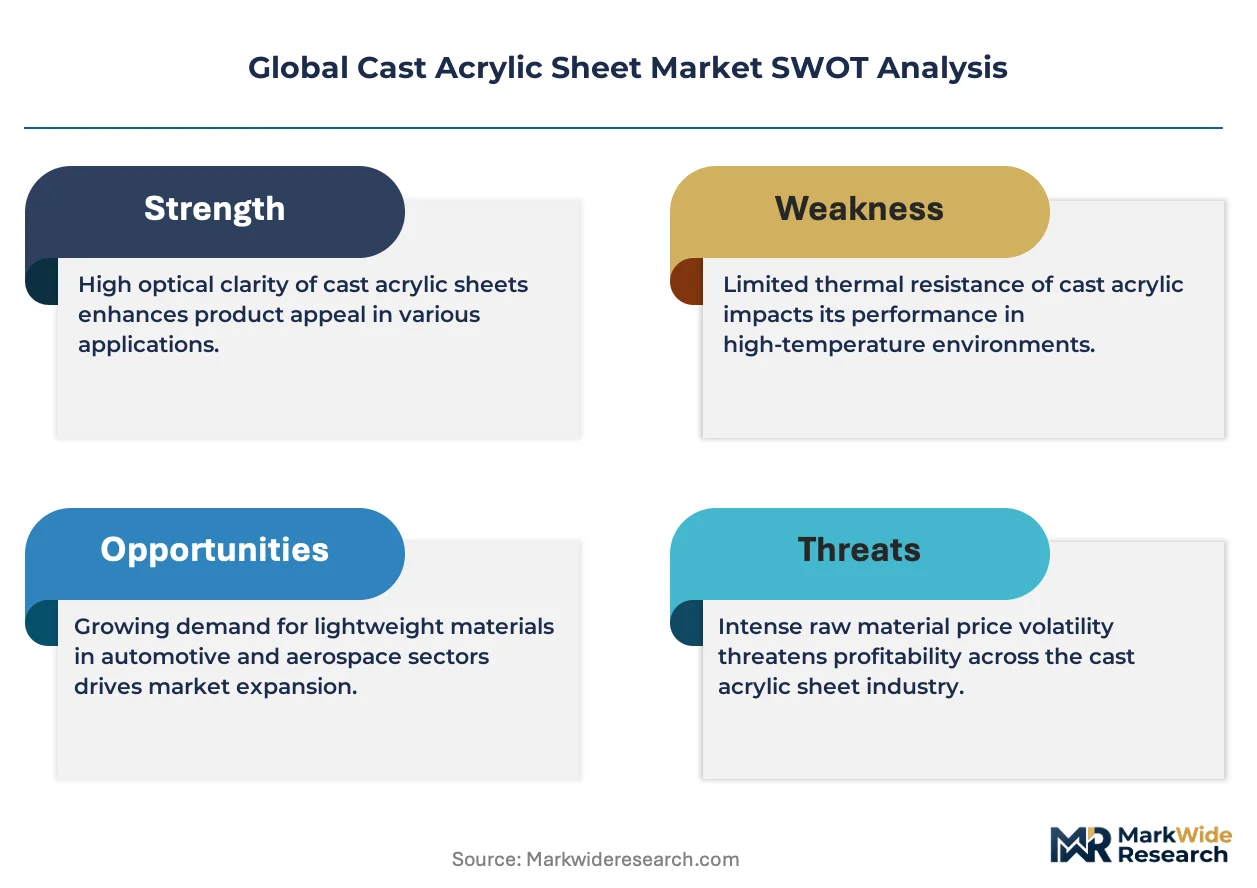
Polycarbonate is hardening its position as a direct substitute in automotive lighting and safety glazing, pressuring cast acrylic suppliers to defend optical clarity and weathering advantages. Röhm GmbH leverages captive monomer supply and European extrusion assets to sustain margin control. Plaskolite anchors North American distribution through broad signage and retail fixture channels. Mitsubishi Chemical Corporation dominates Asian technical sheet production with precision casting lines serving display manufacturers.
Cast acrylic sheet consists of polymethyl methacrylate polymerized in cell-cast or continuous-cast processes, yielding optical clarity of 92% light transmission and surface hardness of 2H to 4H pencil scale for display and glazing applications. UV-resistant sheets command premium positioning in architectural glazing and outdoor signage where photodegradation resistance extends service life. Colored sheets compete in point-of-sale fixtures where brand-matching pigmentation drives specification. Flat sheets remain the volume form factor, though custom fabricated pieces capture higher value in aquarium and specialty display builds.
FDA food-contact regulations, EPA emissions standards for methyl methacrylate vapor recovery, and REACH monomer purity requirements collectively elevate compliance costs for producers serving multiple jurisdictions. CE marking under the EU Construction Products Regulation mandates fire performance testing for architectural glazing applications, filtering non-certified suppliers from European project specifications. Stakeholders must monitor monomer price volatility and regulatory divergence between North American and Asian compliance frameworks to calibrate regional capacity investments.
Market Dynamics
LED backlighting integration in retail and architectural signage is compressing specification cycles for optical-grade cast acrylic, forcing sheet producers to synchronize extrusion capacity with display manufacturer ramp schedules.
Growth Catalysts
- REACH monomer purity mandates:EU compliance thresholds are redirecting procurement toward certified producers with verified methyl methacrylate supply chains, tightening supplier qualification windows.
- Automotive lighting module expansion:LED headlamp and taillight assemblies in Germany, China, and the United States are specifying UV-stabilized cast acrylic for lens covers and light-guide applications.
- Cell-cast optical clarity:Precision casting processes achieving 92% light transmission are capturing specification share from continuous-cast alternatives in high-end display manufacturing.
Market Restraints
- Methyl methacrylate price volatility:Crude derivative fluctuations and acetone-cyanohydrin route disruptions are compressing margin stability for non-integrated sheet producers.
- Polycarbonate substitution in automotive:Impact-resistant PC resins are displacing cast acrylic in safety glazing and lighting housings where abrasion resistance is secondary to toughness.
- EPA vapor recovery compliance:Methyl methacrylate emission controls in US production facilities are elevating capital intensity for facility upgrades and monitoring systems.
Strategic Opportunities
- India retail fixture modernization:Organized retail expansion in Mumbai and Delhi is generating specification pull for colored and frosted acrylic sheets in point-of-sale displays.
- Architectural photovoltaic integration:BIPV facade systems are specifying UV-resistant cast acrylic as protective glazing for embedded solar cell arrays.
- GB standard alignment in China:Evolving national standards for construction materials are creating first-mover advantage for domestic producers achieving dual REACH-GB certification.
Industry Challenges
- Skilled casting technician scarcity:Cell-cast process expertise is concentrating among aging workforces in European and Japanese production facilities, constraining quality consistency at greenfield sites.
- CE marking fire performance testing:EU Construction Products Regulation certification timelines for architectural glazing applications are extending project qualification cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cast Acrylic Sheet Market |
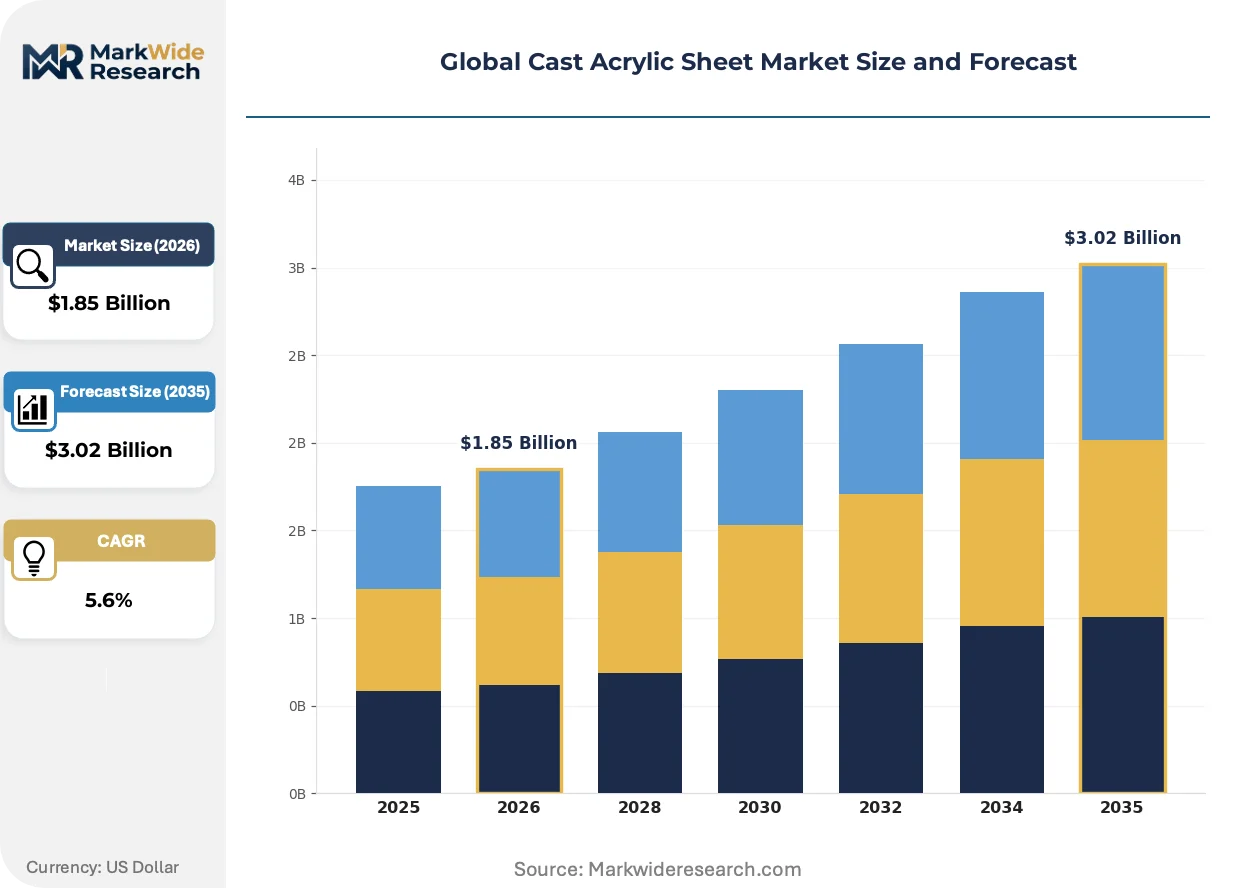
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.02 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Cast Acrylic, UV-Resistant Sheets, Colored Sheets, Textured Panels, Impact Modified Sheets Application: Signage Displays, Automotive Lighting, Point-of-Sale Fixtures, Architectural Glazing, Aquariums End User Industry: Construction Contractors, Automotive OEMs, Retail Storeowners, Marine Fabricators, Advertisement Agencies Form: Flat Sheets, Tubes, Rods, Blocks, Custom Fabricated Pieces |
| Companies Covered | Röhm GmbH, Plaskolite, Evonik Industries AG, Mitsubishi Chemical Corporation, 3A Composites, Altuglas International, Aristech Acrylics, Madreperla, Asia Poly Industrial, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cast Acrylic Sheet Market Shifts & Advancements
Continuous casting automation and digital thickness control systems are compressing cost structures while tightening optical tolerances, reshaping competitive differentiation between cell-cast and continuous-cast supply bases.
Precision thickness gauging integrated with real-time extrusion die adjustment is automating quality consistency in continuous-cast lines. Display manufacturers in South Korea and Taiwan are adopting these tight-tolerance sheets for edge-lit LED panels. The technology is automating the displacement of manual inspection protocols and reducing downstream fabrication waste.
China's GB standards evolution for construction materials is tightening monomer purity and fire performance thresholds. Domestic producers are retrofitting casting lines with vapor recovery and automated annealing systems to maintain market access. Technical sheet grades for architectural glazing face the steepest compliance escalation, filtering smaller producers from project specifications.
Specification consolidation among multinational retail fixture chains is compressing supplier qualification to three-tier certified producers. Brand owners in Germany and the United States are mandating REACH-compliant, UV-stabilized sheet with documented carbon footprint data. This behavior shift is most visible in aquarium and specialty display builds where custom fabrication value hinges on material traceability.
Global Cast Acrylic Sheet Market Segmentation
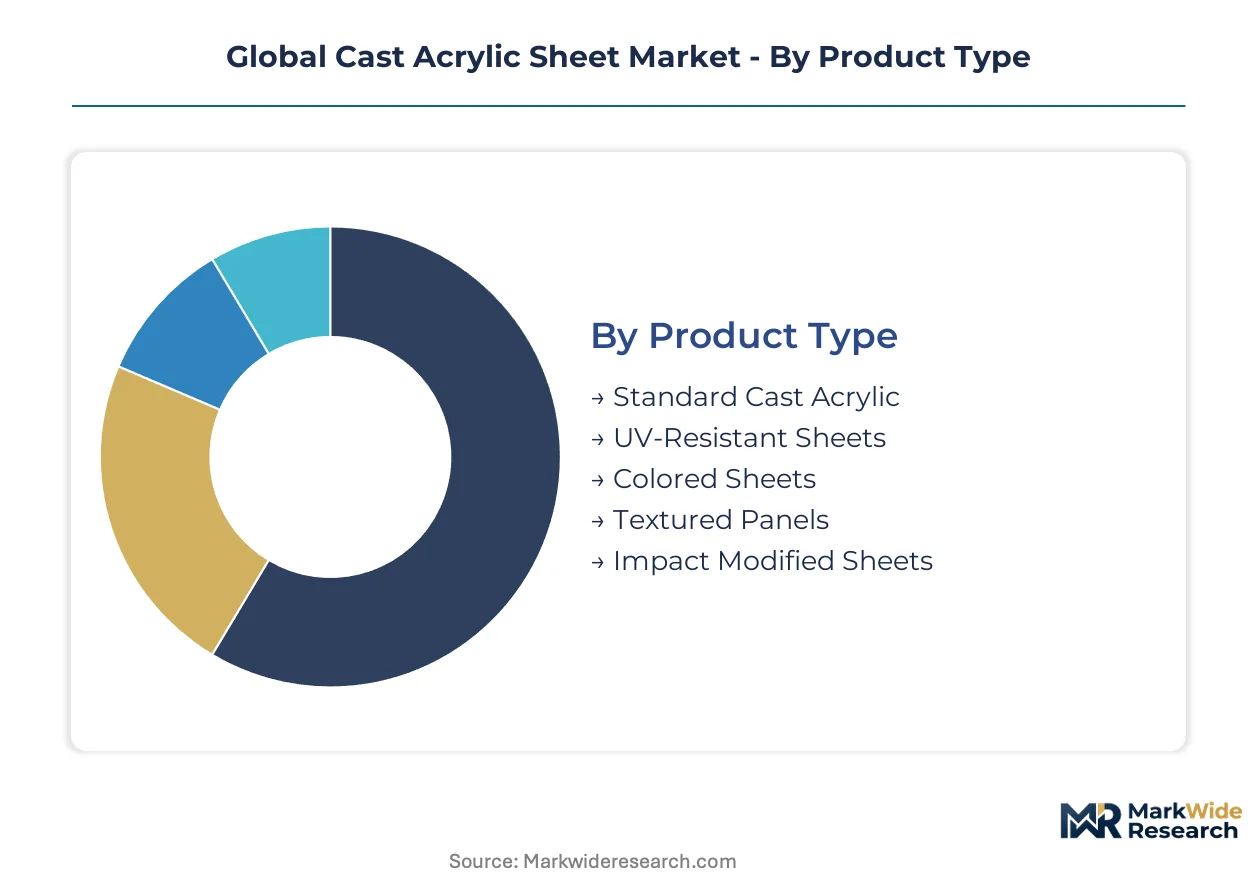
Cast acrylic sheet producers calibrate extrusion lines and inventory profiles around four distinct segmentation axes. Each axis reflects different specification pressures, certification requirements, and margin structures that determine competitive positioning.
Product Type:
Customization intensity varies sharply across this spectrum, from commodity-grade bulk production to precision-engineered specialty grades demanding captive monomer supply and certified purity documentation.
- Standard Cast Acrylic:General-purpose polymethyl methacrylate sheets with 92% optical clarity serve high-volume signage and retail fixture fabrication. Demand concentrates in China and Germany where sheet extrusion clusters feed regional automotive and display supply chains, though margin pressure from continuous-cast automation is compressing differentiation.
- UV-Resistant Sheets:Photostabilized formulations incorporating hindered amine light stabilizers extend service life in outdoor architectural glazing and marine applications. Specification pull from BIPV facade integrators in Germany and the United States is accelerating as building-integrated photovoltaic systems require protective glazing with documented weathering performance.
- Colored Sheets:Pigmented cast acrylic matches brand specifications in point-of-sale displays and retail fixtures.
- Textured Panels:Surface-patterned sheets diffuse light in decorative architectural and signage applications.
- Impact Modified Sheets:Rubber-toughened formulations compete with polycarbonate in safety-critical glazing where abrasion resistance must balance toughness.
Most installed capacity flows through Standard Cast Acrylic. Expansion is steepest in UV-Resistant Sheets.
Application:
Cost tier stratification separates commodity-specification segments from premium grades commanding certified supply chain documentation and extended warranty terms.
- Signage Displays:LED backlighting integration in retail and architectural applications demands tight thickness tolerances and edge-lit optical performance. South Korean and Taiwanese display manufacturers are specifying precision-cast sheets with real-time gauging certification, compressing qualification cycles to match ramp schedules.
- Automotive Lighting:UV-stabilized lens covers and light-guide applications in LED headlamp assemblies require REACH-compliant monomer purity and documented thermal stability. German and Chinese OEMs are tightening supplier qualification to certified producers with vapor recovery systems and batch traceability.
- Point-of-Sale Fixtures:Colored and frosted sheets serve brand-matching retail environments in India and the United States.
- Architectural Glazing:CE marking under EU Construction Products Regulation mandates fire performance testing, filtering non-certified suppliers.
- Aquariums:Thick cast blocks and custom fabricated pieces command premium positioning where optical clarity and seam welding compatibility determine specification.
Volume concentrates in Signage Displays. Value expansion is climbing the fastest in Automotive Lighting.
End User Industry:
Customer procurement sophistication separates price-driven bulk buyers from specification-intensive technical purchasers requiring compliance documentation and carbon footprint data.
- Construction Contractors:Architectural glazing and facade contractors in Germany and China specify REACH-compliant and GB-certified sheets with fire performance documentation. CE marking timelines extending 8-14 months are compressing project planning cycles and favoring pre-qualified supplier relationships.
- Automotive OEMs:Lighting module manufacturers in Germany, China, and the United States mandate UV-stabilized grades with verified methyl methacrylate supply chains and vapor recovery certification.
- Retail Storeowners:Fixture specification concentrates among multinational chains consolidating supplier bases to three-tier certified producers.
- Marine Fabricators:Salt-spray resistant UV sheets serve yacht glazing and hatch applications.
- Advertisement Agencies:Display fabricators prioritize optical clarity and fabrication ease for temporary and permanent installations.
Procurement scale concentrates with Construction Contractors. Margin expansion is gaining share fastest among Automotive OEMs.
Form:
Supply concentration and fabrication value-add separate standardized flat sheet commodity flows from engineered custom geometries.
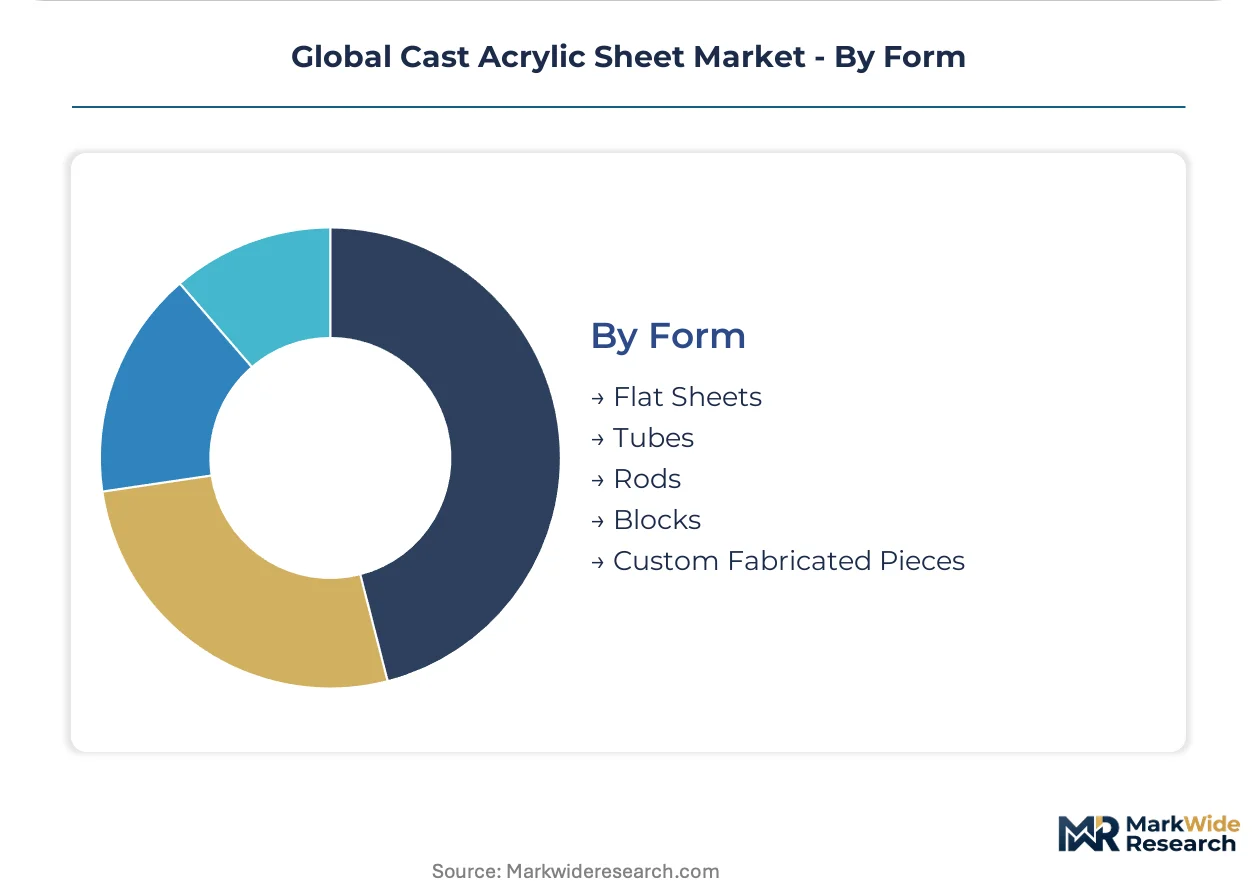
- Flat Sheets:Continuous-cast and cell-cast panels in standard thicknesses serve volume signage, glazing, and fixture fabrication. Chinese and German extrusion clusters dominate supply, with automated thickness control systems compressing cost structures and tightening optical tolerances.
- Custom Fabricated Pieces:Thermoformed, CNC-machined, and bonded assemblies for aquariums and specialty displays capture highest value per kilogram. Specification consolidation among brand owners is mandating documented carbon footprint and REACH compliance as table stakes.
- Tubes:Extruded and cast cylindrical forms serve lighting diffusers and display columns.
- Rods:Solid cast cylinders fabricate into hardware, handles, and decorative elements.
- Blocks:Thick cast slabs enable deep machining for aquarium viewing panels and optical test equipment.
Production volume flows through Flat Sheets. Value growth is expanding most quickly in Custom Fabricated Pieces.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta extrusion clusters dominate global cast acrylic sheet capacity, feeding display manufacturers and automotive lighting module assemblers across East Asia. Regional regulatory divergence between REACH, EPA, and GB standards is fragmenting supplier qualification requirements. Procurement patterns concentrate in Germany, the United States, and China where sheet fabrication serves adjacent manufacturing ecosystems.
China
LED backlighting demand from South Korean and Taiwanese display manufacturers drives specification pull for precision-cast sheets in Suzhou and Shanghai extrusion clusters. GB standards evolution for construction materials is tightening monomer purity thresholds under MEE oversight. Domestic producers in the Yangtze River Delta are retrofitting casting lines with vapor recovery systems to maintain dual REACH-GB certification access.
Germany
Automotive OEM lighting module expansion in Stuttgart and Munich is specifying UV-stabilized grades for LED headlamp assemblies. REACH monomer purity mandates under ECHA are redirecting procurement toward certified producers with verified methyl methacrylate supply chains. The Ruhr industrial corridor anchors captive monomer production integrated with European extrusion assets.
United States
Retail fixture chains and signage display fabricators in the Midwest and Southeast generate volume demand for standard and colored sheet grades. EPA emissions standards for methyl methacrylate vapor recovery are elevating capital intensity for facility upgrades. Ohio and Tennessee extrusion clusters serve regional automotive lighting and point-of-sale supply chains.
India
Organized retail modernization in Mumbai and Delhi is generating specification pull for colored and frosted acrylic sheets in point-of-sale displays. BIS standards alignment with international construction material norms is filtering non-certified suppliers from commercial project specifications. Gujarat and Maharashtra fabrication hubs are scaling technical sheet capacity to serve domestic fixture manufacturers.
Japan
Precision display manufacturing in Osaka and Nagoya demands cell-cast optical clarity grades with documented batch traceability. METI industrial standards for chemical emissions are constraining greenfield casting capacity expansion. Chubu region production facilities concentrate skilled technician expertise for high-tolerance continuous-cast automation.
Global Cast Acrylic Sheet Market Competitive Landscape
Global majors compete with regional champions across certification tier and supply chain integration depth. The vendor base stratifies around three structural tiers: integrated petrochemical groups with captive monomer supply, independent sheet extruders with distribution scale, and specialty fabricators serving custom display builds. Competitive positioning hinges on REACH-EPA-GB regulatory compliance documentation and vapor recovery certification. Dominant moves include backward integration into methyl methacrylate production and strategic partnerships with LED display manufacturers for specification lock-in.
Within the integrated chemical group tier, Röhm GmbH and Mitsubishi Chemical Corporation exemplify archetypes combining monomer production with precision casting assets. Plaskolite occupies a position among North American distribution-anchored independents with broad signage channel coverage. These three names represent the span from European regulatory compliance leadership to Asian technical sheet specialization to continental logistics scale.
| Leading Market Players |
|---|
| Röhm GmbH |
| Plaskolite |
| Evonik Industries AG |
| Mitsubishi Chemical Corporation |
| 3A Composites |
| Altuglas International |
| Aristech Acrylics |
| Madreperla |
| Asia Poly Industrial |
| Others |
Supply & Pricing Matrix
Continuous-cast automation with real-time thickness gauging is compressing production economics while concentrating supply among capital-intensive operators in China and Germany, simultaneously lowering unit costs and tightening margin structures for non-integrated producers.
Pricing Analysis
Methyl methacrylate cost pass-through dominates pricing structures, with acetone-cyanohydrin route volatility feeding directly into sheet quotations. Three-tier pricing separates REACH-certified optical grades from standard signage sheets and commodity continuous-cast volumes. Price differentiation hinges on monomer purity documentation and UV-stabilizer loading. Cost compression in standard grades is intensifying because Chinese continuous-cast automation is flooding regional markets. Retail fixture chains show highest price sensitivity, while automotive lighting OEMs absorb premiums for batch-traceable technical grades.
Supply Chain Analysis
China's evolving GB standards for construction materials are reshaping sourcing patterns, with domestic-content preferences filtering imported sheet from government-backed architectural projects. Supply concentrates in China, Germany, and the United States, where Yangtze River Delta, Ruhr corridor, and Ohio-Tennessee clusters anchor global capacity. Raw material dependencies rest on methyl methacrylate monomer, hindered amine light stabilizers, and precision casting molds. Single-source vulnerability runs through acetone-cyanohydrin feedstock disruptions. Distribution runs through regional extrusion clusters serving adjacent automotive and display manufacturing ecosystems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in cast acrylic sheet production stems from continuous-cast automation driving cost-down capture in high-volume segments, alongside specification consolidation forcing premium-tier pricing power among certified producers.
For Market Incumbents: Cement backward integration into captive methyl methacrylate supply to defend margin stability against acetone-cyanohydrin volatility. Acquire vapor recovery certification and dual REACH-GB compliance to filter non-certified competitors from automotive and architectural specifications. Deepen channel control through direct partnerships with LED display manufacturers in South Korea and Taiwan.
For New Entrants and Emerging Players: E-commerce procurement platforms for custom fabricated aquarium and specialty display pieces offer the lowest barrier to specification entry. Target India's organized retail modernization in Mumbai and Delhi for colored and frosted sheet demand. Pursue white-label fabrication partnerships with multinational fixture chains consolidating supplier bases.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional extruders lacking monomer integration but holding REACH-compliant casting assets. Five-to-ten year viability favors producers with dual European-Asian certification and vapor recovery infrastructure already deployed. Watch methyl methacrylate price spreads as the inflection signal for margin compression timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Methyl Methacrylate | Captive monomer supply insulates margin stability from acetone-cyanohydrin route disruptions. |
| Vapor Recovery System Deployment | EPA and MEE compliance certification filters non-upgraded competitors from OEM qualification. |
| Dual REACH-GB Certification Achievement | First-mover access to Chinese government-backed architectural glazing projects. |
| Continuous-Cast Automation Investment | Real-time gauging compresses cost structures and tightens optical tolerances for display manufacturers. |
| Direct LED Display Manufacturer Partnerships | Specification lock-in with Samsung and LG Display secures volume offtake for precision-cast grades. |
Research Methodology
Bottom-up signage and automotive lighting modeling reconciled against top-down methyl methacrylate supply tracking forms the analytical core. Primary interviews with casting plant managers, procurement leads at display manufacturers, distribution channel partners, and technical R&D directors combined with secondary validation from customs data, ACC and Cefic industry reports, SEC 10-K filings, and GB standards documentation. Triangulation across these sources anchored volume and value estimates.
Input-output matrices map methyl methacrylate monomer flows through cell-cast and continuous-cast production routes into end-use segments across the analysis window. Segmentation dimensions include product type, application, end-user industry, and form factor. CAGRs derive from elasticity modeling against LED backlighting adoption curves and automotive lighting module expansion. Forecast inputs incorporate REACH and GB regulatory compliance timelines and continuous-cast automation penetration rates.
The model assumes a particular technology adoption path; alternative pathways for continuous-cast automation displacing cell-cast volumes would alter the outlook. Forecasts reflect assumptions around methyl methacrylate price stability and regulatory divergence persistence. A small set of triggers—acetone-cyanohydrin supply disruptions, CE marking timeline extensions, and polycarbonate substitution acceleration—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Global High Pressure Seals Market
Industrial Materials
Wire Mesh Market
Industrial Materials
Industrial Heaters Market
Industrial Materials
Shrink Tanks Market
Industrial Materials
High Performance Random Packing Market
Industrial Materials
Middle East Activated Carbon Market
Industrial Materials
GCC Welding Consumables Market
Industrial Materials
Plastic Injection Mold Market
Industrial Materials
Plastics in Electrical and Electronics Market
Industrial Materials
Metal Molds Market
Industrial Materials
Saudi Arabia Industrial Insulation Market
Industrial Materials
Plastic Compounding Machinery Market
Industrial Materials
Crimped Wire Brushes Market
Industrial Materials
Global Machined Seals Market
Industrial Materials
Isotropic Graphite Market
Industrial Materials
Asia Pacific Expanded Polyethylene (EPE) Foam Market