
 Global Packaging Additives Market | 2026-2036
Global Packaging Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Global Packaging Additives Market Foresight
China is narrowing the technical gap in antioxidant and stabilizer production through state-backed polymer chemistry parks. BASF SE leverages its Ludwigshafen integrated site to sustain captive supply advantages across European flexible packaging. Dow Inc. anchors North American demand through its polyethylene additive portfolio tied to Gulf Coast resin production. Clariant AG differentiates via color masterbatch and anti-fog specialization for high-barrier food films.
Packaging additives comprise functional chemical compounds—typically dosed at 0.1% to 5.0% by weight—that modify polymer processability, shelf stability, or surface properties during extrusion, injection molding, or blow molding operations. Their primary commercial purpose is to protect packaged contents from oxidative degradation, mechanical failure, or visual defects while enabling thinner gauge films and faster line speeds. Antioxidants and stabilizers command the deepest margin pools due to technical complexity and reformulation barriers, while biodegradable polymer additives represent the fastest-expanding category as converters respond to EFSA and FDA food-contact notification requirements. Slip and anti-blocking agents occupy mature, price-sensitive segments where volume scale determines supplier viability.
The EPA regulates volatile organic compound emissions from additive compounding facilities under Clean Air Act Title V permits, while REACH restricts phthalate plasticizer migration into fatty food simulants. China's MEE enforces GB standards for heavy metal content in recycled polyethylene streams used for secondary packaging. Stakeholders must monitor how evolving FDA Food Contact Notification pathways and EU Packaging and Packaging Waste Regulation revision timelines reshape acceptable additive chemistries and regional sourcing obligations.
Market Dynamics
EU REACH chemical restrictions and the EU Green Deal are forcing converters to abandon legacy stabilizer chemistries, creating simultaneous demand destruction in phthalate plasticizers and demand creation in bio-based alternatives.
Growth Catalysts
- Extended shelf-life mandates:Food brands in Germany and France are reformulating high-barrier films with advanced antioxidant packages to reduce retail spoilage rates.
- REACH Annex XVII restrictions:The EU's tightening limits on phthalate migration into fatty food simulants are accelerating certified bio-plasticizer adoption across European flexible packaging converters.
- China's state-backed polymer chemistry parks:Government-funded R&D clusters in Jiangsu and Zhejiang provinces are narrowing technical gaps in hindered amine light stabilizer production.
Market Restraints
- Feedstock volatility:Propylene and benzene derivative costs for antioxidant synthesis fluctuate with Gulf Coast petrochemical outages.
- Supplier concentration risk:European antioxidant supply depends heavily on Ludwigshafen-integrated production corridors, creating single-point vulnerability.
- Technical substitution ceiling:Bio-based stabilizers currently fail to match phenolic antioxidant performance in high-temperature extrusion of polyolefin thin films.
Strategic Opportunities
- India's underpenetrated food packaging sector:FSSAI food-contact notification pathways for novel additives remain less congested than FDA or EFSA queues.
- Dual carbon alignment in China:GB standards for recycled polyethylene heavy metal content are creating certified additive demand in secondary packaging streams.
- Anti-fog specialization for fresh produce films:High-barrier agricultural packaging in Spain and Italy requires surface-active additive packages that resist humidity cycling.
Industry Challenges
- Reformulation timeline compression:EFSA food-contact notification reviews for novel bio-based chemistries now exceed 18 months, delaying product launches.
- Extrusion line recalibration costs:Switching from conventional to bio-based stabilizer packages requires screw configuration changes and output rate revalidation.
- Cross-border regulatory fragmentation:Divergent FDA, EFSA, and China's NMPA food-contact approval pathways force redundant toxicology testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Packaging Additives Market |
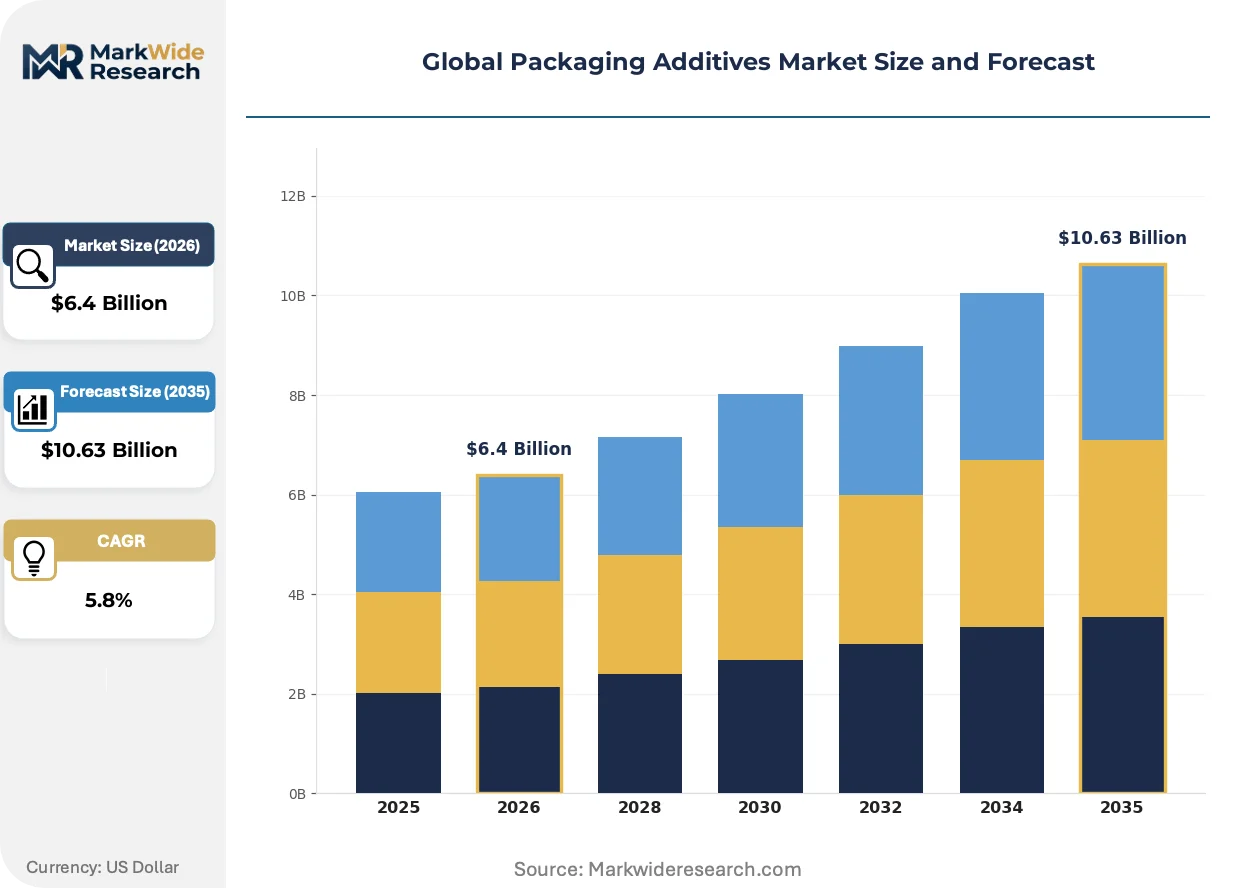
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $10.63 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plasticizers, Stabilizers, Antioxidants, Slip Agents, Anti-blocking Agents, Anti-fog Agents Material Type: Polyethylene, Polypropylene, Polyvinyl Chloride, Polystyrene, Biodegradable Polymers, Polyethylene Terephthalate Application: Food Packaging, Pharmaceutical Packaging, Cosmetic Packaging, Industrial Packaging, Agricultural Packaging, Electronic Packaging End User Industry: Fast-Moving Consumer Goods, Pharmaceuticals, Personal Care, Agriculture, Electronics, Construction |
| Companies Covered | BASF SE, Dow Inc., Clariant AG, Evonik Industries AG, Avient Corporation, Arkema, AkzoNobel NV, ALTANA Group, Ampacet Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Packaging Additives Market Shifts & Advancements
Additive suppliers are racing to decouple performance from petrochemical feedstocks as regulatory chemistry restrictions tighten across multiple jurisdictions simultaneously.
Reactive antioxidant grafting onto polymer backbones is migrating from specialty medical packaging into mainstream food film applications. German and Dutch converters are piloting these covalently bound stabilizers to eliminate additive migration risks. The technology is migrating from niche premium segments toward volume flexible packaging, compressing traditional physical-blend antioxidant margins.
REACH authorization requirements for Substances of Very High Concern are forcing systematic substitution of aromatic amine antioxidants in European food-contact films. The regulation compels reformulation investments across converter supply chains. Flexible packaging for fatty foods faces the most acute compliance pressure, with many operators accelerating bio-phenolic stabilizer qualification.
Brand-led sustainability scorecards are reshaping procurement priorities for packaging additives. Major European retail chains now mandate recycled content percentages that require compatibilizer and stabilizer packages proven effective in mechanically recycled polyethylene streams. This specification tightening is most visible in German and French private-label food packaging contracts.
Global Packaging Additives Market Segmentation
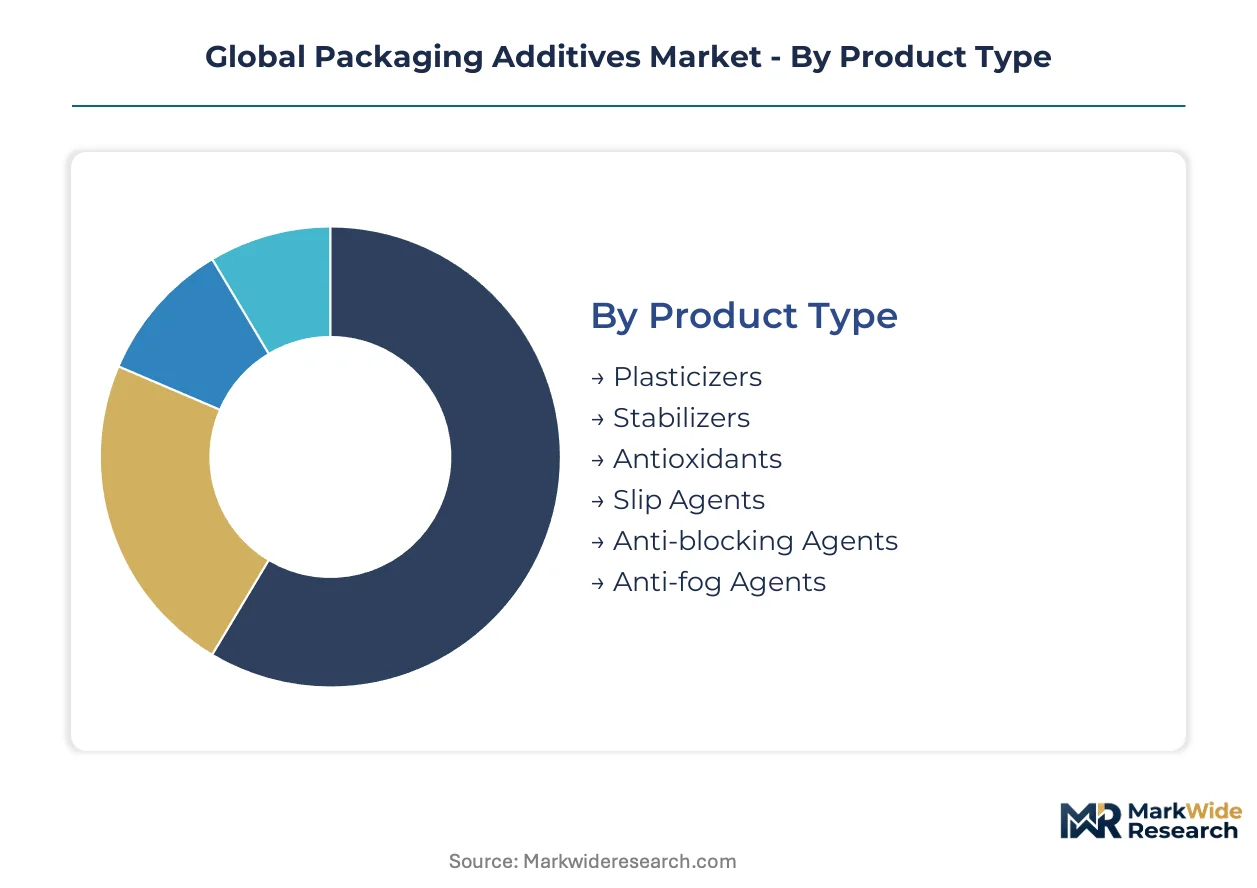
Packaging additives serve distinct functional roles across polymer chemistries and end-use specifications. Segmentation reveals where technical complexity commands premium positioning versus where commodity scale dominates procurement decisions.
Product Type:
Mature commodity chemistries coexist with emerging high-performance formulations across this spectrum.
- Antioxidants:Phenolic and phosphite compounds interrupt oxidative degradation chains in polyolefin extrusion. German flexible packaging converters specify these for high-barrier fatty food films facing EFSA migration limits.
- Stabilizers:Hindered amine light stabilizers and UV absorbers protect outdoor agricultural films across Spain and Italy. REACH Annex XVII restrictions on aromatic amine variants are accelerating bio-based qualification timelines.
- Plasticizers:Phthalate and bio-based alternatives modify polymer flexibility for PVC cling films and medical packaging.
- Slip Agents:Fatty acid amides reduce film-to-film friction in high-speed form-fill-seal operations.
- Anti-blocking Agents:Silica and talc formulations prevent film adhesion in stacked polyethylene rolls.
- Anti-fog Agents:Surfactant packages maintain optical clarity in fresh produce films exposed to humidity cycling.
Antioxidants handle the majority of throughput; anti-fog agents are gaining share fastest on agricultural packaging specialization.
Material Type:
Polymer selection dictates additive compatibility requirements and regulatory scrutiny intensity.
- Polyethylene:Linear low-density and high-density grades consume the largest antioxidant volumes for food-contact films. China's GB standards for heavy metal content in recycled streams are creating certified additive demand in secondary packaging.
- Biodegradable Polymers:PLA and PHA formulations require specialized stabilizers that do not interfere with composting certification. European private-label contracts now mandate recycled content percentages that drive compatibilizer adoption.
- Polypropylene:Homopolymer and copolymer grades use nucleating agents and clarifiers for rigid food containers.
- Polyvinyl Chloride:Heat stabilizers based on calcium-zinc or organotin chemistries address medical and construction film specifications.
- Polystyrene:Expandable and crystal grades employ flame retardants and processing aids for electronics and food service applications.
- Polyethylene Terephthalate:Acetaldehyde scavengers and reheat additives support bottle and tray manufacturing.
Polyethylene anchors volume demand; biodegradable polymers show the steepest expansion trajectory on regulatory pressure.
Application:
End-use performance requirements segment additive specifications by barrier, migration, and shelf-life demands.
- Food Packaging:High-barrier multilayer films for meat and dairy deploy oxygen scavengers and antioxidant packages. French and German retailers specify extended shelf-life formulations to reduce spoilage rates.
- Pharmaceutical Packaging:Blister films and sachets require extractables testing under US FDA and EU EMA guidelines.
- Cosmetic Packaging:Fragrance barrier layers and UV protection additives preserve product integrity in premium personal care.
- Industrial Packaging:Stretch wrap and shrink films prioritize cost-optimized slip and anti-block combinations.
- Agricultural Packaging:Greenhouse films and silage wrap demand UV stabilizers resistant to sulfur fumigation.
- Electronic Packaging:Anti-static and conductive additives protect sensitive components in moisture barrier bags.
Food packaging commands the deepest additive specification complexity; pharmaceutical applications are expanding most quickly on serialization and traceability requirements.
End User Industry:
Procurement sophistication varies sharply across customer categories, from technical specification to spot-market purchasing.
- Fast-Moving Consumer Goods:Brand-led sustainability scorecards mandate recycled content and bio-based additive verification. Major European retail chains now require documentation of stabilizer effectiveness in mechanically recycled polyethylene.
- Pharmaceuticals:Drug master file submissions and drug product compatibility studies drive long qualification cycles.
- Personal Care:Aesthetic requirements for clarity and haze control influence anti-fog and nucleating agent selection.
- Agriculture:Seasonal demand patterns and weather exposure dictate UV stabilizer loading levels.
- Electronics:Moisture vapor transmission rate specifications determine desiccant and barrier coating requirements.
- Construction:Geomembranes and vapor barriers prioritize long-term oxidative stability in buried applications.
Fast-moving consumer goods absorbs the highest additive innovation investment; pharmaceuticals impose the longest technical validation cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Antioxidant and stabilizer production clusters heavily in Germany's Ludwigshafen chemical corridor, creating captive supply advantages that radiate across European flexible packaging converters. Chinese state-backed polymer chemistry parks in Jiangsu and Zhejiang provinces are narrowing technical gaps in hindered amine light stabilizer synthesis. India's food-contact notification pathways remain less congested than FDA or EFSA queues, attracting additive qualification investments.
United States
Gulf Coast petrochemical outages drive propylene and benzene derivative cost volatility for antioxidant synthesis. EPA Clean Air Act Title V permits regulate volatile organic compound emissions from additive compounding facilities in Texas and Louisiana. Houston-area resin production corridors anchor Dow Inc.'s polyethylene additive portfolio, tying stabilizer demand to regional polymer output cycles.
Germany
EFSA migration limits on fatty food simulants compel reformulation of high-barrier meat and dairy films with advanced antioxidant packages. REACH Annex XVII restrictions on phthalate plasticizers accelerate certified bio-plasticizer adoption across Baden-Württemberg and North Rhine-Westphalia converter clusters. BASF SE's Ludwigshafen integrated site sustains captive supply advantages across European flexible packaging through backward integration into antioxidant intermediates.
China
Dual carbon alignment goals and GB standards for heavy metal content in recycled polyethylene streams create certified additive demand in secondary packaging. MEE enforcement of environmental compliance pushes Jiangsu and Zhejiang province converters toward bio-based stabilizer qualification. State-funded R&D clusters in these provinces are narrowing technical gaps in hindered amine light stabilizer production previously dominated by European suppliers.
India
FSSAI food-contact notification pathways for novel additives remain less congested than FDA or EFSA queues, compressing product launch timelines for international suppliers. Maharashtra and Gujarat polymer processing corridors concentrate flexible packaging converter demand for antioxidant and anti-fog formulations. Domestic additive qualification investments are rising as multinational suppliers establish technical service laboratories in Mumbai and Ahmedabad.
France
Extended shelf-life mandates from major retail chains drive reformulation of high-barrier multilayer films with oxygen scavenger and antioxidant packages. EU Green Deal chemistry restrictions force systematic substitution of aromatic amine antioxidants in food-contact films produced in Île-de-France and Auvergne-Rhône-Alpes converter clusters. Private-label food packaging contracts now mandate recycled content percentages requiring compatibilizer and stabilizer packages proven effective in mechanically recycled polyethylene streams.
Global Packaging Additives Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the antioxidant and stabilizer segments where technical complexity sustains margin pools. The vendor base stratifies across three tiers: integrated petrochemical majors with captive additive production, mid-scale specialty chemical houses, and regional masterbatch compounders. Strategic archetypes include backward-integrated polymer producers, technology-licensing specialists, and geographic niche defenders. Competitive moves concentrate on M&A for formulation capabilities and capacity expansion in bio-based chemistries.
Within the integrated majors tier, BASF SE and Dow Inc. exemplify petrochemical producers with captive additive supply chains. Among specialty chemical houses, Clariant AG and Evonik Industries AG occupy positions defined by color masterbatch and functional additive specialization. These named entities anchor competitive dynamics without exhausting the vendor landscape, as regional compounders and emerging bio-based suppliers continue qualification investments.
| Leading Market Players |
|---|
| BASF SE |
| Dow Inc. |
| Clariant AG |
| Evonik Industries AG |
| Avient Corporation |
| Arkema |
| AkzoNobel NV |
| ALTANA Group |
| Ampacet Corporation |
| Others |
Supply & Pricing Matrix
Single-source dependency on Ludwigshafen-integrated antioxidant corridors determines both pricing tier spreads and supply chain shape across European flexible packaging. REACH Annex XVII migration limits on phthalate plasticizers compress margins in legacy formulations while widening premiums for certified bio-based alternatives.
Pricing Analysis
REACH authorization requirements dictate the pricing tier structure across antioxidant and stabilizer categories. Three-tier pricing structure across premium, standard, and economy levels separates reactive-grafting specialty grades from conventional physical blends and commodity masterbatches. Certification grade under EFSA food-contact notification pathways commands substantial premiums over non-food-grade alternatives. Cost compression in standard-tier phenolic antioxidants is intensifying because Chinese state-backed polymer chemistry parks are narrowing technical gaps in hindered amine production. Fast-moving consumer goods procurement teams exhibit the highest price sensitivity, while pharmaceutical packaging buyers prioritize migration compliance over unit economics.
Supply Chain Analysis
Contract-manufacturing concentration in German chemical corridors around Ludwigshafen and Leverkusen anchors European antioxidant supply. Geographic supply concentration centers on Germany, China, and the United States for distinct additive chemistries. Raw material dependencies rest on propylene and benzene derivatives from Gulf Coast petrochemical complexes, hindered amine intermediates from European specialty chemical houses, and bio-based feedstocks from Brazilian and Southeast Asian agricultural processors. Single-source vulnerability in Ludwigshafen-integrated production creates systemic exposure to site-specific outages. Distribution runs through converter-direct technical service relationships rather than merchant chemical distribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Global packaging additives sit at an early-cycle expansion story where bio-based stabilizer qualification timelines are compressing and EFSA notification backlogs are clearing. Extended shelf-life mandates from European retail chains provide durable adoption tailwinds across high-barrier food film segments.
For Market Incumbents: Harden supply chain resilience through backward integration into antioxidant intermediates at Ludwigshafen-scale facilities. Diversify production footprints beyond single-site German concentration to mitigate REACH-driven reformulation disruption. Capture margin expansion in bio-phenolic stabilizers before Chinese state-backed R&D clusters achieve technical parity in hindered amine synthesis. For New Entrants and Emerging Players: Establish a beachhead in India's underpenetrated food packaging sector where FSSAI notification pathways remain less congested than FDA or EFSA queues. Target anti-fog specialization for Spanish and Italian agricultural films where humidity-cycling resistance creates specification stickiness. Lead with technical service laboratories in Mumbai and Ahmedabad rather than price-competing in commodity antioxidant segments. For Investors and Strategic Acquirers: The market sits at a substitution phase that favors bio-based chemistry specialists with EFSA pre-notification dossiers. Long-term viability across the analysis window hinges on regulatory chemistry alignment rather than scale economics alone. Watch EFSA food-contact notification review duration as the primary inflection signal—compression below 12 months would accelerate bio-based stabilizer adoption curves.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Antioxidant Intermediates | BASF SE's Ludwigshafen captive supply model demonstrates margin protection against feedstock volatility. |
| Bio-Based Stabilizer Qualification Investment | REACH Annex XVII aromatic amine restrictions are forcing systematic reformulation across European converter supply chains. |
| Regional Production Footprint Expansion | Jiangsu and Zhejiang province R&D clusters are narrowing technical gaps previously dominated by European suppliers. |
| Anti-Fog Specialization for Agricultural Films | Spanish and Italian greenhouse film demand creates specification premiums resistant to commodity pricing pressure. |
| Technical Service Laboratory Deployment | Mumbai and Ahmedabad facilities compress FSSAI notification timelines for novel additive introductions. |
Research Methodology
Desk research of trade customs data, SEC chemical company filings, and EFSA food-contact substance databases preceded structured interviews with flexible packaging plant managers, polymer procurement leads at FMCG brands, distribution channel partners, and technical R&D directors at additive suppliers. Primary fieldwork across German converter clusters in Baden-Württemberg and North Rhine-Westphalia validated secondary demand estimates. Bottom-up volume modeling triangulated against top-down petrochemical consumption correlations.
Assumption sets held regulatory chemistry restrictions and Gulf Coast feedstock cost structures fixed while varying Chinese R&D cluster productivity and Indian FSSAI processing efficiency across scenarios. Segmentation dimensions modeled include functional additive type, polymer compatibility grade, end-use application barrier requirements, and regional regulatory cluster. CAGRs were derived from production capacity expansion announcements correlated with downstream converter demand surveys. Industry-specific forecast inputs incorporated EFSA notification queue depth and REACH authorization timelines.
Stress conditions across propylene derivative cost volatility, REACH restriction acceleration, and Chinese technical gap closure speed were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumption sets and risk factors including single-source supply concentration and cross-border regulatory fragmentation. Quarterly review of EFSA notification processing rates and Jiangsu province R&D patent filings is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Antimicrobial Ingredients Market
Additives
Feed Additive Nosiheptide Premix Market
Additives
Europe Fuel Additives Market
Additives
Epoxy Type Stabilizers Market
Additives
Asia-Pacific Feed Acidifiers Market
Additives
Monocalcium Phosphate Market
Additives
Global PVC Additives Market
Additives
Global Rheology Modifiers Market
Additives
Global Isononanoic Acid Market
Additives
Global Dicalcium Phosphate (Feed Grade) Market
Additives
North America Potassium Nitrate Market
Additives
Encapsulated Citric Acid Market
Additives
Ballast Tank Corrosion Inhibitors Market
Additives
Japan Sodium Reduction Ingredient Market
Additives
Saudi Arabia Feed Additives Market
Additives
Phenolic Antioxidant Market