
 Inductive Encoder Market | 2026-2036
Inductive Encoder Market Size, Share, and Industry Trends Forecast 2026-2036
Inductive Encoder Market Analysis
Equipment leasing and pay-per-use financing for precision motion systems is fragmenting competitive access across the inductive encoder landscape. Renishaw plc leverages its captive manufacturing of scale and encoder readhead technologies to sustain premium positioning in metrology-grade applications. Pepperl+Fuchs anchors its presence through hazardous-area certification depth and channel density across process automation. HEIDENHAIN dominates high-resolution linear and angular feedback segments for CNC machinery and semiconductor equipment.
An inductive encoder detects rotational or linear position through electromagnetic coupling between a passive scale and active sensing head, typically achieving resolutions below one micrometer without optical contamination vulnerability. These devices furnish absolute or incremental position data to motion controllers in environments where dust, coolant mist, or vibration would degrade optical alternatives. Linear encoders lead product-type revenue pools due to their penetration in machine-tool axis control, while multi-turn encoders represent the fastest-expanding category as warehouse robotics and autonomous guided vehicles demand absolute angular tracking across power cycles. Magnetic encoding technology occupies the largest technology share by unit volume, though digital encoding interfaces are displacing analog outputs in new automation architectures.
FDA device-quality regulations and ISO 13849 machinery-safety standards in the United States shape encoder specification requirements for medical equipment and collaborative robot joints. The EU Machinery Directive and CE marking framework mandate functional-safety ratings that filter lower-tier suppliers from European automation supply chains. REACH substance restrictions and RoHS compliance constrain material choices in coil windings and PCB substrates across both markets. Stakeholders must monitor how IEC 61508 safety integrity level certifications evolve as a procurement gate for encoders entering autonomous mobile robot and human-robot collaboration platforms.
Market Dynamics
Factory automation in automotive manufacturing is accelerating encoder deployment as electromagnetic sensing replaces optical systems in contaminated machining environments. The EU Machinery Directive and CE marking requirements are tightening position-feedback reliability standards, filtering supplier tiers across European automation supply chains.
Growth Catalysts
- EU Machinery Directive functional-safety mandates:CE marking requirements for SIL-rated position feedback are filtering lower-tier suppliers from European automation supply chains, concentrating procurement among certified vendors.
- Warehouse robotics absolute tracking demand:Multi-turn encoders are expanding as autonomous guided vehicles require angular position retention across power cycles in fulfillment centers.
- Stuttgart-Munich industrial corridor concentration:Germany's machine-tool and automotive manufacturing clusters are driving specification intensity for metrology-grade linear encoders in precision axis control.
Market Restraints
- Copper and ferrite input cost volatility:Coil winding materials and magnetic core substrates face price pressure from energy-intensive smelting operations and rare-earth processing bottlenecks.
- Optical encoder residual performance gap:Nanometer-resolution semiconductor lithography and scientific instrumentation still favor interferometric and optical grating technologies where contamination control permits.
- REACH substance restrictions on PCB substrates:ECHA-regulated flame retardants and laminate chemistries constrain material choices in encoder electronics, extending qualification timelines.
Strategic Opportunities
- Medical equipment FDA device-quality pathways:ISO 13849 machinery-safety standards and FDA quality system regulations are creating specification entry points for encoders in surgical robotics and imaging gantries.
- Digital interface convergence with industrial Ethernet:BiSS-C and EtherCAT encoder protocols are displacing analog outputs in new automation architectures, enabling single-cable integration with servo drives.
- Human-robot collaboration safety certification:IEC 61508 SIL-2 and SIL-3 requirements for collaborative robot joints are opening procurement gates for functional-safety-rated inductive feedback systems.
Industry Challenges
- Functional-safety engineering talent scarcity:SIL certification expertise and FMEA methodology for safety-critical motion systems remain concentrated among specialized engineering consultancies and tier-one automation vendors.
- Legacy analog infrastructure integration friction:Retrofitting digital BiSS or SSI encoders into existing CNC machinery with ±10V or 1Vpp analog interfaces requires signal conditioning hardware and controller parameter revalidation.
- Multi-axis synchronization calibration complexity:Sub-micron contouring accuracy in five-axis machine tools demands thermal drift compensation and geometric error mapping across cascaded linear and rotary encoder chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inductive Encoder Market |
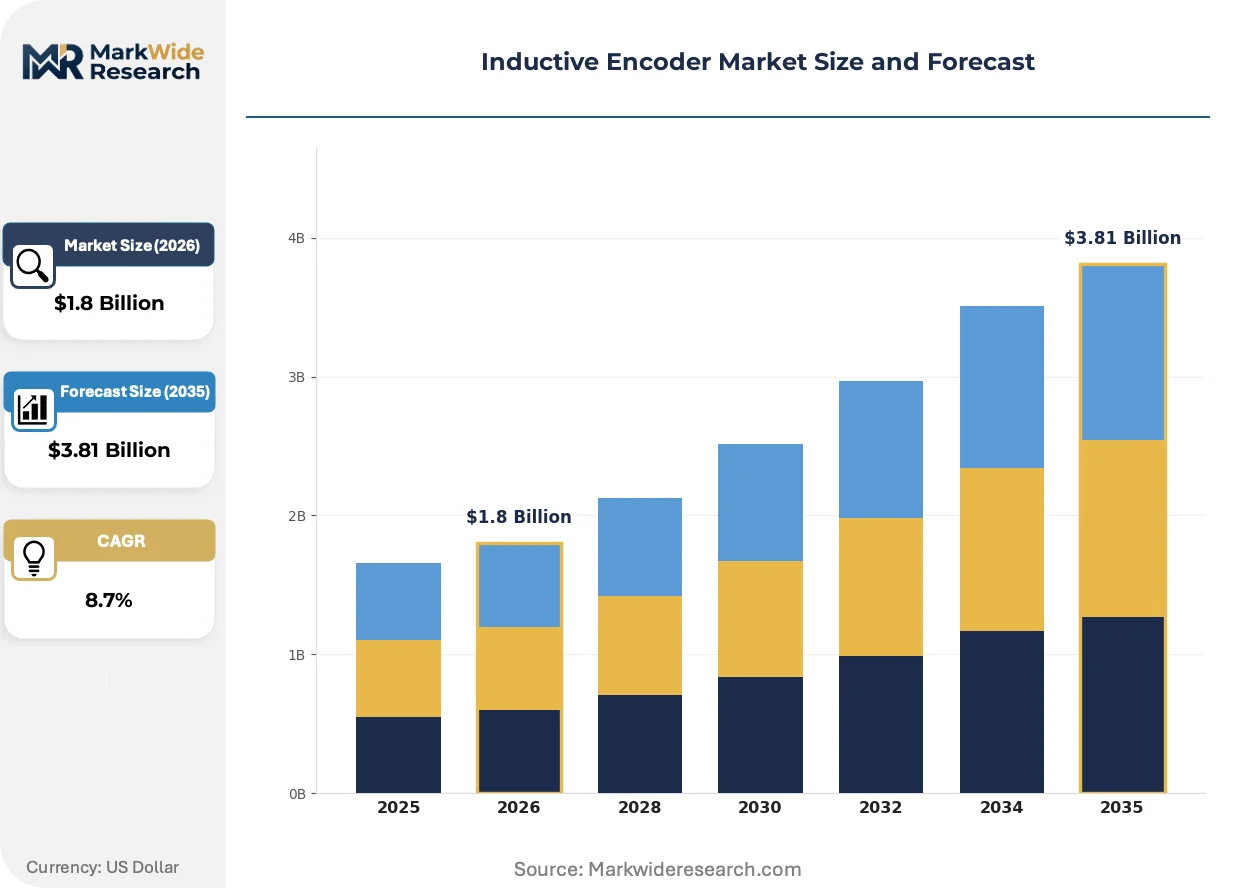
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Angular Encoders, Linear Encoders, Multi-turn Encoders, Single-turn Encoders Application: Robotics, CNC Machinery, Automation, Material Handling End User: Aerospace, Food & Beverage, Automotive Manufacturing, Packaging Industry Technology: Magnetic Encoding, Optical Encoding, Capacitive Encoding, Digital Encoding |
| Companies Covered | Renishaw plc, Pepperl+Fuchs, HEIDENHAIN, FRABA B.V., ifm electronic, Sensata Technologies, SICK AG, Hans Turck, Fortive (Dynapar), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inductive Encoder Market Emerging Trajectories
Electromagnetic sensing architectures are actively displacing optical alternatives in environments where coolant mist, metal dust, and vibration degrade glass-scale performance. Three convergent developments are reshaping competitive positioning and procurement patterns across factory automation, mobile robotics, and precision metrology.
Single-chip inductive sensing ICs with integrated signal conditioning and digital output drivers are collapsing the cost and size barriers that historically separated encoder electronics from motor drive integration. Automotive tier-one suppliers and collaborative robot manufacturers are adopting these monolithic solutions at 18-month design cycles. This integration is collapsing the traditional boundary between encoder module vendors and servo drive OEMs, compressing margins for standalone readhead suppliers.
REACH substance restrictions and RoHS compliance directives from ECHA are forcing reformulation of coil winding insulation and PCB laminate chemistries across European automation supply chains. Industrial encoder manufacturers are qualifying halogen-free substrates and lead-free solder alloys under extended thermal cycling protocols. Medical equipment and semiconductor capital equipment segments are most affected, with OEMs demanding full material disclosure documentation upstream to satisfy downstream regulatory filing requirements.
Equipment-as-a-service financing models are fragmenting competitive access across precision motion system procurement. Machine-tool builders and logistics automation integrators are unbundling encoder hardware from long-term service contracts, shifting specification authority from capital equipment buyers to fleet operators managing total cost of ownership. This transition is most visible in Germany's automotive manufacturing corridor, where Stuttgart-based OEMs are consolidating vendor panels around lifecycle performance guarantees rather than unit purchase price.
Inductive Encoder Market Segmentation
Inductive encoder procurement patterns diverge sharply across motion-control architectures, with product type determining integration complexity and application context dictating environmental resilience requirements. Understanding these segment boundaries clarifies where specification authority concentrates and how supplier capabilities map to buyer priorities.
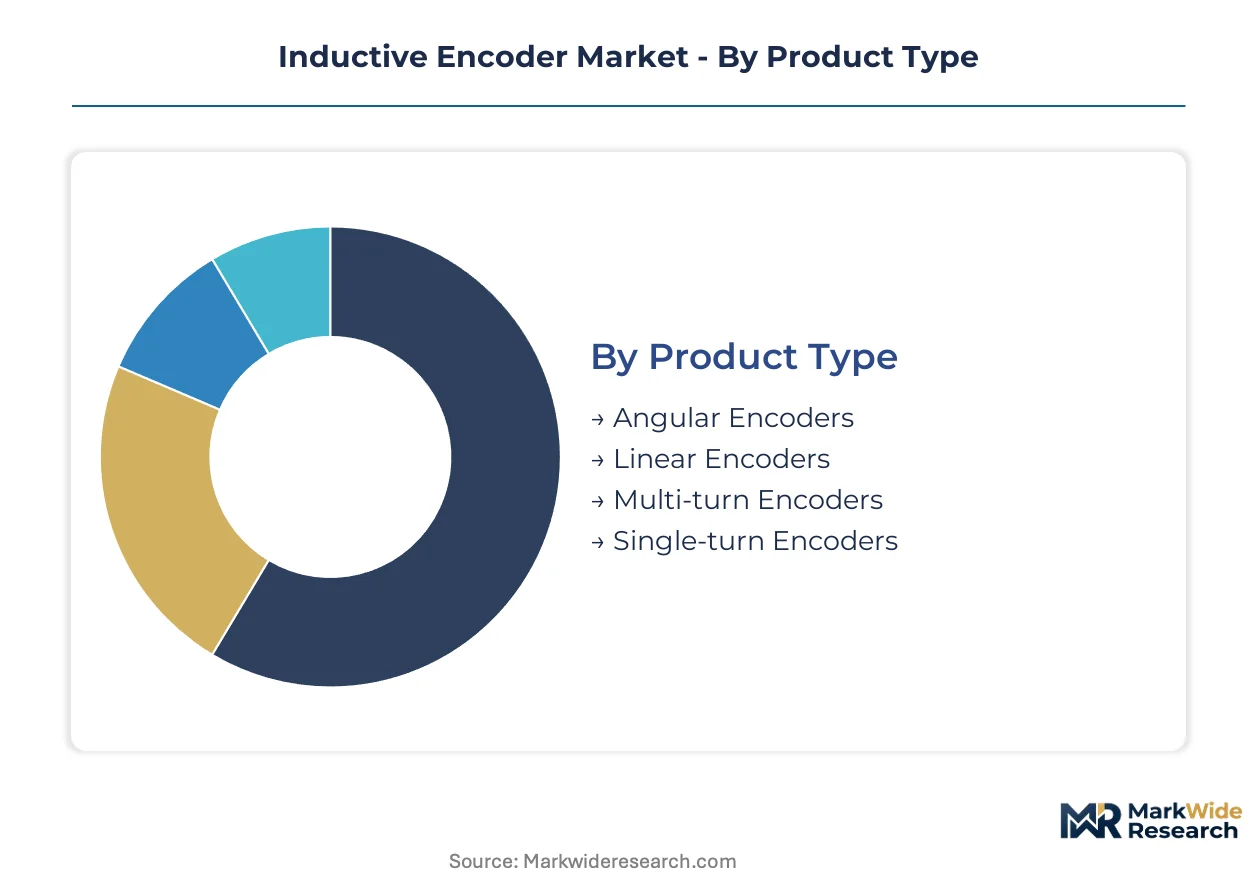
Product Type:
Replacement cycles stretch from 7-10 years for industrial machine-tool installations down to 18-24 months for mobile robotics platforms, compressing design-in windows for certain formats while locking others into decade-long supply relationships.
- Linear Encoders:These devices measure position along a straight axis through electromagnetic coupling between a passive scale and active sensing head, achieving sub-micrometer resolution without optical contamination vulnerability. Demand concentrates in Germany's Stuttgart-Munich industrial corridor where machine-tool builders specify metrology-grade feedback for precision axis control under heavy coolant mist conditions. HEIDENHAIN and Renishaw dominate this segment through captive scale manufacturing and calibration infrastructure.
- Multi-turn Encoders:Absolute angular position retention across power cycles eliminates homing routines in warehouse robotics and autonomous guided vehicles. Fulfillment center automation in the United States and European logistics hubs is driving specification intensity for battery-backed or gear-based turn-counting mechanisms that maintain location data during emergency stops.
- Angular Encoders:Rotary position feedback for servo motors and direct-drive turntables, with hollow-shaft designs penetrating collaborative robot joints.
- Single-turn Encoders:Incremental or absolute rotation sensing for cost-sensitive applications where power-cycle position loss is acceptable.
Linear encoders anchor the volume base while multi-turn encoders gain share at the steepest rate.
Application:
Cost tiers separate specification-intensive precision machinery from price-sensitive material handling systems, with certification requirements and interface complexity driving tier boundaries.
- CNC Machinery:Five-axis machine tools and precision grinding equipment demand sub-micron contouring accuracy with thermal drift compensation across cascaded encoder chains. Germany's automotive manufacturing corridor and Japan's machine-tool builders specify HEIDENHAIN and Renishaw systems with BiSS-C or EnDat digital interfaces, filtering suppliers without geometric error mapping capabilities.
- Robotics:Collaborative robot joints and surgical systems require IEC 61508 SIL-2 or SIL-3 functional safety ratings combined with compact form factors. FDA device-quality regulations in the United States and ISO 13849 machinery-safety standards shape encoder specifications for medical equipment and human-robot collaboration platforms.
- Automation:Factory floor motion control for assembly systems and test equipment, with EtherCAT integration displacing analog outputs.
- Material Handling:Conveyor positioning and crane feedback prioritize environmental sealing over resolution, with Pepperl+Fuchs hazardous-area certifications penetrating process industries.
CNC machinery commands the premium tier while robotics applications are expanding most quickly.
End User:
Customer concentration patterns reveal how OEM consolidation and fleet operator procurement authority reshape competitive access across vertical markets.
- Automotive Manufacturing:Electromagnetic sensing replaces optical systems in contaminated machining environments across Germany's Volkswagen-BMW-Mercedes supply base. Equipment-as-a-service financing models are shifting specification authority from capital equipment buyers to Stuttgart-based fleet operators managing total cost of ownership through lifecycle performance guarantees.
- Aerospace:Flight control surface actuation and landing gear position sensing demand DO-178C software assurance and extended temperature ranges. Boeing and Airbus tier-one suppliers qualify encoder vendors through multi-year reliability demonstrations.
- Food & Beverage:IP69K washdown ratings and stainless steel housings predominate in packaging and processing equipment subject to caustic cleaning protocols.
- Packaging Industry:High-speed rotary sealing and labeling machines prioritize compact hollow-shaft designs with 10,000+ RPM capability.
Automotive manufacturing anchors the volume base while aerospace applications are climbing the fastest.
Technology:
Interface architecture determines integration friction and margin structure, with digital protocols collapsing traditional boundaries between encoder module vendors and servo drive OEMs.
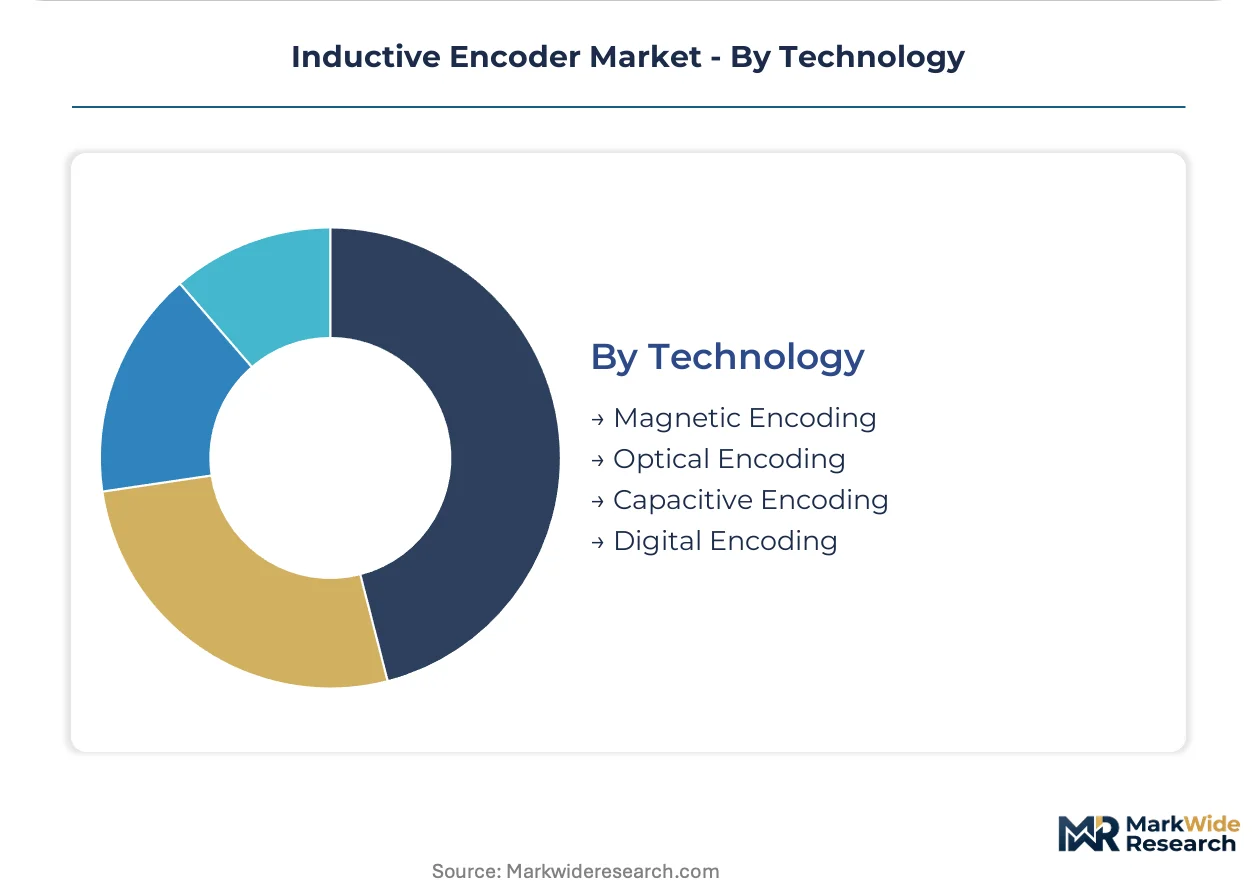
- Magnetic Encoding:Anisotropic magnetoresistive and Hall-effect sensing dominate unit volume through cost-optimized single-chip solutions. Automotive tier-one suppliers and collaborative robot manufacturers are adopting monolithic inductive sensing ICs at compressed 18-month design cycles, integrating signal conditioning and digital output drivers directly onto motor drive PCBs.
- Digital Encoding:BiSS-C, EtherCAT, and EnDat protocols are displacing analog outputs in new automation architectures, enabling single-cable integration with servo drives and reducing wiring complexity. This interface convergence is compressing margins for standalone readhead suppliers while favoring vendors with protocol stack expertise.
- Optical Encoding:Interferometric and grating technologies retain nanometer-resolution applications in semiconductor lithography where contamination control permits.
- Capacitive Encoding:Emerging for ultra-compact applications with moderate precision requirements and severe space constraints.
Magnetic encoding commands the volume base while digital encoding is gaining share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics favor established manufacturing economies with captive encoder production. Germany and Japan maintain trade surpluses in precision feedback systems. The United States and China balance domestic assembly against component sourcing from European specialists.
Germany
Machine-tool builders in Baden-Württemberg and Bavaria specify metrology-grade linear encoders for precision axis control under heavy coolant mist. The EU Machinery Directive and CE marking requirements filter procurement toward SIL-certified vendors. Stuttgart-based automotive OEMs consolidate vendor panels around lifecycle performance guarantees rather than unit purchase price.
United States
Warehouse robotics and autonomous guided vehicles drive multi-turn encoder specifications for absolute angular tracking across power cycles. FDA device-quality regulations and ISO 13849 machinery-safety standards shape encoder requirements for surgical robotics and imaging gantries. Fulfillment center automation concentrates demand in the Midwest logistics corridor and California's Inland Empire distribution hubs.
Japan
Semiconductor capital equipment and precision grinding machinery sustain demand for sub-micron resolution feedback systems. METI industrial standards and JIS certification frameworks govern encoder integration into CNC architectures. Nagoya's machine-tool cluster and Tokyo's precision equipment corridor anchor specification intensity for digital interface protocols.
China
Domestic automation equipment builders accelerate encoder deployment as factory floor electrification expands. MIIT industrial internet standards and GB certification requirements shape local procurement toward interoperable digital outputs. The Yangtze River Delta manufacturing belt and Pearl River Delta electronics corridor concentrate demand for cost-optimized magnetic encoding solutions.
South Korea
Display manufacturing equipment and battery cell assembly lines specify high-resolution linear encoders for precision positioning. MFDS medical device regulations and KOSHA industrial safety standards filter encoder selection for collaborative robot joints. The Seoul Capital Area and Busan-Ulsan industrial complex anchor demand for EtherCAT-integrated feedback systems.
Inductive Encoder Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying readheads and scale technologies. The vendor base stratifies across three tiers: metrology-grade precision houses, industrial automation generalists, and cost-optimized volume manufacturers. Two strategic archetypes dominate competitive positioning: captive scale manufacturers with calibration infrastructure, and protocol-stack specialists enabling single-cable servo integration. Consolidation pressures favor vendors with functional-safety certification depth and digital interface expertise.
Among precision feedback specialists, Renishaw plc and HEIDENHAIN occupy positions exemplifying the metrology-grade archetype through captive manufacturing of scale technologies. Pepperl+Fuchs represents the hazardous-area certification depth model, anchoring process automation penetration through channel density. These three firms illustrate how supplier tier boundaries harden around CE marking compliance and SIL-rated engineering capabilities.
| Leading Market Players |
|---|
| Renishaw plc |
| Pepperl+Fuchs |
| HEIDENHAIN |
| FRABA B.V. |
| ifm electronic |
| Sensata Technologies |
| SICK AG |
| Hans Turck |
| Fortive (Dynapar) |
| Others |
Supply Flow & Price Mechanics
The Rhine-Alpine freight corridor's container cost dynamics feed directly into encoder pricing power, concentrating margin leverage among German and Swiss vendors while forcing tier-two suppliers toward standard-grade positioning. Supply concentration in Baden-Württemberg and Bavaria amplifies this effect, as logistics proximity to Stuttgart-Munich machine-tool clusters enables premium pricing for metrology-grade linear systems while distant competitors absorb freight penalties or concede specification intensity.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on SIL certification grade and volume scale, with CE-marked functional-safety encoders commanding substantial premiums over uncertified alternatives. Pricing pressure stems from single-chip inductive sensing ICs collapsing the cost barrier between encoder modules and integrated motor drives. Tier-one automotive OEMs exhibit lowest price sensitivity due to lifecycle performance guarantees, while logistics automation integrators face acute cost compression from equipment-as-a-service financing models.
Supply Chain Analysis
Copper wire feedstock and ferrite core substrates draw from German, Chinese, and Japanese metallurgical suppliers, with coil winding operations concentrated in Central European electronics manufacturing corridors. Rare-earth processing for magnetic materials rests on Chinese separation capacity, creating tariff exposure amid escalating trade friction. Single-source vulnerability permeates the precision scale substrate tier, where HEIDENHAIN and Renishaw maintain captive manufacturing. Distribution runs through authorized automation distributors and direct OEM supply contracts, with channel density in process industries filtering toward Pepperl+Fuchs and SICK AG.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against optical encoder residual performance in nanometer-resolution semiconductor lithography, where contamination-controlled environments still favor interferometric technologies. Incumbents must harden their electromagnetic sensing value proposition while encroaching on optical strongholds through environmental resilience messaging.
For Market Incumbents: Pre-empt margin compression from integrated motor-drive encoders by deepening SIL certification depth and protocol-stack expertise in BiSS-C and EtherCAT architectures. Backward integration into scale manufacturing secures supply security against rare-earth processing bottlenecks. Defend metrology-grade positioning through captive calibration infrastructure in Germany's industrial corridor.
For New Entrants and Emerging Players: Pursue white-space penetration in warehouse robotics multi-turn encoders for autonomous guided vehicles, where battery-backed turn-counting mechanisms face specification intensity but certification barriers remain lower than CNC machinery. Target Midwest US logistics corridor fulfillment centers with cost-optimized magnetic encoding solutions. Anchor go-to-market through equipment-as-a-service fleet operators rather than capital equipment buyers.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underutilized encoder divisions lacking functional-safety certification depth. Long-term viability favors vendors with IEC 61508 SIL-2 and SIL-3 engineering capabilities as procurement gates tighten for collaborative robot joints. Watch for inflection in EtherCAT encoder protocol adoption rates as a signal of digital interface convergence maturity.
| Strategic Initiative | Industry Significance |
|---|---|
| Functional-Safety Certification Investment | IEC 61508 SIL-2 and SIL-3 ratings filter European automation supply chains toward certified vendors. |
| Digital Interface Protocol Integration | BiSS-C and EtherCAT adoption enables single-cable servo integration, compressing standalone readhead margins. |
| Captive Scale Manufacturing Expansion | In-house production of precision substrates secures supply continuity against rare-earth processing constraints. |
| Equipment-as-a-Service Partnership Model | Lifecycle performance guarantees with Stuttgart-based automotive OEMs shift specification authority from buyers to operators. |
| Halogen-Free Substrate Qualification | REACH-compliant laminate chemistries satisfy medical equipment and semiconductor capital equipment disclosure requirements. |
Methodological Framework
Operator-level perspectives from plant engineers, OEM procurement teams, aftermarket service heads, and automation system integrators anchored the qualitative base. Primary interviews combined with secondary validation from SEC filings, customs and trade data, machine-tool production databases, and EU Machinery Directive implementation guidance. Bottom-up encoder shipment estimates triangulated against top-down industrial automation capex analysis across the projection horizon.
Scenario-bracketing framed the analytical approach, with segmentation dimensions spanning product type, application context, end-user vertical, and digital interface protocol. CAGRs derived from installed base replacement cycles and new automation architecture penetration curves. Forecast inputs incorporated machine-tool axis control specification intensity and warehouse robotics absolute tracking demand across the analysis window.
Macroeconomic conditions sit as an overlay; deviation in industrial capital expenditure cycles and rare-earth commodity pricing would shift the trajectory. Forecasts reflect assumptions around EU Machinery Directive enforcement consistency and semiconductor lithography contamination control standards. Cross-checking against German machine-tool order intake data and US logistics automation deployment metrics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
PID Controller Market
Sensors and Controls
Europe Acoustic Sensors Market
Sensors and Controls
North America Proximity Sensor Market
Sensors and Controls
United States Smart Sensors Market
Sensors and Controls
Light Detection and Ranging (Lidar) Market
Sensors and Controls
Asia-Pacific CO2 Gas Sensor Market
Sensors and Controls
Laser Scanner Market
Sensors and Controls
GCC Air Purifiers Market
Sensors and Controls
Global Sonar Systems and Technology Market
Sensors and Controls
Fiber Bragg Grating Sensor Market
Sensors and Controls
Global Single Loop Controller Market
Sensors and Controls
Global Sensors Market
Sensors and Controls
Industrial Wireless Sensor Market
Sensors and Controls
Global RFID Sensor Market
Sensors and Controls
Wind Speed Sensor Market
Sensors and Controls
Smart Visor Market