
 Global Sensors Market | 2026-2036
Global Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sensors Market Outlook
Multi-sourcing strategies for MEMS foundry capacity is broadening vendor options for fabless sensor designers. STMicroelectronics leverages captive 200mm and 300mm fabs to sustain gross margins on inertial and environmental sensors. Texas Instruments anchors North American supply security through its Sherman, Texas 300mm analog fab complex. Robert Bosch GmbH competes on automotive pedigree, extending its dominance in pressure and gas sensors for powertrain management.
Sensors are transducer devices that convert physical, chemical, or biological stimuli into measurable electrical signals, typically operating across sensitivity ranges from microvolts to millivolts with response times measured in milliseconds. Their primary commercial purpose is enabling closed-loop control, safety interlocks, and condition monitoring in electromechanical systems. Pressure sensors lead industrial automation deployments where process control mandates SIL-rated measurement chains. MEMS technology occupies the fastest-expanding margin pool, shrinking die sizes while integrating signal conditioning on-chip. Smart sensors are maturing in consumer electronics, where on-device inference reduces cloud dependency for gesture and ambient-light detection.
FDA 21 CFR Part 820 quality system requirements shape design controls for sensors embedded in Class II and Class III medical devices, while EU MDR imposes stricter clinical evidence thresholds on patient-contacting physiological monitors. REACH substance restrictions and RoHS hazardous material limits constrain electrode and packaging material choices across European-bound product lines. Stakeholders must monitor how IEC 61508 functional safety standards propagate from automotive into industrial robotics and autonomous logistics platforms.
Market Dynamics
Automotive electrification is compressing sensor qualification timelines while multiplying functional safety requirements per platform, forcing foundry partners to synchronize process maturity with tier-one validation gates.
Growth Catalysts
- EU Green Deal emissions mandates:Powertrain electrification requires exhaust gas, battery thermal, and cabin air quality sensors at densities exceeding internal combustion baselines by an order of magnitude.
- China smart city infrastructure:Municipal procurement of environmental monitoring nodes and traffic flow detection arrays is accelerating MEMS and optical module deployment across tier-one and tier-two urban clusters.
- Edge AI inference:On-device neural processing is creating demand for smart sensors with integrated preprocessing, reducing cloud round-trip latency for gesture recognition and predictive maintenance.
Market Restraints
- 200mm silicon wafer supply concentration:MEMS fabrication depends on mature-node substrates where foundry capacity is tightening against automotive and industrial analog demand.
- Palladium and platinum electrode cost volatility:Gas sensors for automotive and industrial safety applications face input cost swings tied to precious metal commodity markets.
- REACH substance restrictions:RoHS hazardous material limits and ECHA candidate list updates constrain lead-free solder alternatives and piezoelectric ceramic formulations.
Strategic Opportunities
- India industrial automation:PLI scheme incentives for electronics manufacturing are drawing sensor module assembly and test capacity to Gujarat and Tamil Nadu corridors.
- Digital health physiological monitoring:FDA 21 CFR Part 820 and EU MDR convergence is creating design-win opportunities for Class II wearable sensors with clinical-grade signal chains.
- Photonics-MEMS convergence:LiDAR and optical coherence tomography applications are driving heterogeneous integration of micro-optics with inertial sensing die.
Industry Challenges
- Functional safety certification timelines:IEC 61508 SIL qualification for industrial pressure and gas sensors extends development cycles by 18-24 months.
- Multi-physics simulation talent scarcity:Coupled electro-mechanical-fluidic modeling for MEMS design requires specialized expertise concentrated in academic and national lab ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sensors Market |
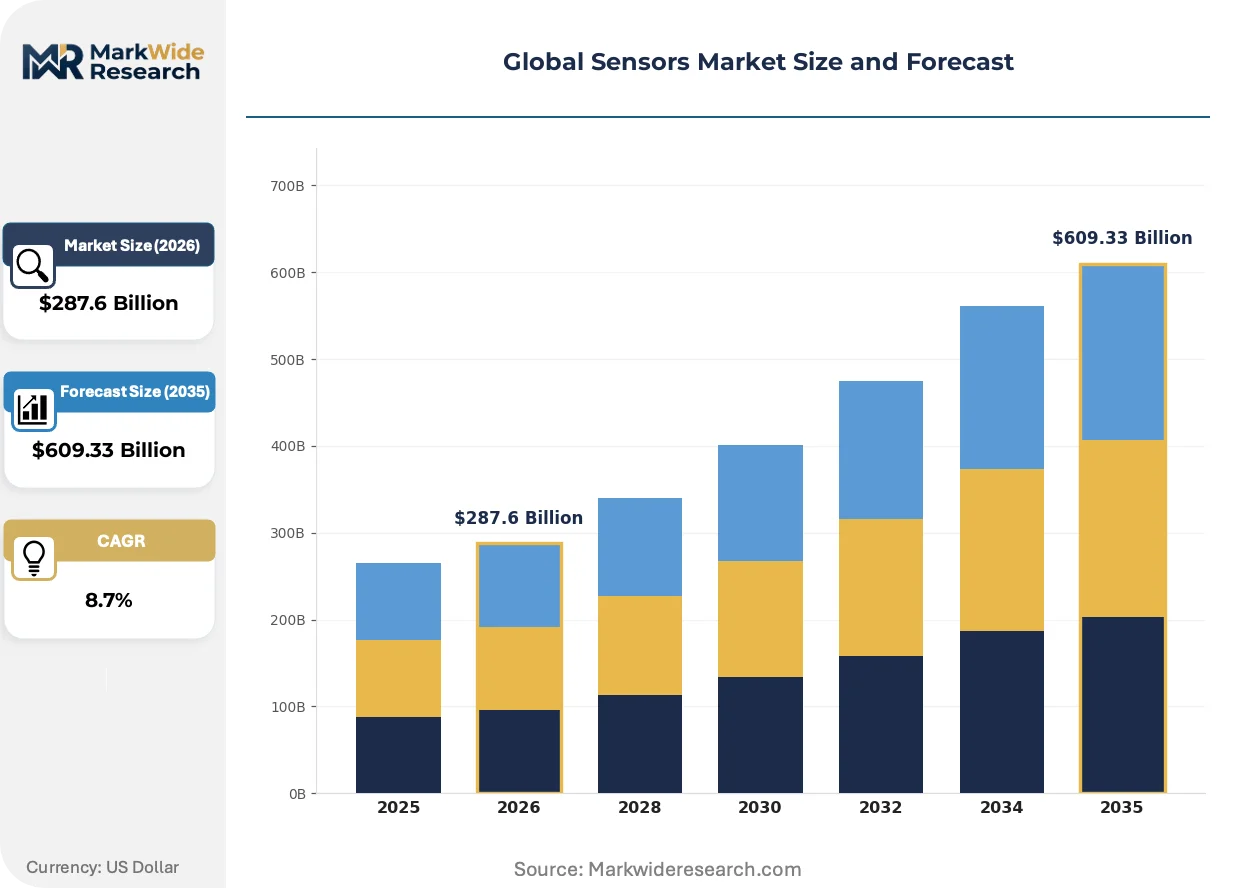
| Market Size in 2026 | $287.6 Billion |
| Market Size in 2035 | $609.33 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Temperature Sensors, Pressure Sensors, Proximity Sensors, Light Sensors Application: Consumer Electronics, Automotive Automation, Industrial Automation, Healthcare Monitoring Technology: MEMS, Optical Sensors, Smart Sensors, Analog Sensors End User: Manufacturing, Healthcare, Automotive, Telecommunications |
| Companies Covered | STMicroelectronics, Texas Instruments, Infineon Technologies AG, NXP Semiconductors, Honeywell International Inc., Robert Bosch GmbH, Analog Devices, Inc., TE Connectivity Ltd, Omron Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sensors Market Strategic Shifts
Sensor architectures are fragmenting between centralized domain controllers and distributed edge nodes, with packaging and power management innovations determining competitive positioning in power-constrained applications.
Time-of-flight and structured light depth sensing is decentralizing 3D perception from dedicated vision processors into compact modules for robotics and consumer devices. Automotive cabin monitoring and warehouse automation vendors are adopting these units at qualification volumes. This diffusion is compressing the addressable market for discrete camera-plus-processor combinations.
EU AI Act risk classification tiers are mandating transparency and human oversight for sensors embedded in high-risk applications including biometric identification and critical infrastructure monitoring. Industrial OEMs are redesigning signal chains to enable local logging and audit trails. Medical device manufacturers face the strictest evidentiary thresholds for patient-contacting physiological monitors.
Direct contracting between automotive OEMs and MEMS foundries is displacing traditional tiered supplier hierarchies for inertial and pressure sensing die. German and Japanese vehicle manufacturers are establishing preferred supplier status with 200mm and 300mm analog fabs. This restructuring is visible most acutely in powertrain and chassis domains where single-source qualification carries liability exposure.
Global Sensors Market Segmentation
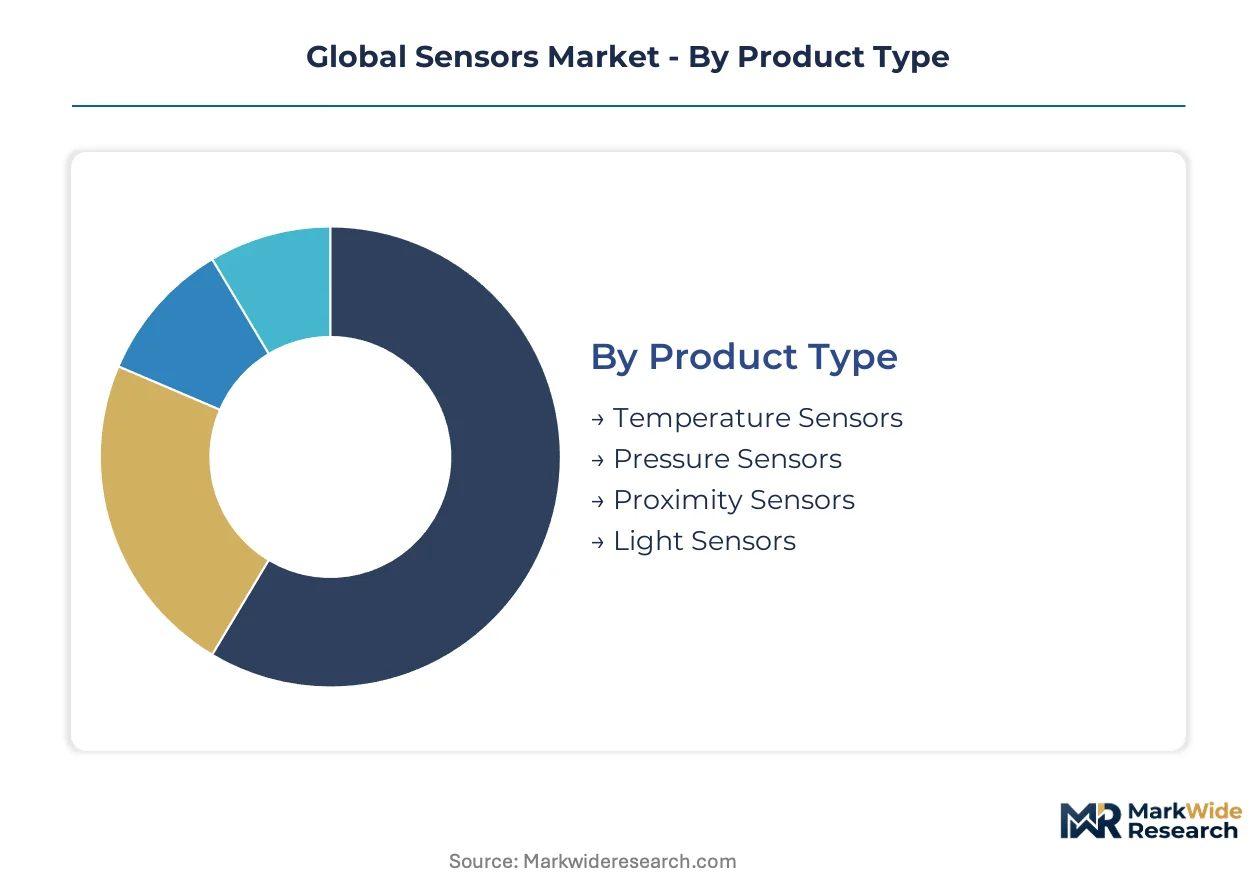
Sensor architectures fragment across multiple classification axes, each revealing distinct procurement patterns and margin structures. Understanding these segment boundaries enables targeted positioning against qualification timelines and foundry capacity constraints.
Product Type:
Thermal and mechanical transduction specifications define die design rules and packaging requirements across industrial qualification tiers.
- Temperature Sensors:Thermocouple, RTD, and thermistor architectures span measurement ranges from cryogenic to exhaust gas environments. Automotive battery thermal management and industrial process control in Germany and Japan concentrate procurement for SIL-rated variants.
- Pressure Sensors:Piezoresistive MEMS and capacitive ceramic elements dominate, with automotive manifold absolute pressure and industrial hydraulic systems driving volume. Tier-one automotive OEMs in Stuttgart and Toyota City are establishing direct foundry relationships for these components.
- Proximity Sensors:Inductive, capacitive, and ultrasonic detection principles serve industrial safety interlocks and mobile device wake functions.
- Light Sensors:Photodiode and phototransistor arrays enable ambient light adjustment and optical encoders.
Pressure sensors lead on scale; temperature sensors lead on momentum across electrification platforms.
Application:
End-use environments impose divergent reliability and certification burdens that reshape vendor selection criteria.
- Automotive Automation:Powertrain electrification multiplies sensor counts per platform while compressing qualification timelines. EU Green Deal emissions mandates in France and Italy are accelerating exhaust gas and battery thermal sensor procurement beyond internal combustion baselines.
- Industrial Automation:Process control mandates SIL-rated measurement chains for pressure and gas detection. Manufacturing corridors in Gujarat and Tamil Nadu under India's PLI scheme are drawing module assembly capacity.
- Consumer Electronics:On-device inference reduces cloud dependency for gesture and ambient-light detection.
- Healthcare Monitoring:FDA 21 CFR Part 820 and EU MDR convergence creates design-win opportunities for Class II wearable sensors with clinical-grade signal chains.
Industrial automation leads on scale; automotive automation leads on momentum.
Technology:
Fabrication node maturity and integration density determine competitive positioning in power-constrained deployments.
- MEMS:Micro-electromechanical systems shrink die sizes while integrating signal conditioning on-chip, occupying the fastest-expanding margin pool. China smart city infrastructure in Shenzhen and Chengdu is accelerating procurement of MEMS environmental monitoring nodes.
- Smart Sensors:On-device neural processing creates demand for integrated preprocessing, reducing cloud round-trip latency for predictive maintenance.
- Optical Sensors:Time-of-flight and structured light depth sensing decentralizes 3D perception into compact modules for robotics.
- Analog Sensors:Discrete transducer architectures persist where electromagnetic immunity or extreme temperature operation exceeds CMOS integration limits.
MEMS leads on scale; smart sensors lead on momentum.
End User:
Procurement concentration and contract structures vary sharply across vertical integration levels.
- Automotive:German and Japanese vehicle manufacturers are restructuring supplier hierarchies, establishing preferred foundry status for inertial and pressure sensing die. Direct OEM-foundry contracting is displacing traditional tiered relationships in powertrain domains.
- Manufacturing:Industrial OEMs are redesigning signal chains to enable local logging and audit trails under EU AI Act transparency mandates.
- Healthcare:Patient-contacting physiological monitors face strictest evidentiary thresholds under EU MDR.
- Telecommunications:Network infrastructure monitoring drives environmental and power sensing for edge data centers.
Automotive leads on scale; healthcare leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting sensor module assembly toward jurisdictions with streamlined environmental compliance and targeted manufacturing incentives. Foundry partners and fabless designers are relocating test-and-packaging operations where REACH substance restrictions and carbon border adjustments impose lighter cost burdens than European baselines.
China
Shenzhen and Chengdu municipal governments are accelerating procurement of MEMS environmental monitoring nodes for smart city infrastructure buildouts. MIIT dual carbon goals mandate denser air quality sensing networks in tier-one urban clusters. Domestic foundry scale in Yangtze River Delta corridors is absorbing fabless design houses seeking captive 200mm capacity.
Germany
Stuttgart and Munich automotive OEMs are establishing direct foundry relationships for pressure and inertial sensing die in powertrain domains. EU Green Deal emissions mandates tighten exhaust gas sensor performance requirements beyond internal combustion baselines. KBA type-approval processes are compressing qualification timelines for battery thermal management systems.
United States
Sherman, Texas analog fab complexes anchor North American supply security for automotive and industrial sensor die. EPA emissions enforcement and NHTSA functional safety standards shape design controls for powertrain and chassis applications. Southeast automotive corridors in Tennessee and South Carolina are drawing module assembly capacity to serve electrification platforms.
India
Gujarat and Tamil Nadu manufacturing corridors under PLI scheme incentives are drawing sensor module assembly and test operations. BIS certification requirements for industrial automation components are streamlining against European SIL-rated benchmarks. Domestic procurement of process control sensors is concentrating in Pune and Bengaluru industrial clusters.
Japan
Toyota City and Nagoya automotive suppliers are restructuring tiered hierarchies toward direct OEM-foundry contracting for gas and pressure sensing die. METI technology roadmaps prioritize heterogeneous integration of MEMS with micro-optics for LiDAR applications. Osaka-based industrial OEMs are redesigning signal chains for EU AI Act transparency compliance in export-bound robotics.
Global Sensors Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue smart sensor integration and edge AI preprocessing capabilities. The vendor base stratifies across captive foundry operators, fabless design specialists, and diversified industrial conglomerates with automotive pedigree. European IDMs and Japanese precision manufacturers anchor the premium tier through SIL-rated qualification histories. Competitive moves concentrate on foundry capacity reservation and heterogeneous packaging partnerships for photonics-MEMS convergence.
Among European-based diversified industrials, Robert Bosch GmbH and Infineon Technologies AG exemplify the automotive-pedigree archetype with deep powertrain sensing lineages. STMicroelectronics occupies a position bridging captive foundry scale and consumer MEMS volume. Texas Instruments anchors North American supply security through analog fab concentration. These three represent distinct strategic postures: Bosch the integrated systems supplier, Infineon the automotive semiconductor specialist, and Texas Instruments the analog process technology steward.
| Leading Market Players |
|---|
| STMicroelectronics |
| Texas Instruments |
| Infineon Technologies AG |
| NXP Semiconductors |
| Honeywell International Inc. |
| Robert Bosch GmbH |
| Analog Devices, Inc. |
| TE Connectivity Ltd |
| Omron Corporation |
| Others |
Value Chain & Pricing Dynamics
SIL-rated certification tiers for industrial pressure and gas sensors create a three-rung pricing ladder that separates automotive-qualified MEMS die from commodity analog transducers, with each rung demanding distinct foundry partnerships and qualification timelines that reshape procurement economics across German automotive corridors and Chinese smart city deployments.
Pricing Analysis
Distributor margins on standard-grade proximity and light sensors compress under direct OEM-foundry contracting that German and Japanese vehicle manufacturers now favor for inertial and pressure sensing die. Three-tier pricing structure across automotive-qualified, industrial SIL-rated, and consumer-grade variants reflects the cost of IEC 61508 functional safety certification and REACH-compliant material sourcing. Pricing pressure stems from 200mm wafer supply tightening against automotive analog demand. Tier-one automotive OEMs exhibit lowest price sensitivity due to liability exposure in powertrain domains, while consumer electronics buyers drive hardest bargain on MEMS environmental modules.
Supply Chain Analysis
Engineering talent scarcity in coupled electro-mechanical-fluidic modeling concentrates MEMS design expertise in Massachusetts and Grenoble academic ecosystems, forcing foundry partners to recruit from national lab pipelines. Manufacturing gravity centers on China for module assembly, Germany for automotive-qualified pressure sensors, and Texas for analog fab capacity. Raw material dependencies include palladium and platinum electrodes for gas sensors, 200mm silicon wafers for MEMS fabrication, and lead-free solder alloys for RoHS-compliant packaging. Single-source qualification risk looms where automotive OEMs lock preferred supplier status with specific 200mm fabs. Distribution runs through tiered supplier hierarchies in legacy automotive, direct contracting in electrification platforms, and spot procurement in consumer electronics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sensors market rewards geographic arbitrage between India's PLI-subsidized assembly corridors and Europe's carbon-border-adjusted manufacturing costs, with Gujarat and Tamil Nadu offering 15-25% landed cost advantages on industrial automation modules bound for EU industrial OEMs.
For Market Incumbents: Cement captive foundry relationships through capacity reservation agreements at 200mm and 300mm analog fabs in Sherman, Texas and Dresden, Germany, insulating against MEMS supply concentration while extending SIL-rated qualification histories into emerging LiDAR and battery thermal management applications where emerging photonics-MEMS specialists threaten margin pools. For New Entrants and Emerging Players: Direct-to-OEM digital sales channels bypass entrenched tiered supplier hierarchies in automotive powertrain domains where German and Japanese manufacturers actively seek second-source qualification for inertial sensing die. White-space concentrates in India industrial automation under PLI scheme incentives and in FDA 21 CFR Part 820-compliant Class II wearable sensors where clinical-grade signal chain expertise remains scarce. For Investors and Strategic Acquirers: Asymmetric upside sits with fabless design houses possessing heterogeneous integration capabilities for photonics-MEMS convergence in LiDAR and optical coherence tomography applications. Five-to-ten-year viability hinges on securing preferred foundry status before automotive OEMs complete supplier hierarchy restructuring. Watch for direct contracting announcements between Stuttgart or Toyota City OEMs and 200mm analog fabs as inflection signal for MEMS supply chain reconfiguration.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Foundry Capacity Reservation | Locks 200mm MEMS supply for automotive qualification timelines against tightening substrate availability. |
| Heterogeneous Packaging Partnership | Enables photonics-MEMS convergence for LiDAR modules demanded by German OEM cabin monitoring programs. |
| SIL Certification Fast-Track Investment | Compresses IEC 61508 qualification cycles to match compressed automotive electrification timelines. |
| India Module Assembly Relocation | Captures PLI scheme incentives for industrial automation sensors serving EU AI Act transparency mandates. |
| Direct OEM Sales Channel Development | Displaces tiered supplier margins in powertrain domains where single-source liability drives procurement reform. |
Study Parameters
Bottom-up automotive and industrial automation modeling reconciled against top-down MEMS foundry capacity tracking forms the analytical core of this study. Primary interviews with MEMS design engineers, tier-one automotive procurement directors, industrial OEM maintenance directors, and fabless sensor startup CTOs informed demand-side assumptions. Secondary validation drew from EPA emissions enforcement databases, KBA type-approval filings, MIIT dual carbon goal disclosures, and BIS certification registries. Cross-referencing bottom-up segment builds with top-down supply-side constraints ensured triangulation integrity.
Historical production trendlines for pressure, temperature, and inertial sensing modules established baseline growth patterns across the projection horizon. Segmentation dimensions modeled include product type, application environment, fabrication technology, and end-user vertical, with additional granularity on automotive propulsion architecture and industrial SIL-rating tier. CAGRs were derived from elasticity-adjusted demand curves against foundry capacity expansion schedules. Forecast inputs incorporated EU Green Deal emissions mandate timelines, China smart city procurement cycles, and FDA-EU MDR regulatory convergence patterns.
The model assumes a particular technology adoption path; alternative pathways for edge AI inference integration would alter the outlook if on-device neural processing adoption accelerates beyond gesture recognition into predictive maintenance domains. Forecasts reflect assumptions about palladium electrode cost stability, 200mm wafer supply availability, and REACH substance restriction enforcement consistency. Material deviation in automotive electrification penetration rates, India PLI scheme renewal terms, or EU AI Act implementation rigor warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Piezoelectric Sensor Market
Sensors and Controls
Global Hazardous Location Thermostats Market
Sensors and Controls
Exhaust Sensors Market
Sensors and Controls
Middle East and Africa Lidar Market
Sensors and Controls
Digital Infrared Thermometer Market
Sensors and Controls
Global Biosensors Market
Sensors and Controls
Dew Point Thermometer Market
Sensors and Controls
MEMS Market
Sensors and Controls
Bee Hive Monitoring Sensor Market
Sensors and Controls
Smart Control Socket Market
Sensors and Controls
Reflective Encoder Market
Sensors and Controls
Piezoelectric Devices Market
Sensors and Controls
Automotive Cabin Air Quality Sensors Market
Sensors and Controls
Japan Digital Thermometer Market
Sensors and Controls
Europe Machine Condition Monitoring Market
Sensors and Controls
Global Load Cell Market