
 Asia-Pacific CO2 Gas Sensor Market | 2026-2036
Asia-Pacific CO2 Gas Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific CO2 Gas Sensor Market Insights
Aftermarket calibration and sensor refurbishment revenue is fragmenting across the Asia-Pacific CO2 gas sensor value chain as original equipment manufacturers defend service attach rates. Siemens AG leverages its building automation platform to sustain recurring calibration contracts across Southeast Asian commercial portfolios. Honeywell International anchors its position through channel control of HVAC-integrated sensor distribution in Australia and New Zealand. Vaisala Oyj competes on measurement accuracy in pharmaceutical cleanroom applications across South Korea and Taiwan.
Asia-Pacific CO2 gas sensors employ non-dispersive infrared (NDIR) detection principles, measuring carbon dioxide concentrations typically from 400 ppm to 5,000 ppm with ±30 ppm accuracy for indoor air quality applications. These devices convert infrared light absorption at 4.26 micrometers wavelength into electrical signals for real-time environmental control. Fixed sensors dominate commercial building installations where continuous monitoring integrates with building management systems, while wireless sensors represent the fastest-expanding category as retrofit demand accelerates across aging infrastructure in Japan and Singapore. Optical sensors lead technology margins due to superior stability and reduced drift compared to electrochemical alternatives.
Japan's METI enforces building energy efficiency standards that mandate CO2 monitoring in commercial structures over 2,000 square meters, while China's MEE implements dual carbon compliance frameworks requiring industrial emissions tracking. Australia's NCC Section J provisions and South Korea's Green Building Certification criteria further shape product specification requirements. Stakeholders must monitor regulatory divergence between national building codes and emerging smart city data interoperability standards to anticipate certification burden shifts.
Market Dynamics
Smart building automation mandates across Asia-Pacific commercial real estate are compressing sensor replacement cycles as facility managers prioritize real-time air quality data integration over legacy equipment maintenance schedules.
Growth Catalysts
- China's dual carbon framework:The MEE's industrial emissions tracking requirements force manufacturing facilities to install continuous CO2 monitoring systems for compliance reporting across steel and cement plants.
- Indoor air quality certification:South Korea's Green Building Certification criteria mandate CO2 sensors in new commercial construction above 1,000 square meters, creating specification pull through HVAC contractors.
- Wireless retrofit acceleration:Battery-powered NDIR sensors eliminate wiring costs in aging Japanese and Singaporean infrastructure, expanding addressable building stock without structural renovation.
Market Restraints
- Optical component supply concentration:Infrared sources and detectors concentrate among specialized Japanese and German component suppliers, exposing sensor assemblers to lead time volatility.
- Electrochemical sensor residual demand:Cost-sensitive industrial buyers in India and Vietnam continue specifying electrochemical alternatives despite drift limitations, delaying NDIR volume scaling.
- Calibration labor scarcity:Certified technician pools remain shallow outside Shanghai, Tokyo, and Sydney, constraining aftermarket service revenue capture.
Strategic Opportunities
- India's green building emergence:GRIHA-rated commercial projects in Bangalore and Hyderabad are mandating CO2 monitoring for ventilation optimization, opening specification windows for premium optical sensors.
- Pharmaceutical cleanroom expansion:Taiwan and South Korean biologics manufacturing is specifying ±10 ppm accuracy sensors for batch consistency, commanding margin premiums over standard IAQ devices.
- Sensor-as-a-service bundling:HVAC-integrated hardware vendors are piloting subscription calibration models in Australian commercial portfolios, converting capital sales into recurring revenue.
Industry Challenges
- Multi-protocol integration complexity:BACnet, Modbus, and emerging IoT standards fragment building management system compatibility, forcing sensor vendors to maintain redundant firmware variants.
- Cross-border certification timelines:Japan's PSE marking, China's CCC, and Australia's RCM create sequential approval bottlenecks for unified product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific CO2 Gas Sensor Market |
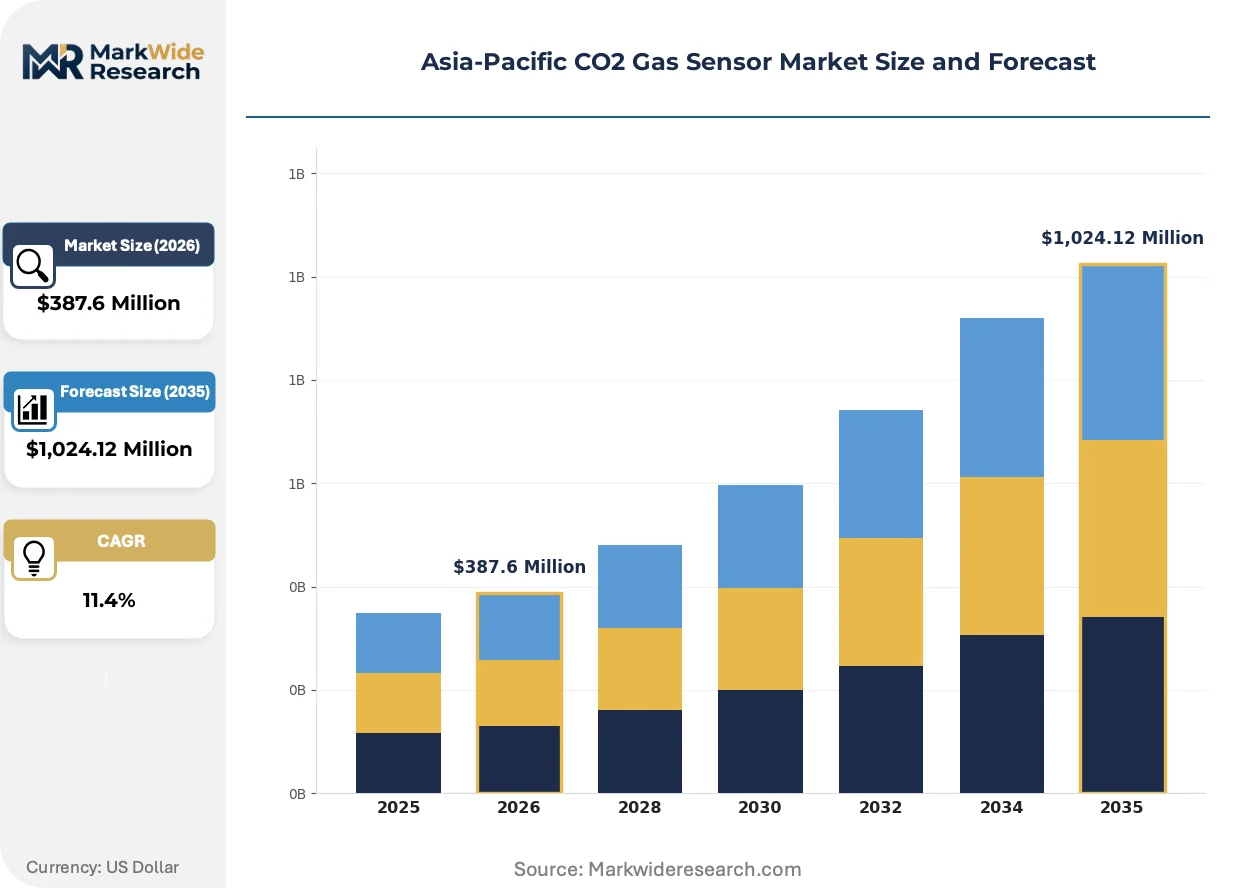
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Sensors, Fixed Sensors, Wireless Sensors, Infrared Sensors Application: Indoor Air Quality Monitoring, Industrial Emissions, HVAC Systems, Environmental Monitoring End User: Commercial Buildings, Industrial Facilities, Residential Homes, Agricultural Sector Technology: Optical Sensors, Chemical Sensors, Solid-State Sensors, Photoacoustic Sensors |
| Companies Covered | Siemens AG, Honeywell International, Vaisala Oyj, SenseAir, Amphenol Corporation, Cubic Sensor and Instrument Co., Zhengzhou Winsen Electronics Technology Co., Figaro, Nemoto & Co., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific CO2 Gas Sensor Market Trends and Innovations
Photonic integration and edge computing architectures are compressing sensor form factors while expanding autonomous diagnostic capabilities, enabling deployment in space-constrained retrofit environments previously inaccessible to conventional hardware.
Silicon photonics-based NDIR architectures are rendering obsolete traditional lamp-and-detector assemblies in mid-range indoor air quality applications. Japanese commercial real estate operators are specifying solid-state sensors for 10-year maintenance-free operation. The elimination of filament degradation is compressing total cost of ownership calculations and accelerating replacement of electrochemical alternatives in premium building segments.
Japan's METI building energy efficiency standards now require CO2-driven demand-controlled ventilation in structures exceeding 2,000 square meters. HVAC system integrators are specifying networked sensor arrays with 15-minute data logging intervals. Pharmaceutical and semiconductor cleanroom operators in Osaka and Nagoya are driving adoption of redundant sensor configurations to satisfy batch record audit requirements.
Facility management procurement teams are unbundling sensor hardware from installation and calibration services, reversing decade-long bundled contracting norms. Australian commercial property managers are separately sourcing sensors, commissioning, and ongoing verification. This fragmentation is compressing OEM service attach rates while expanding independent calibration specialist margins in Sydney and Melbourne metropolitan markets.
Asia-Pacific CO2 Gas Sensor Market Segmentation
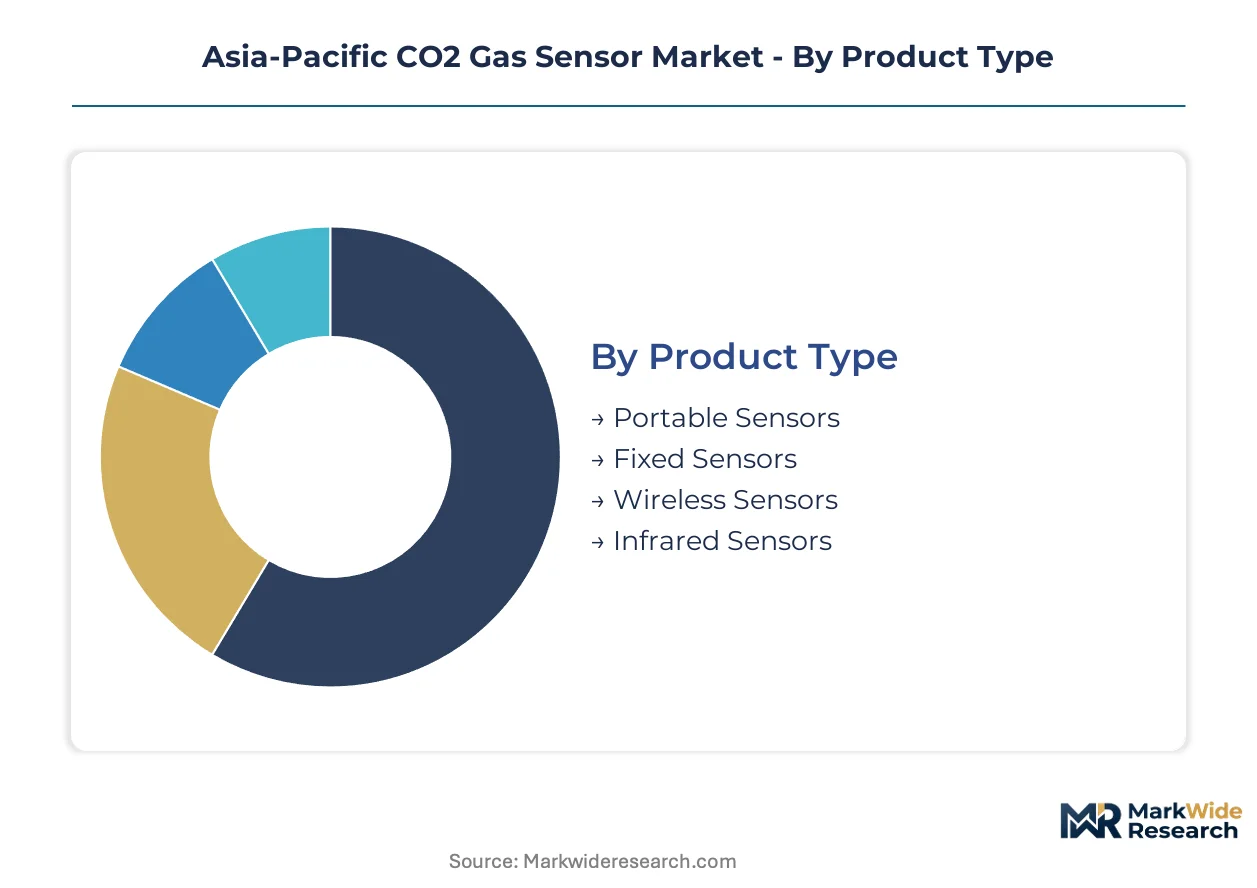
Segmentation in the Asia-Pacific CO2 gas sensor market reveals divergent replacement dynamics across product architectures. Cycle times compress where wireless retrofit demand accelerates, while fixed installations in new construction sustain longer depreciation schedules.
Product Type:
Replacement velocity varies sharply across product architectures, with retrofit-oriented designs turning over fastest as facility managers prioritize connectivity upgrades over hardware longevity.
- Portable Sensors:Handheld NDIR units with 400-5,000 ppm range serve calibration verification and spot-check applications. Demand clusters with MEE compliance auditors across China's steel belt and independent HVAC commissioning agents in Sydney.
- Fixed Sensors:Hardwired wall-mounted devices dominate new commercial construction above 2,000 square meters under Japan's METI energy efficiency mandates. These installations integrate with BACnet building management systems and typically depreciate over 7-10 year cycles.
- Wireless Sensors:Battery-powered LoRaWAN and Zigbee devices eliminate conduit costs in aging Japanese and Singaporean infrastructure. Retrofit penetration accelerates where structural renovation is cost-prohibitive.
- Infrared Sensors:Lamp-based NDIR assemblies face displacement by solid-state alternatives despite maintaining cost advantages in high-volume industrial specifications.
Fixed sensors anchor the volume base while wireless sensors gain share at the steepest rate.
Application:
Specification requirements diverge by compliance intensity, with regulated industrial applications commanding accuracy premiums over comfort-driven commercial deployments.
- Indoor Air Quality Monitoring:400-2,000 ppm measurement range with ±30 ppm accuracy satisfies South Korea's Green Building Certification and Australia's NCC Section J provisions. Sensor density increases in premium office developments across Bangalore's GRIHA-rated commercial corridors.
- Industrial Emissions:Continuous emissions monitoring systems face China's MEE dual carbon reporting requirements across cement and steel facilities. These installations demand 5,000+ ppm range with redundant sensor configurations.
- HVAC Systems:Demand-controlled ventilation integration drives specification through mechanical contractors in Tokyo and Seoul metropolitan markets.
- Environmental Monitoring:Meteorological and urban air quality networks in Singapore and Hong Kong deploy research-grade instrumentation with data logging intervals under 15 minutes.
Indoor air quality monitoring commands the largest installed base while industrial emissions applications expand most quickly under tightening MEE enforcement.
End User:
Procurement sophistication stratifies sharply across customer categories, with institutional buyers extracting service bundling concessions unavailable to fragmented residential purchasers.
- Commercial Buildings:Property managers across Australian commercial portfolios are unbundling hardware from calibration services, compressing OEM attach rates. Specifications favor 10-year maintenance-free solid-state architectures.
- Industrial Facilities:Steel, cement, and chemical plants under China's dual carbon framework require continuous monitoring with compliance-grade documentation. Procurement concentrates through EPC contractors with MEE audit experience.
- Residential Homes:Smart home integration drives demand in Japan's urban condominiums, though price sensitivity sustains electrochemical alternatives in mass-market segments.
- Agricultural Sector:Controlled-environment horticulture in Taiwan and South Korea specifies CO2 enrichment monitoring for yield optimization, typically at lower accuracy tolerances than commercial IAQ applications.
Commercial buildings generate the highest revenue per installation while industrial facilities drive volume scaling through compliance mandates.
Technology:
Margin structures diverge by component integration depth, with solid-state architectures capturing premium pricing against legacy lamp-based alternatives facing commoditization pressure.
- Optical Sensors:NDIR architectures measuring 4.26 micrometer absorption wavelength dominate commercial IAQ with superior stability versus electrochemical alternatives. Japanese real estate operators specify these for 10-year maintenance-free operation in premium assets.
- Chemical Sensors:Electrochemical cells retain residual share in cost-sensitive Indian and Vietnamese industrial applications despite drift limitations requiring annual recalibration.
- Solid-State Sensors:Silicon photonics-based devices eliminate filament degradation and compress form factors for space-constrained retrofit environments.
- Photoacoustic Sensors:Emerging architectures target pharmaceutical cleanroom applications in South Korean and Taiwanese biologics manufacturing where ±10 ppm accuracy commands margin premiums.
Optical sensors dominate current revenue while solid-state alternatives climb the fastest as Japanese and Australian facility managers prioritize total cost of ownership over acquisition price.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys CO2 sensors primarily for industrial emissions compliance, while Japan and Australia prioritize indoor air quality in commercial real estate—creating divergent specification requirements across the region. South Korea and Singapore occupy intermediate positions with balanced regulatory pressure across both applications.
China
Steel and cement plants in the Yangtze River Delta drive continuous monitoring installations under MEE's dual carbon reporting mandates. The ministry's industrial emissions framework requires documented CO2 tracking across energy-intensive facilities. Manufacturing corridors around Shanghai and Nanjing concentrate procurement through EPC contractors with compliance audit experience.
Japan
METI building energy efficiency standards mandate demand-controlled ventilation in commercial structures exceeding 2,000 square meters. Pharmaceutical cleanroom operators in Osaka and Nagoya specify redundant sensor configurations for batch record compliance. Facility managers in Tokyo's premium office stock prioritize 10-year maintenance-free solid-state architectures.
Australia
NCC Section J provisions shape commercial building specifications, with property managers unbundling hardware from calibration services. Sydney and Melbourne metropolitan markets expand independent calibration specialist margins. HVAC-integrated sensor distribution concentrates through mechanical contractors serving commercial portfolios.
South Korea
Green Building Certification criteria mandate CO2 sensors in new commercial construction above 1,000 square meters. Biologics manufacturing in the Seoul Capital Area specifies ±10 ppm accuracy devices for batch consistency. The Busan-Ulsan industrial corridor sustains parallel demand from chemical processing facilities.
India
GRIHA-rated commercial projects in Bangalore and Hyderabad mandate CO2 monitoring for ventilation optimization. Cost-sensitive industrial buyers in Gujarat and Maharashtra continue specifying electrochemical alternatives despite drift limitations. The emerging green building segment opens specification windows for premium optical sensors in premium developments.
Asia-Pacific CO2 Gas Sensor Market Competitive Landscape
Capability concentration sits with specialized measurement technology developers; scale advantage sits with diversified industrial conglomerates with building automation platforms. The market exhibits tiered structure with premium optical specialists, mid-range HVAC-integrated suppliers, and cost-focused electrochemical assemblers. Strategic archetypes include platform-anchored service bundlers, accuracy-differentiated cleanroom specialists, and wireless retrofit enablers. Dominant competitive moves encompass calibration service attach rate defense and silicon photonics technology transitions.
Among diversified industrial technology providers, Siemens AG and Honeywell International exemplify platform-anchored competitors leveraging building automation ecosystems to sustain recurring service relationships. Vaisala Oyj occupies a position within the precision measurement specialist tier, representing accuracy-focused positioning for regulated applications. Chinese sensor assemblers including Cubic Sensor and Instrument Co. and Zhengzhou Winsen Electronics Technology Co. anchor the cost-optimized volume segment, competing on unit economics for price-sensitive industrial deployments.
| Leading Market Players |
|---|
| Siemens AG |
| Honeywell International |
| Vaisala Oyj |
| SenseAir |
| Amphenol Corporation |
| Cubic Sensor and Instrument Co. |
| Zhengzhou Winsen Electronics Technology Co. |
| Figaro |
| Nemoto & Co. |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on Japanese and German infrared component suppliers compresses pricing tier spreads while forcing sensor assemblers into dual-sourcing investments that reshape regional manufacturing footprints. This concentration dynamic rewards integrated platform vendors with calibration attach rate pricing power while fragmenting pure hardware margins.
Pricing Analysis
Long-term calibration service contracts dominate commercial building automation procurement in Australian and Japanese portfolios, while spot-market transactional purchasing persists for cost-sensitive Indian industrial buyers. Three-tier pricing structure across premium optical, standard NDIR, and economy electrochemical levels reflects accuracy certification and after-sales bundling differentiation. Cost compression in the electrochemical tier intensifies because Vietnamese and Indonesian buyers prioritize acquisition price over total cost of ownership. Facility management procurement teams in Sydney and Melbourne exhibit the least price sensitivity, accepting 40-60% premiums for decade-long maintenance-free solid-state architectures.
Supply Chain Analysis
Tariff exposure between China and key component source countries in Japan and Germany dominates supply chain risk calculus for infrared detector procurement. Manufacturing concentration centers on Chinese sensor assembly for volume production, Japanese precision component fabrication, and Taiwanese silicon photonics wafer processing. Infrared sources, thermopile detectors, and MEMS-based optical benches constitute critical input dependencies. Distribution runs through HVAC mechanical contractors in developed markets and industrial equipment distributors in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Australian commercial property managers and Chinese EPC contractors with MEE compliance expertise, compressing OEM service attach rates and fragmenting procurement across unbundled hardware and calibration specialists.
For Market Incumbents: Entrench platform-anchored positions by deepening calibration service integration with building management systems and defending channel control of HVAC-integrated distribution in Australia and New Zealand. Silicon photonics R&D investment represents the critical lever against solid-state sensor displacement threats from emerging Asian component specialists. For New Entrants and Emerging Players: Establish a beachhead in India's GRIHA-rated commercial corridor by targeting ventilation optimization specifications in Bangalore and Hyderabad premium developments. Wireless retrofit demand in aging Japanese and Singaporean infrastructure offers the most penetrable entry vector, with LoRaWAN-enabled battery-powered architectures as the differentiated go-to-market angle. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors precision measurement specialists with pharmaceutical cleanroom certification and silicon photonics IP portfolios. Long-term viability hinges on recurring revenue conversion capability across the analysis window. Acquisition targets should demonstrate ±10 ppm accuracy manufacturing and established METI or MEE audit relationships. The signal to watch is unbundling velocity in Australian commercial property management procurement patterns.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Photonics Transition | Eliminates filament degradation in Japanese 10-year maintenance-free specifications. |
| Calibration-as-a-Service Bundling | Converts capital sales into recurring revenue across Australian commercial portfolios. |
| Pharmaceutical Cleanroom Certification | Commands margin premiums from South Korean biologics batch consistency requirements. |
| Wireless Retrofit Platform Launch | Captures aging infrastructure demand in Japanese and Singaporean building stock. |
| Dual-Carbon Compliance Documentation | Unlocks Chinese steel and cement plant procurement through MEE audit experience. |
Research Methodology
A standing panel of HVAC system integrators, facility management procurement directors, and MEE compliance auditors provided ongoing calibration against secondary data trends. Primary interviews with building automation platform engineers, pharmaceutical cleanroom operators, and industrial EPC contractors anchored demand-side intelligence. Secondary validation drew from METI energy efficiency filings, Australian NCC Section J regulatory updates, Chinese customs trade data, and South Korean Green Building Certification databases. Bottom-up sensor shipment analysis triangulated against top-down building construction permit flows.
Scenario-bracketing around regulatory enforcement intensity and silicon photonics adoption curves bounded volume and value projections across the modeling period. Segmentation dimensions included product architecture, application compliance intensity, end-user procurement sophistication, and technology integration depth. CAGRs derived from fitted growth curves against historical replacement cycle compression patterns and emerging green building specification penetration. Industry-specific inputs encompassed pharmaceutical cleanroom expansion timelines and dual-carbon framework implementation velocity.
Sensitivities concentrate around MEE enforcement consistency, Japanese solid-state sensor specification adoption rates, and infrared component supply lead time volatility. Forecasts reflect documented assumptions regarding regulatory trajectory and technology substitution elasticity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Bioacoustics Sensing Market
Sensors and Controls
Distance Measurement Sensor Market
Sensors and Controls
Europe Touch Sensor Market
Sensors and Controls
Sensor Fusion Market
Sensors and Controls
Laser Scanner Market
Sensors and Controls
Sensor Hub Market
Sensors and Controls
Digital Sensor Sleeves Market
Sensors and Controls
MEMS-Based Oscillator Market
Sensors and Controls
Smart Pressure Sensors Market
Sensors and Controls
Marine Sensors Market
Sensors and Controls
Gyroscope Market
Sensors and Controls
Air Quality Monitoring System Market
Sensors and Controls
Off-Highway Machine Position and Angle Sensor Components Market
Sensors and Controls
Spectral Sensor Market
Sensors and Controls
Current Sensor Market
Sensors and Controls
Air Pressure Sensor Market